
 Positive Patient Identification Market | 2026-2036
Positive Patient Identification Market Size, Share, and Industry Trends Forecast 2026-2036
Positive Patient Identification Market Outlook
HIPAA's evolving enforcement posture is shifting the cost-of-entry calculus for vendors seeking hospital contracts. Imprivata, Inc. leverages deep integration with electronic health record platforms to sustain recurring revenue from large health systems. Zebra Technologies dominates mobile computing and barcode hardware, while RightPatient, Inc. specializes in cloud-based biometric matching that anchors its position in outpatient networks.
Positive patient identification encompasses hardware and software systems that verify patient identity through unique physiological or assigned identifiers, typically employing barcode symbologies, radio-frequency tags, or biometric templates matched against master patient indices. These systems prevent wrong-patient errors during medication administration, specimen collection, and transfusion workflows. Biometric systems lead technology adoption where fingerprint and palm-vein modalities capture premium margins, while RFID technology grows fastest in emergency departments requiring hands-free verification. Software solutions command recurring revenue streams, yet integrated systems that bundle hardware, middleware, and EHR connectivity concentrate margin pools for vendors.
FDA, Joint Commission, and HIPAA frameworks collectively shape product standards and procurement requirements across US health systems. The Joint Commission's National Patient Safety Goals mandate two-identifier verification, directly driving replacement cycles for legacy barcode-only systems. Stakeholders must monitor how emerging state-level biometric privacy laws reshape facial recognition deployment in hospitals and clinics.
Market Dynamics
Biometric verification is displacing barcode-only workflows as health systems confront Joint Commission two-identifier mandates and malpractice liability exposure from wrong-patient errors.
Growth Catalysts
- FDA Unique Device Identification mandate:Hospital procurement teams must integrate UDI-compliant scanners into medication administration workflows, forcing hardware refresh cycles across inpatient units.
- Palm-vein recognition:Contactless biometric matching reduces hospital-acquired infection transmission risk while satisfying HIPAA identity verification requirements in oncology and transplant wards.
- Emergency department throughput pressure:RFID-enabled hands-free patient verification accelerates triage processing in Level I trauma centers facing capacity constraints.
Market Restraints
- Biometric sensor cost concentration:Fingerprint and iris scanning modules rely on semiconductor fabrication capacity concentrated in East Asian foundries, exposing vendors to input price volatility.
- State-level biometric privacy fragmentation:Illinois BIPA and emerging California facial recognition restrictions create compliance patchwork that complicates multi-state health system deployments.
- Legacy EHR interoperability gaps:Proprietary data formats in older Epic and Cerner installations resist middleware integration, extending implementation timelines.
Strategic Opportunities
- Ambulatory surgery center expansion:Outpatient procedural volumes are shifting to ASCs, creating demand for cloud-hosted biometric matching without enterprise IT infrastructure.
- Remote patient monitoring convergence:Home-based biometric identity verification paired with telehealth platforms addresses medication adherence verification for chronic disease management.
- Joint Commission accreditation incentives:Safety score improvements from biometric adoption translate to preferred payer network status and value-based contract bonuses.
Industry Challenges
- Biometric template security architecture:Health systems lack in-house cryptography expertise to implement NIST-compliant template encryption, forcing reliance on vendor-managed security models.
- Multi-modal system integration complexity:Synchronizing fingerprint, palm-vein, and RFID verification across nursing workstations, pharmacy dispensing cabinets, and laboratory information systems demands specialized health IT project management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Positive Patient Identification Market |
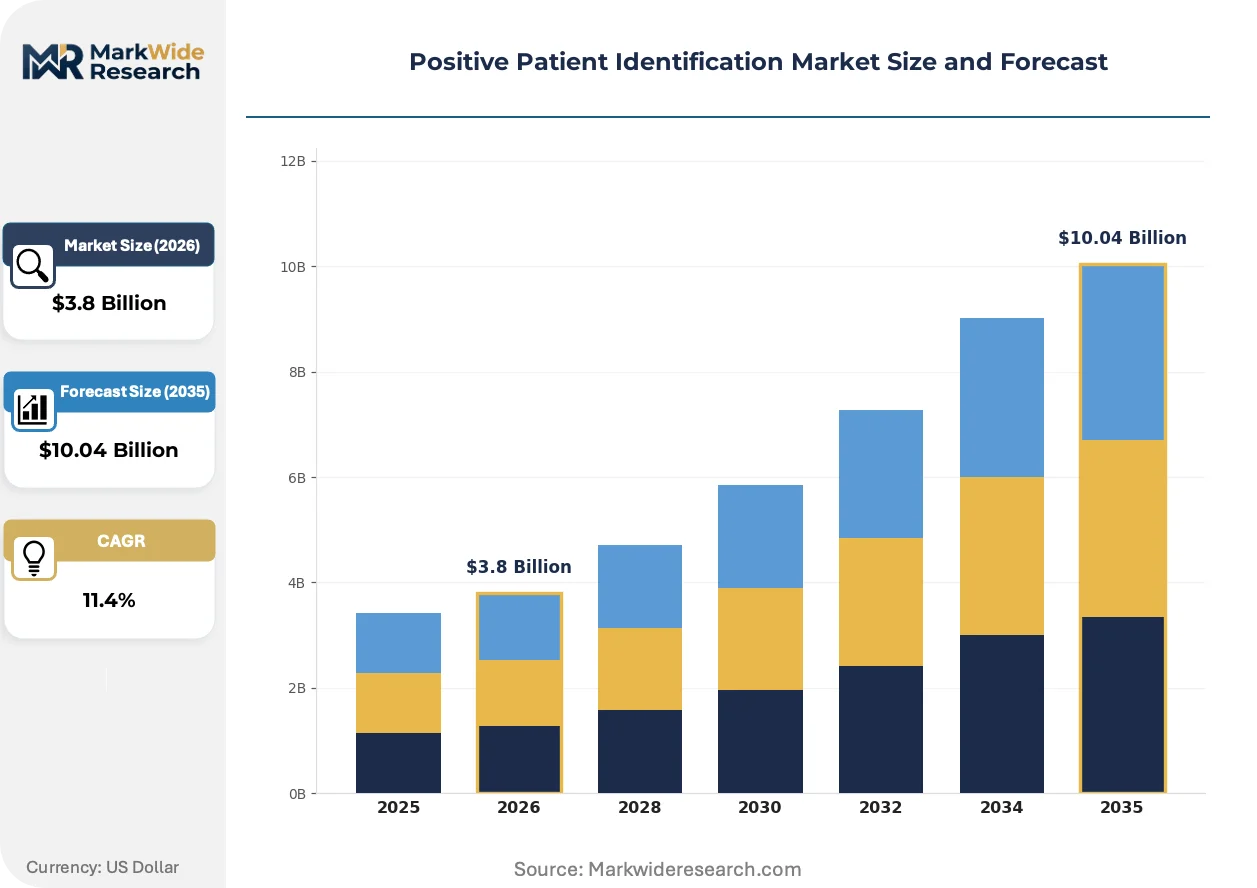
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Barcode Scanners, RFID Technology, Biometric Systems, Facial Recognition Application: Inpatient Care, Outpatient Services, Emergency Departments, Transfusion Services End User: Hospitals, Clinics, Long-Term Care Facilities, Home Health Agencies Solution: Software Solutions, Integrated Systems, Standalone Devices, Mobile Applications |
| Companies Covered | Imprivata, Inc., Zebra Technologies, RightPatient, Inc., Honeywell, General Data Company, Inc., SATO Holdings Corporation, RMS Omega Technologies Group, Inc., PatientWorks Corporation, GBS Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Positive Patient Identification Market Strategic Shifts
Machine learning inference at the network edge is compressing identification latency while regulatory pressure on patient safety errors accelerates hardware replacement cycles.
Computer vision-based facial recognition is automating passive patient verification in waiting areas and radiology suites without requiring conscious patient cooperation. Academic medical centers in Texas and Florida are piloting these systems for unconscious trauma patient identification. The technology is automating the elimination of manual wristband checks that previously consumed 45-90 seconds per patient encounter.
The Joint Commission's 2024 National Patient Safety Goals revision tightened two-identifier requirements for blood product administration. Blood bank supervisors must now document biometric or RFID verification in addition to barcode scanning. Transfusion services departments are responding by retrofitting existing scanners with palm-vein readers or replacing entire workstation fleets.
Subscription pricing for biometric matching software is displacing perpetual license models that dominated early EHR integration contracts. Hospital CFOs prefer operational expenditure treatment for identity infrastructure that requires continuous algorithm updates. This shift is most visible among mid-sized health systems in the Southeast that lack dedicated health IT capital budgets.
Positive Patient Identification Market Segmentation
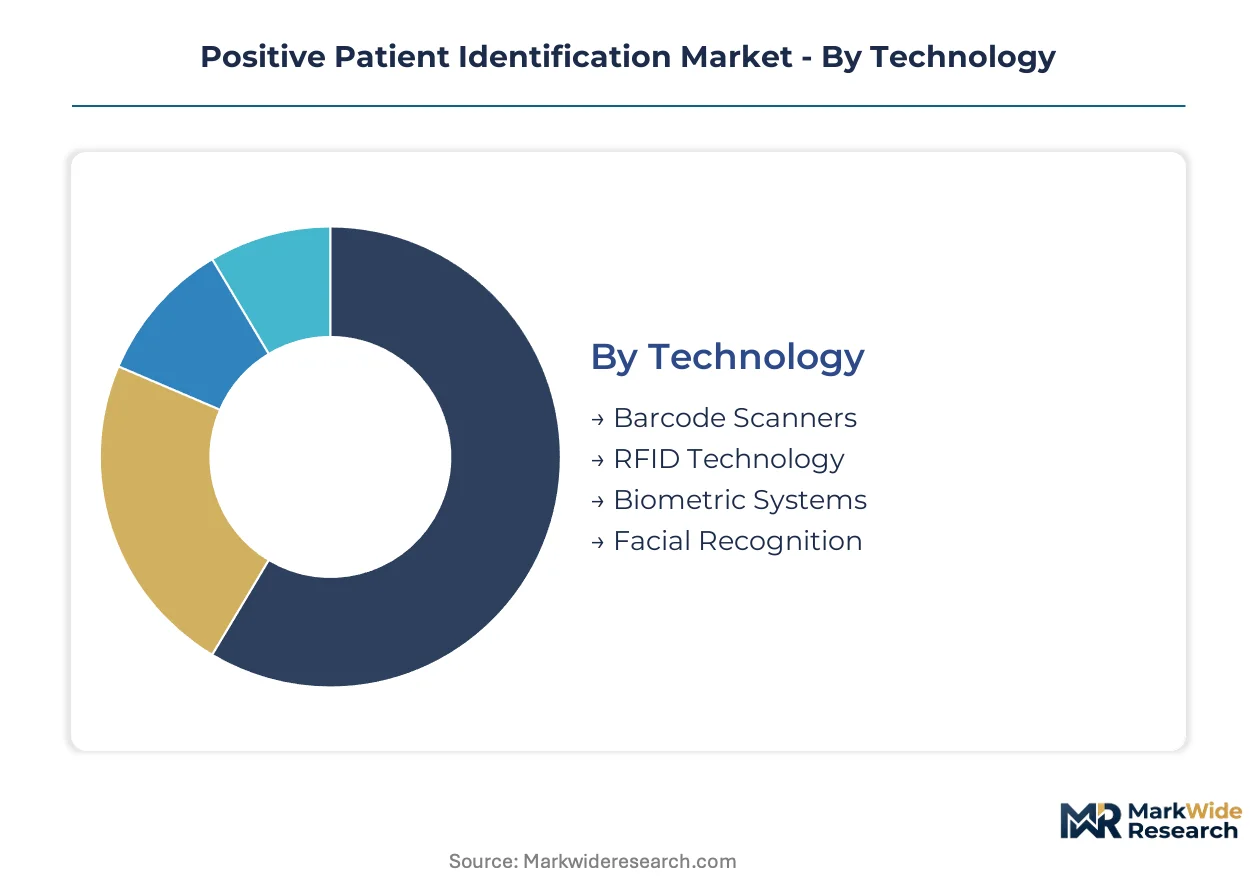
Technology selection in positive patient identification determines compliance posture against Joint Commission mandates and infection control protocols. Procurement patterns diver sharply between health systems prioritizing capital efficiency and those accepting premium hardware for liability reduction.
Technology:
Hospital IT departments differentiate procurement by biometric modality maturity and semiconductor supply exposure.
- Biometric Systems:Palm-vein and fingerprint modalities capture premium margins in oncology and transplant wards where contactless verification reduces hospital-acquired infection transmission. Texas Medical Center and Mayo Clinic Rochester anchor demand for multi-factor biometric workstations that satisfy HIPAA identity assurance requirements.
- RFID Technology:Passive and active radio-frequency tags enable hands-free patient verification in Level I trauma centers facing throughput pressure. Emergency departments at Johns Hopkins Hospital and Massachusetts General Hospital deploy RFID wristbands integrated with real-time location systems to accelerate triage processing without nursing staff intervention.
- Barcode Scanners:Legacy one-dimensional and two-dimensional symbology readers dominate medication administration workflows where EHR integration costs constrain upgrade timelines.
- Facial Recognition:Computer vision-based passive verification pilots at academic medical centers in Florida and Illinois confront state-level biometric privacy law fragmentation.
Barcode scanners lead volumes today; biometric systems are gaining share fastest.
Application:
Clinical workflow risk profiles determine solution complexity and hardware redundancy requirements.
- Transfusion Services:Blood product administration demands the highest identity assurance tier under Joint Commission National Patient Safety Goals. Transfusion services departments at Cleveland Clinic and Cedars-Sinai Medical Center retrofit existing scanners with palm-vein readers to document biometric verification beyond barcode matching.
- Emergency Departments:Unconscious trauma patient identification drives demand for passive biometric verification without conscious cooperation. Academic medical centers in Houston and Miami pilot facial recognition systems that eliminate 45-90 second manual wristband checks per encounter.
- Inpatient Care:Medical-surgical units and intensive care departments deploy barcode-biometric hybrid verification at medication dispensing cabinets and nursing workstations.
- Outpatient Services:Ambulatory clinics prioritize cloud-hosted biometric matching with lower IT infrastructure overhead for episodic patient encounters.
Transfusion services commands the steepest pricing; emergency departments show the strongest volume expansion trajectory.
End User:
Capital budget scale and IT staffing depth separate procurement strategies across provider types.
- Hospitals:Integrated delivery networks with dedicated health IT capital budgets deploy enterprise-wide biometric platforms spanning inpatient towers, emergency departments, and surgical suites. Kaiser Permanente and Intermountain Healthcare anchor demand for EHR-embedded identity verification.
- Clinics:Federally qualified health centers and specialty practices favor subscription-priced biometric software that converts capital expenditure to operational treatment.
- Long-Term Care Facilities:Skilled nursing facilities face Medicaid reimbursement constraints that limit hardware refresh cycles to barcode-only systems.
- Home Health Agencies:Remote patient monitoring convergence creates demand for tablet-based biometric verification during home medication administration visits.
Hospitals dominate absolute spending; clinics are expanding most quickly as ambulatory procedural volumes shift from inpatient settings.
Solution:
Delivery model preferences split between health systems seeking vendor-managed security and those demanding on-premise data control.
- Integrated Systems:Bundled hardware-middleware-EHR connectivity concentrates margin pools for vendors serving large health systems. Epic and Cerner integration certifications determine competitive positioning for enterprise contracts at Stanford Health Care and NYU Langone Health.
- Software Solutions:Cloud-hosted biometric matching algorithms with continuous update subscriptions displace perpetual licenses. Southeast US mid-sized health systems lacking dedicated IT capital budgets drive subscription pricing adoption.
- Standalone Devices:Single-purpose barcode scanners and biometric readers serve specialty departments with isolated workflow requirements.
- Mobile Applications:Smartphone-based verification extends patient identification to home health and telehealth platforms addressing chronic disease medication adherence.
Integrated systems capture the largest contract values; software solutions are climbing the fastest as CFOs favor operational expenditure treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered large-scale biometric patient identification during the 2000s EHR modernization wave. Early deployments at Mayo Clinic Rochester and Cleveland Clinic established clinical validation protocols now replicated internationally. Today procurement concentrates in health systems facing Joint Commission accreditation pressure and malpractice liability exposure.
United States
Texas Medical Center and Johns Hopkins Hospital anchor demand for palm-vein and RFID-integrated systems in trauma and transfusion workflows. The FDA's Unique Device Identification mandate forces hardware refresh cycles across inpatient medication administration. Kaiser Permanente and Intermountain Healthcare deploy enterprise-wide platforms spanning multi-state networks.
Germany
University hospitals in Munich and Heidelberg pilot facial recognition for unconscious patient identification in emergency departments. The EU Medical Device Regulation (MDR) and GDPR biometric data rules create compliance complexity for multi-modal verification systems. Baden-Württemberg's medical technology cluster concentrates vendor engineering operations serving Central European health networks.
United Kingdom
NHS England's patient safety mandates drive replacement of legacy barcode systems in London and Manchester teaching hospitals. The UK Information Commissioner's Office enforces strict biometric template storage requirements under GDPR-derived domestic law. Scotland's NHS boards favor cloud-hosted verification for rural hospital connectivity constraints.
Japan
Tokyo's St. Luke's International Hospital and Osaka University Hospital deploy contactless biometric verification for infection control in oncology wards. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates patient identification hardware as Class II medical devices. METI's healthcare digitization subsidies accelerate RFID adoption in aging rural facilities.
Australia
Royal Melbourne Hospital and Sydney's Westmead Hospital implement multi-factor verification for blood product administration workflows. The Therapeutic Goods Administration (TGA) aligns device identification requirements with FDA UDI standards. Queensland's regional health services prioritize mobile biometric solutions for remote clinic networks.
Positive Patient Identification Market Competitive Environment
The competitive structure tilts toward integrated platform vendors commanding EHR certification advantages. Market concentration reflects high switching costs and proprietary middleware dependencies that protect incumbent positions. Three archetypes dominate: enterprise biometric platform providers, specialized hardware manufacturers, and cloud-native software specialists. Consolidation pressures favor acquisition of niche biometric algorithm firms by larger health IT conglomerates, while strategic partnerships between hardware OEMs and EHR vendors lock out unaligned competitors.
Within the enterprise platform tier, Imprivata, Inc. and Zebra Technologies occupy positions reflecting divergent strategic foundations—software-centric workflow integration versus hardware-dominant mobile computing ecosystems. RightPatient, Inc. exemplifies the cloud-native specialist archetype targeting ambulatory networks with subscription pricing models. These three anchors illustrate how vendor selection splits between health systems prioritizing capital efficiency and those demanding comprehensive EHR-embedded identity infrastructure.
| Leading Market Players |
|---|
| Imprivata, Inc. |
| Zebra Technologies |
| RightPatient, Inc. |
| Honeywell |
| General Data Company, Inc. |
| SATO Holdings Corporation |
| RMS Omega Technologies Group, Inc. |
| PatientWorks Corporation |
| GBS Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive middleware development anchors competitive positioning for enterprise biometric platform vendors, concentrating margin capture among firms with Epic and Cerner integration certifications while forcing hardware specialists toward commoditized scanner production. This vertical integration choice separates vendors sustaining recurring software revenue from those trapped in transactional device sales cycles.
Pricing Analysis
Bundled hardware-middleware-EHR connectivity contracts command premium positioning against unbundled scanner-only procurement. Subscription SaaS models for cloud-hosted biometric matching displace perpetual licenses as hospital CFOs favor operational expenditure treatment. Price differentiation separates certified Epic-embedded platforms from uncertified alternatives, with fingerprint and palm-vein sensor modules carrying semiconductor input volatility. Pricing pressure stems from East Asian foundry capacity constraints for biometric sensors. Federally qualified health centers and specialty practices exhibit highest price sensitivity, while integrated delivery networks accept premium hardware for liability reduction.
Supply Chain Analysis
Biometric sensor fabrication rests on semiconductor foundry capacity concentrated in Taiwan, South Korea, and China. Fingerprint scanning modules and iris recognition cameras draw from CMOS image sensor and near-infrared LED supply chains. Single-source vulnerability runs through Taiwanese wafer production for palm-vein imaging components. Distribution runs through health IT value-added resellers and direct hospital procurement committees, with GPO contracts consolidating purchasing power for large health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into durable demand, with the Joint Commission's 2024 National Patient Safety Goals revision tightening two-identifier mandates for blood product administration and accelerating replacement cycles.
For Market Incumbents: Anticipate margin compression in standalone barcode hardware as biometric verification displaces legacy workflows. Deepen Epic and Cerner integration certifications to defend enterprise contract positions against cloud-native challengers. Acquire niche palm-vein algorithm specialists to consolidate multi-modal biometric capabilities before platform commoditization accelerates. For New Entrants and Emerging Players: Launch via subscription-priced cloud-hosted biometric matching targeted at ambulatory surgery centers lacking dedicated IT infrastructure. Penetrate the Southeast US mid-sized health system segment where capital budget constraints favor operational expenditure models. Lead with RFID-enabled hands-free verification for emergency department throughput applications where incumbent platforms lack deployment flexibility. For Investors and Strategic Acquirers: Roll-up economics work for cloud-native biometric software specialists because hospital procurement fragmentation across 6,000 US facilities prevents single-vendor dominance. Target firms with FDA UDI compliance documentation and active Joint Commission accreditation references. Watch state-level biometric privacy law proliferation as the signal indicating regulatory complexity threshold for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Epic Integration Certification | Embedded EHR connectivity locks in multi-year enterprise contracts at Kaiser Permanente-scale health systems. |
| Palm-Vein Algorithm Acquisition | Contactless biometric IP addresses Joint Commission infection control mandates in oncology wards. |
| Cloud Subscription Transition | Recurring revenue models align CFO preference for operational expenditure treatment in capital-constrained facilities. |
| RFID-Emergency Department Partnership | Hands-free verification pilots at Johns Hopkins and Massachusetts General establish reference architectures for trauma workflow automation. |
| State Privacy Compliance Investment | Illinois BIPA and emerging California restrictions demand specialized legal infrastructure for multi-state deployments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital CIOs, biomedical engineers, GPO contracts managers, and blood bank supervisors with secondary validation against FDA UDI guidance documents, Joint Commission National Patient Safety Goals publications, hospital procurement databases, and CMS Medicare reimbursement filings. Bottom-up facility-level installation tracking and top-down vendor revenue analysis were triangulated to anchor market sizing.
Segment-weighting approaches distributed value across biometric modality, clinical application workflow, and end-user facility type through the projection horizon. Technology adoption curves modeled palm-vein and RFID penetration against legacy barcode baselines. CAGRs derived from replacement cycle analysis of Joint Commission-mandated hardware refreshes and EHR modernization timelines. Forecast inputs incorporated semiconductor supply constraints for fingerprint sensor modules and state-level biometric privacy law proliferation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FDA enforcement actions or Illinois BIPA-class litigation expansion. A small set of named triggers warrants ongoing watch: Joint Commission mandate expansion to outpatient settings, Epic-Cerner middleware API policy changes, and Taiwanese foundry capacity allocation shifts affecting biometric sensor input costs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Global Cold Plasma in Healthcare Market
Diagnostic and Therapeutic Devices
Acupuncture Needles Market
Diagnostic and Therapeutic Devices
Therapeutic Bed Market
Diagnostic and Therapeutic Devices
Skin Biopsy Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Hot and Cold Therapy Market
Diagnostic and Therapeutic Devices
RF Microneedling Market
Diagnostic and Therapeutic Devices
Global Smart Inhaler Technology Market
Diagnostic and Therapeutic Devices
Microneedle Drug Delivery Systems Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Middle-East and Africa Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Global Needle Free Injection Systems Market
Diagnostic and Therapeutic Devices
Upper GI Series Market
Diagnostic and Therapeutic Devices
Dissolving Microneedles Market
Diagnostic and Therapeutic Devices
Automated Immunoassay Analyzers Market
Diagnostic and Therapeutic Devices
Global Far Infrared Therapy Device Market