
 Australia Insulin Delivery Devices Market | 2026-2036
Australia Insulin Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Insulin Delivery Devices Market Analysis
Smart connectivity tier upgrades is rotating the Australia insulin delivery devices market toward higher-value automated systems. Novo Nordisk leverages its integrated diabetes portfolio to sustain R&D leadership in connected pen platforms. Medtronic anchors the premium pump segment through closed-loop algorithm development. Insulet Corporation differentiates via tubeless patch pump designs that reduce patient burden.
Insulin delivery devices are electromechanical or disposable instruments engineered to administer precise insulin doses via subcutaneous tissue, typically calibrated to 0.5-unit or 0.1-unit increments for glycemic control. Their primary commercial purpose is to replicate physiological insulin secretion patterns across basal and bolus requirements for diabetes management. Pen injectors occupy the largest volume position due to Medicare reimbursement familiarity, while smart insulin pens within the technology dimension capture expanding margin pools through data integration. Automated delivery systems represent the fastest structural expansion as CGM-pump convergence reduces hypoglycemic events.
TGA medical device regulations and the Therapeutic Goods (Medical Devices) Standards shape product registration pathways and post-market surveillance obligations for manufacturers. ISO 15197 and IEC 62304 standards govern glucose monitoring accuracy and software lifecycle management, respectively. Stakeholders must monitor reimbursement policy evolution for continuous glucose monitor integration with pump systems to anticipate access expansion decisions.
Market Dynamics
CGM-pump convergence is compressing hypoglycemic events while forcing manufacturers to integrate algorithmic closed-loop systems that synchronize glucose sensing with automated insulin modulation. This technical unification is restructuring competitive requirements across the Australian market.
Growth Catalysts
- Medicare reimbursement expansion:Continuous glucose monitor integration with pump systems is widening patient access across Type 1 diabetes populations. TGA fast-track pathways for breakthrough devices accelerate commercialization timelines.
- Homecare infrastructure density:New South Wales and Victoria maintain concentrated endocrinology networks that reduce specialist consultation friction. State-level diabetes management programs subsidize device acquisition costs.
- Smart pen data ecosystems:Bluetooth-enabled dose logging is creating adherence feedback loops that improve glycemic outcomes. Cloud integration permits remote clinician monitoring.
Market Restraints
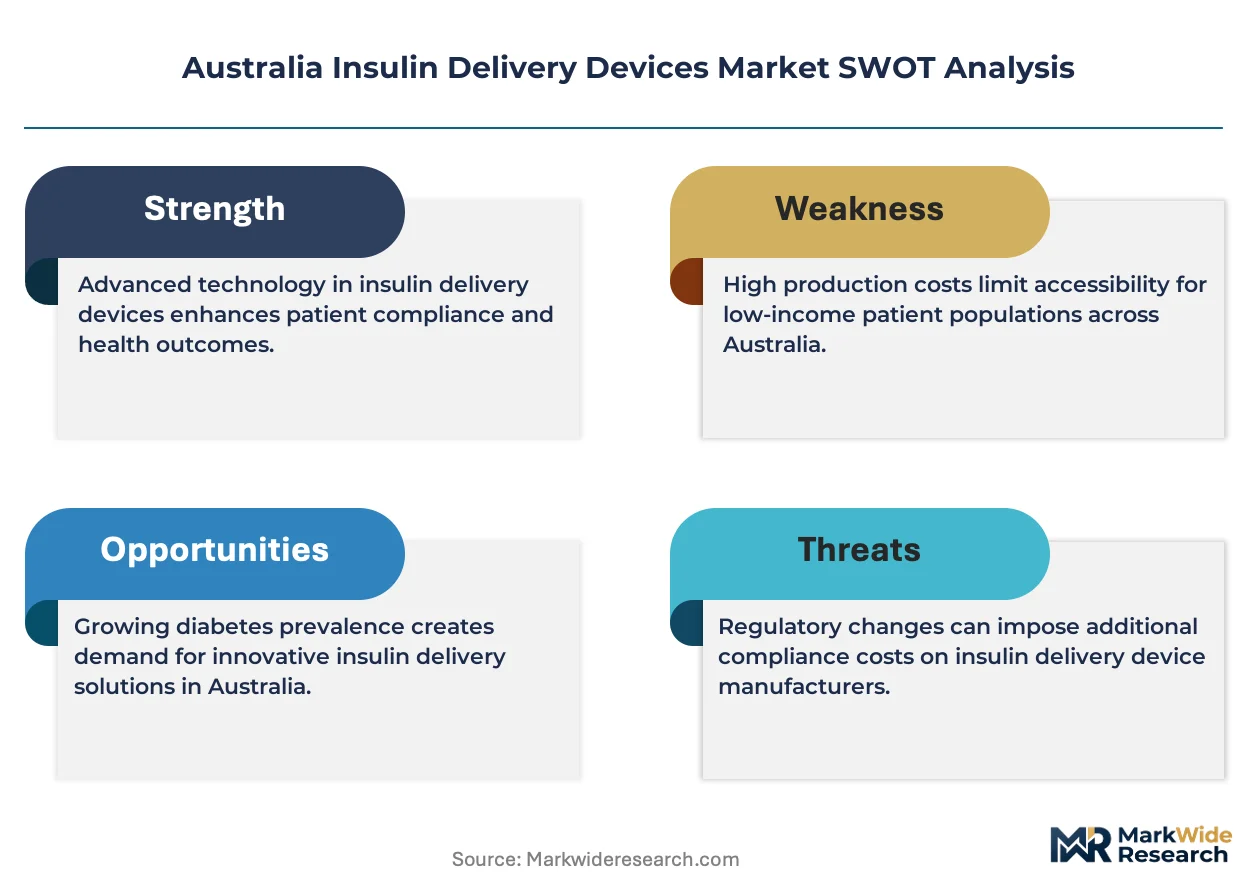
- Premium device cost concentration:Automated insulin delivery systems carry out-of-pocket burdens exceeding AUD 8,000 before reimbursement offsets. Patient cost sensitivity limits penetration among uninsured cohorts.
- CGM sensor supply bottlenecks:Manufacturing concentration in single-source contract manufacturers creates intermittent availability constraints. Australian distributors face allocation prioritization from international headquarters.
- TGA software validation timelines:IEC 62304 compliance documentation requirements extend registration cycles for algorithm-updatable devices. Firmware iteration cycles lag behind clinical evidence generation.
Strategic Opportunities
- Queensland and Western Australia expansion:Specialist endocrinology deserts in these states present whitespace for telemedicine-integrated device distribution. Remote monitoring capabilities reduce geography-dependent care barriers.
- Insulin pump-CGM bundle contracting:Integrated system procurement is consolidating vendor relationships and creating switching costs. Health systems negotiate multi-year service agreements.
- TGA priority review designation:Breakthrough device status offers expedited assessment for closed-loop algorithms demonstrating superior hypoglycemic reduction. Early approval windows compress competitive entry timelines.
Industry Challenges
- Biomedical software engineering scarcity:Algorithm development for closed-loop glucose control requires specialized control systems expertise. Australian universities produce insufficient graduates in physiological modeling.
- Legacy pump migration complexity:Existing Medtronic and Roche device installed bases create data portability friction. Patient reluctance to relearn interface protocols slows upgrade cycles.
- Post-market surveillance capacity:TGA's adverse event monitoring infrastructure strains under real-world performance data volumes from connected devices. Manufacturer vigilance obligations expand reporting burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Insulin Delivery Devices Market |
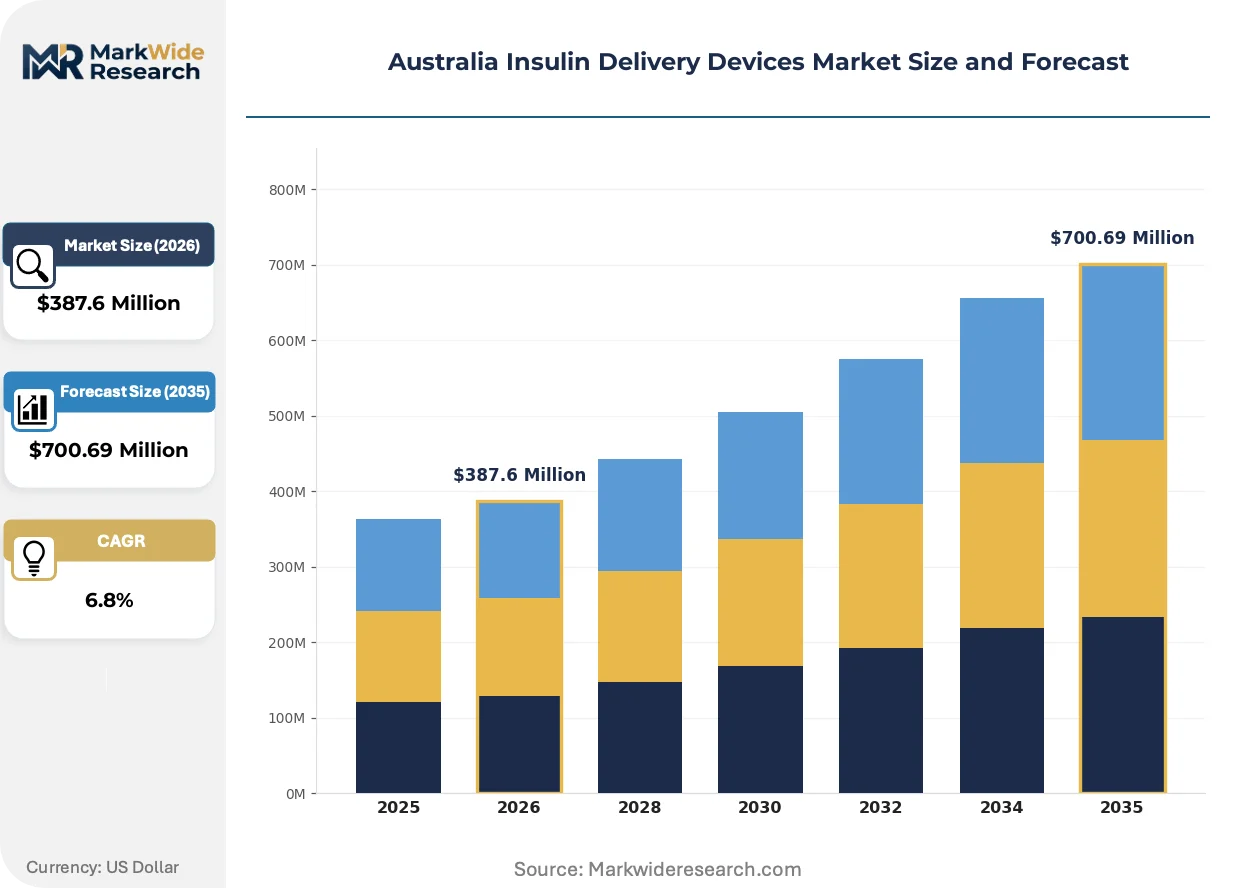
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Insulin Pumps, Pen Injectors, Syringes, Jet Injectors Administration Route: Subcutaneous, Intravenous, Intramuscular, Oral End User: Hospitals, Homecare, Diabetes Clinics, Endocrinology Centers Technology: Smart Insulin Pens, Continuous Glucose Monitors, Automated Delivery Systems, Wearable Devices |
| Companies Covered | Novo Nordisk, Medtronic, Insulet Corporation, Ypsomed, Eli Lilly and Company, Sanofi, Becton Dickinson, Tandem Diabetes Care, Embecta, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Insulin Delivery Devices Market Emerging Trajectories
Algorithmic personalization is displacing fixed-dose protocols across insulin delivery architectures. Device manufacturers embed machine learning that adapts basal rates to individual metabolic patterns. This intelligence layer is becoming the primary differentiation axis.
Tubeless patch pump form factors are fragmenting patient preference segmentation. Insulet's Omnipod platform anchors this category with waterproof, adhesive-mounted designs that eliminate infusion set management. Adolescent and active adult adopters prioritize discretion and mobility freedom over traditional pump precision. The category is fragmenting historical pump market boundaries by capturing pen injector users seeking automation without tubing.
TGA's alignment with EU MDR technical documentation requirements is harmonizing Australian registration pathways with European standards. Manufacturers submitting CE-marked technical files receive streamlined assessment under recognition agreements. Class III active implantable devices face intensified clinical evidence scrutiny. Local sponsors must maintain Australian legal representation for post-market accountability.
Subscription-based device provisioning is replacing capital purchase models in private insurance channels. Patients receive pump hardware, CGM sensors, and algorithm updates through bundled monthly fees. This consumption pattern spreads upfront cost burdens while locking recurring revenue streams. Private health funds in Victoria and New South Wales pilot these arrangements with employer-sponsored plans.
Australia Insulin Delivery Devices Market Segmentation
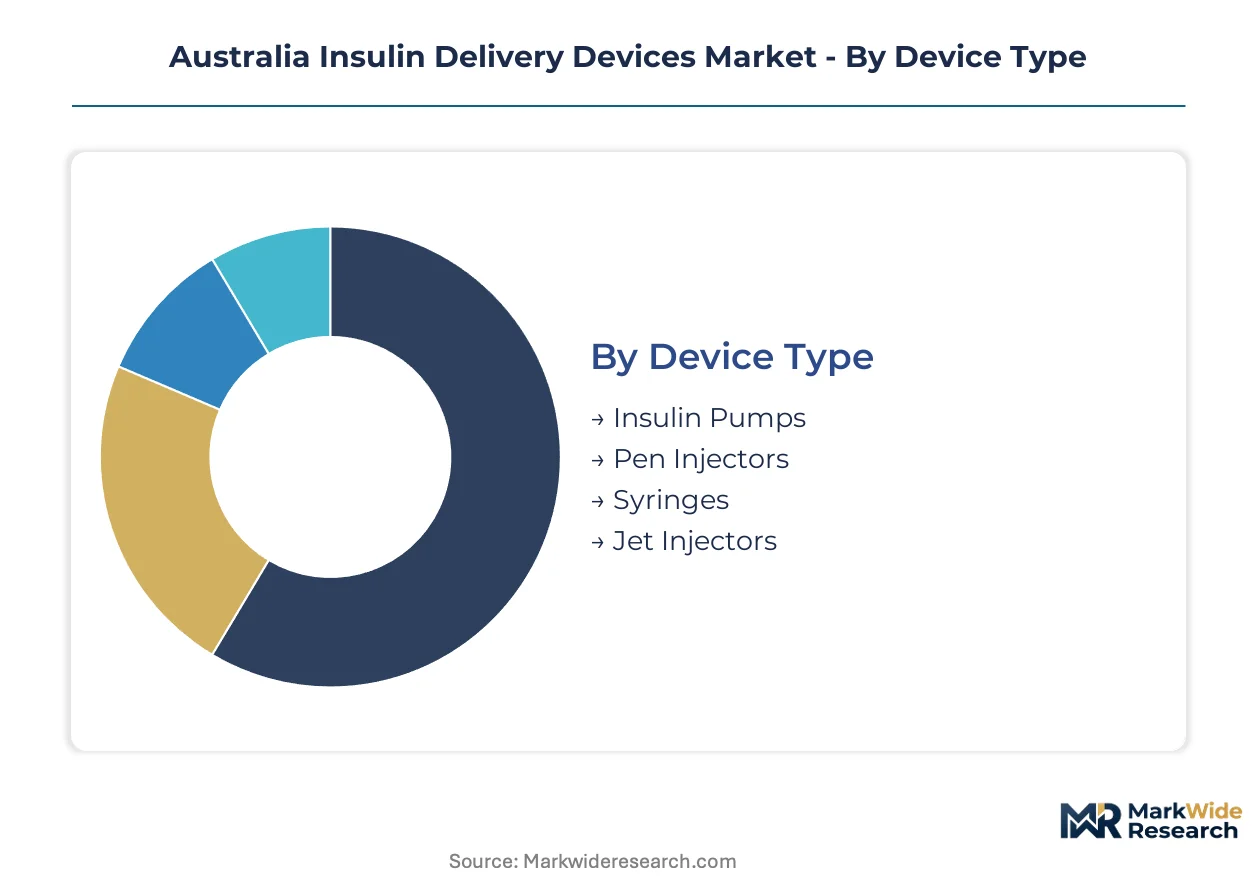
Device taxonomy in the Australian insulin delivery market determines reimbursement pathways, regulatory classification, and patient self-management capability. Segment boundaries increasingly blur as CGM-pump convergence creates hybrid categories that defy traditional hardware definitions.
Device Type:
Premium margin pools concentrate in pump systems where algorithmic automation commands reimbursement premiums, while pen injectors dominate volume throughput through Medicare familiarity.
- Insulin Pumps:Electromechanical devices delivering basal and bolus doses through subcutaneous infusion sets, typically programmed in 0.025-unit increments. Demand clusters among Type 1 diabetes patients in Victoria and New South Wales where endocrinology density supports pump initiation protocols. CGM integration is now standard for new prescriptions.
- Pen Injectors:Disposable or reusable handheld devices using 3mL insulin cartridges with dial-dose mechanisms calibrated to 1-unit or 0.5-unit precision. Pen injectors capture the largest patient population across Type 2 diabetes management in Queensland regional centers where specialist access remains limited. Medicare Part D familiarity reduces prescription friction.
- Syringes:Conventional U-100 calibrated disposable needles requiring manual dose drawing from vials. Syringes persist in cost-sensitive cohorts and institutional bulk purchasing arrangements.
- Jet Injectors:Needle-free systems using pressurized gas to aerosolize insulin through skin pores. Jet injectors serve needle-phobic patients and specific pediatric applications where injection anxiety compromises adherence.
The dominant share belongs to Pen Injectors, while Insulin Pumps is closing the gap fastest.
Administration Route:
Volume distribution across administration routes reflects physiological insulin kinetics and clinical risk tolerance for hypoglycemia.
- Subcutaneous:Tissue deposition into adipose layers via abdomen, thigh, or arm sites, enabling gradual absorption profiles that mimic physiological basal secretion. Subcutaneous delivery anchors virtually all ambulatory diabetes management across Australian homecare settings. TGA device classifications for subcutaneous hardware follow ISO 11608 needle-based injection standards.
- Intravenous:Direct bloodstream delivery reserved for acute hyperglycemic crisis management in hospital intensive care units. Intravenous insulin protocols demand continuous monitoring infrastructure unavailable outside tertiary facilities.
- Intramuscular:Rapid absorption via deltoid or thigh muscle deposition, occasionally employed for ketosis correction when intravenous access is compromised.
- Oral:Experimental and commercialized formulations bypassing hepatic first-pass metabolism through encapsulation or permeation enhancers. Oral insulin remains outside mainstream Australian prescribing guidelines pending TGA registration of viable bioavailability platforms.
Subcutaneous administration holds the installed base majority, though Intravenous maintains irreplaceable status in acute care protocols.
End User:
Care setting segmentation tracks the shift from institutional diabetes management toward patient-directed glycemic control.
- Homecare:Patient or caregiver-administered insulin in residential settings with remote clinician oversight through connected device data. Homecare expansion accelerates through CGM-pump cloud integration that permits Victorian endocrinologists to monitor regional Queensland patients. TGA guidance documents for home-use software-as-medical-device create registration clarity.
- Hospitals:Inpatient glycemic management protocols covering perioperative glucose control and DKA stabilization. Hospital procurement concentrates in New South Wales and Victoria health district tender processes that bundle infusion pumps with enterprise monitoring systems.
- Diabetes Clinics:Outpatient specialist facilities providing device initiation training and algorithm optimization. Diabetes clinics in metropolitan Sydney and Melbourne anchor patient onboarding for complex automated delivery systems.
- Endocrinology Centers:Tertiary referral hubs managing refractory cases and participating in closed-loop clinical trials. Endocrinology centers generate real-world evidence that supports TGA breakthrough device designations.
Homecare has overtaken Hospitals as the primary volume channel, with Endocrinology Centers generating the highest per-patient device revenue.
Technology:
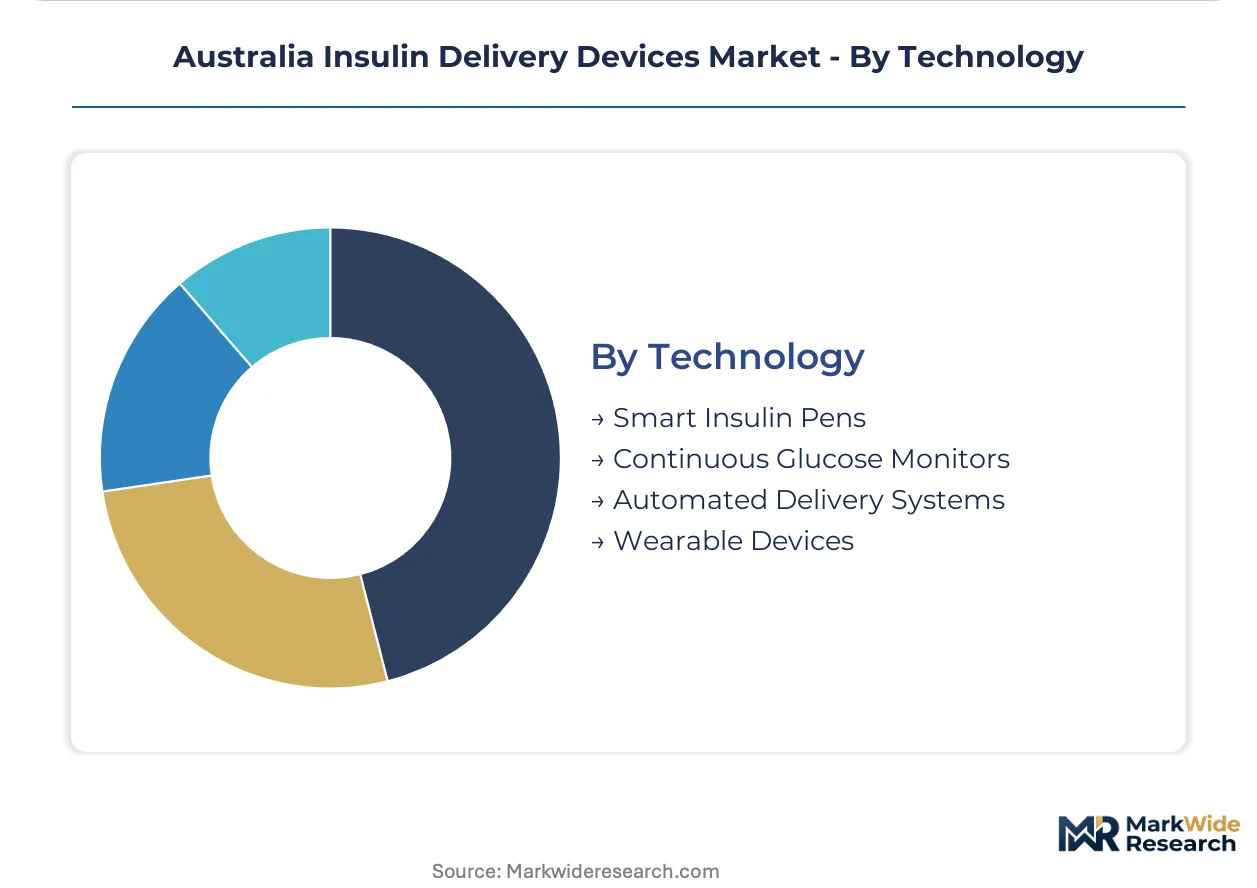
Technology tiering separates data-integrated systems commanding private insurance premiums from legacy hardware approaching commodity status.
- Automated Delivery Systems:Closed-loop architectures combining CGM input, predictive algorithms, and pump modulation to reduce hypoglycemic burden without patient intervention. Automated systems represent the steepest expansion trajectory as TGA priority review pathways compress registration timelines for algorithm-updatable devices. Medtronic and emerging competitors target this category for margin defense.
- Smart Insulin Pens:Bluetooth-enabled dose capture with timestamp and carbohydrate logging transmitted to clinician dashboards. Smart pens penetrate Type 2 populations in Western Australia and South Australia where pump therapy remains clinically unnecessary but adherence monitoring adds value.
- Continuous Glucose Monitors:Interstitial glucose sensing with predictive alerts, increasingly bundled with pump systems rather than sold standalone. CGM sensor supply constraints from contract manufacturing concentration periodically disrupt Australian distributor allocations.
- Wearable Devices:Non-invasive glucose monitoring patches and insulin micro-delivery wearables in early commercialization. Wearable categories face TGA software validation burdens for algorithm-updatable firmware under IEC 62304 requirements.
Automated Delivery Systems captures the premium tier, while Smart Insulin Pens is expanding most quickly among Type 2 managed care populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's insulin delivery device trade flows reflect concentrated import dependence on US and European manufacturers, with limited domestic production capacity. New South Wales and Victoria absorb the majority of inbound shipments through specialized medical device distributors. State-level procurement frameworks create distinct access conditions across jurisdictions.
New South Wales
Demand concentrates in metropolitan Sydney's tertiary hospital networks where endocrinology departments drive automated delivery system adoption. The state's Medical Device Fund subsidizes CGM-pump integration for pediatric Type 1 patients. Sydney's Royal Prince Alfred Hospital anchors clinical trial recruitment for closed-loop algorithm validation.
Victoria
Melbourne's concentration of private endocrinology practices generates premium-tier device prescriptions exceeding national per-capita averages. TGA's Melbourne office maintains proximity to major sponsor organizations, accelerating registration timelines for breakthrough designations. The Alfred Hospital's diabetes research unit produces real-world evidence supporting reimbursement submissions.
Queensland
Regional specialist deserts in Far North and Central Queensland create telemedicine-dependent device distribution models. The state's Diabetes Strategy 2024-2030 allocates funding for remote CGM connectivity infrastructure. Brisbane's Princess Alexandra Hospital coordinates statewide pump initiation training through hub-and-spoke specialist networks.
Western Australia
Perth's geographic isolation from eastern manufacturing centers extends supply lead times for sensor-dependent systems. The Western Australian Country Health Service subsidizes travel costs for regional patients accessing device optimization at metropolitan clinics. Fremantle Hospital's endocrinology unit manages the highest per-capita insulin pump population outside Victoria and New South Wales.
South Australia
Adelaide's compact specialist network enables rapid device trial-to-prescription pathways for emerging technologies. The state's Transforming Health program bundles diabetes device procurement across public hospital networks. Flinders Medical Centre participates in multi-site algorithm personalization studies generating Australian-specific metabolic data.
Australia Insulin Delivery Devices Market Vendor Landscape
Concentration sits with integrated diabetes care conglomerates and specialized pump manufacturers that anchor distinct technology tiers. Market structure exhibits dual-leadership dynamics where one archetype commands algorithmic closed-loop development while another dominates disposable patch pump form factors. Strategic archetypes include full-portfolio diabetes companies, dedicated pump engineering specialists, and pen injector traditionalists. Competitive moves center on CGM-pump bundle contracting and TGA priority review pathway exploitation.
Within the integrated portfolio tier, Novo Nordisk and Sanofi represent archetypes of pharmaceutical-origin diversification into connected delivery hardware. Among dedicated pump engineering specialists, Medtronic exemplifies the algorithm-intensive closed-loop positioning, while Insulet Corporation occupies a position within the tubeless disposable architecture segment. These three companies anchor distinct competitive vectors that structure vendor selection criteria across Australian reimbursement channels.
| Leading Market Players |
|---|
| Novo Nordisk |
| Medtronic |
| Insulet Corporation |
| Ypsomed |
| Eli Lilly and Company |
| Sanofi |
| Becton Dickinson |
| Tandem Diabetes Care |
| Embecta |
| Others |
Supply Flow & Price Mechanics
Single-source manufacturing concentration for CGM sensors and infusion set polymers anchors both supply vulnerability and price floor rigidity across the Australian insulin delivery device market. Scale economies at contract manufacturers in Ireland and Malaysia translate directly into landed cost structures that Australian distributors cannot arbitrage through alternative sourcing.
Pricing Analysis
Private health fund subscribers anchor subscription-based pricing structures that bundle pump hardware, CGM sensors, and algorithm updates into monthly fees. Price differentiation rests on TGA breakthrough device designation tier and remote monitoring service bundling. Cost compression in the standard pump tier is intensifying because Medicare reimbursement familiarity limits premium capture for non-connected devices. Uninsured Type 1 diabetes patients in Queensland and Western Australia exhibit highest price sensitivity, while employer-sponsored plans in Victoria demonstrate lowest sensitivity due to pre-tax benefit structures.
Supply Chain Analysis
Port congestion at Sydney and Melbourne container terminals intermittently extends inbound lead times for sensor-dependent systems arriving from US West Coast and European manufacturing hubs. Supply concentrates in Ireland, Malaysia, and the United States for precision-molded infusion sets and electromechanical pump assemblies. Raw material dependencies center on medical-grade polymers, lithium-ion cells, and glucose oxidase enzyme formulations. Single-source vulnerability in contract CGM sensor manufacturing creates allocation risk when global demand spikes. Distribution runs through specialized medical device distributors holding TGA sponsor licenses for post-market accountability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australian insulin delivery device market sits in early-cycle expansion as Medicare reimbursement for CGM-pump integration penetrates Type 1 populations beyond traditional metropolitan strongholds. Remote monitoring infrastructure investment accelerates homecare adoption in previously underserved regional jurisdictions.
For Market Incumbents: Fortify algorithm development pipelines against emerging closed-loop competitors by deepening physiological modeling partnerships with Australian universities. Secure multi-year CGM-pump bundle contracts with New South Wales and Victoria health systems to create switching costs that delay patient migration to tubeless patch pump alternatives. TGA priority review pathway exploitation remains critical for maintaining registration timeline advantages.
For New Entrants and Emerging Players: TGA breakthrough device designation fast-track offers expedited market entry for closed-loop algorithms demonstrating superior hypoglycemic reduction in Australian-specific metabolic studies. Target Western Australia and Queensland regional centers where telemedicine-integrated distribution models reduce incumbent field service advantages. Partner with Princess Alexandra Hospital's hub-and-spoke training network to accelerate prescriber familiarity without establishing proprietary clinical education infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated delivery system vendors with algorithm-update subscription attach rates exceeding hardware replacement cycles. Long-term viability over the coming decade hinges on software-as-medical-device regulatory navigation capabilities and CGM sensor supply contract security. Acquisition targets should demonstrate TGA sponsor relationships and existing private health fund contracting. The signal to watch is TGA adverse event reporting volume trends for algorithm-updatable devices, which indicate real-world performance validation maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| CGM-Pump Bundle Contracting | Consolidates vendor relationships and creates switching costs across Victorian and New South Wales health systems. |
| TGA Breakthrough Device Designation | Compresses registration timelines for closed-loop algorithms and accelerates commercialization against incumbent portfolios. |
| Telemedicine-Integrated Distribution | Reduces geography-dependent care barriers in Queensland and Western Australia regional specialist deserts. |
| Algorithm Personalization R&D Partnership | Generates Australian-specific metabolic data that supports reimbursement submissions and clinical differentiation. |
| Subscription-Based Device Provisioning | Spreads upfront cost burdens for patients while locking recurring revenue streams through private insurance channels. |
Methodological Framework
Cross-validation between hospital procurement database analysis and clinician interview findings anchors the qualitative findings on device preference drivers and reimbursement access patterns. Primary interviews with endocrinologists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers were combined with secondary validation from TGA registration filings, Medicare Benefits Schedule data, private health fund policy documents, and state-level diabetes strategy publications. Bottom-up patient population modeling and top-down manufacturer shipment analysis were triangulated to establish market sizing.
Sensitivity analysis across reimbursement policy scenarios and CGM sensor supply disruption cases tests forecast robustness over the projection horizon. Segmentation dimensions modeled include device type, technology tier, end-user setting, and state-level regulatory cluster. CAGRs were derived from trend extrapolation of historical adoption curves adjusted for Medicare policy inflection points. Forecast inputs incorporate TGA priority review pathway throughput rates and private health fund subscription pilot expansion trajectories.
Decision-makers should treat outputs as directional under assumptions of stable Medicare reimbursement policy and uninterrupted CGM sensor manufacturing capacity; material deviation would warrant model refresh. Specific risk factors that could revise forecasts include TGA software validation timeline extensions, international sensor supply allocation shifts, and state-level diabetes program funding reallocations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital X-Ray Devices Market
Medical Devices
Minimally Invasive Deformity Correction System Market
Medical Devices
Cyberknife Technology Market
Medical Devices
Cardiac Implants Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Global Disability Devices Market
Medical Devices
Gastric Bands Market
Medical Devices
Thoracolumbar Spine Devices Market
Medical Devices
Spain Artificial Organs and Bionic Implants Market
Medical Devices
Canada General Surgical Devices Market
Medical Devices
Japan Electric Wheelchair Market
Medical Devices
Biologic Injectors Market
Medical Devices
China Minimally Invasive Surgery Devices Market
Medical Devices
Global Medical Footwear Market
Medical Devices
Asthma Device Market
Medical Devices
Corneal Cross Linking Devices Market