
 Global Connected Medical Devices Market | 2026-2036
Global Connected Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Connected Medical Devices Market Foresight
Silicon is decoupling from legacy substrate designs in connected medical device manufacturing as gallium nitride and advanced polymers reduce power consumption and thermal footprint. Medtronic leverages vertical integration across sensor fabrication and cloud analytics to sustain competitive positioning in implantable connectivity. Abbott Laboratories anchors its portfolio in glucose monitoring systems that dominate wearable biosensor categories. Philips Healthcare competes through hospital-grade stationary monitoring platforms that extend into home care channels.
Connected medical devices are electronic instruments equipped with wireless communication modules, embedded sensors, and software interfaces that transmit physiological data to clinical decision support systems, typically operating on low-energy protocols with FDA Class II or CE-marked safety certifications. Their primary commercial purpose is enabling continuous data flow between patients and care teams outside traditional facility settings. Wearable devices capture the largest addressable base as consumer familiarity with wrist-worn biosensors expands into medically regulated applications. Remote patient monitoring generates the fastest-growing revenue pool as payors in the United States and Germany introduce reimbursement codes for continuous physiologic surveillance. Cellular-enabled devices command premium positioning where Wi-Fi infrastructure remains unreliable in rural home healthcare settings.
FDA cybersecurity premarket guidance, EU MDR Annex I software requirements, and HIPAA technical safeguards collectively elevate compliance costs for device manufacturers seeking multi-region market access. The EU AI Act introduces additional conformity obligations for connected devices employing machine-learning diagnostic algorithms. Stakeholders must monitor evolving reimbursement parity between remote monitoring and in-person care delivery across national health systems.
Market Dynamics
Reimbursement parity between remote monitoring and in-person care delivery is restructuring procurement authority across national health systems. Payers in the United States and Germany now authorize continuous physiologic surveillance at rates comparable to facility-based diagnostics, shifting volume toward home healthcare channels.
Growth Catalysts
- Cellular connectivity protocols:LTE-M and NB-IoT modules enable reliable data transmission in rural settings where Wi-Fi infrastructure remains sparse. Home healthcare providers in the United States and Japan are standardizing these modules for cardiac and respiratory monitors.
- FDA cybersecurity premarket guidance:The 2023 guidance mandates software bill of materials and vulnerability disclosure programs for wireless-enabled devices. Manufacturers achieving compliance gain accelerated review timelines and preferred supplier status with hospital procurement.
- Germany's DiGA framework:The Digital Health Applications fast-track reimbursement pathway for prescribed connected devices creates predictable revenue streams. Diabetes management and hypertension monitoring applications dominate approved submissions.
Market Restraints
- Gallium nitride substrate costs:Power-efficient RF components for miniaturized implants depend on specialized foundry capacity concentrated in Taiwan and South Korea. Wafer pricing volatility constrains margin expansion for mid-tier device manufacturers.
- EU MDR Annex I software requirements:The 2021 regulation mandates clinical evidence for algorithm-driven diagnostic functions. Small manufacturers face documentation burdens that extend time-to-market by 18-24 months relative to legacy MDD pathways.
- HIPAA technical safeguard complexity:Encryption standards for protected health information in transit create architectural constraints. Device makers must maintain separate firmware branches for US and European deployments, fragmenting engineering resources.
Strategic Opportunities
- India's PLI scheme for medical electronics:Production-linked incentives cover 5-20% of incremental sales value for domestic manufacturing of high-value connected devices. Multinational firms are qualifying Chennai and Hyderabad facilities for export production.
- Continuous glucose monitoring in Type 2 populations:Wearable biosensor adoption extends beyond insulin-dependent patients to prediabetic and gestational cohorts. Reimbursement pilots in Japan and the Netherlands validate expanded addressable bases.
- Edge-AI inference on-device:Integration of low-power neural processing units with vital sign sensors reduces cloud dependency and latency. Cardiac arrhythmia detection and fall prediction applications are first movers.
Industry Challenges
- Embedded systems security engineering talent:Firmware architects with FDA cybersecurity submission experience command premium compensation. Contract development organizations in Eastern Europe and Vietnam are building specialized practices to address scarcity.
- Multi-jurisdiction certification parallelism:Simultaneous FDA 510(k), CE MDR, and PMDA Shonin submissions require divergent clinical evidence packages. Program management complexity scales non-linearly with target market count.
- Legacy hospital IT integration:HL7 FHIR interoperability with proprietary electronic health record systems demands custom interface development. Epic and Cerner deployments require site-specific validation protocols that extend implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Connected Medical Devices Market |
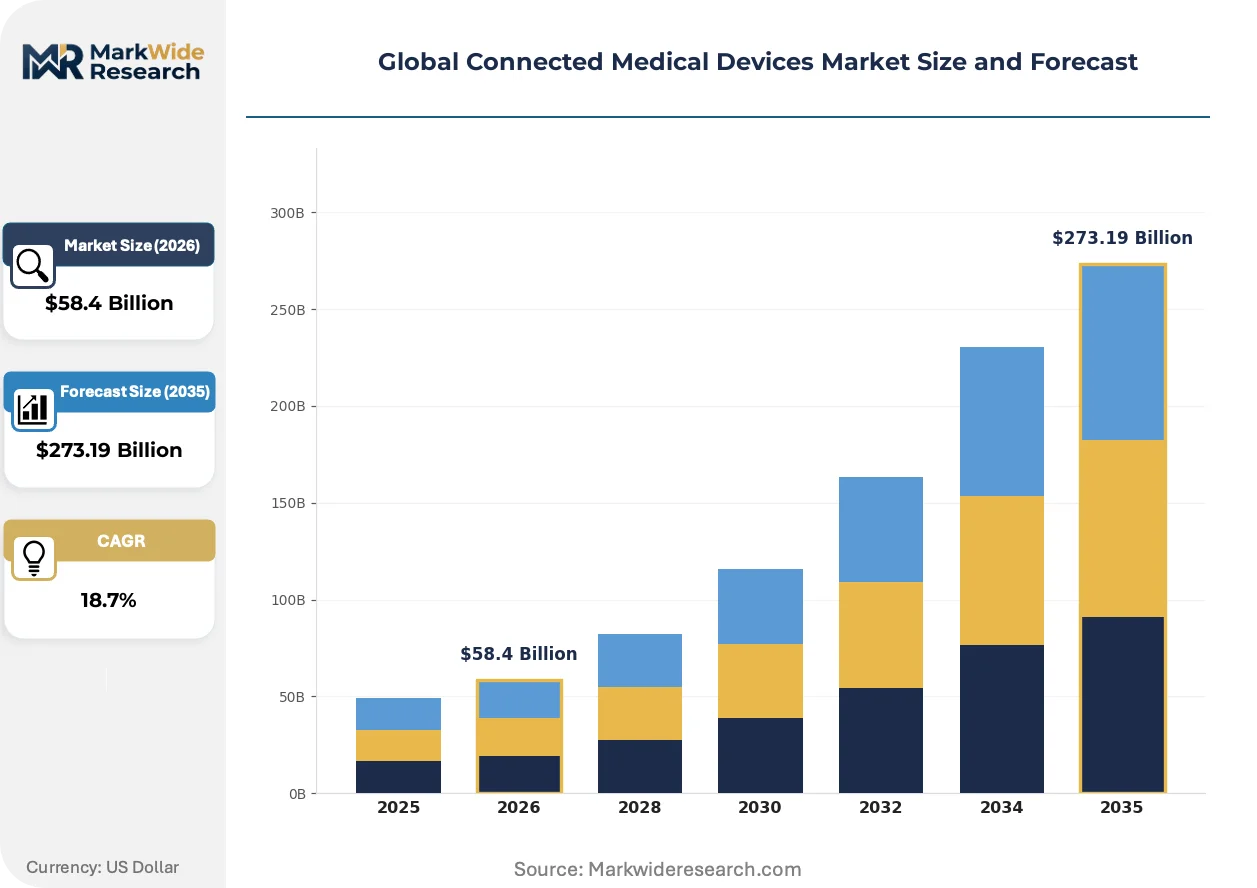
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $273.19 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Implantable Devices, Stationary Monitoring Systems, Portable Diagnostic Devices Technology: Bluetooth, Wi-Fi, Cellular, Zigbee, NFC Application: Remote Patient Monitoring, Chronic Disease Management, Elderly Care, Fitness Tracking, Postoperative Recovery End User: Hospitals, Ambulatory Care Centers, Home Healthcare Providers, Research Institutes |
| Companies Covered | Medtronic, Abbott Laboratories, Philips Healthcare, GE HealthCare, Siemens Healthineers, Johnson & Johnson MedTech, Boston Scientific, Dexcom, Roche Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Connected Medical Devices Market Shifts & Advancements
Silicon substrate architectures are fragmenting as compound semiconductors and advanced polymers enable new form factors. Device manufacturers are reconfiguring supply relationships around materials science capabilities rather than legacy foundry partnerships.
GaN-on-SiC RF front-ends are modularizing power amplifier designs for implantable connectivity modules. Cardiac rhythm management device makers are adopting these substrates to reduce thermal dissipation by 40% while maintaining telemetry range. The shift compresses battery volume requirements and enables smaller leadless pacemaker geometries.
EU AI Act conformity obligations are reshaping algorithm governance for diagnostic-enabled devices. Machine-learning classifiers for arrhythmia detection or diabetic retinopathy screening now require technical documentation, risk management systems, and human oversight protocols. Manufacturers targeting European market access are establishing algorithm change control procedures that exceed FDA software as medical device guidance.
Hospital procurement departments are consolidating vendor panels around integrated platform providers. Standalone device makers face exclusion from IDN-level contracts unless they demonstrate interoperability with established ecosystem players. The United States exhibits the most pronounced concentration, with ten health systems controlling over 25% of connected device purchasing volume.
Global Connected Medical Devices Market Segmentation
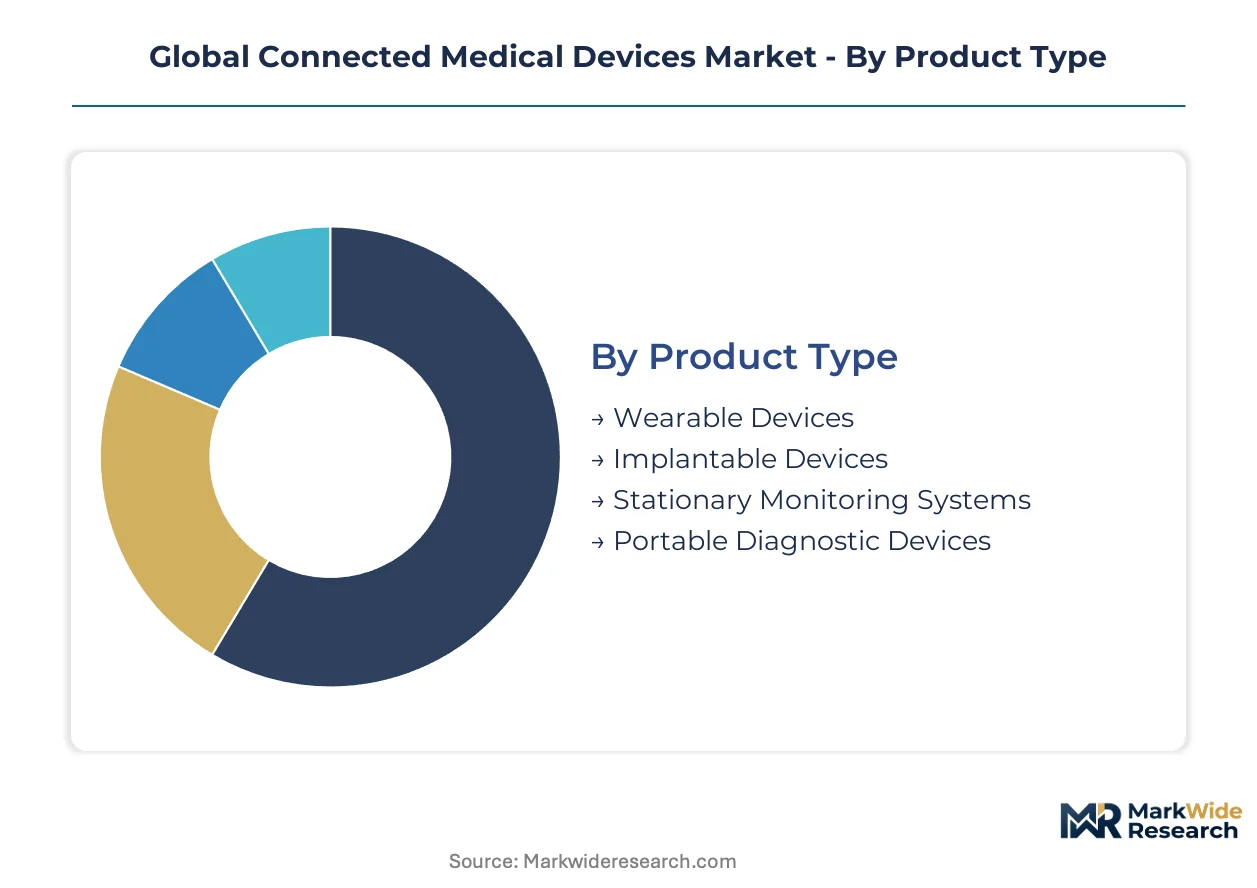
Segmentation in connected medical devices reveals how procurement authority, reimbursement pathways, and technical specifications diverge across care settings. Manufacturers must align hardware configurations, connectivity protocols, and regulatory documentation to the distinct operational constraints of each buyer category.
Product Type:
Buyer differentiation hinges on care setting mobility requirements and patient acuity levels.
- Wearable Devices:Wrist-worn and patch-based biosensors integrate photoplethysmography and accelerometry for continuous vital sign capture. Demand concentrates among home healthcare providers in Germany and the United States where DiGA and RPM reimbursement codes validate prescription workflows. Battery life and waterproofing specifications dominate procurement criteria.
- Implantable Devices:Leadless pacemakers, neurostimulators, and continuous glucose monitors embed subcutaneous sensors with proprietary RF telemetry. Cardiac rhythm management applications in Japan and the United States absorb premium unit economics as PMDA Shonin and FDA PMA pathways mature for long-acting implants. Gallium nitride substrates reduce thermal dissipation constraints.
- Stationary Monitoring Systems:Bedside multi-parameter monitors serve ICU and step-down units with wired and wireless hybrid architectures.
- Portable Diagnostic Devices:Handheld ultrasound, ECG, and pulse oximetry units enable point-of-care triage in ambulatory settings.
Volume sits with stationary systems in hospital procurement; growth tilts toward wearables as reimbursement parity extends beyond acute care.
Technology:
Connectivity protocol selection tracks infrastructure reliability and data throughput requirements across deployment geographies.
- Cellular:LTE-M and NB-IoT modules deliver carrier-grade reliability in rural home healthcare settings where Wi-Fi coverage gaps persist. United States and Japanese providers standardize these for cardiac and respiratory monitors as T-Mobile and NTT DoCoMo expand low-power wide-area networks. Module certification with FCC and TELEC accelerates time-to-market.
- Bluetooth:Low-energy 5.3 protocols dominate wearable-to-smartphone pairing for consumer-facing health applications. Smartphone penetration rates in urban India and Brazil shape addressable market calculations for device makers targeting direct-to-consumer channels. Interoperability with iOS and Android health stacks reduces development overhead.
- Wi-Fi:Hospital-grade 802.11ax supports high-bandwidth telemetry for multi-parameter bedside monitors.
- Zigbee:Mesh networking protocols serve in-facility asset tracking and environmental sensing applications.
- NFC:Near-field pairing enables rapid device onboarding and medication authentication workflows.
Bluetooth claims installed base dominance; cellular climbs fastest as rural home healthcare reimbursement frameworks mature.
Application:
Clinical use case segmentation determines regulatory pathway intensity and evidence generation requirements.
- Remote Patient Monitoring:Continuous physiologic surveillance platforms transmit blood pressure, glucose, and SpO2 data to cloud-based clinical decision support systems. United States Medicare and German statutory health insurance reimbursement parity drives procurement volume as CMS and G-BA expand eligible condition lists. FDA 510(k) and CE MDR submissions require prospective validation studies.
- Chronic Disease Management:Integrated platforms combine connected inhalers, insulin pens, and blood pressure cuffs for diabetes, COPD, and hypertension cohorts. Japan's Ministry of Health, Labour and Welfare pilots validate expanded Type 2 diabetes continuous glucose monitoring coverage. Algorithm-driven dosing recommendations trigger EU AI Act conformity obligations.
- Elderly Care:Fall detection and activity monitoring systems serve aging-in-place populations.
- Fitness Tracking:Consumer-grade wearables operate below medical device thresholds in most jurisdictions.
- Postoperative Recovery:Wound monitoring and mobility tracking devices reduce readmission risk.
Chronic disease management captures current revenue concentration; remote patient monitoring exhibits the steepest expansion trajectory as payor frameworks standardize.
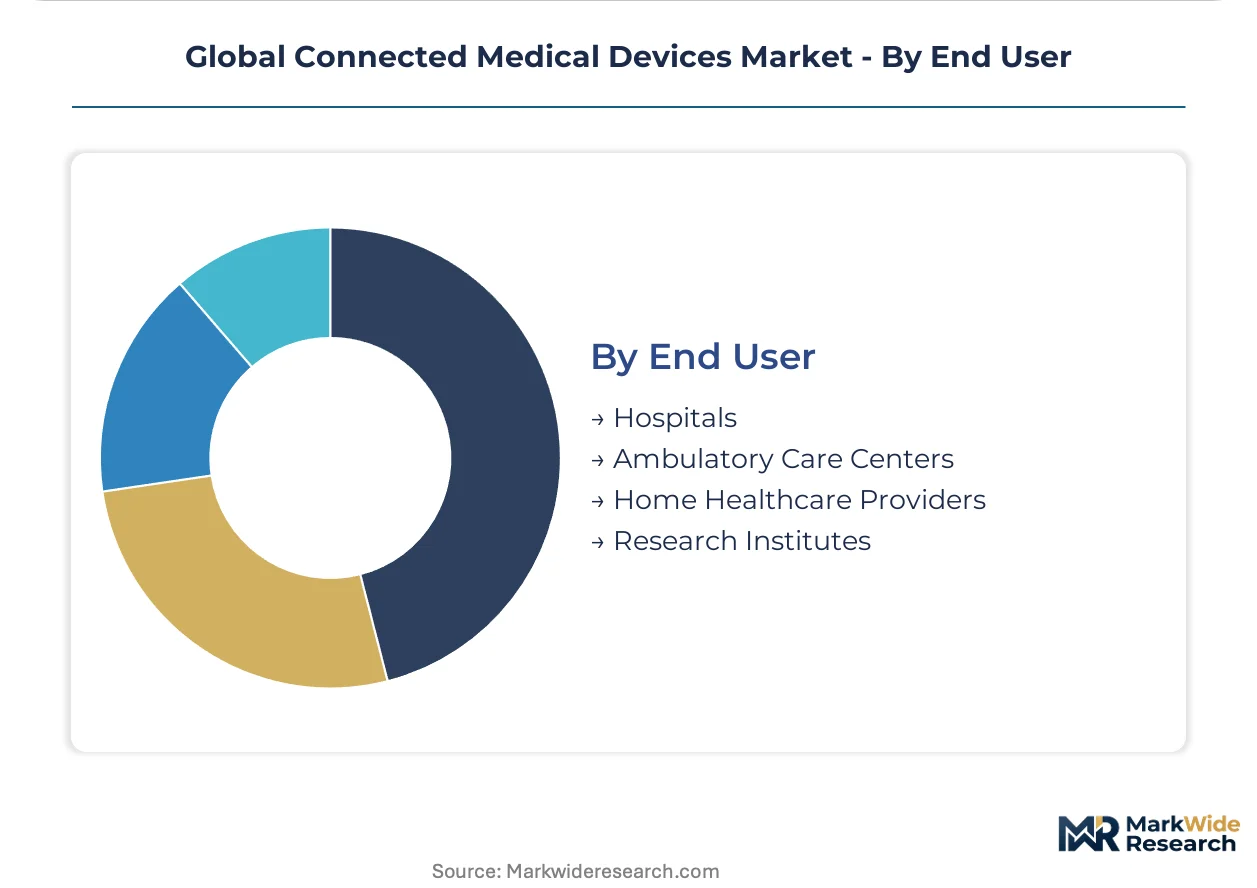
End User:
Procurement sophistication and integration complexity vary sharply across institutional buyer types.
- Home Healthcare Providers:Distributed nursing agencies and hospice operators deploy connected devices for post-acute and palliative care. United States Medicare Advantage plans and German DiGA prescribing physicians drive demand as risk-bearing entities absorb episode-of-care accountability. Logistics networks for device provisioning and retrieval constrain operational scaling.
- Hospitals:Integrated delivery networks consolidate vendor panels around platform providers with Epic and Cerner interoperability. Ten United States health systems control over one-quarter of connected device purchasing volume. Procurement departments demand HL7 FHIR compliance and cybersecurity attestation.
- Ambulatory Care Centers:Specialist clinics and urgent care facilities prioritize portable diagnostic form factors.
- Research Institutes:Academic medical centers and contract research organizations source devices for clinical trial decentralization.
Hospitals anchor procurement volume; home healthcare providers gain share fastest as reimbursement shifts toward site-neutral payment models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States, Germany, and Japan absorb the dominant share of connected medical device procurement as reimbursement frameworks for remote monitoring mature in these markets. Hospital procurement consolidation and government fast-track pathways are restructuring competitive access across each geography.
United States
Medicare Advantage plans and commercial payors now reimburse remote patient monitoring at parity with in-person diagnostics, driving volume toward home healthcare channels. FDA cybersecurity premarket guidance mandates software bill of materials and vulnerability disclosure programs for wireless-enabled devices. Minneapolis and Boston anchor cardiac rhythm management and glucose monitoring development clusters where Medtronic and Abbott Laboratories maintain captive manufacturing.
Germany
Statutory health insurance funds authorize continuous physiologic surveillance under the DiGA fast-track reimbursement pathway, creating predictable revenue streams for prescribed connected devices. EU MDR Annex I software requirements mandate clinical evidence for algorithm-driven diagnostic functions, extending documentation burdens for manufacturers. Berlin and Munich concentrate digital health application developers and notified body expertise serving European market access.
Japan
PMDA Shonin pathways for long-acting implants mature as the Ministry of Health, Labour and Welfare pilots expanded continuous glucose monitoring coverage for Type 2 diabetes populations. METI standards for medical device cybersecurity align with international harmonization efforts. Tokyo and Osaka host cardiac rhythm management and neurostimulator development facilities serving domestic and export markets.
India
Production-linked incentives under the PLI scheme for medical electronics cover 5-20 percent of incremental sales value for domestic manufacturing of high-value connected devices. CDSCO medical device rules tighten registration requirements for wireless-enabled instruments. Chennai and Hyderabad facilities qualify for export production as multinational firms diversify supply chains beyond East Asian concentration.
South Korea
MFDS accelerates review timelines for connected devices demonstrating compliance with international cybersecurity standards. National health insurance reimbursement for remote monitoring expands eligible condition lists beyond diabetes and hypertension. Seoul Capital Area and Busan-Ulsan clusters concentrate RF component foundry capacity and medical device contract manufacturing serving regional export demand.
Global Connected Medical Devices Market Competitive Landscape
Strategic partnerships dominate the current landscape as device manufacturers seek interoperability with electronic health record platforms and cloud analytics providers. The market exhibits tiered concentration with integrated platform providers controlling hospital procurement panels and specialized players occupying wearable and implantable niches. Three archetypes define positioning: diversified conglomerates with vertical sensor-to-cloud control, pure-play connectivity specialists, and hospital-grade stationary system incumbents extending into home channels. M&A activity and technology licensing agreements represent the primary competitive moves as firms address embedded systems security engineering scarcity.
Among diversified medical technology conglomerates, Medtronic, Abbott Laboratories, and Philips Healthcare exemplify distinct strategic archetypes. Medtronic occupies a position representing vertical integration across sensor fabrication and cloud analytics for implantable connectivity. Abbott Laboratories anchors the wearable biosensor category through glucose monitoring systems that dominate prescription workflows. Philips Healthcare sits within the hospital-grade stationary monitoring tier, competing through bedside multi-parameter platforms that extend into reimbursed home care channels. Each firm represents a different pathway to procurement authority as health systems consolidate vendor panels around integrated ecosystem providers.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Philips Healthcare |
| GE HealthCare |
| Siemens Healthineers |
| Johnson & Johnson MedTech |
| Boston Scientific |
| Dexcom |
| Roche Diagnostics |
| Others |
Supply & Pricing Matrix
Gallium nitride wafer costs cascade through three pricing tiers as substrate scarcity from Taiwan and South Korea foundries compresses margins for mid-tier cardiac implant manufacturers while premium players absorb thermal efficiency gains.
Pricing Analysis
Volume concentrates in economy-tier Bluetooth-enabled wearables sold through direct-to-consumer channels in India and Brazil, while margins concentrate in cellular-enabled cardiac monitors prescribed under United States Medicare Advantage and German DiGA reimbursement. Price differentiation hinges on FDA cybersecurity attestation and EU MDR Annex I software certification tiers. Pricing pressure stems from gallium nitride substrate volatility constraining RF component costs. Home healthcare providers in rural United States markets exhibit highest price sensitivity; integrated delivery networks controlling hospital procurement panels exhibit lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea foundries supplying gallium nitride-on-silicon-carbide substrates for implantable RF modules. Raw material dependencies extend to advanced polymers for biocompatible encapsulation and lithium-thionyl chloride cells for long-acting power. Supply chain risk centers on regulatory restriction as EU AI Act conformity obligations fragment firmware development resources across jurisdictions. Distribution runs through hospital procurement departments consolidating vendor panels and home healthcare logistics networks managing device provisioning cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA cybersecurity premarket guidance and EU MDR Annex I software requirements erect barrier-to-entry moats favoring manufacturers with captive regulatory affairs capabilities and multi-jurisdiction submission experience.
For Market Incumbents: Acquire embedded systems security engineering talent pools in Eastern Europe and Vietnam before contract development organizations exhaust qualified firmware architects. Consolidate algorithm change control procedures exceeding FDA software as medical device guidance to preempt EU AI Act conformity obligations. Defend against pure-play connectivity specialists by deepening hospital system partnerships with Epic and Cerner interoperability validation. For New Entrants and Emerging Players: Germany's DiGA framework in the statutory health insurance system opens a window for prescribed diabetes management and hypertension monitoring applications with streamlined reimbursement. Target continuous glucose monitoring expansion into Type 2 diabetes populations in Japan and the Netherlands where reimbursement pilots validate addressable base extension. Pursue edge-AI inference on-device for cardiac arrhythmia detection as a differentiated go-to-market angle reducing cloud dependency. For Investors and Strategic Acquirers: First FDA cybersecurity premarket guidance compliance announcements from mid-tier manufacturers are the leading indicator that procurement authority is shifting toward preferred supplier status with hospital systems. Frame long-term viability around algorithm governance capabilities and multi-jurisdiction certification parallelism rather than hardware innovation cycles. Target acquisition profiles combining vertical sensor fabrication with cloud analytics integration. Watch for India's PLI scheme qualification announcements as supply chain diversification signals.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Premarket Submission | Accelerated review timelines unlock preferred supplier status with United States hospital procurement panels. |
| CE MDR Annex I Software Certification | Clinical evidence packages for algorithm-driven diagnostics enable European market access expansion. |
| Hospital System Partnership | Epic and Cerner interoperability validation secures inclusion in consolidated vendor panels. |
| Software Companion Development | HL7 FHIR-compliant clinical decision support systems differentiate stationary monitoring platforms. |
| Reimbursement Strategy | Medicare Advantage and DiGA pathway alignment captures site-neutral payment model shifts. |
Research Methodology
Document review covered FDA 510(k) and PMA filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and GPO contracts, complemented by interviews with hospital purchasing committee members, biomedical engineers, regulatory affairs leads at device manufacturers, and home healthcare logistics operators. Secondary validation drew from PMDA Shonin submission records, CDSCO medical device registration data, and production-linked incentive scheme announcements. Bottom-up unit economics modeling and top-down reimbursement framework analysis were triangulated against procurement volume estimates.
Cross-referencing historical reimbursement code expansion patterns against clinician panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product mobility tier, connectivity protocol, clinical application intensity, and procurement authority concentration. CAGRs were derived from reimbursement parity progression curves and foundry capacity expansion schedules. Edge-AI inference adoption rates and cellular module certification timelines served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for gallium nitride substrate migration; alternative pathways for silicon-on-insulator RF architectures would alter the outlook for implantable miniaturization. Forecasts reflect assumptions about DiGA and Medicare reimbursement code expansion continuity. Cybersecurity guidance revision, foundry supply disruption, or algorithm governance requirement tightening could revise trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Tympanostomy Products Market
Medical Devices
Implantable Defibrillators Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Oxygen Delivery Systems Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Global Gastric Balloons Market
Medical Devices
Italy Aesthetic Devices Market
Medical Devices
Brazil Angioplasty Devices Market
Medical Devices
Augmented Bone Graft Market
Medical Devices
Global Hysteroscope Market
Medical Devices
Craniomaxillofacial Plate and Installation Tools Market
Medical Devices
Joint Reconstruction Devices Market
Medical Devices
Global Automatic Pill Dispenser Market
Medical Devices
Indwelling Catheter Market
Medical Devices
Australia Minimally Invasive Surgery Devices Market