
 Europe Smart Bed Market | 2026-2036
Europe Smart Bed Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Bed Market Foresight
Modular bed configurations with detachable sensor arrays and upgradeable connectivity modules is broadening buyer choice across European procurement channels. Stryker Corporation leverages its vertical integration into mattress and frame manufacturing to sustain margin control across hospital networks. Stiegelmeyer GmbH & Co. KG anchors its position through specialized German engineering focused on bariatric and intensive-care configurations. Hill-Rom Holdings, Inc. differentiates via connectivity protocols that integrate with existing hospital IT infrastructure.
A smart bed integrates electromechanical actuators, pressure-mapping sensors, and wireless communication modules into an adjustable sleeping platform designed for health monitoring, therapeutic positioning, and remote patient management. Adjustable beds and electric beds command the dominant share of product-type revenue as clinical settings prioritize motorized positioning for pressure-ulcer prevention and respiratory support. Sleep-tracking and smart-home-integration technologies represent the fastest-expanding technology segments, though margin pools remain concentrated in temperature-control systems where component standardization lowers production costs.
The EU Medical Device Regulation and CE marking requirements enforced by national competent authorities shape product-development timelines and market-access barriers for connected sleep platforms. Germany's KBA-equivalent medical device regulator and France's ANSM impose clinical-evaluation standards that filter out uncertified entrants. Stakeholders must monitor evolving interoperability mandates under the EU AI Act as algorithmic health-analytics capabilities expand beyond passive monitoring into diagnostic support functions.
Market Dynamics
The EU Medical Device Regulation is compressing product-development timelines and filtering market entrants, while hospital procurement consolidation across France, Germany, and the United Kingdom concentrates purchasing power into fewer contract frameworks.
Growth Catalysts
- Hospital modernization programs:France's Plan Hôpital 2030 and Germany's Krankenhauszukunftsgesetz allocate dedicated capital streams for connected patient-monitoring infrastructure, accelerating replacement cycles in acute-care settings.
- REACH compliance for sensor materials:Manufacturers achieving full substance-registration transparency for pressure-mapping foams and actuator housings gain preferential access to public-tender channels in Nordic procurement consortiums.
- Pressure-ulcer prevention protocols:Clinical guidelines from the European Pressure Ulcer Advisory Panel mandate motorized repositioning capabilities, embedding smart-bed functionality into standard-of-care requirements.
Market Restraints
- CE marking clinical-evaluation costs:The EU MDR's expanded documentation requirements for Class IIa connected devices impose six-figure certification burdens that disadvantage mid-tier manufacturers without dedicated regulatory affairs functions.
- Semiconductor supply concentration:Dependency on Taiwanese foundries for wireless-communication modules creates lead-time volatility that disturbs just-in-time assembly schedules for German and Polish bed manufacturers.
- Manual bed substitution in price-sensitive channels:Basic electric beds without sensor integration retain 40% cost advantages in long-term care facilities operating under fixed reimbursement rates.
Strategic Opportunities
- Spain and Italy post-acute expansion:Underpenetrated rehabilitation-center networks in Madrid, Barcelona, Milan, and Rome present first-mover advantages for modular bed platforms with detachable telemetry arrays.
- EU AI Act algorithmic-health tailwinds:Anticipated interoperability mandates for diagnostic-support functions create regulatory runway for beds with embedded predictive-analytics engines.
- Home-care channel emergence:Direct-to-patient distribution through specialized medical-device retailers bypasses hospital procurement bottlenecks and captures margin pools in aging-in-place segments.
Industry Challenges
- Embedded-software talent scarcity:Firmware engineering for real-time pressure-mapping algorithms commands premium compensation in Munich, Stuttgart, and Paris technology labor markets, constraining R&D velocity.
- Legacy HIS integration complexity:Proprietary data protocols from incumbent hospital information system vendors require costly middleware development for seamless smart-bed connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Bed Market |
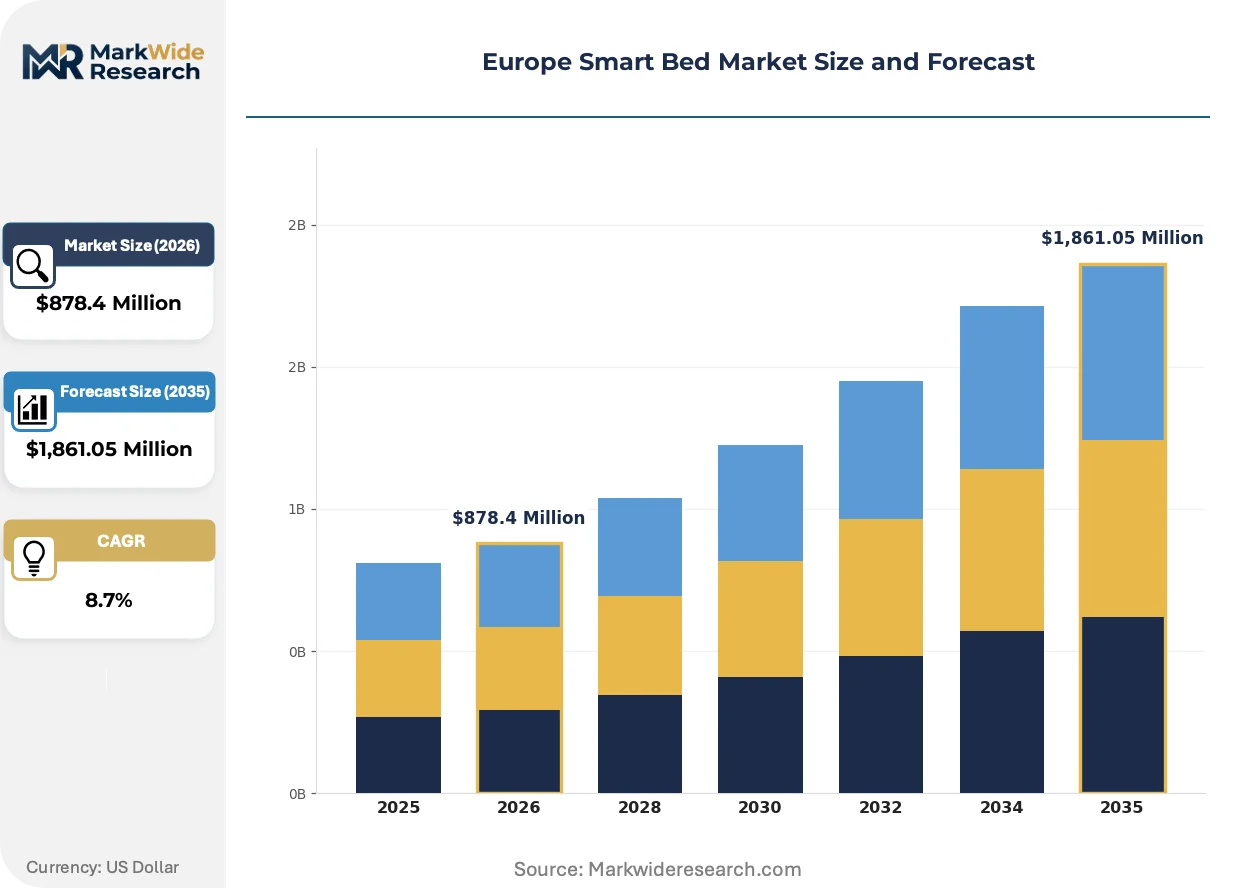
| Market Size in 2026 | $878.4 Million |
| Market Size in 2035 | $1,861.05 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Beds, Adjustable Beds, Electric Beds, Hybrid Beds Technology: Sleep Tracking, Temperature Control, Connectivity, Smart Home Integration End User: Residential, Healthcare Facilities, Hospitality Sector, Rehabilitation Centers Sales Channel: Online Retail, Direct Sales, Specialty Stores, Wholesale Distributors |
| Companies Covered | Stryker Corporation, Hill-Rom Holdings, Inc., Invacare Corporation, Paramount Bed Co., Ltd., LINET spol., Stiegelmeyer GmbH & Co. KG, Arjo AB, Joerns Healthcare LLC, Favero Health Projects SpA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Bed Market Shifts & Advancements
Algorithmic health monitoring is migrating from passive data collection toward diagnostic-support functions, while procurement centralization and sustainability disclosure mandates reshape how beds are specified, financed, and deployed across European care networks.
Capacitive pressure-mapping arrays with textile-integrated electrodes are converging with cloud-based analytics platforms to enable continuous skin-integrity assessment without discrete sensor pads. German university hospitals in Berlin and Heidelberg are piloting these systems for ICU early-warning protocols. This convergence is compressing the boundary between furniture and clinical-grade monitoring equipment, forcing manufacturers to recalibrate quality-management systems toward medical-device standards.
The EU AI Act's risk-classification framework for machine-learning health applications is triggering pre-emptive algorithm-auditing investments among connected-bed developers. Manufacturers must document training-data provenance and performance-validation metrics before commercial deployment. Intensive-care configurations with automated repositioning recommendations face the steepest compliance burdens, prompting some vendors to bifurcate product lines between AI-enabled and rule-based variants.
Consolidated purchasing cooperatives in France and the Netherlands are displacing hospital-level procurement autonomy with framework agreements spanning 50-200 facilities. These buyers demand standardized connectivity protocols, 10-year spare-parts guarantees, and embedded carbon-footprint disclosures. Danish and Swedish regional health authorities are pioneering total-cost-of-ownership contracting that bundles hardware, software maintenance, and predictive-service interventions into per-patient-day fees.
Europe Smart Bed Market Segmentation
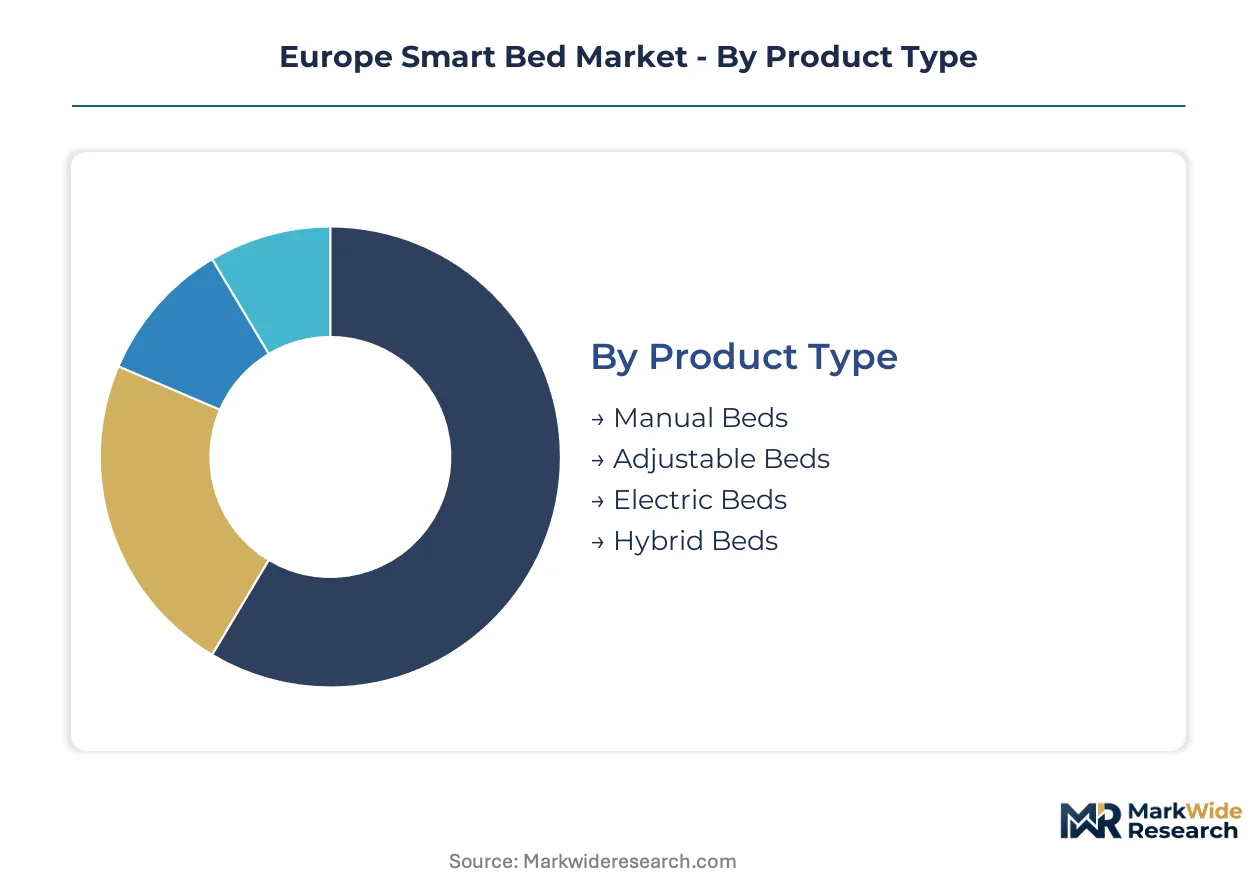
Smart bed segmentation in Europe reflects divergent value capture strategies across clinical precision and consumer convenience. Manufacturers must align component specifications with distinct procurement workflows spanning hospital tender boards, hospitality procurement consortia, and direct-to-patient retail channels.
Product Type:
Adjustable beds dominate hospital procurement volumes while electric beds command premium pricing through sensor integration.
- Adjustable Beds:Motorized frame configurations with manual or semi-automated positioning controls serve acute-care pressure-ulcer protocols. German university hospitals in Berlin and Heidelberg specify these for ICU early-warning systems, driven by European Pressure Ulcer Advisory Panel repositioning mandates.
- Electric Beds:Fully motorized platforms integrate electromechanical actuators, pressure-mapping sensors, and wireless modules for remote patient management. France's Plan Hôpital 2030 capital streams accelerate replacement cycles in Paris and Lyon hospital networks seeking connected monitoring infrastructure.
- Manual Beds:Basic mechanical frames without powered positioning retain cost advantages in Spanish and Italian long-term care facilities operating under fixed reimbursement structures.
- Hybrid Beds:Modular configurations blending manual backup systems with upgradeable sensor arrays target rehabilitation centers in Madrid and Barcelona seeking phased technology adoption.
Today's leader: Adjustable beds. Tomorrow's challenger: Hybrid beds.
Technology:
Connectivity infrastructure determines interoperability premiums while temperature control standardization compresses production costs.
- Temperature Control:Embedded heating and cooling elements with closed-loop feedback maintain therapeutic thermal ranges for pressure-injury prevention. Nordic procurement consortiums prioritize REACH-compliant foam substrates in these systems, filtering suppliers by substance-registration transparency.
- Connectivity:Wireless communication modules enabling HL7 and FHIR protocol integration with hospital information systems command margin premiums. Dutch and Danish regional health authorities mandate standardized connectivity in framework agreements spanning 50-200 facilities.
- Sleep Tracking:Capacitive textile-integrated electrodes with cloud-based analytics enable continuous biometric monitoring. These systems face steepest EU AI Act compliance burdens for algorithmic diagnostic-support functions.
- Smart Home Integration:Voice-activated controls and IoT ecosystem compatibility target aging-in-place residential segments in Germany and the United Kingdom, bypassing hospital procurement bottlenecks.
Connectivity protocols lock in hospital contracts. Sleep tracking gains share fastest in home-care channels.
End User:
Healthcare procurement concentrates purchasing power while hospitality seeks brand differentiation through wellness amenities.
- Healthcare Facilities:Acute-care hospitals and clinics specify CE-marked Class IIa devices with clinical-evaluation documentation. Germany's Krankenhauszukunftsgesetz allocates dedicated capital for connected patient-monitoring infrastructure.
- Residential:Direct-to-patient distribution through specialized medical-device retailers captures margin pools in aging-in-place segments across France and the United Kingdom.
- Rehabilitation Centers:Post-acute facilities in Milan and Rome present first-mover advantages for modular platforms with detachable telemetry arrays, currently underpenetrated relative to Northern European markets.
- Hospitality Sector:Premium hotel chains in Barcelona and Amsterdam deploy smart beds as wellness amenities, prioritizing sleep-tracking interfaces over clinical-grade monitoring.
Healthcare facilities anchor procurement volumes. Rehabilitation centers offer the steepest expansion trajectory.
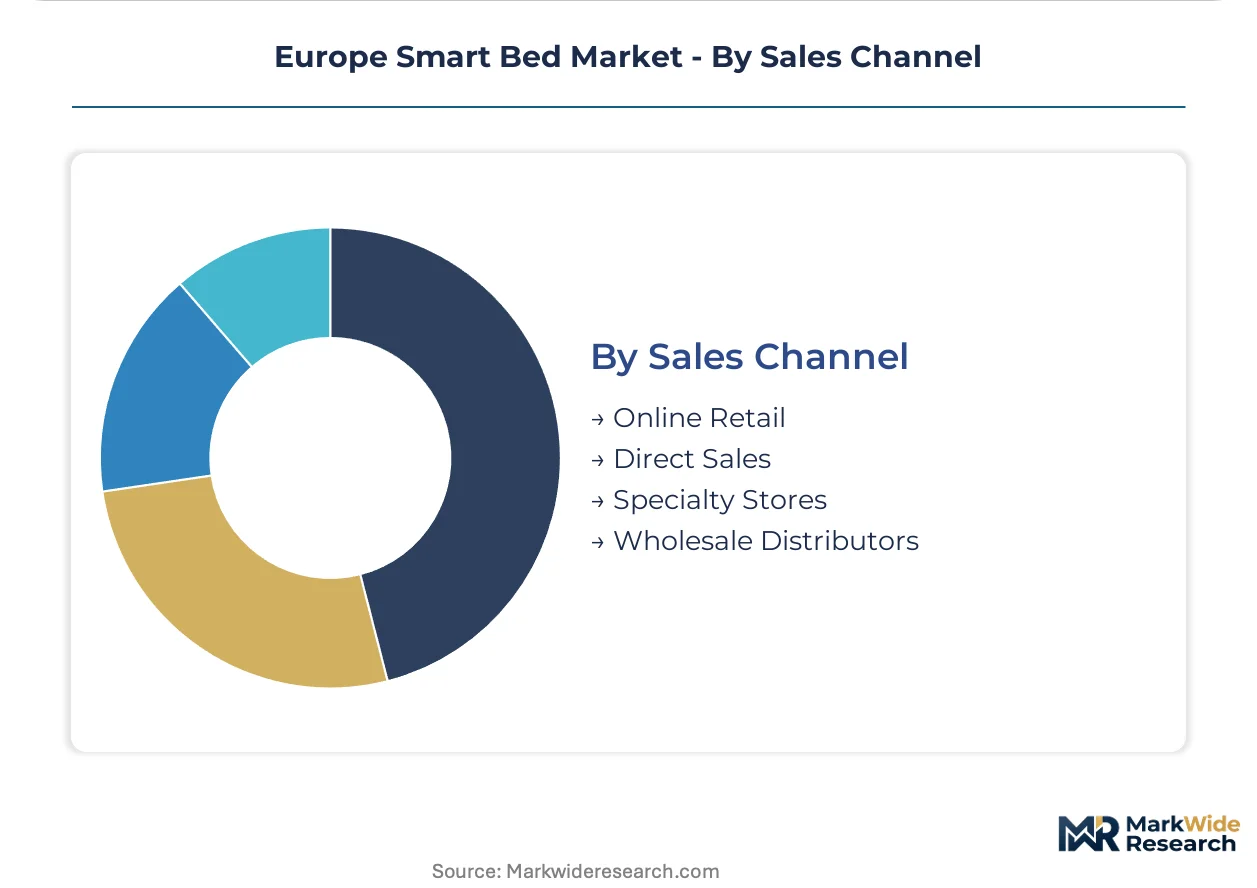
Sales Channel:
Direct sales capture institutional margins while online retail fragments consumer price discovery.
- Direct Sales:Manufacturer-led contracting with consolidated purchasing cooperatives in France and the Netherlands secures multi-year framework agreements with standardized service bundles.
- Specialty Stores:Medical-device retailers in Stuttgart and Munich provide firmware configuration support for bariatric and intensive-care specifications, sustaining premium positioning.
- Wholesale Distributors:Regional logistics networks serve Polish and Czech hospital systems with just-in-time assembly schedules vulnerable to Taiwanese semiconductor lead-time volatility.
- Online Retail:E-commerce platforms aggregate price-transparent comparisons for residential adjustable beds, compressing margins on standard configurations without clinical certification.
Direct sales dominate contract value. Online retail is displacing specialty stores in consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered electromechanical hospital bed manufacturing during post-war reconstruction, establishing engineering standards that shaped European clinical equipment procurement. This industrial heritage concentrates production expertise across the Rhine-Ruhr corridor and southern manufacturing belts.
Germany
Acute-care networks in Berlin and Heidelberg drive sensor-integrated bed procurement under Krankenhauszukunftsgesetz modernization mandates. The KBA-equivalent medical device regulator enforces clinical-evaluation documentation for Class IIa connected devices. Bavarian engineering clusters around Munich and Stuttgart anchor firmware development for pressure-mapping algorithms.
France
Hospital consolidation around Paris and Lyon accelerates framework contracting for connected patient-monitoring infrastructure. ANSM oversight of CE marking timelines filters market entrants without dedicated regulatory affairs functions. The Plan Hôpital 2030 capital allocation prioritizes ICU early-warning systems in Île-de-France university hospitals.
United Kingdom
Aging-in-place residential demand concentrates in Greater London and Southeast England medical-device retail channels. NHS procurement consolidation shifts purchasing power toward national framework agreements spanning 50-200 facilities. Manchester and Birmingham rehabilitation centers pilot modular platforms with detachable telemetry arrays.
Italy
Post-acute rehabilitation networks in Milan and Rome present first-mover expansion opportunities for hybrid bed configurations. Regional health authorities in Lombardy and Lazio operate under fixed reimbursement structures that favor phased technology adoption. Northern Italian industrial districts supply electromechanical actuator components to cross-border OEMs.
Netherlands
Consolidated purchasing cooperatives in Randstad urban corridors mandate standardized connectivity protocols and 10-year spare-parts guarantees. Dutch regional health authorities pioneer total-cost-of-ownership contracting that bundles hardware, software maintenance, and predictive-service interventions into per-patient-day fees.
Europe Smart Bed Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and connectivity-integration dimensions. The vendor base stratifies between vertically integrated hospital-system suppliers and modular-component specialists serving rehabilitation channels. Three archetypes dominate: full-stack manufacturers with captive mattress production, connectivity-protocol developers, and regional engineering specialists focused on bariatric configurations. Consolidation pressures favor M&A activity among mid-tier firmware developers, while capacity expansion concentrates in Polish and Czech assembly operations serving just-in-time schedules.
Among North American-headquartered diversified health-technology conglomerates, Stryker Corporation and Hill-Rom Holdings, Inc. occupy positions reflecting full-stack manufacturing archetypes with upstream control over frame and mattress production. Stiegelmeyer GmbH & Co. KG represents the German engineering-specialist archetype, anchoring premium positioning through intensive-care and bariatric configurations. These three entities exemplify distinct competitive vectors: scale-driven vertical integration, protocol-level hospital IT interoperability, and precision-engineered clinical specialization respectively.
| Leading Market Players |
|---|
| Stryker Corporation |
| Hill-Rom Holdings, Inc. |
| Invacare Corporation |
| Paramount Bed Co., Ltd. |
| LINET spol. |
| Stiegelmeyer GmbH & Co. KG |
| Arjo AB |
| Joerns Healthcare LLC |
| Favero Health Projects SpA |
| Others |
Supply & Pricing Matrix
Family-owned German engineering specialists anchor production clusters across the Rhine-Ruhr corridor, channeling retained earnings into captive component manufacturing that insulates margin structures from Taiwanese semiconductor volatility. Their ownership concentration enables decade-long spare-parts guarantees demanded by Dutch and Danish purchasing cooperatives, embedding pricing discipline through backward integration rather than supplier negotiation leverage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CE-marked Class IIa configurations with full clinical-evaluation documentation from basic electric frames lacking sensor integration. Premium tiers command positioning based on HL7/FHIR protocol certification and 10-year service bundling, while economy segments face margin compression from manual-bed substitution in Spanish and Italian long-term care channels. Cost compression in standard tiers intensifies because consolidated purchasing cooperatives extract volume discounts across 50-200 facility frameworks. Healthcare procurement committees exhibit lowest price sensitivity due to total-cost-of-ownership contracting, whereas hospitality wellness amenity buyers prioritize sleep-tracking interfaces over clinical-grade specifications.
Supply Chain Analysis
Refurbishment flows for electromechanical actuators and pressure-mapping sensor arrays concentrate in Polish and Czech assembly operations serving just-in-time schedules for German OEMs. Component sourcing draws from Taiwanese foundries for wireless-communication modules, REACH-compliant foam substrates from Nordic chemical suppliers, and precision-machined actuator housings from northern Italian industrial districts. Single-source vulnerability in semiconductor supply creates lead-time volatility that disturbs assembly sequencing. Distribution runs through consolidated purchasing cooperatives in France and the Netherlands, with specialty medical-device retailers in Stuttgart and Munich handling firmware configuration for bariatric specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation operates as a regulatory compounder, with Class IIa clinical-evaluation documentation requirements filtering market entrants and concentrating procurement power among vertically integrated incumbents.
For Market Incumbents: Hedge against firmware engineering talent scarcity in Munich and Paris technology labor markets by acquiring mid-tier algorithm developers before EU AI Act compliance burdens escalate. Anchor market position through backward integration into REACH-compliant foam substrate manufacturing, securing preferential access to Nordic procurement consortiums that filter suppliers by substance-registration transparency. For New Entrants and Emerging Players: Direct-to-patient e-commerce channels bypass hospital procurement bottlenecks and capture margin pools in UK and German aging-in-place residential segments. Target rehabilitation centers in Milan and Rome with modular hybrid bed platforms enabling phased telemetry adoption under fixed reimbursement structures. Lead with voice-activated smart-home integration rather than clinical-grade monitoring to differentiate from entrenched hospital suppliers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier firmware developers lacking dedicated regulatory affairs functions yet possessing algorithmic health-monitoring IP. Long-term viability over the next decade hinges on embedded-software capabilities migrating from passive monitoring toward diagnostic-support functions under EU AI Act frameworks. Monitor ANSM and KBA-equivalent regulator staffing levels as inflection indicators for CE marking timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | Accelerates market access under EU MDR clinical-evaluation timelines for Class IIa connected devices. |
| Hospital System Partnership | Locks in multi-year framework agreements with consolidated purchasing cooperatives in France and the Netherlands. |
| Backward Integration into Sensor Manufacturing | Captures margin pools in pressure-mapping arrays while insulating supply from Taiwanese semiconductor volatility. |
| Software Companion Development | Enables predictive-analytics engines that anticipate EU AI Act interoperability mandates for diagnostic-support functions. |
| Reimbursement Strategy Alignment | Positions modular platforms for phased adoption in Italian and Spanish fixed-reimbursement rehabilitation channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads at connected-bed manufacturers with secondary validation against EU MDR compliance databases, hospital tender records, and REACH substance-registration disclosures. Bottom-up facility-level procurement tracking and top-down vendor revenue analysis triangulated market sizing across product type, technology, and end-user segments.
Segment-weighting approaches distributed value estimates across adjustable, electric, manual, and hybrid bed configurations, with technology tiers weighted by connectivity protocol certification status and temperature-control standardization levels. CAGRs derived from facility replacement-cycle analysis under Germany's Krankenhauszukunftsgesetz and France's Plan Hôpital 2030 capital allocation schedules, incorporating semiconductor lead-time volatility and firmware engineering compensation inflation as sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for algorithmic diagnostic-support functions would alter the outlook if EU AI Act risk-classification frameworks tighten faster than anticipated. Forecasts reflect assumptions about procurement consolidation velocity and REACH compliance timeline adherence. Practitioners should monitor ANSM and KBA-equivalent regulator guidance publications and Taiwanese foundry capacity utilization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Gel Stent Market
Medical Devices
Global Medical Exoskeleton Market
Medical Devices
North America Organ-On-Chip Market
Medical Devices
Balloon Inflation Devices Market
Medical Devices
Laser Resurfacing Market
Medical Devices
Bronchial Thermoplasty Catheter Market
Medical Devices
Global Hip Implant Market
Medical Devices
Indwelling Catheter Market
Medical Devices
Peritoneal Dialysis Solutions Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
Motorized Prosthesis Market
Medical Devices
US Nebulizer Market
Medical Devices
3D Printed Implants Market
Medical Devices
Global Mobile C-Arm Market
Medical Devices
Nerve Stimulators Market