
 Clot Management Devices Market | 2026-2036
Clot Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Clot Management Devices Market Intelligence
Recurring software-defined service layers for device performance monitoring and predictive maintenance is pivoting vendor-customer relationships toward outcome-based contracts. Medtronic leverages its integrated digital health infrastructure to sustain long-term engagement with catheterization laboratories. Boston Scientific Corporation anchors its competitive stance through specialized thrombectomy catheter portfolios. Penumbra, Inc. differentiates via concentrated R&D intensity in aspiration-based clot removal platforms.
Clot management devices encompass mechanical, pharmacological, and ultrasound-assisted instruments engineered to dissolve, extract, or bypass thrombotic occlusions in vascular and cerebral circulations, typically operating at catheter diameters between 3F and 9F with aspiration pressures reaching 600-700 mmHg for large-vessel retrieval. These instruments serve the primary purpose of restoring perfusion in acute ischemic events, reducing downstream tissue infarction, and minimizing long-term neurological or cardiopulmonary disability. Thrombectomy devices command the dominant margin pool as hospitals prioritize stent-retriever and aspiration platforms for stroke intervention, while pharmacological intervention segments face pricing pressure from generic anticoagulant competition. Mechanical thrombectomy technology leads procedural volume growth, though ultrasound-assisted platforms represent an emerging structural opportunity for operators navigating distal vessel anatomies.
FDA 510(k) clearance requirements and the EU Medical Device Regulation (MDR) establish divergent compliance burdens, with European notified-body bottlenecks extending time-to-market for novel thrombectomy systems. The EU AI Act introduces additional scrutiny for software-enabled clot detection algorithms integrated into next-generation devices. Stakeholders must monitor how reimbursement parity between thrombectomy and conservative medical management evolves across national health technology assessment frameworks.
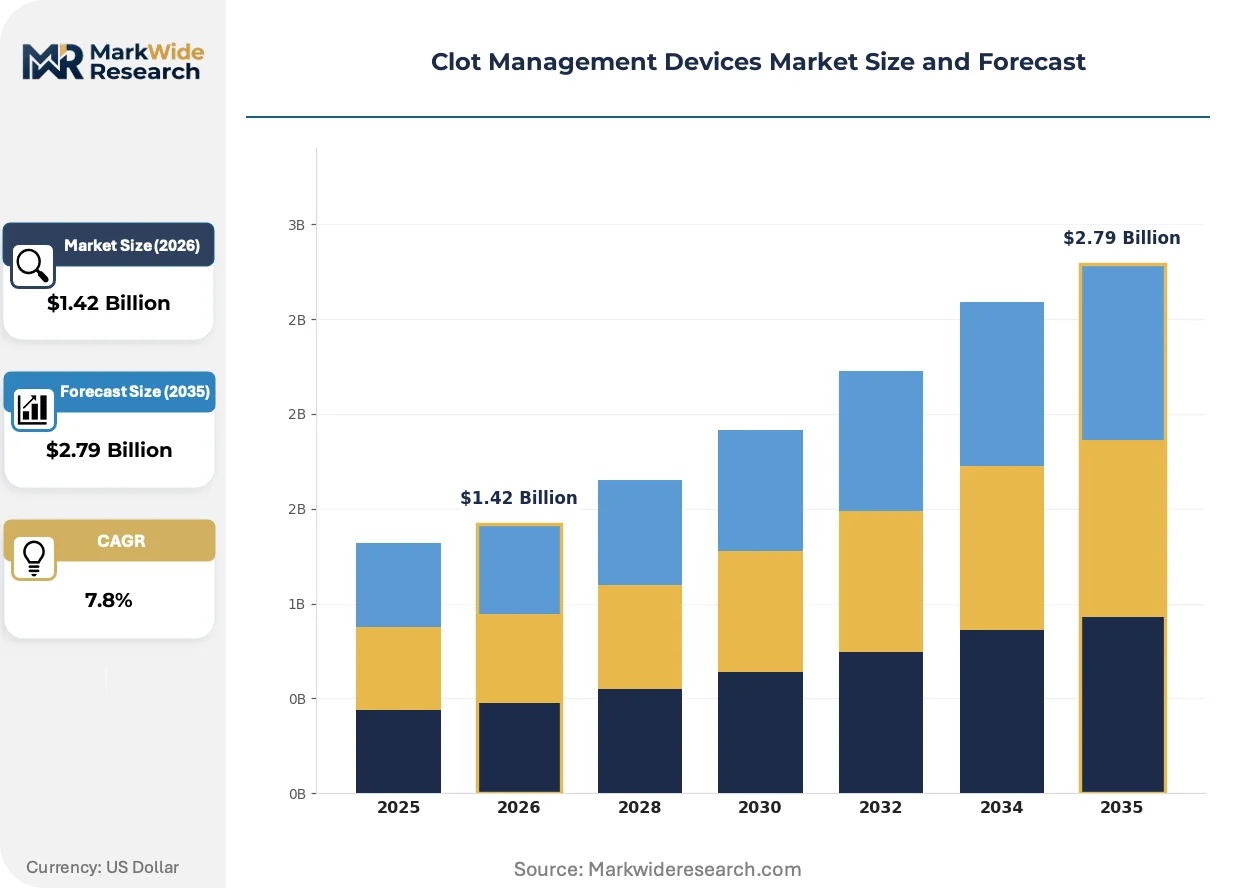
Market Dynamics
Mechanical thrombectomy platforms are consolidating procedural workflows around aspiration-first protocols, compressing operator training curves and shifting capital allocation toward integrated aspiration-suction systems in catheterization laboratories.
Growth Catalysts
- Comprehensive Stroke-Unit Networks:Germany's nationwide stroke-unit certification program mandates mechanical thrombectomy capability, institutionalizing device demand across tertiary centers.
- FDA 510(k) Pathway Clarity:Streamlined predicate-device comparisons for stent-retriever submissions accelerate US market entry timelines for next-generation thrombectomy platforms.
- Distal Vessel Navigation:Aspiration catheters engineered for 3F-4F compatibility enable anterior circulation interventions previously unreachable with conventional 6F systems.
Market Restraints
- Nitinol Raw Material Concentration:Superelastic alloy supply chains concentrate in a limited supplier base, exposing device manufacturers to price volatility and allocation risk.
- EU MDR Notified-Body Bottlenecks:Extended conformity assessment timelines delay CE marking for novel thrombectomy systems, compressing effective patent life in European markets.
- Generic Anticoagulant Substitution:Low-cost pharmacological alternatives for non-acute thrombotic management cannibalize prophylactic clot management device volumes in ambulatory settings.
Strategic Opportunities
- India Stroke Infrastructure Buildout:Government-funded thrombectomy center expansion under the National Programme for Prevention and Control of Non-Communicable Diseases creates first-mover positioning for device vendors.
- EU AI Act Algorithmic Clearance:Software-enabled clot detection modules integrated into aspiration platforms qualify for expedited regulatory pathways, differentiating next-generation product portfolios.
- Telestroke Network Integration:Hub-and-spoke vascular neurology programs in rural US markets extend mechanical thrombectomy candidate identification to previously underserved populations.
Industry Challenges
- Neurointerventionalist Workforce Scarcity:Fellowship-trained operators capable of large-vessel occlusion procedures remain concentrated in academic medical centers, limiting procedural volume expansion.
- Legacy EMR Integration Complexity:Device performance monitoring software requires custom API development for hospital information system compatibility, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clot Management Devices Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thrombectomy Devices, Catheters, Compression Devices, Drugs End User: Hospitals, Clinics, Ambulatory Surgical Centers, Rehabilitation Centers Technology: Mechanical Thrombectomy, Pharmacological Intervention, Ultrasound, Magnetic Resonance Application: Cerebral Stroke, Heart Attack, Pulmonary Embolism, Deep Vein Thrombosis |
| Companies Covered | Medtronic, Boston Scientific Corporation, Stryker, Penumbra, Inc., AngioDynamics, Inc., Edwards Lifesciences Corporation, Teleflex Incorporated, Johnson & Johnson, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clot Management Devices Market Strategic Shifts & Innovations
Digital service layers embedded within clot management hardware are restructuring vendor-hospital relationships around continuous performance optimization rather than discrete capital transactions.
Next-generation aspiration platforms is modularizing catheter tip configurations to accommodate variable vessel tortuosity without system exchange. Stroke centers in the United States are standardizing on these adaptable systems to reduce procedure time and inventory complexity. This flexibility is modularizing purchasing decisions around component ecosystems rather than fixed-device platforms.
The EU AI Act imposes conformity requirements on machine-learning algorithms integrated into clot detection and device navigation systems. Device manufacturers must now document training data provenance and algorithmic transparency for software modules previously treated as ancillary features. European notified bodies are prioritizing review resources toward these submissions, creating temporary regulatory queue advantages for hardware-only predicate devices.
Hospital procurement departments are consolidating thrombectomy device purchasing through integrated delivery networks, unbundling capital equipment from disposable catheter contracts. Academic medical centers in Germany and the United States are leading this transition, negotiating multi-year total-procedure-cost agreements that internalize device selection authority from individual operators. This concentration is compressing vendor switching costs and intensifying price transparency requirements.
Clot Management Devices Market Segmentation
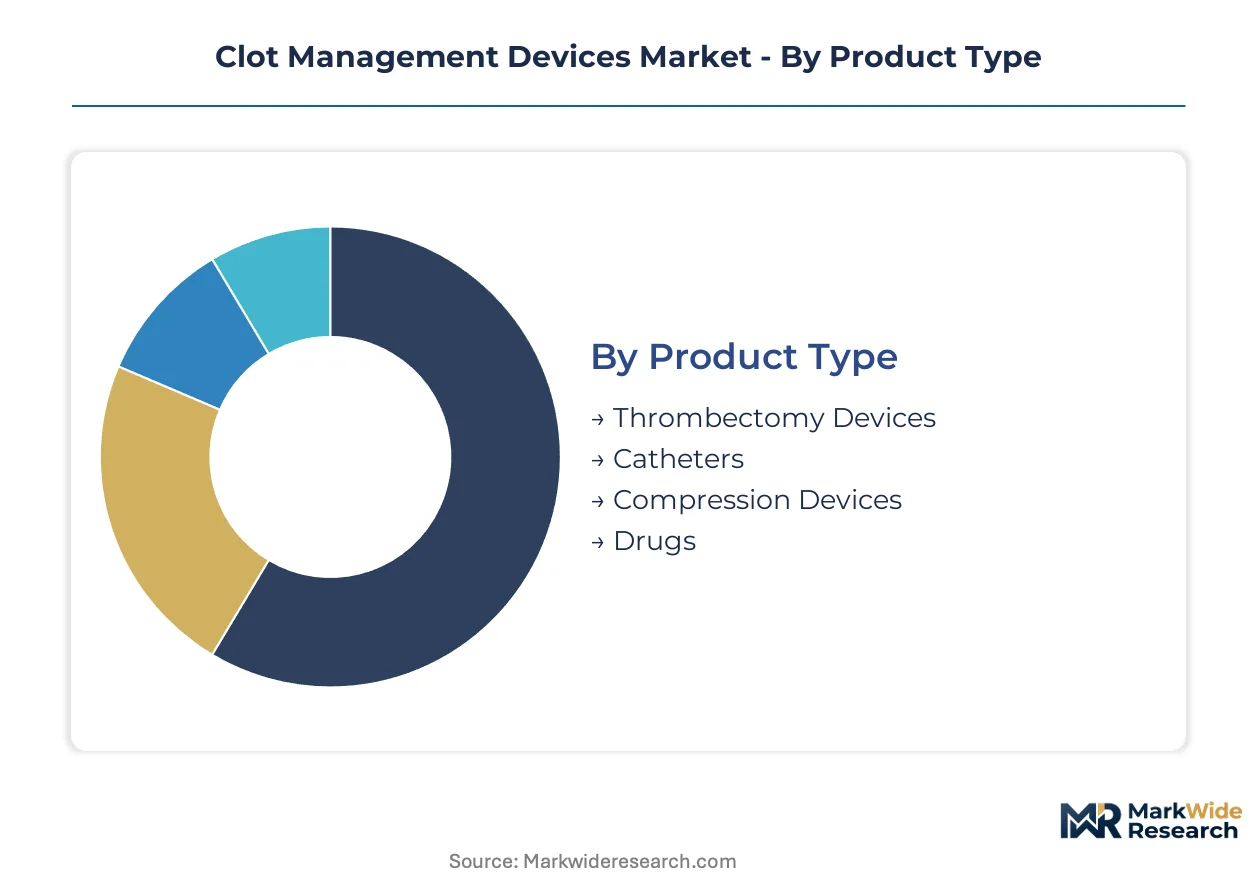
Clot management devices stratify across four dimensions that determine procurement workflows, regulatory pathways, and reimbursement structures. Product type governs capital allocation between disposable catheters and durable aspiration systems. Technology and application segments dictate operator training requirements and site-of-service economics.
Product Type:
Thrombectomy devices demand the heaviest upfront capital commitment, requiring integrated aspiration pumps, suction consoles, and imaging-compatible catheter inventories that can exceed seven figures per stroke-center installation.
- Thrombectomy Devices:Stent-retriever and aspiration platforms incorporating nitinol mesh or polymer suction catheters operate at 6F-9F diameters with 600-700 mmHg aspiration pressures. German stroke-unit networks and US comprehensive stroke centers concentrate procurement volume as these facilities institutionalize mechanical thrombectomy protocols for large-vessel occlusions.
- Catheters:Delivery and aspiration catheters span 3F-4F distal-access configurations through 8F guiding platforms, with hydrophilic coatings and variable stiffness profiles. Demand clusters in tertiary hospitals performing anterior circulation interventions, where catheter exchange frequency drives recurring disposable revenue.
- Compression Devices:Pneumatic and mechanical compression systems for deep vein thrombosis prophylaxis. Post-acute rehabilitation facilities in Germany and ambulatory surgical centers in the United States absorb the majority of placements.
- Drugs:Systemic and catheter-directed thrombolytic agents including tissue plasminogen activator formulations. Generic competition has compressed pricing power, shifting volume toward emergency department protocols rather than interventional suites.
Thrombectomy devices absorb the bulk of installed capacity; distal-access catheters are expanding most quickly as operators push into smaller vessel anatomies.
End User:
Hospital procurement patterns concentrate around integrated delivery networks that bundle thrombectomy device contracts across multiple facilities, compressing vendor switching costs and standardizing platform selection.
- Hospitals:Comprehensive and primary stroke centers with neurointerventional suites performing mechanical thrombectomy for acute ischemic stroke. Germany's certified stroke-unit network and US hub-and-spoke telestroke programs anchor procedural volume, with catheterization laboratories requiring 24/7 operator coverage.
- Clinics:Outpatient vascular access centers managing central venous catheter occlusions and peripheral arterial disease. Demand concentrates in urban clusters with interventional nephrology and cardiology presence, where same-day discharge protocols optimize reimbursement.
- Ambulatory Surgical Centers:Limited thrombectomy volume due to anesthesia and imaging requirements, though select centers perform lower-extremity arterial interventions. Medicare site-of-service differentials influence case migration.
- Rehabilitation Centers:Compression device deployment for deep vein thrombosis prophylaxis in immobilized patients. Post-acute facilities in Germany's integrated care networks and US skilled nursing facilities drive recurring placements.
Hospitals command the dominant share of thrombectomy procedural revenue; clinics are gaining share fastest as peripheral vascular interventions migrate to outpatient settings.
Technology:
Technology selection determines regulatory pathway complexity, with software-enabled modalities triggering additional conformity requirements under the EU AI Act and FDA software-as-medical-device guidance.
- Mechanical Thrombectomy:Aspiration-first and stent-retriever platforms using nitinol superelastic alloys and polymer suction catheters. German stroke centers and US comprehensive stroke centers have standardized workflows around these systems, with operator training curves compressing as aspiration protocols displace combined approaches.
- Pharmacological Intervention:Catheter-directed thrombolysis and systemic anticoagulation protocols. Generic substitution pressure has shifted utilization toward acute emergency settings rather than elective interventional procedures.
- Ultrasound:High-frequency acoustic energy for clot dissolution and microbubble-enhanced drug delivery. Emerging positioning for distal vessel anatomies where mechanical retrieval risks vessel perforation, with European notified bodies prioritizing review resources for these submissions.
- Magnetic Resonance:MR-guided interventional platforms enabling real-time visualization without iodinated contrast. Limited installed base due to magnet compatibility requirements and capital intensity, with academic medical centers in Germany and the United States hosting the primary research deployments.
Mechanical thrombectomy commands the dominant procedural volume; ultrasound-assisted platforms are climbing the fastest as operators seek distal navigation capabilities.
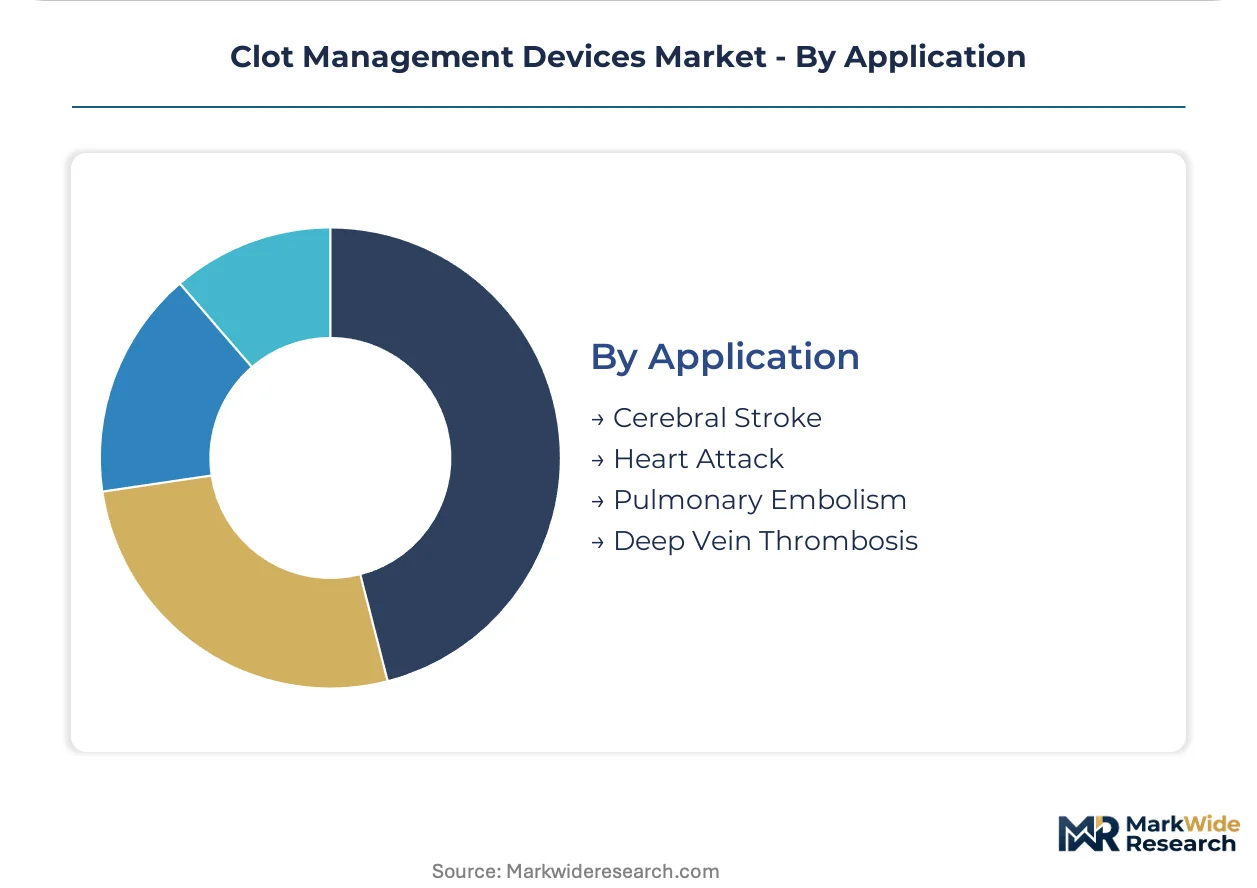
Application:
Application segmentation aligns with emergency medical services protocols, stroke center certification requirements, and reimbursement parity between mechanical thrombectomy and conservative management.
- Cerebral Stroke:Large-vessel occlusion interventions in anterior and posterior circulation territories. Germany's nationwide stroke-unit certification mandates mechanical thrombectomy capability, institutionalizing device demand across tertiary centers and driving aspiration-platform standardization.
- Heart Attack:Coronary thrombectomy during primary percutaneous coronary intervention for ST-elevation myocardial infarction. Cardiac catheterization laboratories in the United States and Germany concentrate utilization, though manual aspiration catheters face pricing pressure from balloon angioplasty dominance.
- Pulmonary Embolism:Catheter-directed thrombolysis and mechanical embolectomy for intermediate-risk presentations. US academic medical centers are expanding interventional pulmonary embolism response team capabilities, creating procedural volume growth.
- Deep Vein Thrombosis:Pharmacomechanical thrombolysis and compression device prophylaxis. Ambulatory settings and post-acute facilities absorb the majority of compression device volume, while interventional suites manage iliofemoral clot burden.
Cerebral stroke applications absorb the bulk of thrombectomy device utilization; pulmonary embolism interventions are gaining share fastest as interventional response teams proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device consumption concentrates in advanced healthcare economies while production of nitinol superelastic alloys and catheter assemblies centers on specialized manufacturing clusters in Germany, the United States, and Switzerland.
United States
Comprehensive stroke centers and hub-and-spoke telestroke networks drive mechanical thrombectomy procedural volume. FDA 510(k) clearance pathways for predicate-device comparisons accelerate market entry timelines for next-generation stent-retriever platforms. Academic medical centers in Boston and Baltimore anchor neurointerventional training pipelines that feed operator demand across the Southeast and Mountain West.
Germany
Nationwide stroke-unit certification mandates mechanical thrombectomy capability across tertiary centers, institutionalizing device demand. EU MDR notified-body bottlenecks extend CE marking timelines for novel thrombectomy systems, compressing effective patent life. Industrial clusters in Baden-Württemberg and Bavaria host precision nitinol fabrication facilities supplying catheter manufacturers across the continent.
China
Government-funded stroke center expansion under national non-communicable disease programs creates first-mover positioning for device vendors. NMPA regulatory pathways for Class III interventional devices require local clinical trials, extending time-to-market for imported platforms. Shanghai and Beijing academic medical centers pioneer interventional neurology fellowships that address operator scarcity in provincial hospitals.
India
The National Programme for Prevention and Control of Non-Communicable Diseases funds thrombectomy center expansion in tier-1 and tier-2 cities. CDSCO medical device rules impose registration requirements that favor joint-venture partnerships with established multinational manufacturers. Maharashtra and Karnataka host the majority of interventional neuroradiology training programs, concentrating procedural expertise in Mumbai and Bangalore.
Japan
Aging demographics and stroke incidence sustain demand for mechanical thrombectomy in metropolitan hospital networks. PMDA approval processes for novel interventional devices require Japan-specific clinical evidence, creating regulatory moats for incumbent suppliers. The Kanto region around Tokyo concentrates neurointerventional procedural volume and device procurement authority within integrated academic medical center networks.
Clot Management Devices Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the clot management device landscape. Integrated medical technology conglomerates with captive manufacturing of nitinol components and polymer extrusion capabilities face competition from specialized interventional firms outsourcing catheter fabrication to contract manufacturers. The market structure tiers across diversified cardiovascular platforms, dedicated neurovascular specialists, and emerging regional assemblers. Consolidation pressure intensifies as integrated delivery networks bundle purchasing contracts and compress vendor switching costs.
Among diversified medical technology conglomerates, Medtronic, Boston Scientific Corporation, and Penumbra, Inc. occupy positions representing distinct strategic archetypes. Medtronic exemplifies the integrated platform approach leveraging digital health infrastructure for catheterization laboratory engagement. Boston Scientific Corporation anchors the specialized thrombectomy catheter portfolio tier. Penumbra, Inc. sits within the concentrated R&D intensity segment for aspiration-based clot removal platforms. These three entities collectively represent the competitive positioning spectrum from broad cardiovascular diversification through targeted neurovascular specialization.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Stryker |
| Penumbra, Inc. |
| AngioDynamics, Inc. |
| Edwards Lifesciences Corporation |
| Teleflex Incorporated |
| Johnson & Johnson |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
Captive nitinol fabrication in Baden-Württemberg and Bavaria anchors both supply security and premium pricing power for German catheter manufacturers serving EU stroke-unit networks. This backward integration into superelastic alloy production insulates incumbents from raw material volatility while enabling three-tier pricing structure across premium, standard, and economy levels based on CE marking tier and aspiration pressure specifications.
Pricing Analysis
Margin tightening in standard-tier thrombectomy platforms reflects integrated delivery network bundling in US and German hospital systems. Per-unit transactional pricing dominates, with differentiation driven by FDA 510(k) predicate tier and nitinol sourcing transparency. Cost-down pressure accelerates as GPO contracts consolidate purchasing authority, compressing vendor switching costs. Academic medical centers exhibit lowest price sensitivity due to outcome-based contract structures, while ambulatory surgical centers face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with nitinol superelastic alloy suppliers concentrated in Germany, the United States, and Switzerland. Device fabrication draws from polymer extrusion facilities in Bavaria, precision laser-cutting operations in Baden-Württemberg, and hydrophilic coating specialists in Switzerland. Tariff exposure on Chinese-sourced catheter components compounds regulatory restriction risks under EU MDR notified-body bottlenecks. Distribution runs through integrated delivery networks and specialized interventional device distributors serving catheterization laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clot management device sector is becoming a vertical-integration race, with nitinol alloy supply and digital health infrastructure representing the decisive upstream and downstream levers.
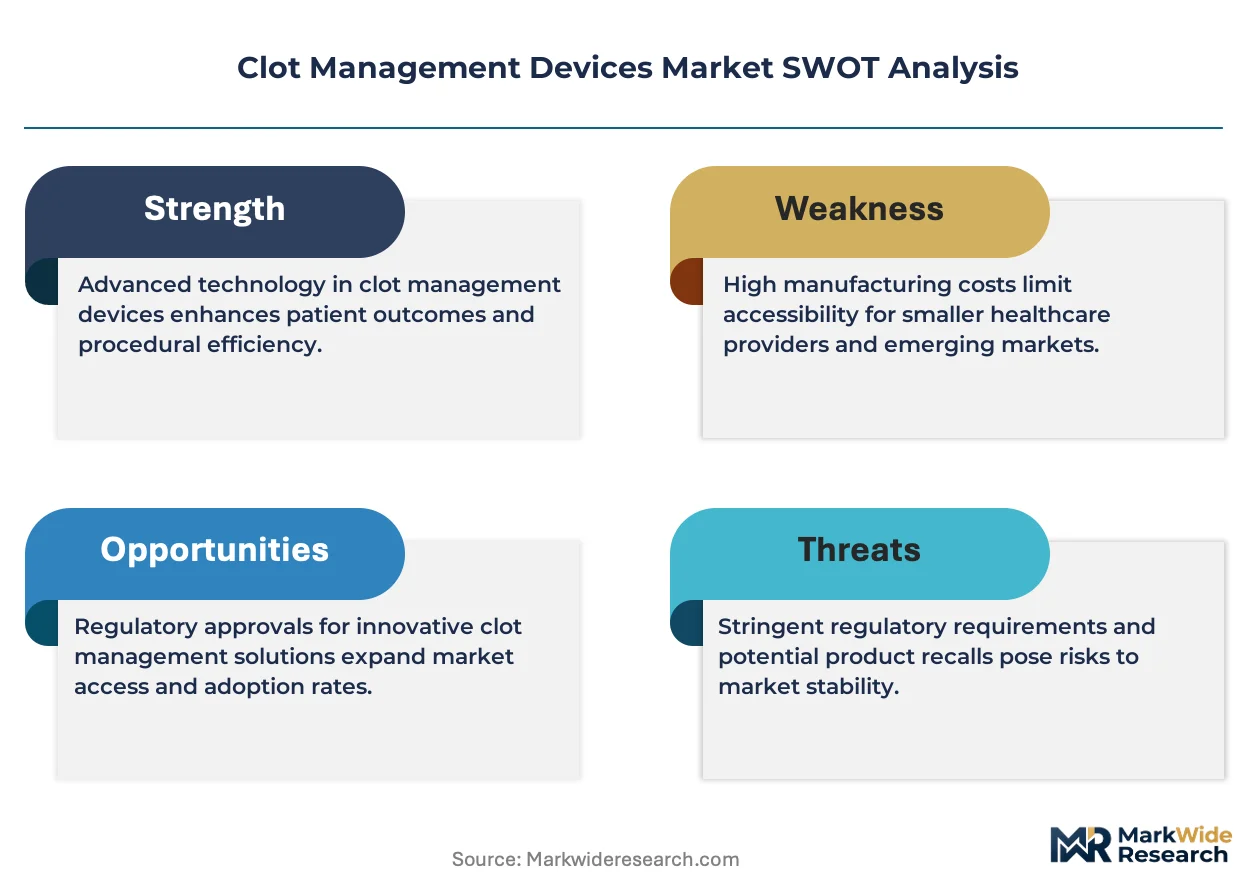
For Market Incumbents: Deepen backward integration into nitinol superelastic alloy production to defend against raw material allocation risk and generic catheter substitution. Secure long-term supply agreements with German precision fabrication clusters while expanding software-enabled performance monitoring layers to lock in catheterization laboratory relationships through outcome-based contracts. For New Entrants and Emerging Players: Enter via India's government-funded thrombectomy center expansion under the National Programme for Prevention and Control of Non-Communicable Diseases, where CDSCO registration requirements favor joint-venture structures. Target tier-2 cities in Maharashtra and Karnataka with simplified aspiration platforms designed for operator training curve compression, leveraging telestroke network integration as the primary go-to-market channel. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified cardiovascular conglomerates seeking neurovascular specialization. Long-term viability hinges on software-enabled differentiation under EU AI Act algorithmic clearance requirements. Watch for inflection signals in European notified-body prioritization toward hardware-only predicate devices versus software-integrated submissions.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Accelerated review for aspiration-first platforms preserves effective patent life in German stroke-unit networks. |
| Hospital System Partnership | Multi-year total-procedure-cost agreements with integrated delivery networks internalize device selection authority. |
| Software Companion Development | AI-enabled clot detection modules trigger expedited pathways under EU AI Act algorithmic transparency requirements. |
| Backward Integration into Nitinol | Captive superelastic alloy production insulates margin position from supplier concentration in German industrial clusters. |
| Reimbursement Strategy | Parity negotiation between mechanical thrombectomy and conservative management shapes site-of-service economics. |
Research Approach
Independent corroboration across neurointerventionalists, hospital purchasing committees, biomedical engineers, and GPO contracts managers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU MDR notified-body submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up catheter installation counts and top-down stroke-center capacity estimates triangulate market sizing across product type, technology, and application dimensions.
Comparable-period anchoring to historical thrombectomy procedural volumes and stroke-unit certification timelines structures the forecast window across the analysis window. Segmentation modeling incorporates product type, technology modality, application indication, and end-user facility tier. CAGRs derive from installed base expansion rates, procedure volume intensity per center, and pricing trajectory assumptions. Forecast inputs include EU MDR regulatory queue dynamics and telestroke network penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act algorithmic scrutiny intensity and nitinol supply allocation disruptions. Forecasts reflect assumptions around operator workforce expansion, reimbursement parity evolution, and integrated delivery network consolidation momentum. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Japan Drug Delivery Devices Market
Medical Devices
Global Surgical Navigation System Market
Medical Devices
Portable Medical Ventilators Market
Medical Devices
North America Advanced Drug Delivery Systems Market
Medical Devices
Pulmonology Lasers Market
Medical Devices
Neurosurgical Products Market
Medical Devices
Digital Orthodontics Market
Medical Devices
Clinical Rollators Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Nephrostomy Devices Market
Medical Devices
Intravascular Ultrasound [IVUS] Devices Market
Medical Devices
Digital Intraoral Sensors and Consumables Market
Medical Devices
Enteral Feeding Devices Market
Medical Devices
Global Total Wrist Replacement Market