
 Pleural Effusion Treatment Market | 2026-2036
Pleural Effusion Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pleural Effusion Treatment Market Analysis
Device-agnostic software platforms for remote drainage monitoring is restructuring how pleural effusion therapy gets sold and reimbursed. Smiths Medical leverages its telemetry-enabled chest drainage systems to sustain recurring revenue beyond the initial hardware placement. Becton, Dickinson and Company anchors hospital procurement contracts through bundled catheter-and-monitoring packages that reduce per-procedure variability. Teleflex Inc. differentiates by specializing in indwelling pleural catheter designs that extend dwell time and minimize replacement cycles.
Pleural effusion treatment encompasses the clinical management of abnormal fluid accumulation in the pleural space through mechanical drainage, chemical or surgical pleurodesis, and minimally invasive thoracoscopic intervention, typically employing catheters ranging from 8 to 28 French in diameter with suction capabilities between negative 20 and negative 40 cm water pressure. The primary purpose is to restore pulmonary expansion, relieve dyspnea, and prevent recurrent effusions in patients with congestive heart failure, malignancy, or post-surgical complications. Thoracentesis and indwelling catheter systems occupy the largest volume share as first-line interventions, while video-assisted thoracic surgery commands premium pricing in complex or recurrent cases where pleural biopsy and definitive pleurodesis are indicated. Among end users, hospitals retain the dominant margin pool due to bundled reimbursement structures, though homecare settings are gaining traction as payer pressure shifts lower-acuity drainage management away from inpatient stays.
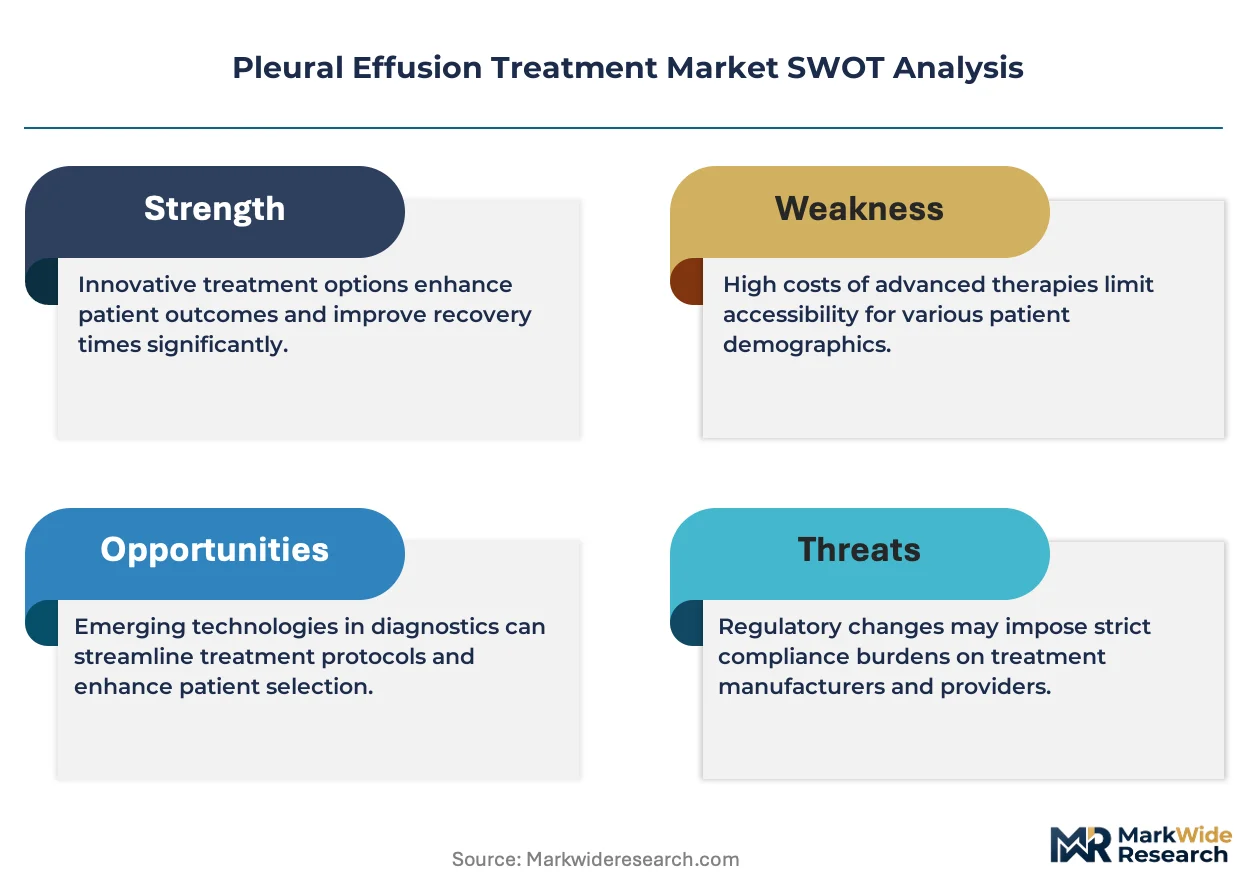
The FDA regulates pleural drainage devices as Class II medical devices requiring 510(k) premarket notification, while the Centers for Medicare and Medicaid Services shapes demand through inpatient versus outpatient procedural reimbursement differentials. In Europe, the Medical Device Regulation imposes stricter clinical evidence requirements on thoracic intervention kits, elevating compliance costs for manufacturers seeking CE marking. Stakeholders must monitor how evolving digital health integration standards and value-based care contracts reshape procurement criteria for drainage hardware and associated monitoring services.
Market Dynamics
The shift from inpatient drainage management to ambulatory and home-based care is compressing hospital revenue cycles while expanding the addressable market for telemetry-enabled catheter systems and remote monitoring services.
Growth Catalysts
- Aging oncology burden:Germany's expanding elderly population with lung and breast malignancies is straining thoracic surgery capacity and accelerating demand for indwelling catheter alternatives to repeated thoracentesis.
- MDR compliance elevation:The EU Medical Device Regulation's stricter clinical evidence requirements for thoracic intervention kits is filtering out marginal competitors and consolidating procurement around established manufacturers with robust technical files.
- Telemetric drainage systems:Real-time pressure and volume monitoring via cellular-connected hardware is enabling early discharge protocols and reducing readmission penalties under US value-based care contracts.
Market Restraints
- Silicone raw material volatility:Indwelling catheter production depends on medical-grade silicone supply chains concentrated in Southeast Asian petrochemical corridors, exposing manufacturers to feedstock price swings and force majeure disruptions.
- Reimbursement compression:The Centers for Medicare and Medicaid Services is narrowing the differential between inpatient and outpatient procedural codes, squeezing hospital margins on pleurodesis and limiting hardware upgrade budgets.
- Antibiotic-coated catheter substitution:Silver-impregnated and antibiotic-eluting designs are displacing standard polyurethane systems in infection-prone populations, rendering legacy product lines obsolete without formulation redevelopment.
Strategic Opportunities
- Homecare channel expansion:Payer pressure to reduce length-of-stay is opening direct-to-patient distribution for drainage management kits with telehealth nursing support, bypassing traditional hospital procurement.
- Japan's super-aging demographic:METI's healthcare infrastructure investments targeting respiratory disease management in patients over 75 create demand for minimally invasive alternatives to surgical pleurodesis.
- AI-assisted drainage algorithms:Machine learning integration with continuous monitoring data is enabling predictive effusion recurrence scoring, creating software-as-a-service revenue streams atop hardware placements.
Industry Challenges
- Interventional pulmonology workforce scarcity:Fellowship-trained specialists capable of advanced thoracoscopic pleurodesis remain concentrated in academic medical centers, limiting procedure volume growth in community hospital settings.
- 510(k) pathway complexity:The FDA's evolving digital health integration standards for telemetry-enabled drainage devices is extending premarket notification timelines and requiring novel cybersecurity documentation.
- Legacy EHR integration friction:Proprietary data formats from competing catheter monitoring platforms resist seamless incorporation into Epic and Cerner workflows, complicating hospital IT procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pleural Effusion Treatment Market |
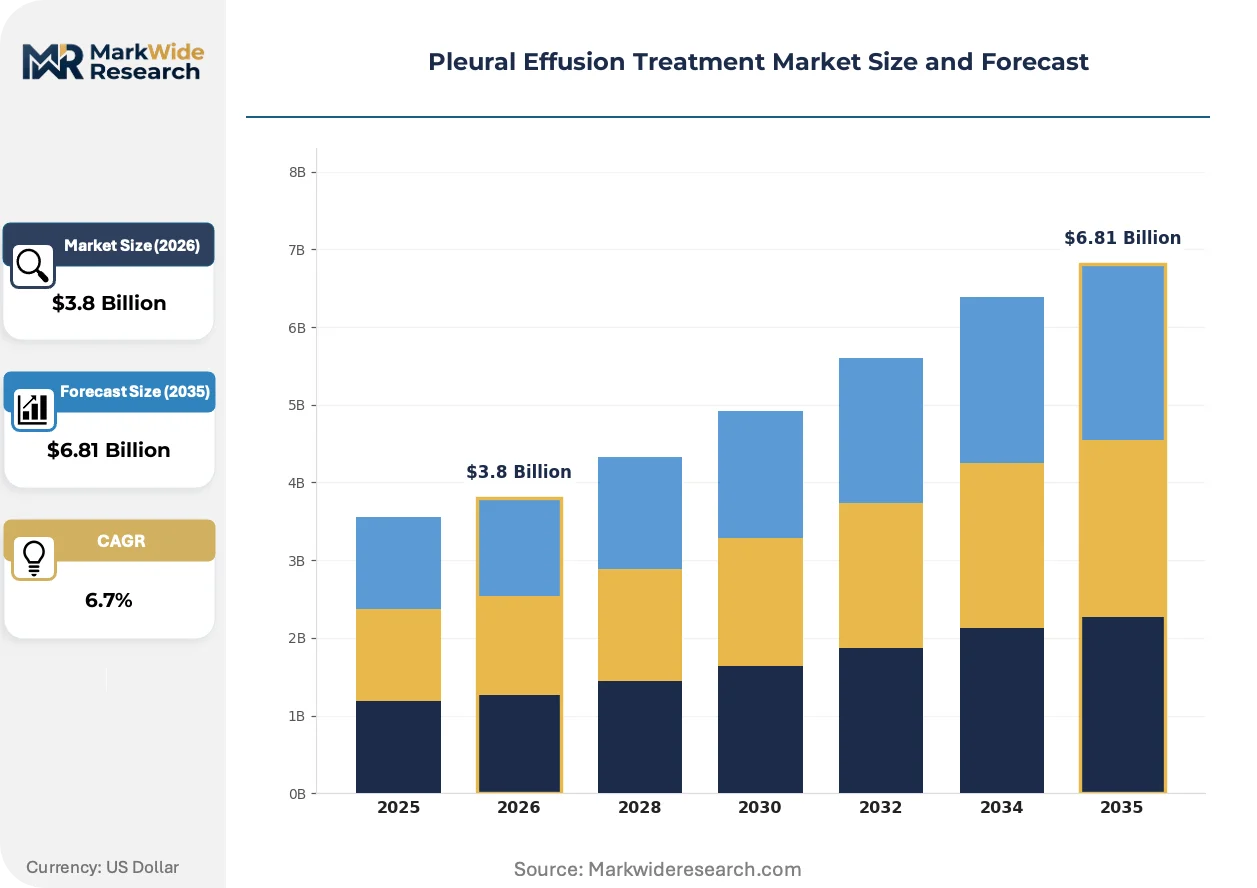
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thoracentesis, Chest Tube, Pleurodesis, Video-Assisted Thoracic Surgery End User: Hospitals, Outpatient Clinics, Specialty Centers, Homecare Settings Therapy Area: Oncology, Cardiology, Pulmonology, Infectious Diseases Delivery Mode: Inpatient, Outpatient, Teletherapy, Remote Monitoring |
| Companies Covered | Smiths Medical, Cardinal Health, B. Braun Melsungen AG, Boston Medical Products Inc., Biometrix, Becton, Dickinson and Company, Rocket Medical, Teleflex Inc., Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pleural Effusion Treatment Market Emerging Trajectories
Digital telemetry, regulatory harmonization pressures, and ambulatory care migration are converging to transform how pleural effusion therapy is delivered, reimbursed, and monitored across acute and post-acute settings.
Wireless pressure-sensing catheters with Bluetooth Low Energy transmission is rewriting the economics of post-discharge monitoring by enabling automated alerts for tube occlusion or air leak without nursing home visits. Community oncology practices in the United States are piloting these systems for malignant effusion patients completing systemic therapy. The structural consequence is a compression of home health nursing utilization and a shift toward device-plus-subscription revenue models.
REACH regulation amendments targeting per- and polyfluoroalkyl substances in medical device coatings are forcing reformulation of hydrophobic catheter surface treatments across European manufacturing. German and French notified bodies are demanding extended biocompatibility studies for fluoropolymer alternatives. Thoracic surgery kit suppliers with early bio-based coating certifications are capturing preferred supplier status in EU hospital tenders.
Hospital purchasing consortia are consolidating pleural drainage procurement into multi-year sole-source agreements that bundle catheters, suction canisters, and remote monitoring subscriptions. Group purchasing organizations in the United States are displacing individual hospital negotiations with standardized specifications and volume commitments. This concentration is most visible in the Southeast and Midwest, where Catholic health systems and regional IDNs dominate respiratory care service lines.
Pleural Effusion Treatment Market Segmentation
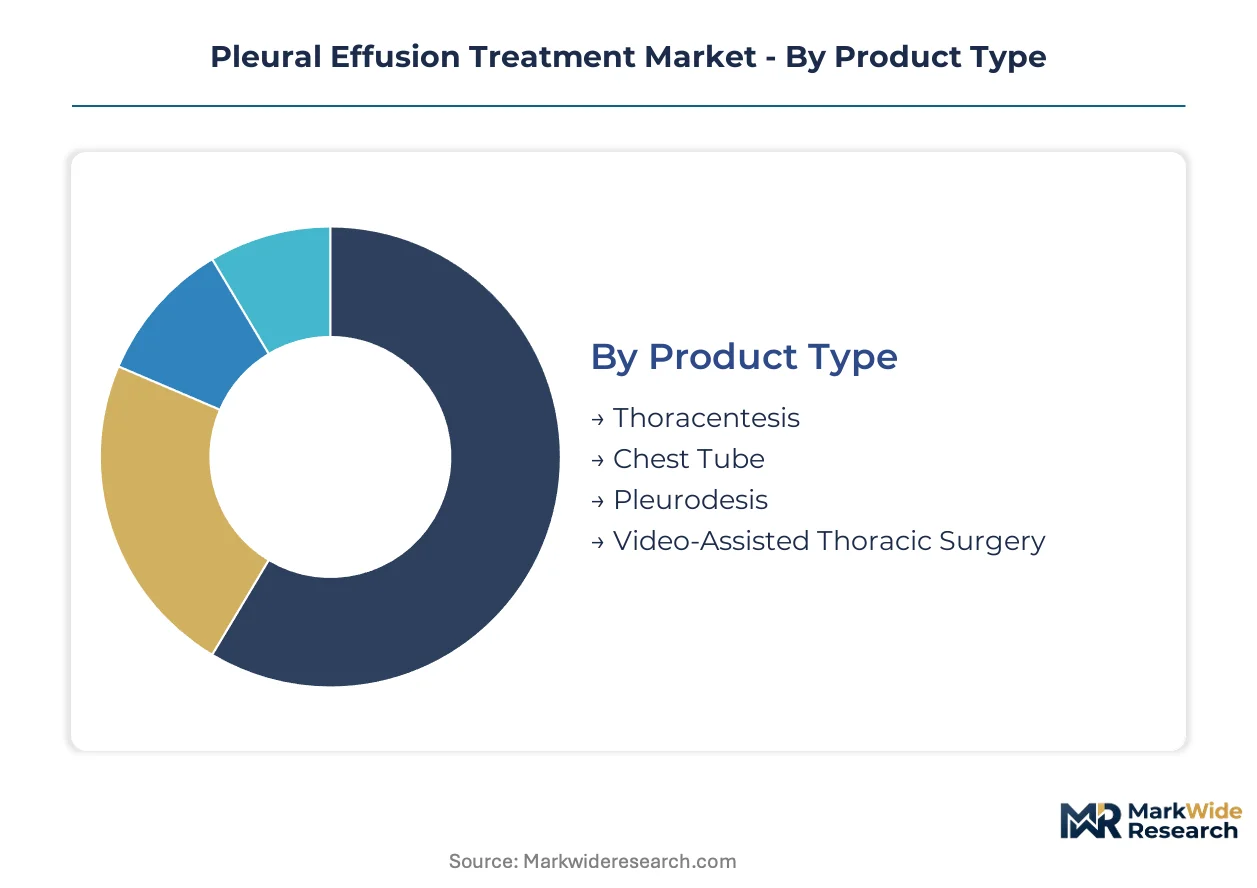
Pleural effusion treatment modalities span capital-intensive surgical suites to disposable catheter systems, creating distinct investment profiles and margin structures across product categories. Understanding how segments cluster by upfront expenditure, reimbursement intensity, and clinical workflow integration reveals where procurement budgets concentrate and where technology substitution accelerates.
Product Type:
Capital intensity varies sharply across intervention modalities, with surgical platforms demanding multimillion-dollar infrastructure while catheter-based systems operate on consumable economics.
- Thoracentesis:Ultrasound-guided needle aspiration using 18-21 gauge needles with one-way valve systems dominates first-line diagnostic and therapeutic drainage. Demand clusters in US emergency departments and German ambulatory oncology units where same-day discharge protocols reduce hospitalization costs.
- Chest Tube:Large-bore (28-36 French) and small-bore (8-14 French) silicone or polyurethane drainage systems with integrated suction control. Community hospitals in the US Southeast and Midwest are upgrading to digital suction regulators to meet value-based care readmission benchmarks.
- Pleurodesis:Chemical (talc, bleomycin, doxycycline) or mechanical abrasion techniques to achieve pleural symphysis. Talc poudrage via thoracoscopy retains preference in French and Italian thoracic surgery centers despite talc safety controversies.
- Video-Assisted Thoracic Surgery:Minimally invasive thoracoscopic platforms with 5-10mm optics and specialized instrumentation for biopsy and definitive pleurodesis. Academic medical centers in Boston, Heidelberg, and Tokyo anchor installed base; community adoption remains limited by fellowship-trained surgeon availability.
Most installed capacity flows through Chest Tube systems. Expansion is steepest in Video-Assisted Thoracic Surgery as regional referral networks consolidate complex cases.
End User:
Customer archetypes diverge by procurement sophistication, with integrated delivery networks leveraging volume leverage against standalone specialty centers optimizing for procedure throughput.
- Hospitals:Inpatient surgical suites and interventional pulmonology departments with 24/7 thoracic coverage. US hospital systems are consolidating pleural drainage procurement into multi-year sole-source agreements bundling hardware, disposables, and telemetry subscriptions.
- Outpatient Clinics:Ambulatory surgical centers and oncology infusion units performing same-day thoracentesis and indwelling catheter placement. German onco-pulmonology day clinics are expanding capacity faster than inpatient wards.
- Specialty Centers:Dedicated thoracic surgery institutes and cancer centers with high-volume pleurodesis programs. These facilities command premium reimbursement for complex recurrent effusions requiring multidisciplinary management.
- Homecare Settings:Direct-to-patient drainage management with visiting nurse oversight and remote monitoring support. US payer pressure to reduce length-of-stay is accelerating direct distribution of indwelling catheter kits bypassing hospital discharge pharmacies.
Revenue concentration remains heaviest in Hospitals. Homecare Settings are climbing the fastest as telemetric drainage systems enable early discharge protocols.
Therapy Area:
Clinical indication shapes product selection, with malignant effusions driving indwelling catheter adoption while cardiac etiologies favor rapid thoracentesis.
- Oncology:Malignant pleural effusions from lung, breast, and lymphoid primaries requiring recurrent drainage or definitive pleurodesis. US community oncology practices are piloting Bluetooth-enabled catheters for patients completing systemic therapy.
- Cardiology:Transudative effusions secondary to congestive heart failure managed with diuretic optimization and intermittent thoracentesis. German cardiology wards are integrating point-of-care ultrasound to reduce radiology dependency.
- Pulmonology:Parapneumonic effusions and complicated pneumonia requiring drainage and intrapleural fibrinolytics. British thoracic societies have published updated guidelines favoring early small-bore catheter placement over surgical intervention.
- Infectious Diseases:Empyema and tuberculous pleuritis demanding prolonged drainage and antimicrobial therapy. Indian tertiary centers report rising multidrug-resistant organism prevalence complicating catheter management.
Procedure volume concentrates in Oncology. Infectious Diseases represents the fastest-expanding indication as antimicrobial resistance prolongs drainage duration.
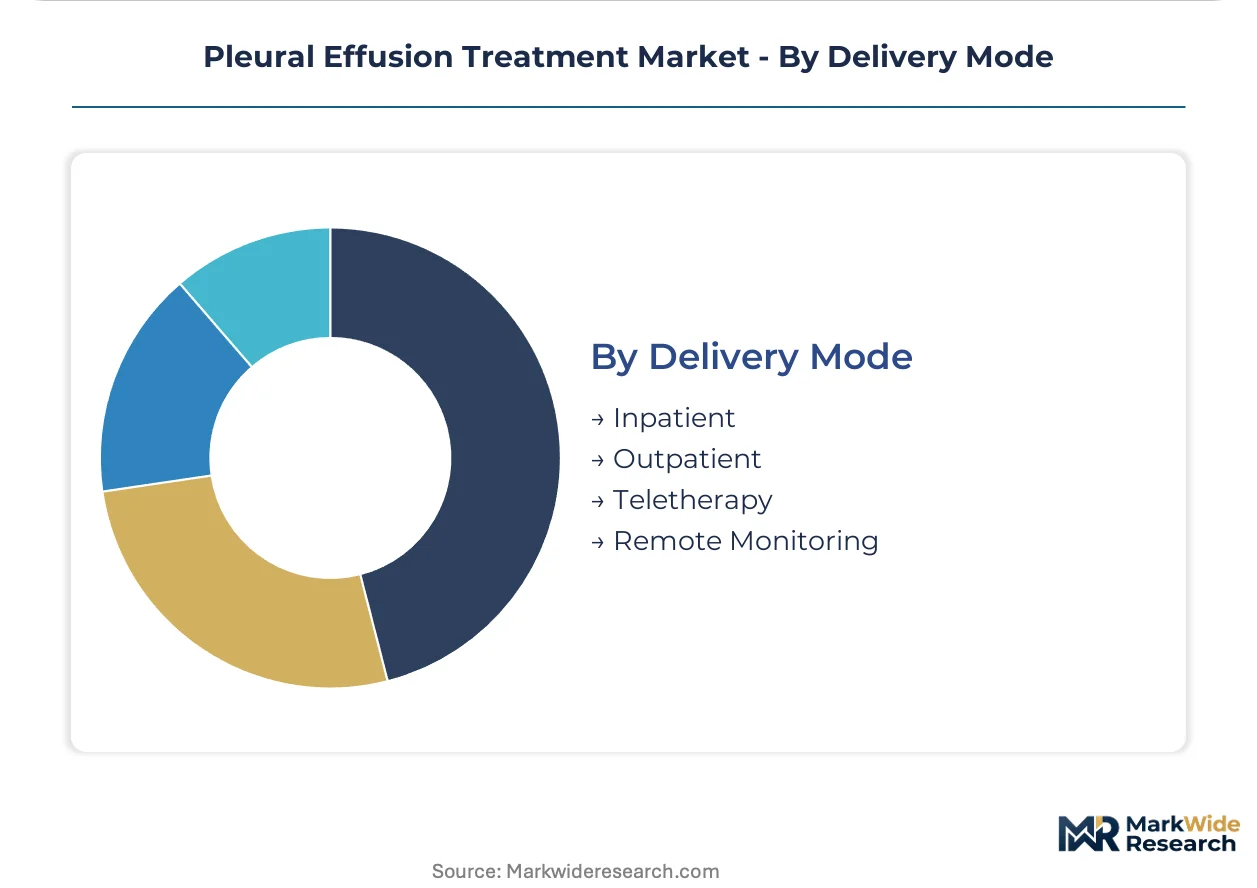
Delivery Mode:
Care setting migration is restructuring reimbursement economics, with remote capabilities capturing margin from traditional inpatient stays.
- Inpatient:Acute surgical drainage, complex pleurodesis, and hemodynamically unstable patients requiring continuous monitoring. CMS reimbursement differentials between inpatient and outpatient codes are narrowing, compressing hospital margins.
- Outpatient:Same-day thoracentesis, indwelling catheter placement, and chemical pleurodesis in ambulatory surgical centers. French and German same-day surgery incentives are accelerating facility investment.
- Teletherapy:Virtual consultation for effusion management decisions and remote pleurodesis eligibility assessment. US telehealth parity laws post-pandemic have stabilized reimbursement for these encounters.
- Remote Monitoring:Cellular-connected drainage systems transmitting pressure, volume, and air leak data to centralized nursing platforms. Smiths Medical and BD are competing to anchor hospital contracts through subscription-based monitoring services.
Patient volume still flows predominantly through Inpatient channels. Remote Monitoring is gaining share fastest as 30-day readmission penalties intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's respiratory care infrastructure strains under oncology patient volumes that outpace US interventional pulmonology capacity expansion, while Japan's super-aging demographic accelerates demand for minimally invasive alternatives to surgical pleurodesis.
United States
Hospital systems in Boston and Houston consolidate interventional pulmonology departments to manage malignant effusions through catheter-based approaches. FDA guidance on Class II thoracic devices accelerates 510(k) pathways for telemetry-enabled drainage hardware. Southeast purchasing consortia bundle catheter-and-monitoring contracts across Catholic health networks.
Germany
Aging demographics and lung malignancy prevalence strain thoracic surgery capacity in Heidelberg and Munich academic centers. EU Medical Device Regulation elevates clinical evidence requirements for pleurodesis kits, filtering marginal competitors from procurement tenders. Bavarian hospital networks prioritize indwelling catheter alternatives to repeated thoracentesis.
Japan
METI healthcare infrastructure investments target respiratory disease management for patients over 75 in Tokyo and Osaka metropolitan areas. PMDA regulatory frameworks accommodate digital health integration for remote drainage monitoring. Kansai region oncology centers pilot Bluetooth-enabled catheters for ambulatory malignant effusion care.
United Kingdom
NHS England reimbursement differentials between inpatient and outpatient pleurodesis codes compress hospital margins on surgical drainage. British Thoracic Society guidelines favor early small-bore catheter placement over thoracotomy for parapneumonic effusions. London and Manchester academic centers anchor video-assisted thoracic surgery training pipelines.
India
Tertiary centers in Mumbai and Delhi report rising multidrug-resistant organism prevalence complicating empyema catheter management. CDSCO regulatory pathways for imported thoracic devices require extended biocompatibility documentation. Western and Southern state hospital procurement is shifting toward disposable drainage systems over reusable surgical instrumentation.
Pleural Effusion Treatment Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with telemetry-integrated systems commanding premium positioning against commodity catheter suppliers. The vendor base clusters around three strategic archetypes: diversified medical technology conglomerates with hospital contracting leverage, interventional pulmonology specialists with procedure-specific hardware expertise, and regional fabricators serving price-sensitive institutional procurement. Dominant competitive moves include sole-source agreement consolidation through group purchasing organizations and backward integration into medical-grade silicone compounding to secure feedstock stability.
Among diversified technology conglomerates, Becton, Dickinson and Company and Cardinal Health anchor hospital procurement through bundled hardware-and-service contracts that reduce per-procedure cost variability. Teleflex Inc. exemplifies the interventional specialist archetype with focused positioning on indwelling catheter designs that extend dwell time. Smiths Medical occupies a distinct position at the telemetry-enabled vector, leveraging cellular-connected drainage systems to capture recurring subscription revenue beyond initial device placement.
| Leading Market Players |
|---|
| Smiths Medical |
| Cardinal Health |
| B. Braun Melsungen AG |
| Boston Medical Products Inc. |
| Biometrix |
| Becton, Dickinson and Company |
| Rocket Medical |
| Teleflex Inc. |
| Cook Medical |
| Others |
Supply Flow & Price Mechanics
Hospital purchasing consortia in the United States Southeast and Midwest anchor procurement volume, locking catheter-and-monitoring bundles into multi-year sole-source agreements that compress per-unit pricing variability and elevate switching costs for competing suppliers.
Pricing Analysis
Capacity additions in Malaysia and Thailand are reshaping price floors for medical-grade silicone components, pressuring legacy manufacturers to absorb margin compression or reformulate toward bio-based alternatives. Three-tier pricing structure across telemetry-integrated premium systems, standard indwelling catheters, and economy thoracentesis kits separates vendors by FDA 510(k) pathway complexity and after-sales monitoring bundling. Cost compression in the standard catheter tier is intensifying because REACH regulation amendments force coating reformulation investments. Community hospitals exhibit highest price sensitivity, while academic medical centers prioritize dwell-time performance and EHR integration over per-unit cost.
Supply Chain Analysis
Ocean freight rate volatility from Southeast Asian petrochemical corridors to European notified bodies is elevating landed cost uncertainty for thoracic intervention kits awaiting CE marking validation. Medical-grade silicone compounding concentrates in Malaysia, Thailand, and Germany, with catheter assembly tethered to cleanroom manufacturing clusters in Ireland and Costa Rica. Feedstock exposure to force majeure disruptions in Southeast Asian petrochemical corridors represents the dominant structural risk. Distribution runs through group purchasing organization contracts in the United States and direct hospital tenders in Germany, with emerging direct-to-patient channels bypassing traditional discharge pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pleural effusion treatment market reads as a late-cycle quality story, with payer pressure on length-of-stay accelerating demand-shift toward telemetry-enabled systems that command subscription premiums beyond hardware placement.
For Market Incumbents: Deploy backward integration into medical-grade silicone compounding to neutralize feedstock volatility exposure from Southeast Asian suppliers. Consolidate sole-source GPO contracts across Catholic health networks before emerging telemetry specialists achieve scale. Antibiotic-coated catheter substitution threatens legacy polyurethane lines without formulation redevelopment investment. For New Entrants and Emerging Players: Begin with Japan's super-aging respiratory care infrastructure, where METI investments and PMDA digital health frameworks create regulatory alignment for Bluetooth-enabled ambulatory systems. Homecare channel expansion offers the most penetrable white-space, bypassing hospital procurement through direct-to-patient distribution with telehealth nursing support. Anchor initial go-to-market through Kansai region oncology center pilot programs. For Investors and Strategic Acquirers: Diversified medical technology conglomerates with hospital contracting leverage are the most active acquirer in this space, seeking telemetry capabilities to bundle with existing interventional portfolios. Target acquisition archetypes include interventional pulmonology specialists with indwelling catheter IP and remote monitoring SaaS developers with FDA 510(k) clearance. Watch for CMS reimbursement differential narrowing between inpatient and outpatient pleurodesis codes as inflection signal for hardware upgrade budget compression.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry-Enabled Drainage System Launch | Smiths Medical and BD compete to anchor hospital contracts through cellular-connected hardware capturing recurring subscription revenue. |
| CE Marking Pathway Investment | EU MDR stricter clinical evidence requirements filter marginal competitors and consolidate procurement around established technical files. |
| Hospital System Partnership | Southeast purchasing consortia bundle catheter-and-monitoring contracts across Catholic health networks displacing individual negotiations. |
| Software Companion Development | AI-assisted drainage algorithms enable predictive effusion recurrence scoring creating SaaS revenue streams atop hardware placements. |
| Reimbursement Strategy | Value-based care contracts reduce readmission penalties through early discharge protocols enabled by remote monitoring capabilities. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with interventional pulmonologists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers with secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR technical file disclosures. Bottom-up installed base modeling and top-down expenditure flow analysis triangulated market sizing across telemetry-integrated and standard catheter categories.
Segment-weighted projections applied differential growth assumptions across thoracentesis, chest tube, pleurodesis, and video-assisted thoracic surgery modalities, with end-user splits between hospital inpatient, outpatient clinic, specialty center, and homecare settings. CAGRs derived from procedure volume elasticity to oncology incidence, interventional pulmonology workforce expansion constraints, and payer migration incentives toward ambulatory care. Forecast inputs incorporated REACH coating regulation compliance costs and silicone feedstock price trajectory sensitivity.
Several conditions sit outside the modeled scope, including force majeure disruptions in Southeast Asian petrochemical corridors, unanticipated FDA digital health cybersecurity guidance revisions, and interventional pulmonology fellowship training pipeline expansion beyond academic medical center capacity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Interventional Pulmonology Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market
Respiratory Therapy
Respiratory Disorders Treatment Market
Respiratory Therapy
Diaphragm Pacing Therapy System Market
Respiratory Therapy
Artificial Lung Market
Respiratory Therapy
Respiratory Trainer Market
Respiratory Therapy
Respiratory Inhaler Market
Respiratory Therapy
Metered Dose Inhalers Market
Respiratory Therapy
Bronchial Thermoplasty Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Global Oxygen Therapy Market
Respiratory Therapy
Respiratory Gating Market