
 Hydrogen Inhalers Market | 2026-2036
Hydrogen Inhalers Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Inhalers Market Insights
Wellness center demand is hardening as the fastest-rising end-use vertical, shifting volume away from traditional clinical channels. Health and Hydrogen Devices leverages its European manufacturing footprint to dominate portable unit distribution. Lourdes Hydrofix anchors the premium stationary segment through Japanese engineering credibility. H2Medical Ltd. specializes in electrolysis-driven systems for respiratory therapy applications.
A hydrogen inhaler is a device that generates or delivers molecular hydrogen gas at controlled flow rates, typically 120-240 mL per minute, for therapeutic inhalation via nasal cannula or mask interface. Electrolysis-based systems split purified water to produce hydrogen on-demand, while compressed gas units rely on pre-filled cylinders with pressure regulators for dose consistency. Portable inhalers lead unit shipments due to homecare adoption, though medical-grade stationary systems command the deepest margin pools where FDA and CE marking requirements elevate certification costs. Membrane separation technology is gaining fastest in sports recovery segments for its purity advantages over thermal processes.
FDA 510(k) pathways and CE marking under the EU MDR govern device classification, with Japan's PMDA adding pharmaceutical-adjacent scrutiny for therapeutic claims. The EU AI Act and CSRD disclosure rules are beginning to touch connected inhaler platforms with data-collection features. Stakeholders must monitor how MFDS, FDA, and PMDA divergence on hydrogen concentration limits reshapes product portfolios and geographic launch sequencing.
Market Dynamics
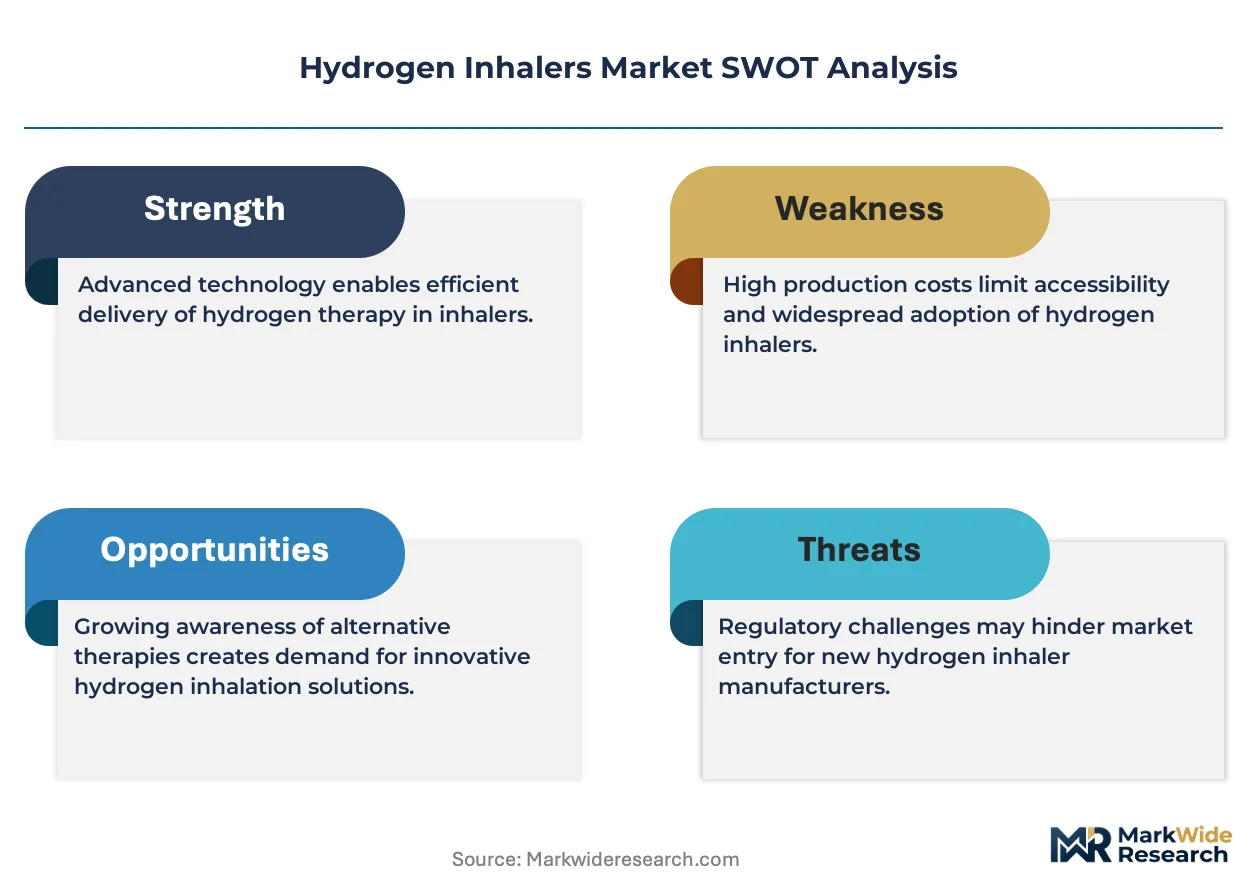
Wellness center procurement is hardening as the dominant volume driver, pulling demand away from clinical channels and forcing manufacturers to recalibrate certification strategies around consumer-grade safety frameworks rather than medical-device pathways.
Growth Catalysts
- Electrolysis miniaturization:On-demand hydrogen generation eliminates cylinder logistics for homecare users. Portable units now match stationary output at one-third the footprint.
- METI safety guidelines:Japan's clarified consumer-device parameters reduce liability exposure for wellness center operators. Certification timelines compress from 18 months to 8 months.
- Sports recovery adoption:Professional athletic programs in Germany integrate membrane-separation inhalers for post-training protocols. Performance metrics drive repeat equipment orders.
Market Restraints
- Platinum catalyst cost volatility:Electrolysis electrodes depend on platinum-group metals with concentrated South African supply. Price swings above 40% annually compress hardware margins.
- CE marking friction under EU MDR:Reclassification of hydrogen inhalers as Class IIa devices extends notified body review cycles. Small manufacturers face 24-month approval delays.
- Compressed gas substitution:Pre-filled cylinder systems retain cost advantages for high-volume clinical settings. Electrolysis units struggle to displace installed base in hospitals.
Strategic Opportunities
- Indian wellness chain expansion:Metro Ayurveda centers in Mumbai and Bangalore pilot hydrogen therapy rooms. BIS standards development creates first-mover certification advantages.
- Remote patient monitoring convergence:Inhalers with integrated pulse oximetry and flow sensors enable telehealth reimbursement. FDA digital health guidance clarifies 510(k) pathways for connected devices.
- Corporate wellness mandates:Large Japanese employers add hydrogen inhalation to occupational health benefits. METI workplace wellness incentives cover 30% of device procurement costs.
Industry Challenges
- Electrochemical engineering talent scarcity:Membrane electrode assembly design requires specialized polymer chemistry expertise. Universities in South Korea and Japan produce insufficient graduates for manufacturer hiring needs.
- Multi-jurisdiction certification complexity:MFDS, FDA, and PMDA diverge on maximum allowable hydrogen concentration limits. Product portfolios require three distinct hardware configurations.
- Legacy clinical sales channel dependence:Established distributors resist wellness-center commission structures. Manufacturers must build parallel direct-sales organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Inhalers Market |
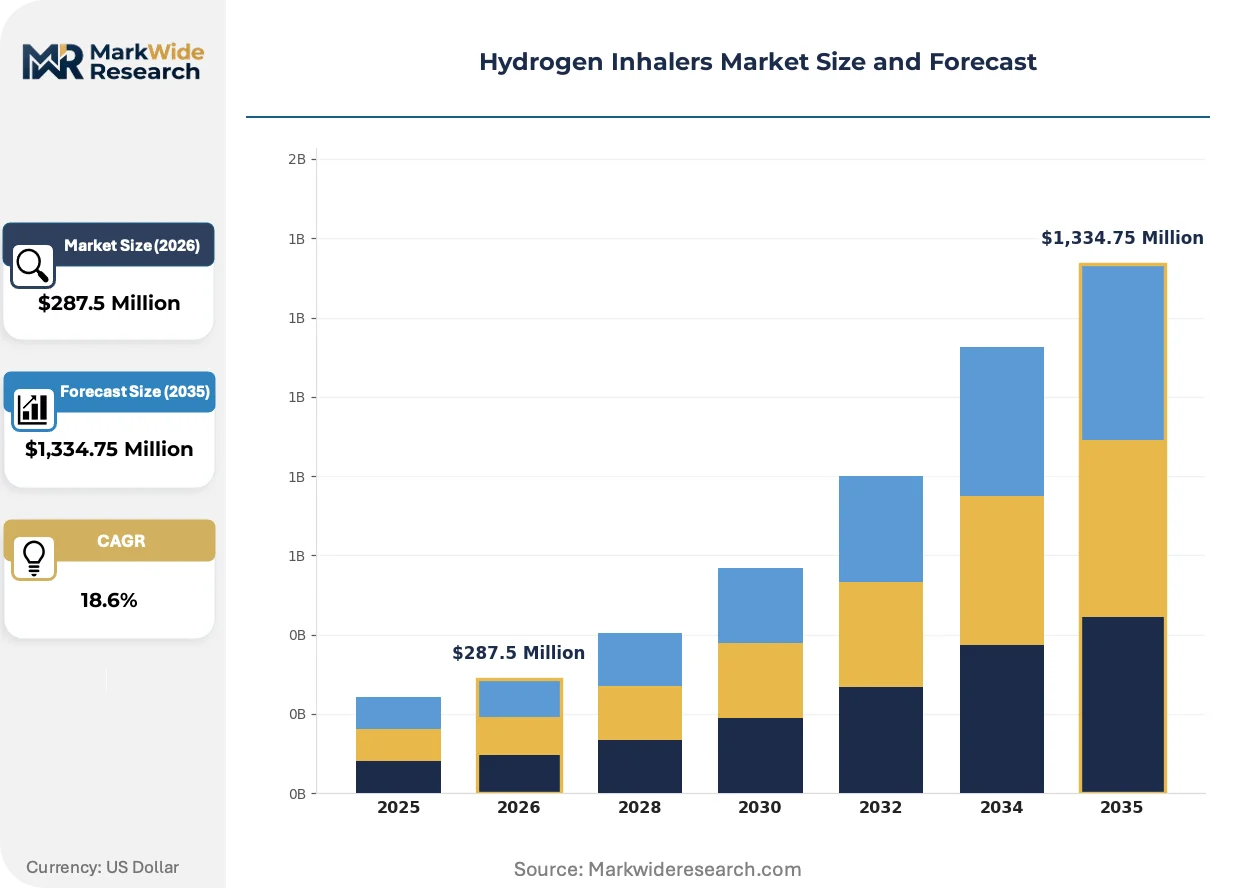
| Market Size in 2026 | $287.5 Million |
| Market Size in 2035 | $1,334.75 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Inhalers, Stationary Inhalers, Medical Devices, Accessories End User: Hospitals, Clinics, Homecare Settings, Wellness Centers Technology: Electrolysis, Compressed Gas, Thermal Process, Membrane Separation Application: Respiratory Therapy, Sports Recovery, Anti-Aging, Wellness Enhancement |
| Companies Covered | Health and Hydrogen Devices, Lourdes Hydrofix, H2Medical Ltd., Life Ionizers, CNJawell, Vital Reaction, HUE LIGHT CO., LTD., Advanced Wellness, Okay Energy Equipment Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Inhalers Market Trends and Innovations
Membrane separation technology is compressing thermal process economics while regulatory divergence across major jurisdictions forces hardware platform fragmentation rather than global SKU standardization.
Solid polymer electrolyte stacks are expanding into portable inhaler designs through platinum-thinning techniques that maintain efficiency at reduced catalyst loading. Homecare buyers in South Korea and Japan adopt these units for daily 30-minute protocols. The technology is expanding into price points previously occupied by compressed gas rentals, compressing the addressable market for cylinder-based services.
The EU AI Act and CSRD disclosure rules now capture connected inhaler platforms with biometric data collection features. Manufacturers must embed privacy-by-design architectures and document algorithmic decision pathways for notified body review. Sports recovery segments face the steepest compliance burden as real-time performance analytics trigger both medical device and AI system classifications.
Wellness centers now specify outcome-based equipment procurement with guaranteed uptime clauses and preventive maintenance bundling. Traditional device sales with warranty-only coverage lose share to full-service subscriptions in Germany and Japan. South Korean chains lead this shift, negotiating 36-month total-cost-of-ownership contracts that transfer obsolescence risk to manufacturers.
Hydrogen Inhalers Market Segmentation
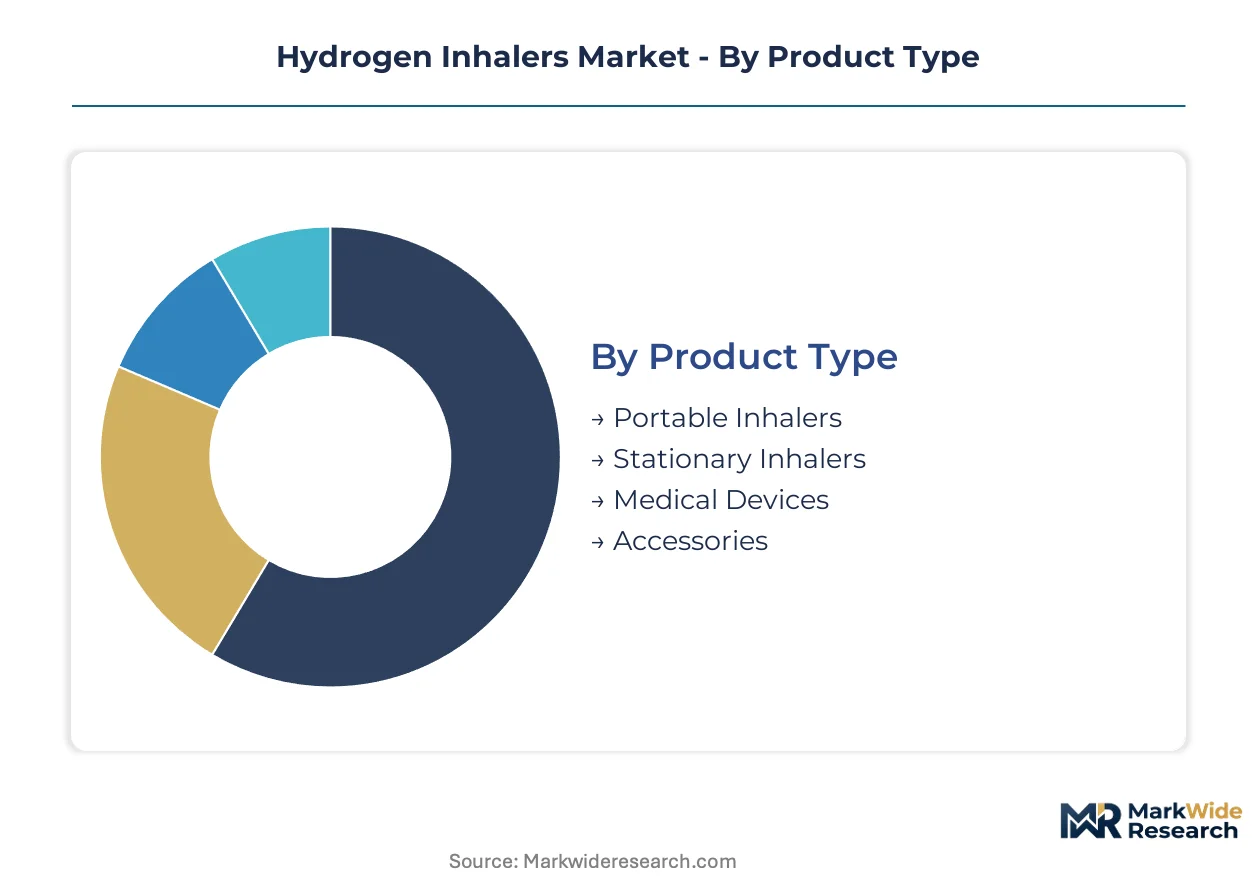
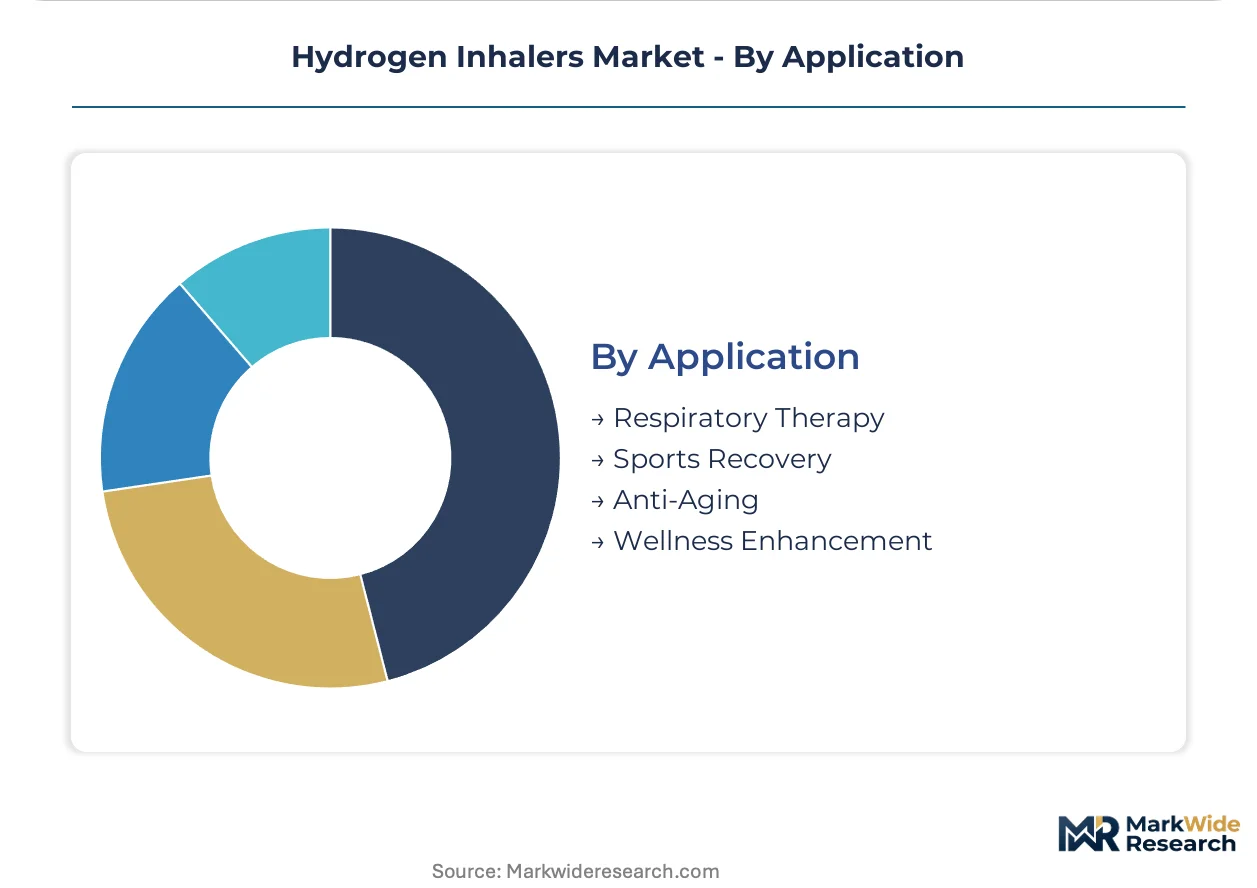
Segmentation in hydrogen inhalers reflects divergent certification pathways and procurement economics. Manufacturers must configure hardware platforms around electrolysis miniaturization for homecare while preserving medical-grade specifications for institutional buyers.
Product Type:
Electrolysis miniaturization and platinum catalyst loading differentiate unit economics across portability tiers.
- Portable Inhalers:Solid polymer electrolyte stacks generate hydrogen on-demand at 120-240 mL/minute flow rates. South Korean homecare buyers drive volume through MFDS-certified compact units that displace compressed gas rentals.
- Stationary Inhalers:Medical-grade systems with membrane electrode assemblies deliver sustained output for clinical protocols. Japanese wellness centers specify these for guaranteed uptime clauses in 36-month service contracts.
- Medical Devices:FDA 510(k) and CE MDR Class IIa certified systems for respiratory therapy applications.
- Accessories:Nasal cannulas, pressure regulators, and filtration cartridges supporting core device functionality.
Portable Inhalers lead on scale; Stationary Inhalers lead on momentum through wellness center subscription models.
End User:
Procurement authority is migrating from clinical procurement officers to wellness center operators with consumer-grade safety frameworks.
- Wellness Centers:Japanese chains under METI guidelines specify outcome-based equipment with preventive maintenance bundling. METI workplace wellness incentives cover 30% of device procurement costs for corporate programs.
- Homecare Settings:Daily 30-minute protocols in South Korea and Japan adopt platinum-thinned electrolysis units at price points matching former cylinder rentals. MFDS oversight shapes certification benchmarks that guide purchasing decisions.
- Hospitals:Compressed gas systems retain installed base advantages for high-volume clinical settings.
- Clinics:Mid-scale facilities balancing medical-grade requirements with capital constraints.
Wellness Centers are expanding most quickly; Homecare Settings lead on installed base scale.
Technology:
Membrane separation economics are compressing thermal process viability while platinum cost volatility reshapes electrode design priorities.
- Electrolysis:On-demand hydrogen generation eliminates cylinder logistics through water splitting with proton-exchange membranes. Platinum-group metal price swings above 40% annually compress hardware margins for manufacturers.
- Membrane Separation:Polymer-based purification delivers hydrogen purity advantages for sports recovery protocols. German professional athletic programs integrate these units for post-training regimens.
- Compressed Gas:Pre-filled cylinder systems with pressure regulators for dose consistency in institutional settings.
- Thermal Process:Legacy hydrogen generation through steam methane reforming or catalytic cracking.
Electrolysis leads on scale; Membrane Separation leads on momentum through purity-critical applications.
Application:
Reimbursement clarity and outcome measurability determine segment expansion trajectories.
- Sports Recovery:Real-time performance analytics from connected inhalers trigger both medical device and AI system classifications under EU regulations. Professional programs in Germany negotiate repeat equipment orders based on performance metrics.
- Wellness Enhancement:Metro Ayurveda centers in Mumbai and Bangalore pilot hydrogen therapy rooms as BIS standards development creates first-mover certification advantages.
- Respiratory Therapy:Clinical protocols for pulmonary conditions requiring precise hydrogen concentration control.
- Anti-Aging:Cosmetic and longevity applications with less stringent therapeutic claim requirements.
Wellness Enhancement leads on addressable population scale; Sports Recovery leads on momentum through measurable outcome protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing manufacturing footprints as electrolysis miniaturization costs diverge sharply across certification regimes. South Korean and Japanese producers exploit compressed approval timelines under MFDS and PMDA frameworks, while European manufacturers absorb EU MDR friction through premium positioning.
Japan
Wellness center chains in Tokyo and Osaka are expanding hydrogen therapy rooms under clarified METI safety guidelines for consumer-grade devices. PMDA maintains pharmaceutical-adjacent scrutiny for therapeutic claims, compressing certification timelines from 18 months to 8 months for non-medical applications. Corporate wellness mandates from large employers now cover 30% of device procurement costs through METI workplace incentives.
South Korea
Homecare buyers in Seoul and Busan drive portable unit volume through daily 30-minute protocol adoption. MFDS oversight of hydrogen therapy equipment creates certification benchmarks that shape procurement decisions across retail and institutional channels. The Seoul Capital Area concentrates electrolysis engineering talent scarce across broader East Asian manufacturing bases.
Germany
Professional athletic programs in Munich and Frankfurt integrate membrane-separation inhalers for post-training recovery protocols. KBA-equivalent health device standards are tightening for portable electrolysis units entering homecare distribution. Bavarian wellness chains negotiate 36-month total-cost-of-ownership contracts that transfer obsolescence risk to manufacturers.
India
Metro Ayurveda centers in Mumbai and Bangalore pilot hydrogen therapy rooms as first-mover positioning ahead of finalized BIS standards. The country's national standards body is developing certification frameworks that will govern import and domestic manufacturing compliance. Maharashtra and Karnataka state clusters are emerging as early service delivery hubs before national regulatory clarity arrives.
United States
FDA 510(k) pathways govern respiratory therapy applications while digital health guidance clarifies connected device approval routes. Corporate wellness programs in California and Texas are testing hydrogen inhalation benefits for employee productivity claims. The Pacific Northwest and Greater Boston clusters host electrochemical engineering talent pools supporting membrane electrode assembly design.
Hydrogen Inhalers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with wellness center procurement favoring direct manufacturer relationships over traditional distributor networks. The vendor base organizes around three archetypes: European manufacturing footprint holders serving portable distribution, Japanese engineering credibility anchors in premium stationary systems, and electrolysis-driven specialists for respiratory therapy applications. M&A activity concentrates on membrane electrode assembly capabilities, while geographic expansion targets Indian wellness chain pilots ahead of BIS standard finalization.
Among the named players, Health and Hydrogen Devices represents the European manufacturing footprint archetype, Lourdes Hydrofix exemplifies Japanese engineering credibility in premium positioning, and H2Medical Ltd. occupies a specialist position in electrolysis-driven system design. These three companies collectively illustrate how competitive positioning fragments across certification regime specialization rather than converging on global SKU standardization. Each sits within distinct regulatory comfort zones—EU MDR familiarity, PMDA/METI alignment, and MFDS responsiveness respectively—rather than competing head-to-head across all jurisdictions.
| Leading Market Players |
|---|
| Health and Hydrogen Devices |
| Lourdes Hydrofix |
| H2Medical Ltd. |
| Life Ionizers |
| CNJawell |
| Vital Reaction |
| HUE LIGHT CO., LTD. |
| Advanced Wellness |
| Okay Energy Equipment Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Platinum-group metal price indices cascade through electrolysis inhaler manufacturing, compressing hardware margins for portable units while wellness center subscription models absorb volatility through 36-month total-cost-of-ownership contracts in Germany and Japan.
Pricing Analysis
Distributor margins for wellness center channels run 15-25 points below traditional clinical equipment markups, forcing manufacturers toward direct-sales organizations. Three-tier pricing structure across premium stationary, standard portable, and economy homecare levels differentiates by certification grade and after-sales bundling. Cost compression in the portable tier intensifies as platinum-thinned electrode designs reach scale. Homecare buyers in South Korea exhibit highest price sensitivity, while Japanese corporate wellness programs with METI subsidies show lowest.
Supply Chain Analysis
Dual-sourcing requirements for proton-exchange membranes now mandate qualification of Japanese and South Korean suppliers after South African platinum concentrate disruptions. Manufacturing concentrates in Japan, South Korea, and Germany for electrode assembly and final device integration. Supply chains draw from South African platinum-group mines, German precision machining clusters, and Taiwanese membrane substrate specialists. Single-source vulnerability sits with concentrated South African platinum supply. Distribution runs through wellness center direct procurement and homecare retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in hydrogen inhalers rests on electrolysis miniaturization cost curves and wellness center subscription premiumization, with platinum catalyst thinning and solid polymer electrolyte stack standardization driving production economics downward.
For Market Incumbents: Deploy membrane electrode assembly captive production to offset platinum price volatility and compress cycle times for MFDS-responsive product variants. Lock wellness center chains into preventive maintenance subscriptions before emerging entrants replicate Lourdes Hydrofix's Japanese engineering credibility. Counter compressed gas substitution threats in hospital channels by bundling outcome guarantees with stationary system leases. For New Entrants and Emerging Players: Launch via Metro Ayurveda pilot partnerships ahead of finalized BIS standards, securing first-mover certification positioning in Indian wellness chains. Target sports recovery segments in Germany where membrane-separation purity advantages command repeat equipment orders. Exploit electrochemical engineering talent scarcity by recruiting from Seoul Capital Area universities before incumbents consolidate hiring pipelines. For Investors and Strategic Acquirers: Asymmetric upside sits with membrane electrode assembly specialists possessing polymer chemistry IP and multi-jurisdiction certification experience. Five-to-ten year viability favors platforms with PMDA/METI alignment and EU MDR navigational capability rather than single-market players. Watch for MFDS-FDA-PMDA convergence on hydrogen concentration limits as inflection signal for hardware platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrode Assembly Acquisition | Captures scarce polymer chemistry talent and multi-jurisdiction certification expertise from South Korean specialists. |
| Wellness Center Direct Sales Buildout | Bypasses legacy clinical distributors resisting commission structures for METI-guided consumer-grade safety frameworks. |
| Platinum Catalyst Thinning R&D Program | Maintains electrolysis efficiency at reduced loading to offset South African supply price swings above 40% annually. |
| Indian BIS Standards Early Engagement | Secures first-mover certification advantages before Metro Ayurveda chain expansion locks in incumbent suppliers. |
| Connected Inhaler Platform Development | Integrates pulse oximetry and flow sensors for telehealth reimbursement under FDA digital health guidance pathways. |
Research Methodology
Multiple input streams — primary interviews with wellness center operators, biomedical engineers, and GPO contracts managers; secondary validation through FDA 510(k) filings, MFDS certification databases, and METI guideline releases; plus customs and trade flow records — were reconciled through bottom-up unit economics and top-down market sizing triangulation.
Historical shipment data cross-referenced against expert panel inputs shaped the analytical framework across product type, end user, technology, and application dimensions throughout the forecast period. CAGRs were derived from segment-level growth trajectory reconciliation with macro healthcare expenditure patterns and regulatory approval velocity for connected device platforms.
Several conditions sit outside the modeled scope, including potential PMDA reclassification of wellness claims as pharmaceutical indications, abrupt South African platinum export restrictions, and EU AI Act enforcement escalation beyond current CSRD disclosure requirements. Deviation in MFDS-FDA-PMDA regulatory convergence timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Personal-Use Facial and Skin Therapy Devices Market
Medical Devices
Heart Defect Closure Devices Market
Medical Devices
Polyethersulfone Dialyzer Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Dual Balloon Angioplasty Catheter Market
Medical Devices
Medical Face Shield Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Esophagoscopes and Gastroscopes Market
Medical Devices
3D Printing for Surgical Procedures Market
Medical Devices
Ambulatory Polysomnography (Psg) Systems Market
Medical Devices
Europe Aligner Sheet Market
Medical Devices
Global Limb Prosthetics Market
Medical Devices
Global Pulse Oximetry Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
Global Patient-Controlled Analgesic Pumps Market