
 Spinal Access Systems Market | 2026-2036
Spinal Access Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Access Systems Market Analytics
ISO 13485 certification cycles for spinal device manufacturers is collapsing from twenty-four months to under fourteen months at leading notified bodies. Medtronic leverages its vertically integrated manufacturing footprint across multiple continents to sustain supply continuity for retractor and dilator portfolios. Stryker anchors its competitive stance through dedicated robotics divisions that pair access systems with navigation platforms. Globus Medical differentiates via specialized expandable cage and access technologies that target lateral spine approaches.
Spinal access systems constitute instruments designed to create and maintain operative corridors to the vertebral column, typically incorporating titanium or stainless steel retractor blades with working channel diameters between 18mm and 26mm for minimally invasive procedures. These devices serve the primary purpose of preserving neural and vascular structures while enabling visualization and instrument passage during thoracolumbar and cervical interventions. Retractors and dilators dominate current revenue pools due to their universal deployment across open and minimally invasive fusion procedures, while robotic-assisted technology represents the fastest-expanding segment as capital equipment budgets shift toward integrated surgical platforms. Endoscopic technology occupies a mature but stable position, particularly in Asian markets where cost constraints favor reusable optical systems over disposable alternatives.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation (MDR) establish divergent compliance burdens that fragment product launch sequencing across North American and European markets. The EU AI Act and FDA software-as-medical-device guidance are beginning to capture robotic-assisted access platforms that incorporate real-time navigation algorithms, adding validation layers that favor well-capitalized incumbents. Stakeholders must monitor how reimbursement coding for minimally invasive spine procedures evolves at CMS and parallel national payers, as procedural volume authorization directly determines capital allocation for access system upgrades.
Market Dynamics
Minimally invasive surgical corridors are compressing operative footprints while expanding visualization demands, forcing retractor and dilator portfolios to integrate with navigation platforms and robotic guidance systems.
Growth Catalysts
- EU Medical Device Regulation:The MDR's enhanced clinical evidence requirements for Class IIb spinal devices are accelerating consolidation among notified bodies, concentrating certification expertise at BSI and TÜV SÜD and favoring manufacturers with established technical documentation.
- Ambulatory surgical centers:Freestanding spine facilities in the United States are expanding procedural volumes for lumbar decompressions, driving demand for compact access systems with smaller sterile footprints and faster turnover protocols.
- Expandable cage technology:Lateral interbody fusion approaches utilizing expandable titanium cages are creating pull-through demand for specialized retractor systems with integrated nerve monitoring compatibility.
Market Restraints
- Titanium alloy supply concentration:Aerospace and defense procurement cycles in the United States and Japan are constraining spot availability of Ti-6Al-4V ELI grades, forcing spinal device manufacturers to extend raw material hedging horizons.
- EU AI Act classification thresholds:Real-time navigation algorithms embedded in robotic access platforms face reclassification as high-risk AI systems, triggering additional conformity assessment layers that extend European launch timelines.
- Reusable endoscope durability:Optical channel degradation in high-cycle sterilization environments limits serviceable lifespan of Asian-manufactured rigid endoscopes, creating hidden total cost of ownership penalties versus disposable alternatives.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentive allocations for high-value orthopedic implants are attracting contract manufacturing investments that could localize access system assembly for South Asian and Middle Eastern markets.
- Navigation-robotics convergence:Integration of intraoperative imaging with autonomous retractor positioning is opening premium pricing tiers for systems that reduce fluoroscopy exposure in pediatric and adolescent scoliosis corrections.
- Direct-to-hospital distribution:Bypassing traditional distributor networks for capital equipment sales is compressing sales cycles for integrated access-robotic platforms at consolidated United States health systems.
Industry Challenges
- ISO 13485:2016 transition audits:Leading notified bodies are collapsing certification cycles but simultaneously intensifying scrutiny of software lifecycle processes, forcing quality system rewrites for navigation-enabled access platforms.
- OR integration complexity:Hybrid operating rooms require electromagnetic interference shielding and spatial calibration protocols that extend installation timelines for robotic access systems.
- Sterile processing standardization:Divergent hospital protocols for single-use versus reprocessed retractor blades create inventory management friction and complicate field service deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Access Systems Market |
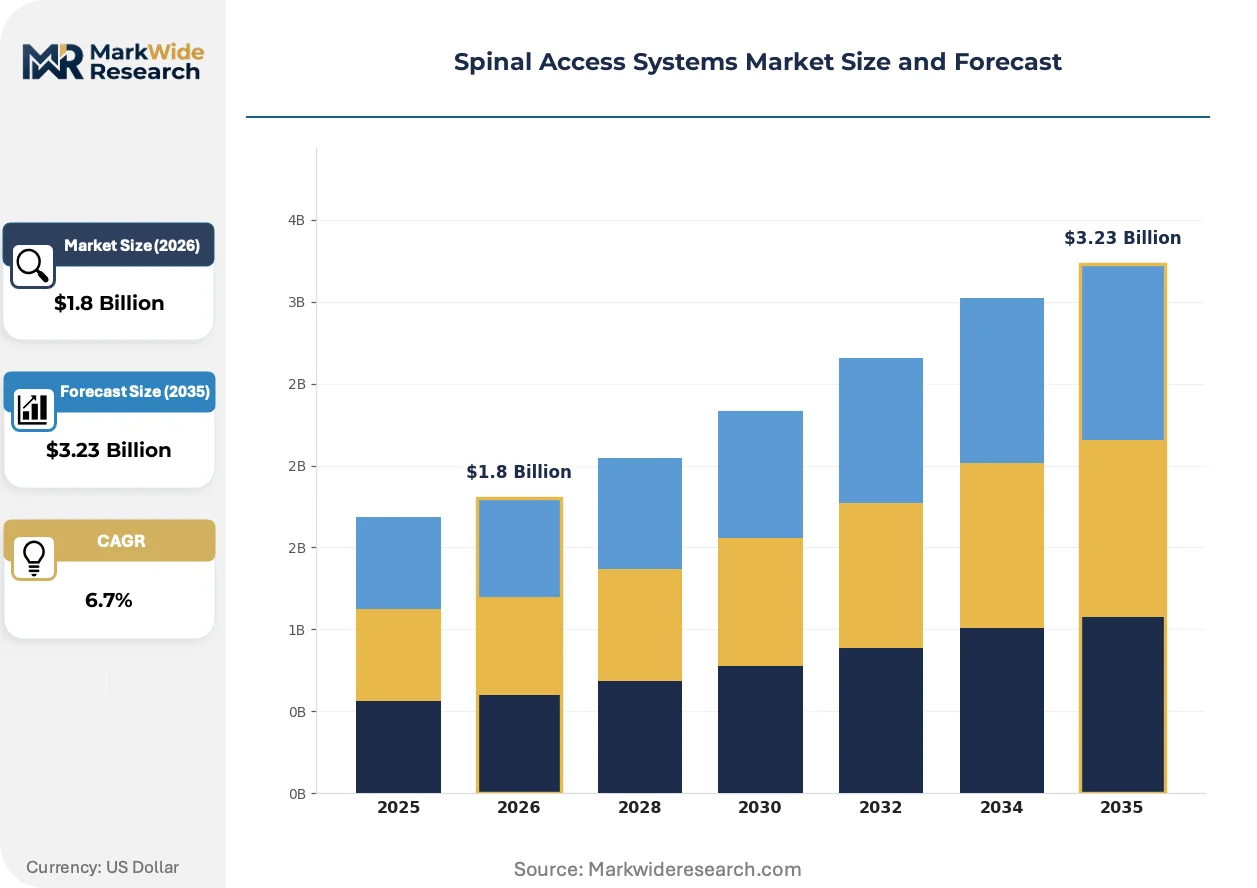
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retractors, Cannulas, Trocar Systems, Dilators Technology: Endoscopic, Fluoroscopic, Robotic-assisted, Open Surgery End User: Hospitals, Surgical Centers, Orthopedic Clinics, Rehabilitation Facilities Application: Spinal Fusion, Decompression Surgery, Discectomy, Tumor Resection |
| Companies Covered | Medtronic, Stryker, Johnson & Johnson, Globus Medical, NuVasive, B. Braun, SeaSpine, Alphatec Spine, Spineology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Access Systems Market Evolving Landscape
Access system architectures are fragmenting into modular component ecosystems that separate mechanical retraction from optical delivery and navigation tracking, enabling upgrade paths that protect capital investments.
Single-use polymer retractor blades with integrated suction and illumination channels are decomposing traditional stainless steel instrument sets in high-volume United States ambulatory centers. Hospital materials management departments are adopting these disposable configurations to eliminate reprocessing bottlenecks and reduce sterilization validation burdens. The shift is compressing average selling prices for conventional reusable retractor systems while expanding recurring revenue pools for consumable-compatible platforms.
FDA software-as-medical-device guidance is capturing navigation algorithms that previously operated in regulatory gray zones, forcing spinal access manufacturers to submit premarket notifications for real-time trajectory planning modules. The guidance's risk-based classification framework is segmenting the competitive landscape between systems with locked software versions and those permitting field updates. Robotic-assisted platforms with autonomous bone removal features face the steepest validation requirements, favoring incumbents with established quality management systems.
United States health system procurement committees are consolidating vendor relationships for spine service lines, bundling access systems with interbody cages, biologics, and robotics under multi-year enterprise agreements. Integrated delivery networks are leveraging volume commitments to extract price concessions and dedicated field engineering support. This concentration is visible most acutely in the Southeast and Midwest, where Catholic health initiatives and for-profit chains have achieved substantial market share in elective spine procedures.
Spinal Access Systems Market Segmentation
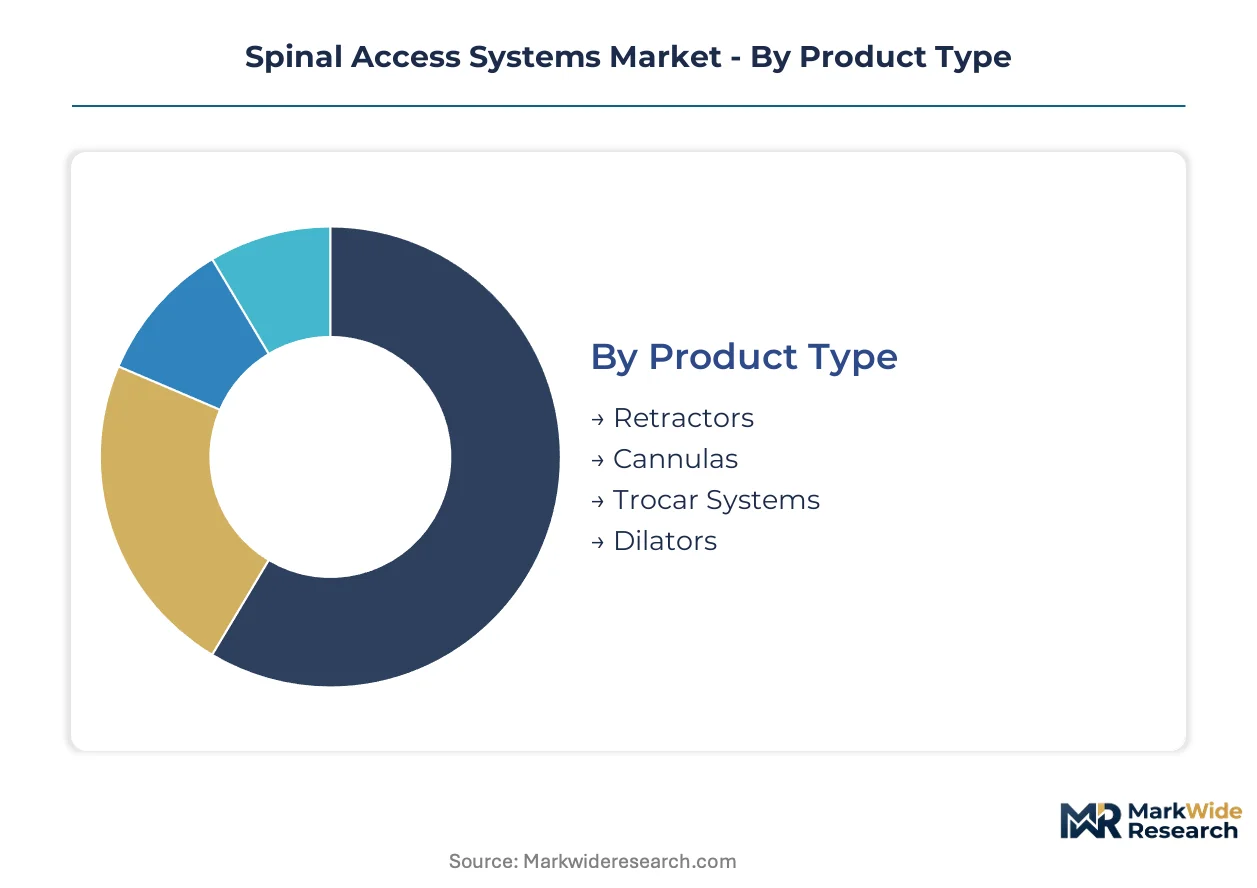
Segmentation in spinal access systems reveals how procurement channels, clinical workflows, and reimbursement pathways fragment demand across distinct customer configurations. Manufacturers must align product architectures with the specific throughput, capital intensity, and sterile processing protocols that characterize each segment's operational environment.
Product Type:
Channel-mix dynamics vary sharply across mechanical access instruments, with capital equipment flowing through distributor networks while consumable blades and modular components penetrate via direct-to-hospital contracts.
- Retractors:Titanium and stainless steel blade assemblies with working channel diameters between 18mm and 26mm constitute the foundational access platform for both open and minimally invasive approaches. United States hospital systems and specialized spine centers in Texas, Florida, and Ohio concentrate procurement of integrated retractor-navigation systems as they consolidate vendor relationships under enterprise agreements.
- Dilators:Serial fascial dilator sets with graduated diameters enable percutaneous corridor creation while preserving neural and vascular structures. Ambulatory surgical centers in the Southeast and Midwest favor compact, single-use polymer dilator configurations that eliminate reprocessing bottlenecks and accelerate OR turnover protocols.
- Cannulas:Tubular access conduits with integrated suction and illumination channels serve as working sleeves for endoscopic and microscopic procedures. Japanese and South Korean manufacturers dominate reusable rigid cannula supply for Asian markets where cost constraints favor sterilizable optical systems.
- Trocar Systems:Sharp obturator-sheath combinations facilitate initial percutaneous entry with minimal tissue displacement. These systems see concentrated deployment in lateral interbody fusion approaches where expandable cage technologies create pull-through demand for specialized access platforms.
Retractors dominate installed base across hospital systems and surgical centers. Dilators are where expansion concentrates as ambulatory facilities displace traditional reusable sets with disposable configurations.
Technology:
Cost tier stratification separates premium integrated platforms from standard mechanical systems, with capital budgets and reimbursement coding determining adoption velocity across clinical settings.
- Robotic-assisted:Autonomous retractor positioning systems integrated with intraoperative imaging and real-time navigation algorithms command premium pricing tiers. United States health systems with dedicated spine service lines in California, New York, and Massachusetts concentrate procurement as they seek to reduce fluoroscopy exposure in pediatric and adolescent scoliosis corrections.
- Endoscopic:Rigid and flexible optical systems with integrated working channels enable visualization through minimal access corridors. Asian markets in Japan, South Korea, and India favor reusable endoscopic platforms where high-cycle sterilization environments create total cost of ownership advantages over disposable alternatives.
- Fluoroscopic:C-arm guided access techniques rely on real-time radiographic visualization for trajectory confirmation. These systems maintain stable penetration in cost-constrained settings where capital equipment budgets preclude integrated navigation-robotics platforms.
- Open Surgery:Conventional retractor systems without integrated visualization or navigation support continue serving high-volume decompressions and trauma interventions. These configurations retain relevance in emerging markets and rural United States facilities where procedure complexity and reimbursement levels do not justify premium technology acquisition.
Fluoroscopic and open surgical technologies retain the broadest installed base. Robotic-assisted platforms are climbing the fastest as integrated delivery networks consolidate capital procurement around enterprise vendor relationships.
End User:
Customer type determines packaging, field service intensity, and sterile processing support requirements, with consolidated health systems extracting dedicated engineering coverage that smaller facilities cannot command.
- Hospitals:Academic medical centers and community hospital systems perform the majority of complex spinal fusion and deformity correction procedures. United States hospital procurement committees in the Southeast and Midwest leverage volume commitments to extract price concessions and bundled service agreements for access-robotic platforms.
- Surgical Centers:Freestanding ambulatory facilities concentrate on lumbar decompressions and single-level fusions with same-day discharge protocols. These settings drive demand for compact access systems with smaller sterile footprints and disposable-compatible retractor configurations that eliminate reprocessing validation burdens.
- Orthopedic Clinics:Specialized spine practices with in-office surgical suites perform select diagnostic and minor interventional procedures. These facilities favor portable, lower-capital access instruments that support limited procedure volumes without full OR infrastructure.
- Rehabilitation Facilities:Post-acute settings occasionally deploy access systems for pain management injections and minor decompressions under local anesthesia. Procurement concentrates on basic mechanical retractors with minimal capital requirements and simplified sterilization protocols.
Hospitals anchor capital equipment procurement volume. Surgical centers are gaining share fastest as minimally invasive techniques mature and reimbursement shifts favor outpatient migration.
Application:
Procedure complexity and reimbursement levels create margin tier differentiation, with deformity and tumor procedures supporting premium platform economics that simple decompressions cannot sustain.
- Spinal Fusion:Interbody and posterolateral fusion procedures require sustained access corridor maintenance through multi-hour interventions. United States hospital systems concentrate procurement of integrated access-robotic platforms for these high-reimbursement procedures, particularly in consolidated markets where enterprise agreements bundle cages, biologics, and navigation systems.
- Decompression Surgery:Laminectomy and laminotomy procedures for stenosis represent high-volume, lower-complexity interventions. Ambulatory surgical centers in Texas, Florida, and Arizona drive demand for single-use retractor configurations that support rapid OR turnover and same-day discharge protocols.
- Discectomy:Herniated nucleus pulposus removal through tubular or endoscopic approaches requires precise neural structure preservation. These procedures favor cannula-based access systems with integrated nerve monitoring compatibility, particularly in Japanese and German markets with established minimally invasive training pathways.
- Tumor Resection:Oncologic spine surgery demands extended access corridors with integrated navigation for margin definition and neural preservation. Academic medical centers in Boston, Baltimore, and Houston concentrate specialized retractor systems with intraoperative imaging compatibility for these complex interventions.
Spinal fusion commands the largest revenue pool across technology platforms. Decompression surgery is expanding most quickly as ambulatory migration and disposable adoption reshape procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes in India and accelerated FDA 510(k) review pathways in the United States are redirecting capital flows toward localized manufacturing and faster market entry. Regulatory divergence between the EU MDR and US FDA frameworks fragments launch sequencing, forcing manufacturers to prioritize one geography over another.
United States
Hospital procurement committees in Texas, Florida, and Ohio consolidate vendor relationships under enterprise agreements that bundle access systems with interbody cages and biologics. FDA 510(k) premarket notification requirements shape competitive timelines, with robotic-assisted platforms facing intensified software validation scrutiny. The Southeast and Midwest regions concentrate elective spine procedure volume at Catholic health initiatives and for-profit chains.
Germany
Academic medical centers in Berlin and Munich drive demand for integrated navigation-robotic platforms in complex deformity corrections. The EU Medical Device Regulation's enhanced clinical evidence requirements for Class IIb spinal devices accelerate consolidation among notified bodies, concentrating certification expertise at BSI and TÜV SÜD. Baden-Württemberg hosts specialized spine centers that favor cannula-based access systems with nerve monitoring compatibility.
Japan
Reusable rigid endoscopic platforms dominate procurement patterns in Tokyo and Osaka where high-cycle sterilization environments create total cost of ownership advantages. METI industrial policy supports domestic manufacturers of optical systems and precision-machined retractor components. The Kansai region maintains established minimally invasive training pathways that sustain demand for tubular access conduits.
India
The PLI scheme for medical devices attracts contract manufacturing investments for high-value orthopedic implants, localizing access system assembly for South Asian and Middle Eastern markets. CDSCO regulatory pathways for imported spinal devices create compliance bottlenecks that favor joint ventures with domestic distributors. Maharashtra and Gujarat concentrate sterile processing infrastructure for reprocessed retractor blade configurations.
South Korea
MFDS fast-track approval programs for innovative surgical devices compress time-to-market for navigation-enabled access platforms. Seoul Capital Area hospitals integrate robotic-assisted systems with intraoperative imaging to reduce fluoroscopy exposure in pediatric scoliosis corrections. Busan-Ulsan industrial clusters supply titanium alloy components to global spinal device manufacturers facing aerospace procurement competition.
Spinal Access Systems Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory navigation capabilities. The vendor base stratifies into three tiers: diversified medtech conglomerates with full spine portfolios, mid-cap pure-plays focused on access and navigation, and regional contract manufacturers serving private-label demand. Strategic archetypes include integrated platform providers, modular component specialists, and disposable-compatible system developers. M&A activity concentrates on navigation-robotics convergence targets, while capacity expansion favors India and Mexico for cost-sensitive retractor blade production.
Within the diversified medtech tier, Medtronic and Stryker exemplify vertically integrated manufacturers with multi-continental production footprints that sustain supply continuity for retractor and dilator portfolios. Globus Medical occupies a position among specialized spine pure-plays targeting lateral approach technologies. These three companies represent distinct strategic postures: captive manufacturing scale, dedicated robotics divisions, and expandable cage specialization respectively.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Johnson & Johnson |
| Globus Medical |
| NuVasive |
| B. Braun |
| SeaSpine |
| Alphatec Spine |
| Spineology |
| Others |
Value Network & Pricing Analysis
Capacity utilization at ISO 13485-certified contract manufacturers in Ireland and Costa Rica shapes both supply concentration and price floors for spinal access systems, as sterile processing infrastructure investments create minimum viable scale thresholds that smaller competitors cannot cross.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 510(k)-cleared and MDR Class IIb-certified systems commanding substantial premiums over basic mechanical retractors. Three-tier pricing structure across premium navigation-robotic, standard integrated, and economy mechanical levels reflects this divergence. Cost compression in the economy tier is intensifying as Indian contract manufacturers scale polymer dilator production for ambulatory surgical centers. Hospital procurement committees demonstrate lowest price sensitivity for integrated access-robotic platforms, while freestanding surgical centers in the Southeast and Midwest exhibit highest sensitivity to per-procedure consumable costs.
Supply Chain Analysis
Japan and Germany anchor precision-machined titanium retractor component production, while India and Mexico concentrate polymer dilator and disposable blade assembly. Supply draws from Ti-6Al-4V ELI alloy feedstock, optical fiber bundles for endoscopic systems, and high-performance polymers for single-use configurations. Single-source vulnerability concentrates in Japanese optical channel suppliers serving reusable endoscope manufacturers. Distribution runs through specialized surgical device distributors in developed markets and direct-to-hospital contracts at consolidated United States health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spinal access systems sit in early-cycle expansion as ambulatory surgical center migration and disposable adoption create new procurement channels beyond traditional hospital capital budgets.
For Market Incumbents: Compound defensive positioning through backward integration into titanium alloy supply and captive sterile processing capacity in Costa Rica or Ireland. Navigation-robotics convergence threatens standalone mechanical retractor margins, demanding accelerated software validation investment and dedicated field engineering coverage at consolidated United States health systems.
For New Entrants and Emerging Players: FDA breakthrough device designation and South Korean MFDS fast-track programs offer compressed regulatory pathways for navigation-enabled platforms. India's PLI scheme for medical devices presents the most penetrable geography for contract manufacturing entry. Direct-to-hospital distribution models bypass entrenched distributor relationships at ambulatory surgical centers seeking rapid OR turnover solutions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among disposable-compatible platform developers serving high-volume United States ambulatory chains. Long-term viability centers on software-enabled access systems with field-update capabilities rather than locked-version mechanical platforms. Watch CMS reimbursement coding shifts for minimally invasive spine procedures as the critical inflection signal for capital equipment refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated review pathways at CDRH compress competitive timelines for robotic-assisted platforms. |
| CE Marking Pathway | MDR Class IIb clinical evidence requirements concentrate certification expertise at BSI and TÜV SÜD. |
| Hospital System Partnership | Enterprise agreements at Catholic health initiatives and for-profit chains bundle access systems with biologics. |
| Software Companion Development | FDA software-as-medical-device guidance captures navigation algorithms previously in regulatory gray zones. |
| Reimbursement Strategy | CMS procedural coding for minimally invasive spine interventions determines capital allocation for platform upgrades. |
Research Methodology
The analysis maps retractor and dilator portfolios, robotic-assisted platforms, and endoscopic systems, each validated through hospital purchasing committees, biomedical engineers, GPO contracts managers, and spine surgeons. Primary interviews with these stakeholders combined secondary validation from FDA 510(k) filings, EU MDR notified body certificates, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up installed base modeling and top-down expenditure triangulation cross-check volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include product type, technology tier, end-user facility type, application complexity, and regional regulatory cluster. CAGRs derived from procedure volume elasticity to reimbursement shifts, capital equipment replacement cycles, and ambulatory migration penetration curves. Industry-specific inputs incorporate ISO 13485 certification cycle compression and aerospace titanium alloy procurement competition.
Decision-makers should treat outputs as directional under stable FDA review timelines and CMS reimbursement frameworks; material deviation would warrant model refresh. Specific risk factors include EU AI Act reclassification of navigation algorithms, titanium alloy supply disruption from defense procurement cycles, and OR integration delays for robotic systems. Recalibration cycles align with material shifts in regulatory guidance, reimbursement coding, and raw material availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Non-Invasive Ventilators Market
Medical Devices
Vaginal Inserts Market
Medical Devices
Heel Pressure Injury Relieving Devices Market
Medical Devices
Cryoballoon Ablation System Market
Medical Devices
Contact Thermometer Market
Medical Devices
India Contraceptive Devices Market
Medical Devices
Robotic Catheterization Systems Market
Medical Devices
Veterinary Ultrasound Devices Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
Medical Puncture Navigation Robot Market
Medical Devices
Stool Management Systems Market
Medical Devices
Global Artificial Kidney Market
Medical Devices
Internal Trauma Fixation Device Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
Urolithiasis Management Devices Market