
 Interstitial Lung Disease Treatment Market | 2026-2036
Interstitial Lung Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Interstitial Lung Disease Treatment Market Outlook
Hospital formulary decision-making is decoupling from pure cost-containment logic toward outcomes-based contracting for high-cost antifibrotics. Boehringer Ingelheim leverages its nintedanib franchise to sustain pulmonologist loyalty through dedicated specialist education programs. F. Hoffmann-La Roche Ltd anchors its position in idiopathic pulmonary fibrosis through biomarker-linked patient stratification tools. Merck & Co., Inc. competes in the immunosuppressant segment with established corticosteroid combinations that dominate earlier-stage interstitial lung disease protocols.
Interstitial lung disease treatment encompasses pharmacological interventions targeting progressive fibrotic remodeling of alveolar architecture, with antifibrotic agents such as nintedanib and pirfenidone functioning as tyrosine kinase inhibitors that attenuate TGF-beta signaling and platelet-derived growth factor pathways. These therapies primarily serve to slow forced vital capacity decline in fibrotic lung conditions and reduce acute exacerbation frequency in progressive phenotypes. Antifibrotic agents command the deepest margin pools due to orphan-drug pricing structures and limited therapeutic alternatives, while biologic drugs represent the fastest-expanding segment as IL-6 and IL-13 pathway inhibitors advance through Phase III programs. Oral delivery dominates volume share through patient convenience and home administration feasibility, though intravenous biologics concentrate in specialty centers with infusion infrastructure and protocol compliance monitoring.
The FDA accelerates review timelines through breakthrough therapy designation for novel antifibrotic mechanisms, while the EMA's orphan drug framework shapes European pricing and market exclusivity terms. Japan's PMDA maintains distinct efficacy thresholds for forced vital capacity endpoints that influence regional trial design and label differentiation. Stakeholders must monitor evolving biomarker qualification standards and payer evidence requirements that will determine which pipeline candidates secure favorable access positions.
Market Dynamics
Hospital formulary committees across the United States, Germany, and Japan are decoupling antifibrotic procurement from traditional cost-containment frameworks toward outcomes-based contracting models that tie reimbursement to forced vital capacity preservation metrics.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's accelerated approval pathway compresses commercial timelines for novel antifibrotic mechanisms, enabling earlier patient access and faster revenue recognition for qualifying therapies.
- Specialist Referral Network Density:Concentrated pulmonologist clusters in tertiary medical centers across the United States and Germany facilitate rapid diagnosis-to-treatment intervals for progressive fibrotic phenotypes.
- Orphan Drug Pricing Structures:Limited therapeutic alternatives for idiopathic pulmonary fibrosis sustain premium pricing power and deep margin pools for approved antifibrotic agents.
Market Restraints
- Biomarker Qualification Uncertainty:Evolving FDA and EMA standards for surrogate endpoint acceptance create regulatory friction that delays label expansion for pipeline candidates targeting non-IPF interstitial lung disease subtypes.
- Reimbursement Density Concentration:Premium therapy access remains constrained to markets with established specialty pharmacy infrastructure, excluding broad patient populations in lower-income geographies.
- Acute Exacerbation Prediction Limitations:Current diagnostic algorithms lack precision in identifying patients at highest risk of rapid decline, reducing the addressable population for early intervention protocols.
Strategic Opportunities
- IL-6 and IL-13 Pathway Inhibitors:Phase III biologic programs targeting alternative fibrotic signaling mechanisms offer white-space expansion beyond tyrosine kinase inhibition in progressive interstitial lung disease.
- Japan's Distinct Efficacy Thresholds:PMDA-specific forced vital capacity endpoints create opportunities for regional label differentiation and tailored commercial positioning.
- Home Administration Infrastructure:Oral antifibrotic delivery formats align with expanding remote patient monitoring capabilities, reducing dependency on specialty infusion centers.
Industry Challenges
- Patient Stratification Complexity:Heterogeneous disease progression patterns across interstitial lung disease subtypes complicate clinical trial enrollment and endpoint selection, extending development timelines.
- Legacy Corticosteroid Protocol Entrenchment:Established immunosuppressant combinations in earlier-stage disease management create switching friction that delays antifibrotic adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interstitial Lung Disease Treatment Market |
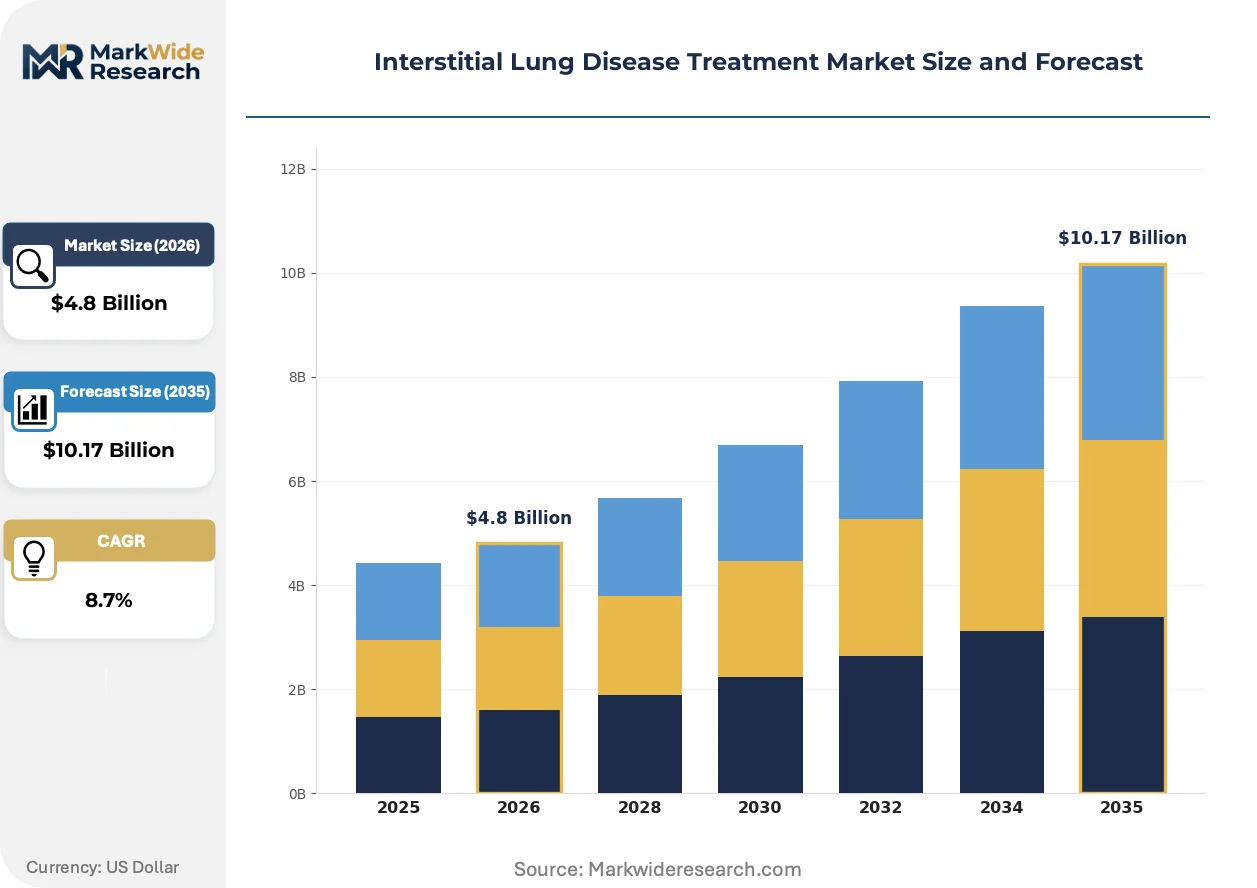
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
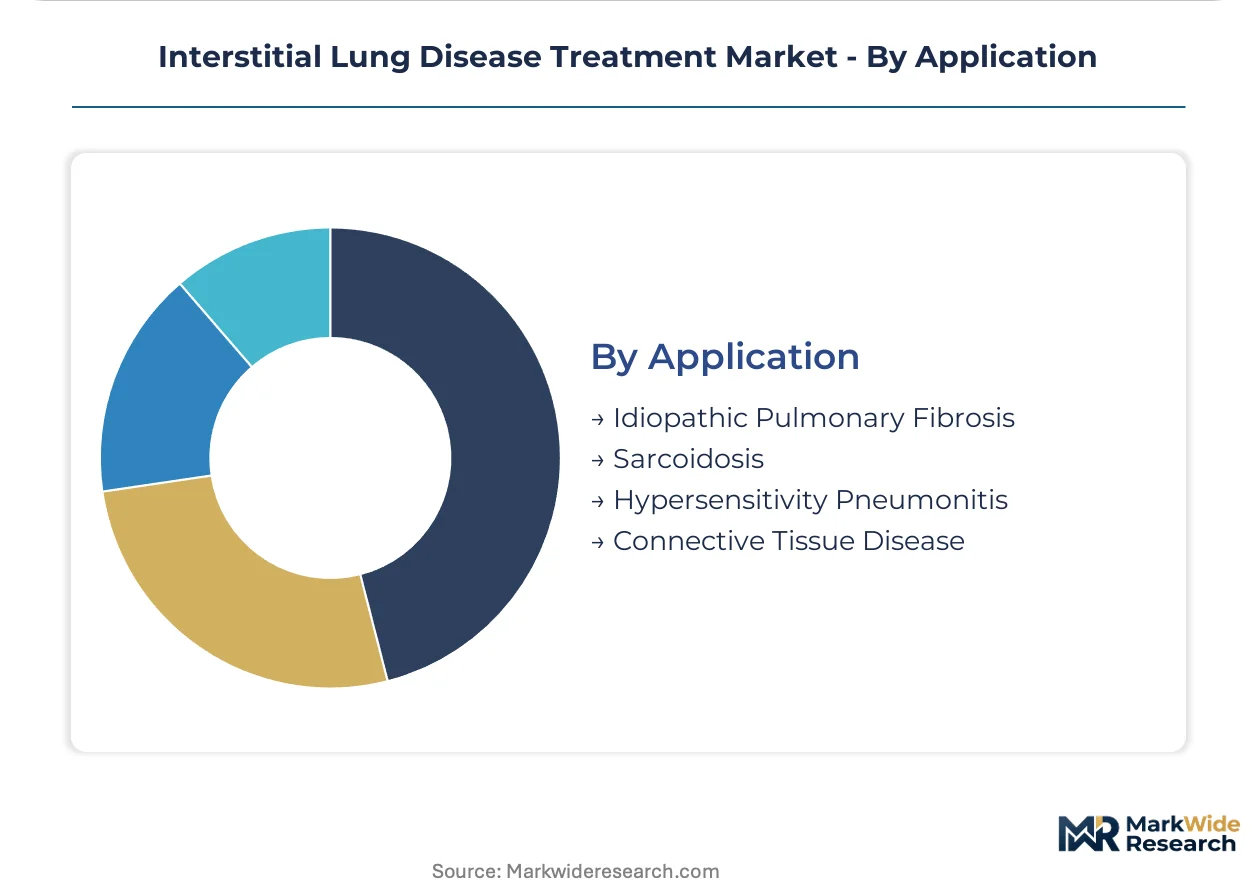
| Segmentation | Product Type: Corticosteroids, Antifibrotic Agents, Immunosuppressants, Biologic Drugs Delivery Mode: Oral, Injectable, Inhalation, Intravenous End User: Hospitals, Clinics, Homecare, Specialty Centers Application: Idiopathic Pulmonary Fibrosis, Sarcoidosis, Hypersensitivity Pneumonitis, Connective Tissue Disease |
| Companies Covered | Boehringer Ingelheim, F. Hoffmann-La Roche Ltd, Merck & Co., Inc., Bristol-Myers Squibb Company, Cipla Ltd, Glenmark Pharmaceuticals Ltd., Gilead Sciences Inc, FibroGen Inc, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interstitial Lung Disease Treatment Market Strategic Shifts
Biomarker-linked patient stratification tools are compressing diagnostic timelines and enabling precision therapy matching in progressive fibrotic lung disease, reshaping how specialists identify candidates for antifibrotic intervention.
Digital pathology platforms integrating artificial intelligence-assisted pattern recognition is modularizing the diagnostic workflow for usual interstitial pneumonia, enabling community pulmonologists to identify honeycombing and traction bronchiectasis with specialist-level accuracy. Regional hospital networks in Germany and Japan are deploying these tools to reduce referral bottlenecks. This capability compression is decentralizing diagnosis from academic medical centers toward secondary care settings.
EMA's orphan drug framework revision is tightening post-market evidence requirements for antifibrotic therapies, mandating prospective registries that capture real-world forced vital capacity trajectories. Manufacturers must now budget for extended pharmacovigilance infrastructure that extends beyond traditional clinical trial periods. The United Kingdom and Netherlands are piloting linked electronic health record systems that automate this data capture.
Specialty pharmacy channels are displacing traditional hospital outpatient dispensing for oral antifibrotics, unbundling medication distribution from institutional reimbursement bundles. United States payers are steering patients toward limited distribution networks that provide adherence monitoring and side-effect management. This channel consolidation concentrates volume with pharmacy benefit managers possessing dedicated rare-disease infrastructure.
Interstitial Lung Disease Treatment Market Segmentation
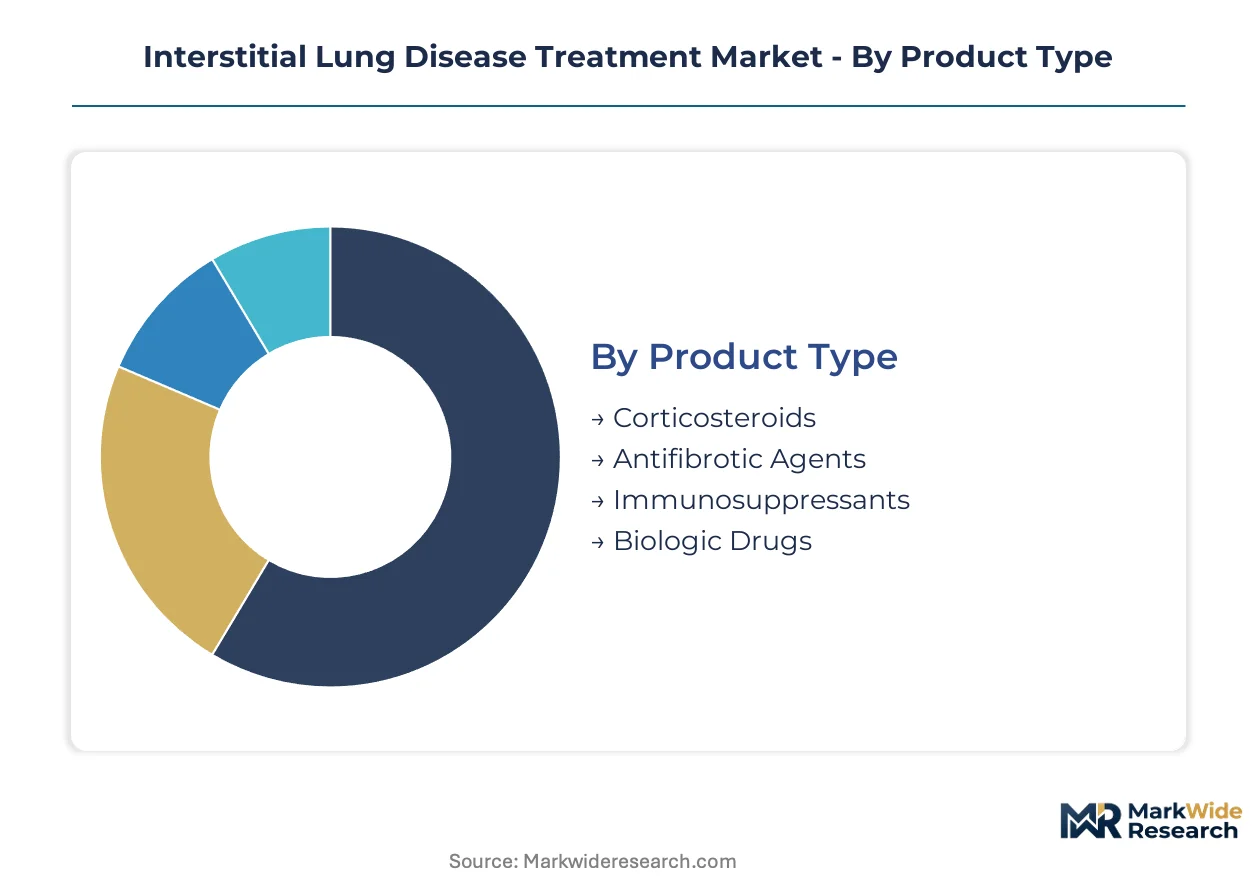
Interstitial lung disease treatment segmentation reflects divergent clinical priorities across disease progression stages and care settings. Product type differentiation separates acute symptom management from disease-modifying interventions, while delivery mode selection hinges on patient mobility and monitoring infrastructure availability.
Product Type:
Cost tier separates acute-care protocols from chronic disease management investment levels.
- Antifibrotic Agents:Tyrosine kinase inhibitors including nintedanib and pirfenidone attenuate TGF-beta and PDGF signaling to slow forced vital capacity decline. United States and Germany concentrate procurement through specialty pharmacy networks that bundle adherence monitoring with drug distribution.
- Biologic Drugs:IL-6 and IL-13 pathway inhibitors target alternative fibrotic mechanisms through monoclonal antibody platforms. Japan's PMDA maintains distinct efficacy thresholds that shape regional trial design and commercial positioning for pipeline candidates.
- Corticosteroids:Established immunosuppressant combinations dominate earlier-stage protocols with lower per-patient cost profiles.
- Immunosuppressants:Azathioprine and mycophenolate mofetil serve connective tissue disease-associated interstitial lung disease with established reimbursement pathways.
Volume sits with corticosteroids; growth tilts toward biologic drugs.
Delivery Mode:
Patient mobility constraints and site-of-care economics drive route selection.
- Oral:Nintedanib capsules and pirfenidone tablets enable home administration with remote monitoring, reducing dependency on infusion infrastructure. United States payers steer patients toward limited distribution networks that capture adherence data.
- Intravenous:Biologic infusions concentrate in tertiary centers with protocol compliance monitoring and acute adverse event response capability. Germany's hospital networks deploy these in pulmonology departments with high referral density.
- Injectable:Subcutaneous biologic formulations expand community-based administration options.
- Inhalation:Aerosolized corticosteroid delivery targets localized airway inflammation with limited systemic exposure.
Oral formats capture volume share; intravenous biologics command the steepest expansion trajectory.
End User:
Reimbursement density and diagnostic capability concentration determine site-of-treatment allocation.
- Specialty Centers:Dedicated interstitial lung disease clinics in the United States, Germany, and Japan compress diagnostic-to-treatment intervals through multidisciplinary teams. These sites anchor antifibrotic initiation with biomarker-linked stratification tools.
- Hospitals:Tertiary medical centers manage acute exacerbations and comorbidity complexity through integrated pulmonology-rheumatology services.
- Homecare:Remote patient monitoring infrastructure supports oral antifibrotic continuation outside institutional settings.
- Clinics:Community pulmonology practices handle stable patient follow-up with digital pathology support for pattern recognition.
Specialty centers concentrate premium therapy initiation; homecare is gaining share fastest as remote monitoring capabilities mature.
Application:
Disease subtype heterogeneity shapes endpoint selection and regulatory pathway strategy.
- Idiopathic Pulmonary Fibrosis:Progressive fibrotic phenotype with established forced vital capacity decline endpoints and orphan drug pricing structures. FDA breakthrough therapy designation compresses timelines for novel mechanisms targeting this indication.
- Connective Tissue Disease:Systemic sclerosis and rheumatoid arthritis-associated interstitial lung disease drive immunosuppressant demand with distinct progression patterns from IPF.
- Sarcoidosis:Granulomatous inflammation with corticosteroid-responsive acute phases and chronic fibrotic complications.
- Hypersensitivity Pneumonitis:Environmental trigger identification shapes management alongside pharmacological intervention.
Idiopathic pulmonary fibrosis anchors revenue concentration; connective tissue disease applications are expanding most quickly as biomarker qualification advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for interstitial lung disease treatment concentrates in the United States, Germany, and Japan where specialist referral networks and reimbursement density support premium antifibrotic access. These markets anchor procurement volume for nintedanib and pirfenidone through distinct regulatory and infrastructure configurations.
United States
Pulmonologist clusters in tertiary medical centers compress diagnostic-to-treatment intervals for progressive fibrotic phenotypes. The FDA's breakthrough therapy designation pathway accelerates review timelines for novel antifibrotic mechanisms, enabling earlier commercial access. Specialty pharmacy networks in Boston, New York, and San Francisco bundle adherence monitoring with drug distribution, displacing traditional hospital outpatient dispensing.
Germany
Hospital formulary committees decouple antifibrotic procurement from pure cost-containment logic toward outcomes-based contracting tied to forced vital capacity preservation. EMA's orphan drug framework shapes market exclusivity terms and post-market evidence requirements through prospective registry mandates. The Ruhr-Rhine corridor and Bavarian hospital networks deploy digital pathology platforms with AI-assisted pattern recognition to reduce referral bottlenecks.
Japan
PMDA maintains distinct efficacy thresholds for forced vital capacity endpoints that influence regional trial design and label differentiation for pipeline candidates. METI-supported initiatives expand home administration infrastructure for oral antifibrotics aligned with remote patient monitoring capabilities. Tokyo and Osaka specialist centers anchor biologic infusion capacity with protocol compliance monitoring systems.
United Kingdom
NHS England's specialized commissioning frameworks concentrate antifibrotic initiation in designated interstitial lung disease clinics with multidisciplinary team structures. The UK pilots linked electronic health record systems that automate real-world forced vital capacity trajectory capture for EMA pharmacovigilance compliance. Manchester and London hospital networks lead decentralized diagnosis deployment toward secondary care settings.
Switzerland
Swissmedic's alignment with EMA orphan drug standards enables rapid market access for approved antifibrotic therapies with premium pricing structures. Basel and Zurich hospital procurement leverages outcomes-based contracting models that tie reimbursement to disease progression metrics. The country's dense specialist infrastructure supports biomarker-linked patient stratification tool adoption for precision therapy matching.
Interstitial Lung Disease Treatment Market Competitive Environment
German and Swiss producers anchor the established antifibrotic tier; United States-based biologic specialists hold the pipeline expansion vector. The market exhibits consolidated leadership in tyrosine kinase inhibition alongside fragmented competition in immunosuppressant combinations and emerging biologic platforms. Strategic archetypes span research-intensive pharmaceutical conglomerates, mid-cap fibrosis-focused developers, and generic immunosuppressant manufacturers. Dominant competitive moves include biomarker-linked patient stratification tool deployment and specialty pharmacy channel consolidation for adherence capture.
Within the research-intensive tier, Boehringer Ingelheim and F. Hoffmann-La Roche Ltd exemplify divergent positioning archetypes. Boehringer Ingelheim, a German family-owned pharmaceutical group, sustains pulmonologist loyalty through dedicated specialist education programs anchored to its nintedanib franchise. F. Hoffmann-La Roche Ltd, a Swiss healthcare conglomerate, occupies a precision-medicine position through biomarker-linked stratification tools in idiopathic pulmonary fibrosis. Merck & Co., Inc., a United States-based pharmaceutical corporation, represents the established immunosuppressant archetype with corticosteroid combinations dominating earlier-stage disease protocols.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Cipla Ltd |
| Glenmark Pharmaceuticals Ltd. |
| Gilead Sciences Inc |
| FibroGen Inc |
| Novartis |
| Others |
Value Chain & Pricing Dynamics
Captive production of nintedanib and pirfenidone active pharmaceutical ingredients anchors supply security for Boehringer Ingelheim and F. Hoffmann-La Roche Ltd, translating directly into sustained orphan-drug pricing power across United States, German, and Japanese markets. This vertical control over tyrosine kinase inhibitor synthesis insulates premium tiers from raw material volatility while enabling value-based contracting negotiations with hospital formulary committees.
Pricing Analysis
Volume concentrates in corticosteroid combinations with thin margins, while antifibrotic agents capture deep margin pools through orphan-drug exclusivity and limited therapeutic alternatives. Three-tier pricing structure across premium antifibrotics, mid-tier immunosuppressants, and economy corticosteroids reflects disease progression stage and reimbursement density. Pricing pressure stems from EMA's tightening post-market evidence requirements and prospective registry mandates that extend pharmacovigilance costs. Community pulmonology practices exhibit highest price sensitivity due to limited specialty pharmacy infrastructure, while tertiary medical centers with outcomes-based contracting demonstrate lowest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements for biologic drug substances compel manufacturers to qualify secondary suppliers in Switzerland and Ireland alongside primary production in Germany and the United States. Active pharmaceutical ingredient production draws from specialized chemical synthesis facilities in India and China, with fill-finish operations concentrated in German and Swiss sterile manufacturing sites. Single-source vulnerability persists for IL-6 and IL-13 pathway inhibitor cell lines, creating concentration risk for pipeline biologics. Distribution runs through limited specialty pharmacy networks in the United States and hospital outpatient channels in Germany and Japan, with direct-to-patient home delivery expanding for oral antifibrotic formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EMA orphan drug framework revisions force smaller developers to absorb extended pharmacovigilance infrastructure costs that strain limited balance sheets.
For Market Incumbents: Extend biomarker-linked patient stratification tool deployment to community pulmonology settings, compressing diagnostic timelines before pipeline biologics reach market. Build captive production capacity for IL-6 pathway inhibitor candidates in Switzerland to preempt supply constraints. Counter emerging biologic specialists by locking exclusive specialty pharmacy network partnerships that capture adherence data and switching friction.
For New Entrants and Emerging Players: Begin with connective tissue disease-associated interstitial lung disease applications where biomarker qualification uncertainty has delayed incumbent label expansion, creating white-space opportunity. Target Japan's distinct PMDA efficacy thresholds for regional trial design that enables label differentiation from global protocols. Pursue licensing agreements with established German hospital networks for infusion infrastructure access rather than building de novo specialty center relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap fibrosis-focused developers with Phase III biologic assets and established pulmonologist key opinion leader relationships. Five-to-ten year viability hinges on successful biomarker qualification for non-IPF indications, expanding addressable population beyond idiopathic pulmonary fibrosis concentration. Monitor FDA breakthrough therapy designation announcements as inflection indicator for accelerated commercial timeline compression and acquisition premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Qualification Advancement | FDA and EMA surrogate endpoint acceptance unlocks label expansion for pipeline candidates targeting non-IPF subtypes. |
| Specialty Pharmacy Network Consolidation | Limited distribution partnerships with United States pharmacy benefit managers capture adherence monitoring data and patient switching costs. |
| Outcomes-Based Contracting Implementation | German hospital formulary committees tie reimbursement to forced vital capacity preservation metrics, reshaping procurement logic. |
| Regional Trial Design Tailoring | PMDA-specific efficacy thresholds in Japan enable label differentiation and commercial positioning for pipeline biologics. |
| Digital Pathology Platform Deployment | AI-assisted pattern recognition tools in German and Japanese hospital networks reduce referral bottlenecks and decentralize diagnosis. |
Study Parameters
Independent corroboration across formulary director interviews, regulatory affairs lead consultations, and payer access specialist discussions underwrites the qualitative findings on hospital procurement decoupling trends. Primary fieldwork with pulmonologists in United States tertiary medical centers, German hospital networks, and Japanese specialist centers combined with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary database audits. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored volume and value estimates.
Rate-of-change decomposition across the projection horizon separates volume expansion from price trajectory and mix shift contributions. Segmentation dimensions modeled include product type tier, delivery mode route, end-user site concentration, and disease subtype application, with regional regulatory cluster effects incorporated throughout. CAGRs derived from epidemiology-adjusted patient population forecasts, therapy penetration assumptions, and pricing evolution scenarios. Forecast inputs incorporated forced vital capacity endpoint qualification timelines and specialty pharmacy channel migration rates.
Biomarker qualification uncertainty, reimbursement density concentration shifts, and acute exacerbation prediction algorithm advances are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions on regulatory pathway timelines and payer evidence requirements. A model refresh is warranted upon material change in FDA breakthrough therapy designation patterns or EMA orphan drug framework enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Necrobiosis Lipoidica Diabeticorum Market
Specialty Medicine
Bartter Syndrome Treatment Market
Specialty Medicine
Tularemia Therapeutics Market
Specialty Medicine
Congenital Adrenal Hyperplasia Treatment Market
Specialty Medicine
Global Glaucoma Therapeutics Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Histamine Toxicity Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Polyarticular Juvenile Idiopathic Market
Specialty Medicine
Endometriosis Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Allergic Conjunctivitis Market
Specialty Medicine
Selectin Blocker Market
Specialty Medicine
Nonalcoholic Steatohepatitis Market
Specialty Medicine
Global Neurotrophic Keratitis Treatment Market