
 North America Pen Needles Market | 2026-2036
North America Pen Needles Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pen Needles Market Insights
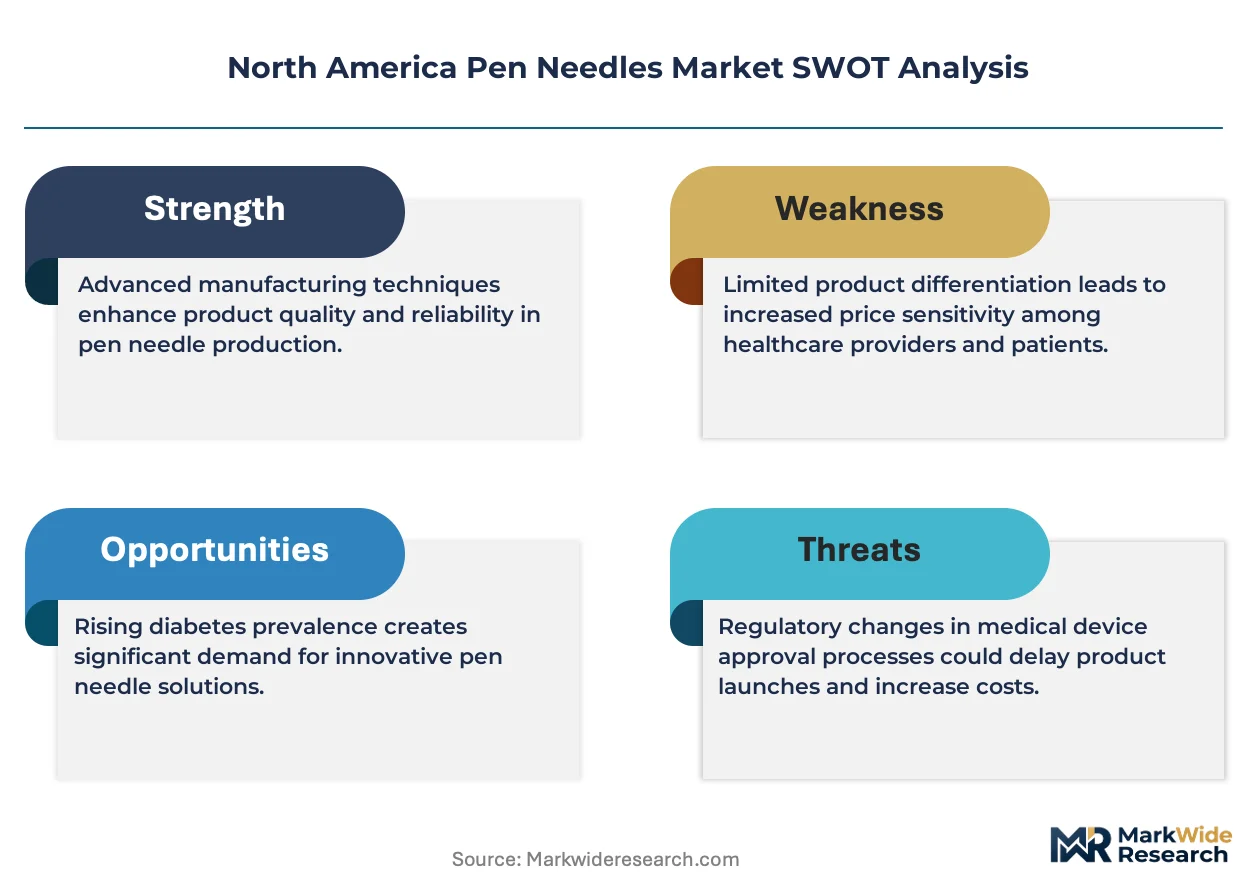
North American pen needle manufacturing capacity is hardening around integrated producers with captive polymer and steel tubing operations. BD sustains broad vertical control from raw material through finished sterile packaging across multiple U.S. production sites. Embecta Corp. anchors its position through dedicated diabetes care infrastructure spun from legacy Becton Dickinson assets. Novo Nordisk A/S competes via paired device-drug ecosystems that lock in needle compatibility with its insulin delivery platforms.
Pen needles are hollow, ultra-fine stainless steel cannulas mounted on plastic hubs, typically ranging from 4mm to 12mm in length and 29G to 32G in diameter, designed for subcutaneous drug delivery via pen injector devices. Safety needles lead volume substitution as OSHA bloodborne pathogen compliance and state-level sharps injury mandates phase out standard formats in hospital procurement. Electromechanical and digital assistive needle technologies capture expanding margin pools as diabetes patients self-administer with dose-logging and injection-depth feedback functions. Smart needle adoption remains nascent but concentrates among integrated health systems pursuing remote glycemic monitoring.
FDA 510(k) clearance requirements and OSHA bloodborne pathogen standards govern product entry and workplace safety specifications across the United States, while Health Canada and PMRA oversee parallel device licensing and pharmacovigilance in the Canadian market. State-level sharps injury prevention regulations in California, New York, and Texas create fragmented but tightening procurement standards that favor safety-engineered designs. Stakeholders must monitor pending FDA guidance on connected drug delivery accessories and track provincial formulary reimbursement shifts that could rechannel patient out-of-pocket spending toward premium needle formats.
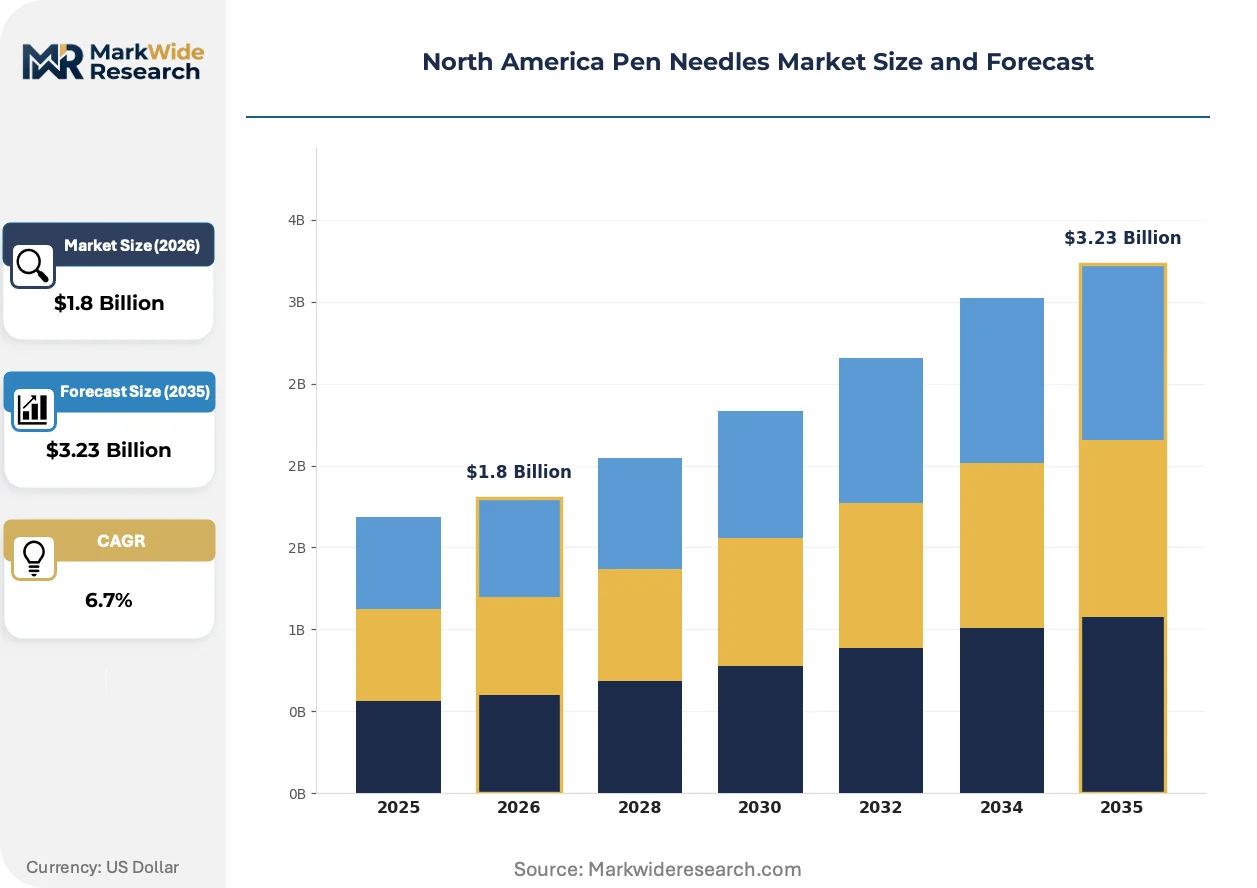
Market Dynamics
FDA 510(k) clearance pathways and OSHA bloodborne pathogen mandates are hardening procurement standards toward safety-engineered retractable formats, compressing standard needle volumes across hospital systems and home care channels.
Growth Catalysts
- OSHA Compliance Mandates:Federal workplace safety standards and state-level sharps injury prevention laws in California, New York, and Texas are phasing out conventional needles from institutional procurement.
- Geriatric Home Care Expansion:Diabetes self-management among aging populations across the United States and Canada is elevating pen injector utilization rates in residential settings.
- Safety-Engineered Device Substitution:Retractable and shielded needle formats are capturing volume from standard designs as integrated health systems consolidate supplier contracts.
Market Restraints
- Stainless Steel Input Volatility:Ultra-fine cannula manufacturing depends on specialized 304/316L steel tubing with limited qualified suppliers, exposing margins to raw material price swings.
- Great Lakes Supply Concentration:Polymer hub molding and final sterile packaging capacity clusters in the U.S. pharmaceutical manufacturing corridor, creating geographic vulnerability to regional disruptions.
- Health Canada Licensing Friction:PMRA device licensing timelines and provincial formulary reimbursement variability create market access delays distinct from FDA-cleared U.S. pathways.
Strategic Opportunities
- Connected Needle Accessories:Bluetooth-enabled dose-logging and injection-depth feedback functions are opening premium positioning among integrated health systems pursuing remote glycemic monitoring.
- Ontario Medical Device Cluster:Canada's concentrated manufacturing infrastructure offers tariff-advantaged production bases for U.S. market access under USMCA provisions.
- Digital Therapeutic Convergence:Pairing electromechanical needle technologies with smartphone-based adherence platforms is creating stickier patient-device relationships.
Industry Challenges
- Cleanroom Sterilization Certification:ISO 13485 and FDA QSR compliance for gamma-irradiated packaging requires capital-intensive facility validation cycles that extend product launch timelines.
- Polymer Hub Precision Molding:Tight-tolerance medical-grade plastic component production faces qualified technician shortages across Midwest manufacturing zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pen Needles Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Needles, Safety Needles, Retractable Needles, Multi-Use Needles End User: Diabetes Patients, Healthcare Professionals, Pharmacies, Clinics Technology: Mechanical Needles, Electromechanical Needles, Digital Assistive Needles, Smart Needles Distribution Channel: Online Retail, Hospitals, Hypermarkets, Specialty Stores |
| Companies Covered | BD (Becton, Dickinson and Company), Embecta Corp., Novo Nordisk A/S, Ypsomed AG, Terumo Corporation, B. Braun Melsungen AG, Owen Mumford Limited, UltiMed, Inc., Allison Medical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pen Needles Market Trends and Innovations
Electromechanical and sensor-embedded needle technologies are absorbing development investment as manufacturers differentiate beyond commodity cannula formats toward data-generating drug delivery ecosystems.
Smart needle platforms with integrated depth sensors and wireless connectivity are absorbing margin compression in standard safety needles by enabling subscription-based remote monitoring services. Large integrated delivery networks in Minnesota and Wisconsin are piloting these devices for high-risk diabetes cohorts. The technology is absorbing patient adherence data streams that pharmaceutical partners value for outcomes-based contracting.
State-level sharps injury prevention regulations are tightening faster than federal OSHA minimums, creating a patchwork of procurement specifications that favor multi-format safety portfolios. California's Cal/OSHA standards and New York's public employee protection laws now mandate engineered sharps injury protections in virtually all clinical settings. Hospital purchasing cooperatives are responding by consolidating supplier relationships with manufacturers offering full safety-needle line coverage.
Home-based diabetes management is shifting volume from clinic-administered injections toward patient-directed pen injector use, elevating demand for ultra-short 4mm and 5mm needles optimized for subcutaneous delivery. Retail pharmacy channels and mail-order distributors are displacing traditional hospital supply contracting for recurring needle purchases. This pattern concentrates in Medicare-covered populations across Florida, Arizona, and Texas retirement corridors.
North America Pen Needles Market Segmentation
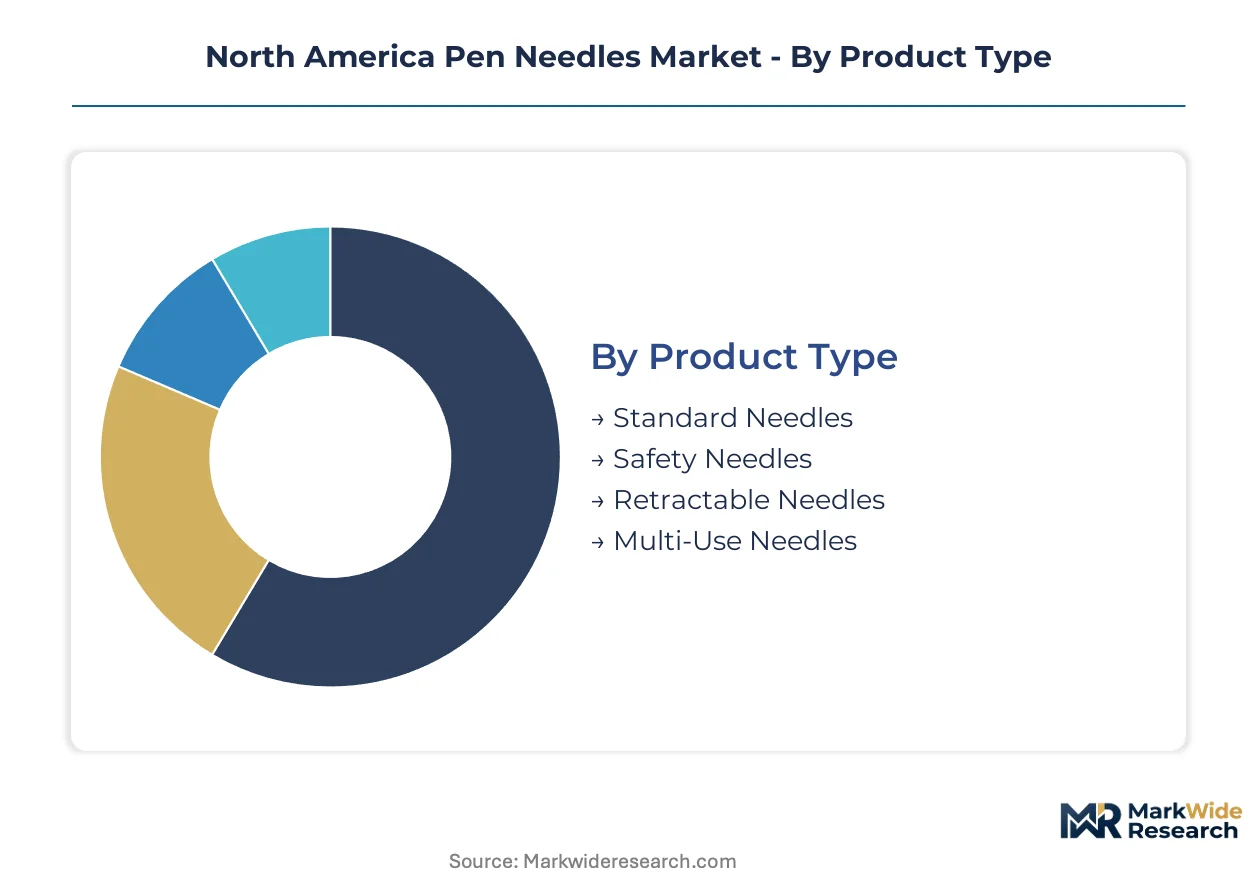
Pen needle procurement patterns diverge sharply between institutional buyers governed by OSHA compliance mandates and individual patients optimizing for out-of-pocket costs. Understanding these segment boundaries clarifies where safety-engineered premiums command pricing power versus where commodity cannulas retain volume.
Product Type:
Hospital procurement teams and home-care patients evaluate needle formats through fundamentally different risk-cost tradeoffs.
- Safety Needles:Shielded or retractable mechanisms activate automatically post-injection to prevent sharps injuries. Demand concentrates in California, New York, and Texas hospital systems where state-level mandates exceed federal OSHA minimums, compressing standard needle procurement.
- Retractable Needles:Integrated spring-loaded cannula retraction systems eliminate exposed sharp surfaces entirely. Medicare Advantage plans in Florida and Arizona retirement corridors are steering home-based diabetes patients toward these formats despite 15-25% price premiums over standard alternatives.
- Standard Needles:Fixed cannula designs without engineered injury protection dominate cash-pay retail pharmacy channels where uninsured patients prioritize unit cost over safety features.
- Multi-Use Needles:Reusable hub designs with replaceable cannula components serve niche veterinary and research applications with limited human therapeutic penetration.
Safety needles lead volumes today; retractable formats are gaining share fastest among integrated health network contracts.
End User:
Volume concentration and purchasing authority split between patient-directed retail acquisition and institutional procurement governed by formulary committees.
- Diabetes Patients:Medicare Part D and provincial formulary coverage in Ontario and British Columbia determine out-of-pocket exposure for insulin-dependent populations. Mail-order pharmacy penetration in Texas and Florida retirement corridors is elevating 90-day supply purchasing patterns.
- Healthcare Professionals:Physician office practices and home health agencies face dual OSHA and state sharps injury prevention compliance burdens that mandate safety-engineered device adoption regardless of reimbursement differentials.
- Pharmacies:CVS, Walgreens, and independent chains function as gatekeepers between manufacturer promotions and patient selection, with generic substitution protocols varying by payer contract.
- Clinics:Federally qualified health centers and dialysis facilities operate under 340B drug pricing programs that extend to ancillary device procurement, compressing realized prices for premium needle formats.
Diabetes patients drive absolute unit volumes; healthcare professional procurement is tightening specifications fastest through consolidated supplier contracts.
Technology:
Development investment is concentrating where data capture capabilities enable pharmaceutical adherence partnerships and remote monitoring reimbursement.
- Smart Needles:Bluetooth-enabled platforms with integrated depth sensors and dose-logging wireless transmitters. Mayo Clinic and Cleveland Clinic integrated delivery networks in Minnesota and Wisconsin are piloting these devices for high-risk diabetes cohorts under value-based care contracts.
- Digital Assistive Needles:Audible or haptic feedback mechanisms guide injection depth and angle for patients with visual impairment or limited dexterity. Demand clusters in Veterans Affairs facilities serving aging diabetic populations.
- Electromechanical Needles:Motorized insertion mechanisms reduce user variability in subcutaneous delivery. Premium positioning targets patients with needle phobia or inconsistent technique.
- Mechanical Needles:Passive cannula designs without electronic components retain cost advantages for price-sensitive segments and emerging market export.
Mechanical needles anchor volume today; smart needle platforms are climbing the fastest as integrated health systems pursue remote glycemic monitoring capabilities.
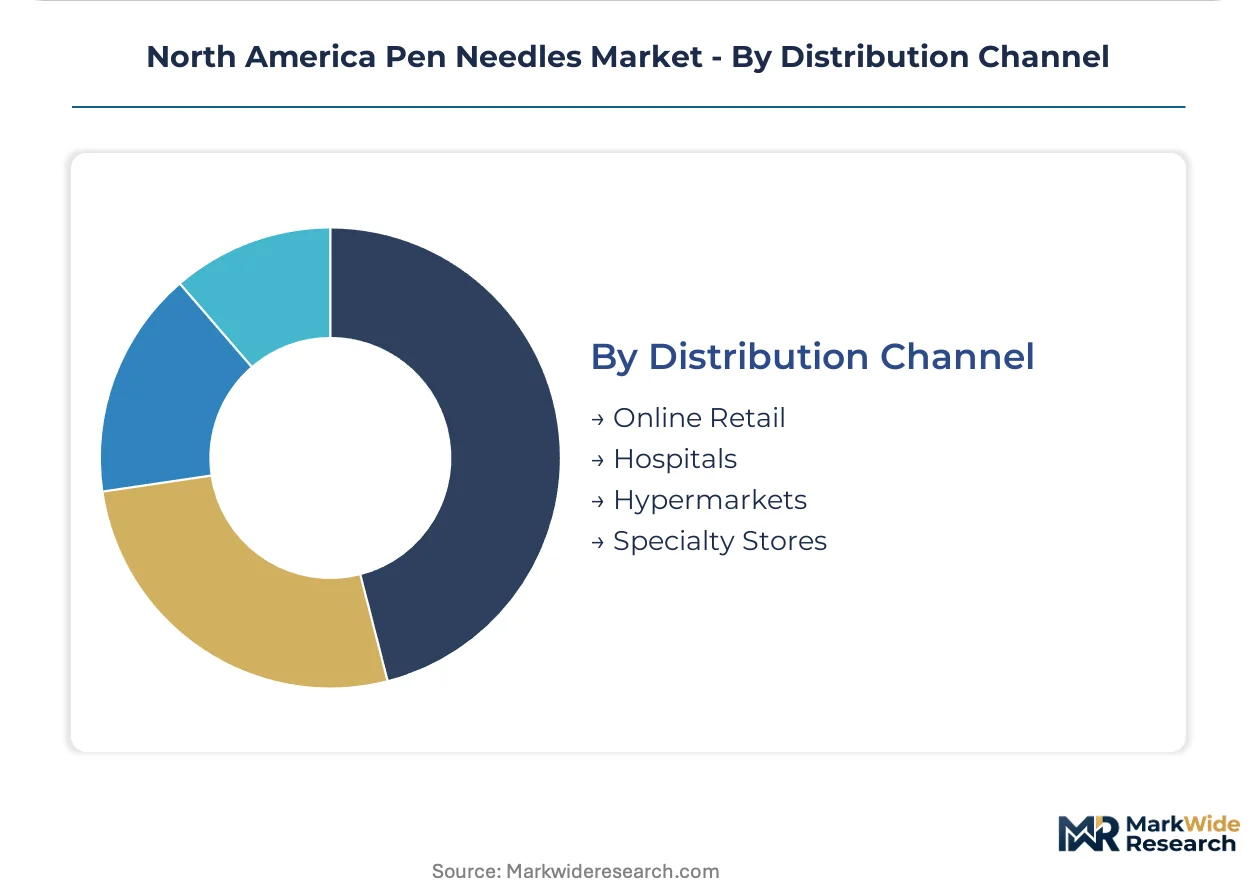
Distribution Channel:
Channel selection determines margin realization through pricing transparency, inventory carrying costs, and promotional spend requirements.
- Online Retail:Amazon, diabetic supply specialists, and manufacturer direct-to-patient platforms are absorbing volume from traditional pharmacy as subscription auto-ship models reduce patient adherence friction.
- Hospitals:Group purchasing organization contracts with Premier and Vizient consolidate procurement across multi-hospital systems, favoring suppliers with full safety-needle portfolio coverage.
- Hypermarkets:Walmart and Costco pharmacy counters leverage foot traffic for impulse accessory purchases, though needle selection remains narrower than specialty channels.
- Specialty Stores:Independent diabetic supply retailers and durable medical equipment dealers serve Medicare Part B billing pathways for insulin pump and continuous glucose monitor bundling.
Hospitals dominate institutional procurement today; online retail is expanding most quickly among Medicare-covered home administration populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production arbitrage between FDA-regulated U.S. manufacturing and Health Canada-licensed Ontario facilities is reshaping supply chain configuration across the continent. Manufacturers exploit the cost-of-compliance gap while maintaining USMCA tariff advantages for cross-border distribution.
United States
Medicare Advantage penetration in Florida and Arizona retirement corridors elevates retractable needle demand despite premium pricing. OSHA bloodborne pathogen mandates and Cal/OSHA standards in California accelerate safety-engineered substitution in hospital procurement. The Great Lakes pharmaceutical manufacturing corridor concentrates polymer hub molding and sterile packaging capacity across Illinois, Michigan, and Ohio production sites.
Canada
Provincial formulary reimbursement variability in Ontario and British Columbia creates patient out-of-pocket exposure that channels demand toward standard formats. Health Canada and PMRA device licensing timelines extend market access relative to FDA-cleared pathways. Ontario's medical device cluster in the Toronto-Waterloo corridor offers tariff-advantaged production bases for U.S. market access.
Mexico
Maquiladora operations in Baja California and Chihuahua absorb component manufacturing for U.S.-based final assembly, exploiting labor cost differentials in cannula finishing operations. COFEPRIS regulatory alignment with FDA standards facilitates streamlined cross-border product registration. Tijuana and Ciudad Juárez medical device parks concentrate sterile packaging and final labeling operations for North American distribution.
North America Pen Needles Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue connected-device and digital therapeutic adjacencies. The vendor base concentrates around integrated manufacturers with captive polymer and steel tubing operations, alongside specialized diabetes care spin-offs. Three archetypes dominate: vertically integrated conglomerates with raw-material-to-sterile-packaging control; device-drug ecosystem builders pairing proprietary needles with insulin delivery platforms; and regional specialists serving 340B and mail-order pharmacy channels. Competitive moves center on M&A consolidation of safety-engineered patent portfolios and strategic partnerships with integrated delivery networks for smart needle pilot programs.
Among the named participants, BD exemplifies the fully integrated archetype with broad vertical control across multiple U.S. production sites. Embecta Corp. occupies a position as a diabetes care pure-play spun from legacy Becton Dickinson infrastructure. Novo Nordisk A/S anchors the device-drug ecosystem tier through paired needle compatibility with its insulin delivery platforms.
| Leading Market Players |
|---|
| BD (Becton, Dickinson and Company) |
| Embecta Corp. |
| Novo Nordisk A/S |
| Ypsomed AG |
| Terumo Corporation |
| B. Braun Melsungen AG |
| Owen Mumford Limited |
| UltiMed, Inc. |
| Allison Medical, Inc. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between FDA-cleared safety-engineered formats and uncertified standard alternatives manifests in divergent margin structures and supplier qualification barriers across the United States and Canada. Premium retractable needles command hospital procurement premiums through OSHA compliance bundling while commodity cannulas face price erosion in cash-pay retail channels dependent on polymer hub and steel tubing input costs.
Pricing Analysis
Distributor margin stacking in group purchasing organization contracts compresses realized prices for safety-needle portfolios while direct-to-patient subscription models bypass intermediary markups. Three-tier pricing structure across premium smart-needle, standard safety-engineered, and economy mechanical levels differentiates by FDA 510(k) clearance status and Bluetooth connectivity features. Pricing pressure stems from Medicare Part D formulary restrictions in Florida and Arizona retirement corridors where out-of-pocket exposure steers patients toward lower-cost alternatives. Uninsured cash-pay patients at CVS and Walgreens pharmacy counters exhibit highest price sensitivity; integrated health networks under value-based care contracts show lowest sensitivity due to bundled reimbursement.
Supply Chain Analysis
Dual-sourcing requirements from Premier and Vizient group purchasing organizations mandate qualified backup suppliers for 304/316L stainless steel tubing and medical-grade polymer resins. Manufacturing concentrates in the United States Great Lakes corridor, Ontario's Toronto-Waterloo cluster, and Baja California maquiladora zones for final sterile packaging. Raw material dependencies rest on specialized steel tubing from qualified metallurgical suppliers, gamma-irradiation sterilization services, and precision injection molding equipment. Single-source vulnerability concentrates in ultra-fine cannula drawing operations with limited qualified technicians. Distribution runs through hospital GPO contracts, retail pharmacy chains, and Amazon direct-to-patient platforms with divergent inventory carrying cost structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pen needles hinges on smart-needle premium tier adoption offsetting commodity cannula price compression, with connected-device ecosystems capturing recurring revenue streams from integrated health networks.
For Market Incumbents: Deepen backward integration into captive polymer hub molding across Illinois and Michigan production sites to defend against Embecta and Ypsomed supply chain disruption threats. Secure exclusive supplier status with Mayo Clinic and Cleveland Clinic pilot programs for Bluetooth-enabled dose-logging platforms before competitive lock-in hardens. Prioritize ISO 13485 certification maintenance and cleanroom capacity expansion to extend lead times for emerging entrants facing facility validation delays. For New Entrants and Emerging Players: Cal/OSHA standards in California open a window for retractable needle specialists to capture share in hospital systems phasing out conventional formats under state mandates exceeding federal minimums. Target mail-order pharmacy channels in Texas and Florida retirement corridors where 90-day supply purchasing patterns reduce patient switching friction. Pursue white-label manufacturing partnerships with Ontario medical device cluster facilities to exploit USMCA tariff advantages for U.S. market access without FDA facility inspection timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where safety-engineered patent portfolios face expiration windows and smart-needle R&D requires capital scale beyond mid-tier players. Long-term viability favors device-drug ecosystem builders with paired insulin delivery platform compatibility or connected-health data partnerships with pharmaceutical adherence programs. Target acquisition archetype: regional specialists with 340B contract access and mail-order pharmacy relationships. Watch Health Canada PMRA guidance on connected drug delivery accessories as inflection signal for premium format reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Smart Needle Platform | Accelerates market access for Bluetooth-enabled dose-logging devices under OSHA-compliant procurement mandates. |
| Hospital System Partnership for Pilot Deployment | Locks in preferred supplier status with integrated delivery networks pursuing remote glycemic monitoring capabilities. |
| Backward Integration into Polymer Hub Molding | Reduces exposure to Midwest qualified technician shortages and tight-tolerance medical-grade component volatility. |
| Reimbursement Strategy for Medicare Advantage Plans | Steers Florida and Arizona retirement corridor patients toward retractable formats despite premium pricing. |
| Software Companion Development for Adherence Tracking | Creates sticky patient-device relationships through smartphone-based injection logging and pharmaceutical data partnerships. |
Research Methodology
Direct dialogue with hospital purchasing committee members, GPO contracts managers, biomedical engineers at integrated delivery networks, and diabetes care specialists at Veterans Affairs facilities grounded qualitative findings. Secondary validation drew from FDA 510(k) device filings, Health Canada PMRA licensing databases, CMS Medicare Part D formulary data, and OSHA bloodborne pathogen compliance records. Bottom-up demand modeling triangulated against top-down market sizing across safety-engineered and standard needle format segments.
Bottom-up volume projections aggregated patient population estimates, injection frequency assumptions, and pen injector device penetration rates across Medicare-covered demographics. Segmentation modeling captured product type divergence, end-user procurement authority splits, technology adoption curves, and channel margin structures. CAGRs derived from regression analysis of historical volume trends, adjusted for regulatory mandate phase-in schedules and smart-needle pilot program scaling assumptions. Forecast inputs incorporated stainless steel tubing price indices and provincial formulary reimbursement variability in Ontario and British Columbia.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Health Canada licensing timeline delays or rapid Medicare Advantage smart-needle coverage expansion. Projections reflect assumptions regarding OSHA state-level mandate adoption rates, polymer hub molding capacity expansion, and connected-device pharmaceutical partnership formation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Atrial Fibrillation Devices Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Global Reflex Hammer Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
Face Mask Device Market
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Artificial Eye Market
Medical Devices
Polyethersulfone Dialyzer Market
Medical Devices
Mechanical Chest Compression System Market
Medical Devices
South America C-Arms Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
North America General Surgical Devices Market
Medical Devices
Medical Bionic Implants and Exoskeletons Market
Medical Devices
Implantable Port Devices Market
Medical Devices
Electrophysiology Market