
 Europe Smart Medical Devices Market | 2026-2036
Europe Smart Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Medical Devices Market Insights
Project finance for hospital technology upgrades is tilting competitive advantage toward vendors with balance-sheet capacity for long-term service contracts. Siemens Healthineers leverages its imaging-to-digital platform integration to anchor large European hospital group purchasing decisions. Philips competes through vertical control over patient monitoring data architectures, while Fresenius Medical Care specializes in connected dialysis devices that dominate renal care settings.
Europe smart medical devices encompass sensor-embedded diagnostic and therapeutic instruments that transmit physiological data through Bluetooth, RFID, or NFC protocols to clinical decision systems, typically manufactured under ISO 13485 quality management with biocompatible housings and encrypted wireless stacks. Wearable monitors lead device type revenue pools due to cardiovascular and diabetes management applications, whereas remote patient monitoring represents the fastest-growing application segment as home care reimbursement frameworks expand. IoT-enabled platforms command premium positioning against basic Bluetooth telemetry, reflecting where margin pools concentrate across technology tiers.
EMA medical device guidance, EU MDR conformity requirements, and GDPR health data rules collectively shape product development timelines and cross-border data flows for connected device vendors. The EU AI Act introduces additional algorithmic transparency obligations for diagnostic software components, forcing R&D budget reallocation toward compliance infrastructure. Stakeholders must monitor how national health technology assessment bodies weigh digital therapeutic evidence against traditional clinical endpoints when updating reimbursement catalogs.
Market Dynamics
EU MDR clinical evidence requirements and GDPR health data rules are compressing product development timelines while tilting procurement toward vendors with pre-certified device platforms and established quality management systems under ISO 13485.
Growth Catalysts
- Home care reimbursement frameworks:Scandinavian health authorities are expanding remote patient monitoring coverage, accelerating wearable monitor deployment for chronic disease management outside hospital settings.
- EU AI Act algorithmic transparency obligations:Diagnostic software components face mandatory explainability standards, creating first-mover advantage for vendors with pre-built compliance infrastructure.
- Bluetooth 5.3 and ultra-wideband integration:Low-energy wireless protocols enable continuous glucose monitoring and cardiac telemetry with extended battery life and improved hospital-to-home handoff reliability.
Market Restraints
- Biocompatible polymer supply concentration:Medical-grade silicone and thermoplastic elastomer production clusters in Germany and Switzerland create input cost volatility for housing and sensor encapsulation.
- EMA notified body capacity constraints:EU MDR recertification backlogs extend conformity assessment timelines to 18-24 months for Class IIa connected devices.
- Basic Bluetooth telemetry substitution:Low-cost, non-IoT-enabled monitors from Eastern European manufacturers capture price-sensitive primary care segments.
Strategic Opportunities
- France's territorial hospital group consolidation:GHT procurement centralization creates single-entry-point contracts for integrated monitoring platforms across 140+ hospital networks.
- Edge AI and federated learning convergence:On-device inference combined with distributed model training enables real-time arrhythmia detection without raw data transmission.
- Germany's DiGA fast-track pathway:Digital health applications reimbursement catalog expansion opens prescription-channel access for software-embedded therapeutic devices.
Industry Challenges
- Cybersecurity engineering talent scarcity:End-to-end encryption implementation for wireless medical device stacks competes with fintech and automotive sectors for embedded systems specialists.
- Legacy hospital IT architecture integration:HL7 FHIR interoperability requirements force custom middleware development for EHR connectivity across heterogeneous national health information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Medical Devices Market |
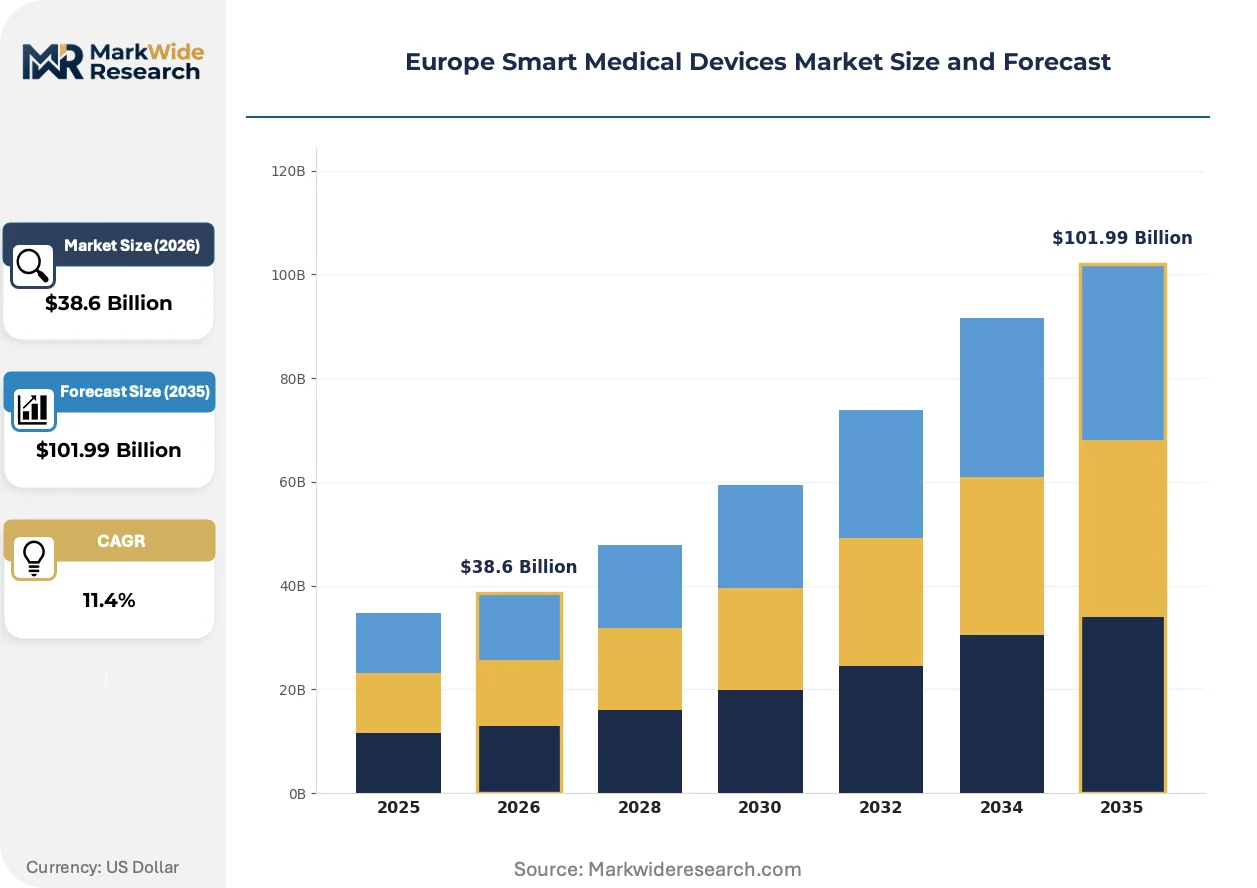
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wearable Monitors, Insulin Pumps, Smart Inhalers, Connected Thermometers End User: Hospitals, Home Care, Nursing Facilities, Clinics Technology: IOT, Bluetooth, RFID, NFC Application: Diabetes Management, Cardiovascular Monitoring, Respiratory Care, Remote Patient Monitoring |
| Companies Covered | Koninklijke Philips N.V., Siemens Healthineers AG, Fresenius Medical Care AG, GE Healthcare, Abbott, Boston Scientific Corporation, B. Braun SE, Medtronic, Stryker, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Medical Devices Market Trends and Innovations
Sensor miniaturization and edge computing architectures are compressing the form-factor-to-functionality ratio while enabling continuous physiological monitoring outside controlled clinical environments.
Multi-modal biosensor arrays combining photoplethysmography, electrocardiography, and impedance spectroscopy in single wearable patches are digitizing cardiovascular risk stratification workflows. German acute care networks are piloting these platforms for post-surgical monitoring at 48-hour discharge intervals. The technology is digitizing patient triage decisions by compressing telemetry-to-alert latency from minutes to seconds.
EU MDR Article 10 post-market surveillance requirements mandate active device follow-up through unique device identification registries. Manufacturers must now maintain clinical evidence portfolios across entire product lifecycles rather than single pre-market submissions. Class III implantable cardiac monitors face the steepest compliance cost escalation as notified bodies demand real-world performance data.
Hospital procurement departments are unbundling device hardware from data platform subscriptions, forcing vendors to compete on transparent software licensing terms. French GHTs and Dutch hospital associations pioneered this separation, with Nordic regions now adopting similar frameworks. Renal care settings remain the exception where Fresenius Medical Care maintains bundled dialysis-device-and-data contracts.
Europe Smart Medical Devices Market Segmentation
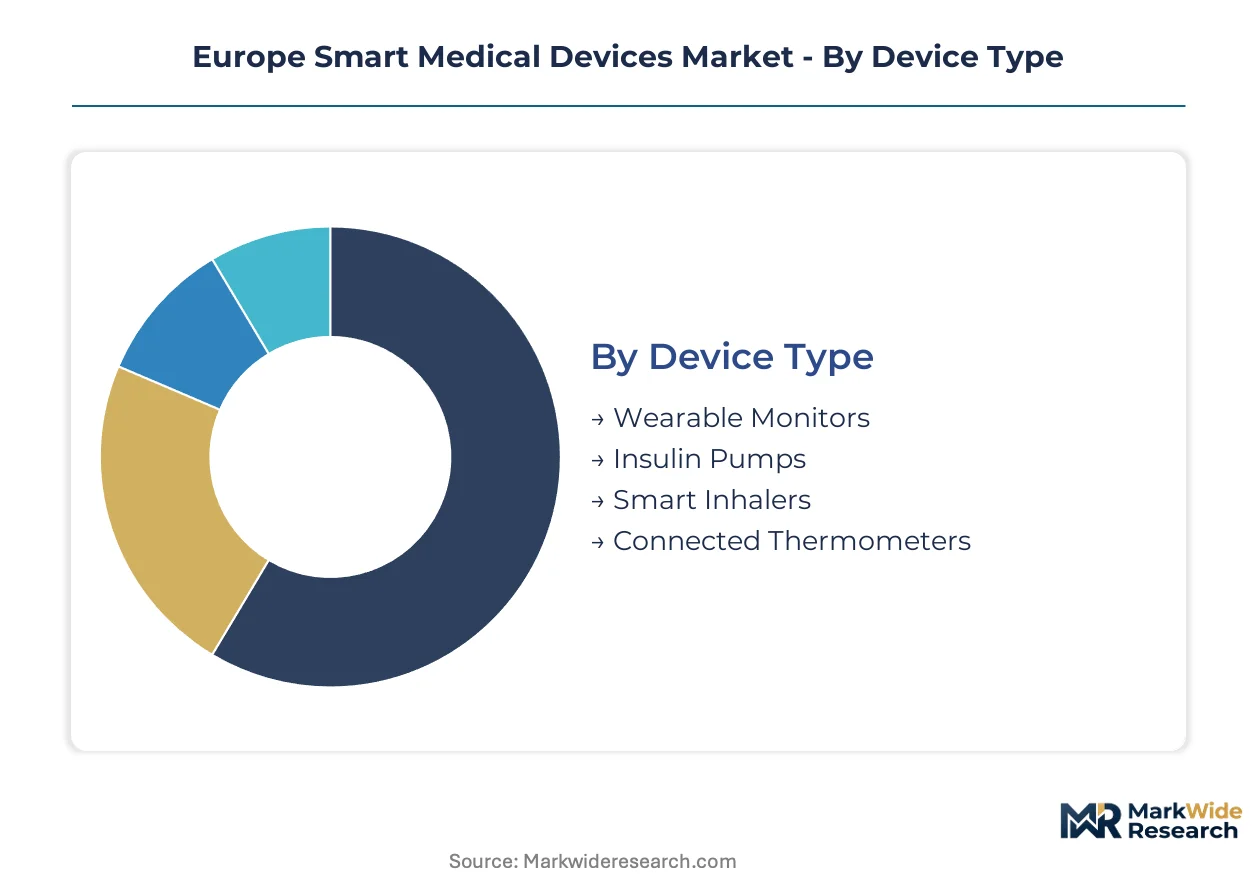
Smart medical device segmentation reveals distinct service contract profiles, hardware refresh cycles, and regulatory compliance burdens that shape vendor profitability across Europe. Procurement patterns in Germany's hospital networks and Scandinavia's home care systems demonstrate how end-use concentration drives technology tier preferences.
Device Type:
After-sales-service intensity varies sharply across device categories, with implantable and wearable platforms demanding multi-year calibration contracts and remote firmware management that alter lifetime value calculations for vendors.
- Wearable Monitors:Multi-sensor patches and wrist-worn devices integrate photoplethysmography, electrocardiography, and accelerometry for continuous cardiovascular and metabolic tracking. German acute care networks and Swedish home care authorities are expanding procurement for post-surgical and chronic disease monitoring, driven by EU MDR post-market surveillance mandates that favor vendors with established quality management systems.
- Insulin Pumps:Closed-loop systems combine continuous glucose monitoring with algorithm-driven insulin delivery, requiring specialized training support and 24/7 technical hotlines. Demand concentrates in Netherlands and Belgium diabetes centers where reimbursement frameworks cover advanced pump therapy, constrained by biocompatible polymer supply bottlenecks for infusion set manufacturing.
- Smart Inhalers:Bluetooth-enabled dose counters track medication adherence and trigger clinical alerts for asthma and COPD management.
- Connected Thermometers:NFC and Bluetooth fever monitors support pediatric and infectious disease surveillance with minimal service infrastructure.
By volume, Wearable Monitors leads. By growth pace, Insulin Pumps is ahead.
End User:
Procurement sophistication and contract duration diverge markedly across care settings, with hospital group purchasing organizations demanding integrated platform solutions while home care segments prioritize standalone device affordability.
- Hospitals:Acute care networks in Germany, France, and Italy deploy centralized monitoring infrastructure with EHR integration and clinical decision support. France's 140+ territorial hospital groups are consolidating procurement for wearable platforms, creating single-entry-point contracts that favor vendors with balance-sheet capacity for long-term service agreements.
- Home Care:Scandinavian health authorities and Dutch municipal care organizations reimburse remote patient monitoring for chronic disease management outside institutional settings. Denmark and Norway lead wearable monitor deployment for heart failure and diabetes patients, propelled by national digital health strategies that prioritize aging-in-place cost containment.
- Nursing Facilities:Long-term care operators in Spain and Poland adopt basic Bluetooth telemetry for fall detection and vital sign surveillance.
- Clinics:Primary care networks in Eastern Europe favor low-cost non-IoT devices for episodic diagnostic screening.
By installed base, Hospitals dominates. By expansion trajectory, Home Care gains share fastest.
Technology:
Wireless protocol selection determines encryption engineering requirements, battery life performance, and interoperability certification costs that segment vendor competitive positions.
- IOT:Cloud-connected platforms with edge computing capabilities enable real-time analytics and predictive alerting for high-acuity monitoring. German hospital networks and Nordic home care systems command premium positioning for these architectures, reflecting where margin pools concentrate as GDPR health data rules and EU AI Act obligations raise compliance barriers for basic connectivity alternatives.
- Bluetooth:Low-energy 5.3 protocols dominate continuous glucose monitoring and cardiac telemetry with extended battery life and improved hospital-to-home handoff reliability. French and Dutch procurement frameworks increasingly unbundle Bluetooth hardware from data platform subscriptions, forcing transparent software licensing competition.
- RFID:Passive and active radio-frequency identification supports asset tracking and patient identification workflows with minimal power requirements.
- NFC:Near-field communication enables secure device pairing and localized data transfer for point-of-care diagnostic instruments.
By revenue contribution, IOT commands premium positioning. By deployment velocity, Bluetooth extends reach most rapidly.
Application:
Clinical evidence requirements and reimbursement pathway maturity create divergent market access timelines across therapeutic domains.
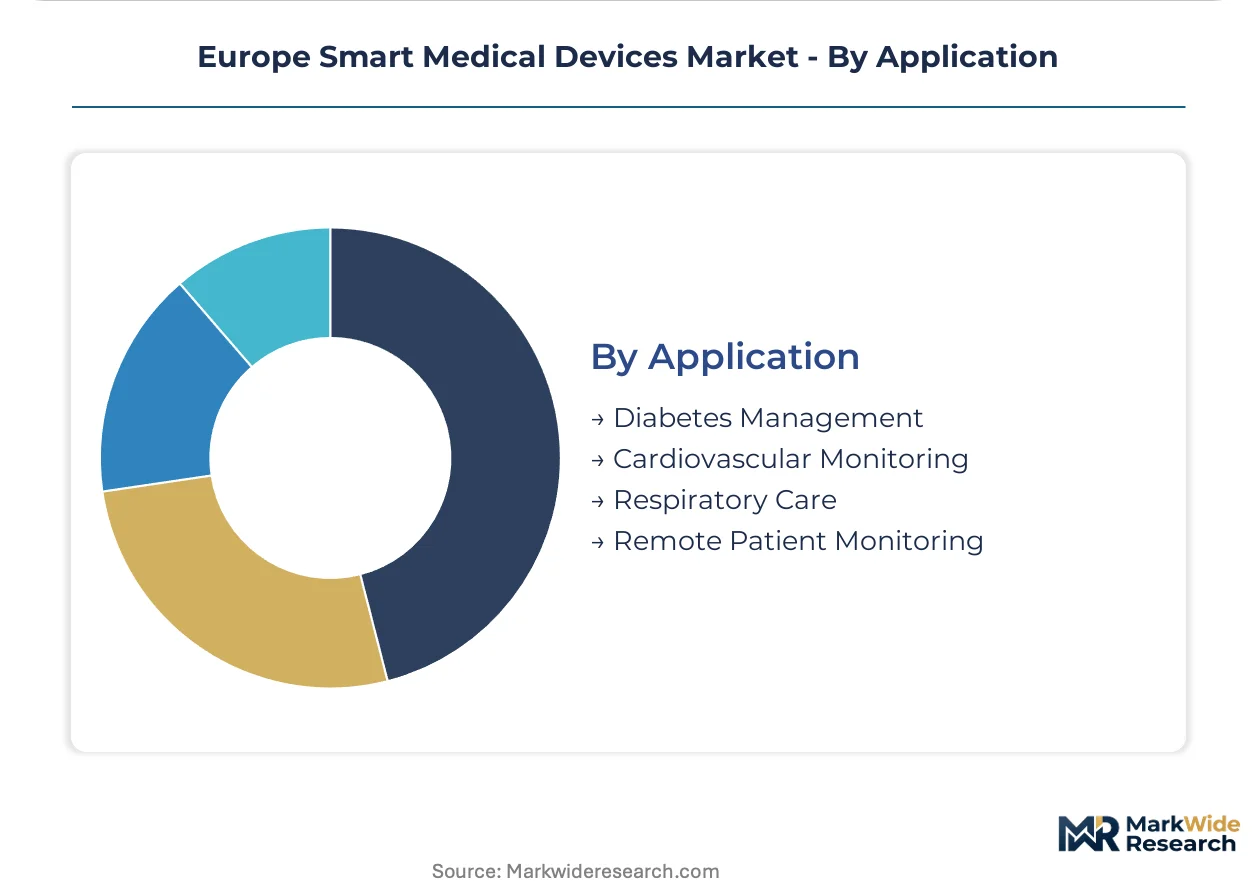
- Diabetes Management:Continuous glucose monitors, smart insulin pens, and closed-loop artificial pancreas systems digitize glycemic control workflows. Germany's DiGA fast-track pathway and Belgium's reimbursement catalog expansion accelerate prescription-channel access for software-embedded therapeutic devices, though EMA notified body backlogs extend EU MDR conformity timelines.
- Cardiovascular Monitoring:Ambulatory ECG, blood pressure, and heart failure sensor platforms enable post-acute surveillance and arrhythmia detection. German hospital groups pilot multi-modal biosensor arrays for 48-hour discharge intervals, while edge AI convergence permits on-device inference without raw data transmission to address GDPR constraints.
- Respiratory Care:Smart inhalers and continuous pulse oximetry support asthma, COPD, and sleep apnea management with medication adherence tracking.
- Remote Patient Monitoring:Integrated platforms spanning multiple physiological parameters enable chronic disease management outside traditional care settings.
By current penetration, Cardiovascular Monitoring leads. By reimbursement momentum, Diabetes Management climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German acute care networks extract pricing premiums through centralized procurement scale, while Eastern European primary care segments absorb cost-pressured basic telemetry alternatives. Scandinavian home care authorities command vendor concessions through national digital health mandates.
Germany
Bavarian and North Rhine-Westphalian hospital groups drive demand for integrated monitoring platforms with EHR connectivity. The DiGA fast-track pathway accelerates prescription-channel access for software-embedded therapeutic devices. Berlin-Brandenburg clusters concentrate edge AI development for on-device arrhythmia detection without raw data transmission.
France
Territorial hospital group consolidation across 140+ networks centralizes procurement for wearable platforms. ANSM post-market surveillance requirements align with EU MDR Article 10 clinical evidence mandates. Île-de-France acute care networks pilot multi-modal biosensor arrays for 48-hour post-surgical discharge intervals.
Scandinavia
Denmark and Norway lead wearable monitor deployment for heart failure and diabetes patients under national aging-in-place strategies. GDPR health data rules and GDPR-aligned national digital health frameworks shape cross-border data flow architectures. Stockholm and Copenhagen clusters concentrate remote patient monitoring platform development for municipal care organization reimbursement.
Netherlands
Diabetes centers in Randstad regions drive closed-loop insulin pump adoption through advanced therapy reimbursement coverage. Dutch hospital associations pioneered hardware-software unbundling in procurement frameworks. Eindhoven-region medical device clusters face biocompatible polymer supply bottlenecks for infusion set manufacturing.
United Kingdom
NHS England integrated care systems expand remote patient monitoring contracts for chronic disease management outside hospital settings. MHRA alignment with EU MDR recertification timelines extends conformity assessment for Class IIa connected devices. London-Southeast clusters concentrate cybersecurity engineering talent for wireless medical device stack encryption.
Europe Smart Medical Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor modules and wireless stacks to multiple OEMs. The vendor base stratifies across imaging-to-digital platform providers, patient monitoring data architects, and connected therapeutic device specialists. Three archetypes dominate: diversified health technology conglomerates with balance-sheet capacity for long-term service contracts; mid-cap device specialists with ISO 13485-certified quality management systems; and software-embedded diagnostic platform developers navigating EU AI Act algorithmic transparency obligations. Competitive moves concentrate on strategic partnerships for EHR interoperability middleware and portfolio diversification into edge AI architectures.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and Siemens Healthineers AG occupy positions anchoring large European hospital group purchasing decisions through imaging-to-digital integration and platform scale. Fresenius Medical Care AG exemplifies the therapeutic device specialist archetype, maintaining bundled dialysis-device-and-data contracts in renal care settings where procurement unbundling has not penetrated. These three represent distinct competitive vectors: vertical platform control, imaging-digital integration, and therapy-specific connected device dominance.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Siemens Healthineers AG |
| Fresenius Medical Care AG |
| GE Healthcare |
| Abbott |
| Boston Scientific Corporation |
| B. Braun SE |
| Medtronic |
| Stryker |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp medical device logistics corridor channels biocompatible polymers and sensor modules from German and Swiss production clusters into French and Dutch assembly operations, with freight cost volatility amplifying margin compression for vendors lacking captive supply of medical-grade silicone while procurement unbundling forces transparent software licensing competition downstream.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with ISO 13485 certification grade and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from Eastern European manufacturers capturing primary care segments with basic Bluetooth telemetry alternatives. Hospital group purchasing organizations exhibit lowest price sensitivity due to long-term service contract requirements, while municipal home care authorities in Scandinavia and Poland drive hardest bargain negotiations.
Supply Chain Analysis
Flex and Jabil medical device divisions concentrate contract manufacturing capacity for European smart medical device OEMs, with additional capacity held by specialized Swiss and German EMS providers. Component sourcing draws from German sensor foundries, Swiss precision polymer processors, and Taiwanese semiconductor packaging operations. Single-source vulnerability concentrates in medical-grade thermoplastic elastomer supply from Basel-region chemical clusters. Distribution runs through hospital group purchasing organizations in France and Germany, direct-to-provider contracts in Nordic home care systems, and regional medical distributors in Eastern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe smart medical devices sit in early-cycle expansion as home care reimbursement frameworks in Scandinavia and Germany's DiGA pathway accelerate prescription-channel access for connected therapeutic platforms.
For Market Incumbents: Pre-empt margin erosion from unbundled procurement frameworks by anchoring long-term service contracts with French GHTs and German hospital groups. Deepen backward integration into biocompatible polymer processing to offset supply concentration risk in Swiss and German chemical clusters. Accelerate edge AI firmware development to meet EU AI Act algorithmic transparency obligations before compliance costs escalate.
For New Entrants and Emerging Players: Mid-market nursing facilities in Spain and Poland represent the most penetrable entry point, with basic Bluetooth telemetry for fall detection and vital sign surveillance underserved by premium-focused incumbents. Eastern European primary care clinics seeking low-cost non-IoT alternatives offer second white-space target. Partner with regional medical distributors rather than pursuing direct hospital contracts to bypass GPO consolidation barriers.
For Investors and Strategic Acquirers: ISO 13485-certified software-embedded diagnostic platform developers with pre-built EU AI Act compliance infrastructure offer prime acquisition targets as regulatory barriers intensify. Long-term viability hinges on reimbursement catalog positioning rather than device hardware margins alone. Watch EMA notified body capacity expansion timelines as inflection signal for Class IIa recertification backlog resolution.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance accelerates market access for connected device vendors against recertification backlogs. |
| Hospital System Partnership | France's 140+ GHT networks consolidate procurement decisions around vendors with balance-sheet capacity for multi-year service agreements. |
| Software Companion Development | Germany's DiGA fast-track pathway opens prescription-channel reimbursement for algorithm-driven therapeutic platforms. |
| Reimbursement Strategy | Scandinavian national digital health mandates prioritize aging-in-place cost containment through remote patient monitoring coverage expansion. |
| Platform Integration | HL7 FHIR interoperability middleware enables EHR connectivity across heterogeneous national health information systems. |
Research Methodology
Cross-validation between hospital procurement database analysis and GPO contract documentation anchors the qualitative findings, with primary interviews conducted across biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs leads at notified bodies. Secondary validation draws from EMA medical device guidance releases, EU MDR recertification timelines, ANSM post-market surveillance reports, and national health technology assessment body reimbursement catalog updates. Bottom-up device shipment modeling and top-down healthcare expenditure allocation triangulate market sizing across the analysis window.
Calibration against historical EU MDR implementation trajectories and GDPR health data enforcement patterns shapes the projection framework. Segmentation modeling spans device type, end user archetype, wireless protocol technology tier, and clinical application domain, with additional dimensioning by national reimbursement pathway maturity. CAGRs derive from penetration curve analysis against comparable digital health adoption cycles, incorporating Bluetooth 5.3 deployment velocity and edge AI inference capability diffusion as technology-specific inputs.
Practitioners should monitor EMA notified body capacity expansion, EU AI Act implementing guidance releases, and national HTA body reimbursement catalog updates for early signals of forecast revision triggers. Quarterly review of GHT procurement consolidation progress, DiGA pathway admission rates, and biocompatible polymer supply chain disruptions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Japan Anesthesia Devices Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Wearable Medical Technology Market
Medical Devices
Global Infusion Pump Software Market
Medical Devices
Intubation Tubes Market
Medical Devices
Bone Power Tools Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Intraoperative Sensor Market
Medical Devices
Global Bone Cement Delivery System Market
Medical Devices
Lactate Meter Market
Medical Devices
Coated Endotracheal Tube Market
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
Glass Syringe Market
Medical Devices
Ventilation Devices Market
Medical Devices
Global Soft Tissue Allografts Market