
 Global Nerve Monitoring System Market | 2026-2036
Global Nerve Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nerve Monitoring System Market Foresight
The EU Green Deal's push for sustainable healthcare procurement is restructuring hospital capital equipment purchasing across Europe. Medtronic leverages its integrated surgical ecosystem to sustain platform loyalty in high-volume orthopedic and neurosurgical accounts. NuVasive anchors its competitive position through specialized spine-focused neuromonitoring systems that dominate ambulatory surgical center penetration in North America.
A nerve monitoring system comprises electrophysiological acquisition hardware, stimulating probes, and signal processing software designed to detect neural pathway integrity in real time during surgical procedures, typically resolving signals at microvolt precision with latency windows under 10 milliseconds. Its primary commercial purpose is preventing iatrogenic nerve injury in procedures where anatomical visualization alone cannot guarantee neural preservation. Intraoperative Monitoring leads product type revenue by capturing the bulk of capital equipment replacement cycles in tertiary hospitals, while Software Solutions represents the fastest-expanding margin pool as vendors shift toward recurring telemetry and cloud-based analytics revenue. Electromyography technology occupies the most mature competitive position, whereas Motor Evoked Potentials competes for share in complex spinal deformity cases where corticospinal tract surveillance commands premium pricing.
The FDA enforces 510(k) premarket notification requirements for nerve monitoring hardware, while the EU Medical Device Regulation mandates enhanced clinical evidence and post-market surveillance for Class IIa and above electrodiagnostic devices. ISO 13485 quality management certification shapes supplier eligibility for hospital group purchasing contracts across both jurisdictions. Stakeholders must monitor how evolving cybersecurity guidance from FDA and notified bodies affects software update cadence and cloud connectivity architectures in next-generation platforms.
Market Dynamics
The EU Medical Device Regulation's enhanced clinical evidence requirements for Class IIa electrodiagnostic devices are compressing product development timelines and forcing vendors to front-load regulatory investments before market entry, fundamentally restructuring competitive economics for neural signal acquisition hardware.
Growth Catalysts
- MDR Compliance Deadlines:The EU Medical Device Regulation's 2024-2026 transition period accelerates hospital replacement cycles for legacy neuromonitoring platforms that cannot meet enhanced post-market surveillance mandates.
- Spine Surgery Volume Concentration:Academic medical centers in the United States are embedding multimodal evoked potential monitoring into standard surgical protocols for complex deformity cases, creating institutional purchasing momentum.
- Cloud Telemetry Architectures:Signal processing software is migrating toward subscription-based analytics platforms, generating recurring revenue streams that improve vendor cash flow predictability and customer lifetime value.
Market Restraints
- Input Cost Volatility:Precision analog-to-digital converters and medical-grade isolation amplifiers face semiconductor supply constraints, particularly affecting hardware margins for mid-tier system manufacturers.
- Specialized Talent Scarcity:Certified neurophysiologists capable of intraoperative monitoring interpretation remain concentrated in tertiary urban hospitals, limiting ambulatory surgical center adoption regardless of equipment availability.
- Reimbursement Compression:CMS coding revisions for intraoperative neuromonitoring in the United States reduce per-procedure payment rates, squeezing hospital capital allocation for platform upgrades.
Strategic Opportunities
- ASC Penetration in Germany:Outpatient spine surgery facilities in Bavaria and North Rhine-Westphalia remain underpenetrated for dedicated neuromonitoring systems, presenting first-mover expansion potential.
- AI-Assisted Signal Interpretation:Machine learning algorithms for real-time artifact rejection and waveform pattern recognition are converging with traditional electrophysiology, enabling technician-level operation in resource-constrained settings.
- EU Green Deal Procurement:Sustainable healthcare purchasing mandates favor vendors with circular economy certifications for hardware refurbishment and component recycling programs.
Industry Challenges
- Cybersecurity Validation Burden:FDA guidance on medical device software updates requires documented threat modeling for cloud-connected platforms, extending quality assurance timelines.
- Legacy System Integration Friction:Hospital information system interoperability with proprietary neuromonitoring data formats demands custom interface development, complicating enterprise-wide deployments.
- ISO 13485 Certification Bottlenecks:Notified body capacity constraints for quality management audits delay supplier eligibility for group purchasing organization contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nerve Monitoring System Market |
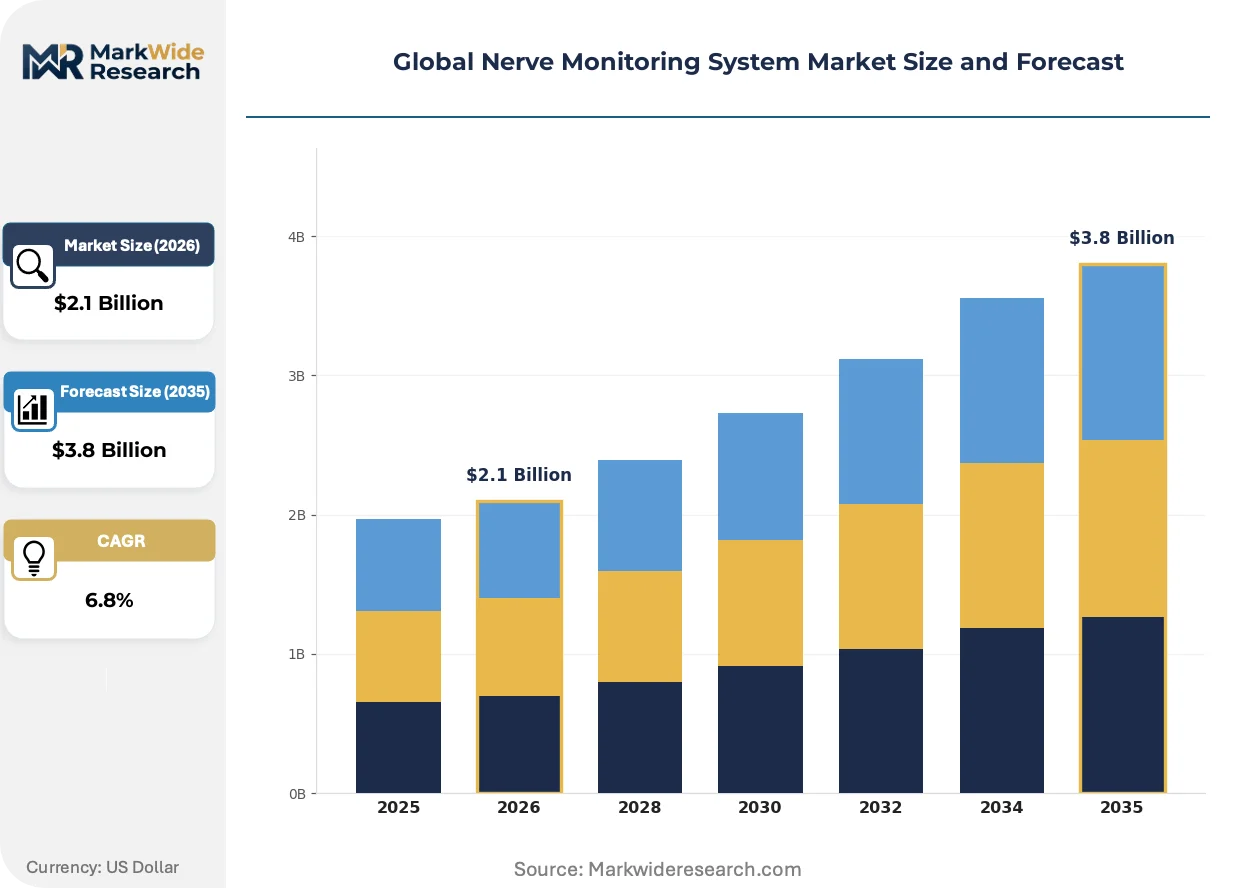
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraoperative Monitoring, Electrodiagnostic Equipment, Neuromonitoring Probes, Software Solutions, Signal Amplifiers Technology: Electromyography, Somatosensory Evoked Potentials, Brainstem Auditory Evoked Potentials, Motor Evoked Potentials, Ultrasound Monitoring Application: Neurosurgery Procedures, Orthopedic Interventions, Head & Neck Surgeries, Spine Surgery, Thyroidectomy End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Academic Research Institutes, Specialty Clinics |
| Companies Covered | Medtronic, NuVasive, Nihon Kohden, Natus Medical, Checkpoint Surgical, Inomed Medizintechnik GmbH, Cadwell Industries, Magstim, Neurovision Medical Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nerve Monitoring System Market Shifts & Advancements
Signal processing architectures are fragmenting into componentized subsystems, enabling surgical equipment vendors to embed neuromonitoring capabilities directly into integrated platforms rather than sourcing standalone capital equipment.
Multimodal acquisition hardware is modularizing around standardized electrode interfaces and swappable amplifier cartridges. High-volume orthopedic accounts in the United States now demand plug-and-play compatibility with navigation systems and robotic guidance platforms. This modularization is compressing standalone system margins while expanding addressable market volume through OEM integration channels.
REACH restrictions on lead-containing solder materials are forcing printed circuit board redesigns for stimulating probes and patient interface cables. European manufacturers face 18-month material qualification timelines that delay product line refreshes. Probe suppliers with pre-validated biocompatible alternatives capture preferential placement in notified body technical documentation reviews.
Hospital capital committees now unbundle neuromonitoring hardware from technical support and software maintenance contracts, treating these as separate line-item negotiations. Tertiary hospitals in the United States increasingly source equipment through third-party financing vehicles while retaining direct vendor relationships for clinical training. This purchasing pattern is most visible in California and Texas health systems pursuing off-balance-sheet treatment of electrophysiology platform investments.
Global Nerve Monitoring System Market Segmentation
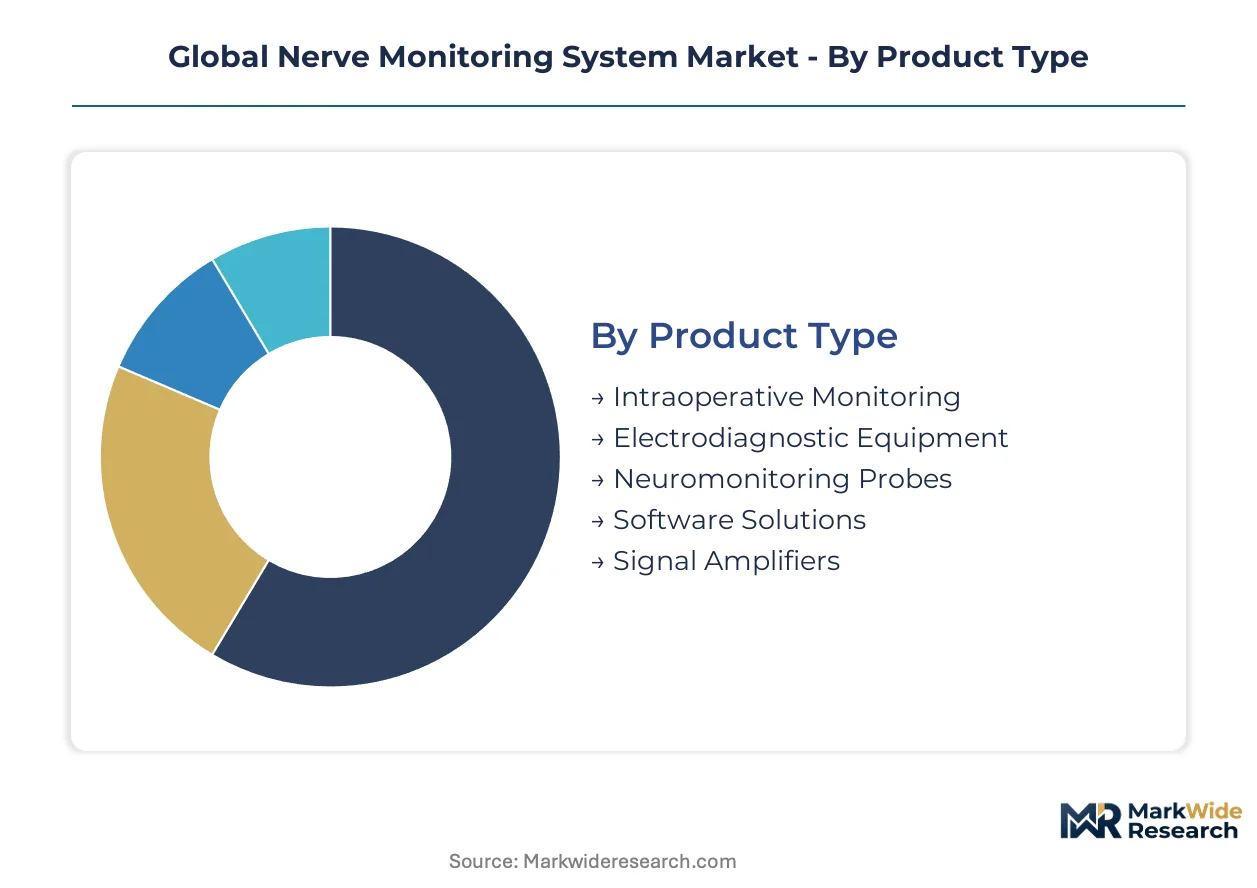
Segmentation in nerve monitoring systems reveals how capital equipment, consumable probes, and software layers command divergent margin profiles and replacement cycles. Understanding these splits exposes where vendors can extract recurring revenue versus competing on upfront hardware tenders.
Product Type:
Intraoperative Monitoring captures high-volume capital replacement cycles in tertiary hospitals, while Software Solutions commands premium recurring margins through telemetry subscriptions.
- Intraoperative Monitoring:Integrated electrophysiological acquisition platforms with microvolt-precision amplifiers and real-time waveform displays. Demand concentrates in academic medical centers across the United States where multimodal monitoring is becoming standard protocol for complex deformity cases. Hardware replacement cycles run 7-10 years, creating predictable refresh revenue.
- Software Solutions:Cloud-based signal processing architectures with AI-assisted artifact rejection and longitudinal analytics dashboards. German hospitals in Bavaria and North Rhine-Westphalia are unbundling software licenses from hardware purchases, treating analytics as separate capital line items. Subscription models improve vendor cash flow predictability.
- Electrodiagnostic Equipment:Standalone diagnostic workstations for preoperative nerve conduction studies and postoperative follow-up assessments.
- Neuromonitoring Probes:Single-use stimulating and recording electrodes with biocompatible interfaces, subject to REACH material compliance timelines.
- Signal Amplifiers:Modular amplifier cartridges enabling plug-and-play compatibility with surgical navigation systems and robotic guidance platforms.
Today's leader: Intraoperative Monitoring. Tomorrow's challenger: Software Solutions.
Technology:
Established electrophysiological modalities face displacement pressure from emerging real-time imaging integration, with Motor Evoked Potentials gaining procedural share in high-complexity spinal cases.
- Electromyography:Surface and needle electrode techniques detecting voluntary and evoked muscle action potentials with established clinical validation. United States ambulatory surgical centers deploy EMG for routine spine cases where corticospinal tract surveillance is not required. Mature competitive position limits pricing power.
- Motor Evoked Potentials:Transcranial electrical stimulation protocols tracking corticospinal tract integrity during high-risk deformity corrections. Academic medical centers in California and Texas health systems embed MEP monitoring into standard protocols for scoliosis and kyphosis procedures, commanding premium equipment configurations.
- Somatosensory Evoked Potentials:Peripheral nerve stimulation with cortical recording for dorsal column pathway assessment during spinal instrumentation.
- Brainstem Auditory Evoked Potentials:Clicks and tone bursts monitoring cranial nerve VIII integrity during cerebellopontine angle and brainstem surgeries.
- Ultrasound Monitoring:Emerging real-time nerve visualization combining electrophysiological data with anatomical imaging, still awaiting standardized reimbursement coding.
Established standard: Electromyography. Steepest expansion trajectory: Motor Evoked Potentials.
Application:
Spine surgery anchors equipment utilization rates, while thyroidectomy represents an underpenetrated ambulatory setting where nerve monitoring adoption lags anatomical risk.
- Spine Surgery:Deformity correction, degenerative disease, and trauma procedures requiring continuous multimodal surveillance of motor and sensory pathways. German hospitals are expanding intraoperative neuromonitoring adoption beyond academic centers into community hospital settings. EU MDR compliance deadlines accelerate replacement of legacy platforms.
- Thyroidectomy:Recurrent laryngeal nerve monitoring during thyroid and parathyroid resections, with growing penetration in outpatient facilities. United States ambulatory surgical centers in Texas and California are piloting technician-supported monitoring protocols where certified neurophysiologist availability is scarce.
- Neurosurgery Procedures:Brain tumor resections, aneurysm clipping, and epilepsy surgeries demanding cranial nerve and cortical mapping capabilities.
- Orthopedic Interventions:Joint replacement and extremity procedures where peripheral nerve proximity to surgical fields creates iatrogenic injury risk.
- Head & Neck Surgeries:Parotidectomy, neck dissection, and skull base procedures requiring facial nerve and lower cranial nerve monitoring.
Volume anchor: Spine Surgery. Penetration opportunity: Thyroidectomy.
End User:
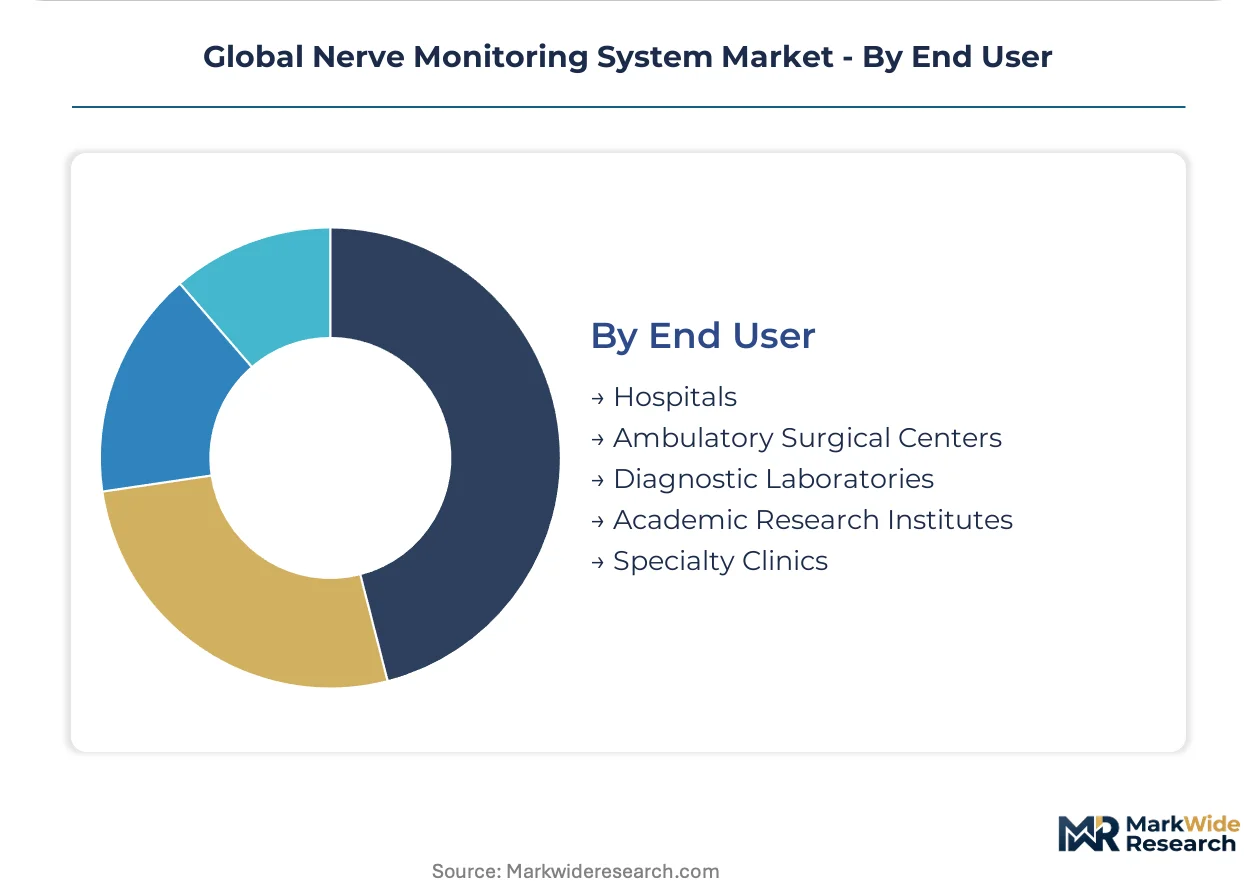
Hospital procurement committees unbundle hardware from service contracts, while ambulatory surgical centers face talent constraints that limit equipment utilization regardless of capital availability.
- Hospitals:Tertiary and community facilities with dedicated neurophysiology departments and 24/7 monitoring coverage. United States academic medical centers integrate multimodal platforms into enterprise surgical protocols. German hospitals pursue sustainable procurement certifications under EU Green Deal mandates.
- Ambulatory Surgical Centers:Outpatient facilities performing spine and ENT procedures with compressed case volumes and limited specialist staffing. Bavaria and North Rhine-Westphalia ASCs remain underpenetrated for dedicated neuromonitoring systems.
- Diagnostic Laboratories:Independent electrodiagnostic testing facilities performing preoperative nerve conduction studies.
- Academic Research Institutes:University-affiliated centers developing novel stimulation protocols and AI-assisted signal interpretation algorithms.
- Specialty Clinics:ENT and spine-focused practices with limited procedure volumes and outsourced monitoring technician models.
Revenue concentration: Hospitals. Structural constraint: Ambulatory Surgical Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The nerve monitoring system industry traces its commercial origins to post-war electrophysiology laboratories in the United States and Germany, where military-surplus oscilloscope technology was adapted for surgical applications. These two markets remain the primary anchors for platform innovation and clinical protocol standardization.
United States
Academic medical centers in California and Texas health systems embed multimodal evoked potential monitoring into standard surgical protocols for complex spinal deformity cases. FDA 510(k) premarket notification requirements govern hardware approval timelines, with recent cybersecurity guidance extending software validation periods. The Greater Boston cluster houses concentrated neurophysiology research institutes developing AI-assisted signal interpretation algorithms.
Germany
Hospitals in Bavaria and North Rhine-Westphalia are expanding intraoperative neuromonitoring adoption beyond academic centers into community hospital settings. The EU Medical Device Regulation mandates enhanced clinical evidence and post-market surveillance for Class IIa electrodiagnostic devices, compressing product development timelines for notified body submissions. The Tübingen-Stuttgart surgical technology corridor hosts specialized amplifier cartridge manufacturers.
Japan
PMDA regulatory frameworks emphasize electrical safety validation for neural signal acquisition hardware, with JIS standards governing medical-grade isolation amplifier specifications. The Kanto region around Tokyo concentrates demand from high-volume orthopedic and neurosurgical accounts integrating neuromonitoring with navigation systems. METI industrial policy supports domestic production of precision analog-to-digital converters.
China
NMPA medical device registration requirements are tightening software validation standards for cloud-connected platforms, affecting update cadence for next-generation systems. The Yangtze River Delta surgical equipment manufacturing base is developing modular amplifier cartridges for OEM integration into robotic guidance platforms. Dual carbon goals are pressuring printed circuit board suppliers to eliminate lead-containing solder materials ahead of REACH-equivalent domestic regulations.
United Kingdom
NHS procurement frameworks are unbundling neuromonitoring hardware from technical support contracts, treating software maintenance as separate line-item negotiations. The London-Southeast corridor concentrates tertiary hospital demand for multimodal monitoring platforms in complex deformity surgery. MHRA post-Brexit regulatory autonomy is diverging from EU MDR timelines for electrodiagnostic device certification.
Global Nerve Monitoring System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the nerve monitoring system value chain. Integrated surgical equipment vendors maintain in-house electrophysiology platform development, while specialized neuromonitoring firms source amplifier cartridges and signal processing modules from third-party foundries. The competitive landscape stratifies into three archetypes: diversified medical technology conglomerates with surgical ecosystem integration, spine-focused neuromonitoring specialists, and component suppliers enabling OEM partnerships. Dominant competitive moves include modular hardware architectures for navigation system compatibility and subscription-based software telemetry migrating revenue toward recurring analytics platforms.
Among diversified medical technology conglomerates, Medtronic leverages its integrated surgical ecosystem to sustain platform loyalty in high-volume orthopedic and neurosurgical accounts. NuVasive anchors its competitive position through specialized spine-focused neuromonitoring systems. Inomed Medizintechnik GmbH represents the European specialist archetype with concentrated presence in German-speaking surgical markets. These three exemplify divergent strategic postures: ecosystem breadth versus segment depth versus regional specialization.
| Leading Market Players |
|---|
| Medtronic |
| NuVasive |
| Nihon Kohden |
| Natus Medical |
| Checkpoint Surgical |
| Inomed Medizintechnik GmbH |
| Cadwell Industries |
| Magstim |
| Neurovision Medical Products |
| Others |
Supply & Pricing Matrix
Captive production of precision analog-to-digital converters and medical-grade isolation amplifiers anchors both supply security and premium pricing power for tier-one neuromonitoring system vendors, while mid-tier competitors remain exposed to semiconductor foundry allocation cycles and input cost volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies according to FDA 510(k) clearance tier and ISO 13485 certification depth, with academic medical centers in California and Texas health systems absorbing premium configurations for multimodal platforms while ambulatory surgical centers in Bavaria and North Rhine-Westphalia gravitate toward economy tiers where technician-supported models compress service bundling. Pricing pressure stems from CMS coding revisions reducing per-procedure reimbursement rates, forcing hospital capital committees to unbundle hardware from software maintenance contracts and extend replacement cycles. Price sensitivity concentrates in community hospitals facing EU MDR compliance deadlines, whereas integrated delivery networks with enterprise purchasing leverage command volume discounts.
Supply Chain Analysis
Dual-sourcing qualification mandates from notified bodies and hospital group purchasing organizations require vendors to maintain qualified suppliers for precision amplifiers across both German and Japanese manufacturing bases, with REACH restrictions on lead-containing solder materials forcing 18-month material qualification timelines that delay product line refreshes. Raw material dependencies center on medical-grade silicon substrates, biocompatible electrode alloys, and specialized printed circuit board laminates. Supply chain risk hinges on single-source vulnerability for Class IIa electrodiagnostic device components subject to EU MDR enhanced clinical evidence requirements. Distribution runs through direct sales forces for tertiary hospital accounts and specialized surgical equipment distributors for ambulatory surgical center penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation's 2024-2026 transition period functions as a regulatory compounder, accelerating hospital replacement cycles for legacy neuromonitoring platforms and compressing competitive economics for vendors unable to front-load clinical evidence investments.
For Market Incumbents: Deepen backward integration into amplifier cartridge production to insulate margins from semiconductor supply constraints, while embedding AI-assisted signal interpretation capabilities into cloud telemetry platforms to defend against software-native entrants. Prioritize ISO 13485 certification maintenance with notified bodies experiencing audit capacity bottlenecks, and secure enterprise-wide deployment contracts with United States academic medical centers before competitive displacement from integrated surgical equipment vendors accelerates. For New Entrants and Emerging Players: Ambulatory surgical center networks in Germany's Bavaria and North Rhine-Westphalia regions represent the most penetrable white-space target, where technician scarcity and underpenetrated dedicated neuromonitoring system adoption create first-mover expansion potential. Pursue OEM integration partnerships with robotic guidance platform manufacturers rather than competing for standalone capital equipment tenders, leveraging modular amplifier cartridge architectures to bypass entrenched hospital purchasing relationships. For Investors and Strategic Acquirers: Roll-up economics work for specialized spine-focused neuromonitoring software developers because hospital procurement committees are unbundling analytics licenses from hardware purchases and treating cloud-based telemetry as separate capital line items. Target acquisition profiles should prioritize vendors with pre-validated REACH-compliant biocompatible electrode alternatives and active FDA 510(k) submission pipelines. Watch AI-assisted artifact rejection algorithm regulatory clearance timelines as the inflection indicator for technician-level operation viability in resource-constrained settings.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Pathway | Accelerated notified body submissions capture hospital replacement cycles in Germany and United Kingdom. |
| Cloud Telemetry Platform Launch | Subscription revenue migration improves cash flow predictability for vendors serving academic medical centers. |
| OEM Integration Partnership | Modular amplifier cartridge compatibility with robotic guidance platforms expands addressable market volume. |
| AI Signal Interpretation Development | Machine learning algorithms enable technician-level operation in ambulatory surgical centers facing neurophysiologist scarcity. |
| REACH-Compliant Material Qualification | Pre-validated biocompatible electrode alternatives secure preferential placement in notified body technical documentation reviews. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down surgical equipment manufacturing tracking forms the analytical core, combining primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and neurophysiologists with secondary validation from FDA 510(k) filings, EU MDR notified body technical documentation, CMS Medicare reimbursement databases, and hospital capital equipment procurement records.
Historical trendline analysis of intraoperative monitoring platform replacement cycles and software subscription attach rates across product type, technology modality, application specialty, and end-user facility tier informs the projection framework, with CAGRs derived from segmented growth rate reconciliation against macro surgical volume forecasts and regulatory compliance deadline impacts throughout the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA cybersecurity guidance evolution and REACH material restriction expansion. Deviation in notified body audit capacity or semiconductor foundry allocation priorities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spectacle Lens Market
Medical Devices
Additional Defibrillator Accessories (AED) Market
Medical Devices
Laparoscopic Surgical Robot Market
Medical Devices
Global Electrotherapy System Market
Medical Devices
Condylar Plate Fixation System Market
Medical Devices
Single Lead ECG Equipment Market
Medical Devices
Spinal Traction Market
Medical Devices
Urethral Bulking System Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
Submucosal Injections Market
Medical Devices
Global Corneal Topographers Market
Medical Devices
Polysomnography Devices Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Anterior Cervical Plating Market