
 Microinsurance Market | 2026-2036
Microinsurance Market Size, Share, and Industry Trends Forecast 2026-2036
Microinsurance Market Intelligence
Mobile-first distribution infrastructure is consolidating the economics of last-mile coverage. Allianz SE leverages its parametric agricultural platforms to sustain premium collection in drought-prone regions. MicroEnsure Holdings Limited anchors partnerships with mobile network operators across East Africa, while Ping An Insurance (Group) Company of China Ltd. competes through embedded health products within its ecosystem apps.
Microinsurance denotes risk-transfer instruments with capped benefits, simplified underwriting, and premium thresholds aligned to irregular income streams, typically administered through digital or agent-light channels to minimize acquisition costs. Its primary commercial purpose pools catastrophic risks among populations excluded from conventional actuarial markets. Health insurance products command the deepest premium pools due to hospitalization frequency, while digital platform delivery models represent the fastest-expanding structural segment as smartphone penetration reduces friction in policy issuance and claims settlement. Agricultural insurance retains substantial latent demand among smallholder farmers, though basis risk in index-based products constrains margin expansion.
IRDAI in India, the Insurance Regulatory Authority in Kenya, and the National Insurance Commission in Ghana each enforce capital adequacy and consumer-protection standards that determine which entities qualify for microinsurance licenses. These frameworks shape product design by mandating cooling-off periods, limiting exclusions, and prescribing maximum expense ratios that compress distributor margins. Stakeholders must monitor whether emerging interoperability standards between national identity systems and insurer databases will unlock automated eligibility verification at scale.
Market Dynamics
Parametric weather-indexed products are compressing claims settlement cycles from months to days, fundamentally restructuring how agricultural risk transfers to capital markets. This technological shift is redrawing competitive boundaries between traditional indemnity-based insurers and algorithmic risk platforms.
Growth Catalysts
- IRDAI simplified disclosure mandates:India's relaxed capital requirements for microinsurers have accelerated licensed market entry, expanding product availability to informal sector workers previously excluded from conventional coverage pools.
- Mobile wallet integration:M-Pesa's embedded premium collection infrastructure in Kenya is automating recurring payments, reducing policy lapse rates among irregular income households.
- Smallholder farmer demand concentration:Drought exposure across sub-Saharan Africa is pulling agricultural index products into mainstream distribution through cooperative aggregators and input suppliers.
Market Restraints
- Basis risk in index triggers:Mismatches between parametric payouts and actual farm losses erode policyholder trust, constraining renewal rates in satellite-data-dependent agricultural lines.
- Smartphone penetration gaps:Rural populations without device access remain locked out of digital-first distribution, forcing costly agent networks in low-margin segments.
- Expense ratio ceilings:IRDAI-mandated maximum cost structures compress distributor commissions, limiting incentive alignment for last-mile sales agents.
Strategic Opportunities
- Interoperable identity verification:Linking national ID databases to insurer eligibility systems would automate KYC at scale, cutting acquisition costs for rural customer segments.
- Embedded health products:Super-app ecosystems in Southeast Asia present white space for outpatient and maternity coverage bundled with ride-hailing or e-commerce transactions.
- Mutual and cooperative models:Community-based risk pools in Ghana offer regulatory pathways for member-owned structures with lower capital requirements than commercial licenses.
Industry Challenges
- Actuarial data scarcity:Limited historical claims datasets for novel perils force conservative pricing that pushes premiums beyond informal sector affordability thresholds.
- Climate model recalibration:Increasing weather volatility requires continuous algorithm updates, straining technical capacity at smaller insurers without captive catastrophe modeling teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microinsurance Market |
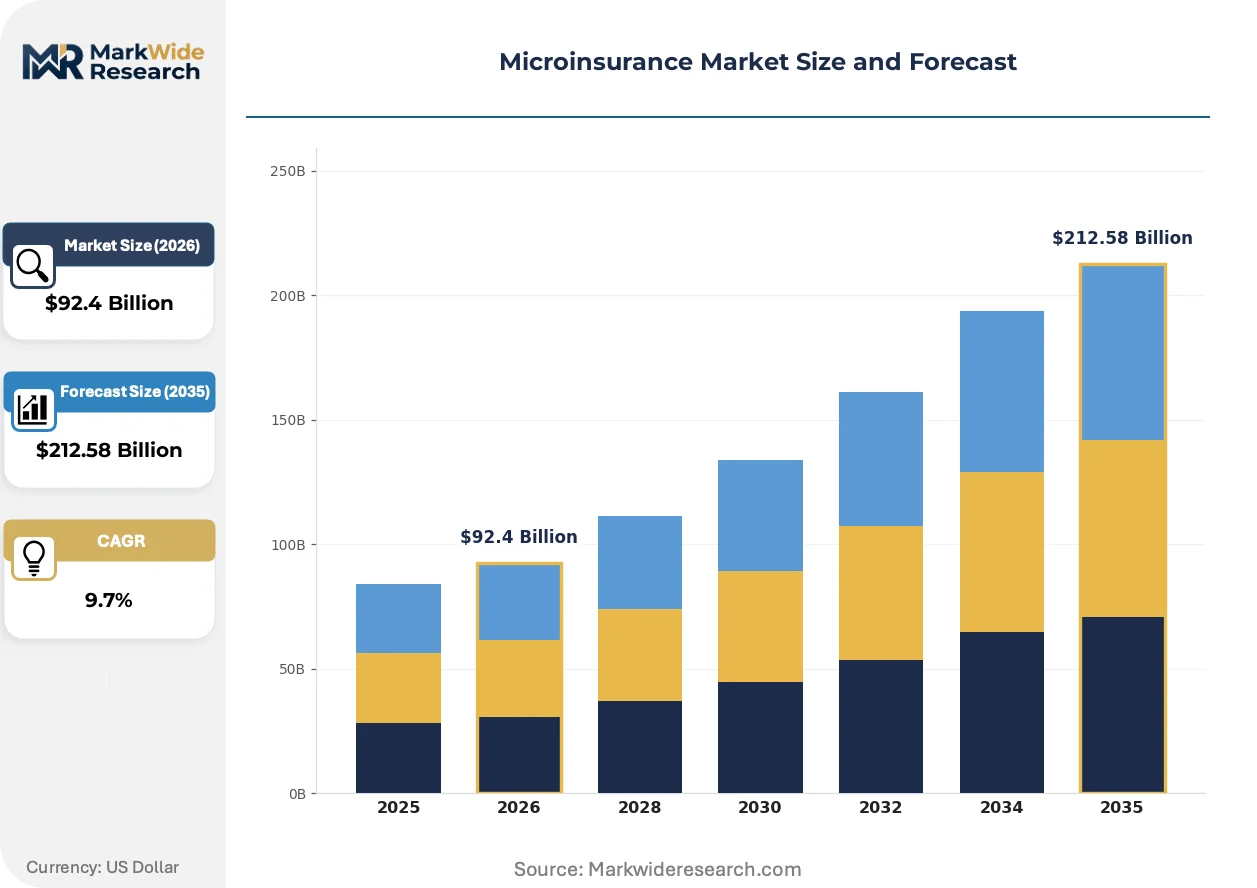
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $212.58 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health Insurance, Agricultural Insurance, Life Insurance, Property Insurance Delivery Model: Direct Sales, Partnerships, Digital Platforms, Community-Based Target Population: Low-Income Households, Smallholder Farmers, Micro-Entrepreneurs, Rural Communities Premium Type: Micro Premiums, Variable Premiums, Monthly Payments, Pay-As-You-Go |
| Companies Covered | MetLife Inc., American International Group Inc., Allianz SE, Swiss Re Group, Munich Re Group, Ping An Insurance (Group) Company of China Ltd., AXA SA, MicroEnsure Holdings Limited, Zurich Insurance Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microinsurance Market Strategic Shifts & Innovations
Algorithmic underwriting is displacing manual risk assessment across microinsurance value chains, compressing policy issuance from days to minutes while expanding addressable markets among thin-file customers.
Blockchain-enabled smart contracts are automating parametric payout execution, triggering settlement upon verified weather station or satellite data without manual claims adjustment. Agricultural cooperatives in Kenya and Ethiopia are adopting these instruments fastest, drawn by immediate liquidity post-disaster. Settlement automation is collapsing administrative costs and enabling premium levels viable for sub-dollar daily wage earners.
IRDAI's sandbox framework for microinsurance product testing is compressing regulatory approval timelines, allowing iterative benefit design without full filing requirements. Domestic insurers are piloting outpatient telemedicine bundles and livestock mortality covers under these provisions. The sandbox mechanism is accelerating product-market fit experimentation in health and agricultural lines previously stifled by rigid filing protocols.
Subscription-based microinsurance attached to mobile airtime purchases is displacing annual policy structures, aligning premium timing with cash flow patterns of informal workers. East African mobile network operators pioneered this model; Latin American carriers are now replicating the architecture. Flexible micropayment schedules are reducing lapse rates among agricultural households with seasonal income concentration.
Microinsurance Market Segmentation
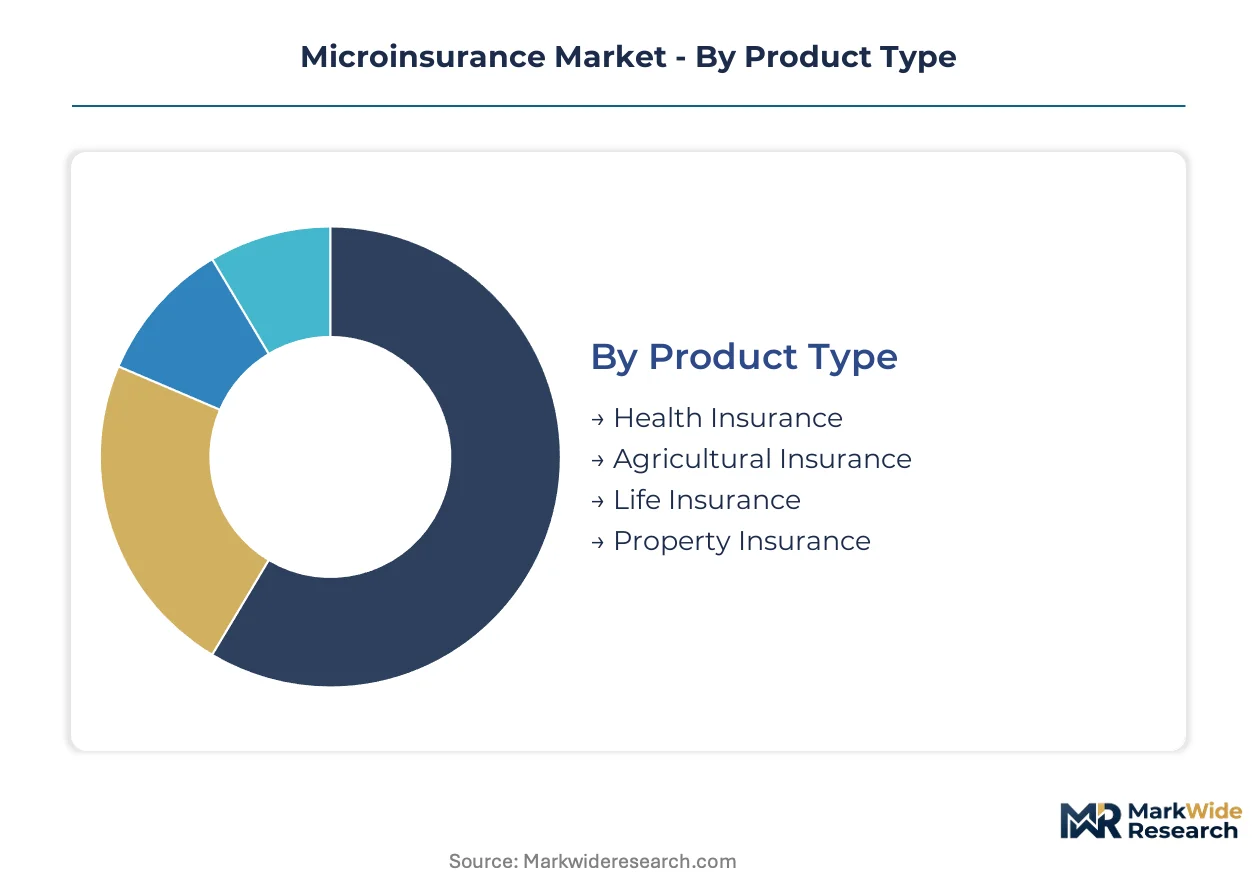
Microinsurance product architectures must balance standardized, scalable designs against localized customization for irregular income patterns and peril-specific exposures. Segment boundaries increasingly blur as digital platforms enable hybrid delivery models and parametric triggers reshape traditional product categories.
Product Type:
Standardized benefit structures dominate high-frequency health and life lines, while agricultural products require extensive localization for crop-specific index calibration.
- Health Insurance:Outpatient and hospitalization coverage with capped benefits and simplified exclusions. Demand concentrates in India's informal sector workers following IRDAI disclosure simplifications, though premium affordability thresholds constrain penetration in sub-dollar daily wage segments.
- Agricultural Insurance:Parametric weather-indexed products with satellite-triggered payouts. Smallholder cooperatives in Kenya and Ethiopia drive adoption fastest, drawn by immediate post-disaster liquidity, though basis risk between index triggers and actual field losses erodes renewal rates.
- Life Insurance:Term products with simplified underwriting and funeral benefit riders.
- Property Insurance:Micro-dwelling and livestock mortality covers with community-based risk pooling.
Leading the category by volume: Health Insurance. Expanding most quickly: Agricultural Insurance.
Delivery Model:
Cost tier determines channel viability, with digital platforms achieving lowest customer acquisition expense and community models absorbing highest last-mile servicing overhead.
- Digital Platforms:Smartphone-enabled policy issuance and claims settlement through embedded insurance architectures. M-Pesa integration in Kenya automates premium collection and reduces lapse rates among irregular income households.
- Partnerships:Bancassurance and mobile network operator distribution leveraging existing customer touchpoints. MicroEnsure Holdings anchors East African MNO partnerships, while input suppliers and cooperatives aggregate agricultural policyholders.
- Direct Sales:Agent-light networks with simplified product training.
- Community-Based:Member-owned mutual structures with lower capital requirements than commercial licenses, prevalent in Ghana's cooperative regulatory pathway.
Digital Platforms command the steepest expansion trajectory. Partnerships retain dominant volume share.
Target Population:
Customer type segmentation reflects income volatility patterns and risk exposure concentration rather than absolute poverty thresholds.
- Low-Income Households:Informal sector workers with irregular cash flows requiring flexible premium timing. Subscription models attached to mobile airtime purchases displace annual structures, aligning payments with liquidity availability.
- Smallholder Farmers:Agricultural households with seasonal income concentration and drought exposure driving parametric product demand. Cooperative aggregators in sub-Saharan Africa pool risk and negotiate group rates.
- Micro-Entrepreneurs:Solo operators and family businesses needing liability and asset protection.
- Rural Communities:Populations beyond conventional agent network reach, dependent on digital or community-based distribution.
Smallholder Farmers show the fastest-growing policy uptake. Low-Income Households constitute the largest addressable base.
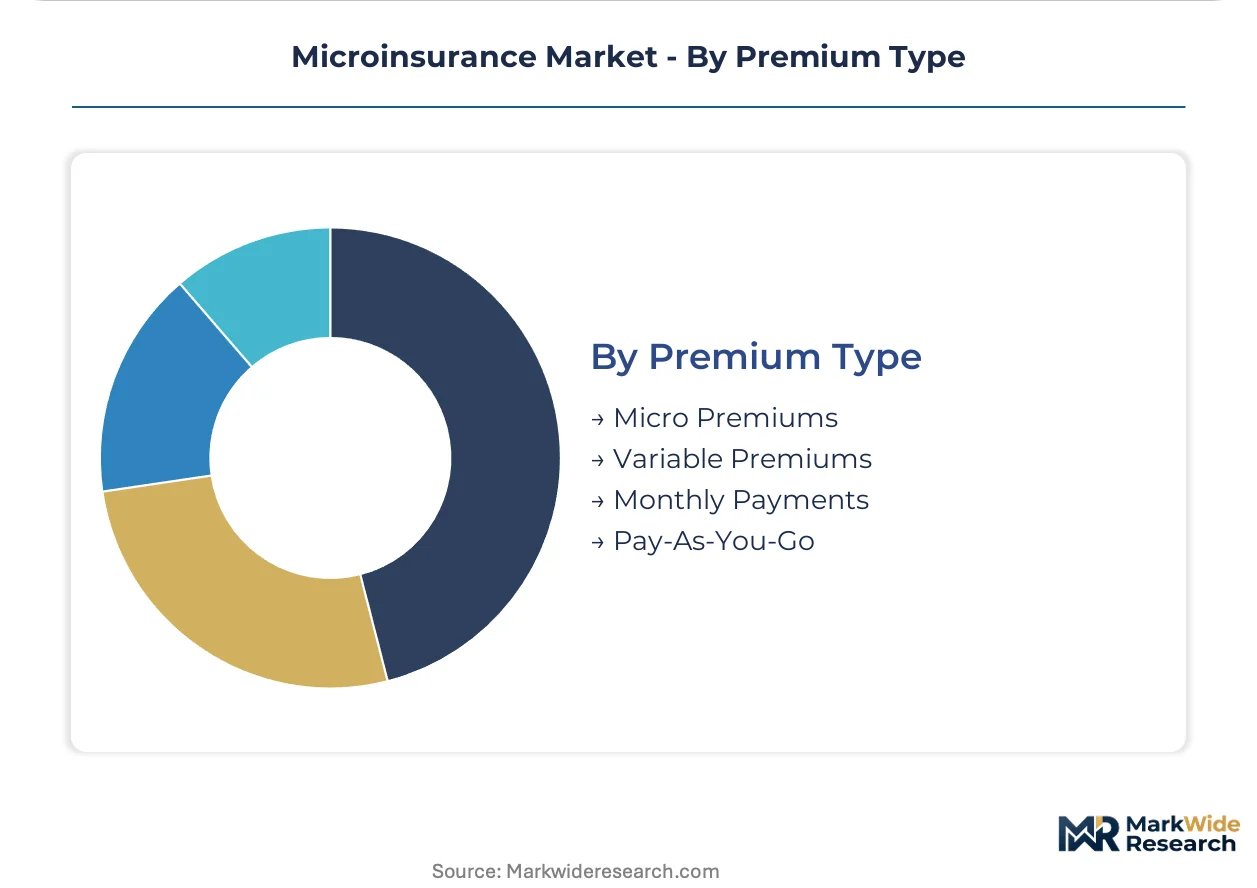
Premium Type:
Payment structure innovation determines inclusion depth, with frequency and flexibility mattering more than absolute price for thin-file customers.
- Micro Premiums:Sub-dollar periodic payments with minimal benefit caps. Mobile airtime bundling in East Africa and Latin America reduces transaction friction and enables viable unit economics.
- Pay-As-You-Go:Usage-triggered coverage activation tied to specific transactions or events. Embedded health products within super-app ecosystems in Southeast Asia pilot this architecture for outpatient and maternity lines.
- Variable Premiums:Income-adjusted payment scales.
- Monthly Payments:Fixed schedule aligned with salaried informal workers.
Micro Premiums dominate current issuance volume. Pay-As-You-Go models are gaining share fastest among platform-integrated distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the deepest regulatory innovation in microinsurance licensing, while Kenya's mobile payment infrastructure anchors the most mature digital distribution ecosystem. Sub-Saharan Africa's smallholder farmer segment is pulling parametric agricultural products into mainstream channels. The report identifies four critical national markets where product architecture and delivery models are diverging.
India
Informal sector workers in Maharashtra and Gujarat drive health microinsurance uptake following IRDAI's simplified disclosure mandates. The Insurance Regulatory and Development Authority relaxed capital requirements for dedicated microinsurers, accelerating licensed market entry. Domestic carriers pilot outpatient telemedicine bundles and livestock mortality covers through the sandbox framework in Mumbai and Bangalore.
Kenya
Smallholder cooperatives in the Rift Valley and Central Highlands anchor agricultural index product demand. M-Pesa's embedded premium collection infrastructure automates recurring payments and compresses policy lapse rates. Nairobi-based mobile network operators partner with international reinsurers to distribute weather-indexed coverage through cooperative aggregators.
China
Ping An's super-app ecosystem in Shenzhen and Guangzhou embeds health microinsurance within ride-hailing and e-commerce transactions. The National Financial Regulatory Administration oversees solvency requirements for digital-first insurers. Yangtze River Delta tech corridors pilot subscription-based models attached to mobile wallet purchases.
Ghana
Community-based mutual structures in the Northern and Ashanti regions exploit lower capital requirements than commercial licenses. The National Insurance Commission enforces consumer-protection standards that shape cooling-off periods and exclusion limits. Accra-based cooperatives aggregate rural policyholders for group-rated agricultural and property covers.
Ethiopia
Drought-exposed agricultural households in Oromia and Amhara drive parametric product experimentation. The Ethiopian Insurance Corporation partners with satellite data providers to calibrate index triggers for smallholder cooperatives. Addis Ababa serves as the coordination hub for blockchain-enabled smart contract pilots that automate post-disaster payouts.
Microinsurance Market Key Industry Players
Strategic partnerships dominate the current landscape as carriers seek mobile distribution reach without building captive agent networks. The market structures around three tiers: global reinsurers providing parametric risk capacity, regional insurers with regulatory licenses, and digital platforms handling last-mile acquisition. Two archetypes define competitive positioning: technology-integrated carriers leveraging algorithmic underwriting, and partnership-heavy distributors relying on mobile network operator channels. Capacity expansion into agricultural index products and embedded health architectures represent the dominant competitive moves.
Within the global reinsurer tier, Swiss Re Group and Munich Re Group occupy positions as parametric risk capacity providers for emerging market carriers. Among partnership-anchored distributors, MicroEnsure Holdings Limited exemplifies the mobile network operator collaboration model across East Africa. Allianz SE represents the technology-integrated archetype through its parametric agricultural platforms. These three entities illustrate how competitive positioning diverges between risk-bearing capacity and distribution infrastructure control.
| Leading Market Players |
|---|
| MetLife Inc. |
| American International Group Inc. |
| Allianz SE |
| Swiss Re Group |
| Munich Re Group |
| Ping An Insurance (Group) Company of China Ltd. |
| AXA SA |
| MicroEnsure Holdings Limited |
| Zurich Insurance Group |
| Others |
Cost & Logistics Intelligence
Actuarial talent concentration in Mumbai and Nairobi drives labor-cost differentials that widen pricing-tier spreads between algorithmic platforms and agent-heavy legacy distributors. Parametric underwriting specialists command premium compensation, forcing cost compression in traditional indemnity-based product lines.
Pricing Analysis
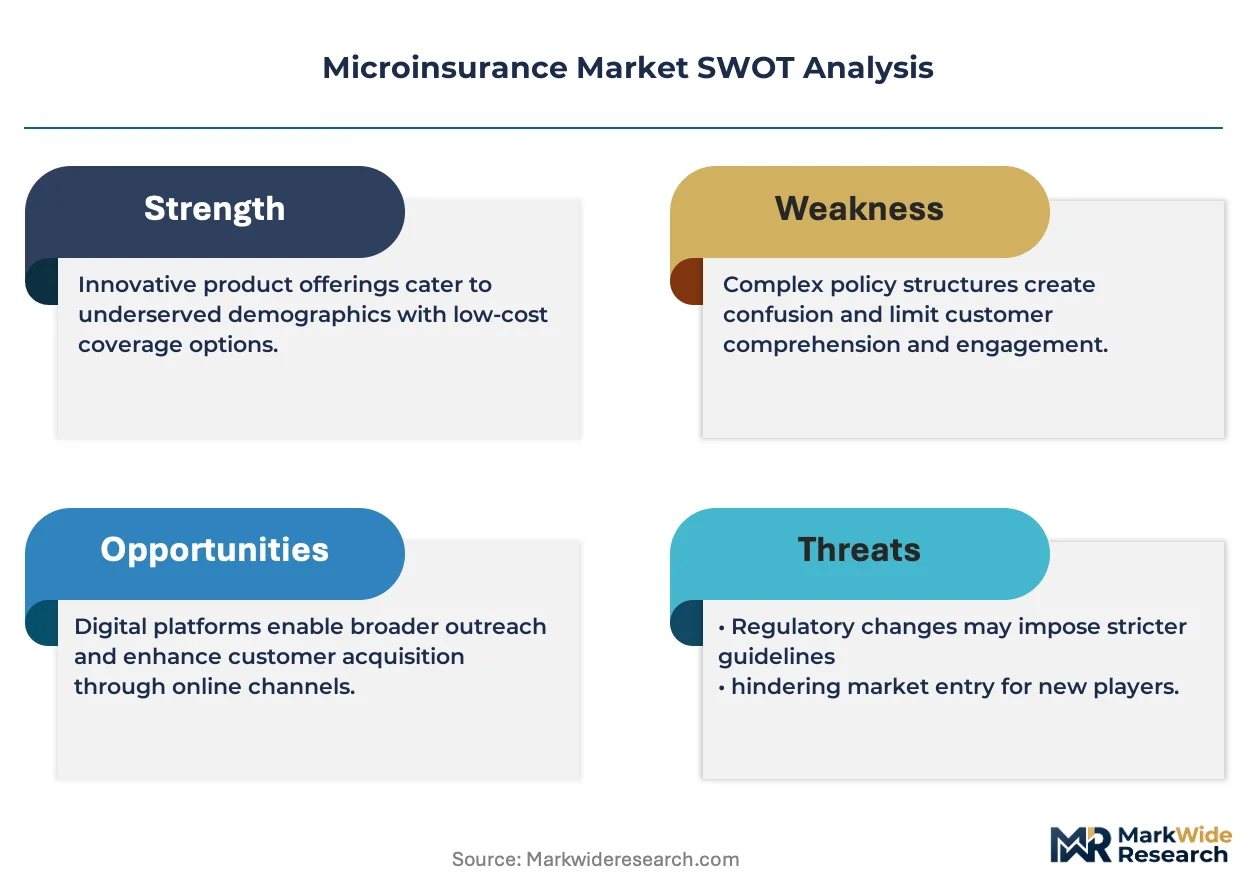
Volume-versus-margin splits separate mass-market micro-premium tiers from specialized agricultural index products. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by claims automation capability and satellite-data integration depth. Pricing pressure stems from IRDAI-mandated expense ratio ceilings that compress distributor commissions. Low-income households with irregular cash flows exhibit highest price sensitivity, while cooperative-aggregated smallholder farmers accept modest premium elevation for immediate post-disaster liquidity.
Supply Chain Analysis
Satellite data provision rests on specialized climate analytics firms in the United States, European Union, and India. Blockchain smart contract infrastructure draws from distributed ledger developers and mobile network operator payment gateways. Single-source vulnerability concentrates in proprietary weather index calibration algorithms. Distribution runs through embedded partnerships with M-Pesa in Kenya, IRDAI-licensed microinsurers in India, and cooperative aggregators across sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Parametric weather-indexed platforms are displacing manual claims-adjustment legacy systems, compressing settlement cycles from months to minutes across agricultural and health lines.
For Market Incumbents: Anchor regulatory license portfolios in IRDAI's simplified disclosure framework and Kenya's mobile wallet infrastructure to defend against algorithmic risk platform entrants. Deepen backward integration into satellite data partnerships to control index calibration costs. Prioritize certification investment in blockchain-enabled smart contract deployment to maintain technical parity with insurtech challengers. For New Entrants and Emerging Players: Algorithmic underwriting capability offers the most penetrable wedge into outpatient telemedicine bundles and livestock mortality covers piloted under India's sandbox framework. White-space targets include Ghana's community-based mutual structures with lower capital requirements and Southeast Asian super-app embedded health products. Go-to-market execution should leverage cooperative aggregator relationships in Ethiopia and Kenya's Rift Valley agricultural corridors. For Investors and Strategic Acquirers: Re-rating potential sits with technology-integrated carriers possessing captive parametric modeling teams given accelerating climate volatility and continuous algorithm recalibration demands. Long-term viability favors entities with demonstrated product-market fit in subscription-based mobile airtime-linked premium collection. Watch interoperability progress between national identity systems and insurer databases as the critical inflection indicator for automated KYC scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Platform Development | Allianz's agricultural index products demonstrate algorithmic underwriting viability in drought-prone regions. |
| Mobile Network Operator Partnership | MicroEnsure's East African MNO collaborations establish embedded premium collection infrastructure with reduced lapse rates. |
| Regulatory Sandbox Engagement | IRDAI's framework enables iterative outpatient telemedicine and livestock cover pilots without full filing requirements. |
| Blockchain Smart Contract Deployment | Ethiopian cooperatives adopting automated payout execution collapse administrative costs for sub-dollar wage earners. |
| Cooperative Aggregator Alliance | Ghana's member-owned mutual structures exploit lower capital requirements than commercial microinsurance licenses. |
Research Approach
Document review covered IRDAI regulatory filings, satellite data provider technical specifications, and mobile network operator partnership disclosures, complemented by interviews with microinsurance product managers, actuarial risk officers, cooperative aggregator leaders, and reinsurance capacity specialists. Secondary validation drew from National Insurance Commission Ghana guidelines, Ethiopian Insurance Corporation public reports, and Kenya's Insurance Regulatory Authority consumer-protection standards. Bottom-up policy issuance modeling triangulated against top-down premium pool estimates across health, agricultural, and life product lines.
Segmentation outputs reflect product type, delivery model, target population, and premium structure dimensions modeled across the projection horizon. CAGRs derived from historical licensed entity entry rates, smartphone penetration trajectories, and smallholder cooperative aggregation patterns. Forecast inputs incorporated parametric payout frequency data and mobile wallet transaction velocity indices.
Several conditions sit outside the modeled scope, including extreme weather event frequency beyond current climate model baselines and regulatory reversals in sandbox framework continuity. Forecasts reflect assumptions regarding interoperability standard adoption and cooperative capital requirement stability. A small set of named triggers warrants ongoing watch: national ID system integration velocity, satellite data provider consolidation, and IRDAI expense ratio ceiling adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
US Property and Casualty (P&C) Insurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
Denmark Property and Casualty Insurance Market
Insurance
Djibouti Insurance Market
Insurance
Germany Electronic Gadgets Insurance Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
France Car Insurance Market
Insurance
B2B2C Insurance Market
Insurance
Insurance Claims Services Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
Aviation Insurance Market
Insurance
Cannabis Crop Insurance Market
Insurance
Switzerland Reinsurance Market
Insurance
Digital Transformation in Insurance Market
Insurance
Global Cargo Transportation Insurance Market
Insurance
Europe Road Assistance Insurance Market