
 Cash Flow Market | 2026-2036
Cash Flow Market Size, Share, and Industry Trends Forecast 2026-2036
Cash Flow Market Intelligence
Mid-market energy conglomerates is bifurcating demand away from legacy manufacturing buyers in the cash flow solutions space. Occidental Petroleum Corp leverages proprietary treasury infrastructure to sustain working capital visibility across volatile commodity cycles. Marathon Petroleum Corp anchors its financial planning through integrated direct-method reporting systems that dominate downstream refining operations. Valero Energy Corp differentiates via real-time margin analytics that extend across renewable fuel transition portfolios.
Cash flow denotes the net movement of monetary resources into and out of an enterprise during a defined accounting period, measured through operating, investing, and financing activities that reveal liquidity position and solvency capacity. Operating cash flow captures core business generation capability, while free cash flow represents discretionary funds available after capital maintenance, a metric that investment firms increasingly demand for enterprise valuation. Corporate finance teams and investment firms represent the fastest-growing end user categories, as both seek automated ratio analysis and forecasting models that reduce reconciliation latency. Small businesses occupy a mature, price-sensitive tier where indirect-method templates still prevail due to lower implementation thresholds.
The SEC mandates quarterly liquidity disclosures that shape how public issuers structure cash flow statements and select analysis software. FERC reporting requirements for energy market participants further tighten working capital transparency standards, while ISO frameworks on financial risk management influence how treasury platforms certify data integrity. Stakeholders must monitor whether regulatory bodies expand direct-method reporting mandates, as this would force wholesale replacement of indirect-method systems and reshape vendor competitive dynamics.
Market Dynamics
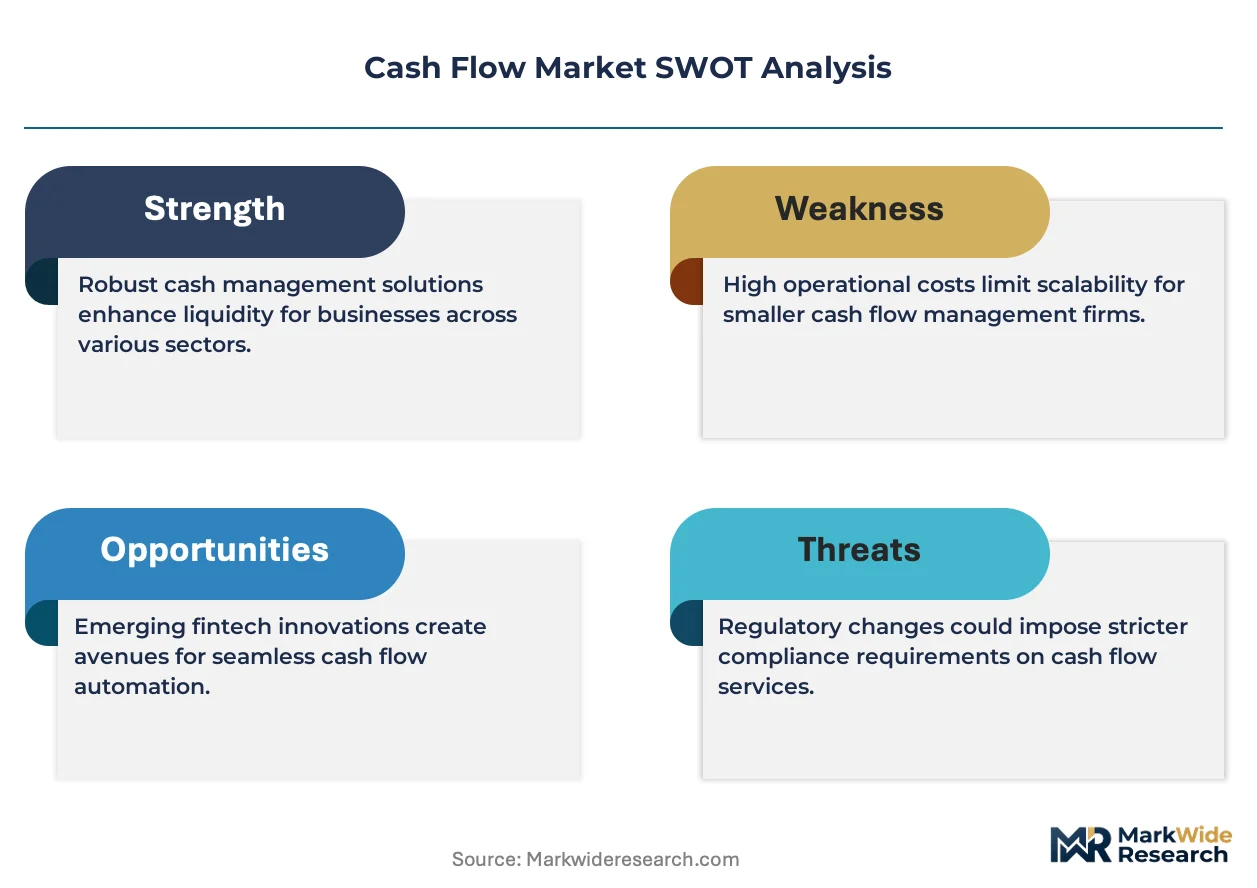
API-first treasury architectures are decomposing legacy spreadsheet workflows across corporate finance teams, forcing incumbent vendors to re-platform or lose mid-market accounts to cloud-native competitors.
Growth Catalysts
- SEC liquidity disclosure mandates:Quarterly reporting requirements for public issuers accelerate software procurement cycles as compliance deadlines tighten.
- Energy sector volatility:Commodity price swings drive working capital visibility investments among downstream refiners and integrated oil majors.
- Cloud-based delivery models:SaaS deployment reduces implementation thresholds for mid-market finance teams previously locked out of enterprise-grade forecasting tools.
Market Restraints
- Data integration complexity:ERP fragmentation across acquired subsidiaries creates reconciliation latency that undermines real-time forecasting accuracy.
- Specialized talent scarcity:Shortage of professionals combining treasury operations expertise with API architecture knowledge limits platform adoption velocity.
- Indirect-method system lock-in:Legacy accounting infrastructure investments create switching costs that delay direct-method reporting transitions.
Strategic Opportunities
- Renewable fuel transition analytics:Margin forecasting tools for biofuel and carbon credit portfolios address unmet demand in European energy markets.
- Small business API penetration:Embedded cash flow modules within neobank platforms unlock price-sensitive segments currently using manual templates.
- FERC reporting automation:Regulatory tailwinds from enhanced working capital transparency standards create vendor replacement windows among regulated utilities.
Industry Challenges
- Multi-ERP harmonization:Finance teams struggle to normalize cash position data across SAP, Oracle, and Workday instances following M&A activity.
- ISO 27001 certification timelines:Data security audit requirements extend sales cycles for vendors targeting investment firm end users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cash Flow Market |
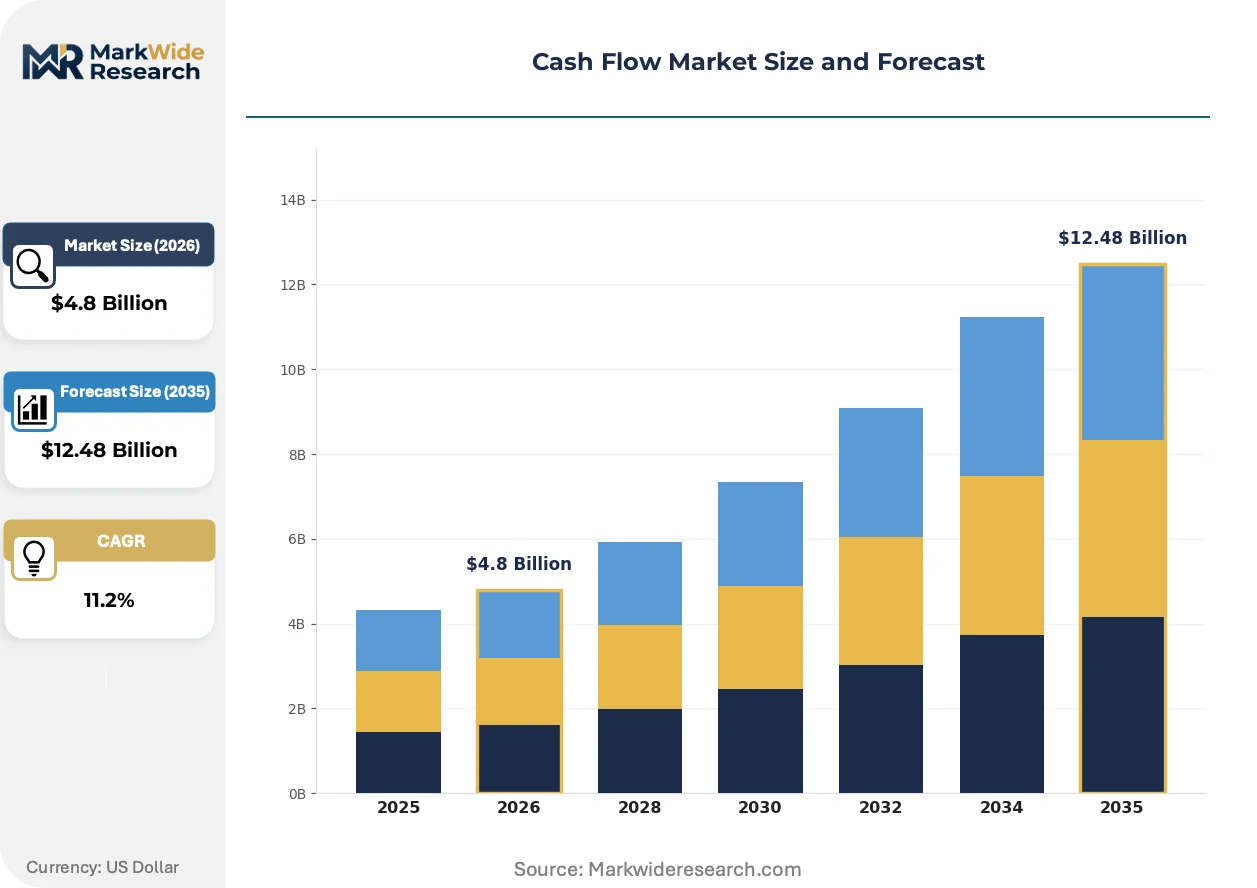
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cash Flow Type: Operating Cash Flow, Investing Cash Flow, Financing Cash Flow, Free Cash Flow Industry Sector: Manufacturing, Technology, Telecommunications, Hospitality, Real Estate, Energy End User: Corporate Finance Teams, Small Businesses, Financial Advisors, Investment Firms, Nonprofit Organizations Analysis Method: Direct Method, Indirect Method, Ratio Analysis, Trend Analysis, Forecasting Models |
| Companies Covered | Occidental Petroleum Corp, Marathon Petroleum Corp, Moderna Inc, Valero Energy Corp, Nucor Corp, Dow Inc, LyondellBasell Industries NV, HP Inc, CF Industries Holdings Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cash Flow Market Strategic Shifts & Innovations
Machine learning inference engines are rewriting how treasury platforms generate scenario-based forecasts, compressing the gap between static reporting and predictive liquidity management.
Embedded AI forecasting modules are decomposing traditional batch-process reporting cycles into continuous cash position monitoring. Mid-market energy conglomerates deploy these tools to stress-test working capital against commodity price shocks. The structural consequence is collapsing the latency between transaction capture and liquidity visibility from days to minutes.
CSRD sustainability reporting requirements in Europe mandate granular cash flow attribution to environmental transition activities. This forces platform vendors to build carbon-adjusted liquidity metrics alongside traditional financial statements. Asset managers and corporate issuers in Germany and France face the steepest compliance curves as 2026 disclosure deadlines approach.
Subscription-based pricing for treasury software is displacing perpetual license models among North American manufacturing buyers. Finance leaders prefer OpEx treatment for forecasting tools amid uncertain capital allocation priorities. This shift concentrates vendor revenue in recurring streams while reducing upfront implementation friction for multi-entity deployments.
Cash Flow Market Segmentation
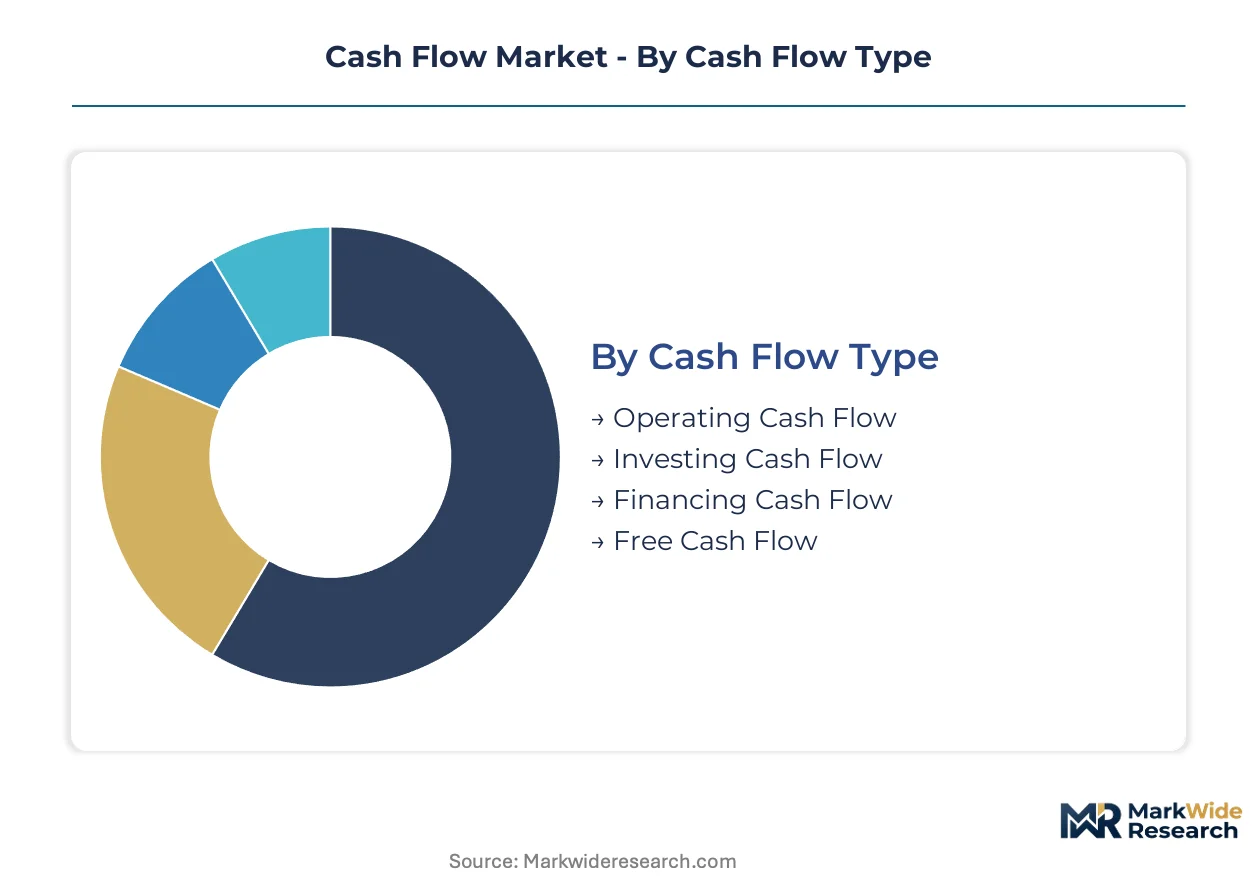
Cash flow solutions serve heterogeneous buyer needs across treasury sophistication levels. Segmentation reveals how deployment models, analytical depth, and regulatory scope fragment addressable demand into distinct commercial tiers.
Cash Flow Type:
Channel mix bifurcates between real-time operational monitoring tools and episodic strategic planning platforms, with API-native vendors capturing the former and legacy suites defending the latter.
- Operating Cash Flow:Captures core business liquidity generation from revenue collection and expense disbursement. Energy sector buyers in Texas and Louisiana concentrate demand here as FERC reporting requirements mandate granular working capital visibility across volatile commodity cycles.
- Free Cash Flow:Represents discretionary funds remaining after capital maintenance obligations. Investment firms in New York and Boston drive procurement of automated free cash flow forecasting modules to compress enterprise valuation reconciliation cycles.
- Investing Cash Flow:Tracks capital deployment across asset acquisitions and divestitures. Manufacturing conglomerates use these tools to normalize cash position data following M&A-driven ERP fragmentation.
- Financing Cash Flow:Monitors debt, equity, and dividend movements affecting capital structure. Corporate treasury departments deploy these solutions to stress-test covenant compliance against interest rate volatility.
Operating Cash Flow dominates installed base. Free Cash Flow is where expansion concentrates.
Industry Sector:
Cost tier stratification separates premium predictive analytics buyers from template-dependent price-sensitive adopters.
- Energy:Downstream refiners and integrated oil majors require real-time margin analytics spanning renewable fuel transition portfolios. SEC liquidity disclosure mandates accelerate software procurement cycles among publicly traded issuers in this vertical.
- Manufacturing:Mid-market conglomerates deploy indirect-method systems due to lower implementation thresholds, though cloud-based delivery models now unlock access to enterprise-grade forecasting tools previously reserved for larger competitors.
- Technology:SaaS-native finance teams favor API-first architectures that decompose legacy spreadsheet workflows into continuous cash position monitoring.
- Telecommunications:Regulated utilities prioritize FERC reporting automation to satisfy enhanced working capital transparency standards.
- Hospitality:Seasonal revenue volatility drives demand for scenario-based forecasting engines that stress-test liquidity against occupancy fluctuations.
- Real Estate:Asset managers require carbon-adjusted liquidity metrics to satisfy CSRD sustainability reporting requirements in European markets.
Energy commands premium pricing tiers. Technology is expanding most quickly.
End User:
Application depth varies from automated ratio analysis for sophisticated institutional buyers to manual template workflows for resource-constrained operators.
- Corporate Finance Teams:Mid-market energy conglomerates anchor demand for integrated direct-method reporting systems that dominate downstream refining operations.
- Investment Firms:Asset managers and corporate issuers in Germany and France face steep compliance curves as CSRD disclosure deadlines approach, forcing platform migrations.
- Small Businesses:Price-sensitive tier where neobank-embedded cash flow modules unlock segments currently using spreadsheet templates.
- Financial Advisors:Independent practitioners require lightweight forecasting tools with rapid implementation cycles.
- Nonprofit Organizations:Grant-dependent entities prioritize donor-restricted fund tracking within restricted net asset frameworks.
Corporate Finance Teams dominate installed base. Investment Firms are climbing the fastest.
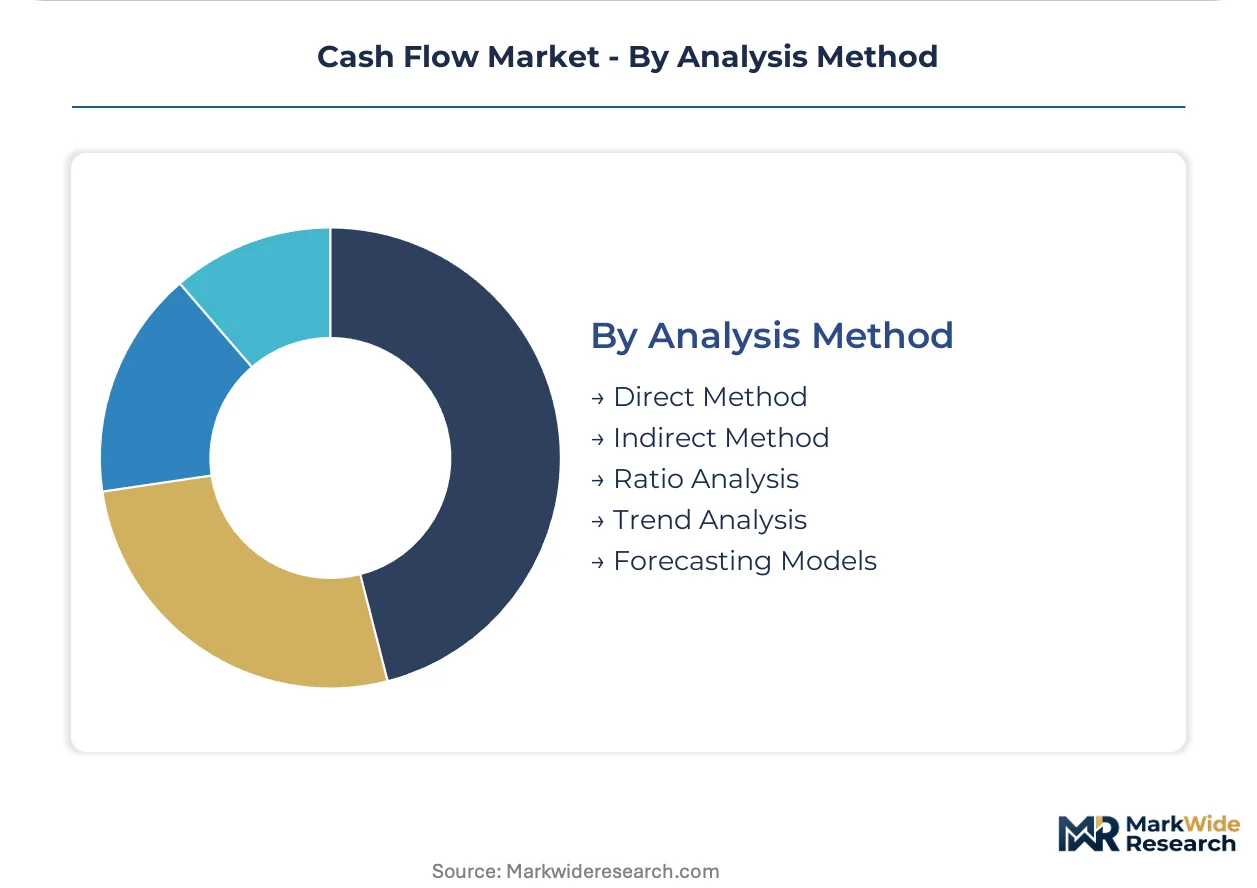
Analysis Method:
Customer type stratification separates compliance-driven direct-method adopters from efficiency-seeking indirect-method incumbents.
- Direct Method:Reports actual cash receipts and payments without accrual reconciliation. SEC regulatory pressure on liquidity disclosures accelerates migration from indirect-method legacy systems among public issuers.
- Forecasting Models:Machine learning inference engines compress the gap between static reporting and predictive liquidity management. Mid-market energy buyers deploy these to stress-test working capital against commodity price shocks.
- Indirect Method:Reconciles net income to operating cash flow through working capital adjustments. Legacy accounting infrastructure investments create switching costs that delay transitions despite regulatory tailwinds.
- Ratio Analysis:Automated liquidity and solvency metrics reduce reconciliation latency for investment firm end users.
- Trend Analysis:Historical pattern recognition tools serve small business segments with limited forecasting sophistication.
Indirect Method dominates installed base. Forecasting Models are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel pipeline network anchors North American energy liquidity infrastructure, enabling real-time cash position monitoring across volatile commodity cycles. This physical backbone shapes how treasury software vendors configure working capital platforms for downstream refiners and integrated oil majors operating across the continent.
United States
SEC quarterly liquidity disclosure mandates accelerate software procurement cycles among publicly traded issuers in Texas and Louisiana. FERC reporting requirements for energy market participants tighten working capital transparency standards. Houston-based downstream refiners deploy API-first treasury architectures to sustain margin visibility across renewable fuel transition portfolios.
Germany
CSRD sustainability reporting requirements mandate granular cash flow attribution to environmental transition activities. The country's national financial regulator enforces disclosure deadlines that reshape platform vendor selection criteria. Frankfurt asset managers and corporate issuers face steep compliance curves as carbon-adjusted liquidity metrics become mandatory.
United Kingdom
London investment firms drive procurement of automated free cash flow forecasting modules to compress enterprise valuation reconciliation cycles. The Financial Conduct Authority's transparency standards influence how treasury platforms certify data integrity. The City of London's fintech cluster incubates embedded cash flow modules within neobank platforms targeting price-sensitive small business segments.
China
Dual carbon goals accelerate demand for carbon-adjusted liquidity metrics among state-owned energy conglomerates. The Ministry of Ecology and Environment enforces environmental disclosure standards that reshape cash flow statement structures. Yangtze River Delta manufacturing hubs deploy cloud-based delivery models to unlock enterprise-grade forecasting tools for mid-market finance teams.
India
SEBI's corporate governance mandates tighten liquidity disclosure requirements for listed energy and manufacturing entities. The central bank's digital payment infrastructure enables real-time transaction capture for treasury platforms. Mumbai and Gujarat industrial corridors attract cloud-native vendors displacing legacy spreadsheet workflows across corporate finance teams.
Cash Flow Market Key Industry Players
Concentration sits with integrated energy conglomerates operating proprietary treasury infrastructure. The market structure fragments between legacy spreadsheet-dependent mid-market manufacturers and cloud-native API-first platforms capturing energy sector accounts. Two strategic archetypes dominate: vertically integrated oil majors with captive cash flow systems, and specialized fintech vendors offering embedded forecasting modules. Competitive moves center on regulatory compliance automation and M&A-driven ERP harmonization capabilities.
Within the energy-major archetype, Occidental Petroleum Corp, Marathon Petroleum Corp, and Valero Energy Corp represent distinct treasury infrastructure models. Occidental anchors working capital visibility through proprietary systems spanning volatile commodity cycles. Marathon exemplifies integrated direct-method reporting dominance in downstream refining operations. Valero occupies a position defined by real-time margin analytics extending across renewable fuel transition portfolios. These three entities sit within a tier where regulatory pressure from the SEC on liquidity disclosures accelerates internal platform investment cycles.
| Leading Market Players |
|---|
| Occidental Petroleum Corp |
| Marathon Petroleum Corp |
| Moderna Inc |
| Valero Energy Corp |
| Nucor Corp |
| Dow Inc |
| LyondellBasell Industries NV |
| HP Inc |
| CF Industries Holdings Inc |
| Others |
Cost & Logistics Intelligence
API-first platform scale economies concentrate vendor margins among cloud-native providers serving mid-market energy conglomerates, while spreadsheet-dependent incumbents face compression from SaaS pricing models that reset price floors across corporate finance tiers.
Pricing Analysis
Volume-discount tiering structures separate enterprise deployments above five hundred seats from mid-market subscriptions and small business embedded modules. Subscription-based pricing dominates North American manufacturing buyers seeking OpEx treatment, while price differentiation rests on API integration depth and ISO 27001 certification status. Pricing pressure stems from neobank-embedded alternatives commoditizing basic forecasting tiers. Small businesses exhibit highest price sensitivity; investment firms show lowest.
Supply Chain Analysis
The United States anchors cloud infrastructure provisioning for treasury platforms, while Ireland and Singapore host data residency centers serving European and Asia-Pacific compliance requirements. Software development draws from distributed engineering hubs across Poland, India, and Vietnam. Single-source vulnerability concentrates in hyperscaler compute dependencies. Distribution runs through direct enterprise sales teams for large accounts and neobank API partnerships for small business penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cash flow solutions sit in early-cycle expansion as SEC liquidity disclosure mandates force wholesale platform replacements among public issuers previously locked into indirect-method legacy systems.
For Market Incumbents: Consolidate API architecture roadmaps to defend against cloud-native entrants capturing mid-market energy accounts. Prioritize ISO 27001 certification investments to compress sales cycles among investment firm buyers. Acquire specialized ERP harmonization capabilities to address multi-instance reconciliation pain points following M&A-driven fragmentation.
For New Entrants and Emerging Players: Anchor in renewable fuel transition analytics for European energy markets where CSRD carbon-adjusted liquidity metrics create vendor replacement windows. Target price-sensitive small business segments through neobank embedded distribution. Pursue FERC reporting automation as the primary go-to-market wedge among regulated utilities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors API-native platforms with proven ERP integration layers over legacy suite vendors facing re-platforming costs. Long-term viability hinges on regulatory compliance automation depth. Acquisition targets should demonstrate direct-method reporting capabilities and machine learning forecasting modules. Watch for SEC expansion of direct-method mandates as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Migration | Decomposes spreadsheet workflows for Marathon Petroleum-style integrated reporting dominance. |
| CSRD Compliance Module Development | Captures Frankfurt and Paris asset manager procurement cycles ahead of disclosure deadlines. |
| ERP Harmonization Capability Acquisition | Addresses SAP-Oracle-Workday fragmentation pain points in post-merger treasury environments. |
| Neobank Embedded Partnership | Unlocks small business segments currently manual-template dependent. |
| Machine Learning Forecasting Investment | Compresses latency from transaction capture to liquidity visibility for commodity volatility stress-testing. |
Research Approach
Operator-level perspectives from corporate treasury directors, ERP implementation specialists, API integration architects, and investment firm portfolio analytics heads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC EDGAR filings, FERC compliance disclosures, ISO certification registries, and cloud vendor marketplace data. Bottom-up deployment counts triangulated against top-down software spend estimates across the analysis window.
Sensitivity analysis tested forecast robustness across varying regulatory enforcement timelines and cloud adoption curves. Segmentation dimensions modeled include cash flow type, industry vertical, end user sophistication, analysis method, and regional regulatory framework. CAGRs derived from historical deployment trajectories and penetration rate assumptions. Key inputs encompassed API adoption velocity among mid-market energy buyers and CSRD compliance deadline proximity effects.
Decision-makers should treat outputs as directional under sustained SEC enforcement intensity and stable hyperscaler pricing; material deviation would warrant model refresh. Forecasts incorporate assumptions regarding indirect-method system replacement rates and small business neobank penetration curves. Recalibration cycles align with material shifts in liquidity disclosure mandates or API standardization breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Online Lottery Market
Financial Services
Global Product Cost Management Market
Financial Services
Global Financial Consulting Software Market
Financial Services
Global Treasury Software Market
Financial Services
Hyperinflation System Market
Financial Services
Benefits Consulting Service Market
Financial Services
United States Payroll Services Market
Financial Services
Reverse Factoring Market
Financial Services
Germany Factoring Services Market
Financial Services
Banknote Counters Market
Financial Services
Europe E-Invoicing Market
Financial Services
Smart Finance Services Market
Financial Services
E-Brokerage Market
Financial Services
Africa Lottery Market
Financial Services
Global Medical Equipment Financing Market
Financial Services
Financial Services Application Market