
 Denmark Property and Casualty Insurance Market | 2026-2036
Denmark Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Property and Casualty Insurance Market Outlook
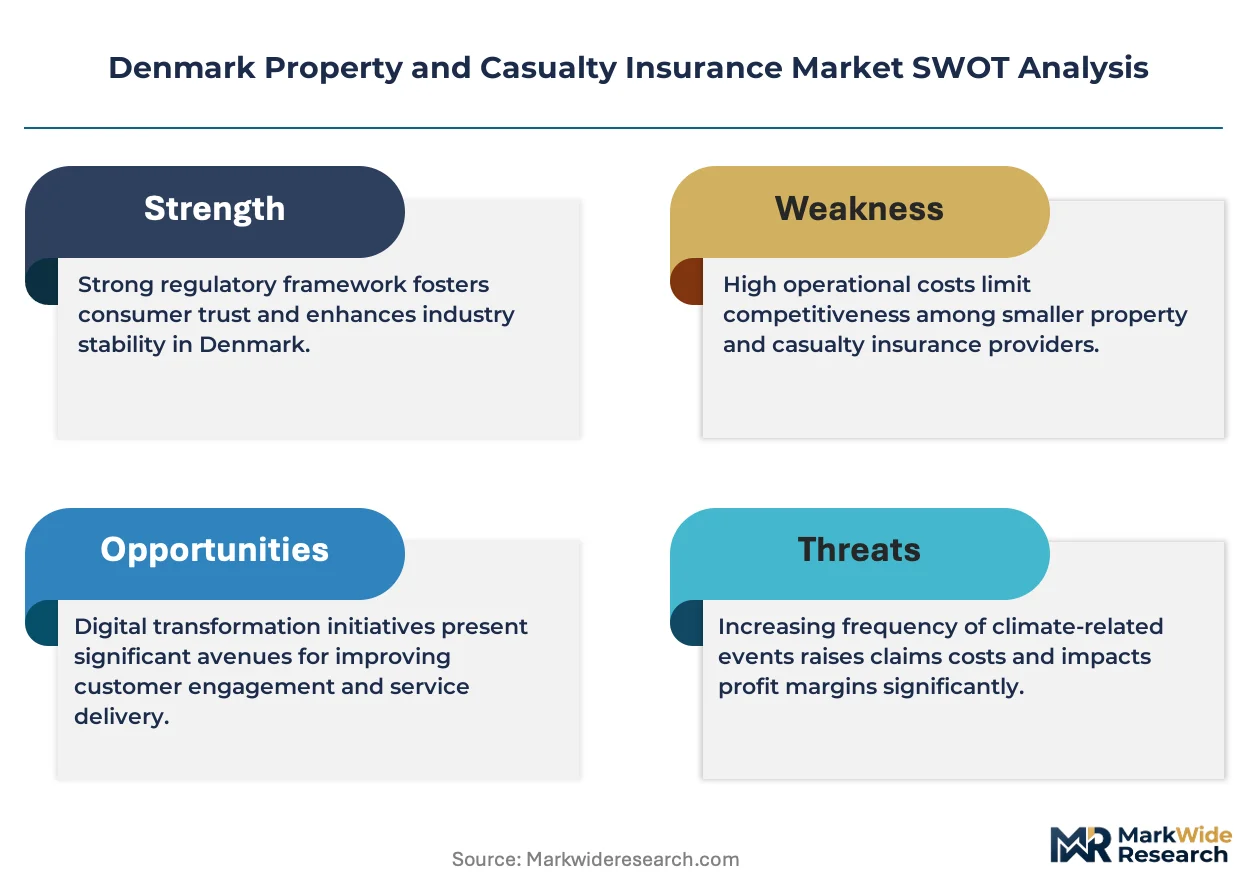
EU Green Deal compliance is pivoting the cost-of-entry calculus for Danish property underwriters. Tryg Forsikring leverages its coastal risk modeling infrastructure to dominate flood-exposed commercial portfolios. Topdanmark Forsikring anchors its competitive position through granular agricultural hail data spanning Jutland. Codan Forsikring differentiates via integrated cyber-liability modules bundled with traditional commercial property coverage.
Property and casualty insurance constitutes a risk-transfer mechanism where insurers pool premiums to indemnify policyholders against specified property damage, liability claims, and business interruption events, with Danish contracts typically incorporating index-linked climate riders and mandatory fire-safety inspections. The product type dimension shows homeowners insurance commanding the largest premium pool while liability insurance captures widening margin pools from director and officer exposure. Auto insurance retains structural maturity with telematics-based usage pricing displacing traditional actuarial tables among individual end users.
Finanstilsynet enforces Solvency II-aligned capital requirements that constrain leverage ratios for Danish carriers, while the Danish Financial Supervisory Authority mandates climate scenario stress testing across property portfolios. The EU AI Act will soon govern automated claims adjudication systems deployed by Copenhagen-based underwriters. Stakeholders must monitor whether Finanstilsynet extends sustainability disclosure obligations to captive insurers operating from Denmark's regulatory perimeter.
Market Dynamics
EU Green Deal compliance is compressing underwriting margins while forcing Danish carriers to rebuild risk models around building energy performance certificates and flood exposure mapping.
Growth Catalysts
- EU Green Deal retrofit mandates:Commercial property owners in Copenhagen must upgrade energy ratings by 2030, generating demand for construction all-risk and performance guarantee coverage.
- Telematics penetration:Usage-based auto insurance is capturing younger driver segments through smartphone-integrated mileage tracking and behavior scoring.
- Jutland agricultural expansion:Large-scale farming cooperatives are consolidating hail and drought coverage into multi-peril crop policies with satellite-triggered indemnity clauses.
Market Restraints
- Solvency II capital charges:Finanstilsynet's risk-based capital requirements consume 25-35% of gross written premium for catastrophe-exposed property lines.
- Reinsurance capacity concentration:Danish primary carriers depend on Munich and London market capacity for North Sea flood layers, creating renewal volatility.
- Legacy IT substitution threat:Cloud-native insurtech platforms threaten traditional policy administration systems with API-first distribution and real-time pricing.
Strategic Opportunities
- Odense-Taulov logistics corridor:Warehouse and cold storage construction is outpacing insurance capacity, opening specialty commercial property niches.
- EU AI Act compliance services:Automated claims adjudication tools require governance frameworks, creating advisory revenue streams alongside core underwriting.
- Cyber-physical convergence:Bundled policies covering both property damage and operational technology breaches are penetrating manufacturing and energy verticals.
Industry Challenges
- Climate modeler talent scarcity:Catastrophe risk teams lack sufficient geospatial data scientists to validate flood and storm surge exposure at postal-code granularity.
- Core system integration friction:Legacy AS400 policy administration platforms resist API connectivity with telematics data streams and IoT sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Property and Casualty Insurance Market |
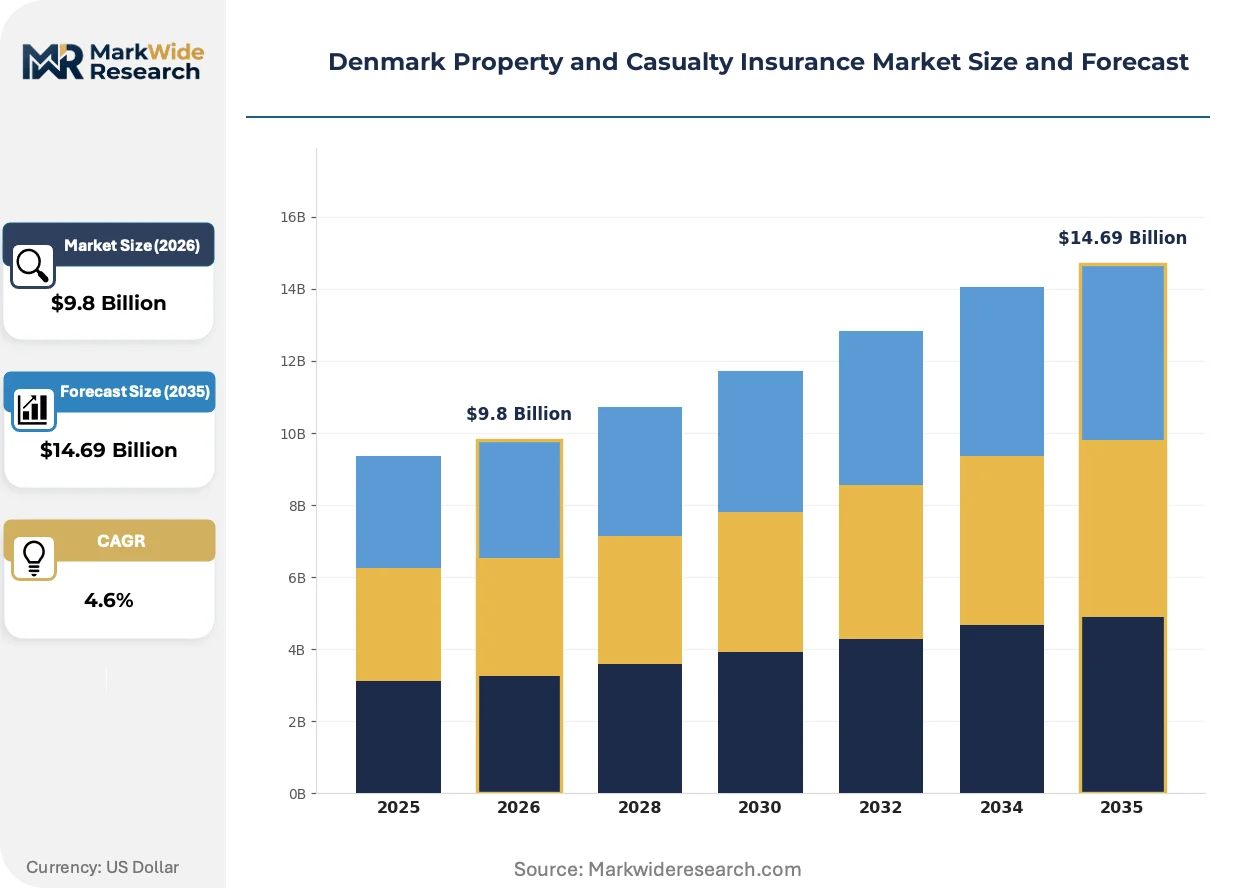
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auto Insurance, Homeowners Insurance, Liability Insurance, Workers' Compensation End User: Individuals, Small Businesses, Corporations, Non-Profit Organizations Distribution Channel: Online, Agents, Brokers, Direct Sales Coverage Type: Comprehensive, Third-Party, Collision, Personal Injury Protection |
| Companies Covered | Tryg Forsikring, Topdanmark Forsikring, Alm.Brand, Codan Forsikring, Gjensidige Forsikring, IF Insurance, LB Forsikring, GF Forsikring, Protector Forsikring, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Property and Casualty Insurance Market Strategic Shifts
Danish property and casualty carriers are rebuilding operational infrastructure around real-time data ingestion, regulatory automation, and usage-based product design. Three forces dominate this transition.
Parametric insurance structures are consolidating traditional indemnity products in climate-exposed commercial lines. Danish carriers now offer predefined payout triggers based on wind speed thresholds or rainfall indices rather than assessed damage. Agricultural and renewable energy buyers in western Jutland are adopting these instruments fastest, compressing claims settlement cycles from months to days while reducing loss adjustment expense ratios.
Finanstilsynet's climate scenario stress testing mandates are forcing portfolio rebalancing across Danish underwriters. The regulator requires forward-looking 10-year catastrophe loss projections under warming scenarios, driving divestment from coastal commercial property concentrations. Copenhagen-based carriers are responding by ceding more flood risk to reinsurance markets and redirecting capacity toward inland industrial risks.
Embedded distribution partnerships are displacing traditional broker channels in personal lines. Danish auto manufacturers and utility providers now bundle insurance at point of sale through API integrations. Tryg and Topdanmark have secured exclusive partnerships with electric vehicle leasing platforms, capturing policyholder relationships before traditional agents intervene. This shift is most visible in Zealand's urban corridors where digital-native consumers dominate new vehicle acquisitions.
Denmark Property and Casualty Insurance Market Segmentation
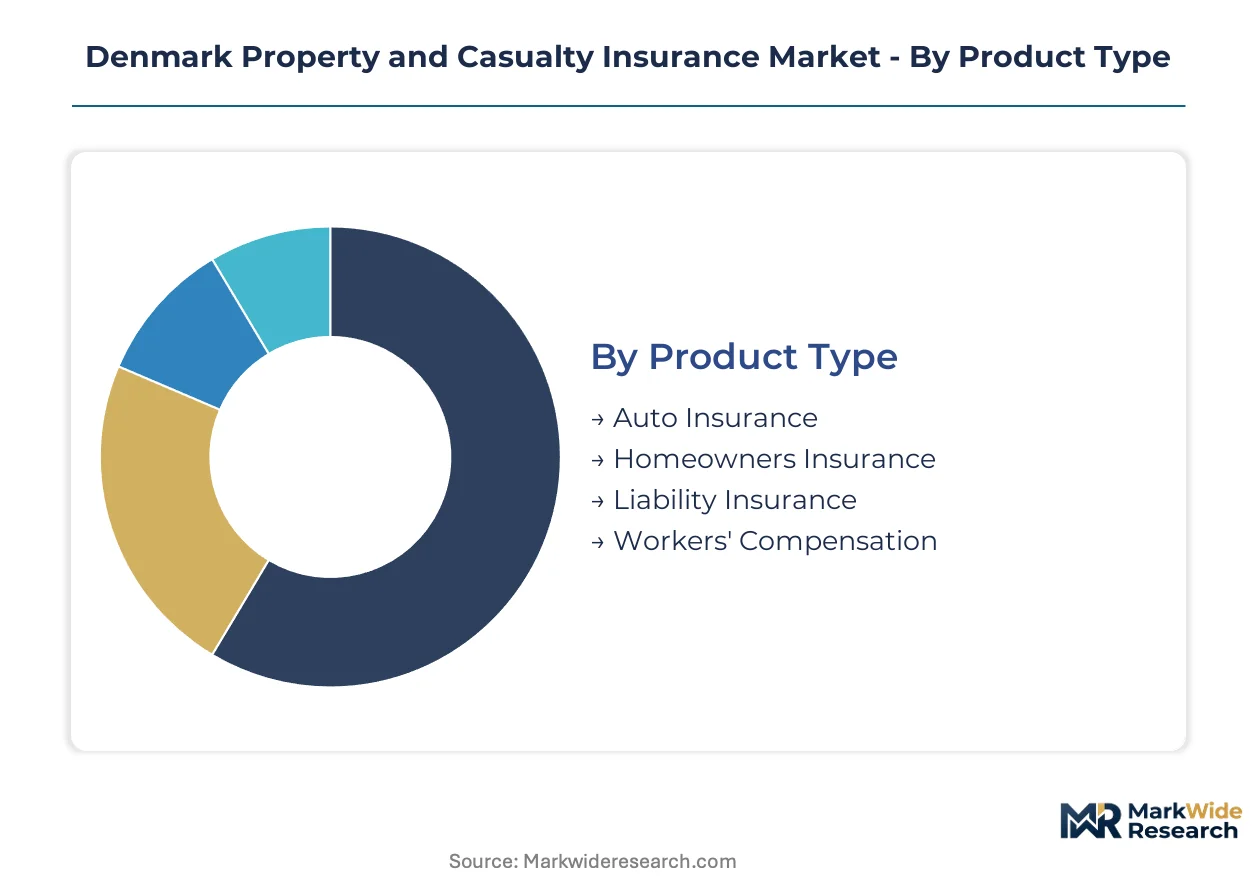
Segmentation in Denmark's property and casualty market reveals how carriers allocate capital across risk pools with divergent margin profiles. Each dimension exposes distinct underwriting pressures from Solvency II capital charges and EU Green Deal retrofit mandates.
Product Type:
Homeowners insurance commands the largest absolute premium volume while liability lines capture widening margin expansion from director and officer exposure.
- Homeowners Insurance:Dwelling coverage bundled with content protection and index-linked climate riders. Demand concentrates in Copenhagen's urban core where flood-exposed properties now dominate renewal negotiations with Tryg Forsikring.
- Auto Insurance:Structural maturity persists despite telematics-based usage pricing displacing traditional actuarial tables. Younger driver segments in Zealand's urban corridors adopt smartphone-integrated mileage tracking fastest.
- Liability Insurance:Director and officer coverage plus professional indemnity lines. Commercial buyers in Odense-Taulov logistics corridor seek bundled cyber-physical protection.
- Workers' Compensation:Mandatory employer coverage with occupational injury provisions. Large-scale farming cooperatives in Jutland consolidate policies under multi-peril agricultural frameworks.
Today's leader: Homeowners Insurance. Tomorrow's challenger: Liability Insurance.
End User:
Corporate accounts generate the highest premium per policyholder while individual segments drive volume through embedded distribution partnerships.
- Corporations:Multi-line commercial portfolios with integrated cyber-liability modules. Renewable energy and manufacturing verticals in western Jutland adopt parametric structures with predefined payout triggers.
- Small Businesses:Construction all-risk and performance guarantee coverage tied to EU Green Deal retrofit mandates. Copenhagen commercial property owners upgrading energy ratings by 2030 fuel demand.
- Individuals:Personal auto and homeowners lines distributed through API-integrated point-of-sale partnerships. Electric vehicle leasing platforms in Zealand capture policyholder relationships before traditional agents intervene.
- Non-Profit Organizations:Specialized liability and property coverage with governance-focused risk assessments. Community housing associations seek climate resilience riders for coastal exposures.
Corporate accounts anchor current profitability. Small Businesses are gaining share fastest as retrofit mandates accelerate.
Distribution Channel:
Cost-to-acquire varies dramatically across channels, with digital platforms compressing expense ratios below traditional broker networks.
- Online:Direct-to-consumer platforms with real-time pricing engines. Cloud-native insurtech competitors threaten legacy policy administration systems through API-first distribution.
- Agents:Tied representatives with exclusive carrier contracts. Established relationships persist in rural Jutland where agricultural hail coverage requires local expertise.
- Brokers:Independent intermediaries accessing multiple carrier panels. Dependence on Munich and London reinsurance markets creates renewal volatility for catastrophe-exposed placements.
- Direct Sales:Carrier-employed field forces targeting mid-market commercial accounts. Cold storage and warehouse construction in the logistics corridor outpaces available underwriting capacity.
Broker networks dominate commercial placements today. Online channels show the steepest expansion trajectory as Finanstilsynet's climate disclosure requirements favor transparent digital workflows.
Coverage Type:
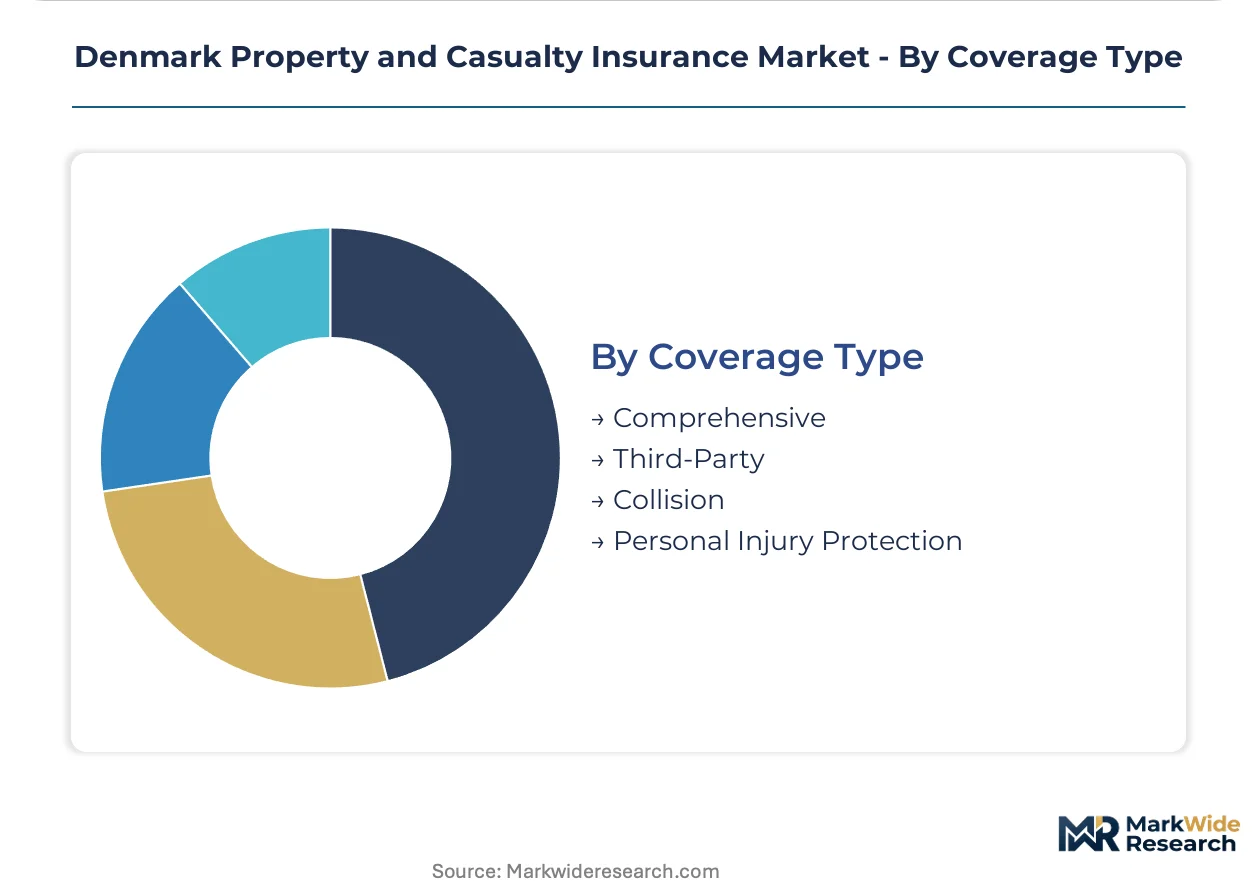
Comprehensive structures absorb the broadest risk transfer while third-party minimums face regulatory pressure on adequacy.
- Comprehensive:All-risk protection spanning property damage, theft, and natural perils. Danish contracts incorporate mandatory fire-safety inspections and postal-code-level flood exposure mapping.
- Third-Party:Minimum legal coverage for liability and auto lines. Finanstilsynet's risk-based capital requirements consume disproportionate solvency margin for catastrophe-exposed layers.
- Collision:Physical damage to insured vehicles with telematics-modified deductibles. Usage-based pricing penetration climbs among digital-native consumers.
- Personal Injury Protection:Medical and income replacement benefits regardless of fault. Integration with Denmark's universal healthcare system creates unique coordination challenges.
Comprehensive coverage holds the premium base. Collision lines are climbing fastest as vehicle technology complexity drives repair cost inflation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Danish property and casualty insurance industry traces its modern lineage to the cooperative mutual movements of Jutland in the late 19th century, when agricultural communities pooled risk against fire and hail losses. Copenhagen's emergence as a regional underwriting hub in the 20th century concentrated actuarial expertise and regulatory capacity in the capital region.
Capital Region
Copenhagen anchors premium generation through commercial real estate concentration and corporate headquarters density. Finanstilsynet's climate scenario stress testing mandates drive portfolio rebalancing among carriers headquartered in the metro. The Ørestad development corridor generates construction all-risk demand as EU Green Deal retrofit deadlines approach.
Central Denmark Region
Aarhus and the surrounding logistics network fuel inland industrial property coverage growth. The Port of Aarhus expansion triggers demand for cargo and warehouse protection. Regional farming cooperatives consolidate hail and drought policies under multi-peril frameworks with satellite-triggered indemnity clauses.
North Jutland
Aalborg's renewable energy cluster drives specialized coverage for wind turbine construction and operational risks. Offshore wind installations in the Kattegat require bespoke marine and property bundled structures. Agricultural hail exposure dominates personal lines penetration in rural postal codes.
Southern Denmark
The Odense-Taulov logistics corridor outpaces available underwriting capacity for cold storage and distribution facilities. Danish carriers cede catastrophe layers to Munich and London markets for flood-exposed commercial portfolios. Regional small businesses seek construction performance guarantees tied to building energy certificate upgrades.
Zealand
Urban corridors around Roskilde and Køge capture embedded auto insurance through electric vehicle leasing platform partnerships. Telematics-based usage pricing penetrates fastest among digital-native consumer segments. Coastal flood exposure concentrates renewal negotiations on climate resilience riders.
Denmark Property and Casualty Insurance Market Competitive Environment
The competitive structure tilts toward mutual and cooperative ownership models with limited listed carrier presence. Danish market concentration rests on three domestic underwriters controlling the majority of gross written premium across personal and commercial lines. Strategic archetypes separate coastal risk specialists, agricultural data aggregators, and integrated cyber-physical bundlers. Competitive moves center on embedded distribution partnerships with auto manufacturers and utility providers, alongside API-first platform investments displacing legacy broker channels.
Among Copenhagen-based underwriters, Tryg Forsikring, Topdanmark Forsikring, and Codan Forsikring occupy the dominant tier. Tryg exemplifies the coastal risk specialist archetype through flood-exposed commercial portfolio concentration. Topdanmark represents agricultural data integration, anchoring position through Jutland hail coverage granularity. Codan sits within the cyber-physical convergence segment, bundling operational technology protection with traditional property structures. These three entities collectively shape regulatory dialogue with Finanstilsynet on Solvency II implementation and climate disclosure frameworks.
| Leading Market Players |
|---|
| Tryg Forsikring |
| Topdanmark Forsikring |
| Alm.Brand |
| Codan Forsikring |
| Gjensidige Forsikring |
| IF Insurance |
| LB Forsikring |
| GF Forsikring |
| Protector Forsikring |
| Others |
Value Chain & Pricing Dynamics
Copenhagen commercial property developers concentrate buying power through portfolio-scale negotiations, anchoring contract-based long-term pricing structures that index premiums to EU Green Deal compliance milestones and flood exposure mapping granularity.
Pricing Analysis
Risk-based pricing stratification across premium, standard, and economy tiers dominates Danish property and casualty contracts, with differentiation driven by Solvency II capital charge intensity and climate scenario stress test outcomes. Cost compression in catastrophe-exposed commercial lines intensifies as reinsurance capacity concentrates in Munich and London markets. Small businesses in the Odense-Taulov corridor exhibit highest price sensitivity, while corporate multi-line accounts absorb premium increases for integrated cyber-physical bundling.
Supply Chain Analysis
Claims refurbishment and salvage recovery flows remain underdeveloped in Danish property insurance, creating reverse-logistics gaps that elevate loss adjustment expense ratios. Underwriting capacity draws from domestic mutual carriers, Nordic reinsurance pools, and London market syndicates. Raw material dependencies center on geospatial data services, climate modeling software, and telematics hardware. Single-source vulnerability concentrates in Munich Re and Swiss Re for North Sea flood layers. Distribution runs through embedded API partnerships with auto manufacturers and utility providers alongside traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denmark's property and casualty market functions as a regulatory-arbitrage play where EU Green Deal compliance costs in Copenhagen outpace inland Jutland, creating geographic dispersion incentives for carrier capital allocation.
For Market Incumbents: Hedge coastal concentration risk through parametric reinsurance structures and cede flood layers to London market capacity. Expand inland industrial property underwriting in Central Denmark Region to offset Finanstilsynet climate stress test pressures. Acquire geospatial data science capabilities to address catastrophe modeler talent scarcity. For New Entrants and Emerging Players: Electric vehicle leasing platforms offer embedded distribution partnerships with pre-built policyholder relationships in Zealand's urban corridors. Target Odense-Taulov logistics corridor cold storage capacity gaps with specialty commercial property niches. Pursue API-first distribution to bypass legacy broker channel friction. For Investors and Strategic Acquirers: Nordic banking groups with bancassurance infrastructure are the most active acquirer in this space, seeking captive distribution control. Five-to-ten year viability hinges on climate model validation capabilities and Solvency II capital efficiency. Monitor Finanstilsynet sustainability disclosure extensions to captive insurers as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Predefined payout triggers based on wind speed thresholds compress claims settlement cycles from months to days. |
| Climate Scenario Stress Testing | Finanstilsynet mandates force portfolio rebalancing away from coastal commercial property concentrations. |
| Embedded Distribution Partnerships | API integrations with electric vehicle leasing platforms capture policyholder relationships before traditional agents intervene. |
| Geospatial Data Science Acquisition | Postal-code-level flood exposure validation addresses catastrophe modeler talent scarcity in Copenhagen underwriting teams. |
| Cyber-Physical Coverage Bundling | Integrated operational technology protection penetrates manufacturing and renewable energy verticals in western Jutland. |
Study Parameters
Coverage spans Capital Region, Central Denmark Region, North Jutland, Southern Denmark, and Zealand, with primary inputs from each territory's underwriting executives, reinsurance brokers, Finanstilsynet regulatory affairs officers, and agricultural cooperative risk managers. Secondary validation draws from Finanstilsynet solvency disclosures, EU Green Deal implementation directives, Danish Meteorological Institute climate data, and Lloyd's market renewal reports. Bottom-up premium volume estimates triangulate against top-down macroeconomic exposure assessments.
Rate-of-change decomposition separates volume expansion from pricing effects across the projection horizon, modeling product type, end user, distribution channel, and coverage type dimensions alongside climate risk exposure tiers. CAGRs derive from historical premium trajectory analysis adjusted for regulatory intervention timing and reinsurance market cycle positioning. Forecast inputs incorporate EU AI Act compliance cost curves and telematics penetration adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Finanstilsynet capital requirement recalibrations and Munich Re capacity allocation shifts. Practitioners should monitor EU Green Deal retrofit mandate enforcement intensity and London market flood layer pricing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Insurance BPO Services Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
Commercial Insurance Market
Insurance
Takaful Insurance Market
Insurance
Telecommunication Insurance Market
Insurance
Vietnam Private Health Insurance Market
Insurance
Green Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Digital Insurance Market
Insurance
Business Travel Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
Global SME Insurance Market
Insurance
Asia-Pacific Electronic Gadgets Insurance Market
Insurance
Germany Electronic Gadgets Insurance Market