
 Saudi Arabia Travel Insurance Market | 2026-2036
Saudi Arabia Travel Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Travel Insurance Market Analytics
SFDA and SAMA alignment on travel health documentation is broadening the cost-of-entry calculus for insurers seeking to serve outbound and inbound travelers. Tawuniya Insurance leverages its domestic branch network to sustain policy accessibility across secondary cities. Allianz Saudi Fransi Cooperative Insurance anchors its competitive stance through specialized medical evacuation protocols. Al Rajhi Takaful differentiates via Takaful-compliant product structures that resonate with faith-conscious travelers.
Saudi Arabia travel insurance constitutes a risk-transfer instrument designed to indemnify policyholders against medical emergencies, trip interruptions, and baggage loss during domestic or international journeys, typically underwritten with 24/7 assistance hotlines and cashless hospital networks. Its primary commercial purpose centers on reducing traveler financial exposure while satisfying visa-entry and employer-mandated coverage requirements. Medical Insurance commands the largest premium pool given mandatory health coverage tied to visa issuance, while Trip Cancellation coverage shows structural momentum as booking volumes rise through digital platforms. The Online distribution channel captures the fastest-growing transaction share, though Insurance Agents retain margin depth through advisory-led family and annual policy sales.
SAMA's bancassurance distribution rules and the Saudi Central Bank's consumer protection framework govern product transparency and channel conduct, directly shaping how insurers design disclosure documents and commission structures. SFDA oversight of travel health requirements for pilgrims intersects with insurance mandates, creating a dual-compliance environment for Hajj and Umrah coverage. Stakeholders must monitor regulatory harmonization between SAMA and health authorities, as evolving visa-linked insurance requirements will determine which product configurations gain market access and which distribution models face compression.
Market Dynamics
SAMA's bancassurance distribution rules and the Saudi Central Bank's consumer protection framework are compressing commission structures while mandating granular disclosure documents, forcing insurers to rebuild product economics around transparency rather than channel incentives.
Growth Catalysts
- Visa-linked insurance mandates:The Saudi Central Bank's requirement for mandatory health coverage tied to visa issuance creates automatic policy attachment at point of application, embedding insurance into the travel workflow.
- Digital platform integration:Umrah and Hajj booking portals now embed insurance selection into reservation flows, collapsing the purchase decision timeline from days to minutes.
- Makkah-Madinah corridor infrastructure:Concentrated religious tourism flows in these two cities generate predictable risk pools that support specialized product development and localized claims servicing.
Market Restraints
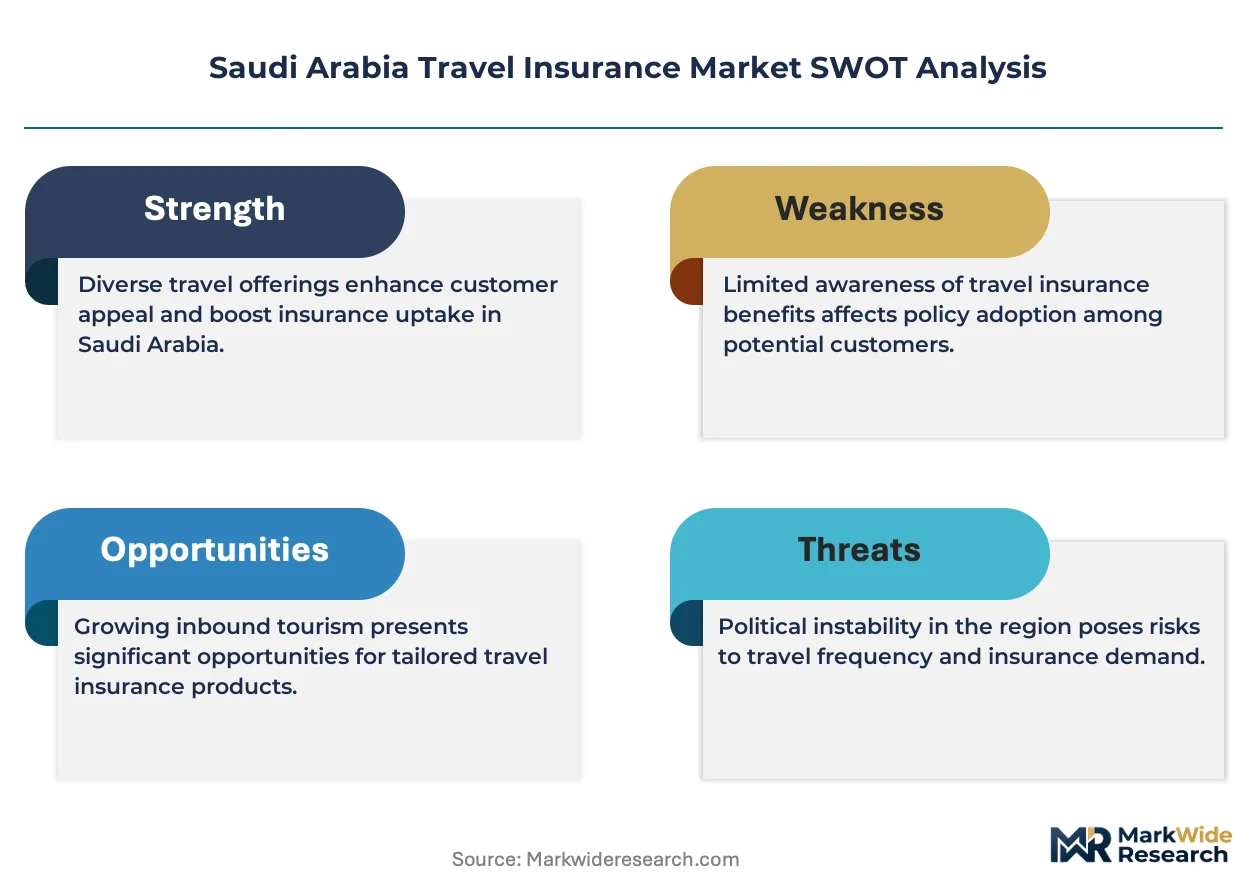
- Medical cost inflation:Hospital tariff escalation in Saudi Arabia's private healthcare sector compresses loss ratios on medical evacuation and inpatient coverage.
- Regulatory fragmentation:SAMA and SFDA maintain overlapping but non-identical documentation requirements for pilgrim health coverage, forcing dual compliance spend.
- Seasonal demand concentration:Hajj's fixed lunar calendar creates acute capacity strain on assistance hotlines and claims adjudication resources for six weeks annually.
Strategic Opportunities
- Secondary city penetration:Jeddah, Taif, and Yanbu host growing outbound travel segments with underdeveloped insurance attachment rates compared to Riyadh.
- Annual multi-trip products:Frequent business travelers between Saudi Arabia and GCC states represent a white space beyond single-trip pilgrimage coverage.
- Takaful-compliant structures:SAMA's Shariah governance guidelines create regulatory tailwind for cooperative insurance models that align with faith-conscious traveler preferences.
Industry Challenges
- Actuarial talent scarcity:Specialized underwriters with pilgrimage risk expertise remain concentrated in Jeddah and Riyadh, constraining product innovation velocity.
- Legacy core system integration:Established insurers face friction connecting SAMA-mandated real-time reporting APIs to decades-old policy administration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Travel Insurance Market |
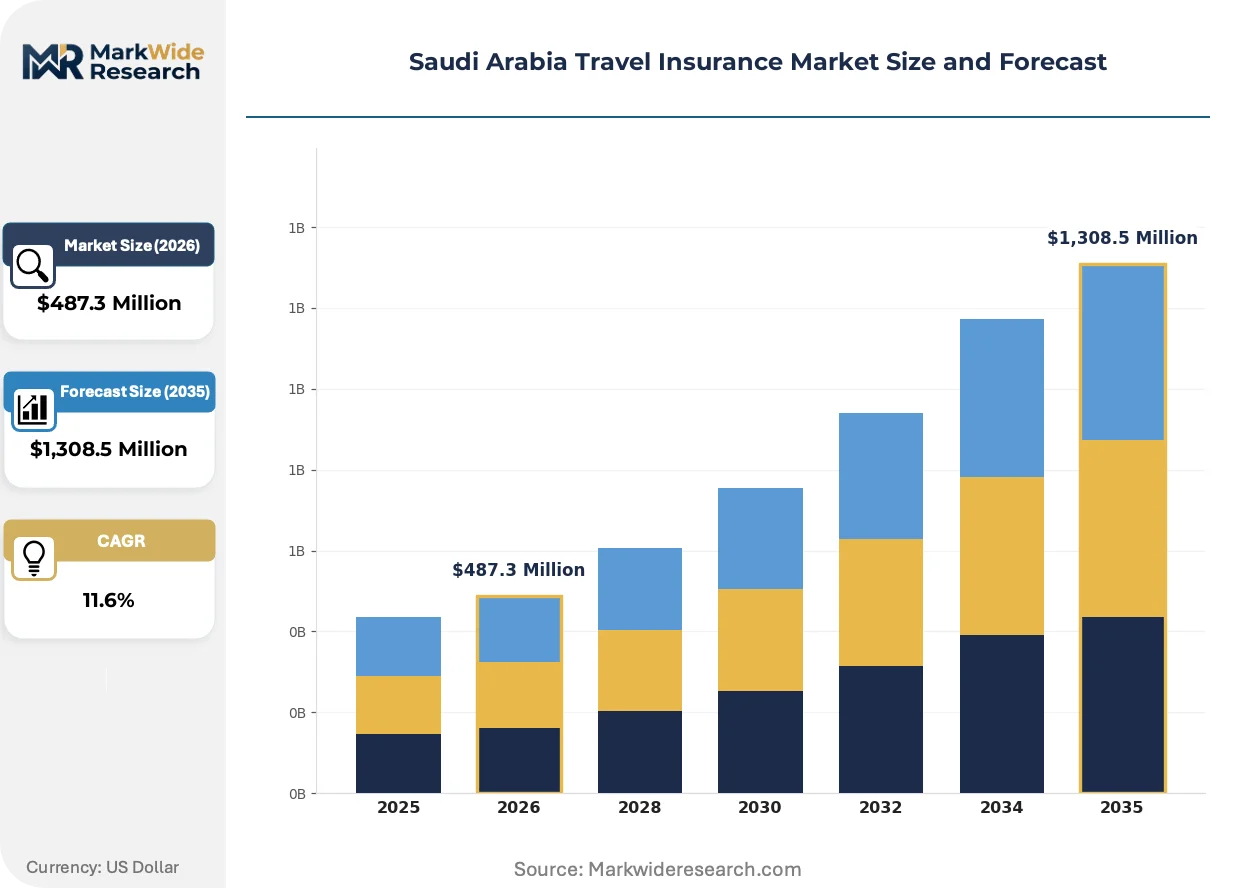
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Insurance, Trip Cancellation, Baggage Insurance, Travel Delay Customer Type: Business Travelers, Leisure Travelers, Families, Students Duration: Short-Term, Long-Term, Annual, Multi-Trip Distribution Channel: Online, Insurance Agents, Travel Agencies, Direct Sales |
| Companies Covered | Tawuniya Insurance, Allianz Saudi Fransi Cooperative Insurance, Al Rajhi Takaful, AXA Cooperative Insurance, Bupa Arabia, MedGulf, Gulf Union Cooperative Insurance, Walaa Cooperative Insurance, Malath Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Travel Insurance Market Evolving Landscape
Travel insurance distribution in Saudi Arabia is bifurcating between embedded digital checkout experiences and advisory-led family policy sales, with technology investments concentrating on claims automation and real-time medical network integration.
AI-powered claims adjudication is automating document verification and hospital bill validation for medical evacuation cases. Tawuniya and Al Rajhi Takaful have deployed machine learning models across their assistance networks, compressing claims settlement cycles from weeks to 48 hours. This capability is automating cost structures that previously required manual review by Arabic-speaking medical assessors.
SAMA's bancassurance distribution rules now cap commission rates and mandate cooling-off periods for policies sold through bank channels. The regulation forces insurers to redesign incentive structures away from volume-based payouts toward customer retention metrics. Hajj and Umrah coverage products face the steepest compliance burden given their high-volume, low-margin economics.
Umrah travelers are increasingly selecting coverage through mobile-optimized booking platforms rather than agent-mediated channels. The shift fragments customer acquisition economics and elevates price transparency, compressing differentiation around brand recognition alone. This behavioral pivot is most pronounced among pilgrims under 35 departing from Jeddah and Riyadh.
Saudi Arabia Travel Insurance Market Segmentation
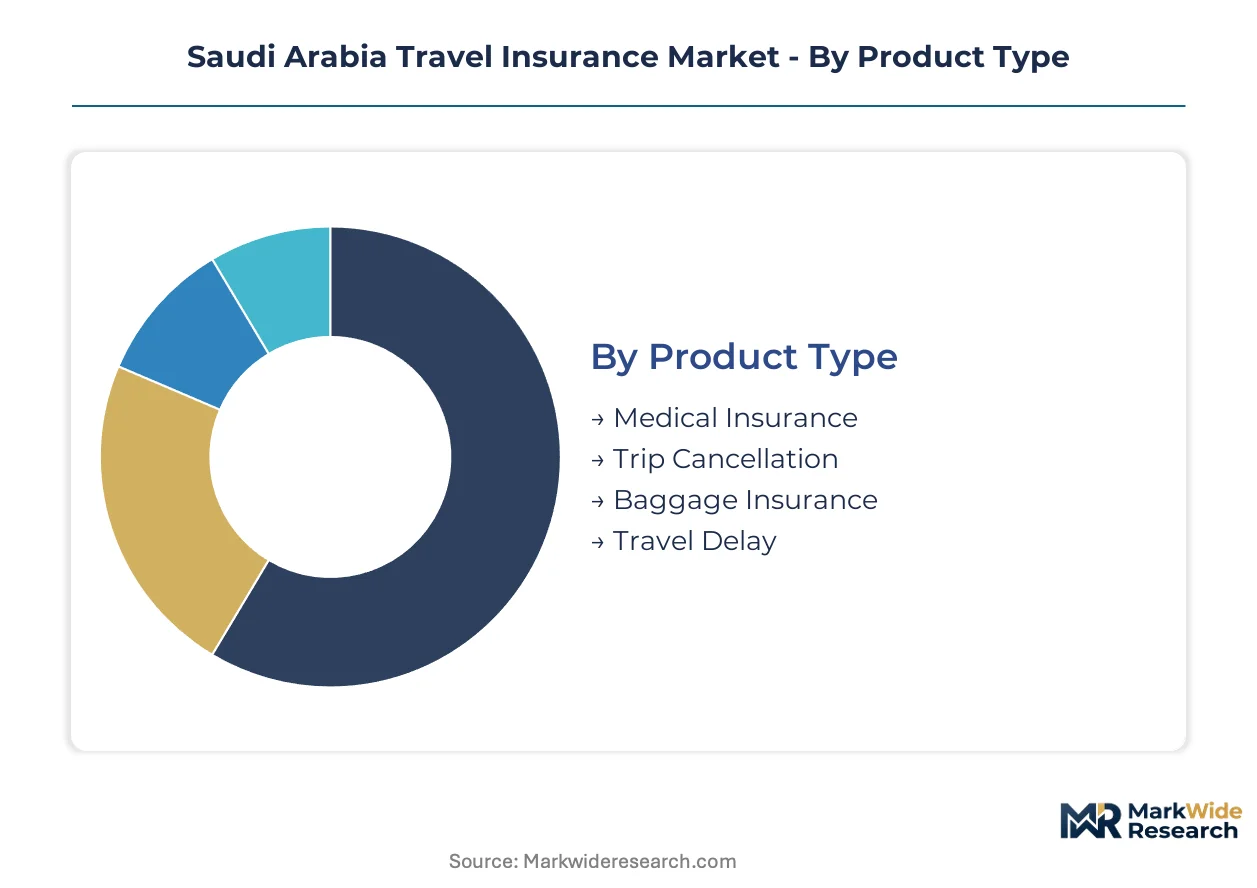
Saudi Arabia's travel insurance market fragments across product architecture, customer profiles, trip duration, and distribution pathways. Each segmentation axis carries distinct regulatory implications and margin structures that shape competitive positioning.
Product Type:
Standalone medical coverage operates independently of bundled travel packages, while trip cancellation and delay products embed into reservation systems.
- Medical Insurance:Core coverage indemnifies emergency hospitalization, evacuation, and repatriation costs. Demand concentrates among Umrah and Hajj pilgrims in Makkah and Madinah corridors where visa mandates require proof of health coverage. SAMA's disclosure rules force granular benefit schedules.
- Trip Cancellation:Protects prepaid, non-refundable travel expenditures against illness, death, or visa denial. Digital booking platforms in Riyadh and Jeddah embed this coverage at checkout, collapsing purchase friction. SFDA health documentation requirements intersect with cancellation triggers.
- Baggage Insurance:Covers loss, theft, or damage to personal effects during transit. Attachment rates lag medical and cancellation coverage due to lower perceived risk severity.
- Travel Delay:Compensates additional accommodation and meal expenses from carrier-schedule disruptions. Demand spikes during Hajj peak periods when airlift capacity strains.
Volume placements concentrate in Medical Insurance; the faster expansion belongs to Trip Cancellation.
Customer Type:
Cost tiers separate corporate procurement from individual leisure purchases, with families commanding premium advisory attention and students representing thin-margin digital acquisition.
- Business Travelers:Employer-sponsored coverage dominates, with multinational corporations in Riyadh and Dhahran mandating annual multi-trip policies. Procurement runs through corporate brokers with negotiated rate schedules.
- Leisure Travelers:Individual purchasers selecting single-trip coverage for vacation or family visits. Online channels capture this segment fastest in Jeddah and Dammam.
- Families:Multi-generational pilgrimage groups require specialized underwriting for pre-existing conditions and age-banded pricing. Insurance agents retain margin depth through advisory-led sales.
- Students:Outbound scholarship recipients and exchange participants need extended-duration coverage meeting host-country requirements. Price sensitivity compresses commission structures.
Margin concentration sits with Families; the steepest volume climb belongs to Business Travelers.
Duration:
Policy architecture separates episodic protection from continuous coverage, with annual products embedding loyalty mechanisms absent from transactional short-term sales.
- Short-Term:Single-trip coverage spanning days to weeks. Hajj and Umrah pilgrims in Makkah corridor drive peak volumes during Ramadan and Dhu al-Hijjah.
- Long-Term:Extended protection for expatriate workers and students abroad exceeding ninety days. Underwriting complexity elevates due to host-country medical inflation exposure.
- Annual:Year-round coverage with trip frequency caps. Frequent flyers between Saudi Arabia and GCC states anchor demand in Riyadh and Khobar.
- Multi-Trip:Unrestricted journey coverage within policy period. Corporate accounts in Dammam and Jubail Industrial City favor this structure for operational flexibility.
Revenue gravity centers on Short-Term; Annual products gain share fastest among frequent regional travelers.
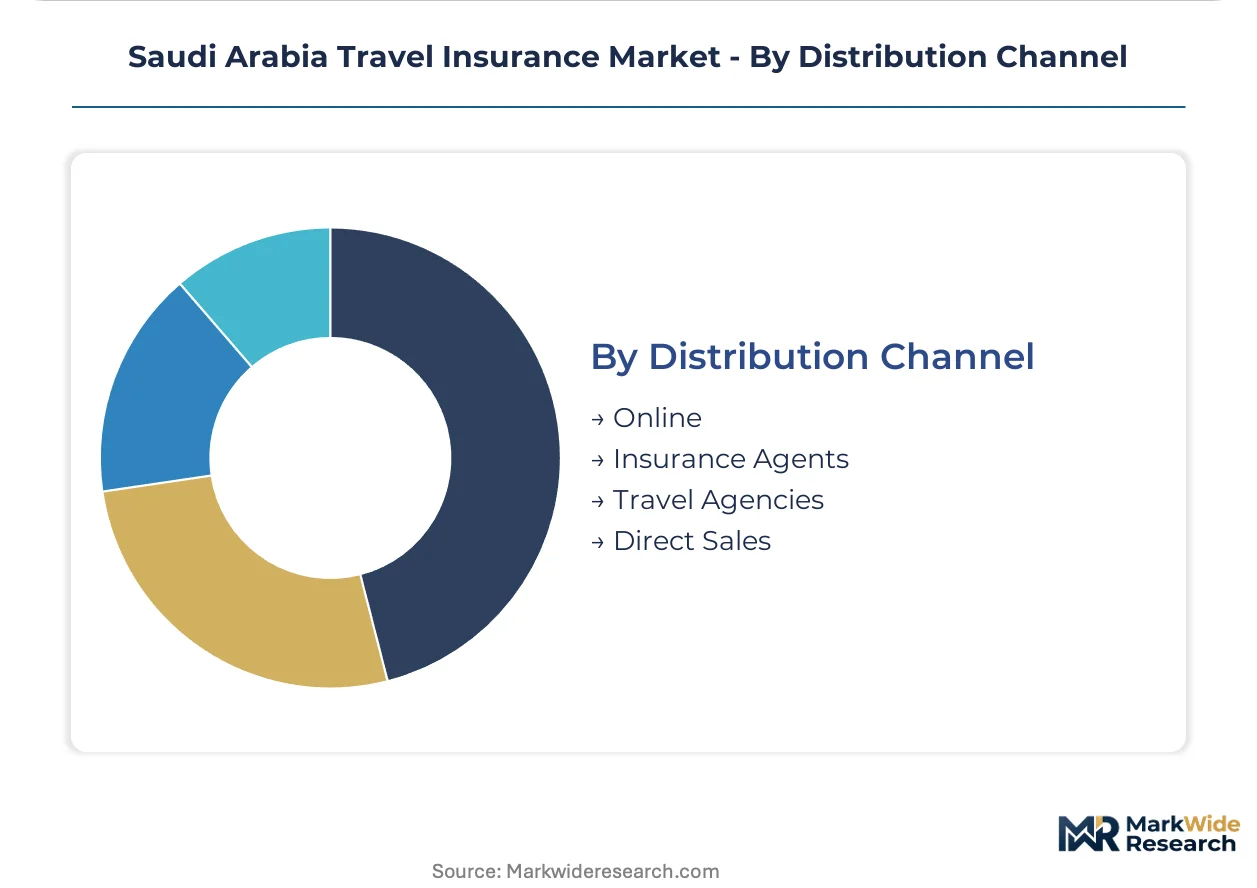
Distribution Channel:
Channel economics bifurcate between automated digital fulfillment and relationship-mediated advisory sales, with SAMA's bancassurance rules compressing traditional commission pools.
- Online:Direct-to-consumer platforms and embedded checkout experiences. Mobile-optimized portals capture pilgrims under thirty-five departing Jeddah and Riyadh.
- Insurance Agents:Licensed intermediaries providing product comparison and claims advocacy. Family and annual policy sales retain margin depth through personalized consultation.
- Travel Agencies:Package tour operators attaching coverage to Hajj and Umrah bookings. Regulatory harmonization between SAMA and SFDA elevates compliance documentation burdens.
- Direct Sales:Insurer-owned branches and call centers. Tawuniya's secondary city network exemplifies this model in Taif and Yanbu.
Transaction volume concentrates in Online; Insurance Agents defend the highest premium-per-policy yields.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Abdullah Economic City special zone concentrates underwriting infrastructure along the Red Sea corridor, drawing insurers toward Jeddah's commercial hub and the western pilgrimage belt.
Riyadh
Corporate travel procurement and government sector contracts dominate premium volumes in the capital. SAMA's regulatory headquarters enforces real-time reporting standards that reshape product disclosure requirements. The Riyadh Financial District hosts captive insurance operations serving multinational energy and construction firms with outbound executive coverage.
Eastern Province
Industrial corridor travelers between Dammam, Jubail, and Khobar generate sustained demand for annual multi-trip policies. Employer-mandated coverage for expatriate workforces aligns with Saudi Central Bank consumer protection frameworks. Aramco-affiliated corporate accounts anchor group policy placements through direct sales channels.
Western Region
Makkah and Madinah corridors process the highest single-trip policy volumes globally during Hajj and Umrah seasons. SFDA health documentation requirements intersect with visa-linked insurance mandates at King Abdulaziz International Airport. Jeddah's Tahlia Street concentration of insurer branches supports real-time claims servicing for inbound pilgrims.
NEOM Northwest
Emerging giga-project tourism and business travel create experimental coverage demand outside traditional pilgrimage patterns. Regulatory sandbox provisions allow pilot products for extended-stay visitors and project contractors. The coastal development zone attracts insurers testing parametric and usage-based policy structures.
Saudi Arabia Travel Insurance Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Saudi Arabia's travel insurance sector. The market structure tilts toward consolidation among domestic cooperatives with established branch networks, while international joint ventures capture premium corporate segments. Three archetypes dominate: Takaful-compliant domestic cooperatives, international partnership structures, and health-focused composite insurers. Competitive moves center on digital platform integration and secondary city branch expansion.
Among domestic cooperative specialists, Tawuniya Insurance and Al Rajhi Takaful occupy positions reflecting contrasting distribution philosophies. Tawuniya anchors the direct sales archetype through physical branch penetration. Al Rajhi Takaful exemplifies faith-aligned product architecture. Allianz Saudi Fransi Cooperative Insurance represents the international partnership model, situating within premium-tier medical evacuation coverage.
| Leading Market Players |
|---|
| Tawuniya Insurance |
| Allianz Saudi Fransi Cooperative Insurance |
| Al Rajhi Takaful |
| AXA Cooperative Insurance |
| Bupa Arabia |
| MedGulf |
| Gulf Union Cooperative Insurance |
| Walaa Cooperative Insurance |
| Malath Insurance |
| Others |
Value Network & Pricing Analysis
Visa-linked insurance mandates from SAMA and the Saudi Central Bank compress purchase decision timelines to minutes, forcing insurers to automate underwriting infrastructure and absorb upfront technology costs that reshape premium economics across distribution tiers.
Pricing Analysis
Short lead-time premiums dominate Hajj and Umrah coverage where pilgrimage booking windows collapse policy issuance cycles. Three-tier pricing structure across premium, standard, and economy levels segments pilgrims by age band, pre-existing condition disclosure, and evacuation service tier. Price differentiation hinges on medical network breadth and Arabic-language assistance availability. Cost compression in standard-tier products intensifies as digital platforms elevate price transparency among Jeddah and Riyadh departures. Students and young leisure travelers exhibit highest price sensitivity; corporate accounts and multi-generational families show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Jeddah-based assistance networks that anchor claims servicing for western pilgrimage corridors. Reinsurance capacity draws from London, Bermuda, and Singapore markets. Medical evacuation fleets and Arabic-speaking case managers constitute critical inputs. Tariff exposure runs through Saudi Arabia's private hospital sector where inpatient cost escalation outpaces premium adjustments. Distribution runs through bancassurance partnerships, direct insurer branches, and embedded digital checkout flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAMA's commission caps and real-time reporting mandates constitute a consolidation pressure that will force sub-scale insurers toward cooperative absorption or exit.
For Market Incumbents: Anchor defensive positioning through backward integration into proprietary assistance networks, reducing reliance on third-party medical evacuation vendors. Deepen branch penetration in Taif and Yanbu before regional specialists establish footholds. SAMA's cooling-off period rules threaten volume-based economics; shift incentive structures toward retention metrics and claims experience pricing. For New Entrants and Emerging Players: Embedded checkout partnerships with Umrah booking platforms offer the lowest-friction customer acquisition route into a market where agent channels face commission compression. Target annual multi-trip coverage for frequent GCC business travelers as the most penetrable white space beyond saturated pilgrimage segments. Lead with mobile-optimized policy issuance and 48-hour claims settlement guarantees. For Investors and Strategic Acquirers: The window for entry favors Takaful-compliant cooperatives with established SFDA alignment and secondary city branch licenses. Long-term viability rests on regulatory harmonization execution between SAMA and health authorities. Watch for SAMA-SFDA documentation unification as the inflection signal that determines which product configurations gain sustainable market access.| Strategic Initiative | Industry Significance |
|---|---|
| Assistance Network Vertical Integration | Captures medical evacuation margin and compresses claims settlement cycles below 48 hours. |
| Secondary City Branch Expansion | Secures Tawuniya-style distribution reach in Taif and Yanbu before competitors establish presence. |
| Embedded Platform Partnership | Collapses purchase friction for Umrah pilgrims booking through mobile-optimized reservation flows. |
| Takaful Product Architecture Investment | Aligns with SAMA Shariah governance guidelines and faith-conscious traveler preferences. |
| Real-Time Reporting API Modernization | Satisfies Saudi Central Bank mandates while enabling dynamic pricing and risk segmentation. |
Research Methodology
Document review covered regulatory filings from SAMA and the Saudi Central Bank, SFDA health documentation requirements, and visa-linked insurance mandate circulars, complemented by interviews with insurance product managers, bancassurance distribution heads, pilgrimage tour operators, and medical assistance network coordinators. Secondary validation drew from SAMA statistical bulletins, cooperative insurance association reports, and customs data on outbound traveler volumes. Bottom-up policy issuance modeling and top-down premium pool estimates were triangulated against disclosed market participant data.
Cross-referencing historical growth patterns against executive panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, customer archetype, trip duration, and distribution channel, with additional granularity on pilgrimage versus non-pilgrimage travel purpose. CAGRs were derived from regression analysis of visa issuance trends, booking platform transaction data, and medical cost inflation assumptions. Forecast inputs incorporated SFDA-SAMA regulatory harmonization scenarios and digital platform penetration curves.
The model holds under stable regulatory enforcement and sustained religious tourism flows; deviation in visa policy relaxation or private hospital tariff caps would shift premium growth trajectories. Forecasts reflect assumptions about compliance cost absorption and technology investment cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Germany Travel Insurance Market
Insurance
Business Insurance Market
Insurance
Critical Illness Insurance Market
Insurance
North America Car Insurance Aggregators Market
Insurance
Japan Parametric Insurance Market
Insurance
MENA Health and Medical Insurance Market
Insurance
Germany Car Insurance Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
Insurance Aggregators Market
Insurance
Dental Insurance Market
Insurance
Global Flood Insurance Market
Insurance
Cargo Insurance Market
Insurance
Bancassurance in ASEAN Market
Insurance
France Car Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
South Africa Property and Casualty Insurance Market