
 Switzerland Reinsurance Market | 2026-2036
Switzerland Reinsurance Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Reinsurance Market Insights
The EU Green Deal is repositioning demand toward climate risk transfer instruments. Swiss Re Ltd leverages its Zurich headquarters to sustain treaty dominance across European cedents. Munich Reinsurance Company anchors global property catastrophe capacity. Hannover Rück S.E. specializes in specialty lines across German-speaking markets.
Reinsurance constitutes a risk transfer mechanism where primary insurers cede portions of their underwritten portfolios to specialized carriers, utilizing probabilistic modeling and layered capital structures to absorb peak losses beyond retention thresholds. Property coverage commands the largest premium pool, while treaty arrangements capture the fastest-growing structural segment as cedents seek multi-year capital relief. Service type stratification reveals facultative placement retaining margin concentration in complex, non-standard risks.
Swiss Federal Office of Private Insurance (FINMA) supervision shapes solvency capital requirements, while EU Solvency II equivalence provisions govern cross-border treaty recognition. Swissmedic and the Swiss National Bank jointly influence health reinsurance liquidity standards. Stakeholders must monitor evolving climate stress test mandates and their cascading effects on pricing model calibration.
Market Dynamics
FINMA solvency stress tests and EU Solvency II equivalence provisions are compressing capital allocation timelines, forcing cedents to accelerate treaty restructuring while reinsurers recalibrate peak loss models for climate volatility.
Growth Catalysts
- EU Green Deal climate risk mandates:Cedents across Germany and France must embed physical risk transfer into underwriting frameworks, expanding multi-year treaty demand for Swiss carriers.
- Parametric trigger technology:Satellite-indexed payout structures eliminate claims adjustment friction, attracting property underwriters seeking immediate liquidity post-catastrophe.
- Zurich treaty hub concentration:Proximity to Lloyd's European syndicates and continental cedent headquarters sustains placement velocity for complex layered structures.
Market Restraints
- Retrocessional capacity scarcity:Bermuda and London ILS markets have contracted peak peril coverage, trapping Swiss Reinsurance carriers with unhedged catastrophe accumulations.
- Swiss franc capital base volatility:SNB interest rate divergence from ECB benchmarks creates currency-hedging costs that erode net treaty margin.
- Model risk in secondary peril pricing:Flood and wildfire probabilistic frameworks lack historical calibration depth, forcing conservative capital loading that prices Swiss carriers above Lloyd's alternatives.
Strategic Opportunities
- Swissmedic health reinsurance liquidity standards:Accelerated regulatory approval for longevity-linked securities opens capital markets integration for life treaty portfolios.
- Alpine parametric agriculture coverage:Index-based drought and hail instruments for Swiss and Austrian viticulture remain underpenetrated relative to French market density.
- Embedded insurance convergence:Partnerships with German automotive OEMs and Swiss fintech platforms distribute micro-duration property coverage through digital origination channels.
Industry Challenges
- Catastrophe modeler talent scarcity:Swiss Federal Institutes produce insufficient actuarial science graduates with climate physics specialization to staff treaty pricing teams.
- Legacy core system integration:Mainframe-based policy administration at established carriers impedes real-time data feeds from IoT-enabled risk monitoring devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Reinsurance Market |
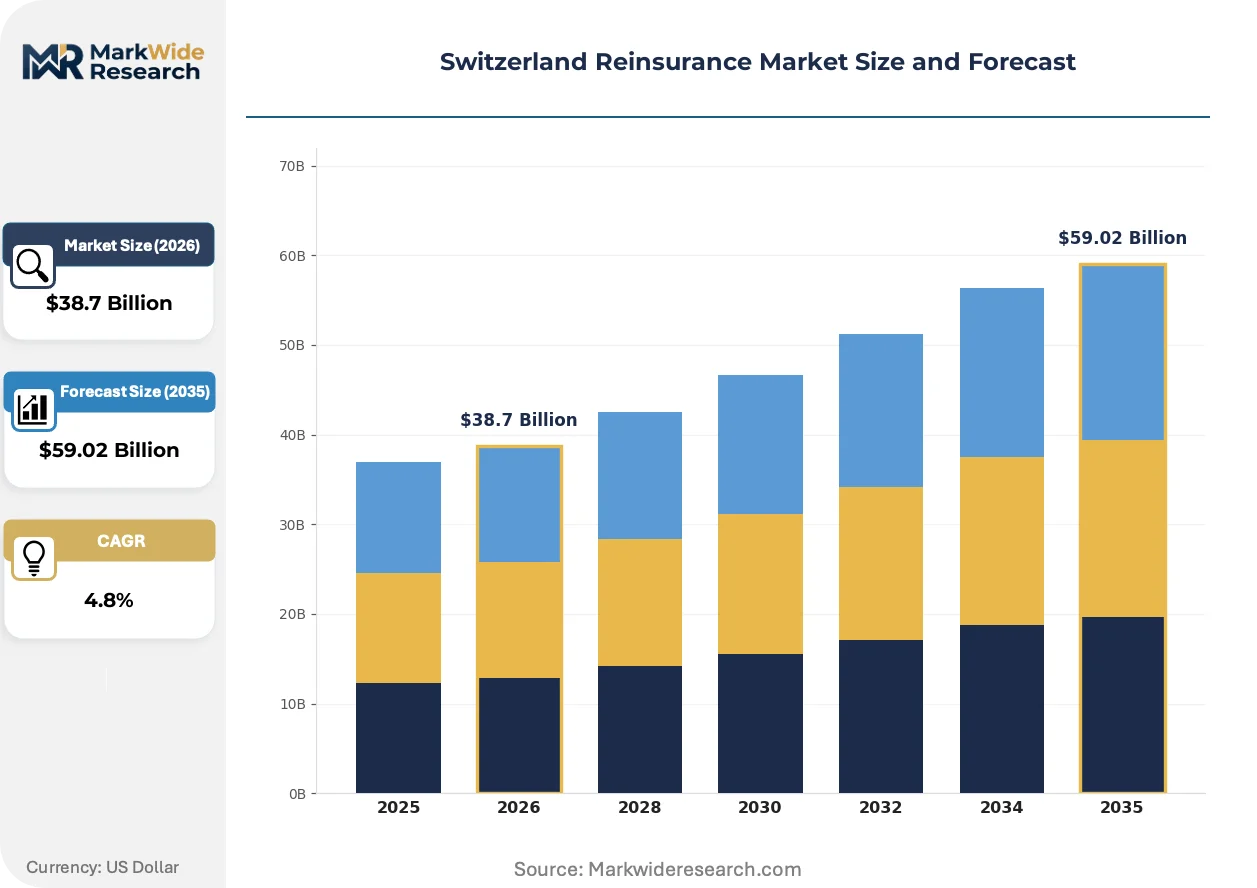
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Property, Casualty, Life, Health Customer Type: Insurance Companies, Corporations, Governments, Brokers Service Type: Facultative, Treaty, Excess of Loss, Quota Share Pricing Model: Risk-Based, Cumulative Premium, Fixed Rate, Commission |
| Companies Covered | Swiss Re Ltd, Munich Reinsurance Company, Hannover Rück S.E., SCOR, Berkshire Hathaway Inc., Lloyd's, Everest Group, Renaissance Re, Deutsche Rückversicherung AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Reinsurance Market Trends and Innovations
Climate risk quantification tools and algorithmic treaty placement platforms are restructuring how Swiss carriers price peak exposures and match cedent demand with capital providers.
Probabilistic climate scenario modeling is overtaking historical loss ratio analysis as the dominant pricing input for property catastrophe treaties. Swiss cedents now mandate stochastic flood and wildfire projections in renewal submissions, compressing traditional experience-rated structures. This shift enables Swiss Reinsurance carriers to command tiered pricing premia for forward-looking risk selection.
EU Solvency II equivalence provisions governing Swiss treaty recognition are tightening collateral posting requirements for cross-border placements. FINMA has responded with streamlined internal model approval pathways, reducing frictional capital costs for qualifying carriers. German and Austrian cedents now prioritize Swiss-domiciled reinsurers with dual regulatory accreditation.
Cedent risk managers are consolidating facultative placements into centralized treaty programs to capture scale economies in premium spend. This procurement compression disadvantages standalone facultative specialists while rewarding Zurich-based carriers with integrated treaty-facultative platforms. The trend is most pronounced among mid-sized German property underwriters seeking simplified counterparty exposure.
Switzerland Reinsurance Market Segmentation
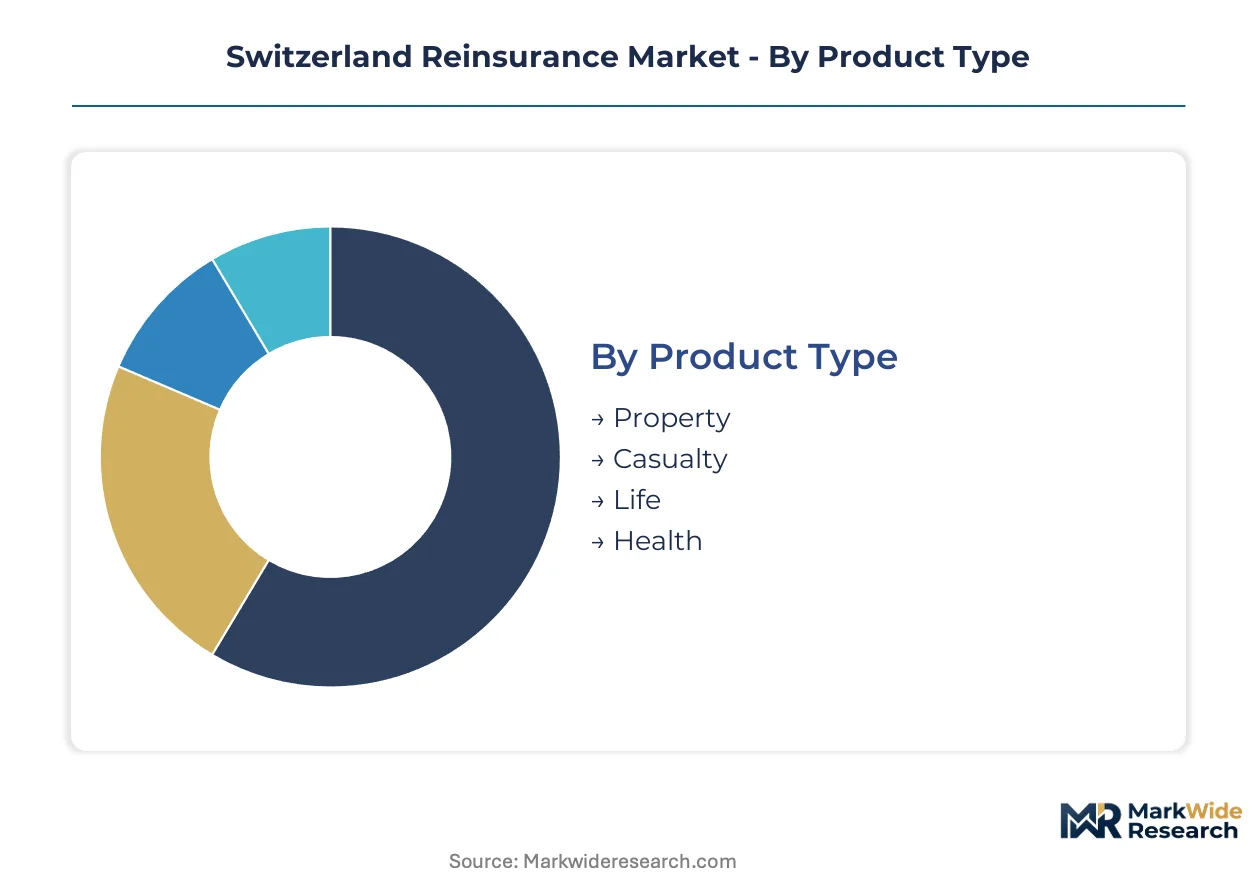
Reinsurance purchasing in Switzerland follows distinct decision hierarchies where cedent capital efficiency, regulatory equivalence, and counterparty concentration shape portfolio construction across product lines and service structures.
Product Type:
Cedent risk managers prioritize capital relief intensity when allocating premium across life and non-life portfolios, with Swiss Solvency Test equivalence driving treaty selection.
- Property:Covers physical damage and business interruption from natural catastrophes, fire, and engineering perils. German and French primary insurers cede peak earthquake and flood exposures to Zurich-based carriers seeking multi-year capacity. Volume sits with Property; growth tilts toward parametric-indexed structures.
- Casualty:Encompasses liability, motor, and general casualty risks with long-tail reserving profiles. Swiss cedents favor casualty treaties for asbestos and environmental legacy runoff, though social inflation in US-exposed portfolios compresses pricing transparency.
- Life:Mortality and longevity risk transfer for annuity and pension liabilities. Swissmedic liquidity standards and FINMA internal model approvals enable Swiss carriers to structure longevity-linked securities for German life insurers.
- Health:Medical expense and disability reinsurance with shorter-duration claims development. Austrian social health insurers access Swiss capacity for cost-containment treaty structures.
Property commands premium concentration; life and health expand fastest under Solvency II equivalence.
Customer Type:
Counterparty sophistication determines placement channel selection, with direct treaty negotiations favoring scale and brokered markets serving fragmented demand.
- Insurance Companies:Primary carriers ceding portfolio slices to optimize capital under Solvency II and Swiss Solvency Test requirements. Mid-sized German property underwriters consolidate facultative placements into centralized treaty programs.
- Corporations:Large industrial captives and risk retention groups accessing reinsurance for employee benefits and property programs. Swiss pharmaceutical multinationals structure captive reinsurance through Zurich-domiciled vehicles.
- Governments:Sovereign catastrophe pools and public risk financing mechanisms. Alpine cantonal governments explore parametric coverage for infrastructure protection.
- Brokers:Intermediaries placing risks on behalf of cedents, particularly for complex layered structures. Lloyd's European syndicates rely on Zurich broker networks for continental treaty access.
Direct cedent relationships dominate volume; brokered channels gain share in specialty and cross-border placements.
Service Type:
Structural arrangement selection hinges on cedent desire for administrative simplicity versus risk-specific customization.
- Treaty:Automatic reinsurance agreements covering predefined portfolios without individual risk assessment. Swiss Re Ltd leverages Zurich headquarters to sustain treaty dominance across European cedents seeking streamlined renewal processes.
- Facultative:Case-by-case placement for non-standard or peak risks exceeding treaty capacity. Margin concentration persists in complex risks requiring individual underwriting judgment.
- Excess of Loss:Coverage activating above specified retention thresholds, protecting cedent capital against severity events. German industrial insurers layer excess structures for natural catastrophe protection.
- Quota Share:Proportional arrangement where reinsurer assumes fixed percentage of all risks in a class. Austrian motor insurers utilize quota share treaties to manage premium volume volatility.
Treaty structures capture volume leadership; facultative placements retain premium rate advantage in complex risks.
Pricing Model:
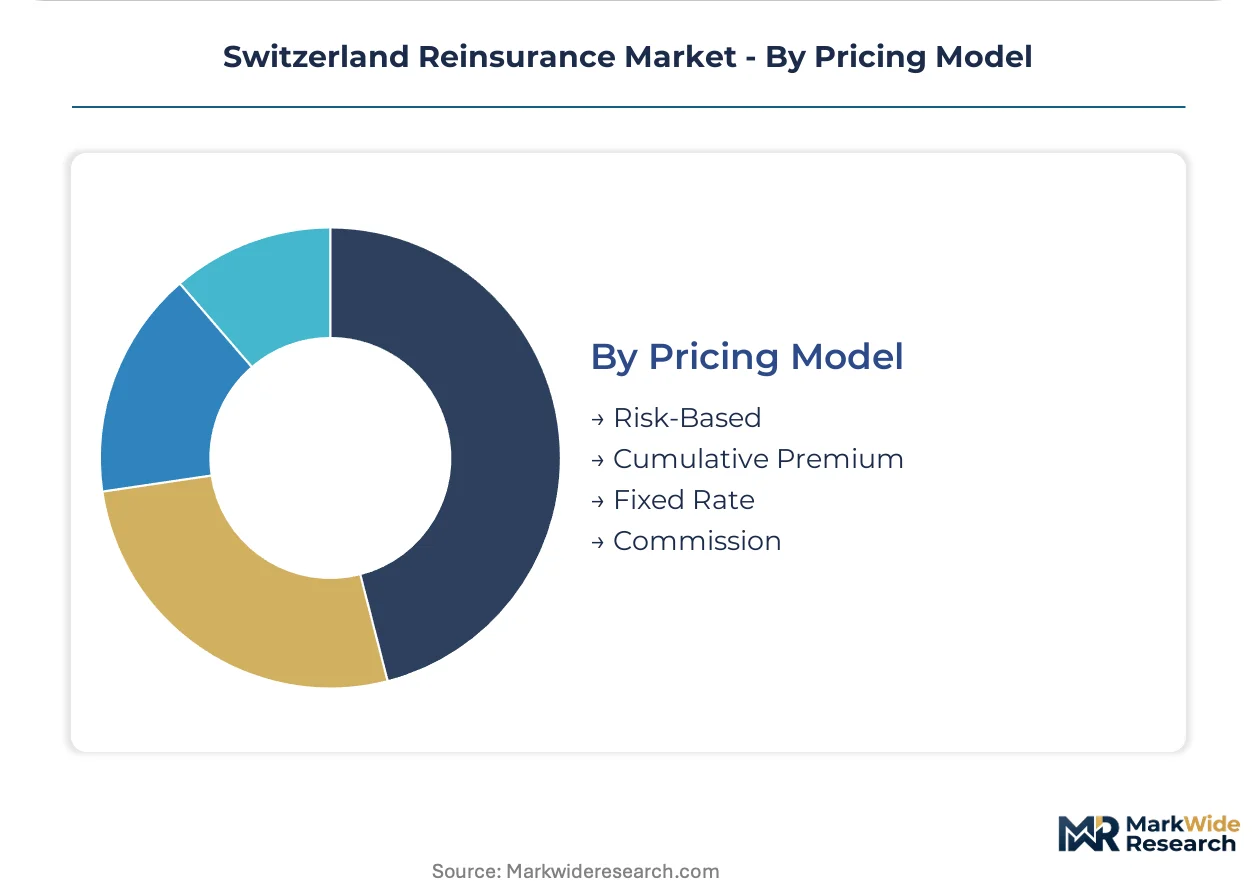
Model selection reflects data availability and cedent preference for predictability versus risk-aligned cost fluctuation.
- Risk-Based:Premium calibrated to individual risk characteristics using probabilistic modeling and exposure data. Climate stress test mandates from FINMA force recalibration of property catastrophe pricing inputs.
- Cumulative Premium:Aggregate pricing across multi-year treaty periods with experience adjustments. Swiss cedents favor cumulative structures for casualty portfolios with extended loss development.
- Fixed Rate:Predetermined premium without subsequent adjustment for actual loss experience. Simplified administration attracts smaller Austrian and German cedents with limited actuarial resources.
- Commission:Compensation structure where reinsurer pays cedent for acquisition and administration services. Proportional treaties incorporate sliding commission scales tied to loss ratio performance.
Risk-based pricing dominates property catastrophe lines; fixed rate structures persist in standardized treaty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zurich anchors treaty placement velocity for European cedents seeking multi-year capacity arrangements. Swiss Re Ltd leverages this headquarters concentration to sustain dominance across German and French primary insurers.
Germany
Munich Reinsurance Company anchors global property catastrophe capacity from its Bavarian base. The country's Federal Financial Supervisory Authority (BaFin) enforces Solvency II capital requirements that drive German cedents toward Swiss treaty partners with equivalence accreditation. Industrial insurers in North Rhine-Westphalia layer excess structures for natural catastrophe protection.
France
EU Green Deal climate risk mandates compel French primary carriers to embed physical risk transfer into underwriting frameworks. The Autorité de Contrôle Prudentiel et de Résolution (ACPR) supervises collateral posting for cross-border treaty placements. Paris-based cedents consolidate facultative placements into centralized programs to capture scale economies.
Austria
Social health insurers access Swiss capacity for cost-containment treaty structures. The Austrian Financial Market Authority (FMA) recognizes FINMA-approved internal models for cross-border recognition. Vienna-based motor underwriters utilize quota share treaties to manage premium volume volatility.
United Kingdom
Lloyd's European syndicates rely on Zurich broker networks for continental treaty access. The Prudential Regulation Authority (PRA) maintains divergent collateral standards that increase frictional costs for Swiss placements. London's specialty underwriters seek parametric trigger technology for immediate post-catastrophe liquidity.
Switzerland Reinsurance Market Competitive Landscape
Premium-margin players sit above commodity-margin players across treaty complexity and counterparty concentration. The Switzerland Reinsurance Market structures around three tiers: Zurich-domiciled giants with dual regulatory accreditation, German-speaking specialists capturing regional specialty lines, and London-Bermuda hybrids competing on catastrophe capacity pricing. Strategic archetypes include integrated treaty-facultative platforms, parametric technology specialists, and retrocessional capacity aggregators. Dominant competitive moves encompass multi-year treaty restructuring for climate volatility and partnerships with IoT-enabled risk monitoring providers.
Within the integrated platform tier, Swiss Re Ltd and Munich Reinsurance Company represent archetypal treaty dominance anchored in Zurich and Munich respectively. Hannover Rück S.E. exemplifies the German-speaking specialty specialist occupying a position between scale-driven giants and niche facultative players. These three entities collectively illustrate how geographic proximity to cedent headquarters, regulatory equivalence, and internal model approval pathways determine competitive positioning across European reinsurance procurement.
| Leading Market Players |
|---|
| Swiss Re Ltd |
| Munich Reinsurance Company |
| Hannover Rück S.E. |
| SCOR |
| Berkshire Hathaway Inc. |
| Lloyd's |
| Everest Group |
| Renaissance Re |
| Deutsche Rückversicherung AG |
| Others |
Pricing and Supply Chain Analysis
Actuarial talent concentration in Zurich and Basel drives labor-cost differentials that widen pricing-tier spreads between treaty specialists and commodity carriers. Swiss Federal Institutes produce insufficient climate-physics graduates, forcing carriers to import catastrophe modelers at premium compensation, which feeds into layered pricing structures that separate integrated platform providers from facultative boutiques.
Pricing Analysis
Risk-based pricing calibrated to probabilistic climate outcomes anchors treaty negotiations between Swiss carriers and German cedents. Price differentiation rests on internal model approval status under FINMA and EU Solvency II equivalence, with dual-accredited carriers commanding placement premia over single-jurisdiction competitors. Cost compression in standard property treaties is intensifying because Lloyd's syndicates and Bermuda ILS vehicles price peak peril capacity below Swiss capital-loading thresholds. Mid-sized Austrian motor underwriters exhibit highest price sensitivity, while Swiss pharmaceutical captives prioritize counterparty concentration over premium cost.
Supply Chain Analysis
Regional distribution centers in Zurich, Munich, and London form a hub-and-spoke pattern for treaty placement velocity, with Lloyd's European syndicates relying on Zurich broker networks for continental access. Capital provision concentrates in Switzerland, Germany, and Bermuda, while retrocessional capacity draws from London ILS markets and collateralized reinsurance vehicles. Single-source vulnerability sits with Bermuda peak peril coverage contraction, which traps Swiss carriers with unhedged catastrophe accumulations. Distribution runs through direct cedent relationships for scale placements and brokered channels for specialty risks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Switzerland Reinsurance Market sits in a technology-transition phase where parametric trigger platforms displace traditional indemnity structures for immediate post-catastrophe liquidity.
For Market Incumbents: Hedge treaty margin erosion by acquiring climate-physics modeling boutiques in Zurich and Basel to reduce actuarial talent scarcity. Prioritize FINMA internal model approval pathways that compress frictional capital costs under EU Solvency II equivalence, defending placement velocity against London-Bermuda competitors.
For New Entrants and Emerging Players: Capture underpenetrated Alpine parametric agriculture coverage for Swiss and Austrian viticulture, where index-based drought and hail instruments lag French market density. Partner with German automotive OEMs for embedded insurance distribution through digital origination channels.
For Investors and Strategic Acquirers: Re-rating potential sits with parametric technology specialists given EU Green Deal climate risk mandates compelling cedent demand for satellite-indexed payout structures. Long-term viability favors carriers with dual regulatory accreditation bridging Swiss and EU frameworks. Watch FINMA climate stress test mandate calibration as inflection indicator for capital requirement severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Platform Development | Satellite-indexed triggers eliminate claims friction for German property cedents post-catastrophe. |
| FINMA Internal Model Approval | Streamlined pathways reduce capital costs under EU Solvency II equivalence provisions. |
| Climate Physics Talent Acquisition | Swiss Federal Institute graduates with catastrophe modeling specialization command placement pricing power. |
| Embedded Insurance Partnerships | German automotive OEMs and Swiss fintech platforms enable micro-duration property distribution. |
| Longevity-Linked Securities Launch | Swissmedic liquidity standards open capital markets integration for German life treaty portfolios. |
Research Methodology
Document review covered regulatory filings with FINMA and BaFin, treaty placement databases, and EU Solvency II equivalence documentation, complemented by interviews with chief underwriting officers at Zurich-domiciled carriers, cedent risk managers at German primary insurers, broker executives placing European layered structures, and actuarial directors specializing in climate risk quantification. Secondary validation drew from FINMA stress test disclosures, Lloyd's market reports, and retrocessional capacity indices. Bottom-up treaty premium aggregation and top-down macroeconomic scenario triangulation anchored market sizing.
Historical treaty renewal patterns cross-referenced against panel input from underwriting executives informed the analytical framework across the analysis window. Segmentation dimensions modeled encompass product type, service structure, customer sophistication tier, and pricing model architecture. CAGRs were derived from stochastic projections of cedent capital efficiency requirements and climate volatility assumptions. Industry-specific inputs included FINMA climate stress test mandate evolution and EU Green Deal implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to retrocessional market contraction, Swiss franc volatility against ECB benchmarks, and secondary peril model calibration advances. Forecasts reflect documented assumptions around regulatory equivalence continuity and climate scenario severity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Africa Insurance Market
Insurance
Consumer Electronics Extended Warranty Market
Insurance
UK Commercial Insurance Market
Insurance
Japan Parametric Insurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
Parametric Insurance Market
Insurance
Earthquake Insurance Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Liability Insurance Market
Insurance
Asia-Pacific Mobile Phone Insurance Market
Insurance
Intellectual Property Insurance Market
Insurance
Disability Insurance Market
Insurance
Takaful Market
Insurance
India Liability Insurance Market
Insurance
MENA Health and Medical Insurance Market
Insurance
Trade Credit Insurance Market