
 Global Cargo Transportation Insurance Market | 2026-2036
Global Cargo Transportation Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cargo Transportation Insurance Market Analysis
All-risk coverage tier upgrades is reorganizing premium allocation across the Global Cargo Transportation Insurance Market. AIG leverages its marine underwriting scale to dominate complex international routes. Zurich Insurance Group anchors European liability portfolios through specialized logistics partnerships. Tokio Marine Holdings competes in Asia-Pacific trade lanes with tailored per-shipment products for electronics manufacturers.
Cargo transportation insurance is a risk-transfer contract indemnifying goods against physical loss or damage during transit by sea, air, rail, or road, typically covering perils from theft and weather to container abandonment with deductibles calibrated to commodity value and route hazard profiles. Its primary commercial purpose is to protect balance sheets of shippers and carriers against supply chain interruption costs. All Risk policies capture the deepest margin pools as multinational manufacturers seek seamless protection across multimodal chains, while Named Perils retains cost-sensitive commodity traders who self-insure partial losses. Single Shipment coverage shows structural growth acceleration from SME e-commerce exporters needing flexible, non-annual terms.
FDA import security requirements and EU CSRD disclosure mandates shape demand for verifiable coverage documentation in transatlantic pharmaceutical and food trade. China's SAMR standardization push on logistics service contracts tightens domestic carrier insurance compliance. Lloyd's of London and Berkshire Hathaway Specialty Insurance navigate these frameworks through localized underwriting authority in London, Singapore, and Bermuda hubs. Stakeholders must monitor how climate stress tests on port infrastructure recalibrate risk models and deductible structures.
Market Dynamics
All-risk coverage tier upgrades are reorganizing premium allocation across the Global Cargo Transportation Insurance Market as multinational manufacturers seek seamless protection across multimodal chains. E-commerce fulfillment networks are expanding coverage purchases for cross-border shipments, while the EU's Corporate Sustainability Reporting Directive pressures logistics firms to disclose supply chain risk exposure.
Growth Catalysts
- EU CSRD disclosure mandates:Logistics firms must document supply chain risk exposure, creating verifiable demand for comprehensive coverage documentation in transatlantic pharmaceutical and food trade corridors.
- Marine cargo policy volumes through Shanghai and Shenzhen port corridors:Manufacturing exports from China are concentrating demand in Asia-Pacific trade lanes, driving structural expansion in per-shipment products.
- Single Shipment coverage:SME e-commerce exporters require flexible, non-annual terms, accelerating structural growth in modular policy products tailored to irregular shipping schedules.
Market Restraints
- Climate stress tests on port infrastructure:Risk models require recalibration as extreme weather events damage container terminals, compressing underwriting margins and forcing deductible structure revisions.
- Carrier compliance fragmentation:China's SAMR standardization push on logistics service contracts creates friction with divergent national requirements, raising administrative costs for cross-border operators.
- Self-insurance by commodity traders:Named Perils coverage retains cost-sensitive bulk shippers who absorb partial losses internally, capping premium growth in standardized product tiers.
Strategic Opportunities
- FDA import security requirements:Pharmaceutical and food trade corridors demand enhanced coverage documentation, creating premium upgrade pathways for specialized underwriters with regulatory expertise.
- Parametric insurance convergence with IoT sensors:Real-time cargo monitoring enables automated claims triggering, opening white space in per-shipment products for electronics manufacturers with high-value, time-sensitive goods.
- India's DGFT trade facilitation frameworks:Export incentive structures for manufacturing hubs are expanding insurance penetration among first-time international shippers in underpenetrated SME segments.
Industry Challenges
- Actuarial talent scarcity in climate risk modeling:Underwriters lack specialized expertise to price emerging weather perils, delaying product launches in catastrophe-exposed routes.
- Legacy policy administration system integration:Incumbent carriers face technical debt when connecting modular per-shipment platforms to core annual policy infrastructure.
- Multi-jurisdiction claims adjudication complexity:Cross-border disputes require harmonized legal frameworks that remain underdeveloped in emerging market corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cargo Transportation Insurance Market |
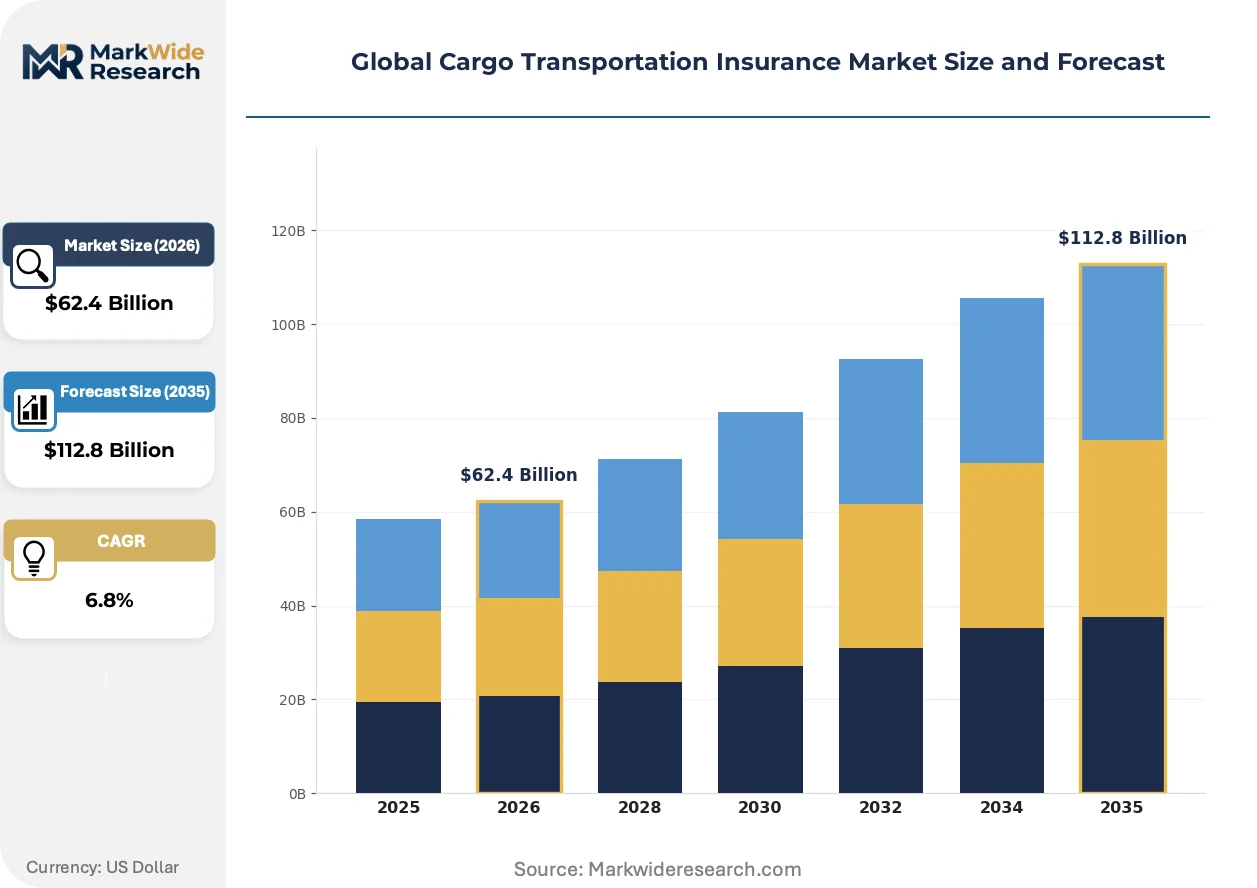
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: All Risk, Named Perils, Total Loss, Minimum Value Policy Duration: Single Shipment, Annual, Multi-Trip, Temporary Coverage Scope: Domestic, International, Intermodal, Freight Forwarder Client Type: Importers, Exporters, Freight Forwarders, Logistics Companies |
| Companies Covered | AIG, Allianz Global Corporate & Specialty, AXA XL, Chubb, Zurich Insurance Group, Tokio Marine Holdings, Lloyd's of London, Liberty Mutual Insurance, Berkshire Hathaway Specialty Insurance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cargo Transportation Insurance Market Emerging Trajectories
Digital risk transfer mechanisms are actively reshaping how cargo exposure is priced, monitored, and settled across multimodal supply chains. The convergence of sensor data, automated underwriting, and regulatory disclosure requirements is compressing traditional policy cycles.
Blockchain-enabled smart contracts are displacing manual documentation and verification processes in marine cargo settlements. Electronics manufacturers with high-frequency Asia-Europe shipments are adopting these instruments fastest. The technology is displacing letter-of-credit intermediaries and reducing settlement friction in multimodal handoffs.
The EU's Corporate Sustainability Reporting Directive mandates granular supply chain risk disclosure for large logistics operators. Industrial consequence includes mandatory insurance documentation as audit evidence. Pharmaceutical cold-chain shippers are most affected, with carriers now bundling coverage certificates into compliance reporting workflows.
Per-shipment procurement models are fragmenting traditional annual policy relationships among SME exporters. Digital brokerage platforms are replacing direct carrier negotiations for irregular shippers. This shift is most visible in China's cross-border e-commerce corridors, where Shenzhen-based sellers purchase coverage transaction-by-transaction through embedded checkout integrations.
Global Cargo Transportation Insurance Market Segmentation
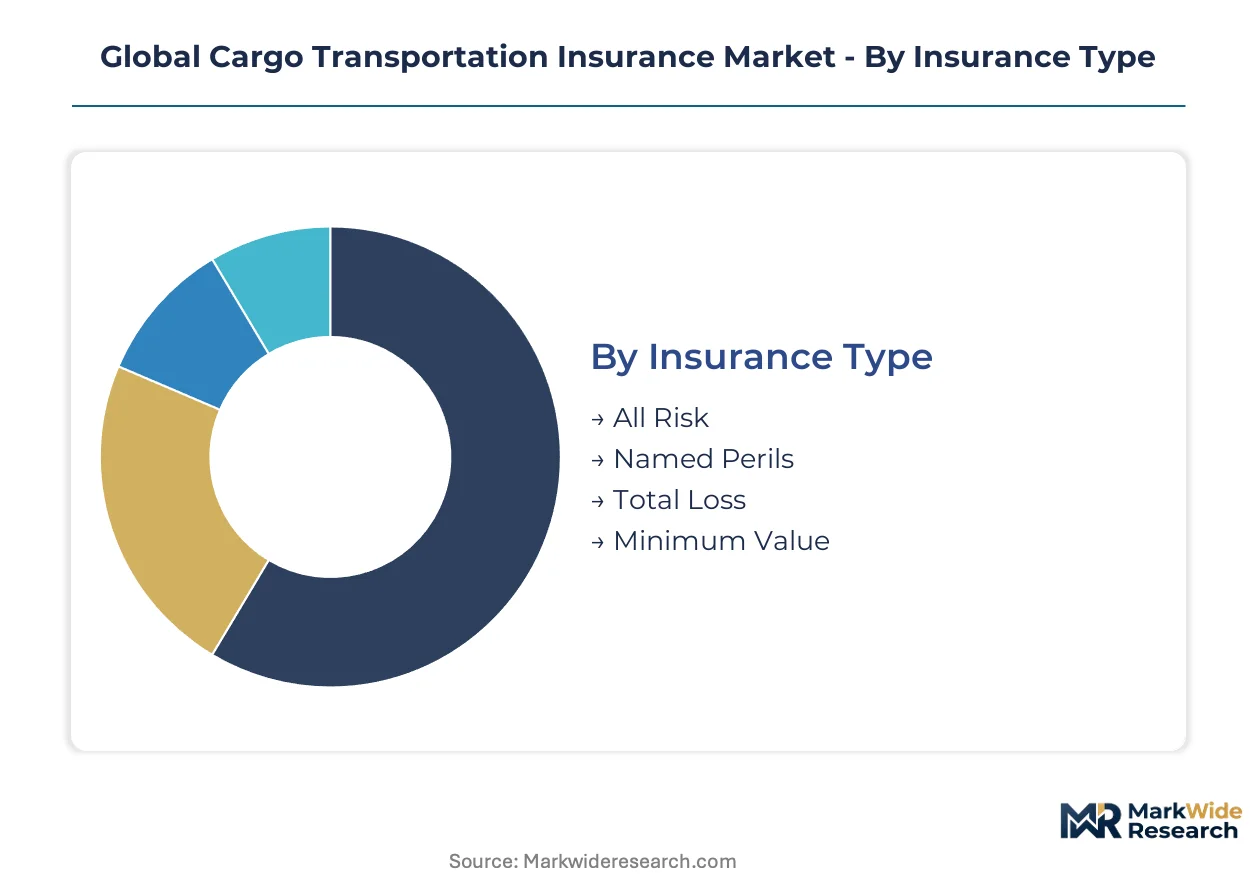
Segmentation in cargo transportation insurance determines how risk capital flows across premium tiers and policy structures. Underwriters calibrate pricing models and distribution channels based on coverage depth, shipment frequency, geographic scope, and client sophistication.
Insurance Type:
Named Perils coverage faces intensifying substitution pressure from parametric alternatives and self-insurance mechanisms among bulk commodity traders.
- All Risk:Comprehensive indemnity against physical loss or damage from external causes except explicitly excluded perils. Demand concentrates among multinational manufacturers routing through Rotterdam and Singapore multimodal hubs, driven by EU CSRD audit requirements for documented supply chain protection.
- Named Perils:Specified-cause coverage listing enumerated risks such as fire, collision, or jettison. Grain and mineral exporters across Black Sea and Brazilian port corridors favor this tier, constrained by thin margins that compress premium tolerance.
- Total Loss:Indemnity triggered only by complete cargo destruction or constructive total loss declarations. Specialist applications include project cargo for industrial equipment with irreplaceable components.
- Minimum Value:Threshold-triggered coverage activating only when loss exceeds predetermined value floors. Small-scale agricultural shippers in Indian and Vietnamese export corridors utilize this structure to manage premium outlays.
All Risk retains volume leadership; Minimum Value holds the steepest expansion curve among cost-sensitive SME exporters.
Policy Duration:
Cost tier stratification separates annual commitments from transactional purchasing, with premium efficiency driving large-fleet decisions and flexibility commanding SME loyalty.
- Single Shipment:Per-transaction coverage purchased for individual cargo movements. Shenzhen and Guangzhou e-commerce exporters dominate uptake, propelled by embedded checkout integrations on digital freight platforms.
- Annual:Twelve-month blanket policies covering all shipments within declared parameters. Major retailers and automotive manufacturers with predictable volume profiles anchor this segment.
- Multi-Trip:Defined-period coverage for specified voyage counts rather than temporal limits. Regional trucking operators across German and Polish corridors favor this structure for irregular but repeated lane coverage.
- Temporary:Short-duration policies spanning days to weeks for project-specific or seasonal cargo movements. Construction and exhibition logistics in UAE and Saudi Arabia generate concentrated demand.
Annual policies command premium scale; Single Shipment is gaining share fastest through platform-enabled distribution.
Coverage Scope:
Geographic application determines regulatory complexity and reinsurance layering, with intermodal handoffs creating the most intricate risk-transfer engineering.
- International:Cross-border coverage spanning multiple jurisdictions with harmonized claims protocols. Pharmaceutical cold-chain shippers between US and EU corridors require this tier for FDA and EMA compliance documentation.
- Intermodal:Seamless protection across sea-air-rail-road transfers with single-point accountability. Electronics manufacturers with high-frequency Asia-Europe rotations prioritize this scope for container handoff risk mitigation.
- Domestic:Single-country coverage aligned with national regulatory frameworks. China's SAMR-standardized logistics contracts are tightening compliance requirements for domestic carrier policies.
- Freight Forwarder:Liability coverage for logistics intermediaries rather than cargo owners. Third-party logistics providers in Indian manufacturing hubs are expanding penetration as export incentive structures mature.
International coverage retains volume leadership; Intermodal holds the steepest expansion curve as supply chain fragmentation accelerates.
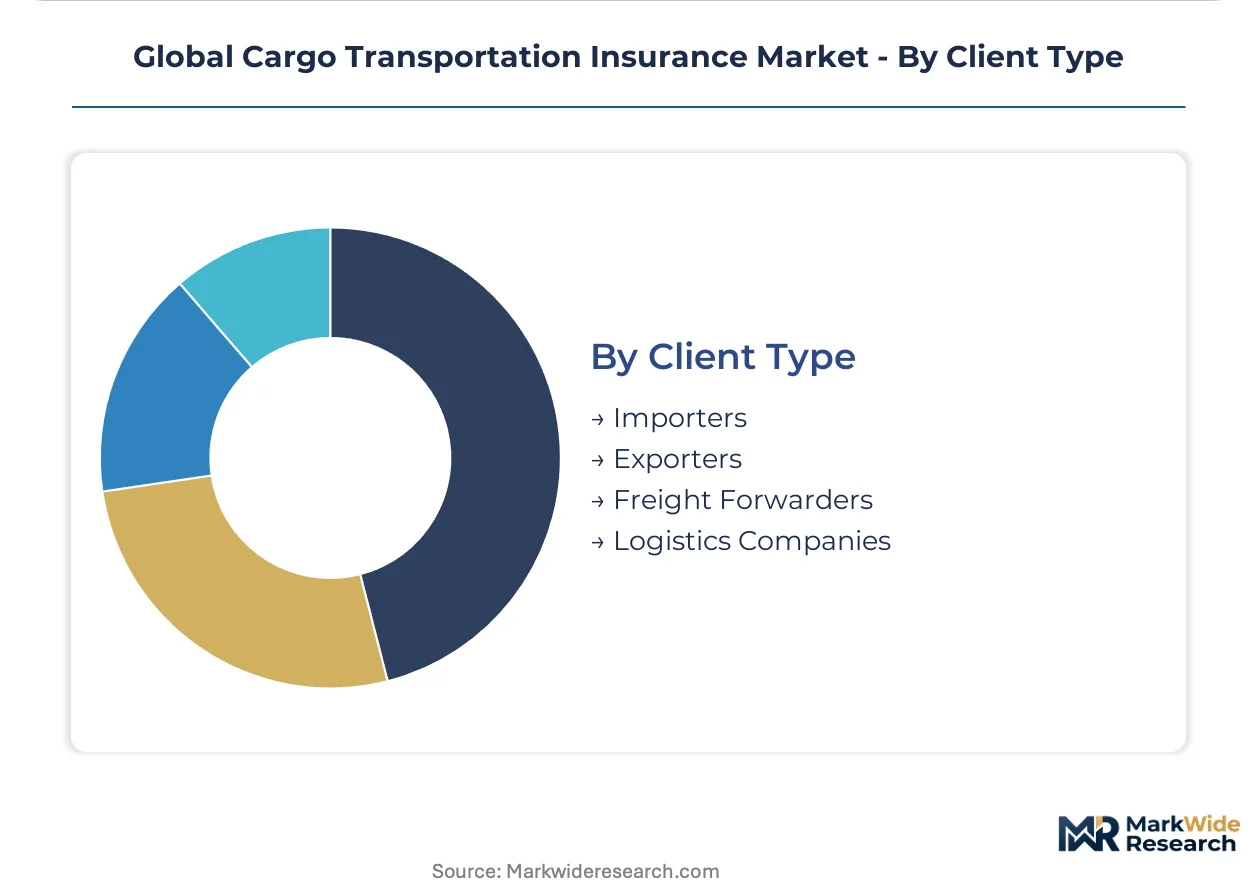
Client Type:
Customer maturity and balance sheet scale dictate service intensity, with freight intermediaries capturing disproportionate advisory value relative to direct cargo ownership.
- Logistics Companies:Asset-heavy carriers and third-party providers purchasing fleet-wide or network-level coverage. DHL and Kuehne+Nagel-scale operators in European corridors drive demand for integrated risk management services.
- Freight Forwarders:Intermediary liability and cargo interest coverage for non-asset-based logistics orchestrators. Consolidation in Asian forwarding networks is concentrating purchasing power among regional platform leaders.
- Exporters:Shipper-procured coverage protecting FOB and CIF contract obligations. Brazilian agricultural and Indonesian palm oil exporters represent volume concentration in commodity trade lanes.
- Importers:Consignee-purchased protection for inbound supply chains. US and EU retailers with China-sourced inventory dominate this segment, particularly under DDP incoterms.
Logistics Companies retain volume leadership; Freight Forwarders hold the steepest expansion curve as intermediary platforms consolidate purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China-to-Europe container flows dominate cargo insurance premium generation, with Rotterdam and Hamburg absorbing the highest claim volumes outside Asia. German automotive manufacturers and Dutch pharmaceutical distributors drive demand for intermodal coverage across these corridors.
United States
Pharmaceutical cold-chain shipments from New Jersey and Illinois generate concentrated demand for FDA-compliant coverage documentation. The FDA's import security requirements mandate verifiable insurance certificates for biologics entering through Port of Newark. Chicago's logistics cluster anchors Midwest distribution networks purchasing annual blanket policies.
Germany
Automotive component exports from Bavaria and Baden-Württemberg require seamless multimodal protection through Rotterdam-Antwerp port complexes. The EU CSRD disclosure mandates pressure DAX-listed manufacturers to document supply chain risk exposure. Hamburg's marine underwriting hub concentrates specialist capacity for complex international routes.
China
Electronics manufacturers in Shenzhen and Guangzhou purchase per-shipment coverage through embedded digital platforms. SAMR standardization on logistics service contracts tightens domestic carrier insurance compliance. Shanghai's port corridor generates the highest marine cargo policy volumes globally.
India
DGFT export incentive structures expand insurance penetration among first-time SME shippers in Maharashtra and Gujarat. The country's national pharmaceutical regulator tightens documentation requirements for active pharmaceutical ingredient exports. Mumbai's forwarding networks consolidate purchasing power among regional platform leaders.
Singapore
Asia-Europe transshipment flows concentrate risk-transfer activity at the city-state's container terminals. The Monetary Authority of Singapore's regulatory framework supports specialized marine underwriting operations. Electronics manufacturers with high-frequency rotations prioritize intermodal coverage for container handoff risk mitigation.
Global Cargo Transportation Insurance Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and geographic footprint. The market structures around three tiers: global multi-line carriers with marine divisions, Lloyd's syndicates with specialized cargo expertise, and regional underwriters focused on single-trade lanes. Strategic archetypes include scale-driven premium aggregators, niche per-shipment product innovators, and compliance-focused documentation specialists. Dominant competitive moves involve M&A to acquire marine underwriting talent and strategic partnerships with digital freight platforms.
Within the global carrier tier, AIG and Zurich Insurance Group occupy positions as archetypal scale players with established marine underwriting infrastructure. Tokio Marine Holdings represents the Asia-Pacific-focused specialist model with tailored per-shipment products. Lloyd's of London sits within the syndicate architecture as the historic center for complex international route capacity.
| Leading Market Players |
|---|
| AIG |
| Allianz Global Corporate & Specialty |
| AXA XL |
| Chubb |
| Zurich Insurance Group |
| Tokio Marine Holdings |
| Lloyd's of London |
| Liberty Mutual Insurance |
| Berkshire Hathaway Specialty Insurance |
| Others |
Supply Flow & Price Mechanics
Parametric insurance platforms replacing traditional all-risk annual policies are redrawing underwriting economics and carrier distribution geography simultaneously. Shenzhen-based digital freight platforms now embed per-shipment coverage at checkout, compressing premium collection cycles and displacing Rotterdam-anchored broker networks that historically intermediated Asia-Europe trade.
Pricing Analysis
Legacy annual-policy pricing faces structural compression from next-generation parametric and IoT-triggered products. Three-tier pricing structure across premium, standard, and economy levels separates multinational manufacturers with EU CSRD audit requirements from SME e-commerce exporters and cost-sensitive commodity traders. Price differentiation hinges on documentation grade for FDA pharmaceutical corridors and volume scale through Shanghai-Shenzhen port clusters. Margins are tightening in standardized Named Perils tiers as self-insurance spreads among Black Sea grain exporters, while All Risk premiums hold firm for intermodal electronics shipments. Cost-sensitive agricultural traders in Indian and Vietnamese corridors exhibit highest price elasticity; pharmaceutical cold-chain shippers demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Port congestion through Rotterdam and Singapore transshipment hubs elevates inbound logistics costs for underwriters maintaining localized claims infrastructure. Marine underwriting capacity concentrates in the United Kingdom, Bermuda, and Singapore, drawing from specialized actuarial talent pools and regulatory sandbox frameworks. Raw material dependencies span IoT sensor hardware from Taiwan, blockchain settlement infrastructure from Switzerland, and reinsurance capital from London and Zurich. Single-source vulnerability runs through Lloyd's syndicate capacity for complex international routes. Distribution runs through digital freight platforms in China's e-commerce corridors and traditional broker networks in European pharmaceutical trade lanes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cargo insurance is crossing into platform economics as embedded checkout integrations and API-first underwriting disaggregate policy manufacturing from distribution. Interoperability between digital freight platforms and parametric claims engines is rewiring how risk capital reaches SME exporters.
For Market Incumbents: Fortify marine underwriting scale through captive reinsurance structures in Bermuda and Singapore hubs. Incumbent carriers face substitution threat from IoT-native parametric specialists who bypass traditional risk-modeling cycles. Priority lever rests on backward integration into sensor data partnerships that enable automated claims triggering for electronics manufacturers with high-frequency Asia-Europe rotations. For New Entrants and Emerging Players: SME per-shipment procurement gaps in India's DGFT-supported export corridors offer immediate white-space access. First-time international shippers in Maharashtra and Gujarat manufacturing hubs remain underpenetrated by annual-policy infrastructure. Go-to-market execution should anchor on embedded checkout integrations with regional digital freight platforms, mirroring Shenzhen's cross-border e-commerce coverage adoption curve. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital brokerage platforms that have achieved regional density but lack global reinsurance relationships. Long-term viability in this market favors underwriters who control both parametric trigger data and claims settlement infrastructure. Signal to monitor: M&A activity targeting IoT sensor networks with maritime certification, as these represent the scarce input for next-generation per-shipment products.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Launch | IoT-triggered coverage captures electronics manufacturers with time-sensitive Asia-Europe shipments. |
| Digital Platform Integration | API-first underwriting embeds per-shipment products into Shenzhen freight marketplace checkout flows. |
| Specialist Firm Acquisition | Marine actuarial talent scarcity makes Lloyd's syndicate underwriting teams prime consolidation targets. |
| Regulatory Sandbox Expansion | Monetary Authority of Singapore frameworks enable faster parametric product approval for regional trade lanes. |
| Backward Integration into Sensor Networks | Captive IoT data streams reduce claims adjudication friction for pharmaceutical cold-chain shippers. |
Methodological Framework
Cross-validation between Lloyd's market underwriting data and Chinese SAMR logistics contract filings anchors the qualitative findings. Primary interviews with marine underwriting directors, digital freight platform executives, pharmaceutical supply chain managers, and EU regulatory compliance officers combined with secondary validation from customs trade statistics, SEC insurer filings, and port authority throughput disclosures. Bottom-up policy volume estimates triangulate against top-down premium generation models across the analysis window.
Sensitivity analysis on climate stress test scenarios and parametric adoption curves shapes the forecast framework. Segmentation dimensions modeled include insurance type tier, policy duration structure, coverage scope geography, and client sophistication level. CAGRs derive from premium volume trajectories calibrated to Shanghai and Shenzhen port corridor expansion rates, EU CSRD disclosure mandate compliance timelines, and SME e-commerce exporter penetration curves in India and Southeast Asia.
Underlying assumptions cover stable reinsurance capacity availability and gradual parametric product adoption, with deviation risk concentrated in extreme weather frequency acceleration and regulatory fragmentation between China's SAMR standardization and EU disclosure frameworks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
United Kingdom Health and Medical Insurance Market
Insurance
Cloud Computing in Insurance Market
Insurance
Global Home Insurance Market
Insurance
Entertainment Insurance Market
Insurance
Insurance Third Party Administrators Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Global Mobile Phone Insurance Ecosystem Market
Insurance
Digital Insurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
Aviation Insurance Market
Insurance
Canada Home Insurance Market
Insurance
IoT Insurance Market
Insurance
Jewelry Insurance Market
Insurance
Road Assistance Insurance Market
Insurance
Africa Insurance Market
Insurance
MENA Health and Medical Insurance Market