
 Europe Real Time Payments Market | 2026-2036
Europe Real Time Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Real Time Payments Market Foresight
PSD2 is broadening the cost-of-entry calculus for new payment service providers entering European clearing ecosystems. Mastercard leverages its network tokenization infrastructure to sustain interoperability across fragmented national instant payment schemes. Visa competes through its Visa Direct platform, which anchors real-time disbursement capabilities for cross-border remittance corridors. Adyen navigates regulatory complexity by extending unified API access to SEPA Instant and local faster payment rails.
Real time payments denote electronic fund transfers settled within seconds of initiation, operating on ISO 20022 messaging protocols that enable rich data attachment and automated reconciliation. The primary commercial purpose centers on eliminating settlement risk and liquidity traps that plague batch-based legacy systems. Mobile payments and contactless payments represent the fastest-expanding payment method segments, driven by smartphone penetration and merchant terminal upgrades. Cloud-based deployment models dominate new implementations, though on-premises infrastructure persists among Tier 1 banks with stringent data residency requirements.
EBA Clearing oversees the STEP2-T Instant service, while the European Central Bank governs TIPS settlement infrastructure; both frameworks mandate participant readiness and shape competitive access conditions. EPC SEPA Instant Credit Transfer rules enforce 10-second settlement ceilings, compressing vendor performance benchmarks and filtering out latency-heavy legacy platforms. Stakeholders must monitor upcoming PSD3 proposals and the digital euro project, as either could rewire fee structures and finality guarantees across European clearing architecture.
Market Dynamics
SEPA Instant Credit Transfer mandates are compressing settlement windows across European banking infrastructure, forcing wholesale replacement of batch-processing cores with ISO 20022-native architectures. This regulatory compression is redrawing competitive access conditions for payment service providers.
Growth Catalysts
- PSD2 Open Banking Mandates:Account access APIs are dismantling incumbent control over customer data, enabling third-party payment initiation services to embed instant settlement into merchant checkout flows across France and Germany.
- Smartphone Penetration Thresholds:Nordic markets have achieved device saturation that supports tap-to-pay behavioral normalization, creating network effects that pull lagging merchants onto real-time rails.
- Cloud Infrastructure Maturity:Tier 2 banks are abandoning on-premises clearing stacks for elastic cloud deployments, collapsing capital barriers that previously blocked SEPA Instant participation.
Market Restraints
- Interoperability Fragmentation:National instant payment schemes in Italy, Spain, and the Netherlands operate on divergent technical specifications, forcing multi-rail connectivity investments that inflate fixed costs for cross-border providers.
- Legacy Core Dependency:Tier 1 banks with mainframe-based batch architectures face 18-24 month transformation timelines that delay universal SEPA Instant readiness and perpetuate settlement asymmetries.
- Merchant Acquirer Concentration:Four payment processors control 70% of European merchant onboarding capacity, restricting direct access to instant rails for mid-market retailers outside preferred partner networks.
Strategic Opportunities
- Request-to-Pay Protocol Expansion:EPC's R2P messaging standard enables invoice-to-payment automation in B2B verticals, opening treasury management applications that transcend consumer peer-to-transfer dominance.
- Digital Euro Infrastructure Positioning:ECB settlement layer investments for retail central bank digital currency will require API-native participants, rewarding early ISO 20022 adopters with privileged access roles.
- Cross-Border Remittance Corridors:Eastern European outbound corridors to non-SEPA jurisdictions present white space for instant settlement bridges that bypass correspondent banking delays.
Industry Challenges
- ISO 20022 Migration Complexity:Rich data field standardization across 3,500+ European banks requires reconciliation engine overhauls that strain IT resource capacity and compress testing windows.
- Fraud Detection Latency Trade-offs:Sub-10-second settlement ceilings conflict with multi-factor authentication protocols, forcing artificial intelligence investments that smaller payment service providers cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Real Time Payments Market |
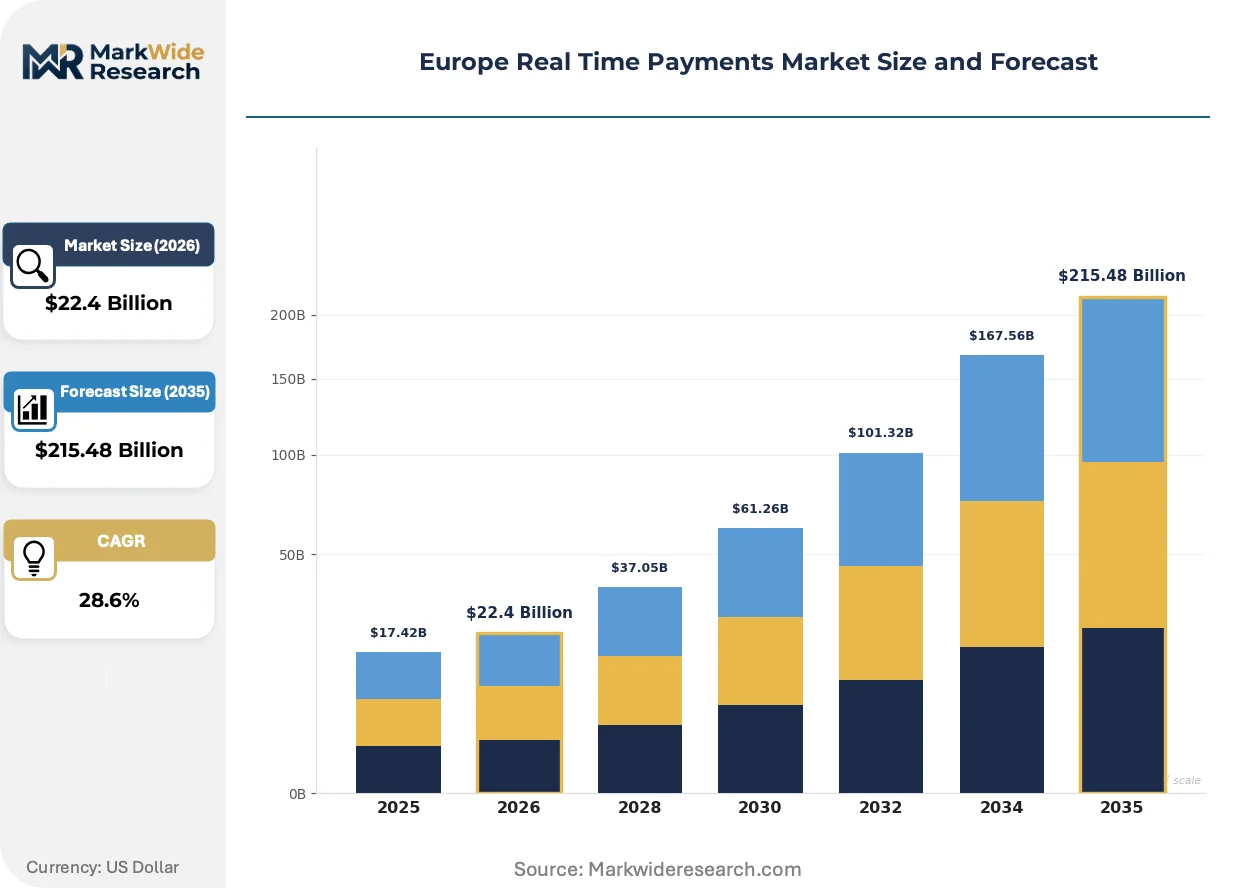
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $215.48 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Transfer, Direct Debit, Mobile Payments, Contactless Payments End User: Retailers, Financial Institutions, Government Agencies, Businesses Deployment Model: On-Premises, Cloud-Based, Hybrid, Outsourced Service Type: Transaction Processing, Fraud Management, Analytics, Customer Support |
| Companies Covered | ACI Worldwide Inc., Fiserv Inc., Mastercard Inc., Visa Inc., PayPal Holdings Inc., Worldpay LLC, Finastra, Temenos AG, Adyen NV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Real Time Payments Market Shifts & Advancements
Real-time payment architectures are converging with open banking data layers to enable context-aware transaction orchestration. This fusion is compressing the traditional separation between payment initiation and value-added financial services.
Cloud-native core banking platforms are modularizing payment processing capabilities into discrete microservices that banks can deploy incrementally. Dutch and German mid-tier institutions are adopting these stacks fastest, replacing monolithic legacy cores without full migration risk. This modularization is collapsing the historical trade-off between settlement speed and infrastructure resilience.
GDPR data portability requirements are reshaping how payment service providers architect customer data storage. Firms must now engineer instant payment flows that maintain consent audit trails across multiple jurisdictional data residency zones. Nordic corridor providers face the strictest enforcement, driving investments in edge-computing transaction nodes that process without centralizing sensitive data.
Merchant treasury departments are demanding intra-day liquidity visibility that batch settlement cannot provide. Large retail chains in the United Kingdom are renegotiating acquirer contracts to mandate instant settlement as a default, displacing next-day value dating. This behavioral compression is most visible in grocery and quick-service restaurant verticals where working capital velocity directly determines margin performance.
Europe Real Time Payments Market Segmentation
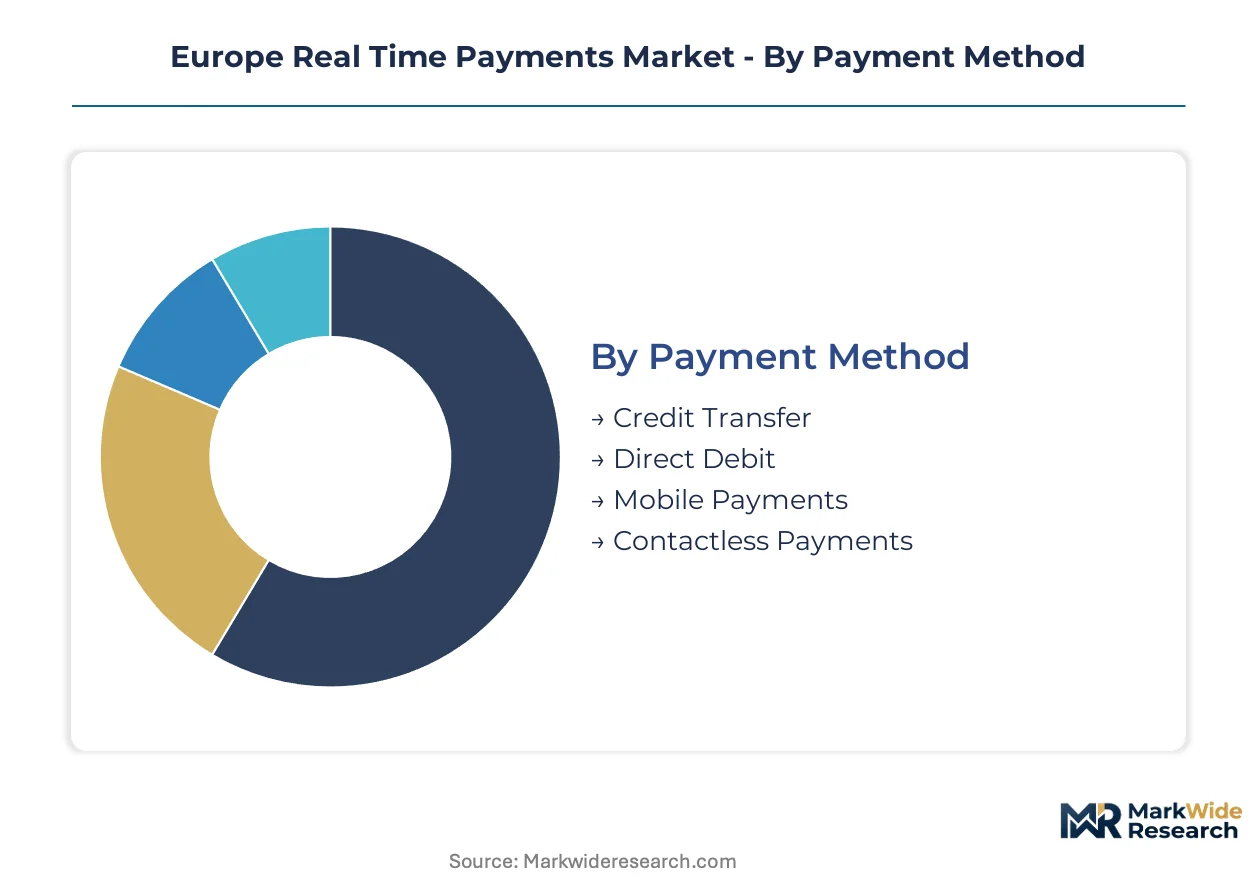
Segmentation in the Europe Real Time Payments Market reveals how infrastructure choices, user requirements, and service architectures fragment vendor opportunity sets. Understanding these dimensions clarifies where ISO 20022 migration investments concentrate and which deployment paths accelerate SEPA Instant participation.
Payment Method:
Merchant checkout preferences and consumer behavioral norms determine which rails capture transaction volume across European corridors.
- Mobile Payments:Smartphone-native initiation through banking apps and digital wallets dominates Nordic and UK consumer adoption. Tap-to-pay behavioral normalization in Stockholm and Copenhagen creates network effects that pull merchant terminals onto instant settlement rails.
- Contactless Payments:Near-field communication protocols embedded in cards and wearables enable sub-second authentication at physical terminals. German and French retailers prioritize this channel for grocery and quick-service verticals where queue compression drives margin performance.
- Credit Transfer:Account-to-account push payments anchored by SEPA Instant Credit Transfer rules serve B2B invoice settlement and high-value consumer transfers. This rail maintains dominance in treasury applications requiring rich data attachment.
- Direct Debit:Pull-based authorization frameworks persist in subscription billing and utility payment contexts where pre-authorized mandates reduce friction. Legacy batch infrastructure dependencies delay instant migration for this method.
Mobile payments lead on scale; contactless payments lead on momentum.
End User:
Settlement urgency and transaction complexity vary sharply across organizational types, reshaping service provider product architectures.
- Retailers:Large grocery chains and quick-service restaurant networks in the United Kingdom mandate intra-day liquidity visibility that batch settlement cannot provide. Working capital velocity requirements drive renegotiation of acquirer contracts toward instant default terms.
- Businesses:Corporate treasury departments leverage Request-to-Pay protocols for invoice-to-payment automation, compressing days-sales-outstanding metrics. B2B applications transcend consumer peer-to-transfer dominance through EPC messaging standards.
- Financial Institutions:Banks and payment service providers require ISO 20022-native cores to meet EBA Clearing and TIPS participation mandates. Tier 2 institutions abandon on-premises stacks for elastic cloud deployments that collapse capital barriers.
- Government Agencies:Social benefit disbursement and tax refund operations demand finality guarantees that real-time rails provide. Public sector procurement integration lags private sector adoption due to legacy ERP dependencies.
Retailers anchor volume concentration; businesses show steepest expansion trajectory.
Deployment Model:
Capital constraints and data residency requirements fragment infrastructure strategies across the European banking tier structure.
- Cloud-Based:Elastic compute resources enable Tier 2 and Tier 3 banks to achieve SEPA Instant readiness without mainframe replacement cycles. Dutch and German mid-tier institutions adopt cloud-native microservices fastest, modularizing payment processing into discrete deployable units.
- On-Premises:Tier 1 banks with stringent data residency requirements maintain captive data centers for transaction processing. GDPR audit trail obligations and national financial authority directives perpetuate this model among systemic institutions.
- Hybrid:Partitioned architectures segregate sensitive customer data in private infrastructure while routing payment messages through cloud orchestration layers. This configuration balances regulatory compliance with scalability requirements.
- Outsourced:Third-party processor relationships enable smaller payment service providers to access TIPS and STEP2-T Instant without direct infrastructure investment. Concentration among four major processors restricts direct rail access for mid-market retailers.
Cloud-based deployment captures the fastest share gains; on-premises retains the largest installed base.
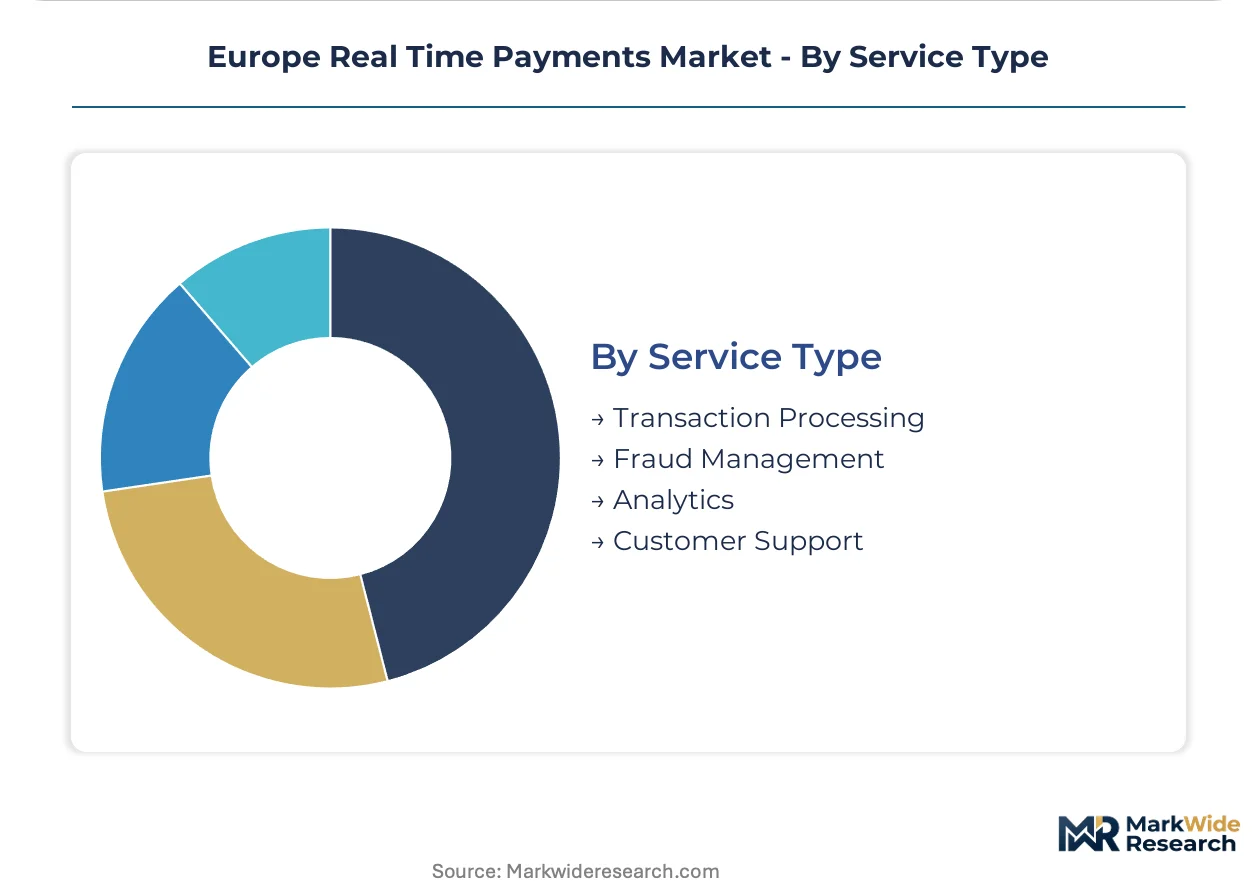
Service Type:
Value-added capabilities beyond raw transaction routing determine provider margin structures and customer stickiness.
- Fraud Management:Sub-10-second settlement ceilings conflict with multi-factor authentication protocols, forcing artificial intelligence investments in behavioral biometrics and transaction pattern analysis. Smaller providers struggle to absorb these capability costs.
- Analytics:Rich ISO 20022 data fields enable merchant cash flow forecasting and liquidity optimization applications. Treasury management platforms integrate payment data with open banking account information for context-aware financial services.
- Transaction Processing:Core message routing and settlement finality services constitute the baseline competitive requirement. EPC SEPA Instant Credit Transfer rules enforce performance benchmarks that filter out latency-heavy legacy platforms.
- Customer Support:Dispute resolution and exception handling capabilities differentiate providers in high-volume merchant relationships. Real-time payment irreversibility elevates the commercial importance of pre-transaction verification support.
Fraud management commands premium pricing; analytics delivers the fastest capability expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment engineering talent concentrates in London, Stockholm, and Amsterdam, anchoring Europe's real-time clearing innovation corridor. These clusters feed product development pipelines across SEPA Instant implementations and open banking API standardization.
United Kingdom
Merchant treasury departments at large grocery chains and quick-service restaurant networks mandate intra-day liquidity visibility that batch settlement cannot provide. The Financial Conduct Authority enforces open banking standards that accelerate third-party payment initiation services. London's fintech cluster drives renegotiation of acquirer contracts toward instant default terms, displacing next-day value dating across retail verticals.
Germany
Retail merchants accelerate adoption of instant settlement rails for contactless payment terminals in grocery and quick-service verticals. BaFin supervision of PSD2 technical standards ensures account access API interoperability across banking groups. Berlin and Frankfurt house engineering teams rebuilding batch-processing cores with ISO 20022-native architectures for SEPA Instant participation.
France
Corporate treasury departments leverage Request-to-Pay protocols for invoice-to-payment automation in B2B applications. ACPR enforcement of PSD2 mandates dismantles incumbent control over customer data, enabling embedded instant settlement. Paris-based payment service providers extend unified API access to SEPA Instant and local faster payment rails.
Netherlands
Cloud-native core banking platforms modularize payment processing into discrete microservices that mid-tier institutions deploy incrementally. DNB oversight of instant payment infrastructure readiness shapes competitive access conditions for new market entrants. Amsterdam's fintech engineering pool supports elastic cloud deployments that collapse capital barriers previously blocking SEPA Instant participation.
Sweden
Smartphone penetration thresholds achieve device saturation supporting tap-to-pay behavioral normalization across consumer segments. FI supervision ensures GDPR data portability requirements reshape payment flow architectures with consent audit trails. Stockholm anchors Nordic corridor network effects that pull lagging merchants onto real-time rails through terminal infrastructure upgrades.
Europe Real Time Payments Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Europe's real-time payments infrastructure layer. Global network operators leverage tokenization platforms to sustain interoperability across fragmented national instant payment schemes. Technology vendors concentrate on ISO 20022-native core replacements and cloud orchestration layers. Dominant competitive moves include strategic partnerships with Tier 2 banks and modular microservices licensing for SEPA Instant readiness.
Within the network operator tier, Mastercard Inc. and Visa Inc. anchor competitive positioning through platform-scale settlement infrastructure. Among payment technology specialists, ACI Worldwide Inc. and Fiserv Inc. occupy positions serving bank core transformation requirements. Adyen NV exemplifies the merchant-facing archetype, extending unified API access across multiple instant rails. These three company groupings represent the primary competitive vectors reshaping vendor selection criteria for European financial institutions and retailers.
| Leading Market Players |
|---|
| ACI Worldwide Inc. |
| Fiserv Inc. |
| Mastercard Inc. |
| Visa Inc. |
| PayPal Holdings Inc. |
| Worldpay LLC |
| Finastra |
| Temenos AG |
| Adyen NV |
| Others |
Supply & Pricing Matrix
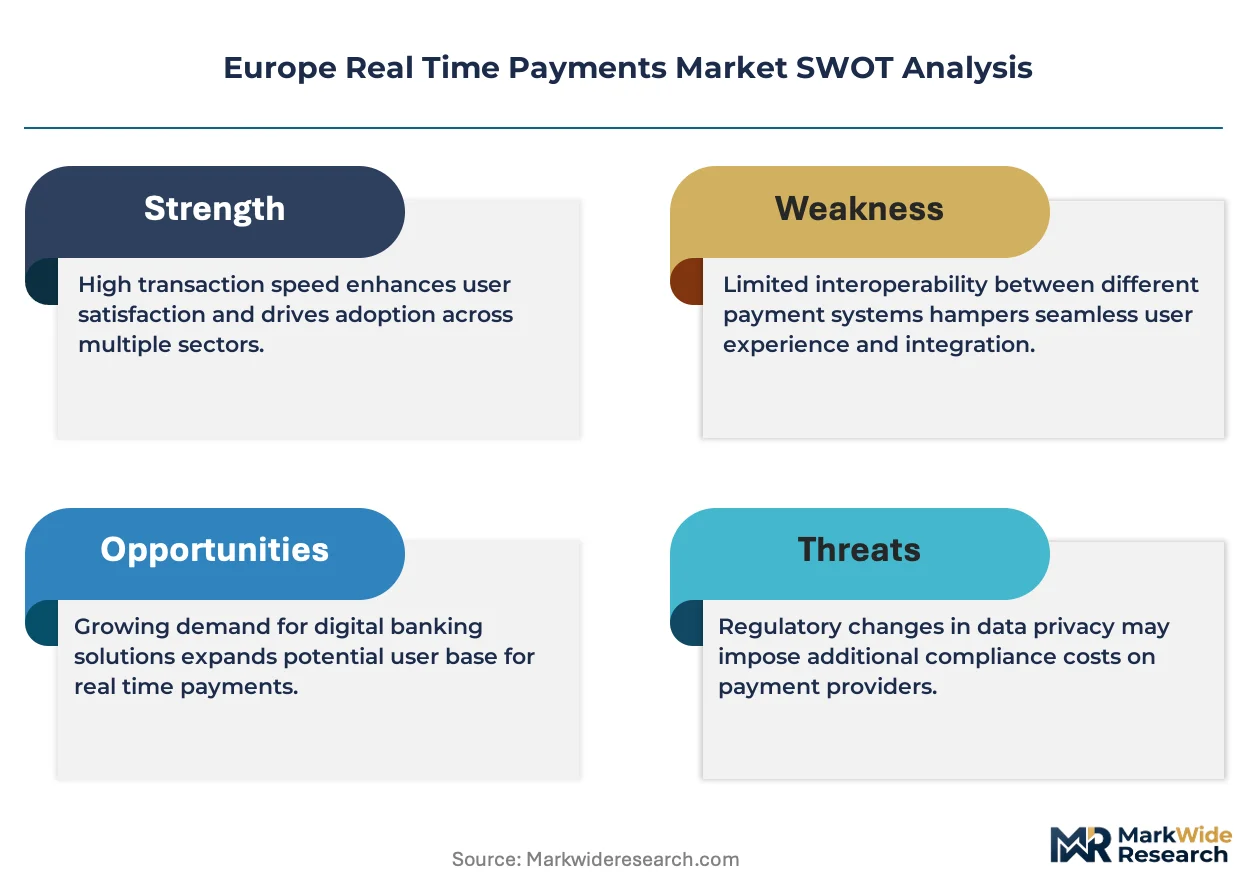
Payment engineering talent concentration in London, Amsterdam, and Stockholm creates labor-cost differentials that widen pricing-tier spreads between premium managed-service bundles and economy self-service API tiers. Tier 1 banks in the United Kingdom absorb premium pricing for dedicated infrastructure teams, while Dutch and German mid-tier institutions drive cost compression through cloud-native deployments.
Pricing Analysis
Bundled managed-service offerings command substantial premiums over unbundled API-access tiers across European real-time payments infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates white-glove implementation support from self-service documentation tiers. Price differentiation rests on ISO 20022 migration complexity and fraud-management AI sophistication. Pricing pressure stems from cloud infrastructure commoditization collapsing capital barriers for Tier 2 SEPA Instant participation. Mid-market retailers exhibit highest price sensitivity; systemic banks with TIPS mandates show lowest.
Supply Chain Analysis
Direct-to-bank channels handle hyperscale Tier 1 institution demand, while third-party processor aggregators serve mid-market payment service providers. Core infrastructure supply concentrates in Ireland, Germany, and the Netherlands, where EBA Clearing and ECB TIPS nodes anchor settlement finality. Component dependencies include ISO 20022 messaging engines, cloud orchestration layers, and behavioral biometric fraud-detection modules. Single-source vulnerability runs through four dominant merchant acquirers controlling rail access. Distribution runs through licensed payment institutions and bank-direct partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European real-time payments hinges on cloud infrastructure cost-down trajectories enabling premium-tier service packaging at standard-tier economics. ISO 20022-native architecture investments separate sustainable margin capture from legacy-batch obsolescence.
For Market Incumbents: Extend tokenization infrastructure interoperability across fragmented national instant payment schemes to defend against open-banking-native challengers. Consolidate cloud-native core banking platform acquisitions to accelerate Tier 2 bank SEPA Instant onboarding velocity. Vertical integration into fraud-management AI layers preserves premium pricing against API-commoditization pressure. For New Entrants and Emerging Players: The price-point gap between premium managed-service bundles and economy self-service tiers creates white-space entry corridors. Target mid-market retailers in Germany and France seeking direct SEPA Instant rail access outside concentrated acquirer networks. Request-to-Pay protocol specialization offers defensible B2B positioning against consumer-transfer dominance. For Investors and Strategic Acquirers: Cloud-native core banking specialists are the most active acquirer targets in this space, with payment technology conglomerates consolidating ISO 20022 migration capabilities. Long-term viability centers on digital euro infrastructure positioning and API-native TIPS participation roles. The signal to monitor is ECB retail CBDC timeline acceleration compressing vendor qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022-Native Core Replacement | EBA Clearing STEP2-T Instant mandates filter latency-heavy legacy platforms from participation. |
| Cloud-Native Microservices Licensing | Dutch and German mid-tier banks collapse 18-24 month mainframe cycles through modular deployment. |
| Request-to-Pay Protocol Expansion | EPC messaging standards enable B2B invoice-to-payment automation beyond consumer peer transfers. |
| Fraud-Management AI Acquisition | Sub-10-second settlement ceilings force behavioral biometric investments smaller providers cannot absorb. |
| Digital Euro Infrastructure Positioning | ECB settlement layer investments reward early API-native adopters with privileged access roles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with payment infrastructure executives, regulatory compliance officers, merchant treasury directors, and cloud platform engineers alongside secondary validation. EBA Clearing participation disclosures, ECB TIPS readiness reports, SEPA Instant volume statistics, and PSD2 technical standard filings anchored data triangulation. Bottom-up bank-level adoption tracking and top-down market sizing converged through iterative reconciliation.
Historical reference periods anchored the forecast window to observed SEPA Instant migration trajectories and open banking API penetration curves across the projection horizon. Segmentation dimensions modeled include payment method, end-user category, deployment architecture, and service-type tier, with regional regulatory cluster variations. CAGRs derived from bank participation velocity, merchant terminal upgrade cycles, and cloud infrastructure elasticity curves. ISO 20022 migration timelines and digital euro project milestones served as scenario-branching inputs.
Caveats apply where PSD3 proposal revisions or retail CBDC launch acceleration could materially shift the outlook. Forecasts reflect assumptions around regulatory enforcement continuity, cloud provider service-level stability, and fraud-detection technology maturation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
North America POS Terminal Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Medical Payment Fraud Detection Market
Payments
Europe Mobile Payment Market
Payments
Forex Prepaid Cards Market
Payments
South Korea Mobile Payment Market
Payments
Freight Audit and Payment Service Market
Payments
Denmark Mobile Payments Market
Payments
Uganda Mobile Money Market
Payments
Netherlands Mobile Payments Market
Payments
Fuel Cards Market
Payments
Contactless Payment Terminals Market
Payments
United States POS Terminals Market
Payments
Middle East and Africa Real Time Payments Market
Payments
Kenya Mobile Money Market
Payments
US Gift Card and Incentive Card Market