
 Saudi Arabia Health Insurance Market | 2026-2036
Saudi Arabia Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Health Insurance Market Intelligence
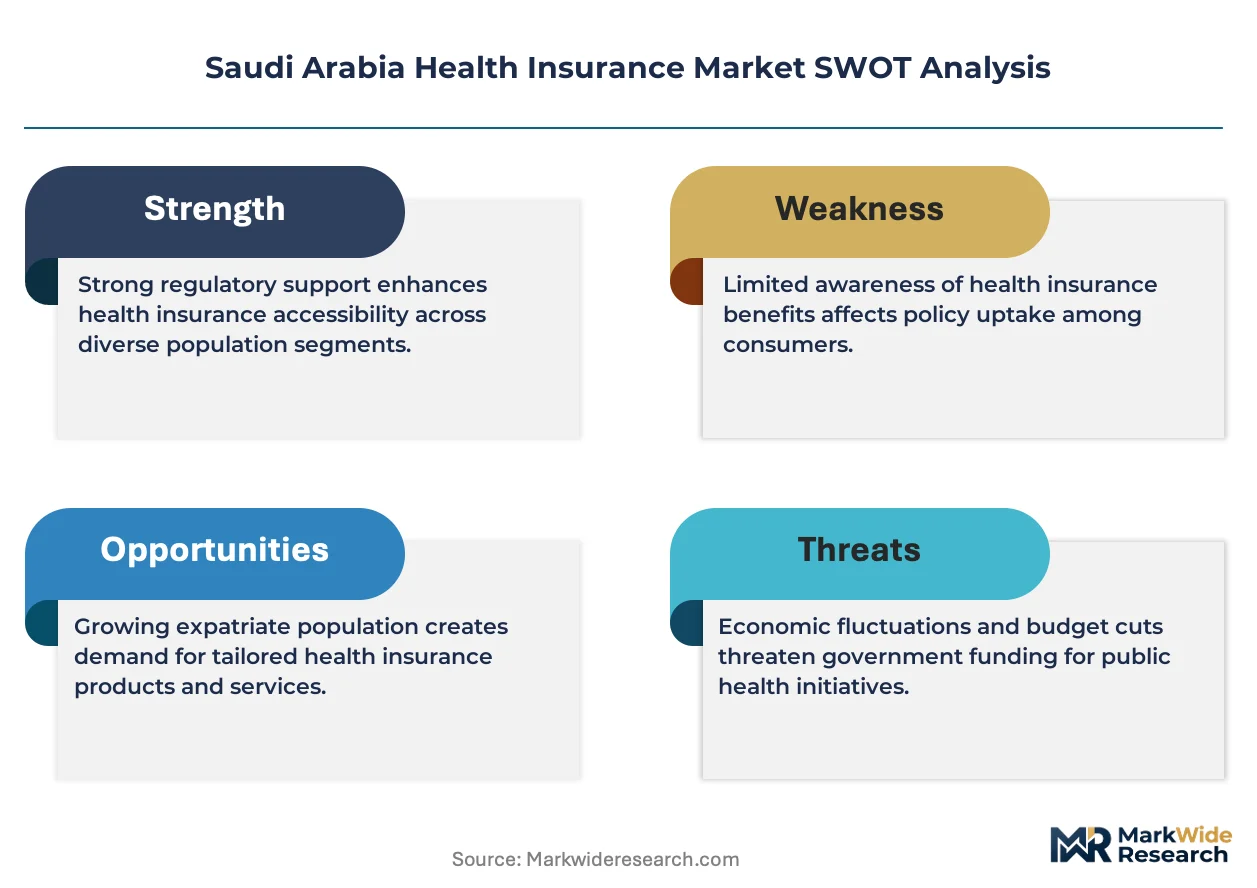
Consolidation among large employer sponsors is repositioning purchasing power toward corporate brokers and third-party administrators. Bupa Arabia for Cooperative Insurance leverages its digital-first platform to sustain retention among multinational clients. Tawuniya anchors the compulsory insurance segment through its dominance in expatriate health coverage mandated by the Council of Health Insurance. Al Rajhi Company for Cooperative Insurance competes on Shariah-compliant product lines that occupy a distinct niche in family-oriented plans.
Saudi Arabia health insurance constitutes risk-pooling financial instruments designed to cover medical expenditures through premium contributions, with policies specifying deductibles, co-payment ratios, and network hospital tiers that determine reimbursement levels. The primary commercial purpose centers on mitigating catastrophic healthcare costs for individuals while enabling employers to attract talent through benefits packages. Group Plans command the largest premium volume due to mandatory employer obligations under the Cooperative Health Insurance Law, while Top-up Plans represent the fastest-growing category as affluent consumers seek private room coverage and international treatment access beyond basic mandated benefits. Comprehensive Coverage captures the widest margin pool by bundling outpatient, inpatient, and dental services into single premium structures.
The Council of Health Insurance enforces mandatory participation and benefit minimums that shape product design across all licensed carriers, while SAMR oversees solvency ratios and consumer protection standards. The country's national pharmaceutical regulator influences drug reimbursement lists that directly impact claims costs and premium calculations. Stakeholders must monitor evolving minimum benefit mandates and digital claims interoperability requirements as the regulator pushes toward real-time adjudication systems.
Market Dynamics
The Council of Health Insurance is tightening mandatory participation rules for small and medium enterprises, compressing enrollment timelines and forcing carriers to reconfigure group policy administration systems.
Growth Catalysts
- Expatriate Coverage Mandates:The Council of Health Insurance enforces compulsory health coverage for all foreign workers, creating a captive demand pool that carriers must serve.
- Digital Claims Platforms:Real-time adjudication systems are reducing processing friction and accelerating premium collection cycles across employer-sponsored plans.
- Riyadh-Jeddah Corporate Clustering:Concentration of multinational headquarters in these cities concentrates purchasing power and simplifies broker distribution economics.
Market Restraints
- Medical Cost Inflation:Rising hospital service charges and pharmaceutical reimbursement rates compress underwriting margins across comprehensive coverage products.
- Broker Channel Concentration:Dependence on corporate intermediaries for group plan distribution limits direct carrier relationships with end employers.
- Basic Benefit Floor Constraints:Council-mandated minimum coverage standards prevent product differentiation at the entry tier and cap price competition.
Strategic Opportunities
- Top-up Plan Penetration:Affluent Saudi households seeking private room coverage and international treatment access represent an underserved premium segment beyond compulsory benefits.
- Telehealth Integration:Remote consultation platforms converging with claims systems enable outpatient cost containment and member retention improvements.
- Eastern Province Expansion:Industrial zones around Dammam and Khobar host underserved expatriate workforces outside the Riyadh-Jeddah corridor.
Industry Challenges
- Legacy System Migration:Carriers must integrate real-time adjudication capabilities with decades-old policy administration platforms without disrupting active enrollment periods.
- Actuarial Talent Scarcity:Shortage of professionals experienced in both Shariah-compliant cooperative models and predictive analytics limits pricing sophistication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Health Insurance Market |
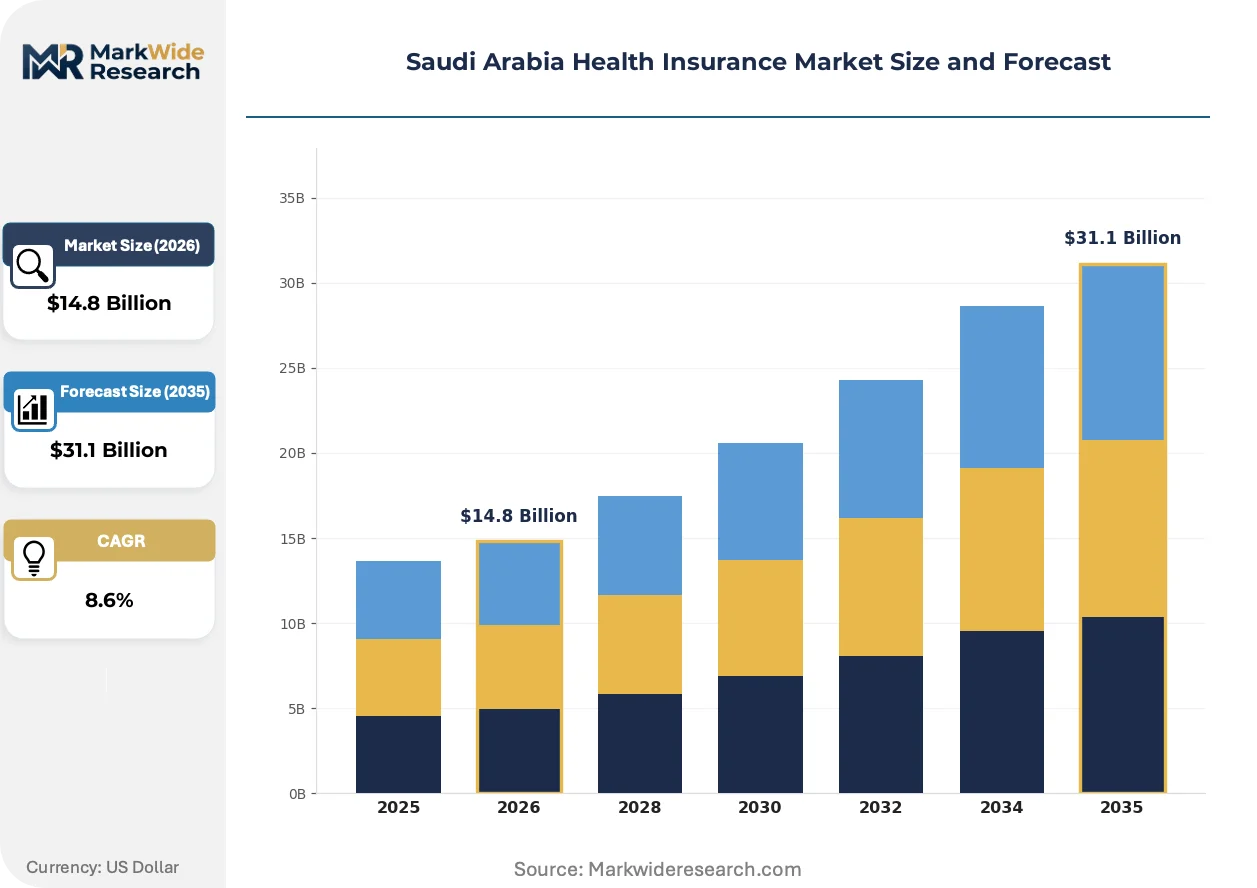
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Individual Plans, Group Plans, Family Floater, Top-up Plans Provider Type: Public Sector, Private Sector, Compulsory Insurance, Voluntary Insurance Claim Type: Outpatient, Inpatient, Emergency, Maternity Coverage Type: Comprehensive, Basic, Supplementary, Catastrophic |
| Companies Covered | Al Rajhi Company for Cooperative Insurance, Walaa Cooperative Insurance, Bupa Arabia for Cooperative Insurance, Allianz Saudi Fransi Cooperative Insurance Company, Malath Cooperative Insurance & Reinsurance Company, Tawuniya (The Company for Cooperative Insurance), Saudi Arabian Cooperative Insurance Company (SAICO), GIG Saudi (Gulf Insurance Group), MedGulf (Mediterranean & Gulf Cooperative Insurance & Reinsurance), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Health Insurance Market Strategic Shifts & Innovations
Digital infrastructure investment is compressing claims cycles from weeks to hours, while regulatory pressure on minimum benefits and buyer demand for flexibility are reshaping product architecture across the sector.
Artificial intelligence-powered fraud detection is electrifying claims verification workflows. Large carriers deploy machine learning models to flag anomalous billing patterns before payment authorization. The technology is electrifying cost containment capabilities and forcing smaller competitors to outsource verification or accept higher loss ratios.
The Council of Health Insurance is mandating interoperable electronic health record connectivity between carriers and providers. This regulation eliminates paper-based pre-authorization processes and accelerates treatment approvals. Group plan administrators in Riyadh and Jeddah are responding by renegotiating hospital network contracts to include real-time data exchange clauses.
Corporate benefits managers are unbundling traditional comprehensive packages into modular components. Employers now select inpatient, outpatient, and dental modules separately rather than accepting standardized bundles. This pattern is most visible among technology and professional services firms in Riyadh's King Abdullah Financial District, where talent competition drives customization demands.
Saudi Arabia Health Insurance Market Segmentation
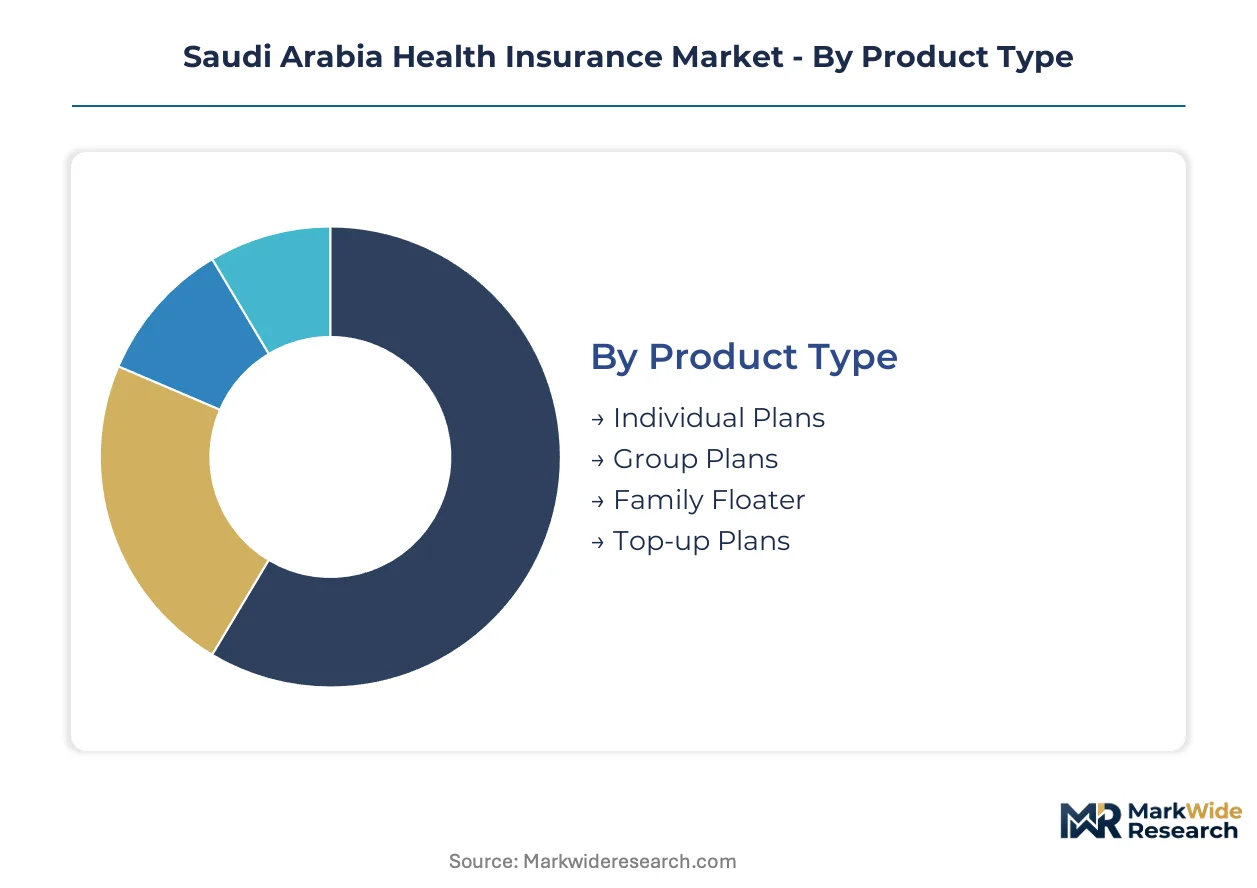
Product architecture in the Saudi Arabia health insurance market stratifies around employer mandates, household structures, and risk layering preferences. Carrier profitability depends on precise alignment between segment design and the Council of Health Insurance's evolving benefit floors.
Product Type:
Standalone products dominate employer procurement, while embedded family riders and voluntary top-ups extend coverage depth without policy replacement.
- Group Plans:Employer-sponsored policies covering employee cohorts under Cooperative Health Insurance Law mandates. Riyadh-based multinational headquarters drive volume concentration through broker-mediated procurement of standardized corporate packages.
- Individual Plans:Retail policies purchased by self-employed professionals and uncovered Saudi nationals outside employer networks. Jeddah's consultant and entrepreneur population sustains demand for personalized benefit schedules.
- Family Floater:Shared sum-insured structures covering multiple dependents under single premium payments. Saudi households in Eastern Province industrial zones favor this format for dependent coverage flexibility.
- Top-up Plans:Supplementary layers activating after base policy exhaustion. Affluent consumers seeking private room access and international treatment options are expanding this segment most rapidly.
Group Plans lead volumes today; Top-up Plans are gaining share fastest.
Provider Type:
Regulatory origin determines capital requirements, distribution constraints, and permissible investment vehicles across the carrier landscape.
- Compulsory Insurance:Mandated coverage pools administered under Council of Health Insurance supervision. Expatriate worker enrollment in Dammam-Khobar industrial corridors sustains this segment's premium base.
- Private Sector:Commercial cooperative insurers competing on network breadth and digital service quality. Bupa Arabia and Tawuniya anchor this tier through differentiated platform investments.
- Public Sector:Government-backed schemes covering civil servants and military personnel. Ministry of Finance payroll integration enables direct premium deduction at scale.
- Voluntary Insurance:Opt-in coverage beyond statutory minimums, including dental and optical riders. Technology sector employers in King Abdullah Financial District are expanding this category through benefits customization.
Compulsory Insurance dominates enrollment counts; Private Sector cooperative models capture the widest margin expansion.
Claim Type:
Service setting shapes reimbursement velocity, fraud exposure, and provider network negotiation leverage for carriers.
- Inpatient:Hospital admission claims involving room charges, surgical procedures, and intensive care. High-value reimbursements concentrate in Riyadh's tertiary medical centers where corporate plan members access specialized treatment.
- Outpatient:Clinic consultations, diagnostics, and pharmacy dispensing without admission. Real-time adjudication platforms are compressing processing cycles for this high-frequency, low-value category.
- Emergency:Unscheduled acute care interventions requiring immediate authorization. 24-hour helpline integration with hospital networks reduces claim disputes and accelerates settlement.
- Maternity:Prenatal, delivery, and postnatal service bundles. Saudi national families prioritize this coverage tier, driving carrier competition on network obstetrics quality.
Outpatient claims process in highest volume; Inpatient claims absorb the largest share of total disbursements.
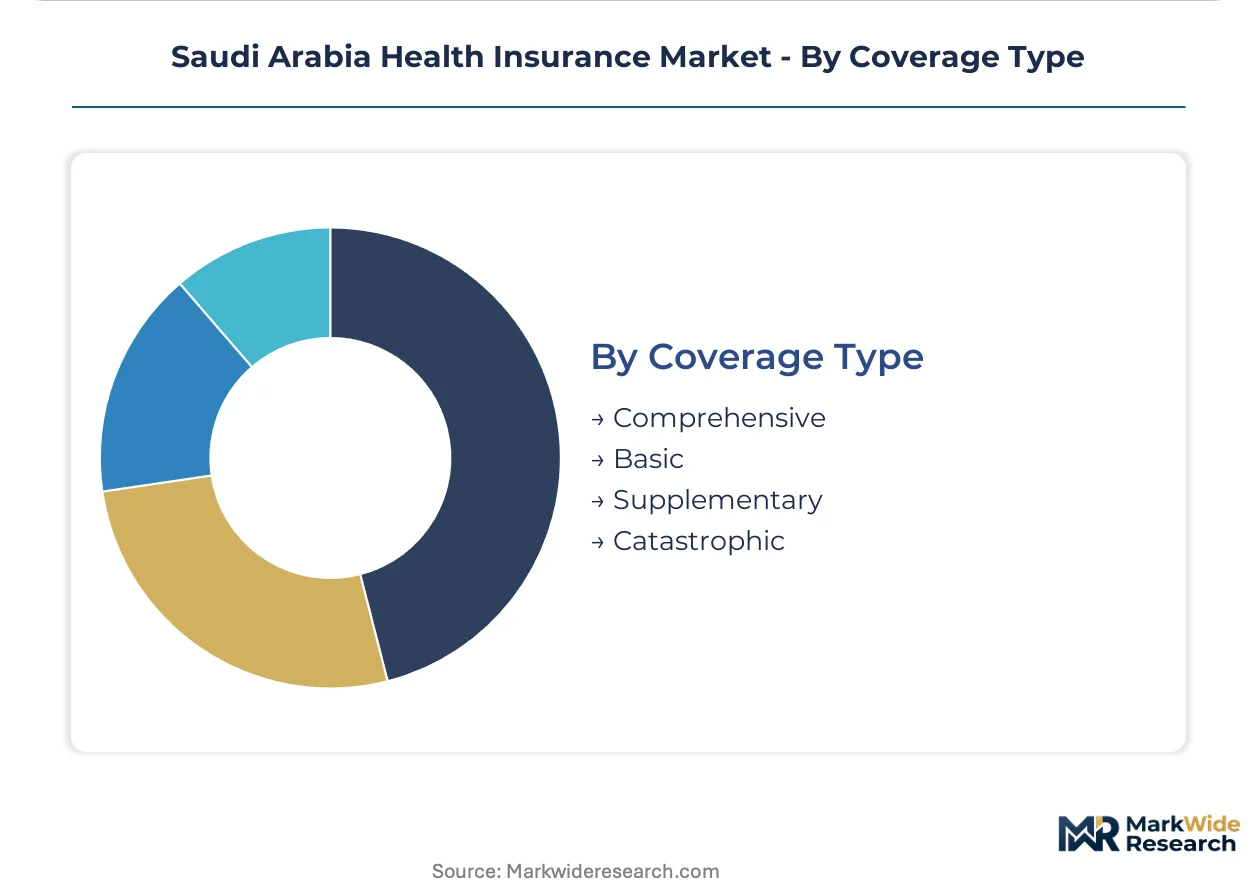
Coverage Type:
Benefit depth tiers separate catastrophic protection from routine care financing, with regulatory floors preventing bare-bones competition.
- Comprehensive:Bundled inpatient, outpatient, dental, and pharmaceutical coverage under unified premium structures. Corporate benefits managers in Jeddah's port and logistics sector favor this format for administrative simplicity.
- Basic:Council-mandated minimum benefits covering essential hospitalization and emergency services. Price competition is constrained by regulatory benefit floors that prevent undercutting.
- Supplementary:Add-on modules for vision, dental, and wellness services unbundled from core medical coverage. Modular procurement trends in professional services firms are expanding this category.
- Catastrophic:High-deductible structures activating for severe illness and prolonged hospitalization. Expatriate construction workers in remote project sites utilize this tier for cost-controlled major event protection.
Comprehensive Coverage commands premium concentration; Supplementary modules show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands premium concentration exceeding any Gulf neighbor, while the UAE pursues regulatory harmonization through Dubai Health Authority mandates that diverge from Riyadh's Council of Health Insurance framework. Both markets enforce compulsory expatriate coverage, yet product architecture and broker economics differ materially.
Riyadh
Corporate headquarters clustering drives group plan procurement through broker-mediated channels. The Council of Health Insurance mandates minimum benefit floors that compress price competition at entry tiers. King Abdullah Financial District technology employers are unbundling comprehensive packages into modular inpatient-outpatient-dental components.
Eastern Province
Dammam-Khobar industrial zones host underserved expatriate construction and petrochemical workforces outside the Riyadh-Jeddah corridor. SAMR solvency oversight applies uniformly, yet carrier network density lags the central region. Aramco-adjacent facilities are negotiating direct hospital contracts bypassing traditional broker channels.
Western Region
Jeddah's port and logistics sector favors administrative simplicity in comprehensive coverage selection. The Hajj pilgrimage infrastructure generates seasonal demand spikes for emergency and inpatient services. King Abdulaziz International Airport proximity concentrates multinational benefits administration in Red Sea coastal zones.
NEOM Northwest
The giga-project zone is mandating captive insurance structures for construction-phase workforces. Council of Health Insurance portability rules are being stress-tested by transient expatriate labor flows. Oxagon industrial city planners are specifying real-time claims interoperability in provider contracts.
Saudi Arabia Health Insurance Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across product tiers, creating a bifurcated structure where scale-driven carriers anchor group mandates while niche operators capture top-up and family floater segments. The vendor base stratifies around three archetypes: cooperative insurers leveraging regulatory preference, multinational joint ventures importing platform technology, and domestic conglomerates cross-selling from banking or takaful franchises. Consolidation pressure is intensifying as SAMR capital requirements and digital infrastructure investments favor balance-sheet depth. Carriers are defending position through strategic partnerships with third-party administrators and backward integration into hospital network equity stakes.
Within the cooperative insurer tier, Tawuniya anchors the compulsory insurance segment through expatriate coverage dominance, while Bupa Arabia exemplifies the digital-first multinational joint venture archetype with platform investments targeting retention. Al Rajhi Company for Cooperative Insurance occupies the Shariah-compliant family plan niche, representing how domestic financial conglomerates cross-sell insurance through existing banking relationships. These three carriers illustrate the strategic positioning spectrum: regulatory-mandated scale, technology-led service differentiation, and religious-compliance product segmentation.
| Leading Market Players |
|---|
| Al Rajhi Company for Cooperative Insurance |
| Walaa Cooperative Insurance |
| Bupa Arabia for Cooperative Insurance |
| Allianz Saudi Fransi Cooperative Insurance Company |
| Malath Cooperative Insurance & Reinsurance Company |
| Tawuniya (The Company for Cooperative Insurance) |
| Saudi Arabian Cooperative Insurance Company (SAICO) |
| GIG Saudi (Gulf Insurance Group) |
| MedGulf (Mediterranean & Gulf Cooperative Insurance & Reinsurance) |
| Others |
Cost & Logistics Intelligence
The Council of Health Insurance's real-time adjudication mandate gates both qualified technology supply and premium-tier pricing access for carriers that cannot meet interoperability deadlines. This regulatory floor compresses margins at the basic benefit tier while rewarding carriers with legacy system modernization capabilities.
Pricing Analysis
Capacity additions in Riyadh's King Abdullah Financial District are reshaping price floors for group plan procurement as technology employers demand modular unbundling. Three-tier pricing structure across premium, standard, and economy levels dominates employer-sponsored coverage, with price differentiation resting on network hospital tier and digital platform integration depth. Cost compression in the standard tier is intensifying because broker channel concentration limits direct carrier-negotiation leverage. Small and medium enterprises exhibit the highest price sensitivity, while multinational headquarters in Jeddah prioritize administrative simplicity over premium minimization.
Supply Chain Analysis
Specialized health IT workforce availability in India, the Philippines, and Eastern Europe anchors carrier digitization timelines and claims platform deployment velocity. Core system components draw from cloud infrastructure providers, medical coding specialists, and API integration vendors concentrated in these geographies. Single-source vulnerability runs through legacy policy administration platforms that resist real-time interoperability retrofitting. Distribution runs through corporate broker networks in Riyadh and Jeddah, with third-party administrators handling claims processing for mid-tier carriers lacking in-house scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi Arabia health insurance market functions as a regulatory compounder where Council of Health Insurance mandate expansions for small and medium enterprises mechanically enlarge the addressable premium pool.
For Market Incumbents: Anchor defensive positioning through backward integration into third-party administrator capabilities and exclusive hospital network contracts in the Eastern Province. Broker channel disintermediation threats from direct employer-carrier platforms demand preemptive digital investment. Capacity addition in Dammam-Khobar industrial zones offers network density leverage against encroaching competitors. For New Entrants and Emerging Players: Begin with white-space capture in top-up plan distribution for affluent Saudi households seeking international treatment access outside compulsory benefit floors. The Eastern Province expatriate construction workforce remains underpenetrated by digital-first carriers. Telehealth-integrated claims platforms offer a differentiated go-to-market angle against legacy incumbents. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale cooperative insurers because SAMR capital requirements and digital infrastructure investments favor balance-sheet depth over organic growth. Five-to-ten year viability hinges on regulatory compliance automation and real-time adjudication capability deployment. Watch Council of Health Insurance minimum benefit mandate expansion velocity as the primary inflection indicator for premium pool growth acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Adjudication Platform Deployment | Council of Health Insurance mandates compress claims cycles from weeks to hours for compliant carriers. |
| Modular Product Unbundling | King Abdullah Financial District technology employers now select inpatient, outpatient, and dental components separately. |
| Eastern Province Network Expansion | Dammam-Khobar industrial zones host underserved expatriate workforces outside Riyadh-Jeddah broker concentration. |
| Third-Party Administrator Acquisition | Backward integration into claims processing insulates margin from broker channel concentration pressure. |
| Telehealth-Claims System Integration | Remote consultation platforms enable outpatient cost containment and member retention improvements. |
Research Approach
Coverage spans Riyadh, Jeddah, the Eastern Province, and emerging NEOM Northwest zones, with primary inputs from each regional cluster. The analysis combines structured interviews with Council of Health Insurance regulatory affairs officers, carrier actuarial directors, corporate benefits managers at multinational headquarters, third-party administrator operations heads, and hospital network contracting specialists with secondary validation. Secondary sources include Council of Health Insurance regulatory filings, SAMR solvency disclosures, hospital procurement databases, and GPO contracts. Bottom-up premium volume estimates triangulate against top-down regulatory enrollment mandates.
Rate-of-change decomposition separates volume growth from pricing dynamics across the analysis window. Segmentation dimensions modeled include product type, provider origin, claim setting, and coverage depth tier alongside employer size archetype and regional regulatory enforcement intensity. CAGRs derive from enrollment mandate trajectories, medical cost inflation assumptions, and digital platform adoption curves. Industry-specific forecast inputs incorporate Council of Health Insurance minimum benefit expansion schedules and real-time adjudication compliance deadlines.
Several conditions sit outside the modeled scope, including macroeconomic disruption affecting expatriate workforce flows, abrupt regulatory reversal on compulsory coverage mandates, and technological leapfrogging that obsoletes current interoperability standards. Forecasts reflect assumptions about regulatory enforcement continuity and carrier technology investment capacity. Material deviation in Council of Health Insurance mandate timelines or SAMR capital requirement adjustments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Digital Transformation in Insurance Market
Insurance
Critical Illness Insurance Market
Insurance
North America Car Insurance Aggregators Market
Insurance
Specialty Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Germany Electronic Gadgets Insurance Market
Insurance
Aviation Insurance Market
Insurance
Europe Travel Insurance Market
Insurance
UK Dental Insurance Market
Insurance
Asia-Pacific Livestock Insurance Market
Insurance
Commercial Cyber Insurance Market
Insurance
Agriculture Insurance Market
Insurance
France Liability Insurance Market
Insurance
United States Bancassurance Market
Insurance
India Health Insurance Market
Insurance
Digital Monetary Insurance Market