
 Cannabis Crop Insurance Market | 2026-2036
Cannabis Crop Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Crop Insurance Market Analysis
Parametric insurance financing and weather-indexed coverage structures is reconfiguring capital deployment for cannabis cultivators previously excluded from traditional agricultural lending. Admiral Insurance Group leverages its surplus lines infrastructure to anchor catastrophic peril coverage for large-scale greenhouse operators across multiple state jurisdictions. Berkley Insurance competes through specialized underwriting units that dominate commercial property-casualty bundles tailored to licensed cultivation facilities. Cover Cannabis differentiates by controlling agent-facing digital platforms that streamline policy issuance for smallholder growers navigating complex state licensing regimes.
Cannabis crop insurance constitutes risk-transfer instruments designed to indemnify licensed cultivators against yield loss, revenue shortfall, and physical damage to living plant inventory, with coverage triggers calibrated to THC compliance thresholds, fire suppression system adequacy, and documented cultivation protocols. Revenue insurance captures the fastest-growing margin pool as vertically integrated operators seek protection against price volatility in state-regulated wholesale markets. Yield insurance occupies a mature position among outdoor cultivators in established state programs, while customized policy structures are accelerating among indoor operators requiring tailored peril schedules for HVAC-dependent controlled environments.
The USDA Risk Management Agency shapes federal hemp coverage parameters, while state insurance commissioners in Colorado and California govern admitted carrier participation and rate filings for THC-containing crops. The National Association of Insurance Commissioners coordinates model legislation that influences whether standard agricultural statutes extend to cannabis cultivators or force reliance on surplus lines markets. Stakeholders must monitor how the SAFE Banking Act's progression alters federal risk classifications and whether state-level social equity licensing programs generate new insured populations with distinct coverage needs and capital constraints.
Market Dynamics
The USDA Risk Management Agency's hemp coverage expansion and California's THC compliance mandates are compressing carrier underwriting cycles while forcing surplus lines migration for THC-containing crops.
Growth Catalysts
- USDA hemp program expansion:Federal crop insurance eligibility for hemp cultivators under Section 508(h) is pulling admitted carriers into previously excluded agricultural jurisdictions.
- California THC testing mandates:State-level potency verification requirements are generating mandatory coverage triggers for licensed cultivators facing crop destruction risks.
- Parametric weather instruments:Satellite-indexed precipitation and temperature derivatives are enabling capital deployment to outdoor cultivators without traditional loss-adjustment infrastructure.
Market Restraints
- Reinsurance capacity scarcity:Lloyd's syndicates and Bermuda markets limit aggregate exposure to Schedule I crop liabilities, constraining primary carrier line sizes.
- Banking exclusion friction:Federal cannabis banking prohibitions prevent premium financing through agricultural lending channels available to conventional crop sectors.
- THC degradation uncertainty:Post-harvest potency loss creates coverage disputes between yield protection and revenue guarantee policy forms.
Strategic Opportunities
- Social equity licensing pipelines:State-mandated equity programs in California and Colorado are generating first-time insured populations requiring technical assistance and micro-premium products.
- Controlled environment agriculture:HVAC-dependent indoor operations need tailored peril schedules covering equipment failure and power interruption risks.
- SAFE Banking Act passage:Federal depository access would normalize premium payment flows and enable standard agricultural lien structures for policy collateral.
Industry Challenges
- Actuarial data scarcity:Limited historical yield and loss data for novel cultivars prevents experience-rated pricing and forces reliance on proxy crops.
- Multi-state licensing complexity:Cultivators operating across Colorado, California, and Oregon face conflicting coverage requirements and non-admitted carrier dependencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Crop Insurance Market |
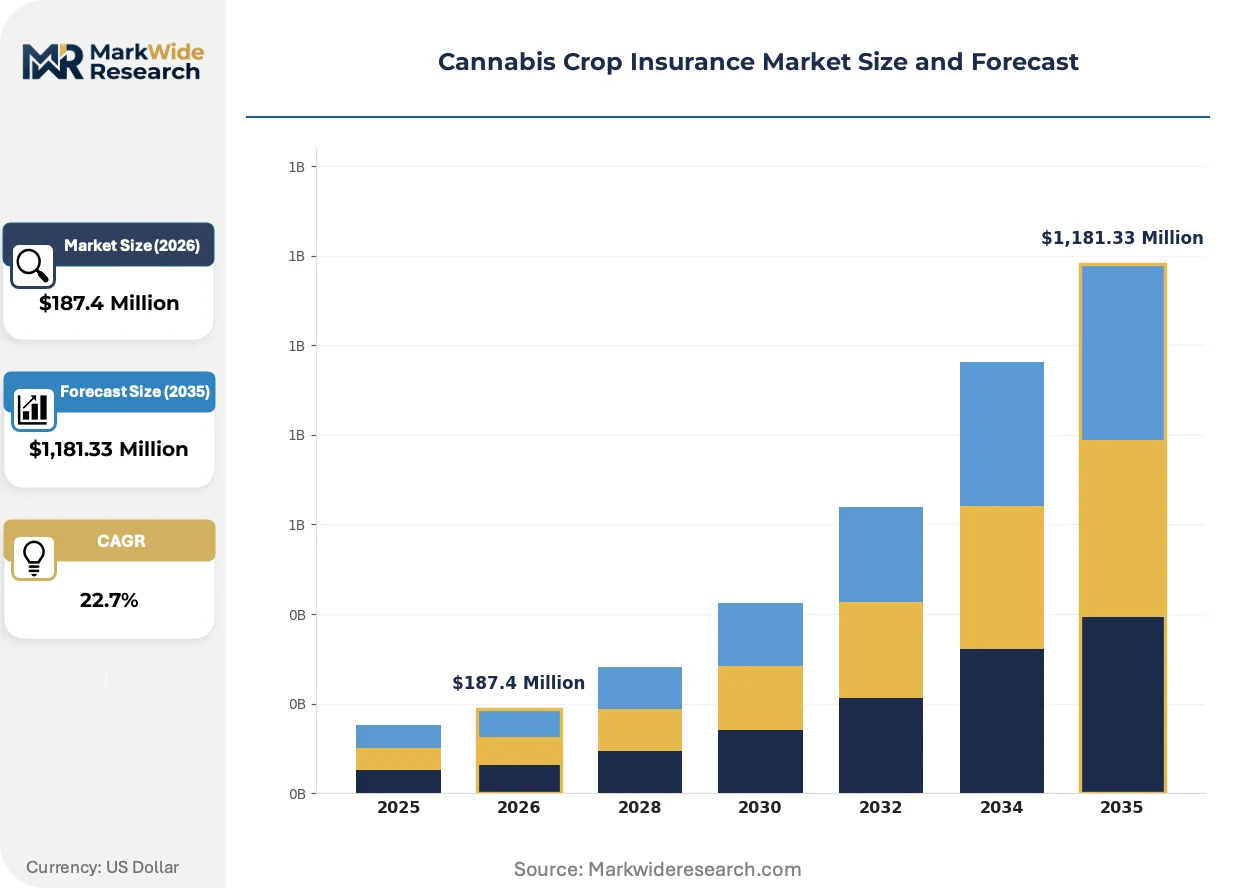
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cover Crop Insurance, Yield Insurance, Revenue Insurance, Crop-Hail Insurance End User: Growers, Distributors, Processors, Retailers Policy Type: Standard Policy, Customized Policy, Bundled Policy, Multi-Peril Policy Distribution Channel: Online, Agents, Brokers, Direct Sales |
| Companies Covered | Cover Cannabis, Admiral Insurance Group, Cannabis Insurance Services (CIS), Berkley Insurance, Acadia Insurance, CARMA365, Millers Insurance Group, Cannassure, SafeHerb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Crop Insurance Market Emerging Trajectories
Weather-indexed parametric structures and blockchain-verified cultivation records are compressing traditional indemnity models while enabling real-time policy adjustments.
Blockchain-enabled provenance tracking is collapsing the information asymmetry between cultivators and underwriters. Large-scale greenhouse operators in Colorado and California are adopting distributed ledger systems to document cultivation protocols. This transparency compression is enabling parametric triggers based on verified growing conditions rather than post-loss adjustment.
The USDA Risk Management Agency's expanded hemp coverage under the 2018 Farm Bill is reshaping federal-state regulatory coordination. State insurance commissioners in cannabis-legal jurisdictions must now align THC threshold definitions with federal crop insurance eligibility. Indoor cultivators in Colorado are responding by segregating hemp and marijuana operations to access federal programs.
Vertically integrated operators are consolidating procurement of coverage across cultivation, processing, and retail functions. This bundling compression is displacing standalone crop policies with enterprise risk programs. The shift is most visible in California, where multi-license holders negotiate master policies covering property, liability, and crop perils under single carrier relationships.
Cannabis Crop Insurance Market Segmentation
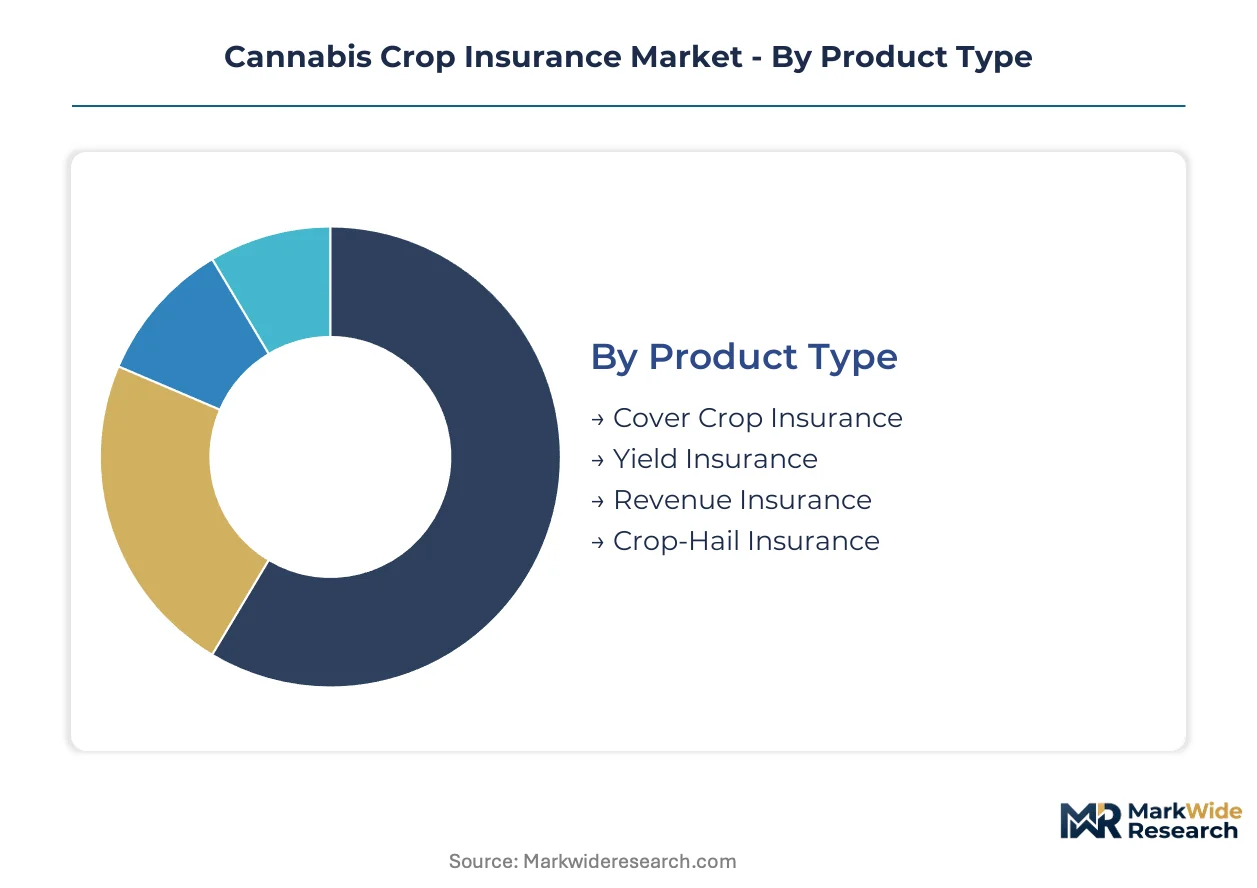
Cannabis crop insurance segments reflect divergent risk profiles across cultivation methods, supply chain positions, and regulatory environments. Insurers calibrate coverage terms, pricing models, and loss-adjustment protocols to each segment's distinct loss drivers and compliance requirements.
Product Type:
Coverage instruments segment by the economic loss metric they indemnify—physical plant damage, quantified yield shortfall, or revenue erosion from price volatility.
- Cover Crop Insurance:Policies indemnify against physical destruction of living plant inventory from named perils including fire, theft, and vandalism. Demand concentrates among outdoor cultivators in California and Colorado facing acute wildfire exposure and crop theft risks from remote cultivation sites.
- Revenue Insurance:Instruments protect against the product of yield loss and price decline, with coverage triggers tied to state-tracked wholesale price indices. Vertically integrated operators in state-regulated markets purchase these policies to hedge against price compression from oversupply cycles.
- Yield Insurance:Coverage pays on quantified production shortfall against documented historical averages, with loss adjustment requiring THC compliance verification. Mature demand exists among established outdoor growers with multi-year cultivation records.
- Crop-Hail Insurance:Named-peril coverage for hail damage to greenhouse and outdoor operations, typically written as standalone supplemental policies in hail-prone western counties.
Revenue insurance holds installed capacity. Cover crop insurance is rotating up the share rankings.
End User:
Supply chain position determines risk exposure type—biological cultivation risk, inventory transit risk, processing equipment risk, or retail liability accumulation.
- Growers:Licensed cultivators face biological perils across seed-to-harvest cycles, with coverage needs scaling by operation size and controlled environment dependence. California's THC testing mandates generate mandatory coverage triggers for this segment.
- Distributors:Wholesale intermediaries require transit and warehouse coverage for high-value inventory subject to potency degradation and diversion risks. Interstate commerce prohibitions fragment coverage placement across state-licensed carriers.
- Processors:Extraction and manufacturing facilities need equipment breakdown and product liability coverage alongside traditional crop perils. Demand clusters among concentrated processing hubs in Colorado and California.
- Retailers:Dispensaries carry minimal direct crop exposure but purchase contingent business interruption tied to supplier crop failures. Social equity licensing programs in multiple states are expanding this insured population.
Growers dominate premium volume. Processors are climbing the fastest as extraction capacity expands.
Policy Type:
Contract structure varies by standardization level—admitted carrier filings, surplus lines customization, enterprise bundling, or federal multi-peril frameworks.
- Standard Policy:Admitted carrier forms with state-filed rates and mandatory coverage provisions, available primarily for hemp cultivators under USDA programs. Federal eligibility constraints exclude THC-containing marijuana from this segment.
- Customized Policy:Surplus lines contracts with tailored peril schedules, sub-limits, and exclusions negotiated for specific cultivation protocols. Indoor operators in Colorado and California use these for HVAC-dependent controlled environment risks.
- Bundled Policy:Enterprise programs combining property, liability, crop, and directors coverage under single carrier relationships. Vertically integrated multi-license holders in California drive demand for this structure.
- Multi-Peril Policy:Comprehensive coverage bundling yield, revenue, and property perils with single deductible structures. Commercial multi-peril policies are gaining traction among licensed cultivators as state compliance mandates harden.
Customized policies command premium pricing. Bundled policies are gaining share fastest among integrated operators.
Distribution Channel:
Placement method reflects customer sophistication, transaction scale, and regulatory complexity navigation requirements.
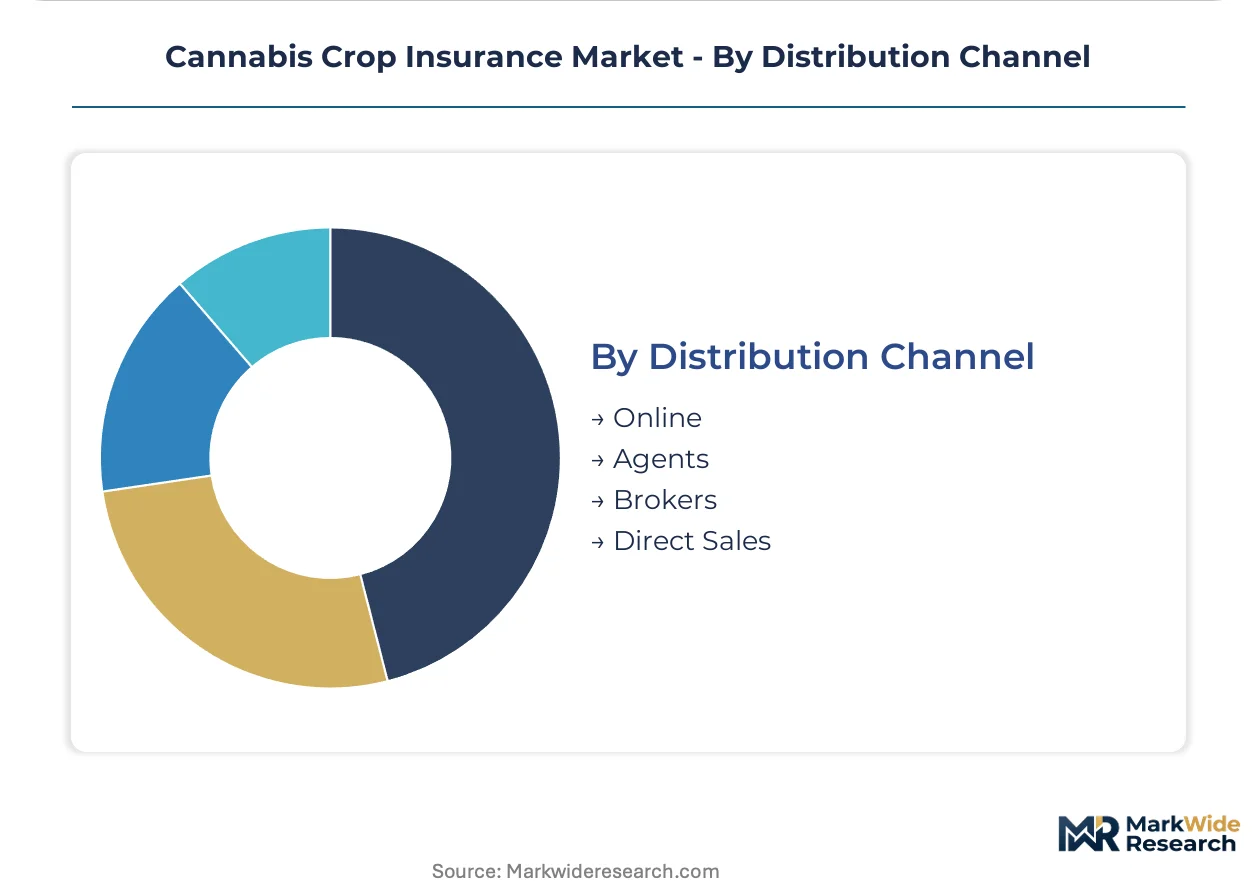
- Agents:Captive and independent producers with state licensing expertise place admitted and surplus lines coverage for smallholder growers. Agent-facing digital platforms streamline policy issuance for cultivators navigating complex state licensing regimes.
- Brokers:Wholesale intermediaries access non-admitted markets and structure layered programs for large-scale operations. Lloyd's syndicates and Bermuda markets are accessed primarily through this channel.
- Online:Direct-to-consumer platforms with automated underwriting for standardized hemp coverage and micro-premium products. Social equity licensees with capital constraints utilize this channel for cost efficiency.
- Direct Sales:Carrier-employed producers targeting large greenhouse operators and multi-state cultivators for master policy relationships. Admiral Insurance Group anchors catastrophic peril coverage through this channel.
Agents retain the largest placement volume. Online distribution is expanding most quickly for hemp and smallholder segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal hemp coverage expansion under USDA Section 508(h) is pulling admitted carriers into agricultural jurisdictions previously excluded from standard crop insurance programs. State-level THC compliance mandates in mature markets are compressing underwriting cycles and forcing surplus lines migration for marijuana-containing crops.
United States
California's THC testing mandates generate mandatory coverage triggers for licensed cultivators facing crop destruction risks from potency failures. The USDA Risk Management Agency governs federal hemp eligibility parameters while state insurance commissioners in Colorado and Oregon regulate admitted carrier participation. Denver and Los Angeles anchor the largest concentrations of greenhouse operators purchasing catastrophic peril coverage.
Canada
Health Canada's cannabis licensing framework creates standardized coverage requirements for federally regulated producers. The country's national agricultural insurer administers modified crop insurance products for licensed cultivation facilities. British Columbia's Okanagan Valley and Ontario's greenhouse clusters drive demand for controlled environment agriculture policies.
Germany
The country's national pharmaceutical regulator oversees medical cannabis importation and domestic cultivation licensing. German insurers are developing specialized agricultural products for the limited domestic cultivation permits issued under federal narcotics law. Bavaria and North Rhine-Westphalia host the primary processing and distribution facilities requiring inventory coverage.
Switzerland
Low-THC hemp cultivation enjoys liberal federal authorization, creating demand for standard agricultural coverage products. Swissmedic coordinates with cantonal agricultural authorities on THC threshold verification for insurance eligibility. The Zurich and Geneva regions concentrate greenhouse operations seeking property-casualty bundles.
Netherlands
The country's tolerance policy for licensed coffee shop supply chains generates crop insurance demand for regulated domestic cultivation. Dutch agricultural insurers are piloting revenue protection products tied to government-tracked wholesale price indices. North Brabant's greenhouse agriculture cluster leads adoption of controlled environment peril schedules.
Cannabis Crop Insurance Market Vendor Landscape
On the supply side, the industry is fragmented across surplus lines specialists, admitted carriers with agricultural divisions, and digital-native intermediaries targeting smallholder segments. Three strategic archetypes dominate: catastrophic peril underwriters leveraging Lloyd's syndicate capacity, bundled property-casualty providers serving vertically integrated operators, and agent-facing platform specialists streamlining policy issuance. Competitive moves concentrate on geographic expansion into newly legalized state jurisdictions and portfolio diversification beyond standalone crop into enterprise risk programs.
Among surplus lines specialists, Admiral Insurance Group and Berkley Insurance exemplify the catastrophic peril tier, anchoring coverage for large-scale greenhouse operators across multiple state jurisdictions. Cover Cannabis occupies a distinct position within the digital intermediary archetype, controlling agent-facing platforms that streamline policy issuance for smallholder growers navigating complex state licensing regimes. These three companies collectively represent the dominant competitive positioning patterns visible across the carrier landscape.
| Leading Market Players |
|---|
| Cover Cannabis |
| Admiral Insurance Group |
| Cannabis Insurance Services (CIS) |
| Berkley Insurance |
| Acadia Insurance |
| CARMA365 |
| Millers Insurance Group |
| Cannassure |
| SafeHerb |
| Others |
Supply Flow & Price Mechanics
Surplus lines capacity constraints in Lloyd's and Bermuda markets are compressing underwriting cycles while forcing carriers toward risk-selective pricing postures. Carrier appetite fluctuates with federal hemp program expansions and state THC compliance mandates.
Pricing Analysis
Policy customization level creates the primary spread between standardized hemp coverage and tailored marijuana crop instruments. Three-tier pricing structure across admitted carrier, surplus lines, and parametric indexed products dominates the market. Pricing pressure stems from reinsurance scarcity for Schedule I crop liabilities. Social equity licensees with capital constraints exhibit highest price sensitivity, while vertically integrated multi-state operators negotiate volume discounts.
Supply Chain Analysis
Contract manufacturing concentration among Lloyd's syndicates and Bermuda reinsurers holds capacity for catastrophic peril layers. Primary carrier capacity concentrates in California, Colorado, and Oregon. Risk capital draws from agricultural reinsurance pools, specialty surplus lines wholesalers, and parametric derivative markets. Single-source vulnerability to Lloyd's aggregate exposure limits constrains line sizes. Distribution runs through captive agents for smallholders and wholesale brokers for large greenhouse operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
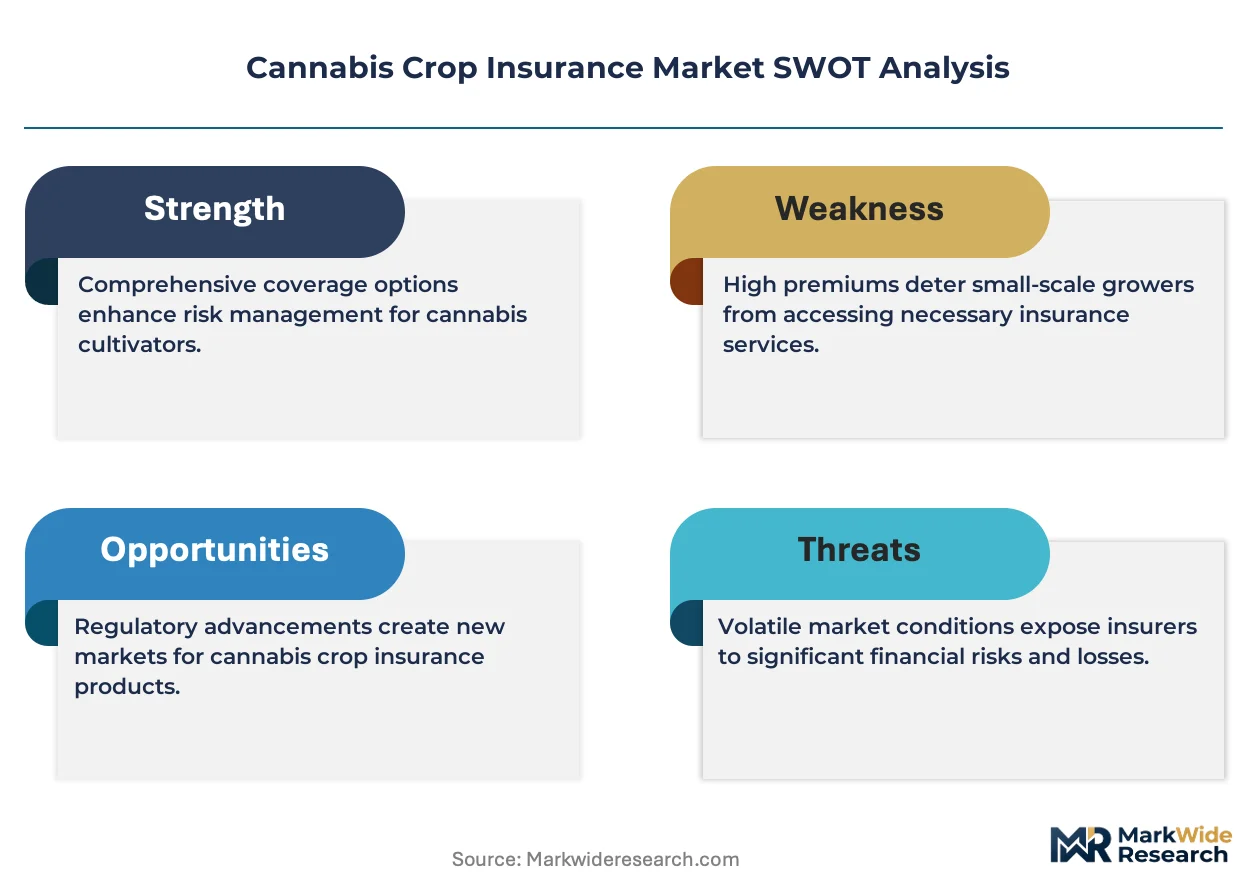
Buyer power is consolidating among vertically integrated multi-license holders in California, fragmenting pricing leverage for standalone crop specialists.
For Market Incumbents: Build regulatory data moats through blockchain-verified cultivation records that compress information asymmetry. Admiral Insurance Group anchors catastrophic coverage by controlling proprietary peril databases across state jurisdictions. Defend against parametric entrants by deepening federal hemp program participation. Capacity addition in Colorado and California greenhouse clusters secures geographic concentration benefits. For New Entrants and Emerging Players: Social equity licensing pipelines in California and Colorado represent the most penetrable entry point for micro-premium digital platforms. Cover Cannabis demonstrates agent-facing platform control as a viable go-to-market angle. Target processors in extraction hubs with equipment breakdown bundles. Parametric weather instruments for outdoor cultivators bypass traditional loss-adjustment infrastructure requirements. For Investors and Strategic Acquirers: Capital is best deployed toward surplus lines specialists with Lloyd's syndicate relationships and multi-state licensing expertise. Long-term viability hinges on SAFE Banking Act progression normalizing premium payment flows. Watch for federal depository access as the inflection indicator enabling standard agricultural lien structures.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Weather-indexed triggers enable capital deployment without loss-adjustment infrastructure. |
| Blockchain Provenance Integration | Distributed ledger systems collapse information asymmetry between cultivators and underwriters. |
| Social Equity Platform Launch | Micro-premium digital products address capital-constrained first-time insured populations. |
| Enterprise Bundling Expansion | Master policies covering property, liability, and crop perils displace standalone coverage. |
| Federal Program Participation | USDA hemp eligibility pulls admitted carriers into previously excluded agricultural jurisdictions. |
Methodological Framework
Initial hypotheses were tested against primary input from carrier underwriting executives, state insurance commissioners, licensed cultivators, and surplus lines brokers and refined through secondary validation. Primary fieldwork combined structured interviews with risk management officers at greenhouse operators and regulatory affairs leads at agricultural insurers. Secondary sources included USDA Risk Management Agency filings, NAIC model legislation databases, state insurance department rate filings, and Lloyd's syndicate exposure disclosures. Bottom-up policy volume estimates triangulated against top-down addressable market calculations.
Demand-supply balance modeling anchored forecast construction across the analysis window. Segmentation dimensions included cultivation method, supply chain position, policy structure standardization, and distribution channel. CAGRs derived from experience-rated pricing trends and proxy crop loss data. Forecast inputs incorporated THC compliance threshold evolution and parametric instrument penetration rates.
Practitioners should monitor SAFE Banking Act legislative progression and state social equity licensing volume for early signals of forecast revision. Cross-checking against USDA hemp program enrollment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Event Insurance Market
Insurance
Russia Property and Casualty Insurance Market
Insurance
Cargo Insurance Market
Insurance
Dental Insurance Market
Insurance
Insurance Claims Services Market
Insurance
Peru Insurance Market
Insurance
Europe Mobile Phone Insurance Market
Insurance
Financial Guarantee Market
Insurance
France Property and Casualty Insurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
Commercial Earthquake Insurance Market
Insurance
South Korea Liability Insurance Market
Insurance
France Car Insurance Market
Insurance
Insurance Third Party Administrators Market
Insurance
Family Floater Health Insurance Market