
 Insurance Claims Services Market | 2026-2036
Insurance Claims Services Market Size, Share, and Industry Trends Forecast 2026-2036
Insurance Claims Services Market Analysis
Third-party administrator networks is reconfiguring how carriers distribute claims handling across geographies and risk classes. Sedgwick anchors a significant share of workers' compensation and liability claims management through its employer-focused service model. Willis Towers Watson leverages actuarial and broking synergies to embed claims analytics within risk advisory engagements. Crawford & Company specializes in catastrophe response, sustaining rapid deployment capabilities through its independent adjuster workforce.
Insurance claims services encompass the end-to-end administration of policyholder requests for indemnification, spanning first notice of loss, investigation, valuation, negotiation, and settlement disbursement, typically governed by state-level unfair claims settlement practices regulations and contractual duty of good faith. Claims Processing commands the largest service type volume due to its ubiquity across all lines of business, while Fraud Detection is accelerating fastest as synthetic identity schemes and medical provider collusion inflate loss costs. AI within the technology dimension is attracting disproportionate capital allocation as carriers deploy natural language processing for demand package analysis and computer vision for property damage estimation.
State insurance departments in the US enforce claims handling timelines and documentation standards, while the NAIC model laws create baseline expectations for market conduct examinations. The EU's Digital Operational Resilience Act and GDPR impose data governance and incident reporting obligations on claims systems processing European policyholder information. Stakeholders must monitor regulatory divergence between speed-to-settle mandates and emerging cybersecurity disclosure requirements that could reshape vendor qualification criteria.
Market Dynamics
Carrier pressure to compress loss-adjustment expense ratios is forcing structural reconfiguration of claims handling networks, with third-party administrator partnerships displacing in-house operations across property and liability lines.
Growth Catalysts
- Catastrophic Weather Exposure:Escalating hurricane and wildfire frequency in Florida and California is expanding demand for rapid-response independent adjuster networks and mobile claims units.
- EU Digital Operational Resilience Act:Mandatory audit trails and incident reporting obligations are compelling European carriers to modernize claims infrastructure, creating vendor substitution windows.
- Litigation Financing:Third-party funders backing plaintiff attorneys are extending claims duration and complexity, elevating specialized liability claims management demand.
Market Restraints
- Adjuster Labor Scarcity:Licensed property adjusters concentrate in Texas and Florida, creating geographic supply bottlenecks during concurrent catastrophe events.
- State Regulatory Fragmentation:Unfair claims settlement practice statutes vary across all fifty US states, multiplying compliance architecture costs for national service providers.
- Legacy System Integration:Core policy administration platforms from the 1990s resist API connectivity, constraining real-time data exchange between carriers and third-party administrators.
Strategic Opportunities
- Parametric Insurance Expansion:Index-triggered coverage for agricultural and flood risks is creating demand for automated, satellite-verified claims settlement workflows.
- AI-Native Fraud Detection:Synthetic identity schemes and medical provider collusion patterns are accelerating adoption of machine learning models for anomaly flagging.
- Cyber Claims Specialization:Ransomware and business interruption coverage growth is opening dedicated incident response and forensic accounting service lines.
Industry Challenges
- Data Science Talent Gap:Natural language processing and computer vision expertise for demand package analysis remains concentrated among technology vendors, not traditional adjusters.
- GDPR-Era Data Governance:Cross-border claims processing involving European policyholders requires jurisdictional data residency compliance, complicating offshore processing arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insurance Claims Services Market |
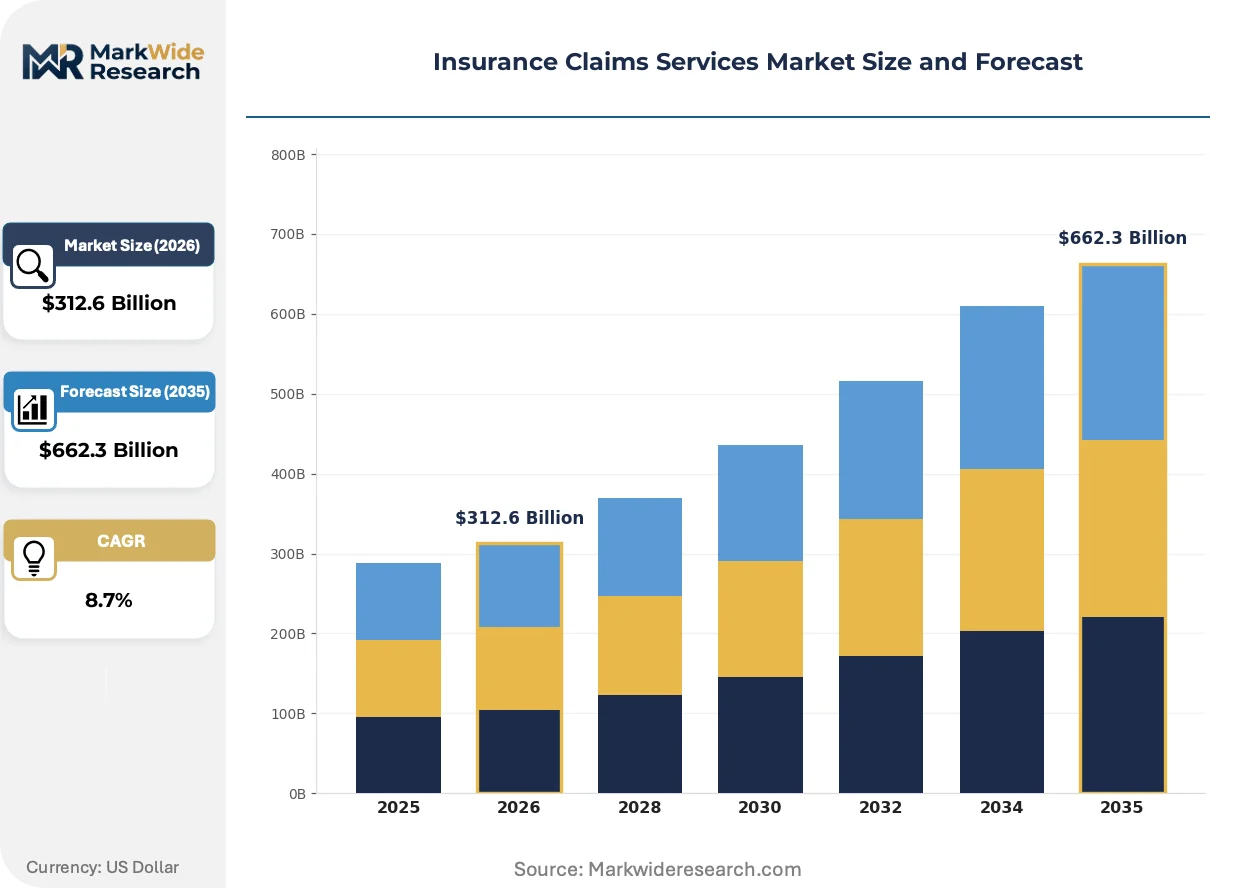
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Claims Processing, Risk Assessment, Fraud Detection, Policy Administration Technology: AI, Cloud Computing, Blockchain, Data Analytics Customer Type: Individual Policyholders, Corporations, Small Businesses, Government Entities End User: Medical Facilities, Automotive Services, Property Owners, Legal Firms |
| Companies Covered | Aon, Arthur J. Gallagher & Co., Sedgwick, Hub International, Alliant Insurance Services, Crawford & Company, Willis Towers Watson, Brown & Brown, Marsh & McLennan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insurance Claims Services Market Emerging Trajectories
Claims service delivery is undergoing platformization, with artificial intelligence compressing investigation timelines and regulatory mandates forcing infrastructure modernization across carrier and vendor ecosystems.
Computer vision for property damage estimation is migrating from pilot programs to standard deployment. National carriers are mandating photo-based initial estimates for auto physical damage and roof claims. The technology is compressing cycle times from days to hours while reducing field adjuster dispatch frequency.
GDPR and the EU Digital Operational Resilience Act are imposing granular data governance and incident reporting obligations on claims systems processing European policyholder information. Carriers must now maintain audit-ready documentation of every processing touchpoint. Vendors serving EU markets are rebuilding infrastructure for jurisdictional data residency compliance.
Self-service digital channels are displacing telephone-first first notice of loss intake. Policyholders now expect mobile app submission with automated status tracking. This behavioral shift is most pronounced among personal auto and renters insurance buyers in urban US markets, where smartphone penetration and digital literacy rates are highest.
Insurance Claims Services Market Segmentation
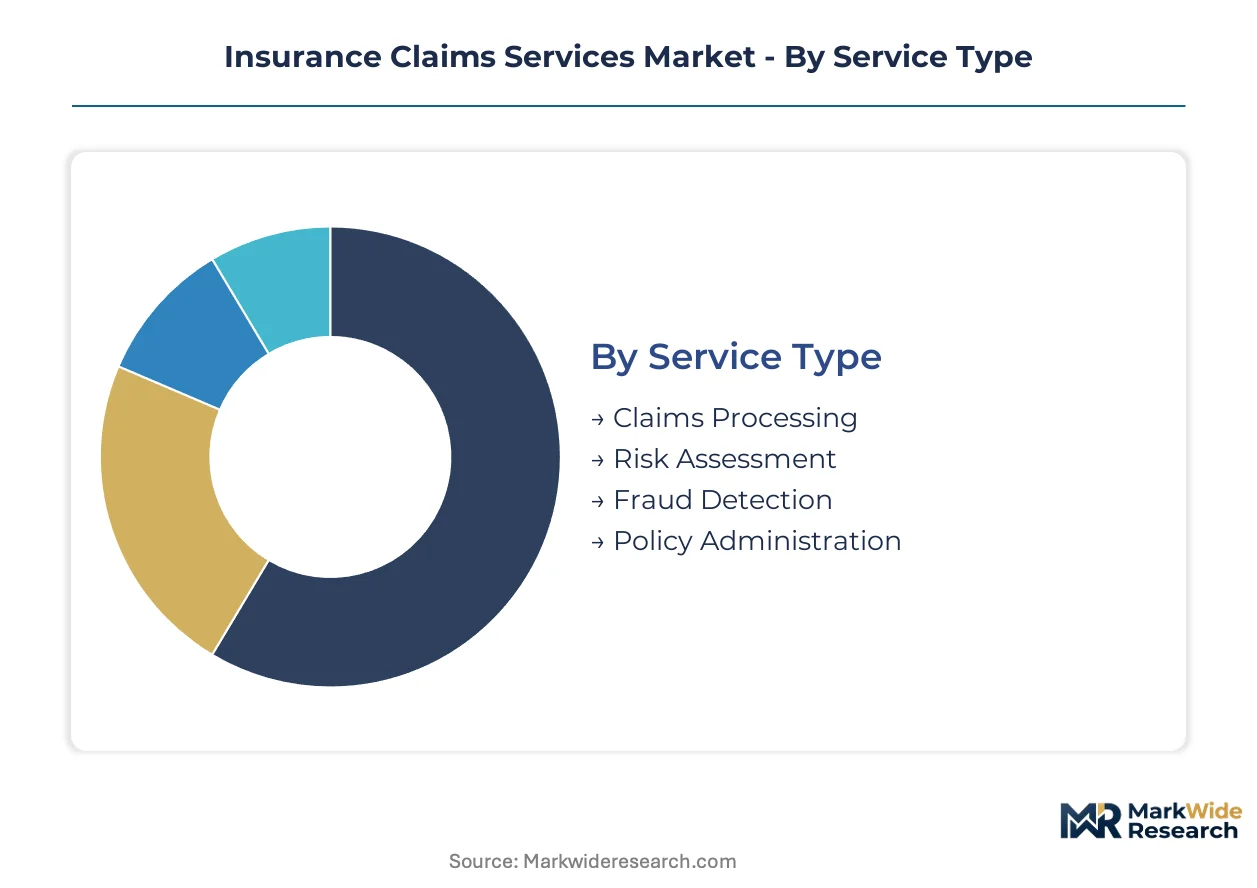
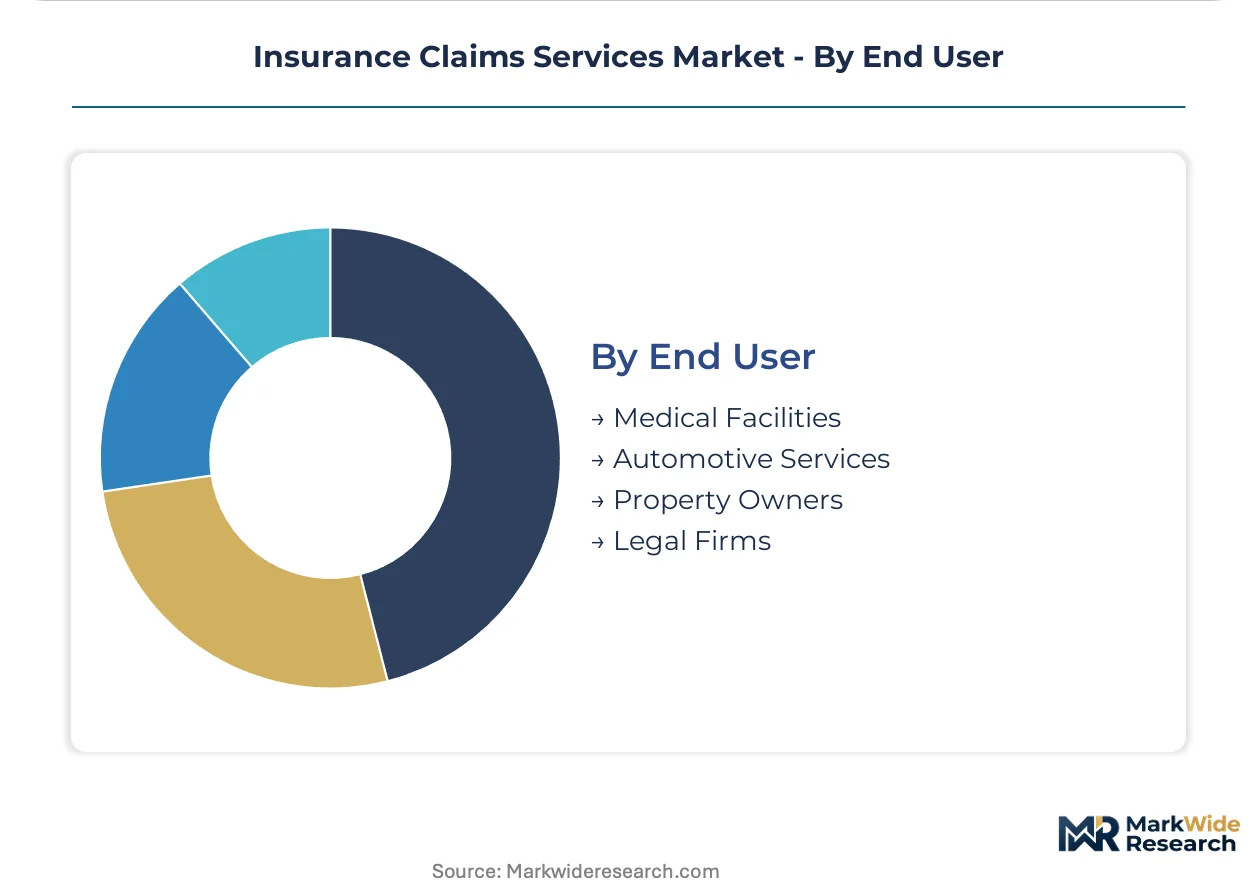
Insurance claims services fragment across four operational dimensions that determine vendor capability requirements and pricing architecture. Service type governs workflow complexity, technology selection dictates infrastructure investment, while customer and end-user profiles shape compliance obligations and delivery channel design.
Service Type:
Cost tier stratification separates commoditized transaction processing from specialized advisory functions that command premium pricing.
- Claims Processing:High-volume transaction administration spanning first notice of loss through settlement disbursement. Demand concentrates among US P&C carriers facing state-mandated speed-to-settle timelines and escalating litigation financing complexity.
- Fraud Detection:Anomaly identification through pattern recognition and forensic investigation. Synthetic identity schemes and medical provider collusion in Florida and California are accelerating carrier investment in machine-learning detection layers.
- Risk Assessment:Pre-loss exposure evaluation and reserve adequacy analysis.
- Policy Administration:Endorsement processing, renewal management, and coverage verification.
Claims Processing commands the established base. The steepest expansion runs through Fraud Detection.
Technology:
Application maturity separates experimental deployments from production-scale infrastructure with measurable ROI documentation.
- AI:Natural language processing for demand package analysis and computer vision for property damage estimation. National US carriers now mandate photo-based initial estimates for auto physical damage, compressing cycle times from days to hours.
- Cloud Computing:Scalable infrastructure for claims platform hosting and data residency compliance. GDPR and the EU Digital Operational Resilience Act are forcing jurisdictional separation of European policyholder data.
- Data Analytics:Predictive modeling for reserve optimization and litigation outcome forecasting.
- Blockchain:Immutable audit trails for smart contract parametric settlements.
Cloud Computing anchors current infrastructure spend. AI attracts the fastest-climbing capital allocation.
Customer Type:
Volume concentration and margin profile vary sharply across buyer sophistication and purchasing centralization.
- Corporations:Multi-line risk management programs requiring integrated claims analytics and captive coordination. Fortune 500 manufacturing and retail operations in Texas and Ohio are consolidating TPA relationships to compress loss-adjustment expense ratios.
- Individual Policyholders:Personal lines consumers demanding mobile-first intake and automated status tracking. Urban US markets with high smartphone penetration are driving self-service channel investment.
- Small Businesses:Workers' compensation and general liability programs with limited risk management staff.
- Government Entities:Public sector self-insured pools and municipal risk retention groups.
Corporations generate the deepest revenue per account. Individual Policyholders represent the volume expansion frontier.
End User:
Geographic clustering of demand centers on catastrophe exposure corridors and litigation intensity zones.
- Property Owners:Residential and commercial real estate claims from hurricane, wildfire, and flood events. Florida and California policyholders are driving demand for rapid-response independent adjuster networks and mobile claims units.
- Legal Firms:Defense counsel coordination and settlement negotiation support. Third-party litigation financing in New York and Texas is extending claim duration and elevating specialized liability management needs.
- Medical Facilities:Provider bill review and utilization management for casualty and workers' compensation.
- Automotive Services:Collision repair networks and total loss valuation coordination.
Property Owners anchor catastrophic event response capacity. Legal Firms are gaining share fastest through litigation complexity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lloyd's of London market infrastructure underwrites the United Kingdom's central role in international claims services, while the Port of Miami's catastrophe logistics hub anchors Florida's adjuster deployment capacity.
United States
Hurricane exposure along the Gulf Coast and litigation financing proliferation in Texas and Florida drive specialized claims management demand. State insurance departments enforce speed-to-settle timelines under NAIC model laws. Miami and Houston concentrate rapid-response independent adjuster networks for catastrophic event mobilization.
United Kingdom
Lloyd's syndicate capacity and London market specialty lines sustain complex international claims expertise. The Financial Conduct Authority imposes conduct standards on claims handling under SMCR accountability frameworks. The City of London anchors marine and aviation claims specialization with deep forensic accounting talent pools.
Germany
Industrial property concentration in the Ruhr and Bavaria generates large-loss engineering claims volume. BaFin enforces Solvency II reporting requirements on claims reserve adequacy and operational risk. Munich and Frankfurt host major reinsurer claims operations serving European cedents.
France
Agricultural parametric coverage expansion and flood exposure along the Loire and Rhône basins create automated settlement demand. ANSM and CNIL impose GDPR-compliant data governance on cross-border claims processing. Paris anchors continental Europe's largest TPA consolidation activity.
Australia
Bushfire and cyclone exposure in Queensland and New South Wales drives catastrophe response infrastructure investment. APRA mandates operational resilience standards on claims system continuity planning. Sydney concentrates Asia-Pacific regional claims hubs for multinational insurers.
Insurance Claims Services Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. National carriers maintain captive operations for high-frequency personal lines while outsourcing complex liability and workers' compensation to specialized administrators. Strategic archetypes include scale-driven TPAs with geographic density, technology-enabled platforms with AI-native workflows, and boutique specialists in catastrophe response. Dominant competitive moves encompass M&A-driven geographic expansion and proprietary technology licensing to carrier clients.
Within the scale-driven tier, Sedgwick and Crawford & Company exemplify employer-focused and catastrophe-specialized positioning respectively. Willis Towers Watson occupies the advisory-integrated segment, leveraging actuarial and broking synergies to embed claims analytics within broader risk engagements. These three entities represent the primary competitive anchors across distinct service archetypes.
| Leading Market Players |
|---|
| Aon |
| Arthur J. Gallagher & Co. |
| Sedgwick |
| Hub International |
| Alliant Insurance Services |
| Crawford & Company |
| Willis Towers Watson |
| Brown & Brown |
| Marsh & McLennan |
| Others |
Supply Flow & Price Mechanics
The Port of Miami freight corridor anchors catastrophe logistics costs for independent adjuster networks, concentrating supply-side pricing power among rapid-deployment specialists while downstream carriers face tiered service procurement decisions across premium response, standard TPA, and economy processing tiers.
Pricing Analysis
Volume-discount tiering separates Fortune 500 multi-line programs from small-business workers' compensation accounts, with pricing stratifying across premium catastrophe-response, standard claims administration, and economy transaction-processing tiers. Price differentiation rests on adjuster certification grade and geographic deployment speed, with Florida and Texas windstorm specialists commanding substantial premiums. Cost compression in economy tiers is intensifying because AI-enabled photo estimation displaces field adjuster dispatch. Small businesses exhibit highest price sensitivity; multinational risk managers prioritize service-level guarantees over unit cost.
Supply Chain Analysis
Export-control regimes limiting AI and computer vision technology flows constrain vendor qualification for European carrier contracts under the EU Digital Operational Resilience Act. Supply concentrates in the United States, United Kingdom, and Germany, with licensed adjuster labor pools and cloud infrastructure anchoring service delivery. Raw material dependencies include specialized forensic accounting talent, satellite imagery verification systems, and jurisdictional data residency compliance architecture. Single-source vulnerability runs through concentrated independent adjuster networks in catastrophe corridors. Distribution runs through direct carrier contracts, broker-embedded TPAs, and managing general agent arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carrier self-insurance and captive formation present substitution threats that claims service providers must neutralize through irreplaceable specialization and technology integration.
For Market Incumbents: Pre-empt carrier vertical integration by deepening proprietary AI capabilities in demand-package analysis and satellite-verified property estimation. Lock in multi-year exclusive deployment agreements with independent adjuster networks in Florida and California to foreclose competitor catastrophe-response capacity. Regulatory pressure from the EU Digital Operational Resilience Act creates compliance-service bundling opportunities that pure technology vendors cannot replicate.
For New Entrants and Emerging Players: Build out cyber claims incident-response capabilities as ransomware coverage expansion outstrips existing forensic accounting supply. Agricultural parametric insurance in France and Australia offers the most penetrable white space, with satellite-triggered settlement workflows requiring minimal legacy system integration. Go-to-market positioning should emphasize API-native architecture that bypasses carrier core-system replacement cycles.
For Investors and Strategic Acquirers: Carve-out targets emerge from large broker consolidations spinning off non-core claims administration units to focus on commission-generating placement. Long-term viability favors technology-enabled platforms with measurable loss-cost reduction documentation over pure labor arbitrage models. Monitor litigation financing volume in Texas and New York as the inflection signal for specialized liability claims management demand.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Platform Development | Natural language processing for demand packages compresses cycle times from days to hours for national carriers. |
| Catastrophe Response Network Expansion | Rapid-deployment adjuster pools in Miami and Houston secure exclusive hurricane and wildfire mobilization contracts. |
| GDPR-Compliant Infrastructure Buildout | Jurisdictional data residency architecture unlocks EU carrier vendor substitution windows under DORA mandates. |
| Cyber Claims Specialization Launch | Ransomware incident response and forensic accounting address coverage growth outpacing existing service supply. |
| Parametric Settlement Automation | Satellite-verified agricultural and flood workflows reduce loss-adjustment expense ratios for index-triggered coverage. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with carrier claims executives, third-party administrator operations directors, independent adjuster network managers, and litigation finance fund administrators. Secondary validation drew from NAIC market conduct examination reports, EU DORA implementation guidance, SEC filings of publicly traded TPAs, and Lloyd's of London syndicate capacity disclosures. Bottom-up service-line revenue builds were triangulated against top-down carrier outsourcing spend estimates.
Calibration against historical outsourcing penetration rates and technology adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass service type complexity tiers, technology deployment maturity, customer purchasing centralization, and end-user geographic exposure patterns. CAGRs were derived from carrier expense ratio targets and vendor substitution elasticity estimates, with inputs including catastrophe frequency baselines and litigation financing volume trends.
Stress conditions across adjuster labor availability, regulatory compliance cost escalation, and AI technology performance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding carrier outsourcing propensity and technology substitution rates. Material shifts in state-level unfair claims settlement practice enforcement or EU data governance interpretation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Europe Travel Insurance Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Crime Insurance Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
Commercial Earthquake Insurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
Global Mobile Phone Insurance Ecosystem Market
Insurance
Germany Health and Medical Insurance Market
Insurance
Asia-Pacific Liability Insurance Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
Germany Electronic Gadgets Insurance Market
Insurance
Global Vehicle Insurance Market
Insurance
Car Insurance Market
Insurance
Asia-Pacific Surety Market
Insurance
UK Dental Insurance Market