
 B2B2C Insurance Market | 2026-2036
B2B2C Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
B2B2C Insurance Market Analysis
Policy administration and claims servicing revenue is fragmenting across embedded distribution partners, eroding traditional carrier control over the customer lifecycle. UnitedHealth Group sustains vertical integration through its Optum health services arm, capturing data flows that strengthen underwriting precision. Ping An Insurance dominates China's ecosystem model, bundling insurance with banking and healthcare through its digital platform. Berkshire Hathaway anchors its competitive position through capital scale and reinsurance leverage rather than technology-led distribution.
B2B2C insurance denotes risk-transfer arrangements where an enterprise intermediary distributes coverage to end consumers, typically embedding policies within a primary transaction such as e-commerce checkout, payroll deduction, or vehicle financing; the architecture relies on API-driven policy issuance, real-time eligibility verification, and automated commission splits between carrier and distribution partner. Health insurance leads service type penetration due to employer mandate structures and rising healthcare costs, while property insurance grows fastest through IoT-enabled embedded home and auto coverage. Online platforms as a distribution channel are displacing agent networks among freelancers and small businesses, though large enterprises still favor broker-mediated bundled services for compliance complexity.
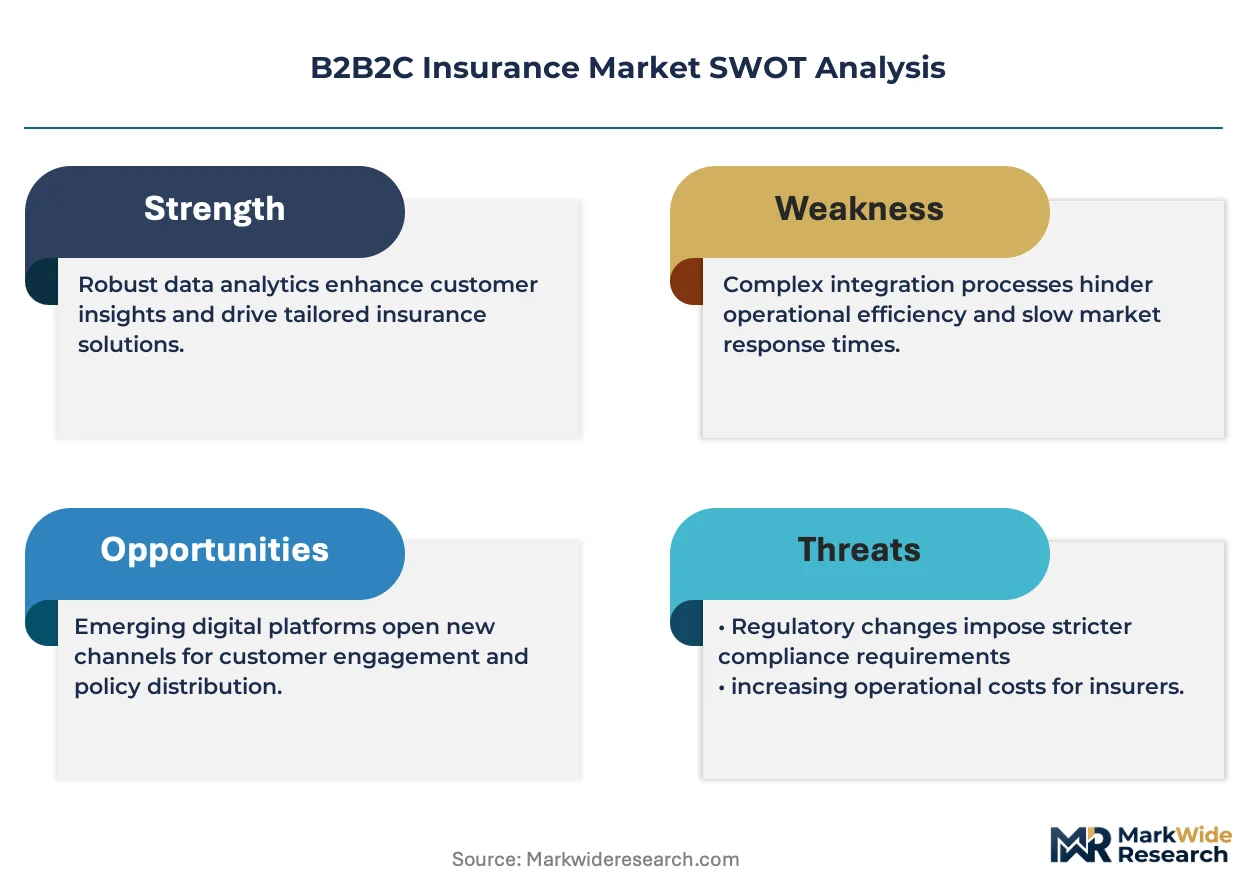
FDA oversight of digital health tools intersects with health insurance product design where wearable data informs dynamic pricing, while the SEC monitors embedded investment-linked coverage and fiduciary disclosure to corporate plan sponsors. The EU AI Act imposes algorithmic transparency requirements on automated underwriting decisions distributed through European digital platforms. Stakeholders must monitor how regulatory fragmentation between data privacy, financial conduct, and insurance solvency standards reshapes partnership economics and technology investment priorities.
Market Dynamics
API standardization is fragmenting policy administration revenue across embedded distribution partners, forcing carriers to surrender direct customer relationships while digital intermediaries capture transaction data and commission flows.
Growth Catalysts
- EU AI Act:Algorithmic transparency mandates across European digital platforms are accelerating carrier investments in explainable underwriting engines, creating competitive differentiation for compliant distributors.
- IoT-enabled auto financing:Connected vehicle data streams embedded at point-of-sale are expanding addressable pools for usage-based coverage among ride-share and delivery fleets.
- Employer-sponsored voluntary benefits:United States payroll deduction structures are concentrating demand for supplemental health and life products through HR technology platforms.
Market Restraints
- Data localization requirements:China's cybersecurity law and India's data protection rules are fragmenting cloud infrastructure for cross-border policy administration, raising compliance costs.
- Legacy core system dependency:Mainframe-based policy administration at incumbent carriers limits real-time API response speeds, constraining embedded checkout integration.
- Reinsurance capacity concentration:Bermuda and London market capacity constraints are hardening rates for catastrophe-exposed property programs distributed through B2B2C channels.
Strategic Opportunities
- Brazil's open finance regime:PIX instant payment infrastructure and regulatory sandbox approvals are enabling insurance embedding within digital banking workflows for underpenetrated middle-market segments.
- Wearable-to-underwriting convergence:Continuous glucose monitors and sleep trackers are creating dynamic pricing models for life and health products through employer wellness platforms.
- Parametric home coverage:IoT water leak sensors and weather station networks are enabling embedded property protection at mortgage origination with automated claims settlement.
Industry Challenges
- Actuarial-technology talent scarcity:Shortage of professionals bridging predictive modeling and insurance pricing is delaying deployment of machine learning-driven eligibility engines.
- Multi-jurisdiction licensing complexity:State-by-state surplus lines approvals and EU passporting variations are extending partner onboarding timelines for platform distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | B2B2C Insurance Market |
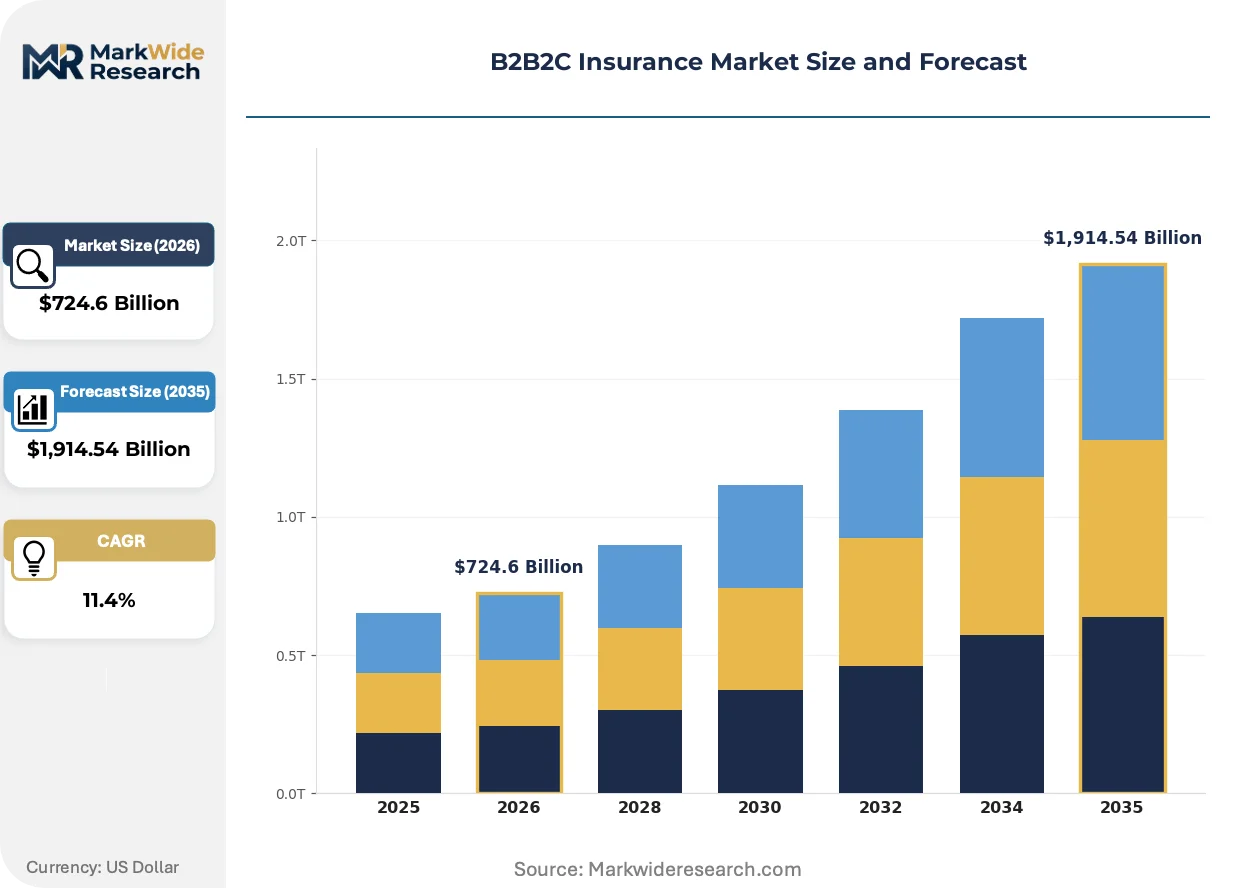
| Market Size in 2026 | $724.6 Billion |
| Market Size in 2035 | $1,914.54 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Life Insurance, Health Insurance, Property Insurance, Liability Insurance Client Type: Corporations, Small Businesses, Freelancers, Large Enterprises Distribution Channel: Online Platforms, Brokers, Direct Sales, Agents Pricing Model: Premium-Based, Pay-Per-Use, Subscription, Bundled Services |
| Companies Covered | Berkshire Hathaway Inc., China Life Insurance Group, UnitedHealth Group Incorporated, Munich Re Group, Zurich Insurance Group AG, Allianz SE, Ping An Insurance (Group) Co. Of China, Swiss Re Ltd, AXA S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
B2B2C Insurance Market Emerging Trajectories
Real-time data ingestion is compressing the gap between risk exposure and pricing adjustment, enabling dynamic policy structures that respond to behavioral signals rather than static demographic segments.
Embedded insurance APIs are digitizing the point-of-sale coverage attachment process, allowing e-commerce platforms and fintech lenders to offer instant policy issuance without redirecting customers to carrier portals. Mid-market retailers and neobanks are adopting these integrations fastest, driven by commission revenue diversification goals. This technology is digitizing traditional agent-mediated distribution, compressing acquisition costs and shifting data ownership toward transaction platforms.
The EU AI Act imposes algorithmic transparency requirements on automated underwriting decisions distributed through European digital platforms, mandating human oversight for high-risk insurance scoring. Carriers must now document training data provenance and model drift monitoring for embedded partner integrations. Small commercial and pet insurance lines face the steepest compliance burden, with distributors in Germany and France accelerating procurement of explainable AI tools to maintain partner eligibility.
Subscription-based coverage models are displacing annual policy renewals in freelance and gig economy segments, with buyers expecting monthly flexibility and cancellation portability. Digital broker platforms and embedded payroll integrations are capturing this demand, unbundling traditional agent servicing relationships. This shift is most visible in United States contingent worker benefits and European platform economy accident coverage, where churn tolerance exceeds price sensitivity.
B2B2C Insurance Market Segmentation
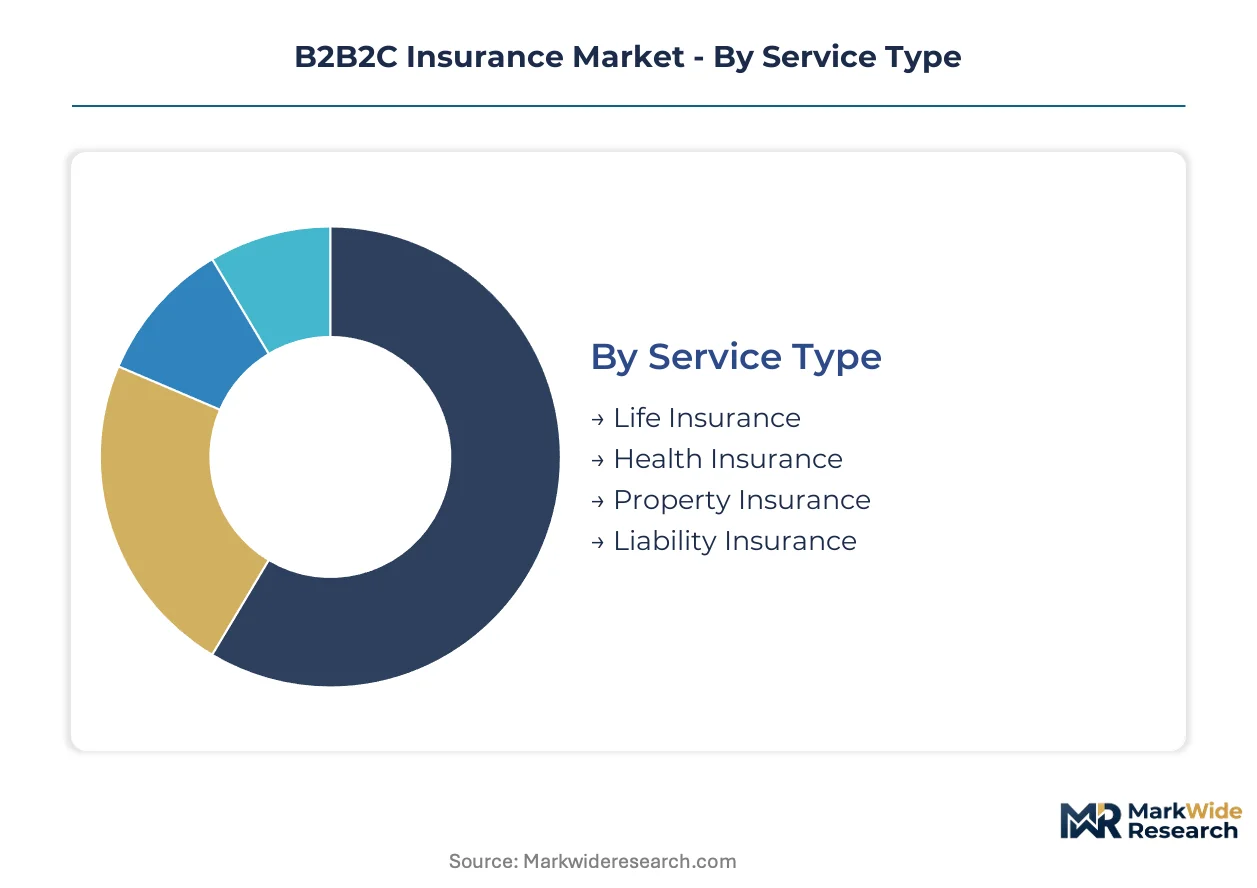
Segmentation in B2B2C insurance reveals how risk-transfer products fragment across distribution architectures and buyer sophistication levels. Understanding these divisions exposes where API-driven embedded distribution captures margin versus where traditional intermediation retains pricing power.
Service Type:
Mature employer-mandated lines anchor revenue stability while emerging sensor-enabled coverage rewrites underwriting economics.
- Health Insurance:Employer-sponsored structures dominate transaction volume through payroll deduction integration with HR technology platforms. United States employer mandate compliance and rising per-employee healthcare costs concentrate demand among large enterprise intermediaries seeking supplemental gap coverage.
- Property Insurance:IoT-enabled embedded home and auto coverage expands fastest through mortgage origination and connected vehicle financing. Sensor networks feeding real-time risk data enable automated claims settlement at point-of-sale, displacing traditional inspection workflows.
- Life Insurance:Simplified issue products attach to digital banking onboarding flows, leveraging instant eligibility verification without medical underwriting delays.
- Liability Insurance:Professional and cyber coverage distributes through freelance management platforms addressing contingent worker protection gaps.
Health Insurance retains volume leadership; Property Insurance holds the steepest expansion curve.
Client Type:
Enterprise scale dictates partnership complexity, with compliance burden separating automated platform integration from broker-mediated procurement.
- Large Enterprises:Multi-state regulatory complexity and fiduciary liability drive preference for bundled broker services over direct platform embedding. Compliance documentation requirements and ERISA oversight sustain intermediary relationships despite higher acquisition costs.
- Freelancers:Gig economy platforms capture this segment through subscription-based portable coverage with monthly cancellation flexibility. Churn tolerance exceeds price sensitivity among contingent workers prioritizing benefit portability across engagements.
- Corporations:Mid-market entities balance compliance support with cost efficiency through digital broker hybrid models.
- Small Businesses:Neobank and payroll platform integrations enable instant coverage attachment without dedicated HR infrastructure.
Large Enterprises command the highest revenue per account; Freelancers expand the addressable base most rapidly.
Distribution Channel:
Digital intermediation captures transaction data ownership while agent networks defend complex commercial relationships.
- Online Platforms:E-commerce checkout and fintech lending workflows embed instant policy issuance via API without carrier portal redirection. Commission revenue diversification drives mid-market retailer and neobank adoption fastest.
- Brokers:Large enterprise bundled services and surplus lines placement retain this channel's relevance where multi-jurisdiction licensing complexity exceeds platform capabilities.
- Agents:Personal lines and small commercial persist in regions with lower digital penetration or regulatory licensing friction.
- Direct Sales:Captive carrier channels concentrate in affinity group marketing and employer voluntary benefit enrollments.
Online Platforms gain share fastest in personal and small commercial lines; Brokers defend the highest-margin enterprise accounts.
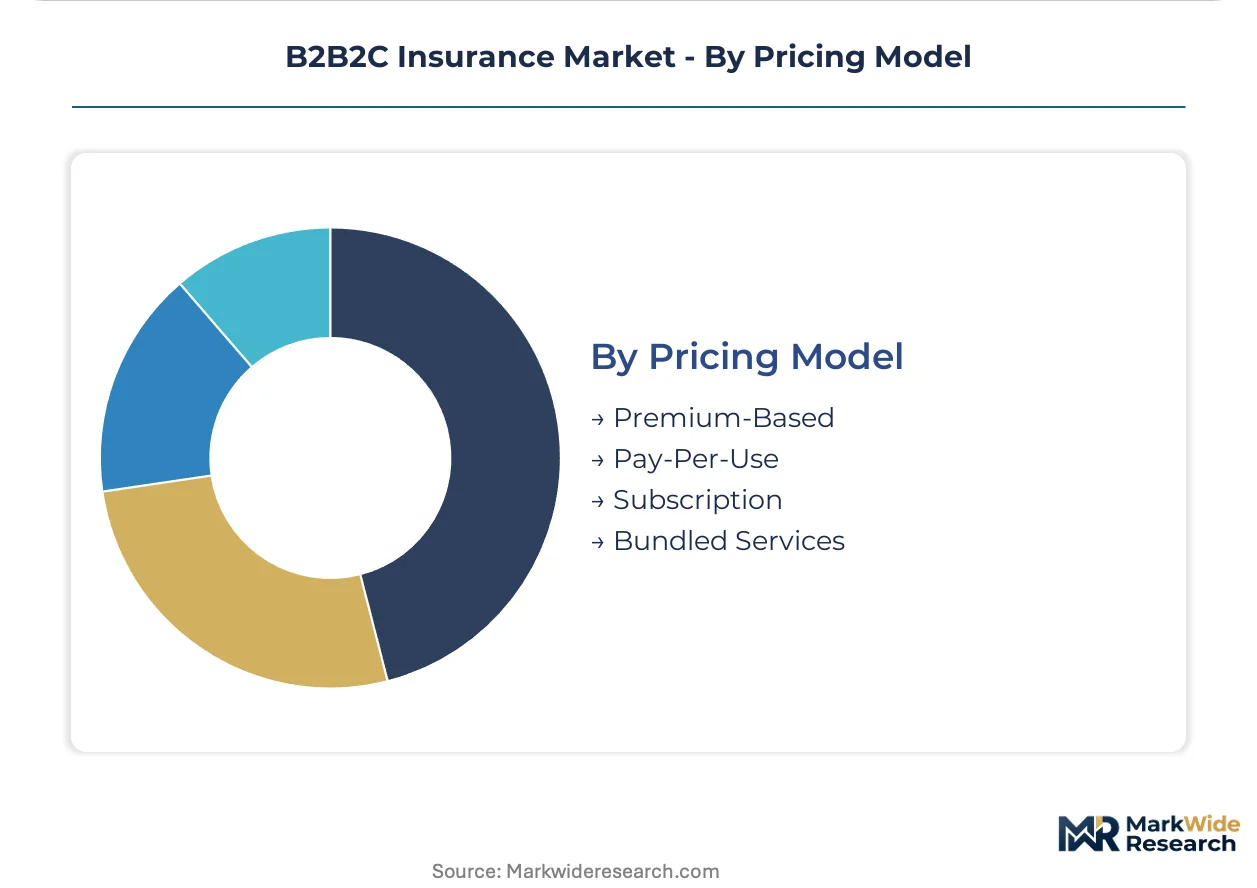
Pricing Model:
Behavioral data feeds dynamic structures that compress traditional annual renewal cycles into responsive risk-adjustment mechanisms.
- Pay-Per-Use:Connected vehicle telematics and IoT sensor data enable usage-based auto and home coverage. Real-time mileage and behavior metrics replace static demographic rating factors for ride-share and delivery fleet operators.
- Subscription:Monthly flexibility and cancellation portability displace annual renewals in freelance benefits and platform economy accident coverage. European digital broker platforms capture this demand through payroll-integrated portability.
- Premium-Based:Traditional risk-pooled rating persists in employer-sponsored health and group life where regulatory filing requirements limit dynamic adjustment.
- Bundled Services:Ecosystem models combine insurance with banking and healthcare through single-platform relationships.
Pay-Per-Use rewrites actuarial fundamentals fastest; Subscription models unlock recurring revenue predictability in volatile segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies: United States employer groups absorb premium increases with minimal attrition, while freelance segments in emerging markets prioritize portability over coverage depth, compressing margins for standardized products.
United States
Employer-sponsored voluntary benefits concentrate demand through HR technology platforms, with payroll deduction structures locking in supplemental health and life coverage. HIPAA portability rules and ERISA fiduciary standards shape product design, mandating disclosure protocols for embedded wellness incentives. The San Francisco Bay Area and New York Metro anchor fintech-insurance partnerships, where neobanks embed instant-issue policies within digital onboarding flows.
China
Ecosystem bundling of insurance with banking and healthcare drives penetration through super-app platforms, capturing transaction data for dynamic underwriting. The national cybersecurity law imposes data localization requirements, fragmenting cloud infrastructure for cross-border policy administration. Shenzhen and Shanghai host the densest clusters of digital insurance intermediaries, where API-driven distribution partnerships with e-commerce platforms scale fastest.
Germany
Mid-market enterprises favor broker-mediated bundled services for compliance complexity, sustaining intermediary relationships despite higher acquisition costs. The EU AI Act mandates algorithmic transparency for automated underwriting decisions, accelerating procurement of explainable AI tools among embedded distributors. Munich and Frankfurt concentrate reinsurance capacity and InsurTech development, bridging traditional carrier infrastructure with platform distribution.
Brazil
PIX instant payment infrastructure enables insurance embedding within digital banking workflows for underpenetrated middle-market segments, bypassing legacy agent networks. The national insurance regulator's sandbox approvals accelerate partnership timelines between carriers and fintech platforms. São Paulo anchors the ecosystem, where open finance regime compliance and neobank distribution partnerships concentrate.
India
Small businesses access instant coverage through payroll platform integrations, eliminating dedicated HR infrastructure requirements. RBI guidelines on digital lending and data protection rules reshape how carriers integrate with non-insurance intermediaries. Mumbai and Bangalore concentrate InsurTech development and digital broker platforms, where API standardization mandates accelerate embedded distribution adoption.
B2B2C Insurance Market Vendor Landscape
Capability concentration sits with technology-integrated carriers; scale advantage sits with diversified conglomerates. The market structures around three tiers: vertically integrated health services groups, capital-heavy reinsurance-led underwriters, and platform-embedded digital distributors. Strategic moves concentrate on API infrastructure investment and ecosystem partnership exclusivity, with carriers racing to secure preferred distribution slots within high-frequency transaction platforms.
Among capital-scale underwriters, Berkshire Hathaway Inc. and Munich Re Group occupy positions anchored by investment float and catastrophe capacity rather than technology-led distribution. UnitedHealth Group exemplifies vertical integration through health services arms that capture data flows strengthening underwriting precision. Within China's ecosystem model, Ping An Insurance (Group) Co. Of China represents the bundled platform approach, combining banking, healthcare, and risk transfer through unified digital infrastructure.
| Leading Market Players |
|---|
| Berkshire Hathaway Inc. |
| China Life Insurance Group |
| UnitedHealth Group Incorporated |
| Munich Re Group |
| Zurich Insurance Group AG |
| Allianz SE |
| Ping An Insurance (Group) Co. Of China |
| Swiss Re Ltd |
| AXA S.A. |
| Others |
Supply Flow & Price Mechanics
Reinsurance capacity concentration in Bermuda and London market hardening rates for catastrophe-exposed property programs, concentrating pricing power with carriers possessing alternative capital structures while eroding margins for distributors dependent on traditional capacity.
Pricing Analysis
Commission revenue from embedded policy issuance drives lifetime value for digital distribution partners, with API integration fees and ongoing servicing splits forming the dominant pricing structure. Price differentiation hinges on data exclusivity agreements and real-time eligibility engine performance, separating premium-tier platforms with proprietary behavioral datasets from standard-tier distributors relying on carrier-provided scoring. Pricing pressure stems from embedded checkout commoditization as neobanks and e-commerce platforms negotiate volume-based rate compression. Large enterprise intermediaries exhibit lowest price sensitivity due to ERISA compliance complexity, while freelance-facing platforms face acute sensitivity from churn-tolerant contingent workers prioritizing portability.
Supply Chain Analysis
Third-party administrator concentration in the United States, India, and Ireland holds capacity for policy administration and claims servicing, with Accenture-owned operations and specialized InsurTech BPOs anchoring carrier outsourcing decisions. Core system dependencies draw from legacy mainframe infrastructure, cloud-native policy engines, and API middleware layers. Single-source vulnerability concentrates in legacy core system providers whose batch-processing architectures constrain real-time embedded integration speeds. Distribution runs through API-driven partner marketplaces where carriers compete for preferred placement slots within high-frequency transaction platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Self-insurance and captive alternatives threaten traditional risk-transfer products as large enterprises internalize predictable exposures, forcing incumbents to demonstrate tangible underwriting value beyond balance-sheet intermediation.
For Market Incumbents: Build data moat exclusivity through wearable-to-underwriting convergence and continuous health monitoring partnerships that substitute carriers cannot replicate. Secure preferred API placement slots within neobank and HR technology platforms before distribution capacity saturates. Invest in explainable AI tooling to preempt EU AI Act compliance disqualification among European embedded partners.
For New Entrants and Emerging Players: Establish a beachhead in Brazil's open finance regime where PIX infrastructure enables insurance embedding without legacy agent network displacement costs. Target India's small business payroll platform segment where RBI guidelines on digital lending create partnership entry points. Lead with parametric home coverage at mortgage origination, leveraging IoT sensor networks for automated claims differentiation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital broker platforms as cloud-native policy engines reduce core system replacement costs. Prioritize acquisition targets with exclusive distribution agreements in high-frequency transaction verticals and proprietary behavioral data streams. Monitor reinsurance capacity availability in Bermuda and London as inflection indicator for property program margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| API Infrastructure Investment | Real-time policy issuance capability secures preferred placement within neobank onboarding flows. |
| Wearable Data Partnership | Continuous glucose monitor integration enables dynamic health pricing through employer wellness platforms. |
| Explainable AI Procurement | EU AI Act compliance maintains embedded distribution eligibility across German and French digital platforms. |
| Parametric Coverage Development | IoT water leak sensors at mortgage origination displace traditional property inspection workflows. |
| Open Finance Compliance | Brazilian regulatory sandbox approvals accelerate carrier-fintech partnership timelines beyond traditional licensing. |
Methodological Framework
Initial hypotheses were tested against primary input from carrier product development executives, embedded distribution platform CTOs, reinsurance broker placement specialists, and HR technology procurement leads and refined through secondary validation. Sources included SEC insurance holding company filings, NAIC statutory financial statements, EU regulatory implementation guidance, and embedded finance partnership announcements. Bottom-up policy issuance volume estimates triangulated against top-down carrier premium growth disclosures.
Demand-supply balance across the analysis window reflects employer-sponsored voluntary benefits absorption capacity, freelance platform churn tolerance, and reinsurance capacity availability for catastrophe-exposed programs. Segmentation dimensions modeled encompass service type, client scale tier, distribution channel architecture, and pricing model structure. CAGRs derived from insurer premium growth trajectories, embedded partnership disclosure patterns, and HR technology platform expansion rates.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting investment float returns and employer healthcare budget elasticity would shift the trajectory. Forecasts reflect assumptions regarding API standardization adoption curves and regulatory sandbox approval velocities. Quarterly review of embedded partnership announcement velocity and reinsurance renewal rate indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Vietnam Private Health Insurance Market
Insurance
Asia-Pacific Travel Insurance Market
Insurance
Global AI in Auto-Insurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
Bancassurance in ASEAN Market
Insurance
Canada Property and Casualty Insurance Market
Insurance
Europe Car Insurance Market
Insurance
Consumer Electronics Extended Warranty Market
Insurance
Internet of Things Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
Europe Parametric Insurance Market
Insurance
US Extended Warranty Market
Insurance
Earthquake Insurance Market
Insurance
Europe EV Insurance Market
Insurance
UK Dental Insurance Market
Insurance
Global Long Term Care Insurance Market