
 Digital Transformation in Insurance Market | 2026-2036
Digital Transformation in Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Transformation in Insurance Market Analysis
Modular platform bundling is realigning how insurers procure technology stacks. Cognizant leverages its cloud-native insurance suites to anchor large carrier relationships across North America. Capgemini competes through embedded finance integrations that extend legacy core systems into distribution partnerships. Shift Technology specializes in AI-driven fraud detection, occupying a defensible niche in claims automation.
Digital transformation in insurance encompasses the systematic replacement of manual underwriting, policy administration, and claims processing with API-orchestrated software architectures operating at sub-second response thresholds. Its primary commercial purpose is to compress expense ratios while enabling real-time risk pricing and personalized product assembly. Cloud Computing and AI Solutions represent the deepest margin pools, as carriers migrate actuarial workloads from on-premises mainframes to elastic infrastructure. SaaS delivery models are displacing perpetual license arrangements fastest among mid-tier health insurers seeking predictable operational expenditure structures.
FDA oversight of software-as-medical-device interfaces intersects with state-level NAIC model laws governing algorithmic fairness in underwriting. The EU AI Act and GDPR collectively mandate explainable decision trees for automated policy recommendations, reshaping vendor development roadmaps. Stakeholders must monitor how fragmented compliance obligations across federal, state, and supranational layers will dictate platform architecture choices and partner selection criteria.
Market Dynamics
Property insurers are deploying IoT-enabled underwriting platforms that compress risk assessment cycles from weeks to hours, fundamentally restructuring how carriers allocate capital across portfolios. This acceleration is forcing wholesale reconfiguration of actuarial workflows, vendor relationships, and regulatory compliance architectures.
Growth Catalysts
- EU AI Act mandates:The EU AI Act's algorithmic transparency requirements for automated claims decisions are compelling carriers to modernize legacy infrastructure, creating immediate procurement demand for explainable AI systems.
- Telematics penetration in auto:Connected vehicle data streams enable real-time premium adjustments, pulling adoption across commercial fleet operators seeking usage-based coverage models.
- German InsurTech clusters:Venture capital concentration in Munich and Berlin is producing specialized vendors that export platform innovations to neighboring European markets.
Market Restraints
- Core system replacement costs:Mainframe migration to cloud-native architectures demands capital commitments that mid-tier carriers defer, perpetuating technical debt.
- Talent scarcity in actuarial data science:The intersection of traditional underwriting expertise and machine learning fluency remains thinly staffed across the sector.
- Fragmented state-level regulation:NAIC model laws governing algorithmic fairness vary in adoption intensity across US jurisdictions, complicating national platform rollouts.
Strategic Opportunities
- Embedded finance convergence:Distribution partnerships with automotive OEMs and e-commerce platforms enable point-of-sale policy origination without traditional agent networks.
- Parametric product expansion:Climate risk instruments tied to objective triggers address protection gaps in agricultural and commercial property segments.
- India's digital infrastructure:The country's stack of Aadhaar, UPI, and digilocker systems enables frictionless KYC and claims verification for greenfield InsurTech entrants.
Industry Challenges
- Interoperability with legacy policy administration systems:API orchestration layers must reconcile real-time digital front-ends with batch-processed back-office databases, inflating integration timelines.
- GDPR-EU AI Act compliance sequencing:Carriers face overlapping obligations for data portability, right-to-explanation, and algorithmic audit trails that strain legal and technical resources simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Transformation in Insurance Market |
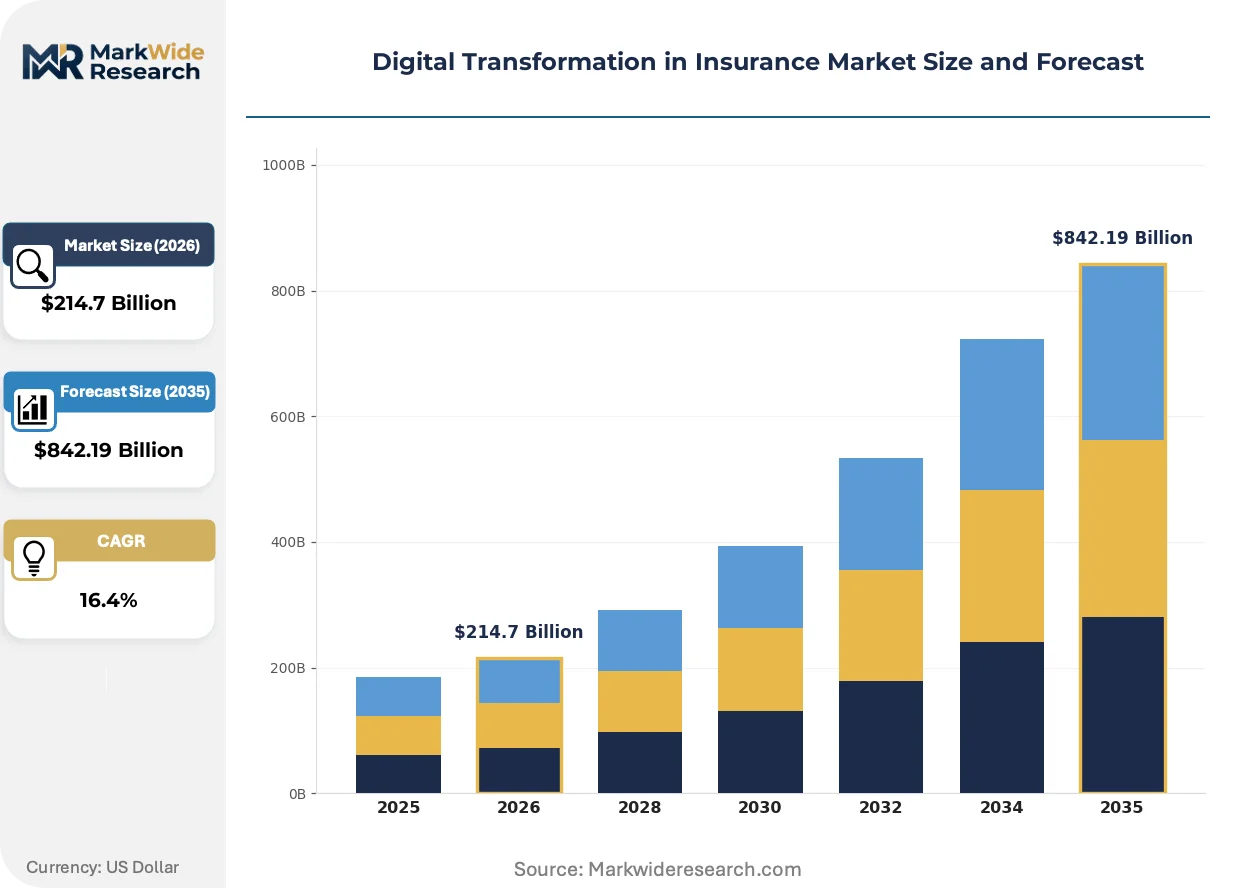
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $842.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud Computing, Data Analytics, Automation Tools, AI Solutions Delivery Model: On-Premises, Hybrid, SaaS, Managed Services End User: Life Insurers, Property Insurers, Health Insurers, Specialty Insurers Technology: Blockchain, IoT, Machine Learning, Cybersecurity |
| Companies Covered | Cognizant, Capgemini, G&Co., NTT DATA, Deloitte Digital, Boston Consulting Group, Bain & Company, Shift Technology, McKinsey & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Transformation in Insurance Market Emerging Trajectories
Insurance technology stacks are converging around API-first architectures that enable modular assembly of underwriting, pricing, and claims capabilities. This shift is dismantling the monolithic core system model that dominated carrier procurement for decades.
Computer vision is automating property damage assessment through aerial imagery and mobile capture tools. Commercial property carriers are deploying these systems across catastrophe response teams to accelerate claim triage. The technology is automating adjuster dispatch decisions, compressing initial reserve estimates from days to minutes.
The EU AI Act's risk-based classification system for automated decision-making is mandating human-in-the-loop protocols for high-stakes underwriting algorithms. Carriers operating across European markets must maintain audit trails demonstrating explainability thresholds. Health and life insurers face the steepest compliance burdens given the sensitivity of biometric data inputs.
Mid-tier health insurers are abandoning perpetual software licenses for subscription-based SaaS arrangements that convert capital expenditure to operational expenditure. This procurement recalibration favors vendors offering consumption-priced infrastructure over traditional enterprise sales cycles. The shift is most pronounced among regional carriers in Germany and the United States seeking predictable technology cost structures.
Digital Transformation in Insurance Market Segmentation
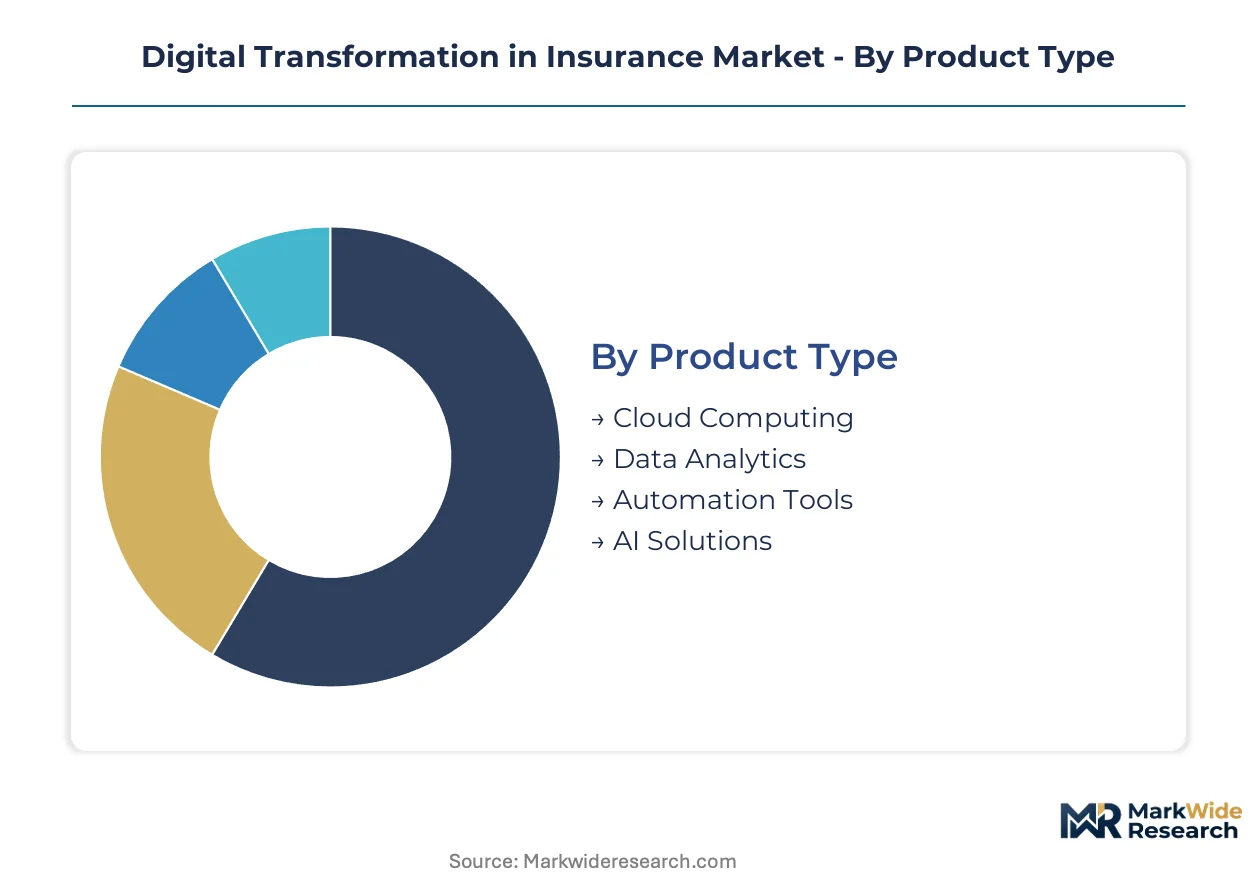
Segmentation in digital insurance transformation reveals how procurement priorities diverge across infrastructure layers and regulatory exposure levels. Carriers weight compliance burden against modernization velocity when allocating technology budgets across product categories.
Product Type:
Cloud Computing and AI Solutions carry the heaviest certification obligations under EU AI Act algorithmic audit requirements and FDA software-as-medical-device pathways for health underwriting applications.
- Cloud Computing:Elastic infrastructure enables actuarial workload migration from on-premises mainframes to consumption-priced environments. Demand concentrates among mid-tier health insurers in Germany and the United States seeking predictable operational expenditure structures.
- AI Solutions:Machine learning models for automated underwriting and claims decisions require explainable decision tree architectures to satisfy GDPR right-to-explanation mandates and EU AI Act transparency thresholds. Health and life insurers face the steepest compliance burdens given biometric data sensitivity.
- Data Analytics:Real-time risk pricing engines process telematics streams and IoT sensor feeds for usage-based coverage models.
- Automation Tools:Robotic process automation compresses policy administration cycles from batch to near-real-time processing.
Leading the category by volume: Cloud Computing. Growing fastest: AI Solutions.
Delivery Model:
Procurement patterns split between capital-intensive on-premises retention and subscription-based conversions favored by carriers managing technical debt.
- SaaS:Subscription arrangements displace perpetual licenses fastest among regional health insurers seeking to convert capital expenditure to operational expenditure. Germany's InsurTech clusters in Munich and Berlin export consumption-priced platform innovations to neighboring European markets.
- Hybrid:Mixed architectures reconcile real-time digital front-ends with batch-processed legacy policy administration systems through API orchestration layers.
- Managed Services:Third-party infrastructure operation appeals to specialty insurers lacking in-house cloud engineering capabilities.
- On-Premises:Mainframe-dependent carriers defer cloud migration due to core system replacement cost constraints, perpetuating technical debt.
Expanding most quickly: SaaS. Retaining largest installed base: On-Premises.
End User:
Regulatory intensity varies by line of business, with health and life segments facing overlapping FDA and NAIC model law obligations that property and specialty carriers largely avoid.
- Health Insurers:Algorithmic fairness requirements under state-level NAIC model laws and HIPAA interoperability mandates drive platform modernization. Mid-tier regional carriers in the United States lead SaaS procurement for predictable cost structures.
- Property Insurers:IoT-enabled underwriting platforms compress risk assessment cycles from weeks to hours, with commercial fleet operators pulling telematics adoption for usage-based coverage.
- Life Insurers:Biometric data inputs trigger EU AI Act high-risk classification, mandating human-in-the-loop protocols and audit trail maintenance.
- Specialty Insurers:Parametric climate risk instruments address agricultural and commercial property protection gaps through objective trigger mechanisms.
Deploying capital fastest: Property Insurers. Facing steepest compliance stack: Health Insurers.
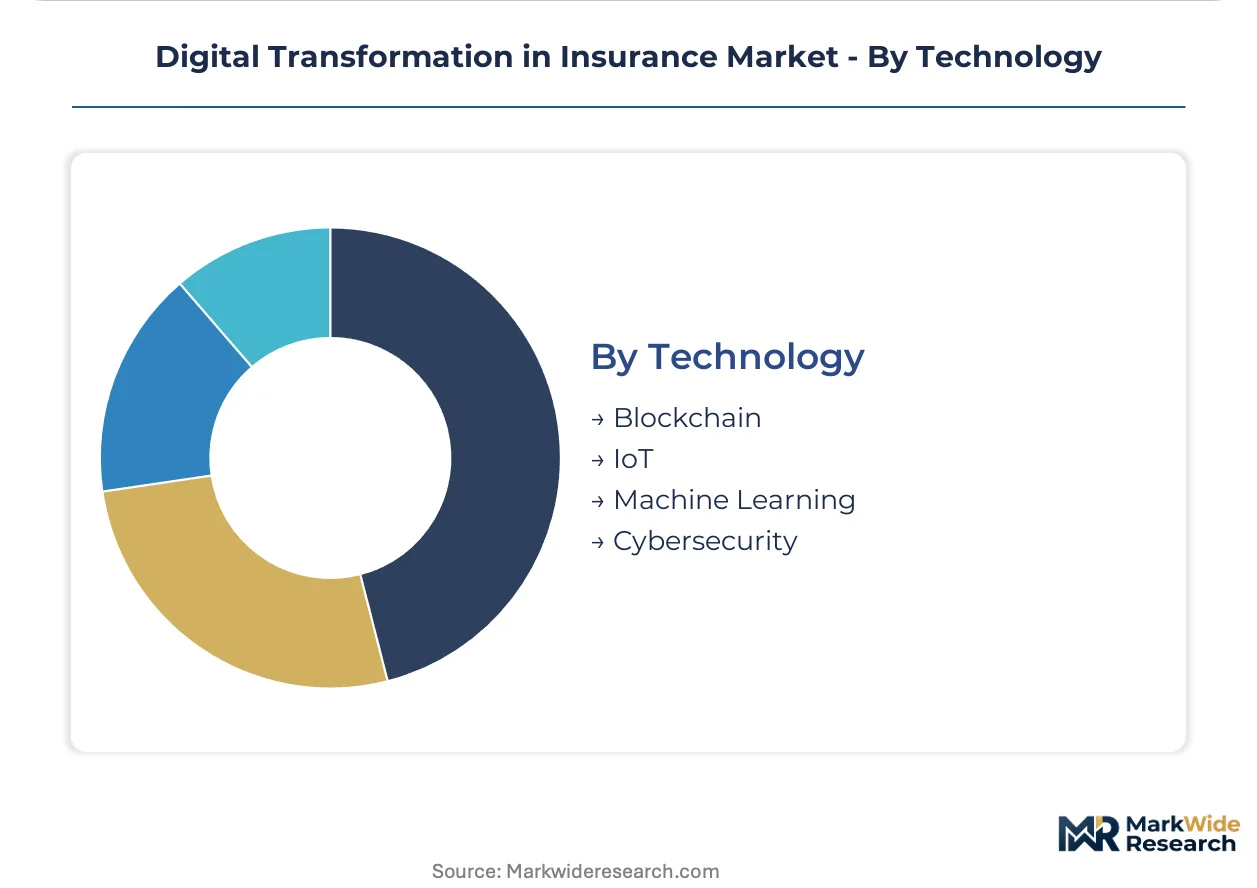
Technology:
Cybersecurity and IoT implementations intersect with sector-specific regulators, while blockchain and machine learning navigate fragmented state-level and supranational frameworks.
- IoT:Connected vehicle and property sensor networks enable real-time premium adjustments. Property insurers deploy these systems across catastrophe response teams to accelerate claim triage and automate adjuster dispatch decisions.
- Machine Learning:Predictive models for fraud detection and risk scoring require explainability documentation under EU AI Act risk-based classification systems.
- Cybersecurity:Data protection architectures must reconcile GDPR data portability requirements with NAIC model law provisions on algorithmic fairness.
- Blockchain:Distributed ledger applications for smart contracts and parametric claims settlement face regulatory ambiguity across US state jurisdictions.
Claiming largest deployment base: IoT. Gaining share fastest: Machine Learning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's InsurTech clusters in Munich and Berlin operate within designated innovation zones that channel venture capital into specialized platform vendors. These concentrations are reshaping how carriers across neighboring markets procure digital infrastructure.
United States
Mid-tier health insurers in regional markets are converting capital expenditure to operational expenditure through SaaS procurement models. State-level NAIC model laws on algorithmic fairness create fragmented compliance obligations that complicate national platform rollouts. The Southeast and Midwest regions host carriers accelerating cloud migration to escape mainframe technical debt.
Germany
Munich and Berlin clusters export consumption-priced platform innovations to neighboring European markets. The EU AI Act mandates explainable decision trees for automated policy recommendations, forcing carriers to modernize legacy infrastructure. Bavaria's density of established carriers and InsurTech startups creates concentrated demand for API-orchestrated software architectures.
United Kingdom
Lloyd's syndicates and commercial carriers are deploying IoT-enabled underwriting platforms that compress risk assessment cycles. GDPR data portability requirements intersect with algorithmic audit obligations under the EU AI Act's risk-based classification system. London's financial services concentration anchors demand for real-time risk pricing engines.
India
Greenfield InsurTech entrants leverage the country's digital infrastructure stack of Aadhaar, UPI, and DigiLocker for frictionless KYC and claims verification. The RBI and IRDAI regulate embedded finance partnerships between insurers and fintech platforms. Maharashtra and Karnataka host venture-funded startups building parametric products for agricultural protection gaps.
Japan
Life insurers face steep compliance burdens under METI guidelines for algorithmic transparency in biometric data processing. The country's aging demographic pulls demand for personalized health underwriting platforms. Tokyo's carrier headquarters concentrate procurement authority for cloud-native core system replacements.
Digital Transformation in Insurance Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the digital insurance transformation market. Tier-one IT services firms anchor large carrier relationships through comprehensive cloud-native suites, while boutique consultancies capture premium fees for strategy advisory. Strategic archetypes include platform-anchored systems integrators, AI-native fraud detection specialists, and embedded finance enablers. Competitive moves concentrate on M&A to acquire actuarial data science talent and strategic partnerships with automotive OEMs for point-of-sale policy origination.
Among the named players, Cognizant and Capgemini occupy positions as diversified systems integrators with carrier relationships spanning multiple continents. Shift Technology exemplifies the AI-native specialist archetype, anchoring a defensible niche in claims automation. These three companies represent the strategic spectrum from broad platform bundling to targeted algorithmic solutions.
| Leading Market Players |
|---|
| Cognizant |
| Capgemini |
| G&Co. |
| NTT DATA |
| Deloitte Digital |
| Boston Consulting Group |
| Bain & Company |
| Shift Technology |
| McKinsey & Company |
| Others |
Supply Flow & Price Mechanics
Horizontal integration through API-orchestrated platform bundling anchors both supply positioning and pricing power for digital insurance vendors. Carriers purchasing cloud-native suites from systems integrators face compressed negotiation leverage when procurement concentrates among Cognizant and Capgemini, while specialized fraud-detection vendors like Shift Technology command premium positioning through defensible algorithmic IP.
Pricing Analysis
Lead-time-driven pricing differentiation separates SaaS vendors offering immediate deployment from legacy migration projects stretching across quarters. Subscription models stratify across premium, standard, and economy tiers based on API call volume and compliance certification level. Cost compression in the mid-tier health segment intensifies as carriers convert capital expenditure to operational expenditure. Regional health insurers in Germany exhibit highest price sensitivity due to predictable cost structure mandates, while life insurers accepting biometric data processing burdens show lowest sensitivity.
Supply Chain Analysis
Local-content rules under the EU AI Act reshape sourcing toward European explainable-AI development centers. Cloud infrastructure concentrates in the United States, Germany, and India, with actuarial workload migration feeding from hyperscaler capacity in these hubs. Talent scarcity in actuarial data science creates single-source vulnerability for machine learning model development. Distribution runs through direct enterprise sales for large carriers and InsurTech platform marketplaces for mid-tier regional players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first architectures are displacing monolithic core systems as the defining technology transition, compressing procurement cycles and rewiring vendor relationships across property, health, and life segments.
For Market Incumbents: To counter embedded-finance entrants from automotive OEMs and e-commerce platforms, legacy carriers should deepen backward integration into proprietary telematics data streams and accelerate certification investment for EU AI Act algorithmic audit compliance.
For New Entrants and Emerging Players: Automotive OEM distribution partnerships offer the most penetrable channel for point-of-sale policy origination, particularly targeting commercial fleet operators seeking usage-based coverage models in Germany and the United States.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by tier-one IT services firms seeking actuarial data science talent, with long-term viability hinging on regulatory technology moats. Watch FDA software-as-medical-device pathway decisions as the inflection signal for health underwriting platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables modular underwriting assembly for Munich and Berlin InsurTech clusters. |
| EU AI Act Compliance Certification | Establishes explainable-AI audit trails for automated claims decisions. |
| Embedded Finance Partnership | Extends distribution into automotive OEM point-of-sale channels. |
| Acquisition of Fraud Detection Specialist | Captures defensible algorithmic IP in claims automation. |
| Telematics Data Supply Agreement | Secures real-time risk pricing inputs from connected vehicle fleets. |
Methodological Framework
Multi-period observation of SaaS procurement volumes, EU AI Act implementation timelines, and InsurTech venture deployment anchored the trend analysis, supplemented by interviews with carrier CTOs, InsurTech platform engineers, regulatory compliance officers, and health insurer procurement leads. Secondary validation drew from SEC 10-K filings, EIOPA supervisory reports, IRDAI regulatory circulars, and NAIC model law adoption tracking. Bottom-up carrier technology spend estimates triangulated against top-down vendor revenue disclosures.
Input-output matrices modeled deployment model, organization size, line of business, and regional regulatory cluster across the projection horizon. CAGRs derived from elasticity-adjusted technology adoption curves and actuarial workload migration patterns. Cloud infrastructure pricing indices and algorithmic audit cost benchmarks fed sensitivity scenarios.
Caveats apply where EU AI Act enforcement intensity or FDA software-as-medical-device reclassification could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
India Dental Insurance Market
Insurance
Canada Property and Casualty Insurance Market
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
Boiler Insurance Market
Insurance
Engineering Insurance Market
Insurance
Asia-Pacific Mobile Phone Insurance Market
Insurance
Reinsurance Market
Insurance
Telematics-Based Auto Insurance Market
Insurance
Green Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
Germany Health and Medical Insurance Market
Insurance
France Car Insurance Market
Insurance
Parametric Insurance Market
Insurance
Commercial Earthquake Insurance Market
Insurance
India Parametric Insurance Market
Insurance
Africa Microinsurance Market