
 Djibouti Insurance Market | 2026-2036
Djibouti Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Djibouti Insurance Market Intelligence
Maritime logistics is realigning risk coverage priorities across Djibouti's insurance landscape. United Insurance Company Djibouti leverages its coastal proximity to dominate marine cargo policies. Salama Assurances Djibouti anchors its portfolio in health and accident lines for port workers. African Reinsurance Corporation (Africa Re) extends capacity to local underwriters facing large infrastructure exposures.
Djibouti insurance comprises risk transfer contracts underwritten by licensed domestic carriers and foreign branches, governed by minimum capital requirements and policy form approvals. The primary purpose is indemnifying policyholders against property damage, bodily injury, or life contingencies while mobilizing long-term savings. Health insurance leads premium growth as employer mandates expand, while property insurance occupies the mature margin pool concentrated in port and logistics assets. Online platforms represent the fastest-growing distribution channel, though brokers still control complex commercial placements.
The country's national insurance regulator enforces solvency margins and mandatory coverage lines, while the central bank supervises bancassurance partnerships. CNSS participation in social security creates a parallel coverage layer that shapes private insurer product design. Stakeholders must monitor how port infrastructure expansion and regional trade corridor developments alter risk accumulation patterns.
Market Dynamics
Port infrastructure expansion at Doraleh and the Ethiopia-Djibouti trade corridor is concentrating risk accumulation patterns, forcing underwriters to recalibrate marine cargo and logistics liability portfolios.
Growth Catalysts
- Mandatory motor third-party liability:The country's national insurance regulator enforces universal auto coverage, creating a stable premium base that subsidizes commercial line development.
- Employer health mandates:Expanding requirements for port and logistics firms to cover workers are accelerating group health policy uptake in Djibouti City.
- Maritime traffic surge:Container volumes through Doraleh Multi-Purpose Port are driving demand for marine cargo and hull insurance from logistics operators.
Market Restraints
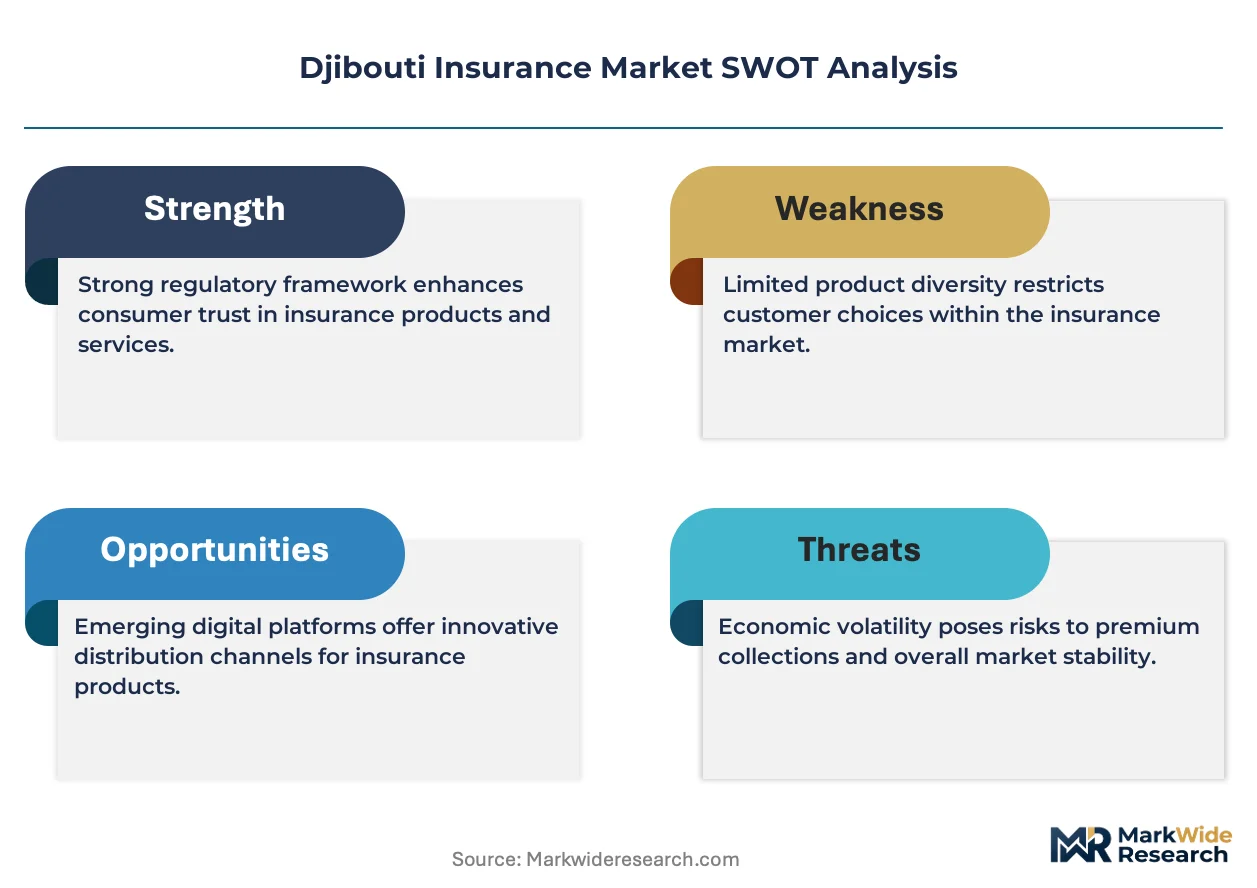
- Capital adequacy thresholds:Minimum solvency margins enforced by the national insurance regulator constrain smaller domestic carriers from underwriting large infrastructure risks.
- Reinsurance dependency:Local underwriters rely on African Reinsurance Corporation capacity for major port and logistics exposures, creating concentration risk in regional reinsurance supply.
- Limited actuarial talent pool:Djibouti lacks trained risk modelers for complex marine and energy lines, forcing reliance on foreign technical services.
Strategic Opportunities
- Rural health penetration:Employer mandates have saturated Djibouti City, leaving Ali Sabieh and Dikhil regions as underpenetrated markets for micro-health products.
- Bancassurance expansion:Central bank supervised partnerships between lenders and insurers offer untapped distribution through Djibouti's banking network.
- Digital platform integration:Online policy issuance and claims processing represent emerging channels that bypass traditional broker-controlled commercial placements.
Industry Challenges
- Legacy system integration:Domestic carriers struggle to connect new digital distribution platforms with core policy administration systems built for paper-based workflows.
- Claims adjudication capacity:Port-related marine cargo disputes require specialized surveyors and adjusters that remain scarce in the local market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Djibouti Insurance Market |
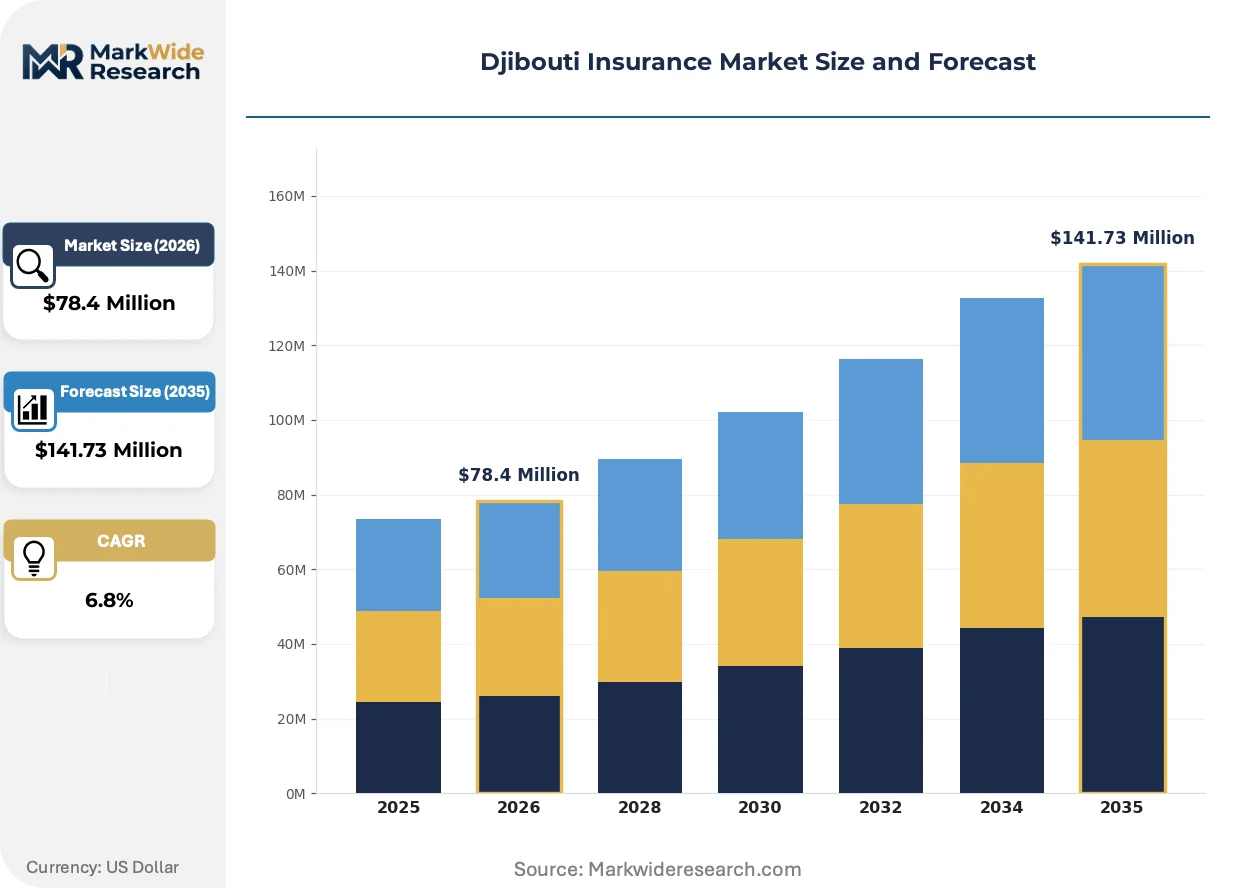
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Health Insurance, Property Insurance, Automobile Insurance Customer Type: Individuals, Corporates, SMEs, Government Distribution Channel: Direct Sales, Brokers, Agents, Online Platforms Coverage Type: Comprehensive, Third-Party, Personal Accident, Travel Insurance |
| Companies Covered | Salama Assurances Djibouti, United Insurance Company Djibouti, GARGASSO Assurance Djibouti, Djibouti Assurance Vie, Caisse Nationale de Sécurité Sociale (CNSS), Djibouti General Insurance Company, African Reinsurance Corporation (Africa Re), Nile Insurance Company Djibouti Branch, GXA Assurances, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Djibouti Insurance Market Strategic Shifts & Innovations
Technology adoption is compressing distribution timelines while regulatory mandates reshape product structures and buyer expectations across Djibouti's insurance landscape.
Telematics-enabled usage-based motor policies are overtaking traditional fixed-premium auto coverage. Fleet operators at Djibouti's port logistics hubs are piloting GPS-linked premium calculations that adjust to actual vehicle utilization and route risk profiles. This data-driven approach is compressing adverse selection in commercial auto portfolios and enabling precise risk-based pricing that static underwriting cannot match.
The country's national insurance regulator has tightened solvency margin requirements and mandated electronic policy registration for all commercial lines. This regulatory pressure is forcing smaller domestic carriers to consolidate or seek foreign capital injections to maintain licensing. Large infrastructure risks—particularly port construction and marine cargo—now face extended approval timelines as the regulator scrutinizes reinsurance backing quality.
Corporate risk managers at Djibouti-based logistics firms are unbundling insurance procurement from bundled broker relationships. These buyers now separate risk placement, claims advocacy, and risk engineering services, selecting specialized providers for each function. This fragmentation is most visible among Ethiopia-Djibouti corridor operators who demand transparent fee structures and direct insurer relationships for their cross-border exposures.
Djibouti Insurance Market Segmentation
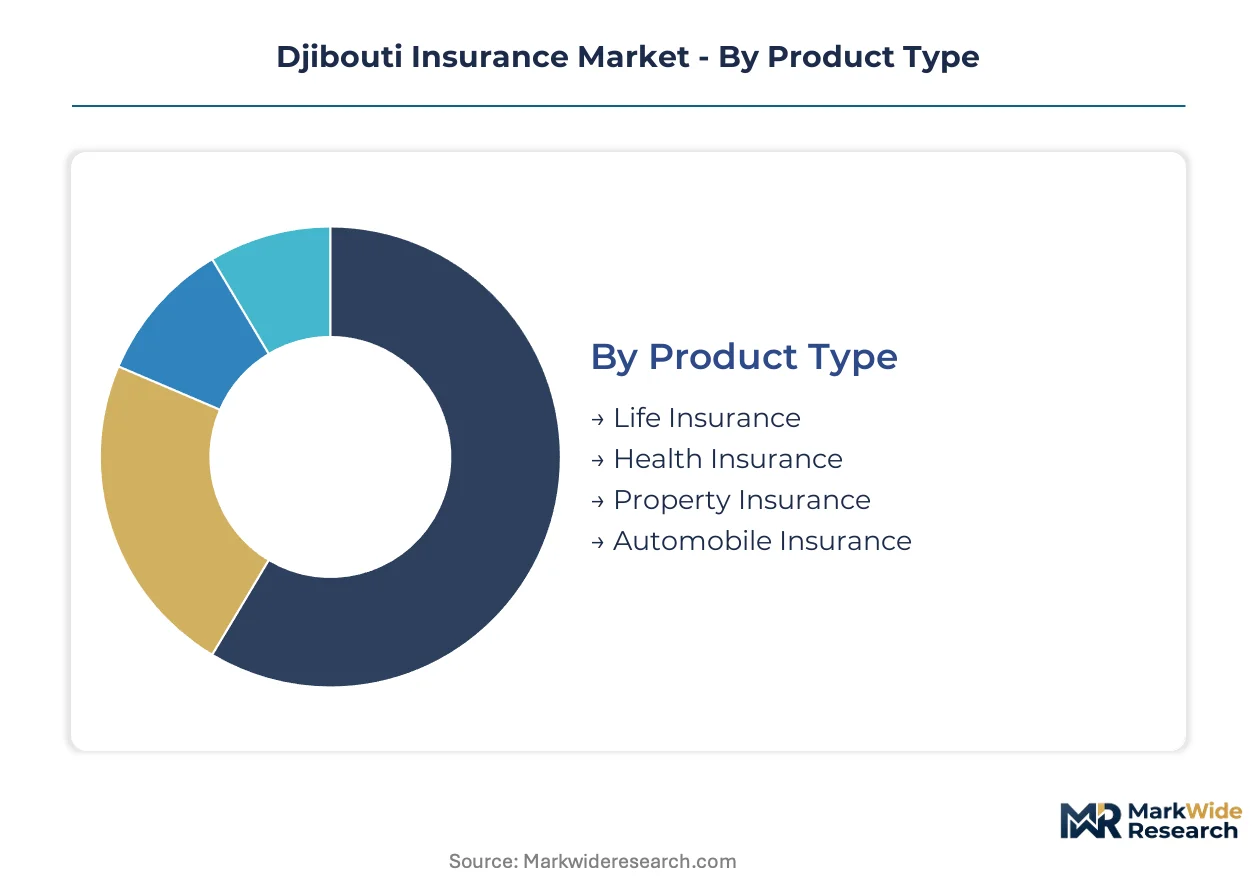
Djibouti's insurance market segments reflect divergent capital requirements and risk profiles. Product lines demand varying technical reserves, while distribution channels require differentiated infrastructure investments. Understanding these structural divides reveals where premium dollars concentrate and which segments absorb regulatory pressure.
Product Type:
Capital intensity separates life and health lines from property and auto coverage, with long-duration liabilities demanding the heaviest solvency backing.
- Life Insurance:Long-term contractual savings products with mortality risk components require substantial statutory reserves. Demand concentrates among salaried employees in Djibouti City's banking and logistics sectors, driven by CNSS supplementary coverage gaps and formal employment expansion.
- Health Insurance:Medical expense reimbursement and hospitalization coverage carry volatile claims frequency. Employer mandates at Doraleh port facilities and Ethiopia-Djibouti corridor operators are accelerating group policy uptake, though rural penetration in Ali Sabieh remains minimal.
- Property Insurance:Fire and marine cargo coverage for port infrastructure and logistics assets. Doraleh Multi-Purpose Port operators dominate commercial placements.
- Automobile Insurance:Motor third-party liability is mandatory per national regulator enforcement, creating a stable premium base subsidizing comprehensive coverage development.
Most installed capacity flows through Health Insurance. Expansion is steepest in Property Insurance.
Customer Type:
Contract sophistication and purchasing power stratify the buyer base, with corporates commanding tailored risk engineering and individuals receiving standardized products.
- Corporates:Large logistics firms and port operators with complex multi-line programs requiring dedicated account management and captive retention structures. Ethiopia-Djibouti trade corridor participants are unbundling broker relationships and demanding direct insurer access.
- SMEs:Small trading enterprises and transport operators with simplified package policies and limited risk management staff. Digital platform distribution is gaining traction among this cost-sensitive segment.
- Individuals:Salaried workers purchasing motor and health coverage through employer channels or direct sales. Mandatory auto liability creates universal participation.
- Government:Public sector employee schemes and state-owned enterprise placements with extended procurement cycles and sovereign risk considerations.
Corporate accounts generate the densest premium concentration. SME digital adoption is climbing fastest.
Distribution Channel:
Channel economics determine reach and margin capture, with technology-enabled platforms compressing acquisition costs against relationship-heavy intermediaries.
- Brokers:Control complex commercial placements for port and logistics risks, commanding fee-based compensation for risk engineering and claims advocacy services.
- Online Platforms:Direct-to-consumer issuance and policy administration with automated underwriting. Fleet telematics integration is piloting usage-based motor pricing for logistics operators.
- Direct Sales:Insurer-employed representatives targeting individual life and health products through employer group schemes.
- Agents:Commission-based intermediaries with localized relationships in Dikhil and rural districts where digital penetration lags.
Broker networks handle the largest risk placements. Online platforms are scaling most aggressively.
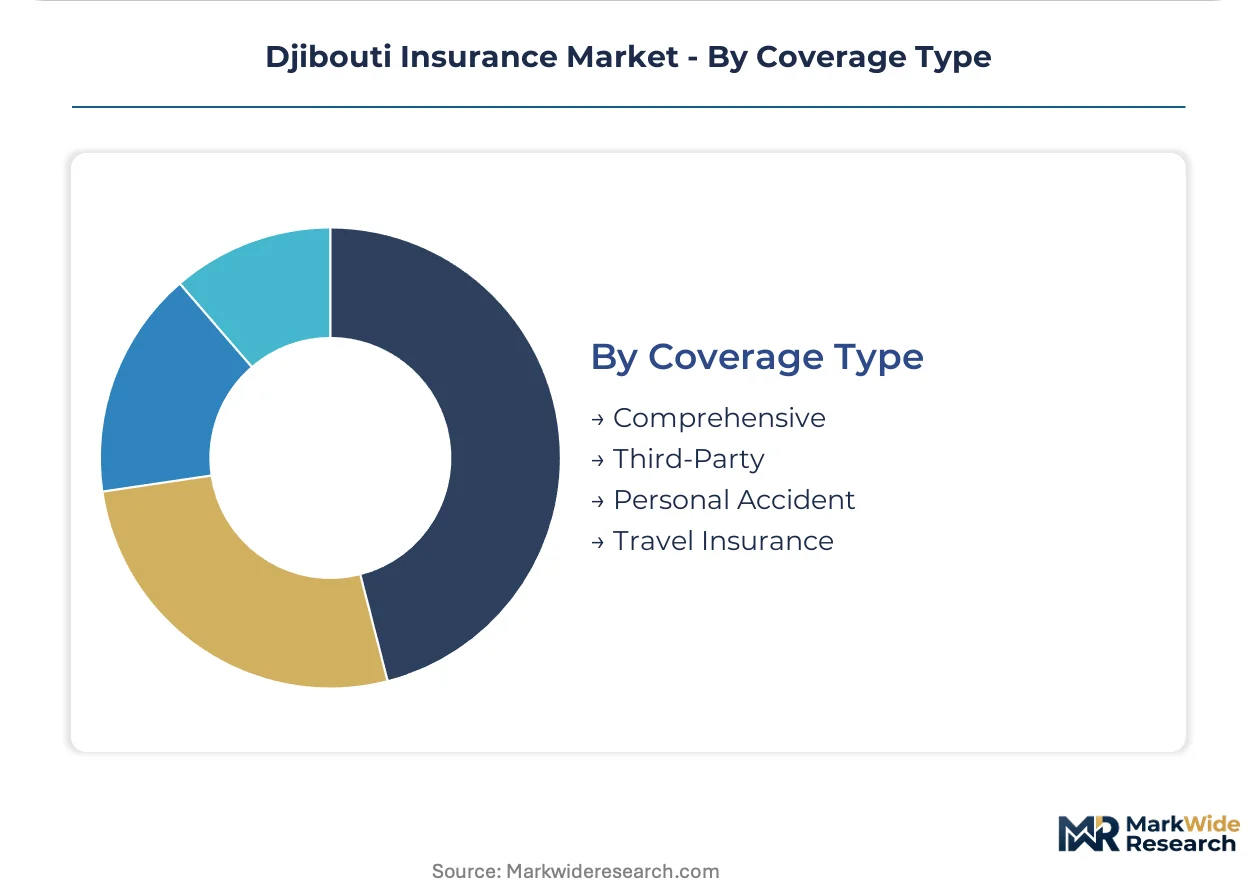
Coverage Type:
Regulatory mandates and buyer risk appetite segment protection levels, from minimum legal compliance to comprehensive asset protection.
- Third-Party:Legally required motor liability coverage enforced by the national insurance regulator, creating universal market participation and cross-subsidization potential.
- Comprehensive:All-risk property and full-coverage motor policies for corporate fleets and high-value port infrastructure assets.
- Personal Accident:Port worker coverage mandated by employer health regulations, with Salama Assurances Djibouti anchoring this line.
- Travel Insurance:Cross-border medical and trip protection for Ethiopia-Djibouti corridor business travelers and regional transit passengers.
Third-Party coverage absorbs the broadest policy count. Comprehensive lines are expanding most quickly among logistics operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is minimal in Djibouti's insurance sector due to the country's national insurance regulator enforcing uniform solvency standards nationwide. Capital requirements and mandatory coverage lines apply identically across all sub-regions, preventing cost-of-compliance migration. Premium concentration instead follows port infrastructure and employer mandate enforcement patterns.
Djibouti City
Corporate risk management spending concentrates in the capital where port operators and logistics firms maintain headquarters. The national insurance regulator maintains its headquarters here, streamlining policy approvals for commercial lines. Doraleh Multi-Purpose Port anchors marine cargo and hull insurance demand, with Ethiopia-Djibouti corridor operators unbundling broker relationships for direct insurer access.
Ali Sabieh
Rural health penetration lags employer-mandated coverage expansion seen in the capital. The national insurance regulator's enforcement of group health requirements weakens outside major employment centers. Micro-health products remain underdeveloped despite cross-border trade activity with Ethiopia creating informal worker populations needing coverage.
Dikhil
Agricultural and pastoral risk pools dominate this interior region with limited commercial insurance uptake. The national insurance regulator's mandatory motor third-party liability creates universal auto participation, though comprehensive coverage penetration trails urban benchmarks. Agent-based distribution persists here where digital platform adoption remains nascent.
Obock
Coastal positioning drives marine cargo exposure for smaller port facilities serving regional fishing and coastal trade. The national insurance regulator scrutinizes reinsurance backing for infrastructure risks in this zone. Limited actuarial talent availability forces reliance on foreign technical services for complex marine line pricing.
Tadjourah
Industrial zone development around the Port of Tadjourah is concentrating construction and logistics liability risks. The national insurance regulator enforces extended approval timelines for large infrastructure placements here. Bancassurance partnerships supervised by the central bank offer emerging distribution channels through regional banking networks.
Djibouti Insurance Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with domestic carriers controlling mandatory lines and foreign branches capturing complex commercial risks. The market structures around three tiers: capital-heavy domestic incumbents with coastal proximity advantages, regional reinsurance capacity providers, and foreign branch operations with technical specialization. Strategic consolidation and digital platform investment dominate competitive moves as smaller carriers face solvency pressure.
Within the domestic carrier tier, United Insurance Company Djibouti and Salama Assurances Djibouti exemplify divergent specialization strategies. United Insurance Company Djibouti occupies a position tied to marine cargo proximity, while Salama Assurances Djibouti anchors health and accident lines for port workers. African Reinsurance Corporation (Africa Re) represents the regional reinsurance archetype extending capacity to local underwriters facing large infrastructure exposures.
| Leading Market Players |
|---|
| Salama Assurances Djibouti |
| United Insurance Company Djibouti |
| GARGASSO Assurance Djibouti |
| Djibouti Assurance Vie |
| Caisse Nationale de Sécurité Sociale (CNSS) |
| Djibouti General Insurance Company |
| African Reinsurance Corporation (Africa Re) |
| Nile Insurance Company Djibouti Branch |
| GXA Assurances |
| Others |
Cost & Logistics Intelligence
Port operators and logistics firms headquartered in Djibouti City command the densest premium concentration, anchoring a broker-mediated pricing model where complex commercial placements sustain fee-based compensation layers. This buyer archetype's unbundling of risk procurement from bundled broker relationships is compressing traditional markup structures while rewarding transparent, direct insurer access.
Pricing Analysis
Broker commission layers dominate channel economics in Djibouti's insurance landscape, with intermediaries commanding substantial fees for risk engineering and claims advocacy on marine cargo and logistics liability placements. Price differentiation rests on reinsurance backing quality and the national insurance regulator's solvency margin scrutiny, with well-capitalized domestic carriers extracting premium spreads over constrained smaller players. Cost compression in SME digital distribution is intensifying because online platforms bypass traditional acquisition costs, though comprehensive coverage for port infrastructure assets retains pricing power. Individual motor third-party liability purchasers exhibit highest price sensitivity, while corporate risk managers at Ethiopia-Djibouti corridor operators prioritize technical service quality over premium minimization.
Supply Chain Analysis
Freight cost dynamics for reinsurance capacity shape Djibouti's insurance supply chain, with treaty placements routed through regional hubs in Nairobi, Johannesburg, and Casablanca before reaching African Reinsurance Corporation's technical resources. Geographic supply concentration centers on Kenya for East African reinsurance brokerage services, South Africa for actuarial technical services, and France for marine cargo surveyor networks. Raw material dependencies include foreign actuarial talent, specialized marine adjusters, and digital platform infrastructure. Single-source vulnerability runs through African Re's regional capacity concentration for large infrastructure exposures. Distribution runs through broker-controlled commercial placements for complex risks, with digital platforms emerging for standardized individual lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Djibouti's insurance market offers margin expansion through digital platform cost compression and premium-tier capture in underserved rural health segments. Broker fee disintermediation and bancassurance scale economics provide the primary cost-down drivers.
For Market Incumbents: Lock in coastal proximity advantages at Doraleh and Tadjourah through exclusive marine cargo underwriting relationships before foreign branch competitors deepen technical service localization. Consolidate smaller domestic carriers facing solvency pressure to capture their regulatory licenses and port-adjacent client relationships. Threat substitution from Nile Insurance Company Djibouti Branch and GXA Assurances demands preemptive capacity positioning. Channel control through bancassurance partnerships supervised by the central bank offers the strongest defensive lever. For New Entrants and Emerging Players: Begin with micro-health product development for Ali Sabieh and Dikhil regions where employer mandate enforcement weakens and private coverage penetration trails urban benchmarks by substantial margins. Rural pastoral and agricultural risk pools remain structurally underpenetrated despite cross-border trade activity creating informal worker populations. Digital-first distribution through mobile platforms bypasses agent-based infrastructure gaps in these interior districts. Go-to-market execution should anchor in CNSS supplementary coverage gaps for salaried employees outside formal port employment. For Investors and Strategic Acquirers: Regional reinsurance groups seeking East African footprint expansion are the most active acquirer in this space, with African Reinsurance Corporation's capacity extension model providing the template for strategic entry. Long-term viability hinges on port infrastructure expansion completion and Ethiopia-Djibouti trade corridor maturation across the next decade. Acquisition targets should display coastal license access plus digital platform investments that reduce expense ratios below traditional broker-dependent operations. The signal to watch is central bank bancassurance partnership approvals, which accelerate distribution scale faster than organic agency buildout.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | Automated underwriting at United Insurance Company Djibouti compresses acquisition costs for SME motor policies. |
| Bancassurance Partnership Expansion | Central bank supervised lender-insurer agreements unlock Djibouti's banking network for rural health penetration. |
| Marine Cargo Specialization | Doraleh proximity anchors premium pricing power for hull and cargo lines against foreign branch competitors. |
| Reinsurance Capacity Diversification | Reducing African Re concentration mitigates single-source vulnerability for large infrastructure risk placements. |
| Telematics-Enabled Motor Products | GPS-linked premium calculations at port logistics hubs enable precise risk-based pricing for fleet operators. |
Research Approach
Bottom-up port operator and logistics firm modeling reconciled against top-down reinsurance capacity tracking forms the analytical core of this study. Primary interviews with risk managers at Ethiopia-Djibouti corridor operators, marine cargo underwriters, central bank bancassurance supervisors, and CNSS scheme administrators combined with secondary validation from the national insurance regulator's solvency filings, central bank partnership disclosures, and African Reinsurance Corporation treaty capacity reports. Triangulation between policy issuance volume data and premium concentration patterns across Djibouti City, Ali Sabieh, Dikhil, Obock, and Tadjourah sub-regions anchored geographic segmentation.
Input-output matrices mapped policyholder demand by corporate, SME, individual, and government customer types against product line supply capacity in life, health, property, and automobile segments. Modeled dimensions spanned distribution channel economics, coverage type regulatory mandates, and sub-regional enforcement intensity variations. CAGRs were derived from premium growth trajectory analysis reconciled against port traffic expansion and employer mandate implementation timelines. Forecast inputs included Doraleh Multi-Purpose Port container volume projections and Ethiopia-Djibouti trade corridor infrastructure completion schedules across the analysis window.
Several conditions sit outside the modeled scope, including potential nationalization of mandatory lines, currency convertibility restrictions on reinsurance remittances, and regional conflict disruption to Ethiopia-Djibouti corridor trade flows. Forecasts reflect assumptions about regulatory enforcement continuity and central bank bancassurance supervision stability. Stakeholders should weight assumptions against their own operating context and monitor national insurance regulator solvency margin adjustments as inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Family Floater Health Insurance Market
Insurance
Intellectual Property Liability Insurance Market
Insurance
Global SME Insurance Market
Insurance
Commercial Cyber Insurance Market
Insurance
United States Insurance Brokerage Market
Insurance
Aerospace Insurance Market
Insurance
Crop Insurance Market
Insurance
Cyber Insurance Market
Insurance
Canada Home Insurance Market
Insurance
Disability Insurance Market
Insurance
North America Car Insurance Aggregators Market
Insurance
Global Sports Insurance Market
Insurance
Canada Parametric Insurance Market
Insurance
China Online Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Europe Parametric Insurance Market