
 Global Mobile Payment Technology Market | 2026-2036
Global Mobile Payment Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Payment Technology Market Intelligence
The talent pool for secure coding and financial data science is rotating towards non-bank technology firms, unlocking new service models. Apple Inc. leverages its hardware ecosystem to create a seamless payment experience. PayPal Holdings Inc. specializes in cross-border peer-to-peer transfers and merchant services. Alibaba Group Holdings Limited dominates the Chinese market with its integrated e-commerce and payment platform.
Mobile payment technology facilitates financial transactions using portable electronic devices like smartphones. These systems often employ Near Field Communication (NFC) or tokenization to securely transmit payment credentials from a digital wallet to a point-of-sale terminal. QR Code-based systems lead in volume in developing economies due to lower infrastructure costs. Within applications, retail transactions and bill payments constitute the largest segments by value.
Regulatory frameworks like Europe's GDPR and China's Personal Information Protection Law (PIPL) impose strict data privacy requirements on payment processors. In the United States, the FTC oversees consumer protection, influencing disclosure and dispute resolution standards. The next strategic decision point for providers involves adapting platforms for the emergence of central bank digital currencies.
Market Dynamics
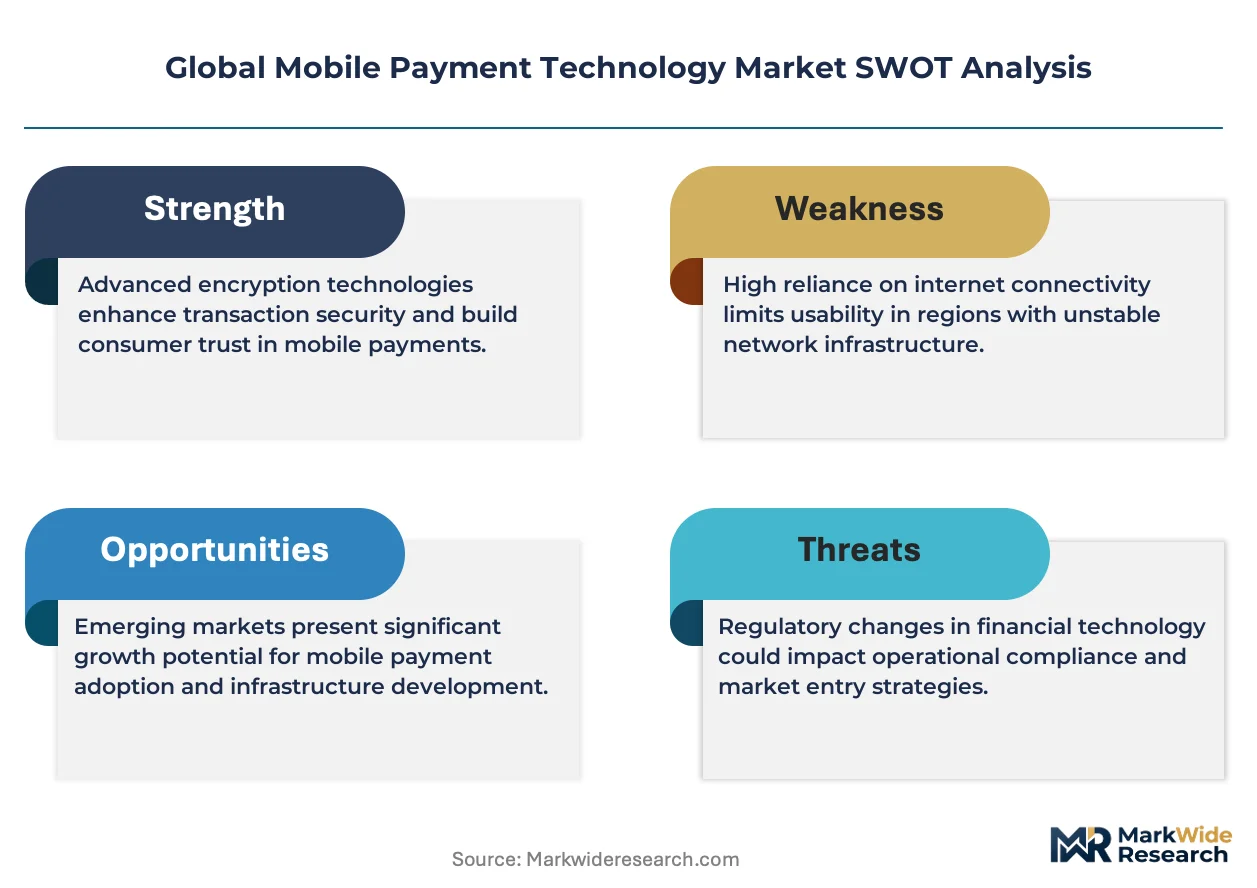
The evolution of mobile payment platforms is shaped by divergent national data privacy regulations. Compliance with frameworks like Europe's GDPR and China's PIPL dictates system architecture and cross-border data flow capabilities for payment processors, influencing market access and feature availability.
Growth Catalysts
- Tokenization Standards:Advanced tokenization substitutes sensitive card data with unique identifiers, boosting user confidence and reducing fraud in retail transactions.
- Government Digitalization Mandates:Initiatives in India promoting unified payment interfaces create a low-cost infrastructure, accelerating adoption among consumers and small businesses.
- QR Code Proliferation:The low infrastructure cost of QR code systems drives high-volume adoption in developing economies, expanding the market for small merchant payments.
Market Restraints
- Interoperability Failures:A lack of universal standards between competing digital wallets and point-of-sale systems creates friction, slowing cross-platform adoption by merchants.
- Data Localization Rules:Regulations like China's PIPL require local data storage, increasing operational complexity and costs for international payment providers.
- Legacy System Dependence:The financial sector's reliance on older banking mainframes complicates the integration of modern, API-driven mobile payment platforms.
Strategic Opportunities
- Southeast Asian Expansion:Markets like Indonesia and Vietnam present growth opportunities, driven by rising smartphone use and an underbanked population adopting digital finance.
- CBDC Integration:Developing platform capabilities to process central bank digital currencies creates a new service frontier for payment providers.
- B2B Payment Automation:Applying mobile payment technology to business-to-business transactions, such as supplier payments, opens a large, underserved market segment.
Industry Challenges
- Cybersecurity Talent Scarcity:A shortage of skilled professionals in secure coding and financial data science creates intense competition for talent, driving up operational costs for providers.
- Navigating Regulatory Fragmentation:Managing compliance across divergent frameworks, such as Europe's GDPR and US FTC rules, demands significant legal and technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Payment Technology Market |
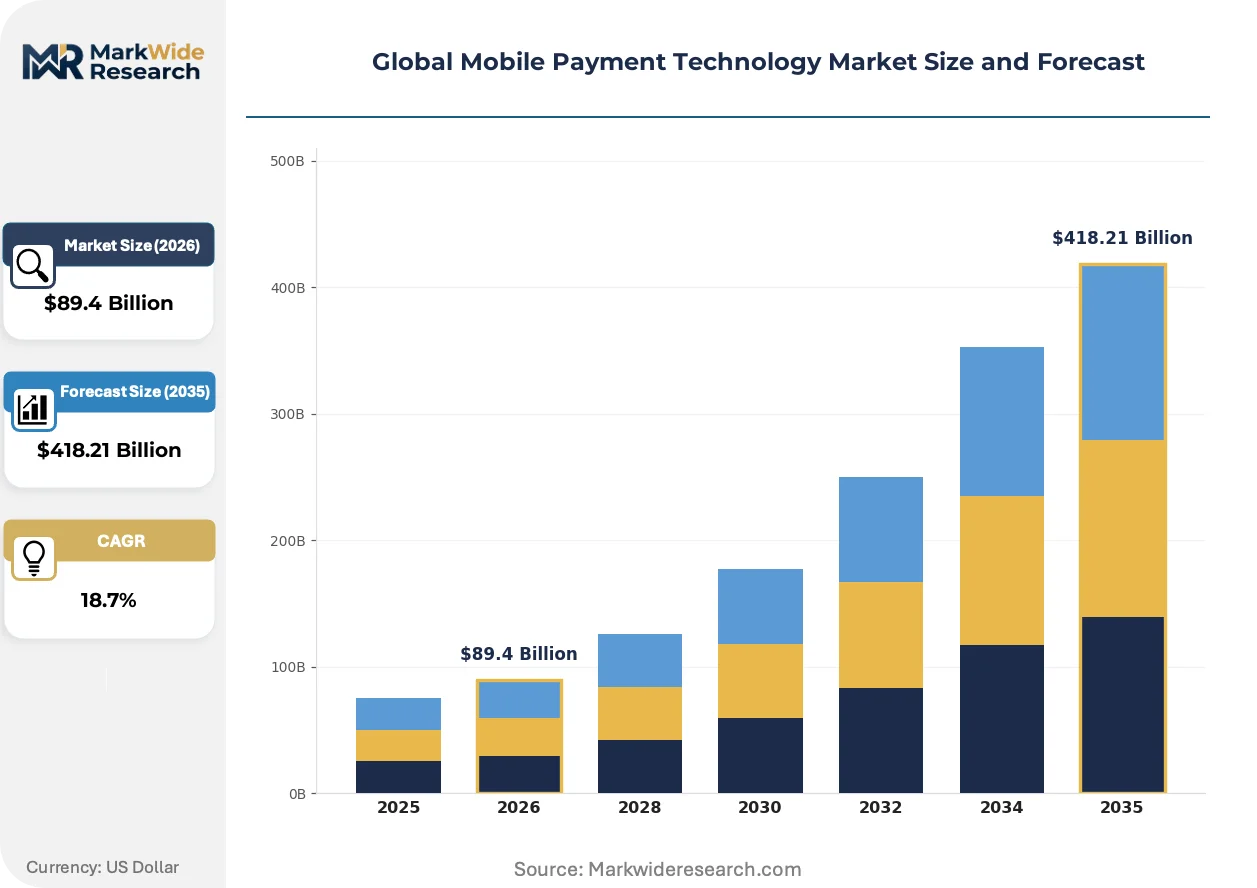
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $418.21 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Near Field Communication, QR Code, Bluetooth, USSD, Tokenization Application: Peer-to-Peer Transfers, Retail Transactions, Bill Payments, Ticket Booking, Loyalty Programs End User: Consumers, Merchants, Financial Institutions, Government Agencies, Telecommunication Providers Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Hosted Services |
| Companies Covered | Apple Inc., Google (Alphabet Inc.), PayPal Holdings Inc., Alibaba Group Holdings Limited, Samsung Electronics Co. Ltd., Visa Inc., Tencent Holdings Limited (WeChat), Amazon.com Inc., Mastercard Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Payment Technology Market Strategic Shifts & Innovations
The market's innovation trajectory is defined by the embedding of payment functions into non-financial applications and hardware ecosystems. This shift prioritizes seamless user experiences over standalone payment apps, altering competitive dynamics between platform providers.
Biometric authentication, utilizing fingerprint or facial recognition, provides a secure method for authorizing mobile payments. Smartphone manufacturers and leading digital wallet providers are rapidly integrating this technology as a default security layer. This embedded verification is displacing traditional PINs and passwords, which reduces transaction friction and combats account takeover fraud.
Europe's updated Payment Services Directive (PSD2) is fundamentally altering the security architecture of online payments. The directive mandates Strong Customer Authentication (SCA) for most electronic transactions, requiring at least two forms of verification. Payment processors and merchants operating in the EU are now forced to redesign their checkout flows to incorporate these multi-factor authentication steps, impacting conversion rates.
Consumer preference is shifting towards integrated "super-apps" that combine payments with other services like messaging, e-commerce, and transportation. This trend challenges the position of single-function digital wallets, as users consolidate activities within a single ecosystem. The model is most advanced in Asia, particularly in China, but is gaining traction in other regions.
Global Mobile Payment Technology Market Segmentation
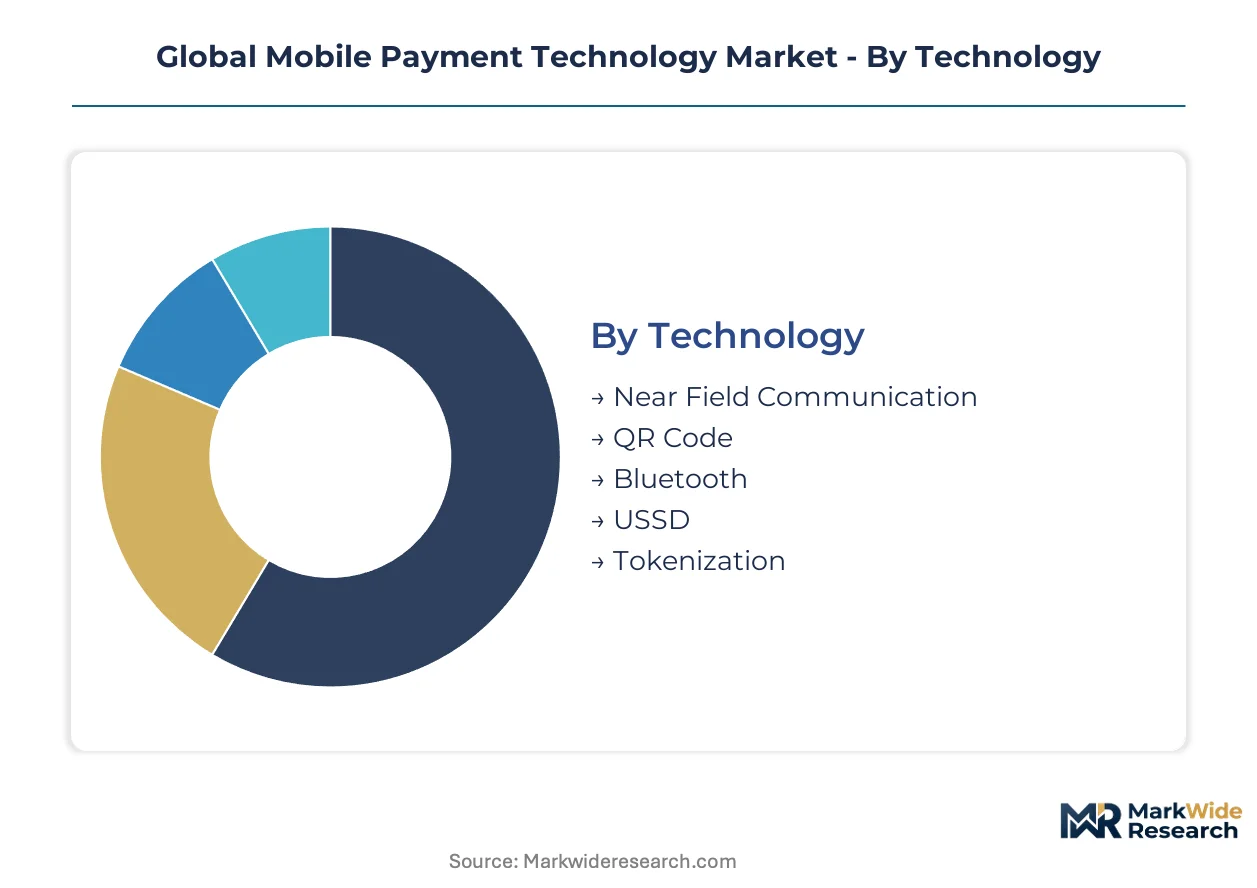
Mobile payment technology segmentation highlights critical areas for strategic investment and market differentiation. Understanding these distinct segments allows providers to tailor offerings, address specific user needs, and navigate competitive pressures. This granular view reveals where innovation is most impactful and where adoption barriers persist.
Technology:
The mobile payment technology landscape faces significant substitution pressure, particularly as newer, more versatile protocols challenge established methods for secure transaction processing.
- QR Code:This technology utilizes scannable two-dimensional barcodes to initiate and complete payment transactions directly from a mobile device. Demand concentrates in India and other developing economies, driven by government digitalization mandates and low infrastructure costs for small merchants.
- Tokenization:Tokenization replaces sensitive payment card data with a unique, encrypted identifier (a token) during a transaction, enhancing security by preventing the exposure of actual card numbers. User confidence in retail transactions increases with this method, reducing fraud risk across global payment networks.
- Near Field Communication:NFC enables short-range wireless communication between devices, facilitating tap-and-pay transactions at compatible point-of-sale terminals.
- Bluetooth:Bluetooth-based payment systems connect mobile devices to payment terminals over short distances, often used in conjunction with specific payment apps.
- USSD:Unstructured Supplementary Service Data provides a text-based communication protocol for mobile payments, particularly prevalent in regions with limited internet access.
QR Code retains volume leadership; Tokenization holds the steepest expansion curve.
Application:
Transaction volume significantly differentiates mobile payment applications, with certain use cases driving the majority of daily interactions across global markets.
- Retail Transactions:These applications enable consumers to make purchases at physical or online stores using their mobile devices, representing the largest segment by value. Strong consumer adoption in diverse retail environments, from supermarkets to e-commerce platforms, drives this segment globally.
- Peer-to-Peer Transfers:P2P applications facilitate direct money transfers between individuals, often across different banking institutions or international borders. PayPal Holdings Inc. specializes in these services, catering to personal remittances and informal commerce globally.
- Bill Payments:This segment allows users to pay utility bills, phone bills, and other recurring expenses directly through mobile payment platforms.
- Ticket Booking:Mobile payment technology integrates into applications for purchasing tickets for transportation, events, and entertainment.
- Loyalty Programs:Mobile payment systems often incorporate loyalty features, allowing users to earn and redeem rewards during transactions.
Retail Transactions command the highest transaction value, while Peer-to-Peer Transfers exhibit substantial growth in user engagement.
End User:
Diverse end-user requirements shape the development and deployment of mobile payment solutions, necessitating tailored features and security protocols for each group.
- Consumers:Individual users who utilize mobile devices to initiate and complete payments for goods, services, and transfers. Widespread smartphone penetration and government digitalization initiatives in countries like India significantly drive consumer adoption of mobile payment solutions.
- Merchants:Businesses of all sizes that accept mobile payments from customers at point-of-sale terminals, online, or via QR codes. The low infrastructure cost of QR code systems particularly benefits small businesses in developing economies, expanding their payment acceptance capabilities.
- Financial Institutions:Banks and credit unions leverage mobile payment technology to offer digital banking services and integrate with payment networks.
- Government Agencies:Public sector entities adopt mobile payment solutions for collecting taxes, fees, and distributing social benefits efficiently.
- Telecommunication Providers:Telecom companies integrate mobile payment services, often through USSD or mobile wallet applications, especially in emerging markets.
Consumer adoption drives the market's primary expansion, while merchants experience direct operational benefits from mobile payment integration.
Deployment:
The underlying infrastructure for mobile payment systems varies significantly by deployment model, influencing operational costs and scalability for providers.
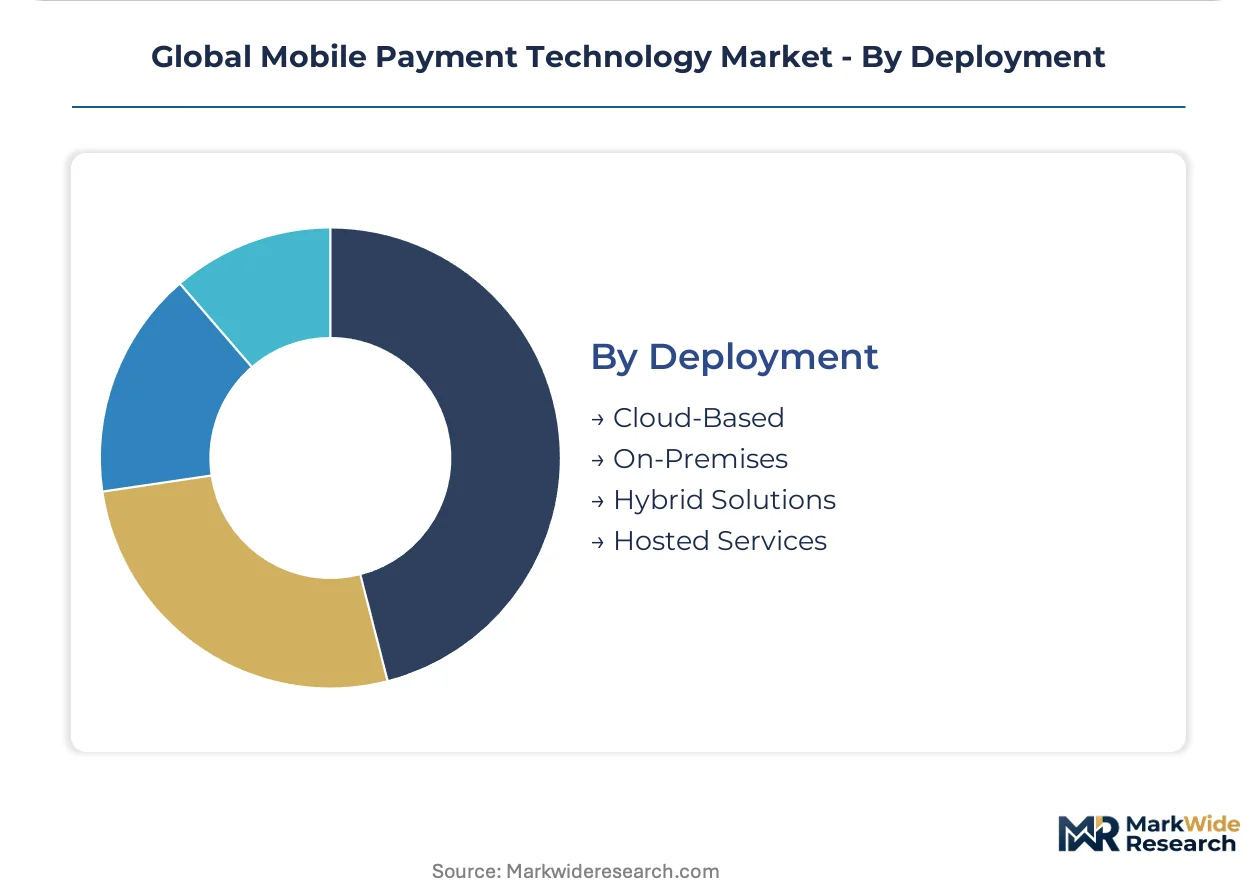
- Cloud-Based:These solutions host payment infrastructure and data on remote servers managed by third-party providers, offering scalability and reduced upfront hardware costs. Providers benefit from flexible resource allocation and continuous updates, making it suitable for rapidly expanding service models.
- On-Premises:Payment systems deployed and managed directly on the end-user organization's own servers and infrastructure, providing maximum data control and customization. This approach is common among large financial institutions with legacy systems and strict security compliance requirements.
- Hybrid Solutions:Hybrid models combine elements of both cloud-based and on-premises deployments, balancing data control with scalability and flexibility.
- Hosted Services:Third-party vendors manage and operate the payment gateway and processing infrastructure for businesses, reducing their technical overhead.
Cloud-Based solutions offer significant operational flexibility, whereas On-Premises deployments prioritize stringent data control for specific entities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile payment technology adoption varies significantly across global markets, driven by differing consumer behaviors and digital infrastructure. While developing economies often prioritize QR code-based systems for low-cost transactions, mature markets integrate tokenization and NFC for enhanced security and convenience. This divergence shapes regional investment priorities and service model development.
India
India leads in mobile payment volume due to robust government digitalization mandates. Initiatives promoting unified payment interfaces, like UPI, create a low-cost infrastructure for transactions. Widespread smartphone penetration across urban and rural areas drives consumer and small business adoption in cities like Bengaluru and Mumbai.
China
The Chinese market demonstrates high mobile payment penetration, primarily through integrated "super-apps". China's Personal Information Protection Law (PIPL) imposes strict data localization rules on payment processors. Major technology hubs such as Shanghai and Shenzhen are centers for innovation in biometric authentication and QR code systems.
United States
Consumer demand for seamless payment experiences drives innovation in the United States, particularly within hardware ecosystems. The Federal Trade Commission (FTC) oversees consumer protection, influencing disclosure and dispute resolution standards for mobile payment providers. Silicon Valley companies and financial centers like New York develop advanced tokenization and NFC solutions.
Germany
European data privacy regulations significantly influence mobile payment development in Germany and the broader EU. Europe's GDPR and the Payment Services Directive (PSD2) mandate Strong Customer Authentication, reshaping transaction security. Financial technology firms in Berlin and Frankfurt are adapting platforms for central bank digital currencies.
Indonesia
Rising smartphone usage and a large underbanked population propel mobile payment growth in Indonesia. Government efforts to promote financial inclusion support the expansion of digital finance services. Jakarta and other major urban centers are seeing increased adoption of QR code and mobile wallet solutions.
Global Mobile Payment Technology Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the mobile payment technology market, creating a tiered competitive landscape. This structure reflects a market where platform providers with established hardware or e-commerce ecosystems compete with agile fintech companies focusing on niche services like cross-border transfers. Strategic partnerships and technology licensing are common competitive moves, alongside continuous portfolio diversification to capture new user segments and geographic expansion into underserved markets.
Within the integrated ecosystem archetype, Apple Inc. exemplifies a hardware-centric approach to mobile payments, leveraging its device base for seamless user experiences. PayPal Holdings Inc. occupies a prominent position in the peer-to-peer transfer and merchant services segment, anchoring cross-border transactions globally. Alibaba Group Holdings Limited, a Chinese Co., Ltd., represents the super-app model, integrating payments with extensive e-commerce platforms and dominating its domestic market through its comprehensive offerings.
| Leading Market Players |
|---|
| Apple Inc. |
| Google (Alphabet Inc.) |
| PayPal Holdings Inc. |
| Alibaba Group Holdings Limited |
| Samsung Electronics Co. Ltd. |
| Visa Inc. |
| Tencent Holdings Limited (WeChat) |
| Amazon.com Inc. |
| Mastercard Incorporated |
| Others |
Cost & Logistics Intelligence
Transaction volume economies of scale significantly influence mobile payment technology. This high-volume processing capability drives supply concentration among major platform providers and establishes competitive price floors for basic services.
Pricing Analysis
Transactional fee structures dominate mobile payment pricing, often supplemented by subscription models for advanced merchant services and value-added analytics. Price differentiation stems from enhanced security features like advanced tokenization and the depth of integration required for complex enterprise systems. Pricing softness reflects intense competition from integrated super-apps and government-backed low-cost interfaces. Small merchants and individual consumers exhibit the highest price sensitivity for basic payment functionalities, while large enterprises value robust compliance and fraud prevention.
Supply Chain Analysis
China and the United States anchor the core software development and specialized hardware components for mobile payment systems. Key dependencies include secure element chips, often sourced from South Korea, and advanced network infrastructure. Data localization rules, such as China's PIPL, represent a structural risk by fragmenting cross-border data flows and increasing operational complexity. Distribution runs through app stores, direct integrations with financial institutions, and partnerships with point-of-sale hardware manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global mobile payment technology market represents a high-growth disruption, fundamentally reshaped by the emergence of central bank digital currencies. This shift necessitates agile strategies across all stakeholder groups.
For Market Incumbents: Shield core transaction processing volumes by investing in advanced tokenization and biometric authentication to maintain user trust. Consolidate market share through strategic partnerships with emerging fintech firms to counter the threat from super-apps. Controlling critical infrastructure, such as payment gateways, acts as a lever against new platform entrants.
For New Entrants and Emerging Players: Regulatory sandbox certification fast-tracks offer a pathway for innovative solutions focusing on underserved segments. Target the B2B payment automation market, which remains largely underpenetrated by mobile solutions. A go-to-market angle emphasizing seamless API integration with existing enterprise resource planning systems provides a strong entry point.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform providers with strong network effects and robust compliance frameworks for long-term viability. Identify acquisition targets specializing in secure cross-border payment rails or central bank digital currency integration capabilities. The signal to watch is the acceleration of government mandates for digital payment infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with CBDCs | Adapting payment systems for central bank digital currencies unlocks new service frontiers for financial institutions. |
| Advanced Tokenization Deployment | Enhancing security protocols with tokenization builds user confidence in retail transactions and reduces fraud risks. |
| Expansion into Southeast Asia | Targeting underbanked populations in markets like Indonesia drives significant growth in mobile payment adoption. |
| B2B Payment Automation Development | Applying mobile payment solutions to business-to-business transactions addresses a large, underserved market segment. |
| Biometric Authentication Integration | Incorporating fingerprint or facial recognition streamlines user experience and strengthens security against account takeovers. |
Research Approach
Operator-level perspectives from payment platform executives, financial institution CTOs, merchant association leaders, and regulatory compliance officers anchored the qualitative base. Primary interviews were combined with secondary validation from SEC filings, central bank reports, industry association publications, and technology patent databases. This approach facilitated bottom-up market sizing and top-down cross-referencing for robust data triangulation.
Sensitivity analysis explored various adoption scenarios across the analysis window, considering factors like smartphone penetration and regulatory shifts. The analytical framework modeled segmentation dimensions including technology type, application, end-user, and deployment model, alongside regional economic growth patterns. Compound annual growth rates were derived from historical trends, projected technology uptake, and anticipated market dynamics. Key forecast inputs included digital payment transaction volumes and mobile device shipment data.
Underlying assumptions cover stable geopolitical conditions and consistent technological advancement, with deviation risk concentrated in unforeseen regulatory changes or major cybersecurity breaches. Forecasts reflect these documented assumptions. Recalibration cycles align with material shifts in named drivers like data privacy laws or central bank digital currency rollouts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
South Korea Payments Market
Payments
Israel Credit Cards Market
Payments
Convergent Billing Market
Payments
Belgium Payments Market
Payments
Norway POS Terminals Market
Payments
Clearing Houses and Settlements Market
Payments
United States Mobile Payment Market
Payments
B2C Payment Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
Digital Transaction Management Market
Payments
Contactless Payment Ring Market
Payments
Mobile POS Market
Payments
Biometric Payment Market
Payments
Global Payment Processor Market
Payments
Japan Payment Gateway Market
Payments
Transaction Monitoring Market