
 GCC Mutual Fund Market | 2026-2036
GCC Mutual Fund Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Mutual Fund Market Insights
UAE's Securities and Commodities Authority fund governance rules is shifting the cost-of-entry calculus for asset managers seeking distribution licenses in the Emirates. SNB Capital leverages its balance sheet depth to anchor institutional mandates across Saudi Arabia. Al Rajhi Capital dominates Shariah-compliant fund construction, while Emirates NBD Asset Management competes through its cross-border UAE-India corridor products.
A mutual fund constitutes a pooled investment vehicle that aggregates capital from multiple investors to purchase a diversified portfolio of securities, with net asset value calculated daily based on underlying holdings. The primary commercial purpose centers on delivering professional portfolio management and diversification to investors lacking scale for direct security ownership. Equity strategies lead asset class flows across the GCC, while fixed income vehicles sustain defensive allocations amid rate volatility. Open-end structures anchor retail accessibility, whereas exchange-traded formats are capturing institutional preference for intraday liquidity.
Saudi Arabia's Capital Market Authority, the UAE Securities and Commodities Authority, and Bahrain's Central Bank collectively shape fund registration, distribution licensing, and disclosure standards across the Gulf. These regulators enforce divergent custody and reporting requirements that fragment cross-border product passports. Stakeholders must monitor evolving fund passporting negotiations between Gulf financial centers to preempt distribution architecture decisions.
Market Dynamics
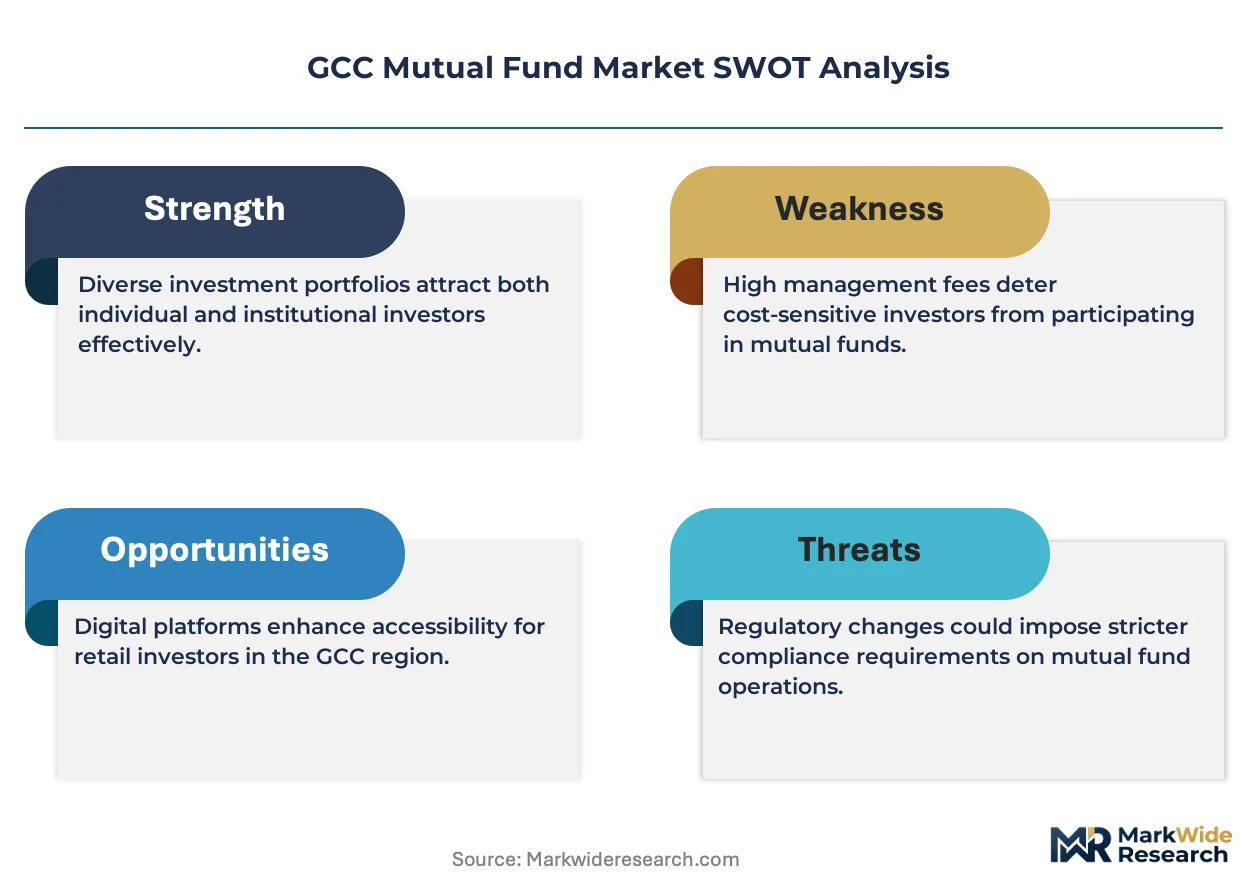
The UAE Securities and Commodities Authority's escalating fund governance standards are compressing the distribution licensing window for new asset managers. This regulatory tightening concentrates competitive advantage among established balance-sheet-backed platforms while raising barriers for boutique entrants seeking retail access across the Emirates.
Growth Catalysts
- Sovereign wealth deployment:Institutional mandates from Gulf pension funds and state investment vehicles are concentrating capital flows into equity-oriented strategies, anchoring fund AUM expansion.
- Shariah-compliant product innovation:Sukuk-structured mutual funds and Islamic equity screens are unlocking retail participation among previously underserved investor segments across Saudi Arabia and the UAE.
- Cross-border fund passporting:Regulatory negotiations between Bahrain's Central Bank and Saudi Arabia's Capital Market Authority are streamlining product distribution across Gulf financial centers.
Market Restraints
- Compliance cost escalation:The UAE Securities and Commodities Authority's enhanced custody and disclosure requirements are inflating operational overhead for new fund registrations.
- Concentrated distribution channels:Saudi National Bank and Emirates NBD control dominant retail banking networks, limiting independent asset manager market access.
- Interest rate sensitivity:Fixed income fund NAV volatility from US Federal Reserve policy transmission is compressing defensive allocation appetite among Gulf institutional allocators.
Strategic Opportunities
- Underpenetrated Kuwait retail segment:Kuwaiti individual investor mutual fund participation lags Saudi and UAE benchmarks, creating white space for digital-first distribution platforms.
- India-Gulf corridor products:Emirates NBD Asset Management's cross-border UAE-India equity strategies demonstrate scalable template for emerging market exposure funds.
- ETF format migration:Exchange-traded fund structures are capturing institutional preference for intraday liquidity, displacing traditional open-end vehicles in sovereign wealth mandates.
Industry Challenges
- Islamic scholar certification scarcity:Qualified Shariah board approval for fund structures faces bottleneck from limited credentialed scholars across the GCC.
- Legacy system integration:Established asset managers' core banking system dependencies complicate real-time NAV calculation and digital subscription platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Mutual Fund Market |
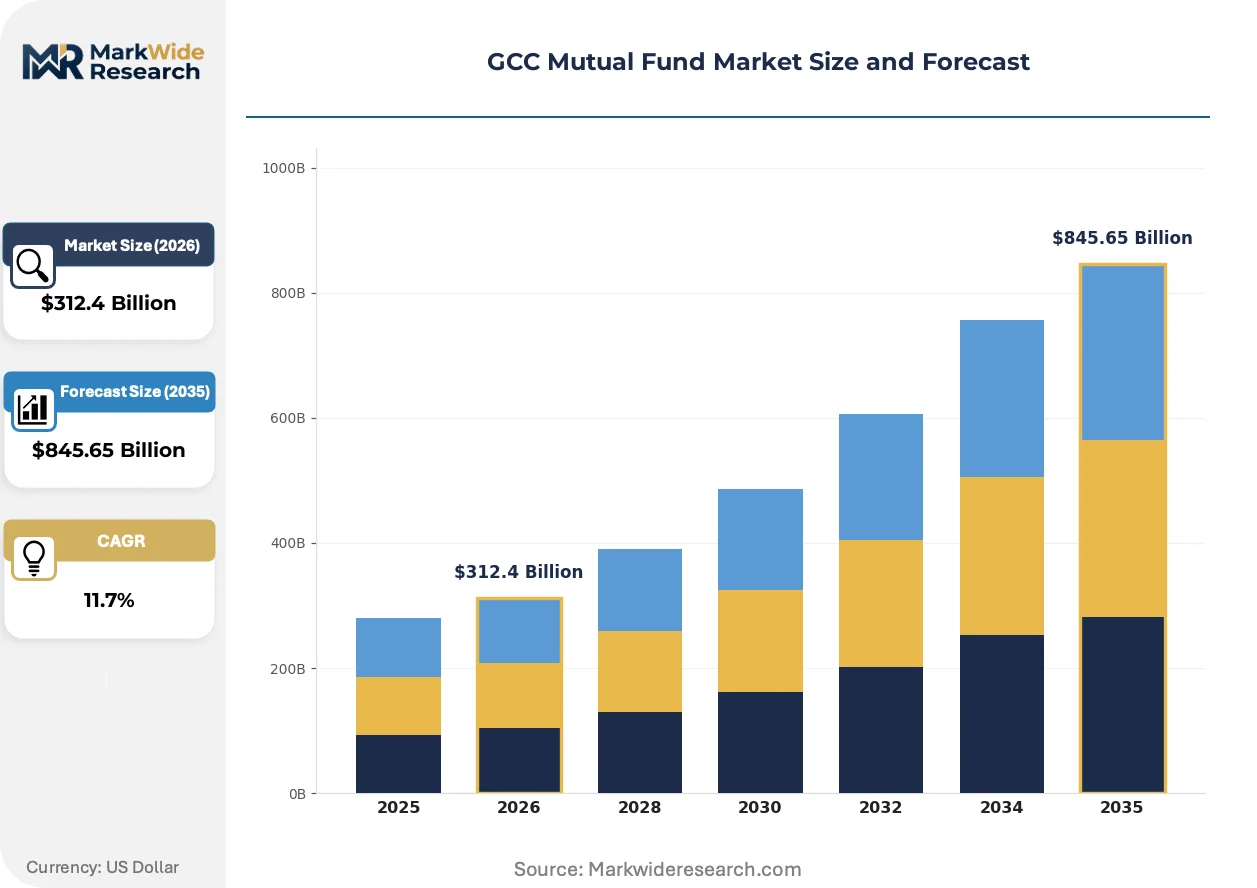
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $845.65 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Growth, Value, Income, Balanced Fund Structure: Open-End, Closed-End, Exchange-Traded, Interval Asset Class: Equities, Fixed Income, Real Estate, Commodities Investor Type: Retail, Institutional, High Net Worth, Family Office |
| Companies Covered | SNB Capital, Al Rajhi Capital, Riyad Capital, Jadwa Investment, Saudi Fransi Capital, Emirates NBD Asset Management, SHUAA Capital, FAB Asset Management, QNB Capital, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Mutual Fund Market Trends and Innovations
Digital distribution infrastructure and regulatory harmonization efforts are compressing the traditional fund manufacturing-to-investor value chain across Gulf financial centers. Asset managers are reconfiguring operational architecture around platform-based access rather than branch-network dependency.
Blockchain-enabled fund administration is consolidating back-office functions across transfer agency, custody reconciliation, and investor registry maintenance. Saudi fintech platforms are piloting distributed ledger structures for real-time NAV verification and automated dividend distribution. This technology compression is reducing operational drag and enabling fractional share ownership for retail participants.
The UAE Securities and Commodities Authority's tightened fund governance framework is mandating enhanced liquidity risk management and stress testing protocols. Asset managers must now maintain higher cash buffers and demonstrate redemption coverage under adverse scenarios. Equity-oriented strategies face the steepest compliance recalibration given their volatility profiles and retail accessibility.
Investor purchasing behavior is rotating toward self-directed digital platforms and away from traditional bank branch intermediation. Younger Gulf retail participants are accessing mutual funds through mobile applications with embedded robo-advisory allocation engines. Saudi Arabia's Capital Market Authority licensing of digital investment advisors is accelerating this channel shift among mass-affluent demographics.
GCC Mutual Fund Market Segmentation
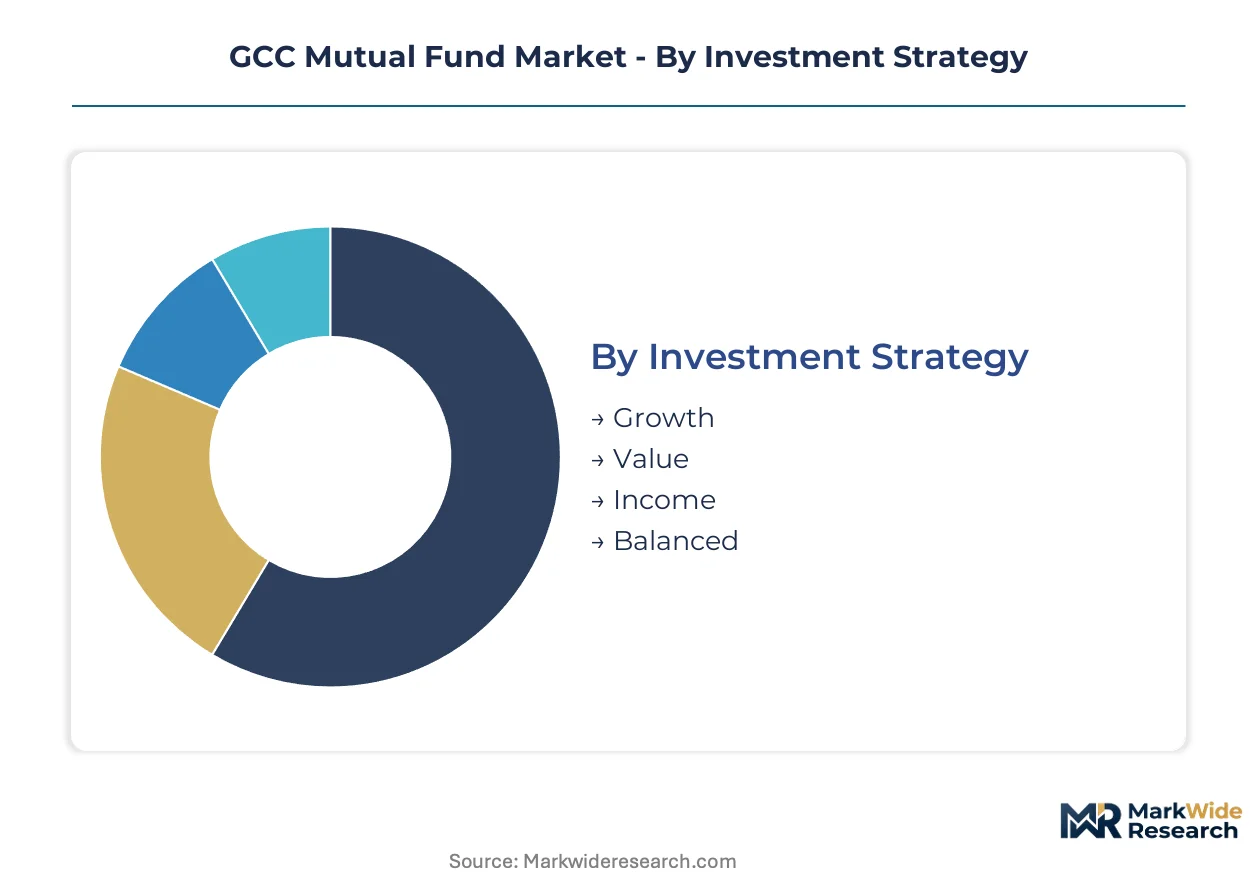
Segmentation in the GCC mutual fund market determines distribution licensing requirements, fee structures, and regulatory treatment across Gulf financial centers. Investment strategy and fund structure choices directly impact custody arrangements and Shariah compliance obligations.
Investment Strategy:
Growth-oriented allocations command premium management fees from Saudi and UAE retail investors seeking equity appreciation.
- Growth:Concentrates capital in high-beta equity positions across Gulf-listed securities. Saudi Arabia's Capital Market Authority licensing requirements for growth-focused retail funds are tightening liquidity buffer mandates.
- Value:Targets discounted equity positions with dividend yield emphasis. UAE pension fund allocators favor value screens for defensive portfolio anchoring amid Fed rate volatility.
- Income:Prioritizes sukuk and dividend-paying equity distributions. Shariah-compliant income vehicles attract Saudi retail participation through Al Rajhi Capital distribution networks.
- Balanced:Maintains fixed equity-bond allocation ratios for risk-averse investors. Bahrain Central Bank registration pathways favor balanced structures for cross-border Gulf passporting.
Growth leads on scale; Income leads on momentum.
Fund Structure:
Structural choice dictates liquidity provision mechanics and secondary market access for Gulf investors.
- Open-End:Issues redeemable shares at daily NAV calculated from underlying holdings. SNB Capital and Emirates NBD anchor retail distribution through banking network subscriptions.
- Closed-End:Fixed share issuance with exchange-traded secondary pricing. Limited penetration in Saudi Arabia due to CMA restrictions on retail closed-end fundraising.
- Exchange-Traded:Intraday tradable units with institutional custody standards. UAE sovereign wealth vehicles are migrating fixed income allocations to ETF formats for liquidity flexibility.
- Interval:Periodic redemption windows with illiquid asset accommodation. Real estate-focused interval structures face UAE Securities and Commodities Authority stress testing requirements.
Open-End dominates AUM concentration; Exchange-Traded climbs the fastest among institutional mandates.
Asset Class:
Asset class selection determines custody complexity and Shariah board certification requirements across Gulf fund registrations.
- Equities:Direct equity ownership with Tadawul or DFM settlement. Saudi retail platforms channel accelerating flows into GCC equity funds.
- Fixed Income:Sukuk and conventional bond portfolios with duration management. Fed policy transmission compresses defensive allocation appetite among Gulf pension funds.
- Real Estate:REIT and direct property exposure with illiquidity premiums. UAE regulatory frameworks mandate enhanced disclosure for real estate fund NAV calculations.
- Commodities:Gold and energy-linked structures with Islamic finance compatibility screens. Limited scholar certification availability constrains product launch velocity.
Equities anchor AUM scale; Real estate gains share fastest among high net worth segments.
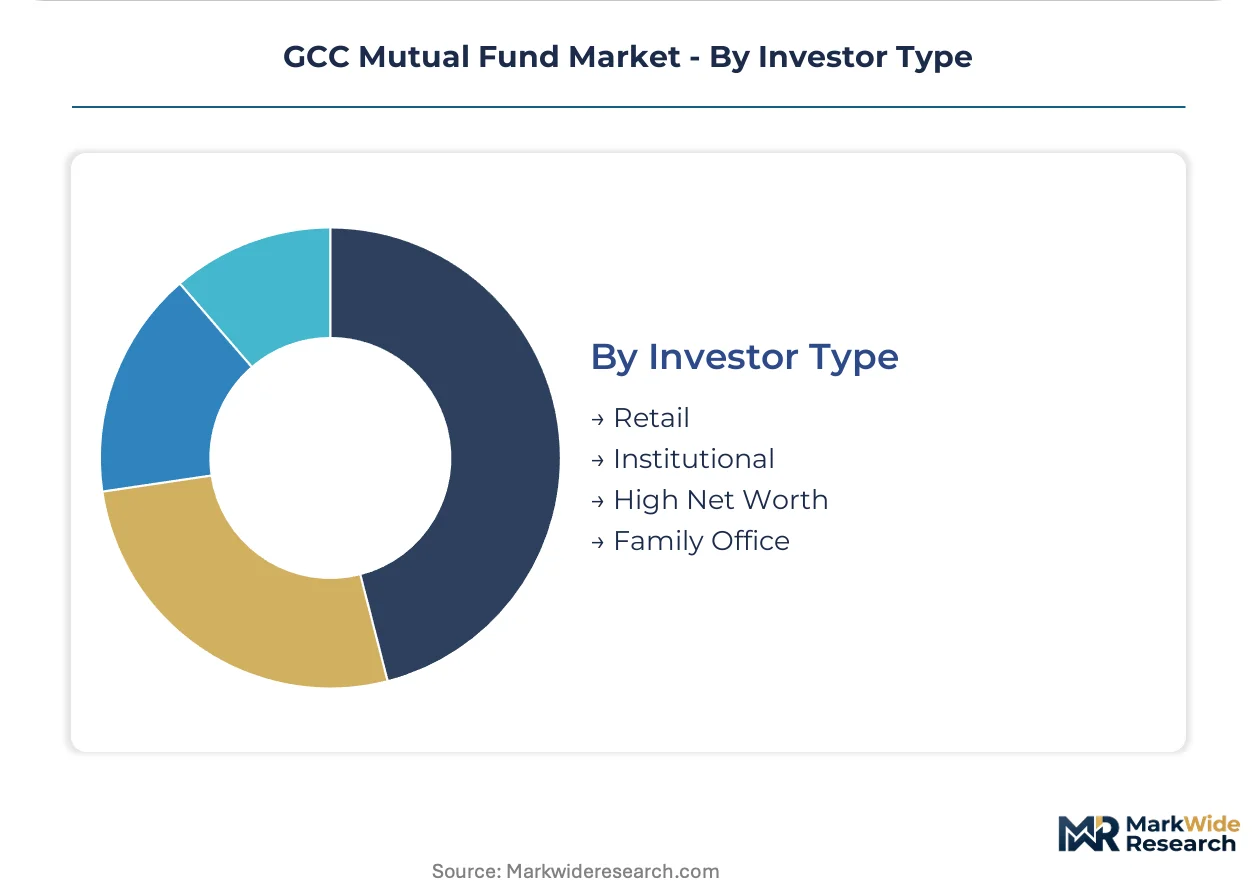
Investor Type:
Investor classification shapes fee schedules, minimum subscription thresholds, and regulatory reporting intensity.
- Retail:Mass-market participants accessing funds through bank branch or digital platforms. Saudi fintech licensing is accelerating mobile-first retail fund adoption.
- Institutional:Pension funds and sovereign wealth vehicles with bespoke mandate terms. ADIA and PIF deployment patterns concentrate demand in large-cap equity strategies.
- High Net Worth:Affluent individuals with customized portfolio construction requirements. Dubai private banking units compete through exclusive fund access and fee negotiation.
- Family Office:Multi-generational wealth structures with direct co-investment rights. Bahrain's regulatory framework accommodates family office fund structuring with reduced disclosure burdens.
Institutional capital leads on absolute deployment; Retail participation expands most quickly through digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asset management talent clusters in Riyadh and Dubai anchor fund distribution architecture across the Gulf. These concentrations concentrate product development expertise and regulatory navigation capacity.
Saudi Arabia
Sovereign wealth deployment from the Public Investment Fund and pension fund capital concentrates demand in large-cap equity strategies. The Capital Market Authority's tightened liquidity buffer mandates for growth-focused retail funds are recalibrating product construction standards. Riyadh's King Abdullah Financial District hosts SNB Capital and Al Rajhi Capital headquarters, where balance-sheet-backed platforms dominate institutional mandate capture.
United Arab Emirates
High net worth individuals and family offices across Dubai and Abu Dhabi drive customized portfolio construction demand. The Securities and Commodities Authority's enhanced custody and disclosure requirements are inflating operational overhead for new fund registrations. Dubai International Financial Centre clusters Emirates NBD Asset Management and SHUAA Capital operations, where cross-border UAE-India corridor products demonstrate scalable emerging market templates.
Kuwait
Retail investor mutual fund participation lags Saudi and UAE benchmarks, creating white space for digital-first distribution platforms. The country's national securities regulator maintains conservative fund passporting protocols that fragment cross-border product access. Kuwait City financial district houses regional asset manager subsidiaries targeting underpenetrated mass-affluent segments through mobile subscription interfaces.
Qatar
Qatar Investment Authority institutional mandates concentrate capital flows into defensive fixed income and real estate strategies. The Qatar Financial Centre Regulatory Authority enforces Shariah compliance certification standards that constrain product launch velocity. Doha's financial district accommodates QNB Capital operations, where sovereign-linked distribution channels anchor captive institutional asset flows.
Bahrain
Family office fund structuring benefits from reduced disclosure burdens under the Central Bank of Bahrain's regulatory framework. Regulatory negotiations between Bahrain's Central Bank and Saudi Arabia's Capital Market Authority are streamlining product distribution across Gulf financial centers. Manama's financial harbor hosts regional asset manager licensing operations targeting cross-border fund passporting efficiencies.
GCC Mutual Fund Market Competitive Landscape
The competitive structure tilts toward balance-sheet-backed banking subsidiaries with captive distribution networks. Saudi National Bank and Emirates NBD control dominant retail banking channels, compressing independent asset manager market access. Three archetypes dominate: bank-owned asset managers leveraging branch infrastructure, specialized Shariah-compliant boutiques, and cross-border specialists targeting India-Gulf corridors. Competitive moves concentrate on digital platform deployment and regulatory license acquisition across multiple Gulf jurisdictions.
Within the bank-owned tier, SNB Capital and Al Rajhi Capital exemplify balance-sheet-anchored platforms that dominate Saudi retail and institutional channels. Emirates NBD Asset Management occupies a position as the cross-border specialist archetype, with product construction targeting UAE-India equity exposure. These three entities represent the concentration of competitive advantage where regulatory tightening favors established players with compliance infrastructure and distribution depth.
| Leading Market Players |
|---|
| SNB Capital |
| Al Rajhi Capital |
| Riyad Capital |
| Jadwa Investment |
| Saudi Fransi Capital |
| Emirates NBD Asset Management |
| SHUAA Capital |
| FAB Asset Management |
| QNB Capital |
| Others |
Pricing and Supply Chain Analysis
Sovereign wealth deployment into equity-oriented strategies across Saudi Arabia and the UAE is compressing fee margins for institutional mandates while elevating performance hurdle rates. Asset managers must absorb rising compliance costs from the UAE Securities and Commodities Authority's enhanced custody requirements without passing full burden to institutional allocators.
Pricing Analysis
The bundled-vs-unbundled service split separates advisory fees from custody and administration charges across Gulf fund registrations. Management fees stratify across institutional, high net worth, and retail tiers, with institutional mandates commanding basis-point compression from scale. Pricing pressure stems from Saudi National Bank and Emirates NBD leveraging captive distribution to negotiate preferential terms. Retail participants demonstrate highest price sensitivity, while family offices accept premium pricing for customized portfolio construction.
Supply Chain Analysis
Fund administration infrastructure draws from India, the Philippines, and Ireland for back-office processing and transfer agency functions. Custody services hinge on local Gulf banks for Tadawul and DFM settlement, while Shariah certification depends on limited scholar pools concentrated in Saudi Arabia and Malaysia. Single-source vulnerability in Islamic scholar approval creates bottlenecks for product launches. Distribution runs through bank-owned platforms and emerging digital fintech channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC mutual fund market functions as a stable compounder anchored by sovereign wealth capital deployment and regulatory-driven consolidation favoring established balance-sheet-backed platforms.
For Market Incumbents: Cement distribution lock-in through exclusive product placement on Saudi National Bank and Emirates NBD digital platforms. Deepen captive supply of Shariah-compliant fund structures by expanding in-house scholar board capacity to preempt certification bottlenecks. Acquire boutique asset managers in Kuwait to capture underpenetrated retail segments before digital entrants establish footholds. For New Entrants and Emerging Players: The Capital Market Authority's digital investment advisor licensing in Saudi Arabia opens a window for mobile-first distribution platforms targeting mass-affluent demographics. Target Kuwait's lagging retail participation through app-based subscription interfaces with embedded robo-advisory engines. Pursue cross-border fund passporting efficiencies via Bahrain Central Bank registration to access Saudi and UAE markets without duplicative compliance infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized Shariah-compliant boutiques possessing credentialed scholar relationships and established track records. The five-to-ten year viability window favors platforms with regulatory licenses across multiple Gulf jurisdictions. Watch for ETF format migration acceleration among sovereign wealth mandates as inflection signal for liquidity-preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | Mobile-first subscription interfaces from Saudi fintech licensees displace branch-network dependency for retail fund access. |
| Cross-Border Fund Passporting | Bahrain Central Bank registrations streamline product distribution across Saudi Arabia and UAE regulatory frameworks. |
| Shariah Board Expansion | In-house scholar capacity at Al Rajhi Capital and SNB Capital accelerates compliant product launch velocity. |
| ETF Format Migration | Exchange-traded structures capture institutional preference from ADIA and PIF for intraday liquidity flexibility. |
| Kuwait Market Entry | Digital-first platforms target underpenetrated retail segments through mobile subscription interfaces in Kuwait City. |
Research Methodology
Bottom-up investor-type modeling reconciled against top-down asset flow tracking forms the analytical core of this study. Primary interviews with fund managers at SNB Capital and Al Rajhi Capital, regulatory affairs officers at the UAE Securities and Commodities Authority, pension fund allocators, and digital platform engineers informed qualitative assessments. Secondary validation drew from Capital Market Authority disclosure filings, Securities and Commodities Authority regulatory circulars, Tadawul fund performance databases, and central bank statistical bulletins. Top-down triangulation against macroeconomic indicators anchored absolute market sizing.
Historical trendline analysis of AUM flows by investment strategy and fund structure established baseline growth patterns across the analysis window. Segmentation modeling incorporated investment strategy, fund structure, asset class, and investor type dimensions with geographic regulatory cluster overlays. CAGRs derived from regression analysis of historical expansion rates adjusted for regulatory inflection points. Forecast inputs included sovereign wealth deployment commitments, digital licensing velocity, and Shariah-compliant product pipeline depth.
Revisions become necessary when regulatory harmonization negotiations stall, sovereign wealth allocation mandates shift away from equity strategies, or scholar certification bottlenecks intensify beyond current capacity constraints. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
US Securities Brokerage Market
Capital Markets and Securities
High-Yield Bonds Market
Capital Markets and Securities
Foreign Exchange Market
Capital Markets and Securities
Asia Pacific ETF Market
Capital Markets and Securities
Gold Derivatives and Futures Market
Capital Markets and Securities
Hong Kong Capital Exchange Ecosystem Market
Capital Markets and Securities
Middle East and Africa ETF Market
Capital Markets and Securities
Global Algorithm Trading Market
Capital Markets and Securities
Special Purpose Vehicle Market
Capital Markets and Securities
China Capital Exchange Ecosystem Market
Capital Markets and Securities
Exchange Traded Fund Market
Capital Markets and Securities
Algorithmic Trading Market
Capital Markets and Securities
North America ETF Market
Capital Markets and Securities
US Capital Exchange Ecosystem Market
Capital Markets and Securities
UK Capital Exchange Ecosystem Market
Capital Markets and Securities
Europe ETF Market