
 US Property and Casualty (P&C) Insurance Market | 2026-2036
US Property and Casualty (P&C) Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
US Property and Casualty (P&C) Insurance Market Insights
Modular policy bundling is rebalancing how commercial buyers structure coverage across property and liability lines. State Farm leverages its captive agency network to sustain regional pricing power in homeowners markets. Progressive competes through direct-channel data analytics that anchors auto insurance acquisition costs below traditional broker models. Berkshire Hathaway differentiates via underwriting discipline and scale concentration in specialty commercial lines.
Property and casualty insurance constitutes a risk-transfer mechanism where insurers pool premiums to indemnify policyholders against specified losses from property damage, liability claims, or business interruption, with pricing calibrated through actuarial loss modeling and reinsurance layering. The primary commercial purpose centers on enabling capital deployment and operational continuity by externalizing unpredictable financial shocks. Auto Insurance dominates premium volume through state-mandated coverage floors and fleet exposure concentration, while Commercial Property Insurance commands elevated margins in catastrophe-prone zones where capacity scarcity tightens pricing. Liability Insurance extends fastest among small business segments facing litigation frequency growth in professional and product risk categories.
State insurance commissioners across all fifty jurisdictions regulate rate filings, reserve adequacy, and market conduct, with NAIC model laws providing coordination infrastructure that shapes product standardization and cross-state licensing efficiency. The National Flood Insurance Program and state wind pools create residual market mechanisms that influence private capital deployment decisions in coastal zones. Stakeholders must monitor how climate stress tests and evolving state-level rate approval timelines reshape capital allocation between growth markets and constrained jurisdictions.
Market Dynamics
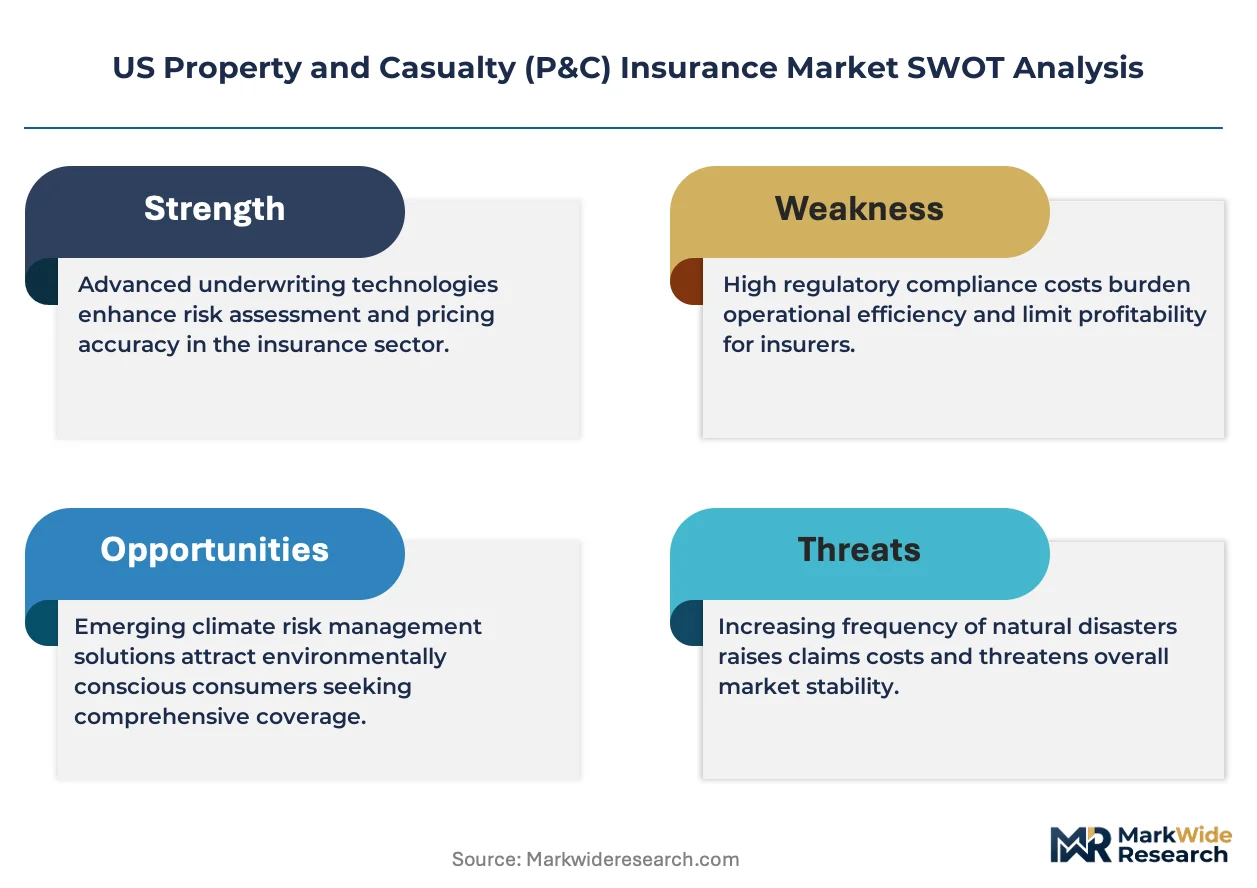
Climate-driven loss severity is compressing underwriting margins across coastal and wildfire-exposed states, forcing carriers to reprice risk at the policy level while state regulators extend rate approval timelines. This tension between actuarial necessity and political affordability defines current market mechanics.
Growth Catalysts
- Inflation Reduction Act tax credits:Commercial property owners accelerate retrofit investments, expanding insured values and driving demand for upgraded coverage endorsements.
- Parametric triggers:Hurricane-exposed enterprises adopt index-based settlement structures that bypass traditional loss adjustment, reducing claim cycle friction.
- Texas Gulf Coast concentration:Petrochemical facility expansions multiply industrial property premiums and specialty liability attachments.
Market Restraints
- Reinsurance capacity scarcity:Florida and California carriers face doubled attachment points and narrowed treaty terms after consecutive catastrophe years.
- Construction cost volatility:Lumber and labor input spikes distort replacement cost estimates, inflating reserve adequacy requirements.
- Judicial rate approval delays:California Department of Insurance review timelines extend 18-24 months, trapping underpriced books.
Strategic Opportunities
- Cyber-physical convergence:IoT-enabled property monitoring merges with traditional coverage, creating preventive risk service bundles.
- Midwestern commercial expansion:Secondary markets in Ohio and Michigan offer rate adequacy with minimal catastrophe exposure.
- Usage-based auto telematics:Real-time driving data enables dynamic pricing that captures previously unprofitable segments.
Industry Challenges
- Actuarial talent scarcity:Climate risk modeling expertise concentrates at specialty consultancies, constraining carrier in-house capabilities.
- Legacy core system integration:Policy administration platforms from the 1990s resist API connectivity with modern data ingestion pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Property and Casualty (P&C) Insurance Market |
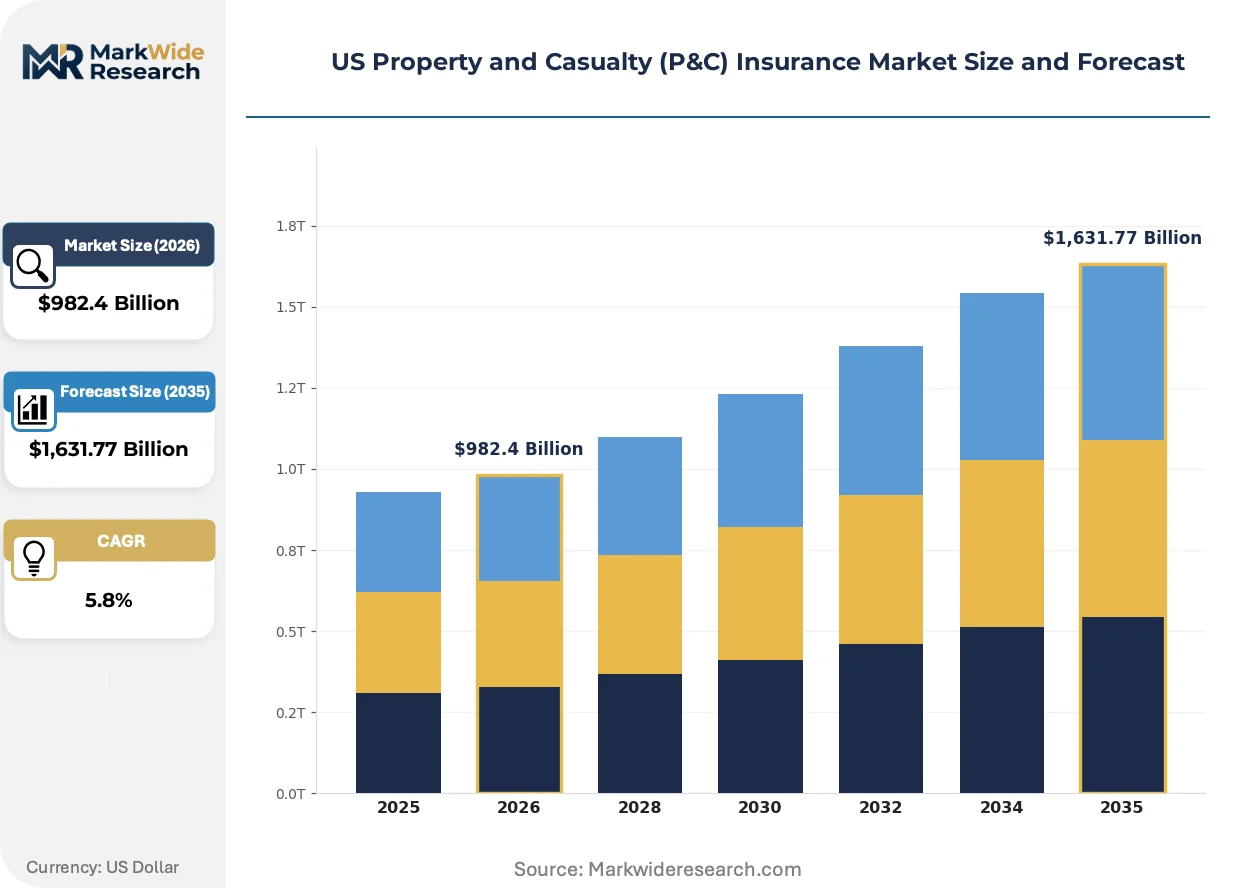
| Market Size in 2026 | $982.4 Billion |
| Market Size in 2035 | $1,631.77 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auto Insurance, Homeowners Insurance, Commercial Property Insurance, Liability Insurance Distribution Channel: Direct Sales, Broker, Online Platforms, Agents End User: Individuals, Small Businesses, Corporations, Government Entities Service Type: Claims Management, Underwriting, Policy Administration, Risk Assessment |
| Companies Covered | State Farm, Progressive, Berkshire Hathaway, Allstate, Liberty Mutual, Travelers Companies, USAA, Chubb, Nationwide, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Property and Casualty (P&C) Insurance Market Trends and Innovations
Digital distribution infrastructure is rewiring how commercial buyers discover, compare, and bind coverage, compressing the traditional agent-mediated purchase cycle. Three interconnected developments are accelerating this structural shift.
Computer vision is absorbing property inspection workflows, enabling carriers to underwrite remote risks without physical site visits. Mid-market commercial property underwriters at regional carriers deploy satellite imagery and drone capture to assess roof condition and wildfire defensible space. This technology is absorbing adjustor field labor costs while expanding addressable markets in rural and catastrophe-restricted zones.
Florida's Senate Bill 2-A restructured attorney fee provisions in property insurance litigation, directly targeting assignment of benefits abuse that inflated loss adjustment expenses. The legislation compresses plaintiff bar incentive structures and redirects dispute resolution toward appraisal clauses. Coastal homeowners carriers respond by re-entering zip codes they had exited, though capacity remains disciplined.
Embedded insurance distribution is displacing standalone policy shopping for small commercial buyers. E-commerce platforms serving contractors and restaurateurs now surface coverage at point-of-transaction, capturing demand before traditional agent engagement. This pattern concentrates in Texas and Georgia metropolitan corridors where digital-native business formation rates exceed national benchmarks.
US Property and Casualty (P&C) Insurance Market Segmentation
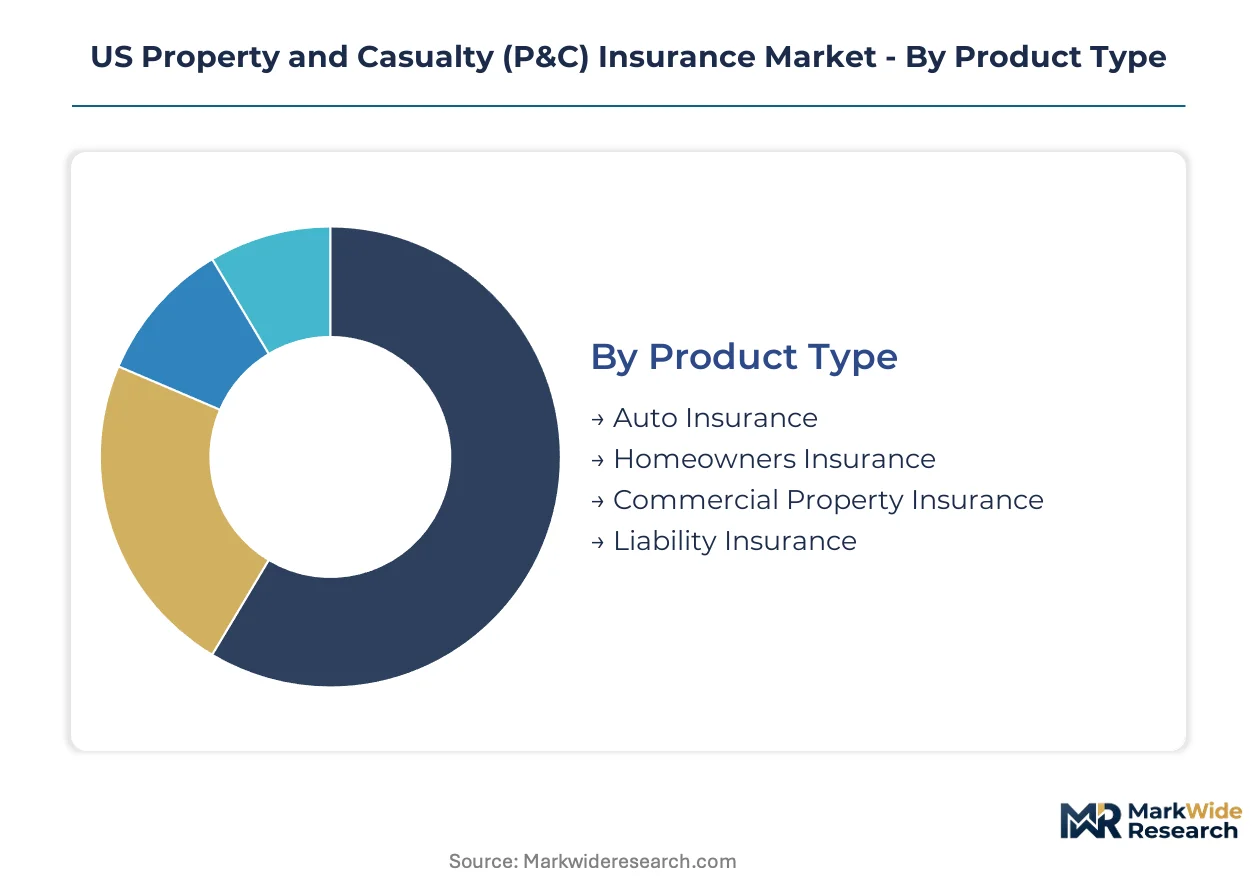
US P&C insurers calibrate product architecture against divergent risk profiles, distribution economics, and regulatory constraints across state lines. Segmentation discipline separates commoditized auto coverage from specialty commercial lines where pricing power persists.
Product Type:
Standardization dominates mass-market personal lines while commercial segments demand bespoke underwriting and layered capacity structures.
- Auto Insurance:State-mandated liability floors create universal addressable demand, with premium volume concentrated in Texas, Florida, and California where fleet density and litigation frequency intersect. Telematics-enabled usage-based pricing is compressing acquisition costs for direct-channel carriers.
- Commercial Property Insurance:Catastrophe-exposed zones command elevated margins through capacity scarcity, with Gulf Coast petrochemical facilities and California wildland-urban interface properties driving specialty treaty demand. Reinsurance attachment points have doubled post-consecutive loss years.
- Homeowners Insurance:Florida and California regulatory delays trap underpriced books as climate severity forces repricing.
- Liability Insurance:Small business professional and product risk categories face litigation frequency growth.
Most installed capacity flows through Auto Insurance. Expansion is steepest in Commercial Property Insurance.
Distribution Channel:
Cost-to-acquire curves separate high-touch intermediated sales from digital-native direct binding, with hybrid models emerging in mid-market commercial.
- Agents:Captive agency networks sustain regional pricing power through localized underwriting authority and relationship-based retention. State Farm deploys this structure to defend homeowners market share in catastrophe-prone counties.
- Online Platforms:Embedded distribution at point-of-transaction captures small commercial demand before traditional broker engagement, concentrating in Texas and Georgia metropolitan corridors where digital-native business formation exceeds national benchmarks.
- Direct Sales:Data analytics anchors auto acquisition costs below traditional broker models.
- Broker:Complex commercial placements rely on wholesale access to specialty capacity.
Agent networks retain the largest premium flow. Online Platforms are gaining share fastest in small commercial segments.
End User:
Risk sophistication and purchasing power determine service intensity, from standardized personal lines to engineered commercial programs.
- Corporations:Risk managers structure multi-line programs with captive alternatives and integrated risk financing, demanding analytics-driven loss prevention services. Fortune 500 placements command dedicated underwriting teams and bespoke claims protocols.
- Small Businesses:Embedded insurance surfaces coverage at point-of-transaction, with contractors and restaurateurs purchasing through e-commerce platforms. Climate risk intensification is expanding coverage purchases beyond statutory minimums.
- Individuals:Price-sensitive auto and homeowners shoppers dominate direct-channel volume.
- Government Entities:Public entity pools and municipal risk retention groups aggregate otherwise uninsurable exposures.
Individual policyholders generate the highest transaction volume. Small Businesses show the steepest coverage expansion trajectory.
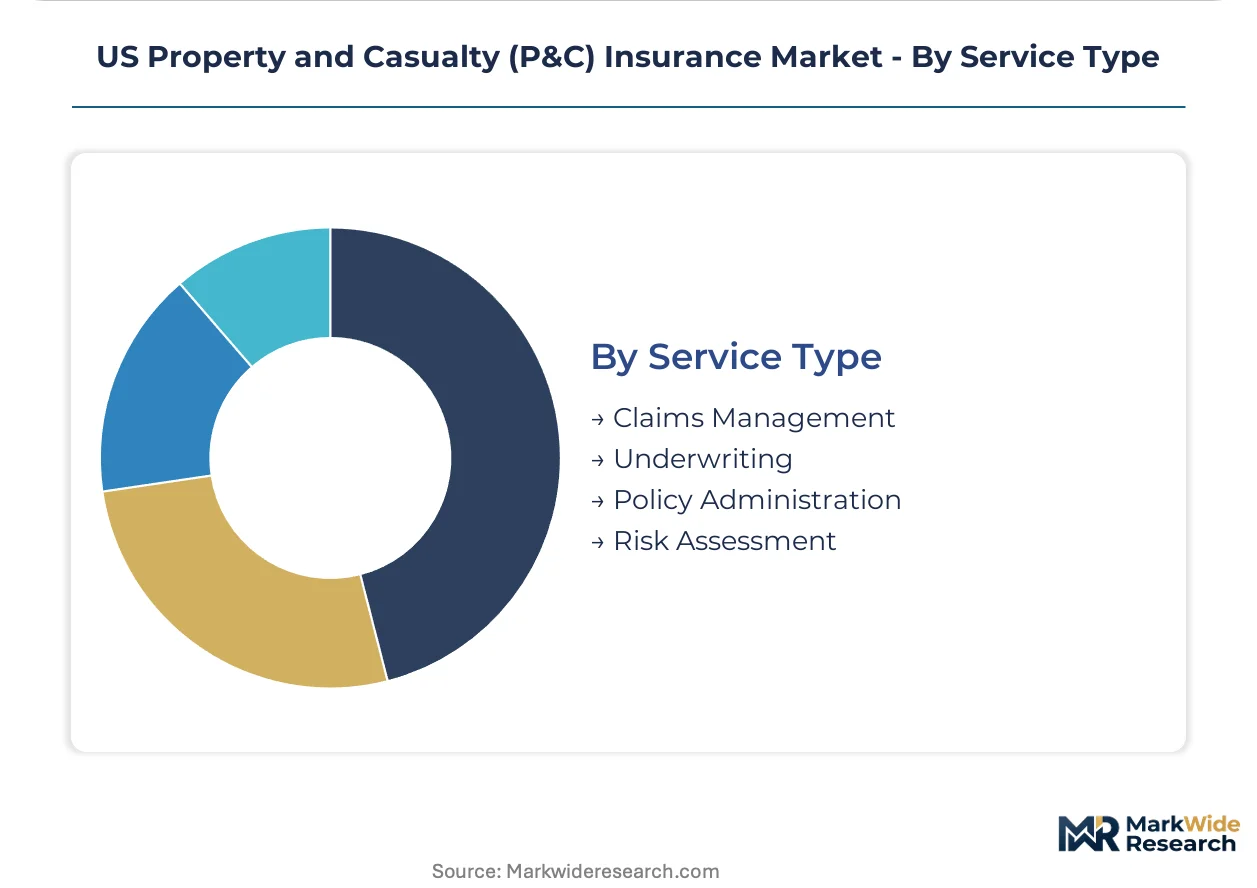
Service Type:
Operational intensity varies from high-frequency transaction processing to specialized technical functions requiring actuarial and engineering expertise.
- Underwriting:Computer vision and satellite imagery now absorb property inspection workflows, enabling remote risk assessment without site visits. Regional carriers deploy this technology to expand in rural and catastrophe-restricted zones.
- Claims Management:Parametric triggers bypass traditional loss adjustment for hurricane-exposed enterprises, compressing settlement cycles from months to days. Florida's Senate Bill 2-A redirects dispute resolution toward appraisal clauses.
- Risk Assessment:Climate stress testing and IoT-enabled property monitoring merge with traditional coverage.
- Policy Administration:Legacy core systems from the 1990s resist API connectivity with modern data pipelines.
Policy Administration handles the largest transaction volume. Underwriting is expanding most quickly through predictive analytics deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US P&C insurance industry traces its modern scale to post-World War II suburban expansion and the 1968 creation of the National Flood Insurance Program. State-level regulatory frameworks and catastrophe exposure patterns now concentrate capital deployment across distinct regional corridors.
Florida
Hurricane frequency and litigation volume drive premium escalation and carrier exits. Florida's Senate Bill 2-A restructured attorney fee provisions to curb assignment of benefits abuse. Miami-Dade and Broward counties see selective market re-entry by coastal homeowners carriers despite doubled reinsurance attachment points.
California
Wildland-urban interface expansion and consecutive drought-intensified fire seasons compress underwriting margins. California Department of Insurance review timelines extend 18-24 months, trapping underpriced books. Los Angeles and San Diego metropolitan areas face capacity withdrawal from admitted carriers into surplus lines.
Texas
Petrochemical facility construction along the Gulf Coast multiplies industrial property premiums and specialty liability demand. Texas wind pool mechanisms supplement private market capacity in coastal counties. Houston and Corpus Christi anchor the nation's largest concentration of energy-sector commercial placements.
New York
Commercial liability frequency and professional services density sustain specialty line pricing power. New York State Department of Financial Services maintains stringent reserve adequacy examinations. Manhattan and Westchester County command dedicated underwriting teams for Fortune 500 risk management programs.
Illinois
Manufacturing and logistics infrastructure generate stable auto and workers compensation premium flows without catastrophe volatility. Illinois Department of Insurance coordinates with NAIC model law harmonization efforts. Chicago metropolitan area serves as Midwest headquarters for multiple national carrier operations.
US Property and Casualty (P&C) Insurance Market Competitive Landscape
Premium-margin players sit above commodity-margin players across distribution channel sophistication and data analytics deployment. The market structures around three tiers: national direct-channel specialists, captive agency network defenders, and diversified multi-line conglomerates. Scale concentration persists in personal auto and homeowners lines while specialty commercial segments fragment across regional underwriters. Dominant competitive moves include portfolio rebalancing between catastrophe-exposed and stable jurisdictions, and technology licensing for telematics-enabled pricing.
Within the captive agency tier, State Farm exemplifies localized underwriting authority and relationship-based retention strategies. Progressive occupies a position at the direct-channel vector, anchoring acquisition cost efficiency through real-time driving data analytics. Berkshire Hathaway represents underwriting discipline and scale concentration in specialty commercial lines, sitting within the diversified conglomerate archetype.
| Leading Market Players |
|---|
| State Farm |
| Progressive |
| Berkshire Hathaway |
| Allstate |
| Liberty Mutual |
| Travelers Companies |
| USAA |
| Chubb |
| Nationwide |
| Others |
Pricing and Supply Chain Analysis
Fortune 500 risk managers anchor pricing power through multi-year program structures that bundle property, liability, and captive alternatives, forcing carriers to compete on service intensity rather than rate alone. This buyer concentration privileges underwriting discipline over volume chasing in commercial lines.
Pricing Analysis
Risk-based pricing stratification across preferred, standard, and non-standard tiers dominates personal auto and homeowners segments, with telematics data enabling dynamic rate adjustments that reflect individual loss propensity. Price differentiation rests on driving behavior scores and property catastrophe exposure scores. Cost compression in Florida and California homeowners lines is intensifying because state regulators delay rate approvals while climate severity escalates. Small commercial buyers show highest price sensitivity; Fortune 500 risk managers show least.
Supply Chain Analysis
Domestic-content requirements in Texas wind pool mechanisms and Florida Citizens Property Insurance are reshaping reinsurance sourcing toward US-domiciled capital. Reinsurance capacity concentrates in Bermuda, London, and Zurich. Treaty structures draw from catastrophe bonds, collateralized reinsurance, and traditional quota share. Single-source vulnerability sits with Bermuda market concentration for peak hurricane capacity. Distribution runs through broker-mediated placements for commercial lines and direct-channel binding for personal auto.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carriers can exploit geographic arbitrage between Texas Gulf Coast rate adequacy and California regulatory compression, capturing margin in jurisdictions where approval timelines align with actuarial necessity.
For Market Incumbents: Anticipate climate-driven reserve adequacy scrutiny from state insurance commissioners by accelerating Midwestern commercial expansion into Ohio and Michigan. Deploy computer vision underwriting to reduce field inspection costs in rural zones. Reinforce captive agency network control where State Farm's localized pricing power persists.
For New Entrants and Emerging Players: Florida Senate Bill 2-A opens a window for litigation-light homeowners carriers to re-enter coastal zip codes with disciplined capacity deployment. Target embedded insurance distribution at Texas and Georgia e-commerce platforms serving contractors. Pursue parametric product structures that bypass traditional loss adjustment friction.
For Investors and Strategic Acquirers: Specialty commercial underwriters are the most active acquirer category in this space, consolidating regional players with catastrophe modeling capabilities. Long-term viability centers on climate risk data infrastructure rather than premium volume scale. Monitor reinsurance attachment point trends as the inflection signal for carrier profitability recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Progressive's real-time driving data anchors acquisition cost efficiency below traditional broker models. |
| Parametric Product Launch | Hurricane-exposed enterprises adopt index-based settlements that compress claim cycles from months to days. |
| Midwestern Geographic Expansion | Secondary markets in Ohio and Michigan offer rate adequacy with minimal catastrophe exposure concentration. |
| Cyber-Physical Convergence Development | IoT-enabled property monitoring merges with traditional coverage to create preventive risk service bundles. |
| Reinsurance Treaty Restructuring | Doubled attachment points post-consecutive loss years force carriers toward collateralized capital structures. |
Research Methodology
Bottom-up policyholder modeling reconciled against top-down premium flow tracking forms the analytical core of this study. Primary interviews with chief underwriting officers, actuarial directors, state insurance regulators, reinsurance brokers, and claims executives combined with secondary validation from NAIC statutory filings, SEC 10-K insurance disclosures, catastrophe bond issuance databases, and state department of insurance rate filing records. Triangulation across these sources ensures coverage of both pricing mechanics and capital deployment patterns.
Historical trendline analysis of premium volume, loss ratio development, and expense ratio trajectories informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, distribution channel, end user sophistication, and state-level regulatory cluster. CAGRs were derived from fitted growth curves calibrated against macroeconomic drivers and industry-specific capacity constraints including reinsurance availability and construction cost inflation indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme hurricane seasons or accelerated climate migration patterns. Forecasts reflect documented assumptions regarding regulatory approval timelines and reinsurance market capacity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Germany Electronic Gadgets Insurance Market
Insurance
Indonesia Private Health Insurance Market
Insurance
Cargo Insurance Market
Insurance
Switzerland Reinsurance Market
Insurance
United States Bancassurance Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
Global Property and Casualty Reinsurance Market
Insurance
Boiler Insurance Market
Insurance
Road Assistance Insurance Market
Insurance
Global Home Insurance Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Cyber Insurance Market
Insurance
Cyber Liability Insurance Market
Insurance
Asia-Pacific Liability Insurance Market
Insurance
UK Travel Insurance Market
Insurance
Europe EV Insurance Market