
 France Car Insurance Market | 2026-2036
France Car Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
France Car Insurance Market Insights
Telematics-driven risk pricing is reconfiguring how insurers capture value from policyholder data streams. Allianz leverages its proprietary connected-car platform to refine individual premium calculations. Axa France Iard anchors its market position through dense agency networks across French metropolitan zones. Covea competes by bundling home and auto coverage into integrated multi-line contracts.
France car insurance constitutes a contractual risk-transfer mechanism under which insurers indemnify policyholders against financial losses arising from vehicle damage, theft, or third-party liability, with premiums calculated through actuarial models incorporating vehicle type, driver history, geographic risk zones, and coverage limits. The primary commercial purpose centers on pooling individual automotive risk across large populations while meeting France's mandatory third-party liability requirement under the Code des Assurances. Liability coverage dominates policy issuance volumes given its legal necessity for all registered vehicles, while electric vehicle segments within the vehicle type dimension attract accelerating premium growth as battery replacement costs reshape claims severity. Fleet categories under customer type concentrate margin pools through negotiated volume contracts and centralized risk management services.
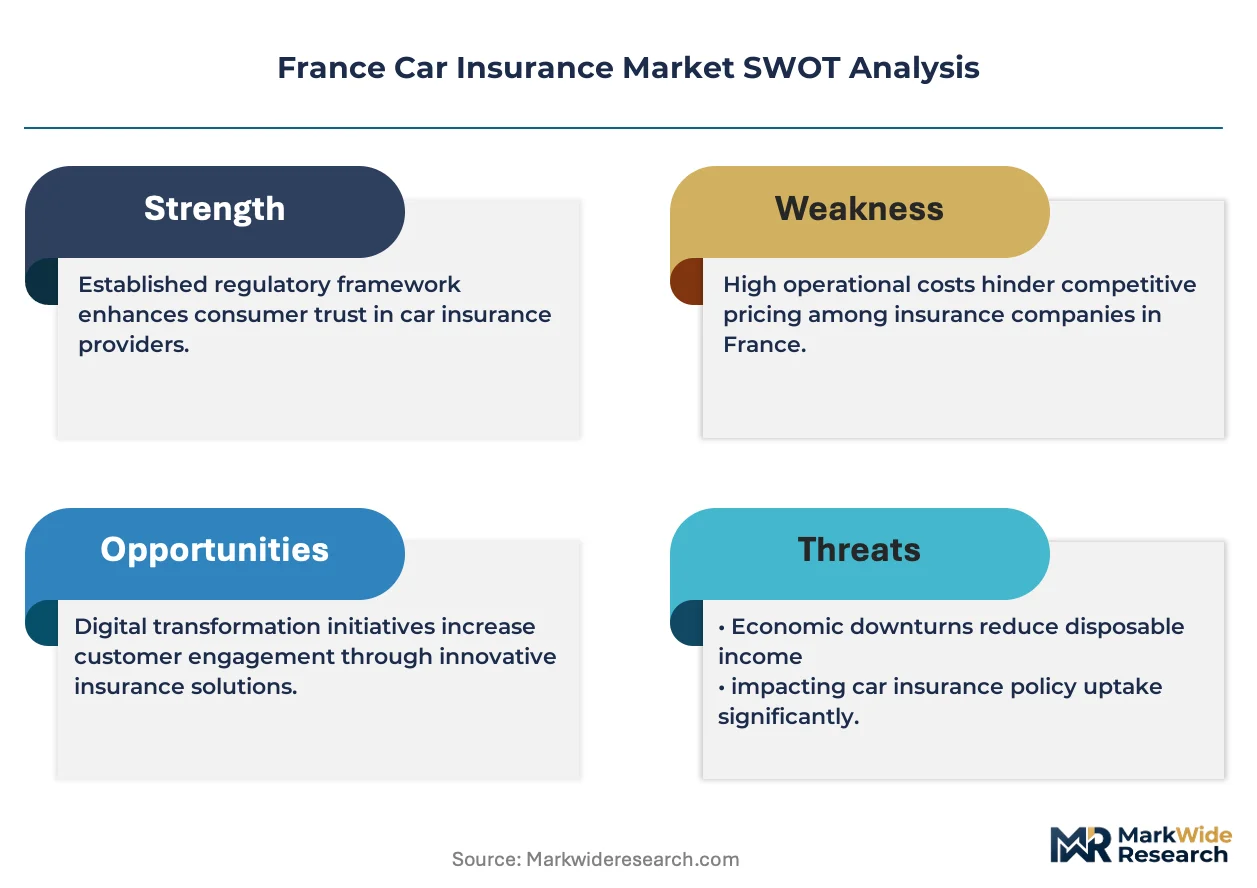
France's car insurance sector operates under dual oversight from the Autorité de Contrôle Prudentiel et de Résolution and the Direction Générale des Finances Publiques, with Solvency II capital requirements dictating insurer reserve adequacy and the EU AI Act imposing algorithmic transparency obligations on automated claims processing systems. The Loi Hamon mandate for simplified policy switching has intensified retention competition among established carriers. Stakeholders must monitor how embedded insurance integrations with vehicle manufacturers and mobility platforms will redistribute distribution control in the coming renewal cycles.
Market Dynamics
Telematics infrastructure is compressing actuarial cycles and forcing carriers to rebuild pricing architectures around real-time behavioral data rather than static demographic proxies.
Growth Catalysts
- Fleet electrification mandates:The EU Green Deal's vehicle emissions standards are compelling commercial operators to replace combustion fleets, generating demand for specialized battery coverage products.
- Telematics penetration:Connected-car platforms now stream braking, acceleration, and mileage data directly to underwriting engines, enabling dynamic premium adjustments.
- Ile-de-France density:Vehicle concentration around Paris sustains the highest premium rates nationally while driving innovation in congestion-adjusted pricing models.
Market Restraints
- Battery replacement cost volatility:Lithium-ion cell prices fluctuate with raw material markets, creating claims severity uncertainty for electric vehicle underwriters.
- Actuarial data scarcity:Limited historical loss experience for electric powertrains forces conservative reserve provisioning that compresses near-term margins.
- Loi Hamon switching friction:Simplified policy cancellation rules intensify retention costs as carriers deploy aggressive discounting to prevent churn.
Strategic Opportunities
- Embedded distribution channels:Vehicle manufacturers and mobility platforms are becoming policy origination points, displacing traditional agency networks.
- Provence-Alpes-Côte d'Azur expansion:Lower penetration rates in southern coastal regions offer whitespace for direct-to-consumer digital acquisition.
- AI Act compliance services:Automated claims processing transparency requirements create advisory revenue streams for algorithmic audit and documentation.
Industry Challenges
- Legacy system integration:Core policy administration platforms require expensive middleware development to ingest streaming telematics feeds.
- Data science talent scarcity:Competition for predictive modelers with automotive risk expertise outpaces French university pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Car Insurance Market |
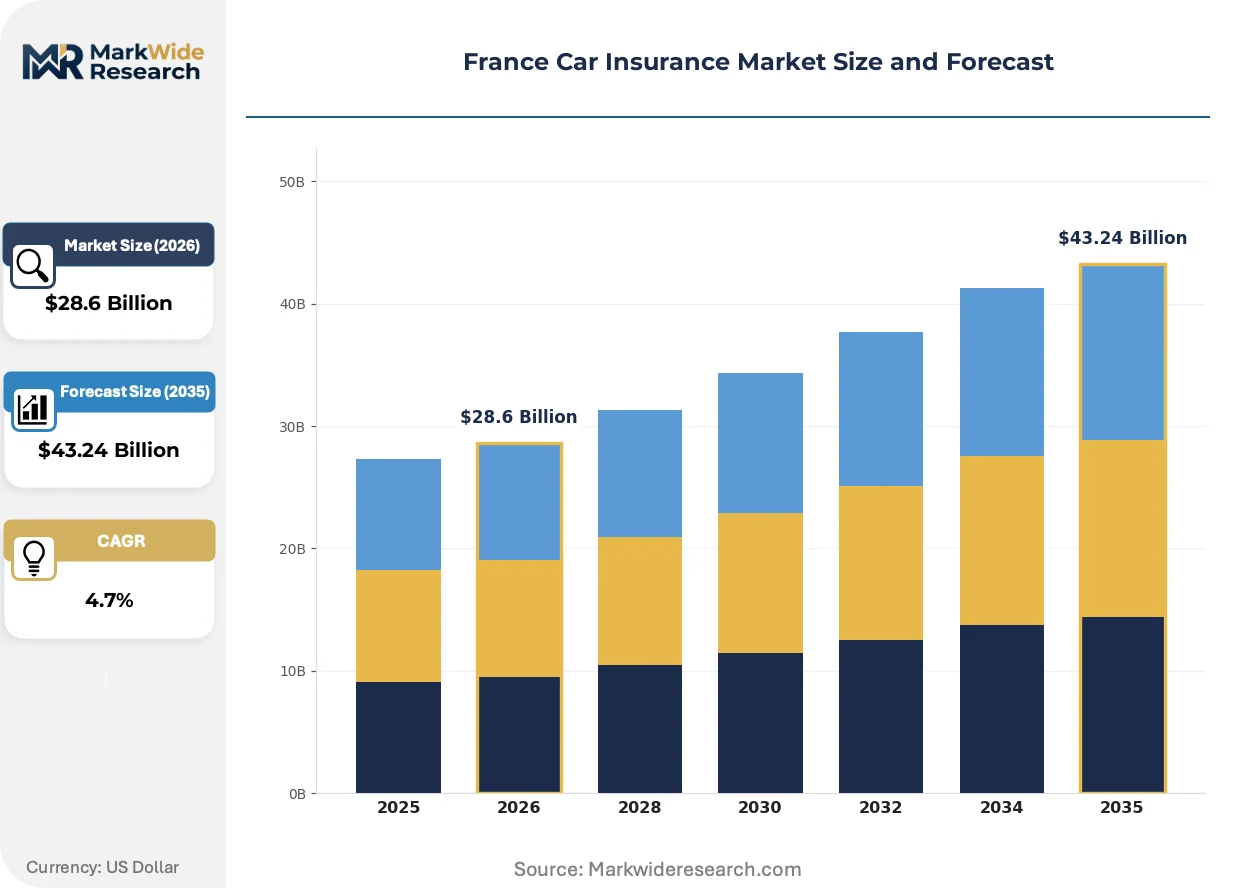
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Liability, Collision, Comprehensive, Personal Injury Protection Customer Type: Private Individuals, Businesses, Fleets, Car Dealerships Policy Duration: Short-term, Annual, Multi-year, Temporary Vehicle Type: Passenger Cars, SUVs, Electric Vehicles, Commercial Vehicles |
| Companies Covered | Predica-Prevoyance Dialogue Du Credit Agricole, Allianz, Generali Iard, Macif, Axa France Iard, Maaf, GMF Assurances, Covea, Groupama, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Car Insurance Market Trends and Innovations
Connected vehicle ecosystems are collapsing the latency between risk occurrence and price adjustment, redefining carrier-policyholder relationships from annual transactions to continuous data exchanges.
Usage-based insurance is migrating from experimental pilot programs to standard product offerings across French direct writers. Mid-market fleet operators now demand pay-per-mile structures that align premium outflows with actual vehicle utilization. This shift is compressing traditional annual policy cycles into monthly or weekly recalibration windows.
The EU AI Act imposes algorithmic transparency obligations on automated claims triage systems deployed by French carriers. Insurers must now document decision logic for damage assessment algorithms and maintain human override capabilities. Personal lines segments with high claim frequency are restructuring processing workflows to meet documentation requirements.
French consumers are consolidating insurance relationships around multi-line bundles that combine auto coverage with homeowner policies. Digital-native distributors are capturing this preference shift through single-quote platforms that cross-sell complementary lines. This behavioral change concentrates margin pools with carriers possessing integrated product portfolios rather than mono-line specialists.
France Car Insurance Market Segmentation
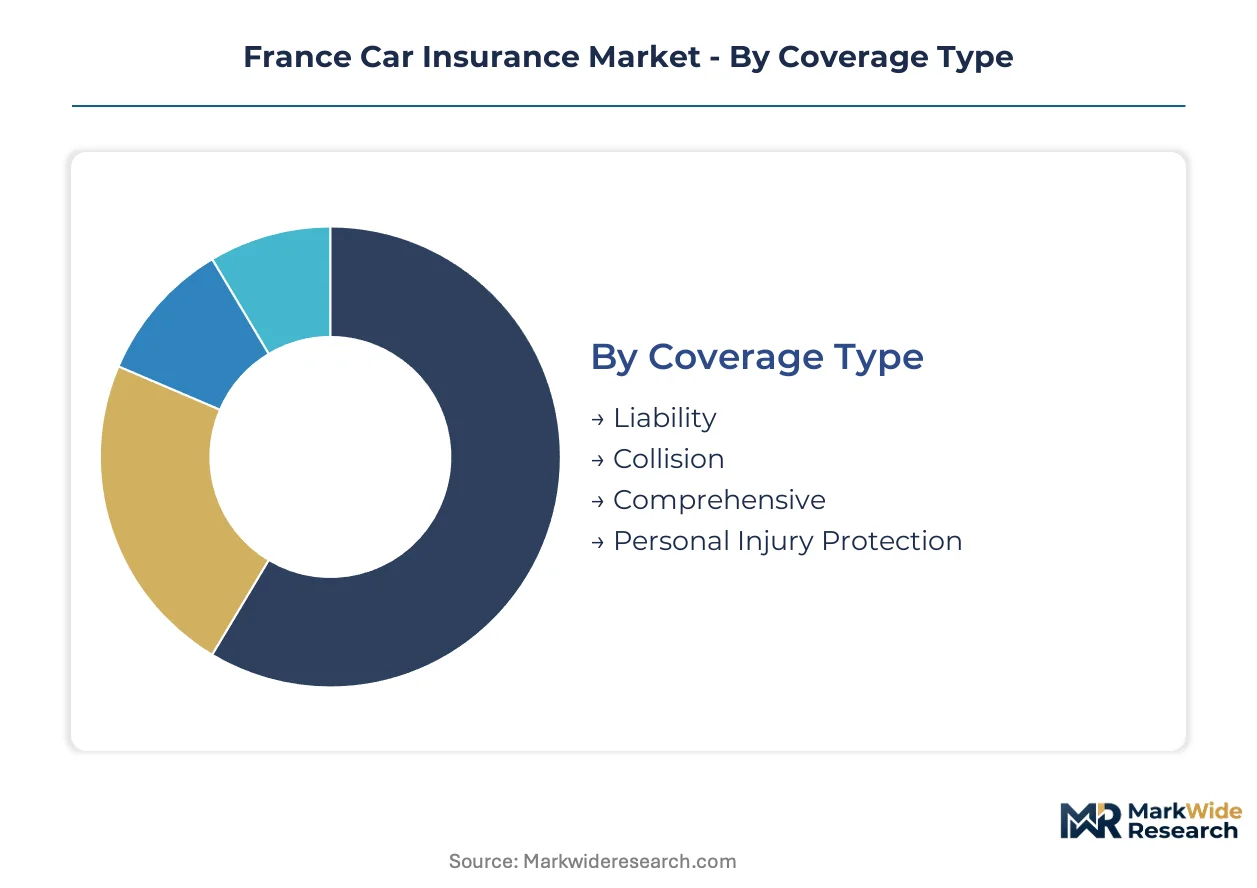
Segmentation in France's car insurance market determines pricing precision, distribution channel selection, and capital allocation across risk pools. Carriers calibrate product architecture to coverage mandates, customer scale, policy flexibility, and vehicle technology profiles.
Coverage Type:
Cost tier structures separate mandatory minimums from discretionary protection layers, with premium gradients reflecting claims severity exposure.
- Liability:Mandatory third-party coverage under the Code des Assurances indemnifies policyholders against bodily injury and property damage to others. Ile-de-France vehicle density sustains the highest premium rates nationally as congestion elevates accident frequency. Regulatory compliance drives universal issuance volume.
- Comprehensive:All-risk protection bundles theft, fire, glass breakage, and weather damage into integrated contracts. Battery replacement costs for electric vehicles are reshaping claims severity and reserve requirements. Demand concentrates among newer vehicle owners seeking asset protection.
- Collision:Covers policyholder vehicle damage from at-fault accidents regardless of third-party involvement. Fleet operators negotiate volume discounts through centralized risk management services.
- Personal Injury Protection:Medical expense and income replacement coverage for driver and passenger injuries. Direct-to-consumer digital channels capture growing interest in health-integrated auto products.
Liability commands the established base. The steepest expansion runs through Comprehensive as electric vehicle adoption accelerates.
Customer Type:
Volume concentration and negotiation leverage differentiate risk pools across individual and commercial accounts.
- Fleets:Commercial operators with 10-plus vehicles procure coverage through negotiated master contracts with centralized billing and unified claims handling. EU Green Deal electrification mandates are forcing fleet managers to restructure coverage around battery degradation and charging infrastructure risks. Telematics integration enables dynamic premium adjustments based on aggregate mileage and driver behavior scores.
- Private Individuals:Personal lines policyholders select coverage through agency networks, direct writers, or comparison platforms. The Loi Hamon simplified switching mechanism intensifies retention competition through aggressive discounting.
- Businesses:Small and mid-sized enterprises insure company vehicles under commercial auto endorsements attached to broader property-casualty programs. Provence-Alpes-Côte d'Azur expansion offers whitespace for digital acquisition among underpenetrated professional segments.
- Car Dealerships:Franchise and independent dealers require garage liability, demonstration vehicle coverage, and inventory protection. Embedded insurance partnerships with manufacturers are redistributing origination control.
Private Individuals anchor premium volume. Fleet segments are climbing the fastest as commercial mobility services expand coverage purchases.
Policy Duration:
Maturity and flexibility dimensions shape carrier cash flow predictability and policyholder retention economics.
- Annual:Standard 12-month policy cycles dominate the French market with automatic renewal provisions and anniversary rate adjustments. Usage-based insurance pilots are compressing traditional annual structures into monthly recalibration windows.
- Short-term:1-30 day coverage serves temporary vehicle borrowing, rental gaps, and seasonal usage patterns. Digital-native distributors capture this preference through single-quote platforms.
- Multi-year:2-3 year contracts lock in premium rates in exchange for guaranteed renewal commitments. Limited penetration reflects consumer price sensitivity and switching incentive structures.
- Temporary:Same-day activation for impromptu vehicle purchases, cross-border travel, and administrative processing delays. Mobile-first interfaces reduce friction for time-bound coverage needs.
Annual policies retain the dominant position. Short-term products are gaining share fastest as mobility platforms and shared vehicle access models proliferate.
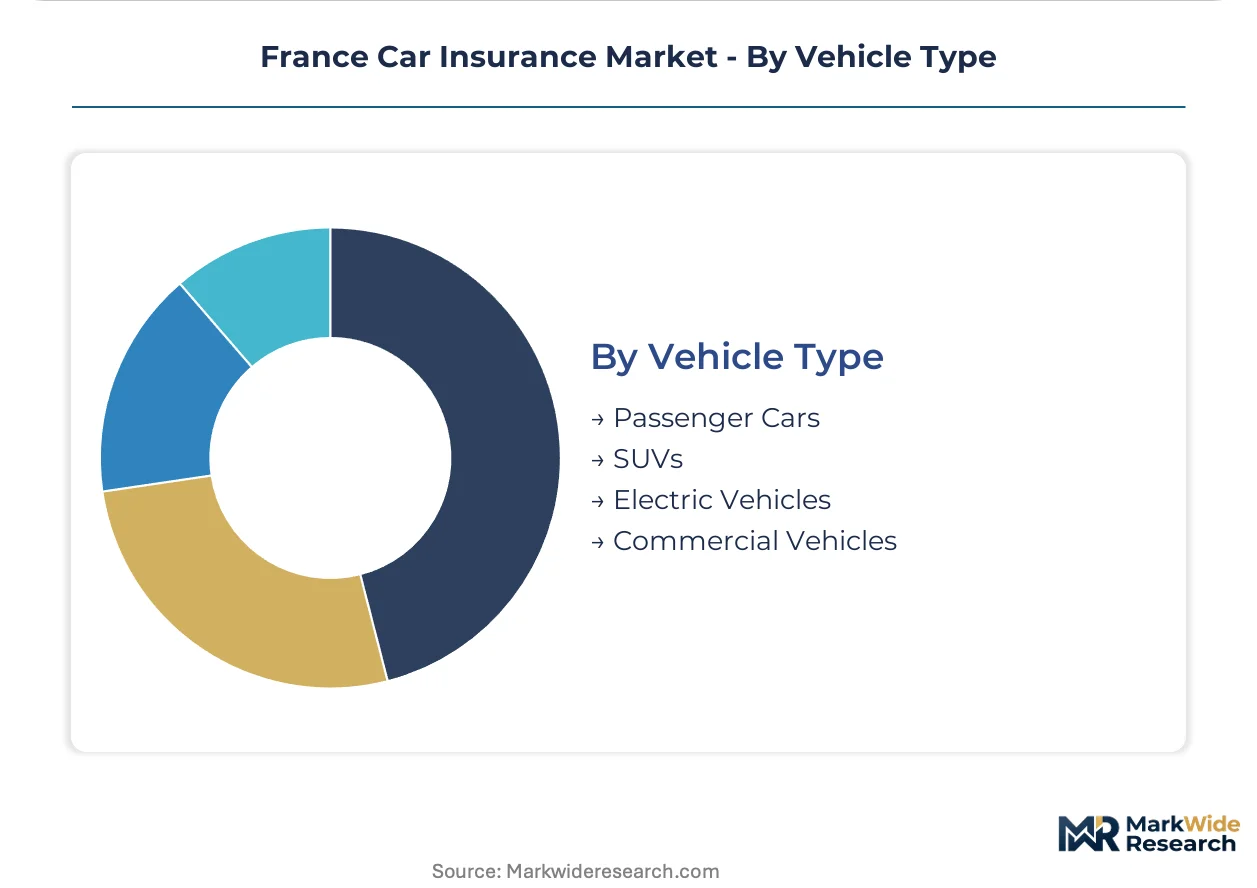
Vehicle Type:
Technology profiles and repair cost structures segment risk pools across powertrain and body classifications.
- Electric Vehicles:Battery electric and plug-in hybrid platforms require specialized coverage for cell degradation, thermal runaway, and charging equipment damage. Actuarial data scarcity forces conservative reserve provisioning that compresses near-term margins. Autorité de Contrôle Prudentiel et de Résolution scrutiny intensifies around evolving risk models.
- Passenger Cars:Standard internal combustion sedans, hatchbacks, and station wagons constitute the historical core of French auto insurance. Telematics penetration is highest in this segment as connected-car platforms stream behavioral data to underwriting engines.
- SUVs:Sport utility vehicles command elevated premiums reflecting higher repair costs and pedestrian injury severity. Ile-de-France congestion-adjusted pricing models capture differential risk profiles.
- Commercial Vehicles:Light and heavy-duty trucks, vans, and specialized equipment serve logistics, construction, and service trades. Fleet electrification mandates are compelling operators to replace combustion platforms and restructure coverage portfolios.
Passenger Cars maintain volume leadership. Electric Vehicles are expanding most quickly as the EU Green Deal drives powertrain transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across French sub-regions. Ile-de-France policyholders absorb the steepest premiums with limited switching, while southern coastal buyers hunt aggressively for rate reductions.
Ile-de-France
Vehicle density around Paris sustains the highest premium rates nationally as congestion elevates accident frequency. The Autorité de Contrôle Prudentiel et de Résolution monitors reserve adequacy for carriers concentrated in this zone. Digital distributors target the Paris periphery with telematics-based congestion-adjusted pricing models.
Auvergne-Rhône-Alpes
Lyon's commercial fleet operators drive demand for multi-vehicle master contracts with centralized risk management. EU Green Deal electrification mandates compel logistics firms to restructure coverage around battery degradation risks. The Grenoble corridor attracts insurtech pilots testing usage-based insurance for alpine driving conditions.
Provence-Alpes-Côte d'Azur
Lower penetration rates in southern coastal regions offer whitespace for direct-to-consumer digital acquisition. The Direction Générale des Finances Publiques tracks premium tax collection efficiency across this underpenetrated zone. Marseille and Nice host emerging embedded insurance partnerships between mobility platforms and regional underwriters.
Hauts-de-France
Industrial logistics hubs around Lille generate concentrated demand for commercial vehicle coverage. Fleet electrification mandates from Brussels reshape procurement patterns for cross-border transport operators. The Calais-Dunkirk corridor sees specialized products for heavy-duty trucks serving Channel freight routes.
Nouvelle-Aquitaine
Rural vehicle ownership patterns sustain traditional annual policy structures with limited telematics adoption. The Loi Hamon simplified switching mechanism intensifies retention competition through aggressive discounting in Bordeaux's suburban sprawl. Biarritz-based brokers test pay-per-mile products for seasonal residents and second-home vehicle fleets.
France Car Insurance Market Competitive Landscape
Capability concentration sits with specialized telematics platforms; scale advantage sits with established mutual networks. The French market structures around three tiers: mutual insurers with dense agency footprints, international carriers with proprietary data infrastructure, and digital-native distributors with direct acquisition engines. Dominant competitive moves include embedded insurance partnerships with vehicle manufacturers and AI-driven claims automation to compress expense ratios.
Among mutual-network carriers, Covea and Groupama exemplify the integrated multi-line bundling archetype that captures consumer preference for consolidated coverage relationships. Axa France Iard occupies a position representing the international carrier tier with connected-car platform investments. These three anchors illustrate how scale, mutual structure, and technology specialization distribute competitive position across the market.
| Leading Market Players |
|---|
| Predica-Prevoyance Dialogue Du Credit Agricole |
| Allianz |
| Generali Iard |
| Macif |
| Axa France Iard |
| Maaf |
| GMF Assurances |
| Covea |
| Groupama |
| Others |
Pricing and Supply Chain Analysis
The Calais-Dunkirk freight corridor's cross-Channel logistics costs cascade through French commercial auto insurance pricing, concentrating premium power with carriers serving heavy-duty fleet operators while forcing price differentiation between international transport specialists and domestic-only coverage tiers.
Pricing Analysis
Extended warranty and battery replacement service contracts now drive lifetime value capture for electric vehicle underwriters. Three-tier pricing structure across premium, standard, and economy levels segments policyholders by telematics adoption depth and claims history granularity. Cost compression in the economy tier is intensifying because direct-to-consumer digital distributors sacrifice margin for volume acquisition. Small and mid-sized enterprises exhibit the highest price sensitivity, while fleet operators with centralized risk management tolerate premium elevation for unified claims handling.
Supply Chain Analysis
EU dual-use technology export controls on advanced telematics hardware limit sensor component flows into French underwriting platforms. Supply concentrates in Germany for actuarial software, Taiwan for semiconductor components, and Ireland for EU regulatory compliance infrastructure. Raw material dependencies span lithium-ion cells for electric vehicle coverage calibration, optical sensors for connected-car data capture, and cloud computing capacity for real-time premium adjustment. Single-source vulnerability runs through proprietary telematics platform licensing. Distribution runs through embedded manufacturer partnerships, agency networks, and direct digital channels in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France car insurance market sits at a platform-economics inflection where connected-vehicle data interoperability standards will determine which carriers capture value from real-time risk streams.
For Market Incumbents: Build data moats through exclusive telematics platform partnerships that lock in proprietary behavioral data feeds. Incumbents must accelerate middleware investment to ingest streaming vehicle data before insurtech challengers achieve API parity. The Loi Hamon switching mechanism threatens retention economics; channel control through embedded manufacturer partnerships offers defensive leverage against price-driven churn. For New Entrants and Emerging Players: Pursue whitespace in Provence-Alpes-Côte d'Azur's underpenetrated professional segments where digital acquisition costs run below Ile-de-France levels. New entrants should target short-term coverage products for mobility platforms and shared vehicle access models, as this segment expands faster than traditional annual policy structures. A mobile-first, single-quote platform architecture enables rapid scaling without legacy system drag. For Investors and Strategic Acquirers: Specialized telematics infrastructure providers with automotive risk modeling capabilities represent the priority acquisition archetype. Long-term viability hinges on carriers' ability to transition from annual transactions to continuous data-exchange relationships with policyholders. Watch for inflection when embedded insurance partnerships capture majority origination volume, signaling redistribution of distribution control.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Allianz's proprietary connected-car infrastructure demonstrates how real-time data streams reconfigure premium calculation precision. |
| Embedded Insurance Partnership | Vehicle manufacturers and mobility platforms are becoming policy origination points that displace traditional agency networks. |
| AI-Driven Claims Automation | The EU AI Act's algorithmic transparency obligations force carriers to restructure processing workflows with human override capabilities. |
| Multi-Line Product Bundling | Covea's integrated home-auto contracts capture consumer preference for consolidated coverage relationships. |
| Geographic Digital Expansion | Direct-to-consumer acquisition in southern coastal regions exploits lower penetration rates outside Ile-de-France. |
Research Methodology
Operator-level perspectives from fleet risk managers, telematics platform engineers, agency network heads, and Autorité de Contrôle Prudentiel et de Résolution supervisory staff anchored the qualitative base. Primary interviews combined with secondary validation from Solvency II regulatory filings, EU Green Deal implementation tracking, and French vehicle registration databases. Bottom-up policy volume estimates triangulated against top-down premium pool calculations from Direction Générale des Finances Publiques tax collection data.
Scenario-bracketing around battery replacement cost volatility and telematics adoption curves framed the analytical approach across the projection horizon. Segmentation dimensions modeled include coverage type, customer scale, policy flexibility, and vehicle powertrain architecture. CAGRs derived from trend extrapolation of fleet electrification mandates and usage-based insurance penetration rates. Industry-specific inputs incorporated charging infrastructure deployment timelines and EU AI Act compliance cost assumptions.
Sensitivities concentrate around lithium price volatility, algorithmic audit requirements, and embedded insurance partnership traction. Forecasts reflect documented assumptions on telematics hardware cost curves and regulatory implementation pacing. Material shifts in EU Green Deal enforcement intensity or battery cell supply chain configuration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Musical Instrument Insurance Market
Insurance
Germany Health and Medical Insurance Market
Insurance
Switzerland Reinsurance Market
Insurance
Critical Illness Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Car Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Telecommunication Insurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
Gap Insurance Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
Employee Benefit Broker Market
Insurance
Australia Parametric Insurance Market
Insurance
India Health Insurance Market
Insurance
Insurance Claims Services Market