
 Europe Road Assistance Insurance Market | 2026-2036
Europe Road Assistance Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Road Assistance Insurance Market Analytics
Market Context
Telematics hardware is recalibrating premium structures across the Europe road assistance insurance landscape, replacing flat-rate models with usage-calibrated pricing. Allianz Partners leverages its pan-European service network to sustain cross-border coverage consistency for international motorists. RAC Motoring Services anchors its competitive stance through proprietary patrol infrastructure that controls response times in the United Kingdom. ADAC dominates the German-speaking corridor with membership density that extends into Austria and Switzerland.
Technical Definition and Segment Structure
Europe road assistance insurance constitutes a specialized non-life coverage product that guarantees emergency roadside intervention—encompassing mechanical repair, vehicle recovery, and onward mobility services—typically triggered by breakdown, accident, or driver incapacitation, with response-time clauses often stipulating sub-60-minute arrival windows on major corridors. The primary commercial purpose centers on reducing driver downtime liability and transferring unpredictable recovery costs to underwritten pools. Towing services occupy the largest share of service-type outlays due to universal applicability across internal-combustion and electric drivetrains, while electric vehicle coverage represents the fastest-expanding vehicle-type segment as battery depletion and high-voltage system failures demand specialized equipment. Corporate and fleet end users concentrate margin pools through multi-vehicle master policies that negotiate volume-based rate cards.
Regulatory Environment and Outlook
EU Green Deal mandates and national motor insurance directives—enforced by EIOPA and member-state financial regulators—are reshaping product standards to incorporate EV-specific recovery protocols and carbon-footprint disclosures in policy documentation. CE marking requirements for roadside equipment and GDPR constraints on telematics data harvesting further tighten operational compliance for insurers and service dispatchers. Stakeholders must monitor how national transpositions of the EU AI Act affect automated claims triage and predictive breakdown algorithms.
Market Dynamics
Telematics penetration is restructuring premium calibration across Europe road assistance insurance, shifting flat-rate contracts toward real-time usage-based pricing that rewards low-mileage drivers and penalizes high-risk behavior patterns.
Growth Catalysts
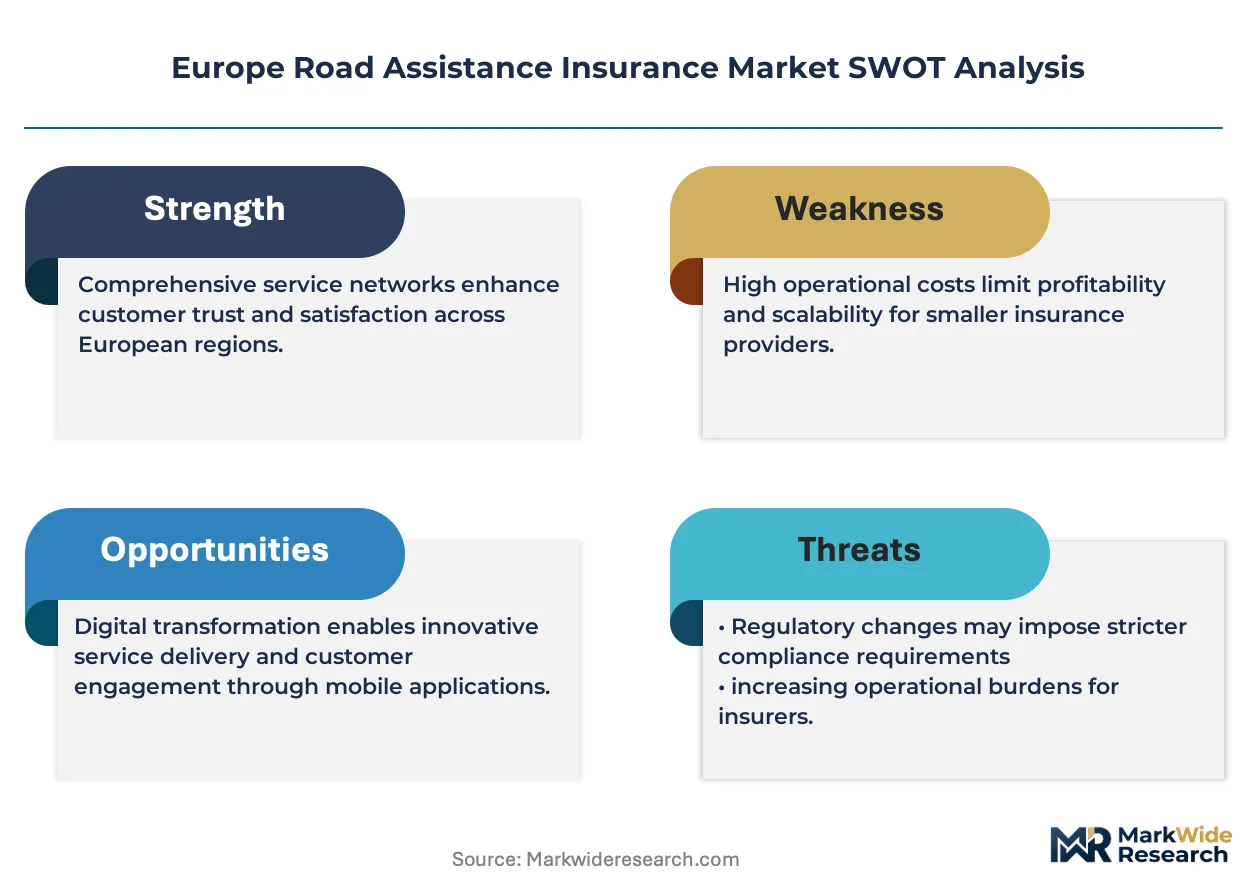
- Fleet electrification mandates:The EU Green Deal's vehicle emission targets are compelling commercial operators to adopt electric drivetrains, generating demand for specialized battery-depletion coverage and high-voltage technician dispatch protocols.
- Cross-border mobility integration:Schengen zone labor mobility and e-commerce logistics are expanding international driver pools that require seamless multi-territory assistance networks with standardized response-time guarantees.
- ADAS proliferation:Advanced driver assistance systems are reducing accident frequency but increasing repair complexity when sensor arrays fail, creating premium opportunities for technology-specific roadside intervention.
Market Restraints
- EV equipment capex concentration:Specialized flatbed trucks with battery isolation systems and insulated lifting gear require capital outlays that concentrate recovery capacity among well-capitalized national operators.
- GDPR data friction:Telematics-driven pricing models face operational constraints from GDPR's purpose limitation and storage minimization requirements, complicating predictive breakdown algorithms.
- Technician certification scarcity:High-voltage safety credentials under EU occupational safety directives remain limited across Southern and Eastern European labor markets, constraining service network expansion.
Strategic Opportunities
- Poland and Romania penetration gaps:Motorway density growth and rising vehicle ownership in these accession markets remain underserved by comprehensive assistance networks relative to Western European coverage depth.
- Subscription mobility bundles:Car-sharing and subscription leasing platforms present white-space distribution channels where roadside assistance integrates into all-inclusive monthly mobility fees.
- CSRD disclosure alignment:The EU Corporate Sustainability Reporting Directive creates competitive differentiation for insurers documenting carbon footprint of recovery fleets and technician routing optimization.
Industry Challenges
- High-voltage technician pipeline:EV-specific safety training programs under national occupational frameworks are failing to match deployment timelines for electric fleet growth, creating dispatch bottlenecks.
- Legacy dispatch system integration:Established assistance networks face technical debt from proprietary software architectures that resist API connectivity with telematics platforms and automated triage engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Road Assistance Insurance Market |
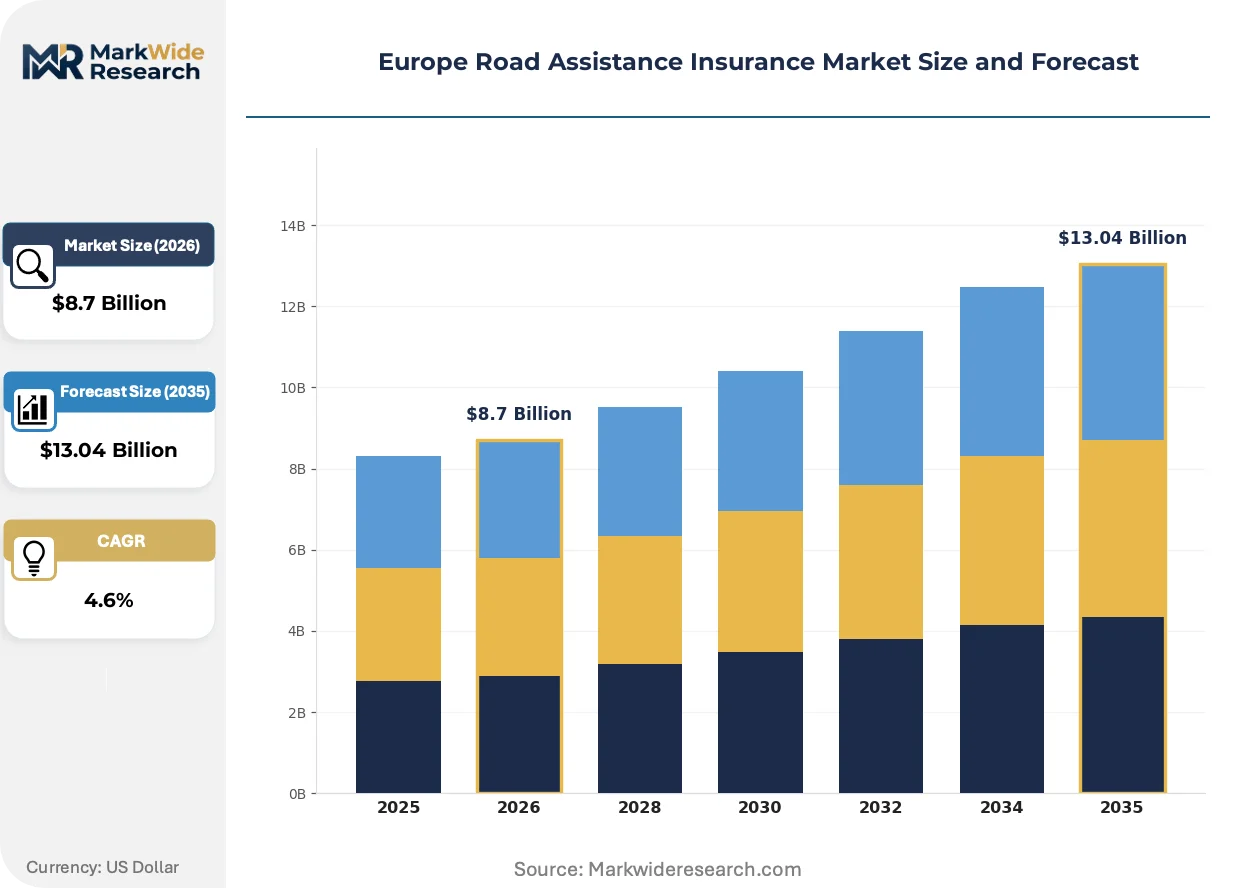
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Towing, Battery Jumpstart, Tire Change, Fuel Delivery End User: Individuals, Corporates, Fleets, Rental Agencies Coverage Type: Comprehensive, Basic, Pay-As-You-Go, Add-On Vehicle Type: Passenger Cars, Motorcycles, Commercial Vehicles, Electric Vehicles |
| Companies Covered | SOS International A/S, Viking Assistance Group, Allianz Partners, RAC Motoring Services, ADAC, ARC Europe SA, Falck A/S, AA plc, Agero Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Road Assistance Insurance Market Evolving Landscape
Digital infrastructure is compressing the interval between breakdown detection and service dispatch, eliminating human call-center intermediation through direct vehicle-to-dispatcher data transmission.
Embedded SIM connectivity is modularizing roadside assistance into original vehicle purchase bundles. OEMs are pre-installing eSIM hardware that transmits diagnostic fault codes directly to contracted assistance networks before driver awareness. This technology is modularizing the traditional post-sale insurance attachment point, compressing independent insurer access to new vehicle buyers.
EU AI Act requirements are reshaping automated claims processing across member states. Algorithmic decision-making in breakdown triage and fraud detection now faces transparency and human-oversight mandates. German and French regulators are enforcing the strictest interpretations, compelling insurers to maintain manual escalation pathways for contested AI determinations.
Fleet procurement teams are consolidating vendor relationships through multi-service master agreements. Large commercial operators now negotiate bundled packages spanning vehicle leasing, maintenance, fuel, and roadside assistance under single-provider frameworks. This concentration is most visible in German logistics corridors where DAX-listed transport groups leverage scale to compress per-incident service fees.
Europe Road Assistance Insurance Market Segmentation
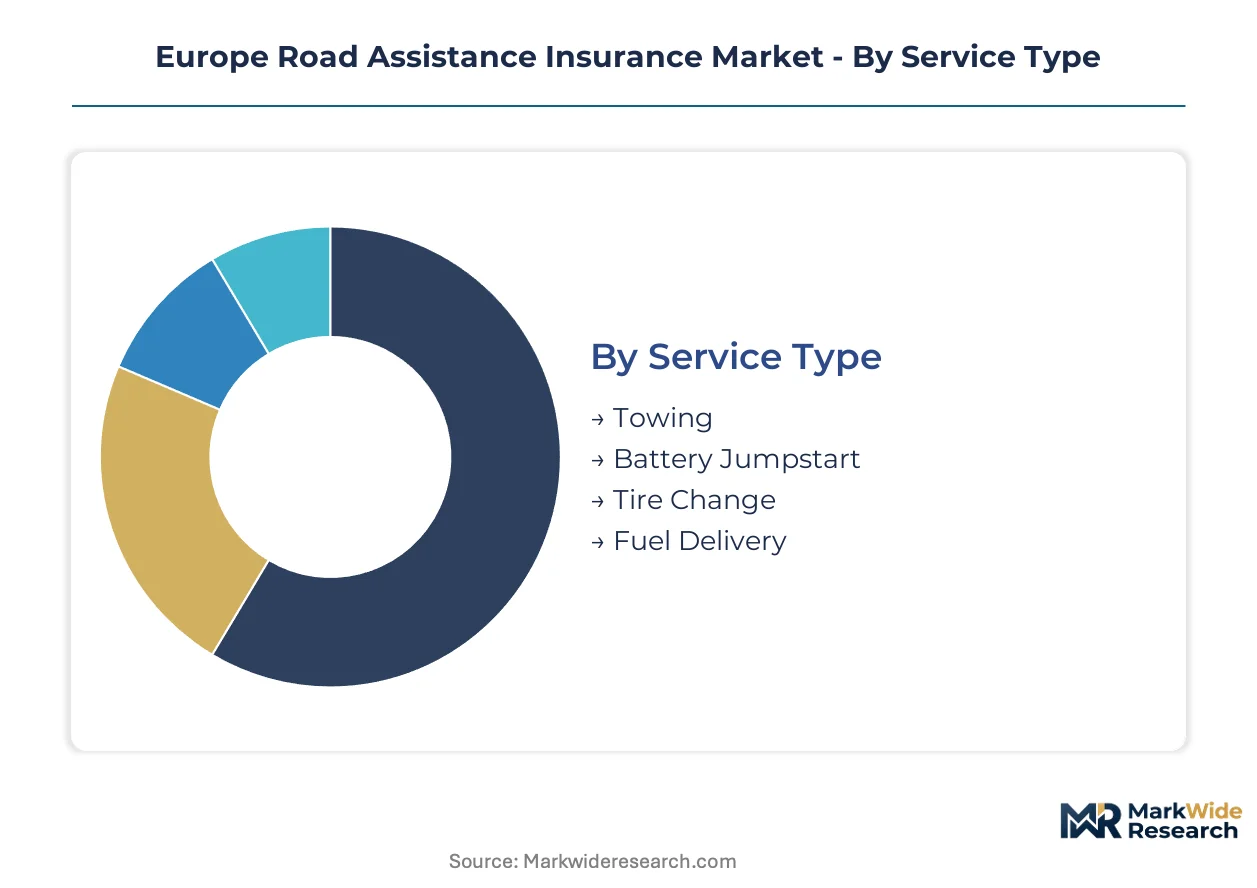
Segmentation in Europe road assistance insurance reveals how coverage products align with divergent risk profiles, dispatch protocols, and regulatory burdens across member states. Insurers calibrate pricing and service networks through these dimensions, matching capital deployment to where recovery complexity and customer lifetime value concentrate.
Service Type:
CE marking requirements under EU machinery directives apply differentially across service categories, with towing equipment facing the heaviest conformity assessment burden while battery jumpstart services operate under lighter electrical safety protocols.
- Towing:Flatbed and wheel-lift configurations dominate infrastructure investment. Recovery operators in Germany and France maintain the densest heavy-capacity fleets to handle commercial vehicle immobilization on motorway corridors. Demand concentrates among fleet operators seeking guaranteed uptime clauses with sub-60-minute response windows.
- Battery Jumpstart:Standardized 12V and 24V systems service conventional internal-combustion fleets. Southern European networks prioritize this capability given aging vehicle pools and extreme temperature-related battery failure rates in Spain and Italy.
- Tire Change:Mobile fitting vans equipped with balancing equipment address run-flat and conventional tire failures. ADAC patrol infrastructure in Germany integrates this as a core membership benefit with dedicated vehicle allocations.
- Fuel Delivery:Emergency diesel and gasoline resupply addresses driver range miscalculation. Rural coverage gaps in Eastern European accession states limit deployment density relative to Western European motorway saturation.
Towing sits at the top of the volume ranking, with battery jumpstart climbing the fastest as EV battery depletion protocols expand service scope.
End User:
Customer acquisition economics vary sharply across buyer types, with fleet master policies delivering scale efficiencies that individual direct-to-consumer channels cannot replicate.
- Individuals:Membership-based models predominate in German-speaking markets where ADAC density creates switching costs. Telematics-linked pricing is displacing flat-rate annual contracts among mileage-variable private motorists.
- Corporates:Multi-vehicle policies covering executive fleets negotiate volume rate cards with pan-European response guarantees. DAX-listed transport groups in Germany leverage procurement scale to compress per-incident fees.
- Fleets:Commercial operators with uptime-dependent business models purchase comprehensive coverage with priority dispatch tiers. EU Green Deal electrification mandates are reshaping fleet specifications toward high-voltage technician requirements.
- Rental Agencies:Airport and urban location networks demand rapid replacement vehicle provisioning alongside roadside intervention. Cross-border Schengen mobility intensifies coverage complexity for international rental pools.
Fleets command the steepest expansion trajectory as electrification mandates and driver safety protocols tighten procurement specifications.
Coverage Type:
Product architecture reflects divergent risk transfer preferences, from comprehensive protection to usage-calibrated micro-policies.
- Comprehensive:All-inclusive protection spanning mechanical failure, accident recovery, onward mobility, and accommodation costs. German motorway density and ADAC competitive pressure sustain premium pricing for this tier.
- Basic:Limited intervention scope covering towing to nearest garage and minimal labor. Price-sensitive segments in Southern and Eastern European markets concentrate here.
- Pay-As-You-Go:Telematics-triggered per-incident billing eliminates annual premium commitment. GDPR data processing constraints complicate predictive pricing algorithm deployment.
- Add-On:Supplementary coverage attached to motor or home insurance policies. Embedded distribution through banking and automotive retail channels dominates this segment.
Comprehensive coverage retains the largest policy count, with pay-as-you-go gaining share fastest among digitally native driver cohorts.
Vehicle Type:
High-voltage safety certification requirements under EU occupational safety directives segment technician deployment capability across drivetrain categories.
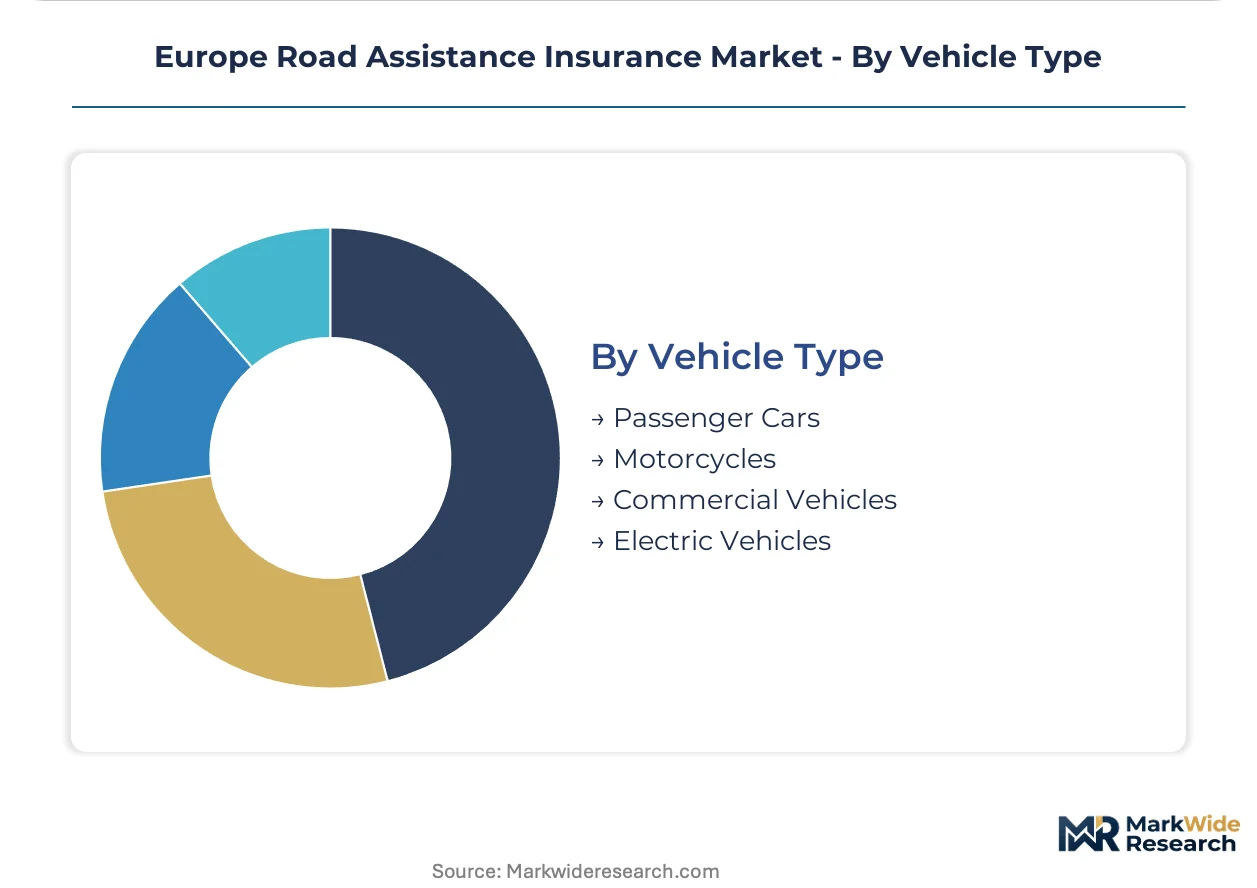
- Passenger Cars:Volume base covering internal-combustion and hybrid drivetrains with standardized recovery protocols. German, French, and UK networks maintain the deepest patrol density for this category.
- Electric Vehicles:Battery isolation systems, insulated lifting gear, and specialized flatbed configurations address high-voltage system failures. Technician certification scarcity across Southern and Eastern Europe constrains network expansion.
- Commercial Vehicles:Heavy-duty towing capacity and cargo recovery protocols serve logistics operators. Fleet procurement consolidation in German corridors drives vendor relationship concentration.
- Motorcycles:Specialized trailer and van configurations accommodate two-wheeler recovery geometry. Mediterranean leisure markets in Italy, Spain, and Portugal sustain seasonal demand concentration.
Passenger cars hold the top volume position, with electric vehicles expanding most quickly as fleet electrification mandates accelerate specialized equipment deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German motorway density and ADAC membership penetration anchor regional demand for comprehensive roadside assistance coverage across Europe.
Germany
Fleet electrification mandates under the EU Green Deal and dense Autobahn infrastructure drive demand for high-voltage technician networks. The KBA enforces strict vehicle safety standards that extend to recovery equipment certification. Bavaria and Baden-Württemberg host the deepest patrol infrastructure concentrations, where commercial logistics operators negotiate uptime-guaranteed master policies.
United Kingdom
Telematics-linked pricing adoption and ADAS-equipped vehicle proliferation reshape coverage requirements for private motorists. The Financial Conduct Authority oversees insurance conduct standards including claims handling transparency. The M1 corridor and Greater London concentrate fleet operator demand for sub-60-minute response guarantees.
France
Cross-border Schengen mobility and e-commerce logistics expansion create demand for seamless multi-territory assistance networks. The ANSM and CNIL enforce GDPR constraints on telematics data harvesting for usage-based pricing. The Île-de-France region anchors corporate fleet procurement consolidation under single-provider frameworks.
Italy
Aging vehicle pools and extreme temperature-related battery failure rates sustain demand for jumpstart services alongside traditional towing. CE marking requirements under EU machinery directives govern recovery equipment deployment. Northern industrial corridors around Milan and Turin concentrate commercial vehicle assistance contracts.
Poland
Motorway density growth and rising vehicle ownership outpace comprehensive assistance network expansion. National transpositions of the EU AI Act affect automated claims triage deployment timelines. The Warsaw-Łódź corridor attracts capital investment from Western European operators seeking geographic diversification.
Europe Road Assistance Insurance Market Competitive Landscape
Global majors compete with regional champions across service network density and cross-border coverage consistency. Market structure shows moderate consolidation around national patrol infrastructure operators, with fragmentation persisting in digital-native entrants and telematics-integrated platforms. Three archetypes dominate: membership-based automobile clubs with proprietary dispatch networks, pan-European insurance partners leveraging cross-border service agreements, and technology-enabled platforms embedding assistance into OEM vehicle bundles. Competitive moves concentrate on M&A to secure technician certification pipelines and strategic partnerships with fleet management platforms.
Among membership-based automobile clubs, ADAC and AA plc exemplify the proprietary infrastructure archetype through dense patrol networks that control response times in their home markets. Allianz Partners occupies a position as the pan-European insurance partner archetype, sustaining cross-border coverage consistency through service network agreements rather than captive infrastructure.
| Leading Market Players |
|---|
| SOS International A/S |
| Viking Assistance Group |
| Allianz Partners |
| RAC Motoring Services |
| ADAC |
| ARC Europe SA |
| Falck A/S |
| AA plc |
| Agero Inc. |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's fleet electrification mandates gate qualified supply and premium-tier pricing access for insurers seeking to underwrite EV-specific roadside coverage. Recovery operators bearing CE-marked battery isolation equipment and high-voltage technician certifications command rate premiums that flat-rate legacy providers cannot match, concentrating margin pools among capitalized national networks.
Pricing Analysis
Input-cost pass-through from specialized EV recovery equipment reshapes premium structures across the Europe road assistance insurance landscape. Three-tier pricing structure across premium, standard, and economy levels segments buyers by response-time guarantees and technician certification tiers. Cost compression in the economy tier intensifies because telematics-enabled pay-as-you-go models displace flat-rate annual contracts. Fleet operators demonstrate the least price sensitivity due to uptime-dependent business models, while individual motorists in Southern European markets exhibit the highest elasticity.
Supply Chain Analysis
Logistics and freight cost escalation from fuel price volatility concentrates recovery fleet procurement decisions in Germany, France, and the United Kingdom. Specialized flatbed trucks with insulated lifting gear draw from automotive OEM chassis production and electrical component suppliers in these core markets. Single-source vulnerability persists for high-voltage safety equipment manufactured under German and French certification regimes. Distribution runs through proprietary patrol networks in membership-based automobile clubs and contracted service agreements with pan-European insurance partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe road assistance insurance market functions as a stable compounder where fleet electrification mandates under the EU Green Deal generate steady demand for specialized coverage products. This regulatory tailwind sustains pricing power for qualified suppliers across the projection horizon.
For Market Incumbents: Acquire high-voltage technician certification pipelines to defend against dispatch bottlenecks as electric fleet deployment accelerates. Consolidate proprietary patrol infrastructure in German motorway corridors where ADAC density creates switching costs. Invest in API connectivity with telematics platforms to neutralize legacy system technical debt. For New Entrants and Emerging Players: Subscription mobility bundles represent an underserved buyer archetype where roadside assistance integrates into car-sharing and leasing platforms. Poland and Romania penetration gaps offer the most penetrable geography given motorway density growth and rising vehicle ownership. Embed coverage through OEM eSIM pre-installation partnerships to bypass traditional insurance distribution channels. For Investors and Strategic Acquirers: Roll-up economics work for regional patrol infrastructure operators because national service networks resist digital-only disruption and retain pricing power through response-time control. Target mid-cap specialists with captive technician training programs and dense coverage in German-speaking corridors. Watch fleet electrification mandate enforcement timelines as the inflection indicator for EV-specific coverage demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Technician Certification Investment | Addresses EU occupational safety directive requirements and removes dispatch bottlenecks for electric vehicle coverage. |
| Telematics Platform Integration | Enables usage-based pricing models that displace flat-rate contracts among digitally native driver cohorts. |
| Cross-Border Service Network Expansion | Supports Schengen mobility demands from international logistics operators and rental agency fleets. |
| OEM eSIM Partnership Development | Captures embedded distribution channels as vehicle manufacturers pre-install diagnostic connectivity hardware. |
| CSRD-Aligned Carbon Disclosure Program | Differentiates coverage products through documented recovery fleet emissions and routing optimization metrics. |
Research Methodology
Coverage spans Western Europe, Central Europe, and the Nordic region, with primary inputs from each market cluster combined with secondary validation. Interviews with fleet procurement managers, roadside assistance network operators, insurance product directors, and telematics platform engineers informed demand-side and supply-side dynamics. Secondary sources included EIOPA regulatory filings, KBA vehicle registration databases, EU Green Deal implementation reports, and member-state motor insurance directive transpositions. Bottom-up policy count estimates triangulated against top-down premium pool calculations.
Rate-of-change decomposition across vehicle electrification penetration, telematics adoption curves, and fleet procurement consolidation patterns anchored the analytical framework. Segmentation dimensions modeled include service type, end-user archetype, coverage tier, and vehicle drivetrain category. CAGRs derived from logistic diffusion curves for EV adoption and linear extrapolation of historical policy growth. Industry-specific inputs encompassed ADAC membership trends, motorway density expansion timelines, and high-voltage technician certification pipeline data.
Inputs from primary stakeholder interviews and published regulatory filings were available through the study window; gaps in real-time telematics pricing algorithm performance introduce uncertainty bands around usage-based coverage adoption forecasts. Forecasts reflect documented assumptions regarding EU Green Deal enforcement consistency and member-state occupational safety directive harmonization. A model refresh is warranted upon material change in fleet electrification mandate timelines or high-voltage technician certification throughput rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Asia-Pacific EV Insurance Market
Insurance
China Business Income Insurance Market
Insurance
Germany Car Insurance Market
Insurance
Finland Cyber (Liability) Insurance Market
Insurance
Aviation Insurance Market
Insurance
B2B2C Insurance Market
Insurance
Logistics Insurance Market
Insurance
Engineering Insurance Market
Insurance
Financial Guarantee Market
Insurance
Asia-Pacific Group Health Insurance Market
Insurance
Income Protection Insurance Market
Insurance
Aerospace Insurance Market
Insurance
China Liability Insurance Market
Insurance
Europe Liability Insurance Market
Insurance
Insurance Third Party Administrators Market
Insurance
Insurance Big Data Analytics Market