
 EV Insurance Market | 2026-2036
EV Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
EV Insurance Market Foresight
A capital-intensity divergence between legacy underwriters and telematics-native entrants is reorganizing competitive dynamics in EV insurance. Allianz leverages its proprietary risk-scoring engine to sustain pricing power across European markets. Ping An Insurance Group anchors its dominance through integrated vehicle-data pipelines from domestic EV manufacturers.
EV insurance constitutes specialized financial protection against damage, liability, and loss incidents involving battery-electric or plug-in hybrid vehicles, with underwriting models incorporating real-time state-of-charge telemetry and thermal-runaway probability algorithms. The primary commercial purpose centers on transferring capital risk from vehicle owners to risk-pooling institutions while aligning premiums with actual driving behavior and battery degradation curves. Liability coverage leads policy issuance volumes due to mandatory minimums across jurisdictions, while pay-as-you-drive plans capture the fastest expansion as usage-based pricing displaces traditional annual contracts. Gap insurance commands concentrated margin pools where rapid EV depreciation outpaces standard comprehensive settlements.
The EU AI Act and national regulators including Germany's KBA and China's MIIT are mandating algorithmic transparency in automated claims decisions, directly shaping product design and market access requirements for algorithmic underwriting platforms. The US NHTSA and EPA coordinate on battery incident reporting standards that determine loss-event categorization and reserve calculations. Stakeholders must monitor whether embedded insurance distribution through OEM captive finance arms will displace independent broker channels before regulatory frameworks crystallize on data ownership and cross-border portability.
Market Dynamics
Telematics-native underwriting platforms are compressing traditional actuarial cycles by ingesting real-time battery-state data streams directly from vehicle OEMs, forcing legacy insurers to rebuild risk-scoring infrastructure around continuous rather than point-in-time assessment.
Growth Catalysts
- Fleet electrification mandates:Commercial logistics operators in California, Germany, and the Netherlands face binding zero-emission vehicle procurement quotas that expand insured asset bases.
- EU AI Act transparency requirements:Algorithmic disclosure rules for automated claims processing are legitimating AI-driven underwriting models and accelerating carrier technology investments.
- Embedded distribution partnerships:Direct integration between insurers and EV manufacturers at point-of-sale is collapsing customer acquisition costs and improving risk-data fidelity.
Market Restraints
- Lithium-ion thermal runaway modeling:Catastrophe reserve calculations remain imprecise due to limited historical battery-fire incident data, inflating capital requirements.
- Repair network concentration:Certified high-voltage technician pools cluster in coastal Chinese provinces and German industrial corridors, extending claim cycle times elsewhere.
- Depreciation-claim mismatch:Rapid EV residual value erosion outpaces traditional comprehensive settlement schedules, generating policyholder disputes and regulatory scrutiny.
Strategic Opportunities
- Second-life battery coverage:Stationary energy storage applications using retired EV packs create uninsured liability exposures requiring novel product development.
- Vehicle-to-grid integration:Bidirectional charging infrastructure exposes homeowners to grid-interconnection risks that standard homeowner policies exclude.
- Pay-per-mile regulatory tailwinds:Usage-based insurance mandates in several European jurisdictions favor telemetry-enabled pricing models over annual contracts.
Industry Challenges
- Cross-border data portability:Vehicle-generated telematics stored in Chinese server farms cannot freely transfer to European underwriters under current data-localization frameworks.
- Legacy system integration:Mainframe-based policy administration platforms at established carriers resist API connectivity with OEM data pipelines, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Insurance Market |
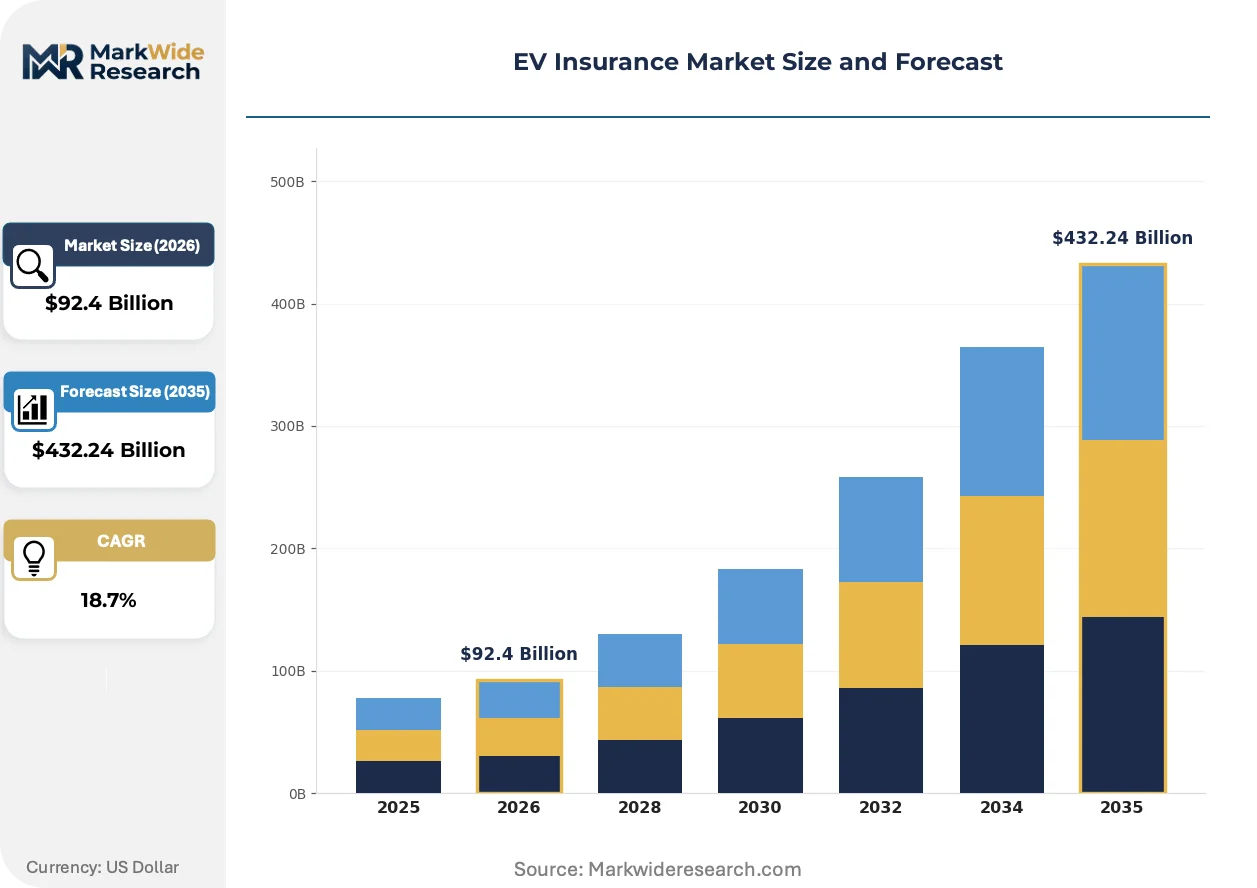
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $432.24 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Liability, Collision, Comprehensive, Gap Insurance Policyholder Type: Individual, Fleet Owner, Commercial, Non-Profit Vehicle Make: Tesla, Nissan, Chevrolet, Ford Payment Plan: Monthly, Annually, Pay-As-You-Drive, Flexible |
| Companies Covered | Aviva, Admiral, Ping An Insurance Group, Generali, Zurich, Allianz, AXA, Progressive, Liberty Mutual Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Insurance Market Shifts & Advancements
Real-time risk instrumentation is collapsing the distinction between underwriting and ongoing asset monitoring, with continuous data feeds replacing annual policy reviews as the dominant customer touchpoint.
Digital twin technology for battery degradation forecasting is decomposing traditional age-mileage rating tables into dynamic health-score pricing. Fleet managers at electrified commercial operators adopt these tools fastest, particularly in German logistics corridors. The shift compresses premium variance between high- and low-utilization vehicles, eroding the cross-subsidy that historically subsidized occasional-use policyholders.
The EU AI Act's algorithmic transparency mandates are forcing claims departments to document automated decision pathways. Insurers must now maintain interpretable model architectures rather than black-box neural networks. European markets face the steepest compliance burden, with Germany's KBA coordinating implementation timelines that lag Brussels by six to twelve months.
Subscription-based insurance products bundled with charging-network memberships are displacing standalone annual policies among urban apartment dwellers without home charging access. OEM captive finance arms pilot these offerings in Shanghai and Shenzhen. The model concentrates distribution power with manufacturers and threatens independent broker channel viability in dense metropolitan markets.
EV Insurance Market Segmentation
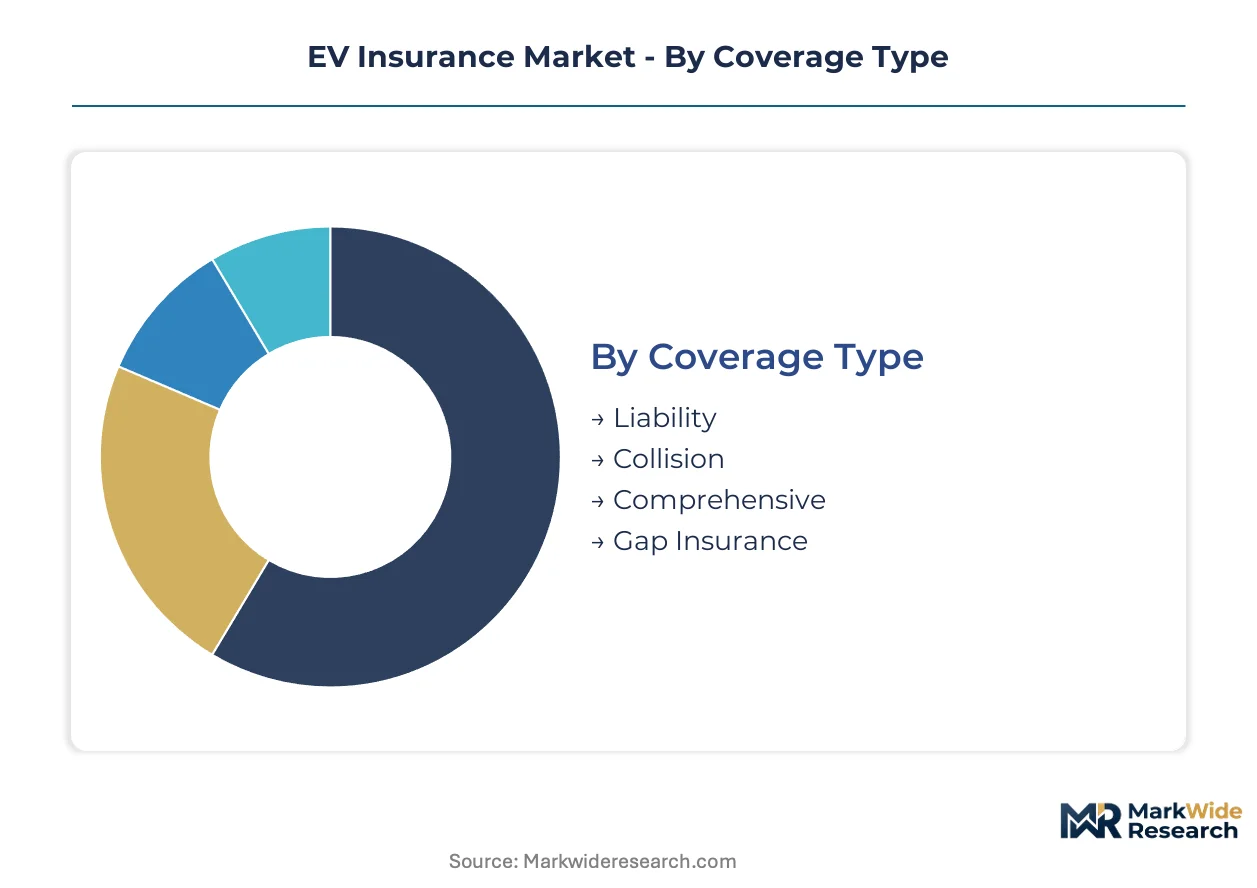
EV insurance segmentation reflects divergent risk profiles across vehicle electrification pathways. Underwriters calibrate pricing models and capital reserves differently for each coverage tier, policyholder class, and telemetry integration depth.
Coverage Type:
Regulatory mandates across Germany, China, and California enforce minimum liability thresholds that vary by vehicle weight class and battery capacity, creating jurisdictional pricing discontinuities for identical coverage bundles.
- Liability:Mandatory third-party protection covering bodily injury and property damage claims from at-fault incidents. Fleet operators in California face binding zero-emission procurement quotas that expand insured asset bases for this coverage tier.
- Collision:Damage repair coverage for at-fault accidents involving other vehicles or stationary objects. Certified high-voltage technician pools cluster in coastal Chinese provinces and German industrial corridors, extending claim cycle times elsewhere.
- Comprehensive:Protection against theft, vandalism, weather damage, and non-collision incidents. Standard settlement schedules struggle to match rapid EV residual value erosion.
- Gap Insurance:Covers the difference between loan balance and actual cash value after total loss. Rapid depreciation outpaces traditional comprehensive settlements, generating concentrated margin pools.
Established volume favors Liability; emerging adoption favors Gap Insurance.
Policyholder Type:
Cost tier differentiation separates mass-market individual purchasers from capital-intensive fleet deployments with integrated telematics infrastructure.
- Fleet Owner:Commercial logistics operators managing multiple electrified vehicles under unified coverage. German logistics corridors adopt digital twin technology for battery degradation forecasting fastest, compressing premium variance between high- and low-utilization assets.
- Commercial:Single-vehicle business use with higher annual mileage exposure. Embedded distribution partnerships with OEM captive finance arms collapse customer acquisition costs.
- Individual:Private passenger vehicle coverage for personal transportation. Subscription-based products bundled with charging-network memberships displace standalone annual policies among urban apartment dwellers.
- Non-Profit:Coverage for charitable and educational fleet operators with constrained capital reserves. Limited historical loss data inflates initial premium quotes relative to commercial equivalents.
Margin concentration sits with Fleet Owner; policy volume expansion centers on Individual.
Vehicle Make:
Application-specific risk scoring varies by manufacturer telemetry integration depth and proprietary battery management system architectures.
- Tesla:Integrated insurance products leverage proprietary vehicle-data pipelines with continuous state-of-charge monitoring. Over-the-air software updates enable dynamic premium adjustments based on real-time driving behavior.
- Nissan:Established actuarial datasets from early Leaf deployments support mature pricing models. Battery degradation curves from decade-long operational history refine reserve calculations.
- Chevrolet:GM's embedded insurance distribution through captive finance arms threatens independent broker channel viability. Bolt thermal-runaway incidents have tightened catastrophe reserve requirements.
- Ford:Commercial F-150 Lightning deployments drive fleet-oriented product development. Bidirectional charging infrastructure exposes homeowners to grid-interconnection risks that standard homeowner policies exclude.
Telematics maturity favors Tesla; commercial volume growth favors Ford.
Payment Plan:
Customer type stratification separates price-sensitive annual payers from behavior-monitored usage-based subscribers.
- Pay-As-You-Drive:Real-time mileage and behavior tracking with monthly premium adjustments. Usage-based insurance mandates in several European jurisdictions favor telemetry-enabled pricing models.
- Monthly:Recurring payment schedules with administrative fee structures. Cash-flow convenience attracts individual policyholders without home charging access.
- Annually:Single upfront payment with discounted rates relative to monthly equivalents. Legacy carrier mainframe systems default to this structure, resisting API connectivity with OEM data pipelines.
- Flexible:Hybrid structures accommodating seasonal usage patterns and temporary vehicle storage. Second-life battery coverage for stationary energy storage applications creates novel product development opportunities.
Regulatory tailwinds favor Pay-As-You-Drive; administrative simplicity favors Annually.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in China outstrips European markets by a factor of three, driven by embedded OEM distribution channels and proprietary telematics pipelines. German underwriters counter with algorithmic sophistication rather than volume scale. Regulatory fragmentation across jurisdictions prevents arbitrage between these divergent market structures.
China
Fleet electrification mandates in Shenzhen and Shanghai expand insured commercial vehicle bases at double-digit rates. MIIT battery-fire reporting standards tighten reserve calculations for thermal-runaway incidents. Ping An Insurance Group dominates distribution through captive partnerships with domestic EV manufacturers in the Yangtze River Delta.
Germany
Logistics operators along the Rhine-Alpine corridor adopt digital twin technology for battery health forecasting faster than any European peer market. KBA implementation of EU AI Act transparency rules lags Brussels by six to twelve months, creating temporary compliance uncertainty. Munich and Stuttgart host the continent's densest pools of certified high-voltage repair technicians.
United States
California's binding zero-emission fleet procurement quotas generate concentrated demand from commercial logistics operators. NHTSA coordination with EPA on battery incident reporting standards determines loss-event categorization for reserve calculations. Detroit and Austin emerge as rival centers for telematics-native underwriting platform development.
United Kingdom
Urban apartment dwellers without home charging access drive subscription-based insurance bundled with charging-network memberships. FCA scrutiny of algorithmic claims decisions accelerates carrier investment in interpretable model architectures. London's financial services cluster incubates pay-per-mile regulatory frameworks before Westminster adoption.
Netherlands
Rotterdam port operators face EU-wide zero-emission logistics deadlines that expand electrified commercial vehicle fleets. Usage-based insurance mandates in Amsterdam and Utrecht favor telemetry-enabled pricing over annual contracts. Eindhoven's automotive technology corridor supplies embedded insurance platforms to German and Belgian carriers.
EV Insurance Market Competitive Landscape
Concentration sits with integrated financial conglomerates possessing proprietary risk-scoring infrastructure and direct OEM data pipelines. The market structure divides between legacy underwriters rebuilding actuarial systems around continuous telemetry feeds and telematics-native entrants compressing traditional pricing cycles. Three archetypes dominate: captive finance arms with embedded distribution, continental insurers with algorithmic transparency compliance, and technology-forward carriers leveraging real-time battery-state monitoring. Competitive moves center on strategic partnerships with vehicle manufacturers and portfolio diversification into second-life battery coverage.
Among European diversified insurers, Allianz and AXA occupy positions defined by algorithmic underwriting sophistication and EU AI Act compliance infrastructure. Ping An Insurance Group anchors the integrated conglomerate tier through exclusive data-sharing arrangements with domestic Chinese EV manufacturers. These three entities exemplify divergent strategic responses to the collapse of traditional annual policy reviews into continuous asset monitoring relationships.
| Leading Market Players |
|---|
| Aviva |
| Admiral |
| Ping An Insurance Group |
| Generali |
| Zurich |
| Allianz |
| AXA |
| Progressive |
| Liberty Mutual Holdings |
| Others |
Supply & Pricing Matrix
Embedded distribution partnerships at point-of-sale lock in premium visibility for insurers while collapsing customer acquisition costs through direct OEM data pipelines. This contract-structure pattern concentrates pricing power with manufacturers possessing captive finance arms, particularly in Chinese markets where Ping An Insurance Group leverages exclusive telemetry-sharing arrangements with domestic EV producers.
Pricing Analysis
The customization-premium spread separates telematics-native underwriters offering real-time battery-state monitoring from legacy carriers relying on static age-mileage tables. Pricing stratifies across telemetry-integrated, standard comprehensive, and basic liability tiers, with differentiation driven by algorithmic sophistication and certified repair network access. Cost compression in the standard tier intensifies as embedded distribution partnerships displace independent broker commissions. Fleet operators demonstrate lowest price sensitivity due to mandatory coverage requirements, while individual urban apartment dwellers exhibit highest elasticity, driving adoption of subscription-based products bundled with charging-network memberships.
Supply Chain Analysis
Extended inventory cycles for certified high-voltage components stretch claim settlement timelines beyond traditional automotive repair benchmarks. Supply concentrates in coastal Chinese provinces and German industrial corridors for battery replacement units, while catastrophe reinsurance capacity clusters in London and Zurich. Raw material dependencies center on lithium carbonate processing, semiconductor-grade silicon for battery management systems, and specialized polymers for thermal isolation barriers. Single-source vulnerability in OEM-certified technician certification programs creates bottleneck risk for collision coverage fulfillment. Distribution runs through captive finance arms at point-of-sale, with secondary flows via independent broker networks in regulatory jurisdictions restricting embedded insurance mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act algorithmic transparency mandates constitute a regulatory inflection that will bifurcate market access between compliant carriers and legacy operators, positioning real-time telemetry integration as the decisive capability for capturing fleet electrification growth.
For Market Incumbents: Consolidate algorithmic underwriting infrastructure around continuous battery-state monitoring rather than point-in-time assessment to defend against telematics-native entrants compressing traditional actuarial cycles. Acquire or partner with OEM data pipeline providers to secure telemetry access before captive finance arms foreclose independent distribution channels. Prioritize EU AI Act compliance infrastructure investment in German and French markets where KBA and CNIL implementation timelines create temporary competitive windows. For New Entrants and Emerging Players: Regulatory fast-track certification for interpretable model architectures under EU AI Act transparency rules opens white-space entry in European markets lagging Brussels implementation. Target second-life battery coverage for stationary energy storage applications, an uninsured liability exposure with minimal incumbent product development. Pursue vehicle-to-grid integration risks as a go-to-market angle, exploiting standard homeowner policy exclusions for bidirectional charging infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward telematics-native underwriting platforms with established OEM data partnerships and proven algorithmic claims-processing capabilities. Long-term viability across the projection horizon hinges on controlling proprietary risk-scoring engines rather than distribution scale. Monitor NHTSA battery incident reporting standard revisions as the critical inflection signal for catastrophe reserve recalibration and carrier capital adequacy requirements.| Strategic Initiative | Industry Significance |
|---|---|
| OEM Data Pipeline Partnership | Ping An Insurance Group's exclusive telemetry-sharing with BYD and NIO anchors pricing power in Chinese markets. |
| Algorithmic Transparency Compliance | EU AI Act interpretable model mandates force claims departments to abandon black-box neural networks for documented decision pathways. |
| Second-Life Battery Coverage Development | Stationary energy storage applications using retired EV packs create uninsured liability pools requiring novel actuarial frameworks. |
| Certified Technician Network Expansion | Munich and Stuttgart's dense high-voltage repair pools extend claim cycle advantages across Rhine-Alpine logistics corridors. |
| Subscription Product Bundling | Charging-network membership integration in Shanghai and Shenzhen collapses customer acquisition costs for urban apartment dwellers. |
Research Methodology
Operator-level perspectives from fleet risk managers, captive finance executives, certified high-voltage repair technicians, and regulatory compliance officers anchored the qualitative base for this analysis. Primary interview findings triangulated against secondary validation from NHTSA battery incident databases, EU AI Act implementation guidance documents, MIIT thermal-runaway reporting standards, and carrier statutory filings with national insurance regulators. Bottom-up policy issuance volume estimates and top-down premium pool calculations converged across the analysis window.
Sensitivity analysis stress-tested forecast outputs against alternative regulatory implementation timelines and battery-fire incident frequency scenarios. The analytical framework modeled segmentation across coverage type, policyholder class, vehicle make, and payment plan architecture throughout the forecast period. CAGRs derived from fitted growth curves incorporating fleet electrification mandate compliance schedules, embedded distribution partnership expansion rates, and telematics adoption penetration curves. Industry-specific inputs included OEM telemetry integration depth indices and certified repair network density metrics by metropolitan cluster.
Decision-makers should treat outputs as directional under assumptions of sustained EU AI Act enforcement continuity and stable lithium-ion battery chemistry incident rates; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Bancassurance Market
Insurance
Digital Transformation in Insurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
Gap Insurance Market
Insurance
Digital Innovation in Insurance Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Single Trip Travel Insurance Market
Insurance
Insurance BPO Services Market
Insurance
Microinsurance Market
Insurance
North America Liability Insurance Market
Insurance
Internet of Things Insurance Market
Insurance
Insurance Claims Services Market
Insurance
United States Insurance Brokerage Market
Insurance
Earthquake Insurance Market
Insurance
Usage-Based Insurance (UBI) Market
Insurance
Employee Benefit Broker Market