
 Germany Electronic Gadgets Insurance Market | 2026-2036
Germany Electronic Gadgets Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Electronic Gadgets Insurance Market Foresight
Cloud-native policy administration is repositioning cost structures across the Germany electronic gadgets insurance sector. Allianz SE leverages its captive digital infrastructure to control distribution economics in smartphone coverage. Simplesurance GmbH anchors its model through embedded checkout partnerships with electronics retailers. Zurich Insurance Group competes via modular API-first architectures that reduce per-policy issuance costs.
Germany electronic gadgets insurance constitutes risk-transfer products covering repair, replacement, or indemnity for portable electronic devices against accidental damage, theft, liquid ingress, or mechanical failure, typically underwritten through annual premiums or point-of-sale micro-policies with automated claims adjudication via optical damage recognition. The coverage type dimension shows accidental damage and theft protection commanding the deepest margin pools due to higher perceived risk and price elasticity, while extended warranty competes primarily on attach rate at retail checkout. End user segmentation reveals individual consumers generating the highest policy volume, though freelancers and startups represent the fastest-growing cohort as device-dependent income amplifies risk aversion.
BaFin's digital distribution guidelines and the German Insurance Contract Act (VVG) shape product transparency, cooling-off periods, and claims-handling standards that directly influence policy design and customer acquisition compliance burdens. KBA and consumer protection frameworks indirectly affect gadget insurance through connected device safety requirements that expand insurable risk categories. Stakeholders must monitor regulatory evolution around algorithmic pricing transparency and embedded insurance disclosure obligations to preserve distribution channel viability.
Market Dynamics
Cloud-native policy administration is compressing distribution costs and enabling real-time claims adjudication across the Germany electronic gadgets insurance sector, forcing incumbents to rebuild core systems or cede ground to API-first competitors.
Growth Catalysts
- BaFin Digital Distribution Guidelines:Embedded insurance partnerships with electronics retailers now operate under clearer disclosure frameworks, reducing compliance friction and accelerating checkout integration velocity.
- Freelancer Device Dependency:Germany's gig economy workforce treats smartphones as income-critical infrastructure, amplifying risk aversion and policy attachment rates at point-of-sale.
- Optical Damage Recognition:Automated claims processing via smartphone camera submissions cuts adjudication cycles from days to minutes, improving customer retention and loss-ratio predictability.
Market Restraints
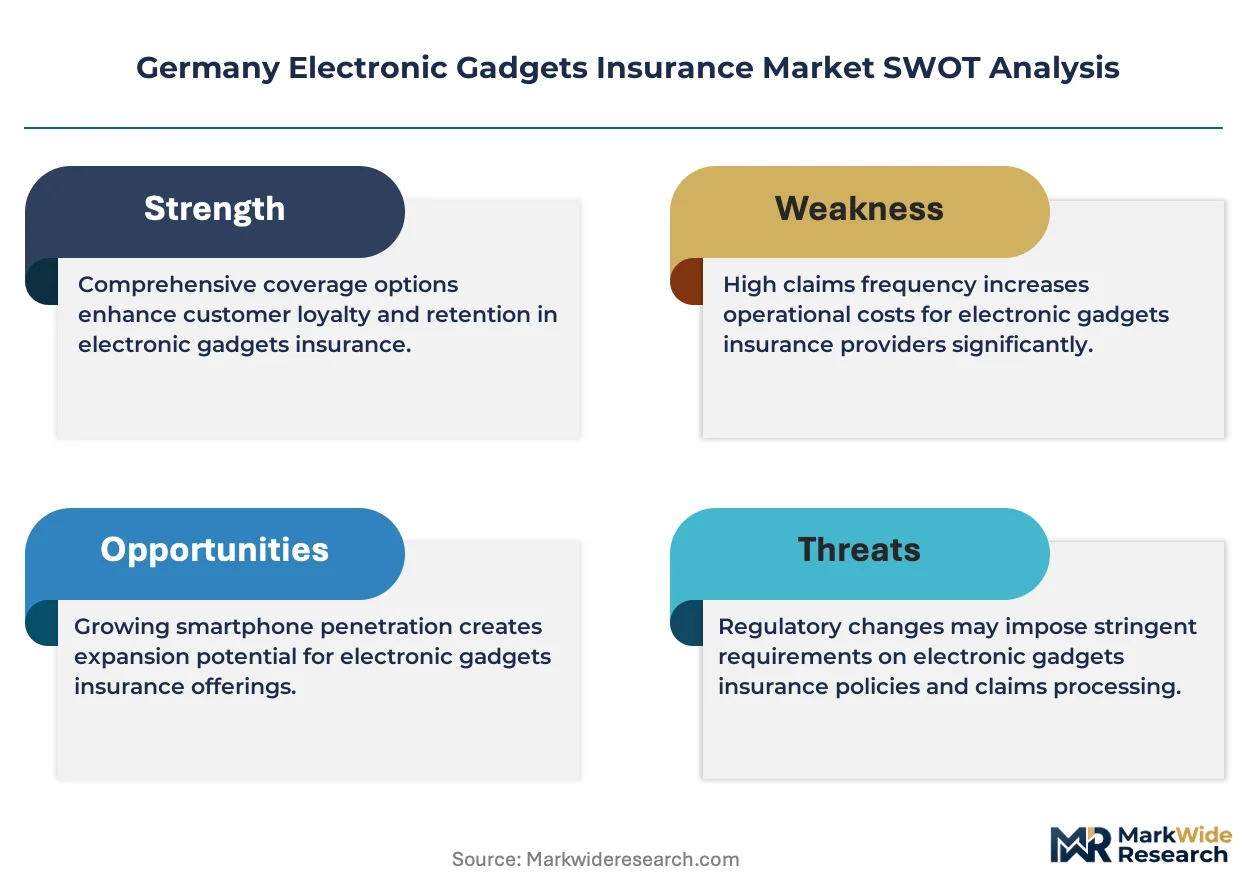
- Extended Warranty Margin Compression:Retail checkout attach rates for mechanical failure coverage face pricing pressure from manufacturer-backed programs, squeezing standalone underwriter economics.
- Algorithmic Pricing Transparency Requirements:BaFin's evolving disclosure obligations on automated underwriting models increase compliance documentation burdens and slow product iteration cycles.
- Component Supply Concentration:Repair cost volatility tracks semiconductor and display panel availability concentrated in East Asian manufacturing clusters, distorting loss reserves.
Strategic Opportunities
- Berlin-Munich-Hamburg Device Replacement Cycles:Urban centers with compressed 18-24 month smartphone refresh rates present concentrated demand pools for annual premium products with rapid depreciation clauses.
- Startup Ecosystem Expansion:Venture-backed hardware companies in Bavaria and Baden-Württemberg require fleet coverage for prototype devices, opening B2B policy lines with higher average premiums.
- VVG Cooling-Off Period Optimization:Digital-first insurers can engineer 14-day withdrawal workflows that exceed baseline compliance, converting regulatory minimums into competitive differentiation.
Industry Challenges
- Legacy Core System Integration:Incumbent insurers face middleware complexity when connecting decades-old policy administration platforms to modern API ecosystems, inflating IT project timelines.
- Fraud Pattern Detection Talent Scarcity:Shortages of data scientists with device damage forensics expertise limit automated claims validation accuracy, requiring manual review escalation.
- Embedded Partner Contract Negotiation:Electronics retailers demand revenue-sharing terms and exclusivity windows that compress underwriting margins and constrain multi-channel distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Electronic Gadgets Insurance Market |
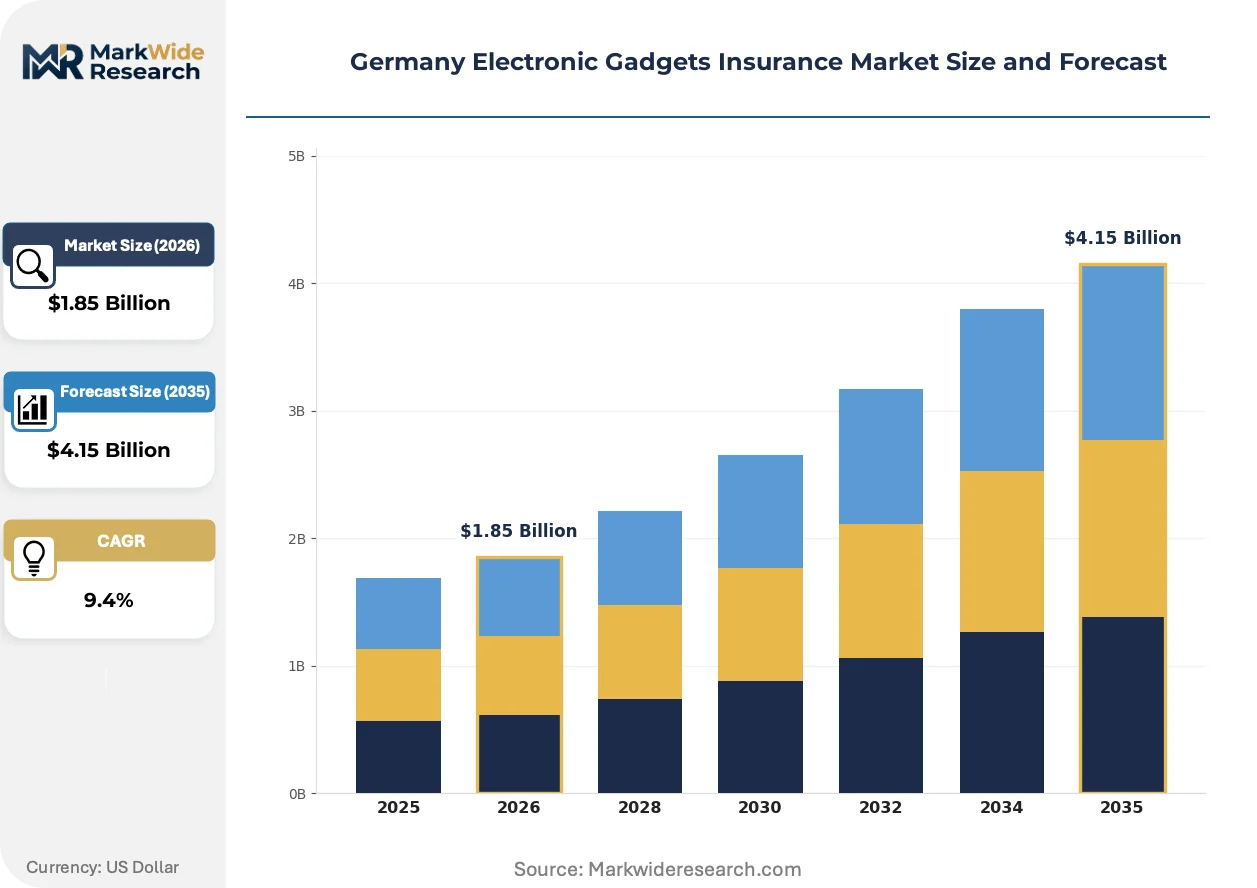
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Tablets, Laptops, Smartwatches, Cameras, Headphones Coverage Type: Accidental Damage, Theft Protection, Extended Warranty, Liquid Damage, Loss Protection, Malfunction End User: Individual Consumers, Small Enterprises, Freelancers, Educational Institutions, Startups Distribution Channel: Online Platform, Retail Stores, Insurance Brokers, Mobile Carriers, Direct Sales |
| Companies Covered | Zurich Insurance Group, Simplesurance GmbH, Allianz SE, Chubb European Group SE, Wertgarantie, AXA Deutschland, Assurant Germany, R+V Versicherung, ERGO Group AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Electronic Gadgets Insurance Market Shifts & Advancements
Real-time risk telemetry from connected devices is rewriting actuarial models, while regulatory pressure on algorithmic transparency and embedded disclosure is reshaping product architecture and partner economics.
Blockchain-enabled parametric claims settlement is decentralizing trust mechanisms between insurers and policyholders. Freelancers and gig workers in Hamburg and Berlin are piloting smart-contract policies that trigger automatic payouts upon verified device failure. This architecture is decentralizing the traditional claims adjuster role and compressing dispute resolution overhead.
Germany's Insurance Contract Act (VVG) amendments are tightening cooling-off period enforcement and mandating granular coverage disclosure in embedded checkout flows. Electronics retailers must now display policy terms in standardized formats before purchase completion. Smartphone coverage sold at point-of-sale faces the steepest compliance adaptation costs as partners reengineer checkout sequences.
Subscription-based device protection is displacing annual premium models among younger demographics in Munich and Frankfurt. Insurtech platforms bundle coverage with device trade-in credits and cloud backup services, unbundling the standalone policy. This shift is most visible among startup employees and creative professionals who prioritize cash-flow flexibility over multi-year commitments.
Germany Electronic Gadgets Insurance Market Segmentation
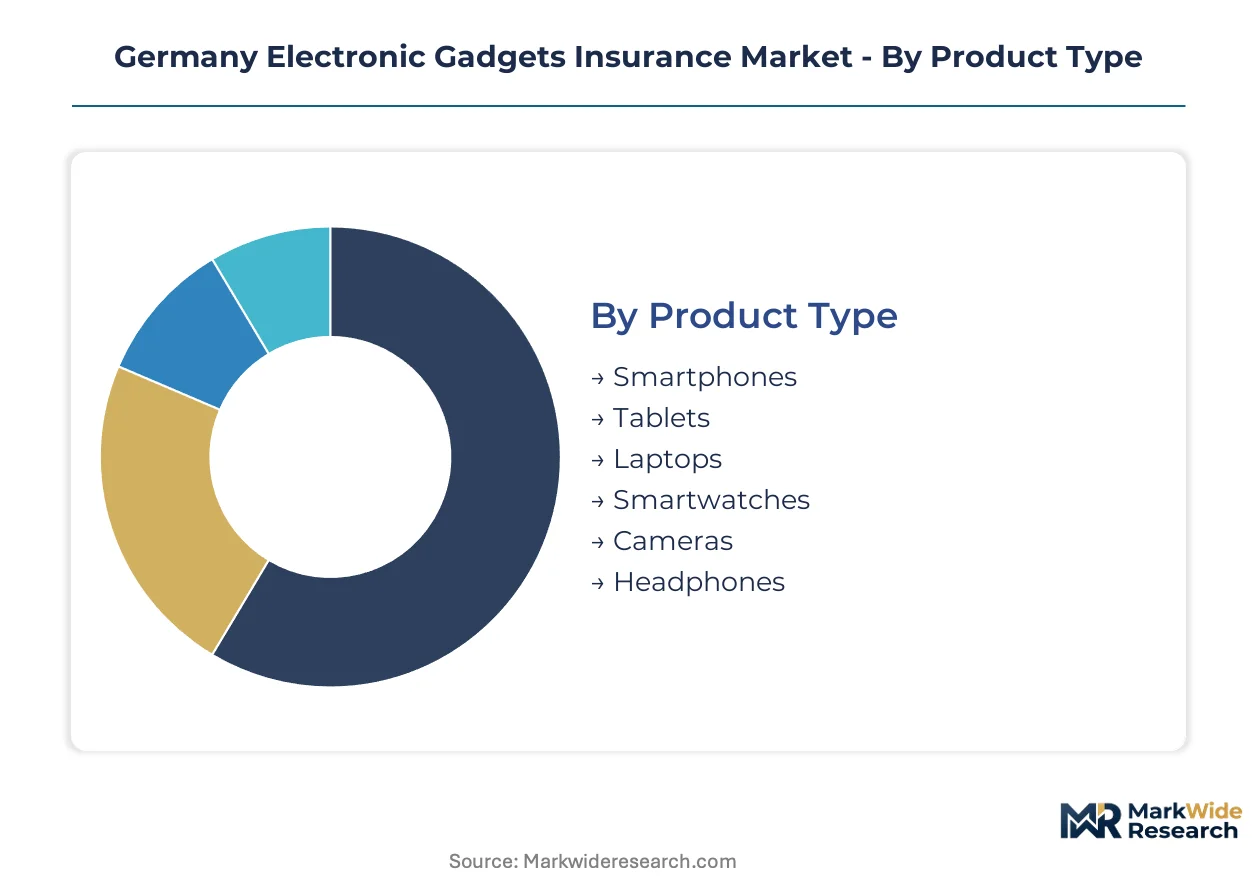
Segmentation in Germany's electronic gadgets insurance market reveals divergent margin economics and acquisition channel strategies across device categories, coverage types, and buyer profiles. Each dimension carries distinct regulatory touchpoints under BaFin guidelines and VVG requirements that shape product architecture and distribution economics.
Coverage Type:
Accidental damage and theft protection command premium pricing power, while extended warranty competes on volume attach rates at retail checkout.
- Accidental Damage:Covers screen fractures, impact damage, and structural deformation from drops or collisions. Demand concentrates among freelancers in Berlin and Munich where device downtime directly interrupts income streams, driving willingness to pay higher premiums for rapid replacement.
- Theft Protection:Indemnifies against device loss through criminal taking, often bundled with tracking recovery services. Urban centers with elevated property crime rates—particularly Hamburg and Frankfurt—show the strongest attachment rates, with gig workers prioritizing this coverage for income-critical smartphones.
- Extended Warranty:Covers mechanical and electrical failures beyond manufacturer terms. Retail checkout integration with electronics merchants drives volume, though manufacturer-backed programs compress standalone underwriter margins.
- Liquid Damage:Protects against submersion, spills, and moisture ingress. Claims adjudication relies heavily on optical damage recognition and moisture indicator verification.
- Loss Protection:Covers misplacement and unexplained disappearance, distinct from theft. Higher moral hazard drives stricter documentation requirements and depreciation schedules.
- Malfunction:Addresses software corruption, operating system failures, and component degradation outside physical damage. Lower claims frequency supports competitive pricing in direct-to-consumer channels.
Mature deployment sits with extended warranty through established retail partnerships. Newer deployment is concentrated in accidental damage via API-integrated digital distribution.
Product Type:
Smartphone coverage dominates policy volume, while laptop and smartwatch segments exhibit divergent replacement cycle dynamics.
- Smartphones:Highest absolute policy count driven by 18-24 month replacement cycles in urban Germany. Freelancers and gig workers treat these as income infrastructure, amplifying risk aversion and point-of-sale attachment.
- Laptops:Longer depreciation horizons and higher average device values support annual premium products with staged payout structures. Small enterprises in Bavaria and Baden-Württemberg drive B2B fleet coverage demand.
- Tablets:Hybrid use patterns between entertainment and productivity create coverage overlap with both smartphone and laptop policies. Educational institutions represent a concentrated procurement channel with volume pricing.
- Smartwatches:Emerging segment with fitness and health monitoring integration. Shorter replacement cycles and lower absolute values favor micro-policy and embedded checkout models.
- Cameras:Professional and prosumer equipment carries specialized valuation challenges. Munich's creative industry cluster generates disproportionate demand for high-value equipment riders.
- Headphones:Lowest average policy value but highest frequency of loss and damage claims. Retail attach rates peak during promotional periods and gift-giving seasons.
Revenue concentration aligns with smartphone and laptop categories. Steepest expansion trajectory appears in smartwatch coverage as wearable adoption broadens beyond early adopters.
End User:
Individual consumers generate foundational volume, while freelancer and startup segments exhibit superior lifetime value through lower churn and higher coverage limits.
- Individual Consumers:Price-sensitive segment acquired primarily through retail embedded channels and mobile carrier bundles. VVG cooling-off period compliance shapes digital onboarding workflows.
- Freelancers:Device-dependent income elevates risk aversion and willingness to pay for comprehensive coverage. Berlin and Hamburg concentrations align with gig economy density.
- Small Enterprises:Fleet policies covering 5-50 devices with centralized administration and consolidated billing. Procurement decisions favor insurance brokers offering multi-line discounts.
- Startups:Venture-backed hardware companies require prototype coverage and rapid replacement terms. Bavaria's hardware startup ecosystem drives specialized B2B product development.
- Educational Institutions:Volume procurement with standardized device fleets and institutional payment terms. Extended warranty and accidental damage dominate coverage mix.
Established account concentration rests with individual consumers through retail partnerships. Emerging account growth centers on freelancers via digital-first distribution platforms.
Distribution Channel:
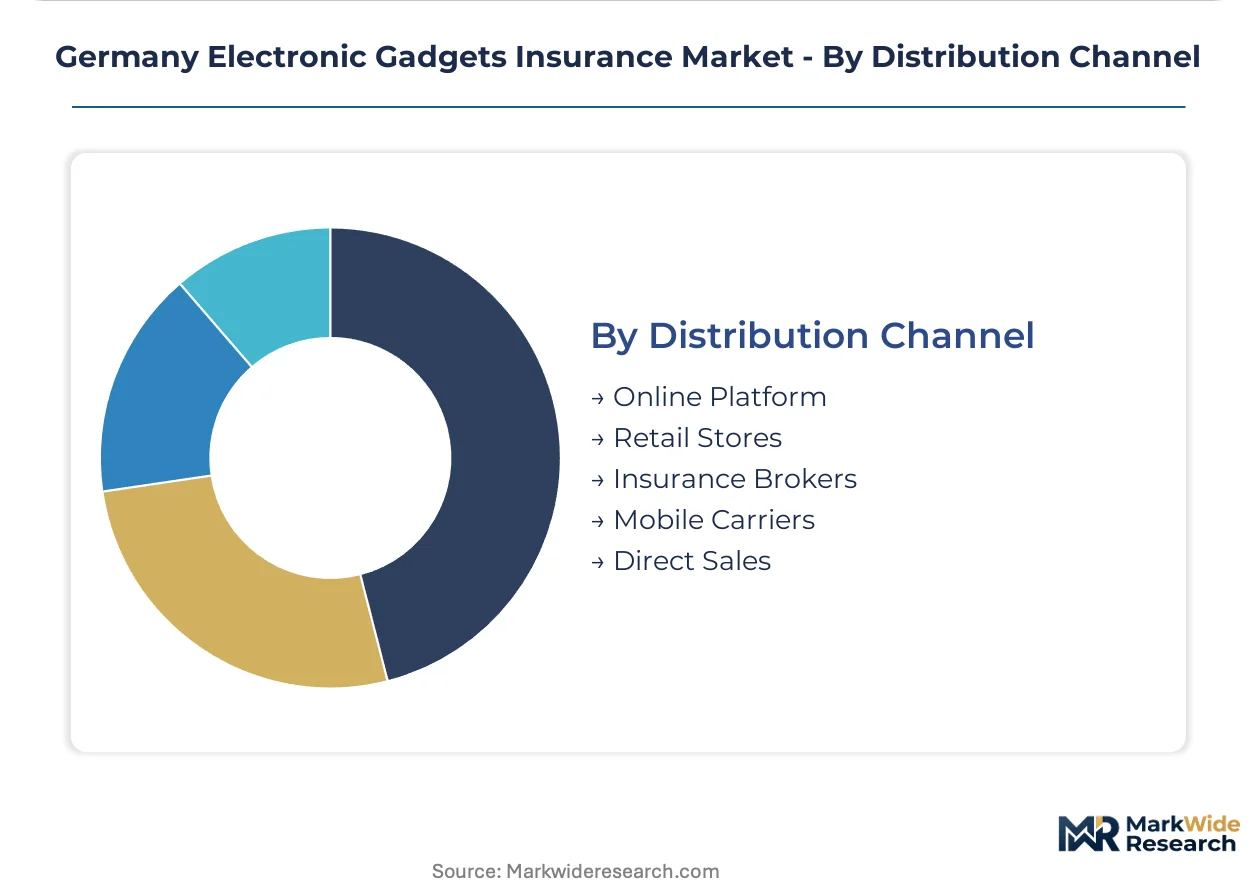
Online platforms capture margin efficiency, while retail stores and mobile carriers dominate volume acquisition through embedded integration.
- Online Platform:Direct-to-consumer acquisition with API-enabled quote-to-bind workflows. BaFin digital distribution guidelines mandate pre-purchase disclosure sequencing that shapes UX architecture.
- Retail Stores:Point-of-sale embedded integration with electronics merchants. Revenue-sharing negotiations and exclusivity windows constrain underwriter economics.
- Insurance Brokers:Advisory channel serving small enterprises and institutional buyers. Consultative sales process supports complex fleet policy customization.
- Mobile Carriers:Device financing bundles with monthly billing integration. Subscriber data enables risk-based pricing but raises algorithmic transparency compliance burdens.
- Direct Sales:Insurer-owned channels with proprietary customer data. Higher acquisition costs offset by superior retention and cross-sell economics.
Volume leadership belongs to retail and carrier embedded channels. Margin optimization is shifting toward online platforms with cloud-native policy administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban centers with compressed device replacement cycles concentrate demand for electronic gadgets insurance across Germany's federal states. Berlin, Munich, and Hamburg generate disproportionate policy volume due to shorter 18-24 month smartphone refresh rates among tech-savvy professionals. BaFin's digital distribution guidelines apply uniformly, though regional implementation varies by local insurance association density.
Bavaria
Hardware startups in Munich and the surrounding metropolitan area drive specialized B2B coverage for prototype devices. KBA vehicle safety standards indirectly expand insurable risk categories for connected automotive gadgets. The Munich creative industry cluster generates concentrated demand for high-value camera equipment riders.
North Rhine-Westphalia
Düsseldorf and Cologne host dense concentrations of freelancers treating smartphones as income-critical infrastructure. The German Insurance Contract Act (VVG) cooling-off period requirements shape digital onboarding workflows for direct-to-consumer platforms. Embedded insurance partnerships with electronics retailers concentrate in the Rhine-Ruhr urban agglomeration.
Baden-Württemberg
Stuttgart's automotive technology ecosystem creates demand for fleet coverage of diagnostic and testing devices. BaFin algorithmic pricing transparency obligations slow product iteration cycles for regional insurtech platforms. Venture-backed hardware companies in the Stuttgart region require rapid replacement terms for development equipment.
Berlin-Brandenburg
Gig economy density in Berlin amplifies risk aversion among device-dependent freelancers. The VVG mandates granular coverage disclosure in embedded checkout flows, forcing retailers to reengineer purchase sequences. Optical damage recognition pilots for automated claims processing concentrate in Berlin's insurtech hub.
Hamburg
Port city logistics workers and maritime professionals generate elevated theft protection demand for income-critical smartphones. BaFin's evolving disclosure obligations on automated underwriting models increase compliance documentation burdens for Hamburg-based insurers. Smart-contract parametric policies for freelancers pilot in Hamburg's blockchain-focused fintech cluster.
Germany Electronic Gadgets Insurance Market Competitive Landscape
Embedded checkout partnerships dominate the current landscape as insurers race to secure electronics retailer integration. The market exhibits tiered structure with incumbent multinationals, digital-native insurtechs, and specialized warranty providers competing through distinct channel strategies. Three archetypes define competitive positioning: cloud-native API-first platforms, captive digital infrastructure operators, and retail-embedded specialists. M&A activity and exclusive distribution negotiations represent the dominant competitive moves, with revenue-sharing terms and multi-year exclusivity windows determining channel access.
Within the incumbent tier, Zurich Insurance Group and Allianz SE exemplify divergent technology strategies. Zurich operates through modular API-first architectures that reduce per-policy issuance costs, while Allianz leverages captive digital infrastructure to control distribution economics. Simplesurance GmbH anchors the insurtech archetype through embedded checkout partnerships with electronics retailers, representing the API-native competitive model.
| Leading Market Players |
|---|
| Zurich Insurance Group |
| Simplesurance GmbH |
| Allianz SE |
| Chubb European Group SE |
| Wertgarantie |
| AXA Deutschland |
| Assurant Germany |
| R+V Versicherung |
| ERGO Group AG |
| Others |
Supply & Pricing Matrix
Data science talent concentration in Berlin and Munich drives actuarial labor-cost differentials that widen pricing-tier spreads between cloud-native insurtechs and legacy underwriters. BaFin's algorithmic transparency mandates add compliance overhead that premium-tier carriers absorb more readily than economy-positioned competitors.
Pricing Analysis
Volume concentrates in embedded checkout micro-policies with razor-thin margins, while annual premium products for freelancers generate superior unit economics. Pricing stratifies across premium, standard, and economy tiers based on claims automation sophistication and coverage breadth. Cost compression in the extended warranty tier intensifies because manufacturer-backed programs eliminate standalone underwriter differentiation. Individual consumers at retail checkout show highest price sensitivity; freelancers purchasing direct-to-consumer annual policies demonstrate lowest elasticity.
Supply Chain Analysis
Freight and logistics costs for replacement device fulfillment hinge on semiconductor and display panel sourcing concentrated in Taiwan, South Korea, and China. Repair cost volatility feeds from NAND flash memory, OLED substrates, and precision camera modules. Single-source vulnerability in advanced node chip fabrication distorts loss reserve calculations. Distribution runs through authorized service networks, third-party repair aggregators, and direct-to-consumer replacement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where controlling claims adjudication technology determines margin capture. Players are pursuing downstream control over repair fulfillment networks to escape partner revenue-sharing compression.
For Market Incumbents: Hedge against API-first insurtech disruption by acquiring optical damage recognition capabilities or licensing computer-vision patents. Prioritize captive repair network buildout in Berlin and Munich to reduce third-party fulfillment costs. Channel control through exclusive electronics retailer contracts remains essential for volume defense. For New Entrants and Emerging Players: Begin with freelancer segment targeting in Hamburg and Berlin where device-dependent income amplifies risk aversion and reduces price sensitivity. White-space exists in B2B fleet coverage for Bavarian hardware startups requiring prototype protection. API-native distribution partnerships with direct-to-consumer electronics platforms offer lowest customer acquisition friction. For Investors and Strategic Acquirers: The window for entry favors insurtech platforms with embedded checkout integration and cloud-native policy administration infrastructure. Long-term viability hinges on claims automation accuracy that compresses loss adjustment expense ratios. Watch BaFin algorithmic pricing disclosure rulemaking as the critical inflection signal for compliance-cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Damage Recognition Deployment | Automated claims adjudication via smartphone camera submissions cuts Zurich Insurance Group's processing cycles from days to minutes. |
| Embedded Checkout Partnership Expansion | Simplesurance GmbH's electronics retailer integrations capture policy attachment at point-of-sale with minimal friction. |
| Captive Repair Network Buildout | Allianz SE's proprietary service infrastructure eliminates third-party fulfillment margins and accelerates replacement velocity. |
| API-First Architecture Migration | Modular policy administration systems reduce per-issuance costs for digital-native competitors against legacy core platforms. |
| Freelancer Segment Product Development | Income-critical device coverage for gig workers commands premium pricing with lower churn than retail-embedded individual policies. |
Research Methodology
Document review covered BaFin regulatory filings, VVG amendment texts, and embedded insurance disclosure guidelines, complemented by interviews with claims operations directors at tier-1 insurers, digital distribution platform CTOs, and electronics retailer partnership managers. Secondary validation drew from insurance association statistical yearbooks, insurtech funding databases, and consumer protection agency complaint records. Bottom-up policy volume estimates triangulated against top-down premium pool calculations.
Cross-referencing historical claims frequency patterns against expert panel input on optical recognition adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include coverage type, device category, end-user archetype, and distribution channel complexity. CAGRs derived from fitted growth curves incorporating freelancer workforce expansion rates and device replacement cycle compression in urban centers.
Underlying measurement precision varies by segment; smartphone coverage volume carries tighter precision than emerging smartwatch categories due to established data sources. Forecasts reflect assumptions on BaFin regulatory enforcement intensity and semiconductor supply normalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
US Electronic Gadgets Insurance Market
Insurance
Auto Compulsory Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Insurance Third Party Administrators Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Musical Instrument Insurance Market
Insurance
United States Dental Insurance Market
Insurance
Denmark Property and Casualty Insurance Market
Insurance
North America Car Insurance Aggregators Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Global Mobile Phone Insurance Ecosystem Market
Insurance
Digital Monetary Insurance Market
Insurance
Employee Benefit Broker Market
Insurance
Asia-Pacific Insurance Aggregators Market
Insurance
Peru Insurance Market