
 Africa Microinsurance Market | 2026-2036
Africa Microinsurance Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Microinsurance Market Intelligence
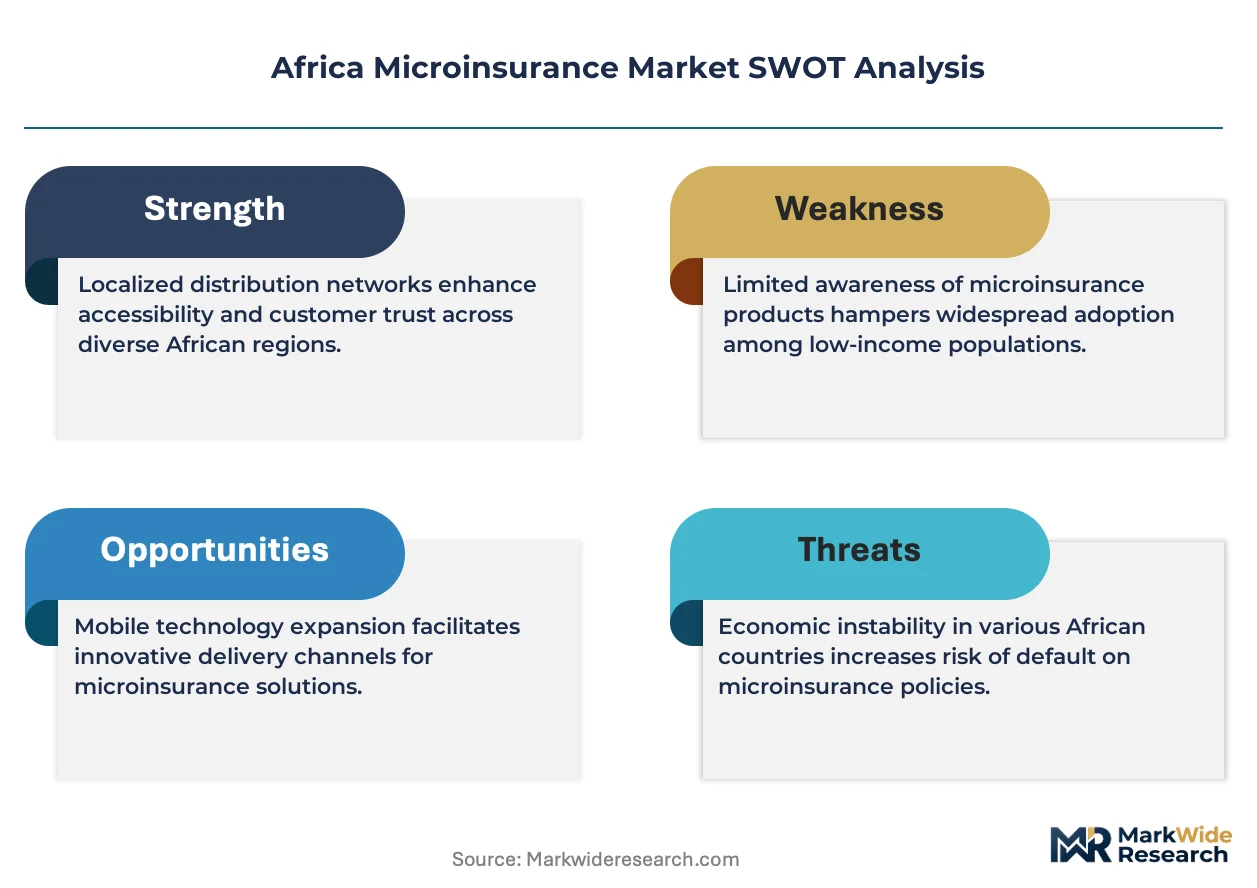
Mobile-first distribution is restructuring premium collection economics across East and West Africa. Discovery Limited leverages its digital health ecosystem to reach previously unbanked populations, while Sanlam Group anchors its position through community-based delivery partnerships in Southern Africa. Jubilee Holdings competes via agricultural microinsurance tied to index-based weather products for smallholder farmers.
Microinsurance denotes risk-pooling mechanisms designed for low-income populations, typically featuring premium thresholds below five percent of household income, simplified underwriting via group enrollment, and claims settlement within fourteen days through mobile money rails. Its primary commercial purpose centers on replacing informal risk-sharing arrangements with formal, scalable protection against health shocks, crop failure, and asset loss. Health Insurance leads product type penetration due to persistent out-of-pocket medical expenditure burdens, while Mobile Platforms represent the fastest-growing delivery channel as telecom interoperability expands. Agricultural Insurance commands concentrated margin pools where index-linked parametric structures reduce claims verification costs.
The African Insurance Organisation coordinates cross-border supervisory standards, while national regulators including South Africa's Financial Sector Conduct Authority and Kenya's Insurance Regulatory Authority enforce capital adequacy and consumer protection mandates. These frameworks shape product filing requirements, agent licensing, and mobile wallet integration protocols that determine market access velocity. Stakeholders must monitor regulatory divergence between francophone and anglophone jurisdictions as digital licensing pathways mature.
Market Dynamics
Mobile money infrastructure is compressing distribution costs and enabling real-time premium collection across previously unreachable rural populations in East and West Africa.
Growth Catalysts
- M-Pesa interoperability:Kenya's mobile money rails allow instant premium deductions and claims disbursement, eliminating cash-handling overhead for rural agents.
- Index-based weather products:Parametric triggers using satellite rainfall data eliminate costly field verification for agricultural coverage in drought-prone regions.
- African Insurance Organisation harmonization:Cross-border supervisory standards reduce compliance duplication for insurers expanding across multiple jurisdictions.
Market Restraints
- Smartphone penetration gaps:Feature-phone limitations constrain complex product interfaces in rural Ghana and Nigeria, forcing simplified SMS-based offerings.
- Actuarial data scarcity:Limited mortality and morbidity baselines for informal workers inflate pricing uncertainty and reserve requirements.
- Climate volatility concentration:Correlated weather shocks across Sahel regions create systemic exposure that reinsurers price punitively or exclude.
Strategic Opportunities
- Ethiopia's unbanked agricultural workforce:Telecom liberalization and banking sector opening create first-mover advantage for embedded crop and livestock products.
- Health-microcredit bundling:Integration with digital lending platforms captures repayment-protected borrowers at point of loan disbursement.
- National microinsurance frameworks:Kenya's Insurance Regulatory Authority sandbox licensing accelerates product approval timelines for innovative delivery models.
Industry Challenges
- Agent network liquidity management:Float requirements for premium collection strain working capital in dispersed rural distribution.
- Legacy core system integration:Insurers' on-premise policy administration platforms require middleware development for mobile API connectivity.
- Fraud detection at scale:Synthetic identity creation for ghost policies demands biometric verification investments that erode thin margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Microinsurance Market |
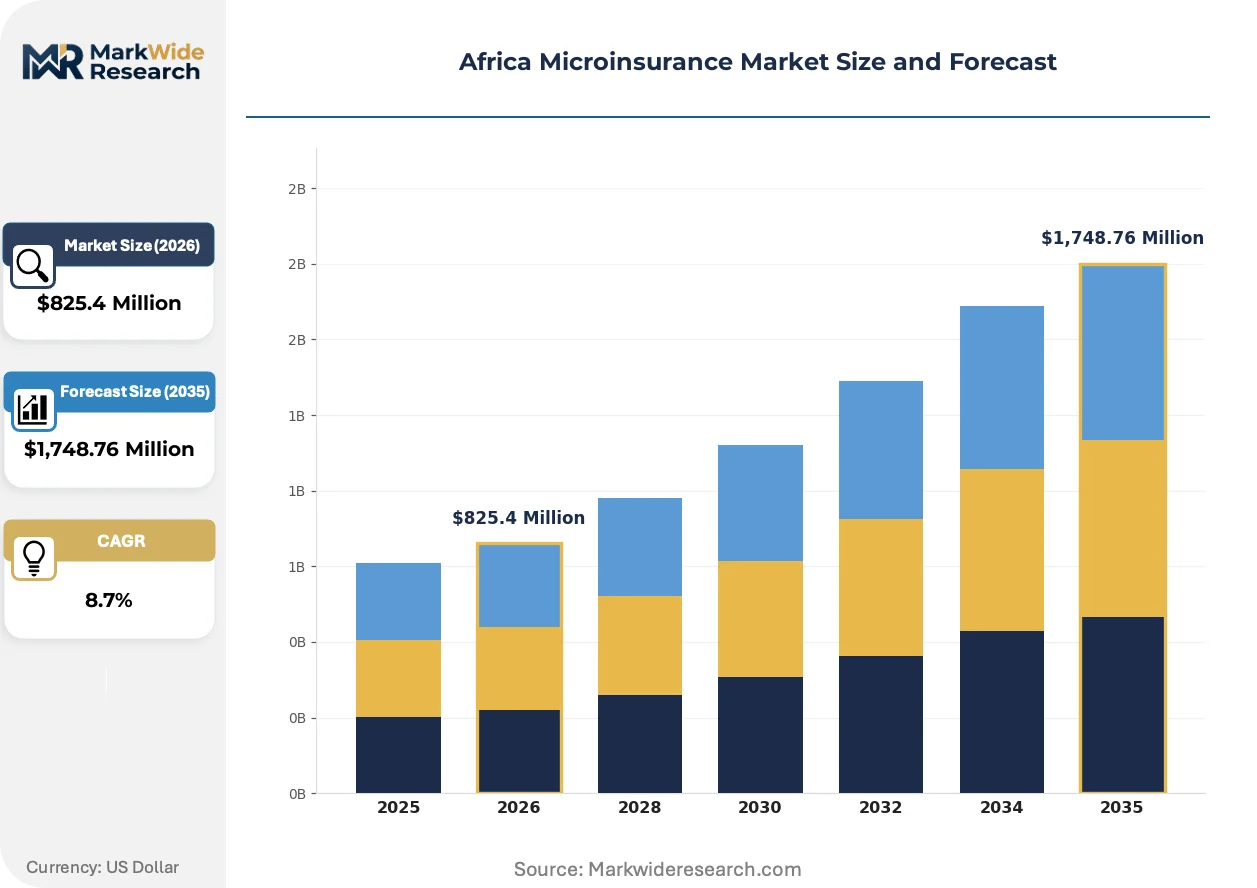
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,748.76 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health Insurance, Life Insurance, Agricultural Insurance, Property Insurance Delivery Model: Direct Sales, Mobile Platforms, Community-based, Broker Distribution Customer Type: Low-Income Households, Informal Workers, Smallholder Farmers, Micro-entrepreneurs Coverage Type: Accidental Death, Crop Failure, Hospitalization, Asset Loss |
| Companies Covered | Discovery Limited, Samb’a Assurances, Sanlam Group, Lumkani, Naa Sika, Old Mutual Limited, Jubilee Holdings, Democrance, Santam Limited, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Microinsurance Market Strategic Shifts & Innovations
Digital distribution architectures are displacing traditional agent hierarchies while regulatory sandboxes accelerate product experimentation. Insurers now compete on data acquisition speed rather than branch density.
Artificial intelligence is integrating into claims assessment workflows across health and agricultural lines. Insurers in Kenya and Nigeria deploy computer vision for crop damage verification and natural language processing for hospital bill validation. This compression of settlement timelines from weeks to hours is integrating mobile-first insurers into customer financial routines previously dominated by informal lenders.
Kenya's Insurance Regulatory Authority introduced a dedicated microinsurance licensing tier with reduced capital requirements and streamlined product filing. The framework permits parametric products without traditional claims investigation. Agricultural and health segments have mobilized fastest under these rules, with index-based drought coverage now dominating crop portfolios.
Smallholder farmers increasingly demand bundled protection combining health, life, and asset coverage into single premium payments deducted at harvest. Cooperatives and aggregators in Ghana and Tanzania are consolidating this demand, replacing individual policy sales with group enrollment negotiated at commodity collection points. This channel compression rewards insurers with existing agricultural supply chain relationships.
Africa Microinsurance Market Segmentation
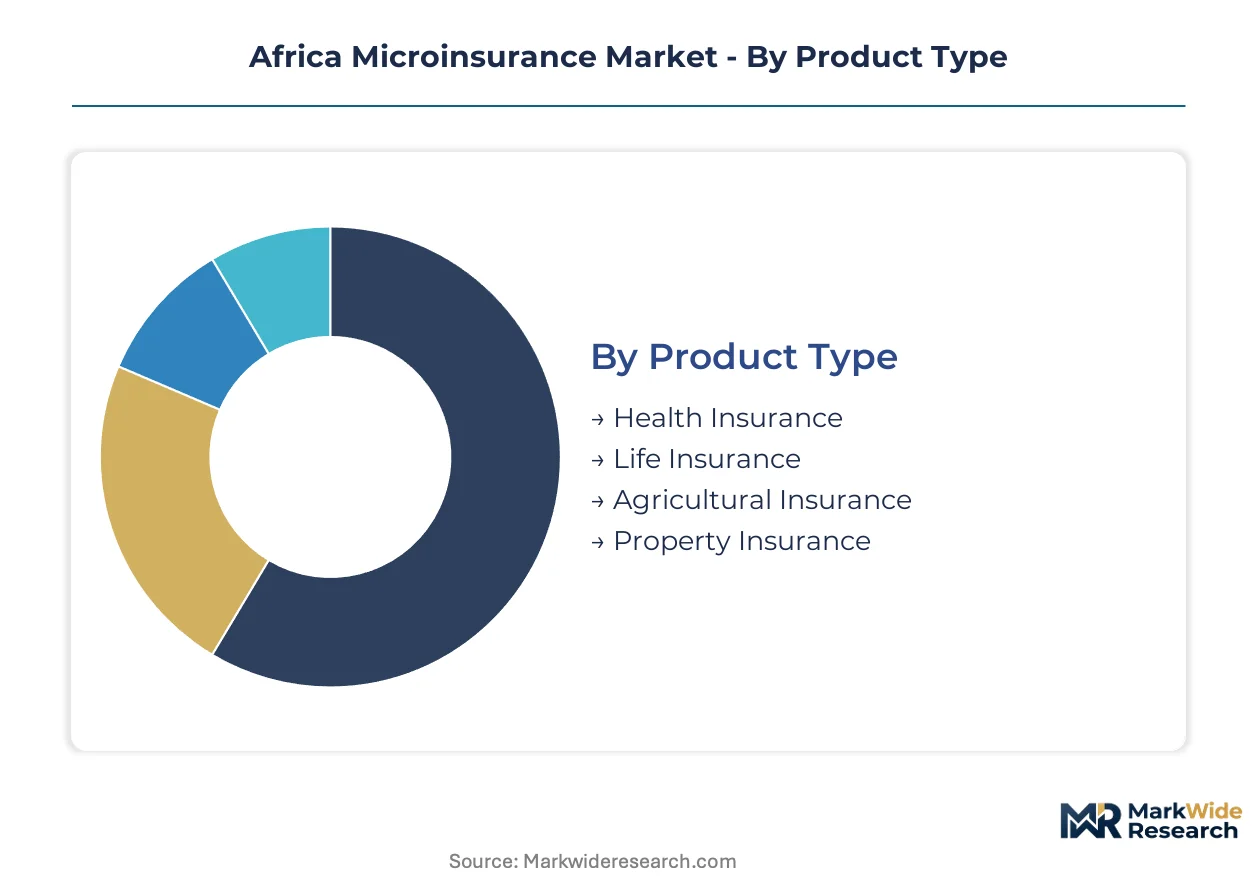
Microinsurance segmentation in Africa reveals distinct risk-pooling architectures where product design, distribution mechanics, and beneficiary economics interlock. Each dimension shapes premium affordability thresholds and claims settlement velocity for low-income populations.
Product Type:
Standalone health products operate independently of other financial services, while agricultural and life coverage increasingly embed within broader rural finance ecosystems.
- Health Insurance:Outpatient and inpatient coverage for informal workers with premium collection via mobile money deductions. Demand concentrates in Kenya and Nigeria where hospital cash benefits address persistent out-of-pocket medical expenditure burdens among urban informal settlements.
- Agricultural Insurance:Index-based weather and livestock mortality products using satellite rainfall data and blockchain-verified ear tags. Smallholder farmers in Ghana's northern regions and Tanzania's maize belts drive uptake where cooperatives aggregate enrollment at commodity collection points.
- Life Insurance:Term coverage with simplified underwriting through group enrollment at workplaces or burial societies. Funeral benefit riders dominate premium flows in Southern African markets.
- Property Insurance:Fire and theft protection for micro-enterprise inventory and dwelling structures. Mobile-enabled rapid claims assessment using photographic evidence expands reach in peri-urban Nigeria.
Health Insurance leads volumes today; Agricultural Insurance is gaining share fastest.
Delivery Model:
Channel economics vary sharply between high-touch community networks and zero-touch digital rails, with cost-to-serve ratios spanning an order of magnitude across the spectrum.
- Mobile Platforms:USSD and smartphone applications enabling instant enrollment, premium deduction, and claims disbursement through integrated mobile money wallets. M-Pesa interoperability in Kenya and MTN Mobile Money in Ghana compress distribution costs to sub-dollar per policy economics.
- Community-based:Aggregated enrollment through cooperatives, faith groups, and village savings associations with peer verification replacing individual underwriting. Tanzania's agricultural cooperatives and South African stokvels anchor this channel's premium volumes.
- Direct Sales:Agent-led face-to-face solicitation with paper-based application processes persisting in regulatory environments with strict physical documentation requirements.
- Broker Distribution:Intermediary access to formal sector employee benefits and microfinance institution portfolios, concentrated in South Africa's regulated advisory market.
Mobile Platforms command the steepest expansion trajectory; Community-based channels retain deepest rural penetration.
Customer Type:
Risk profiles and premium capacity diverge materially across beneficiary segments, with agricultural livelihoods exhibiting correlated systemic exposure distinct from urban informal employment patterns.
- Smallholder Farmers:Rain-fed crop and livestock producers with seasonal income concentration requiring harvest-timed premium collection and parametric triggers for drought or flood events. Ethiopia's unbanked agricultural workforce and Sahel millet growers represent concentrated addressable pools.
- Informal Workers:Urban construction, transportation, and trade workers without employer-sponsored coverage. Kenya's boda-boda associations and Nigeria's market trader collectives enable group-rated accident and health products.
- Low-Income Households:Subsistence-level families prioritizing hospital cash and funeral benefits over asset protection, with premium thresholds capped below five percent of monthly expenditure.
- Micro-entrepreneurs:Small shop owners and service providers seeking business interruption and inventory coverage, typically accessing products through microfinance institution bundling.
Smallholder Farmers generate the largest premium pool; Informal Workers show the fastest enrollment velocity.
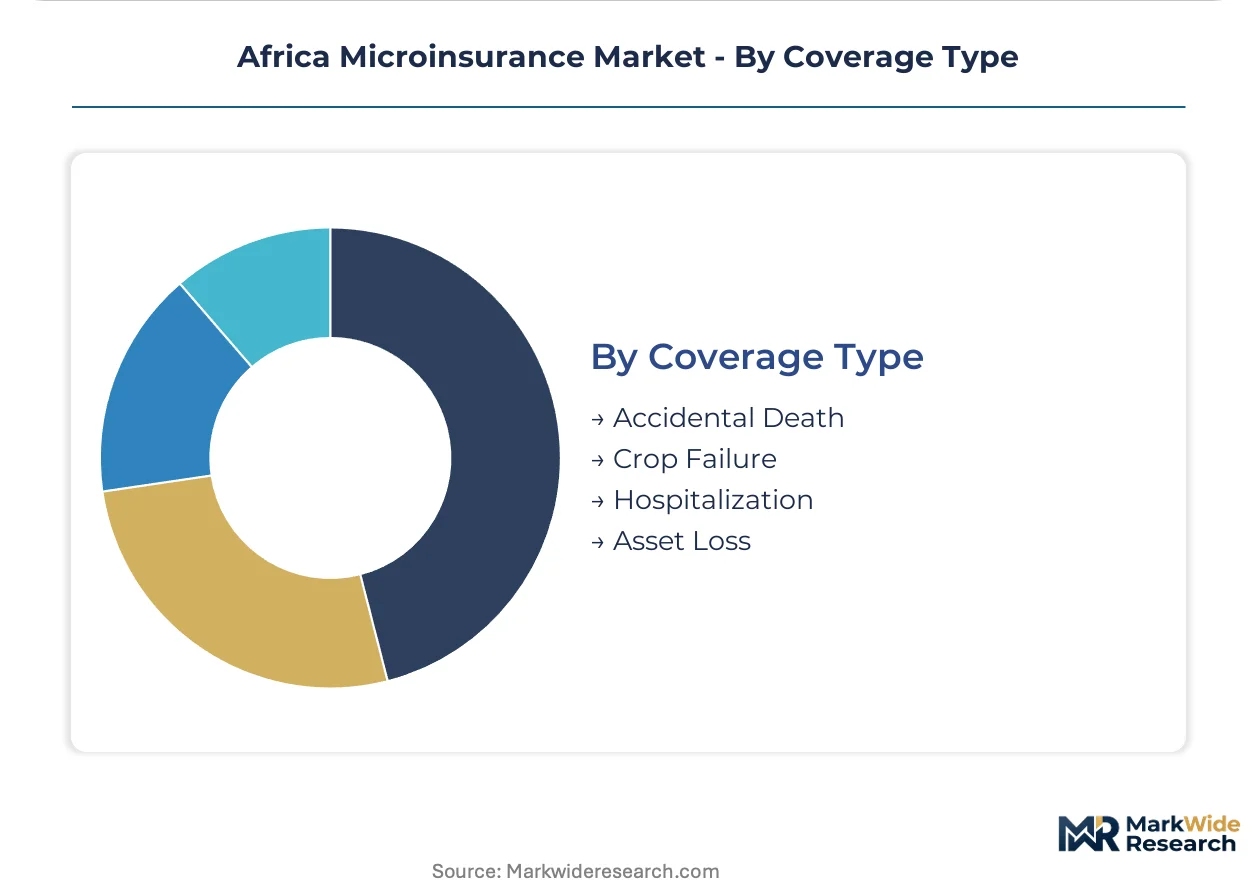
Coverage Type:
Benefit structures align with acute liquidity needs rather than indemnity principles, emphasizing rapid cash disbursement over precise loss verification.
- Hospitalization:Fixed daily cash benefits during inpatient stays, bypassing complex medical billing reconciliation. Kenya's NHIF complementary products and Ghana's private hospital networks anchor demand.
- Crop Failure:Parametric payouts triggered by satellite-derived rainfall indices or area yield shortfalls, eliminating field loss assessment. Drought coverage dominates portfolios across East and Southern African maize belts.
- Accidental Death:Lump-sum benefits for traffic and occupational fatalities with simplified beneficiary verification through mobile-registered next-of-kin. Motorcycle taxi operator associations in Kampala and Lagos drive volumes.
- Asset Loss:Fire, theft, and natural disaster protection for dwelling structures and productive equipment, with claims settlement via mobile money enabling rapid replacement purchasing.
Hospitalization coverage holds the largest installed base; Crop Failure products are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kenya's mobile money corridor anchors premium collection infrastructure across East Africa, with interoperability protocols now extending into neighboring markets. Ghana and Nigeria drive West African expansion through telecom-integrated distribution. Southern Africa retains the deepest regulatory sophistication, while Ethiopia's liberalizing financial sector presents untapped agricultural demand pools.
Kenya
M-Pesa rails enable instant premium deductions and claims disbursement for over 15 million registered users, compressing distribution costs to sub-dollar economics. The Insurance Regulatory Authority's sandbox licensing tier accelerates product approvals for parametric drought coverage. Nairobi's digital health ecosystem clusters mobile-first insurers targeting informal settlements with hospital cash benefits.
Ghana
MTN Mobile Money interoperability with AirtelTigo and Vodafone Cash expands rural premium collection reach across the northern agricultural belts. The National Insurance Commission's microinsurance framework mandates simplified disclosures and caps administrative loadings at 20 percent. Kumasi's maize cooperatives aggregate smallholder enrollment for index-based weather products at commodity collection points.
Nigeria
Lagos and Kano anchor demand for boda-boda operator accident coverage and market trader health products through association-based group enrollment. The National Insurance Commission's tiered capital requirements distinguish microinsurers from conventional operators. Smartphone penetration gaps in rural regions constrain product interfaces to USSD and SMS rails.
South Africa
Johannesburg and Cape Town concentrate formal sector microinsurance distribution through payroll deduction and stokvel partnerships. The Financial Sector Conduct Authority enforces strict conduct standards and claims handling timelines. Funeral benefit riders dominate premium flows, with community-based burial societies serving as the deepest penetration channel.
Ethiopia
The unbanked agricultural workforce in Oromia and Amhara regions presents first-mover opportunity for embedded crop and livestock products. Telecom liberalization and banking sector opening enable mobile money infrastructure deployment. Index-based parametric structures bypass traditional claims verification constraints in regions with sparse agent networks.
Africa Microinsurance Market Key Industry Players
Global insurance majors compete with regional champions across digital distribution capabilities and agricultural supply chain access. Market structure exhibits moderate consolidation, with pan-African financial services groups holding scale advantages in multiple jurisdictions while specialized microinsurance platforms capture niche segments. Three archetypes dominate: mobile-first digital insurers leveraging telecom partnerships, incumbent composite insurers with community-based agent networks, and technology enablers providing white-label platform infrastructure. Competitive intensity centers on M&A activity targeting agricultural data capabilities and strategic partnerships with mobile money operators.
Among South Africa-based financial services groups, Discovery Limited and Sanlam Group exemplify divergent strategic positions. Discovery anchors its approach through digital health ecosystem integration, while Sanlam maintains density through community-based delivery partnerships across Southern Africa. Kenya's Jubilee Holdings occupies a position within the agricultural specialization tier, with index-based weather products tied to smallholder farmer cooperatives. Technology platform providers including Democrance and Lumkani represent the infrastructure-enabling archetype, supplying API connectivity and parametric claims engines to licensed underwriters.
| Leading Market Players |
|---|
| Discovery Limited |
| Samb'a Assurances |
| Sanlam Group |
| Lumkani |
| Naa Sika |
| Old Mutual Limited |
| Jubilee Holdings |
| Democrance |
| Santam Limited |
| Others |
Cost & Logistics Intelligence
Telecom-backed mobile money operators anchor premium collection infrastructure across East and West Africa, compressing distribution economics while enforcing disciplined pricing through platform fee structures that insurers absorb or pass through.
Pricing Analysis
Mobile network operator commissions and biometric verification costs pass through to premium loadings, with platform fees consuming fifteen to twenty percent of collected premiums in Kenya and Ghana. Three-tier pricing structure across premium, standard, and economy levels separates comprehensive health bundles from basic hospital cash and catastrophic-only coverage. Pricing pressure stems from MNO commission renegotiations and agent float financing requirements. Low-income households exhibit acute price sensitivity, while agricultural cooperatives negotiate volume-rated group premiums with reduced per-member acquisition costs.
Supply Chain Analysis
Reverse logistics for policy documentation and claims evidence flows through mobile-enabled field agents who digitize paper records at rural collection points, compressing settlement timelines. Core platform development concentrates in South Africa, Kenya, and Nigeria, with satellite rainfall data services drawing from European and North American meteorological agencies. Supply chain risk centers on single-source mobile money platform dependency where M-Pesa or MTN rails dominate national markets. Distribution runs through telecom-integrated APIs, cooperative aggregators, and microfinance institution partnerships in descending volume share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa microinsurance market compounds steadily as mobile money penetration deepens informal economy financial inclusion, creating embedded distribution channels with near-zero marginal acquisition costs.
For Market Incumbents: Acquire parametric claims data capabilities and satellite-derived agricultural risk models to defend against insurtech platforms leveraging AI-based crop assessment. Reinforce agent network liquidity through pre-positioned mobile money float arrangements. Prioritize backward integration into cooperative aggregator relationships to lock out competitor access at commodity collection points. For New Entrants and Emerging Players: Kenya's Insurance Regulatory Authority sandbox licensing opens a window for embedded health-microcredit bundling at digital lending platforms. Ethiopia's liberalizing telecom and banking sectors present first-mover terrain for index-based livestock products. Target agricultural cooperatives in Tanzania's maize belts through white-label platform partnerships with established underwriters. For Investors and Strategic Acquirers: Valuations sit cheapest among technology enablers supplying API connectivity and parametric engines to licensed carriers rather than full-stack insurers. Long-term viability hinges on data network effects in agricultural risk pricing. Monitor MNO commission structure renegotiations as the inflection signal for distribution economics compression.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Licensing | Kenya's sandbox framework accelerates drought coverage approvals without traditional claims investigation. |
| Mobile Money API Integration | M-Pesa interoperability protocols reduce premium collection costs to sub-dollar economics across rural populations. |
| Agricultural Cooperative Partnerships | Ghana's maize belt aggregators consolidate smallholder demand at harvest-timed enrollment points. |
| Biometric Verification Deployment | Ghost policy fraud detection preserves thin margins through mobile-registered identity validation. |
| Index-Based Data Licensing | Satellite rainfall providers enable parametric triggers eliminating costly field loss assessment. |
Research Approach
Bottom-up mobile platform enrollment modeling reconciled against top-down premium flow tracking forms the analytical core of this study. Primary interviews with microinsurance product managers, mobile money platform executives, agricultural cooperative leaders, and national insurance regulatory officials informed demand segmentation and distribution economics. Secondary validation drew from African Insurance Organisation harmonization frameworks, national regulatory sandbox filings, mobile network operator financial disclosures, and satellite data provider partnership announcements.
Historical trendline analysis across mobile penetration curves, agricultural commodity price cycles, and regulatory licensing velocity established baseline growth parameters. The analytical framework models product type, delivery channel, customer segment, and coverage structure dimensions across the projection horizon. CAGRs derive from enrollment velocity trajectories indexed to MNO subscriber growth and cooperative aggregation expansion, with climate volatility frequency and mobile money interoperability milestones serving as scenario-weighting inputs.
Revisions become necessary when MNO commission structures shift materially, national microinsurance frameworks diverge from harmonized standards, or correlated weather shocks trigger systemic reinsurance capacity constraints. Practitioners should monitor regulatory sandbox expansion timelines and satellite data provider pricing negotiations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Agriculture Reinsurance Market
Insurance
Global Sports Insurance Market
Insurance
MENA Health and Medical Insurance Market
Insurance
Art Insurance Market
Insurance
AI in Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
UK Electronic Gadgets Insurance Market
Insurance
Usage-Based Insurance (UBI) Market
Insurance
US Travel Insurance Market
Insurance
Green Insurance Market
Insurance
Workers Compensation Insurance Market
Insurance
UK Commercial Insurance Market
Insurance
Peru Insurance Market
Insurance
Reinsurance Carriers Market
Insurance
Spain Group Health Insurance Market
Insurance
Specialty Insurance Market