
 Middle East Business Income Insurance Market | 2026-2036
Middle East Business Income Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Business Income Insurance Market Analytics
A capital-intensity divergence between legacy reinsurers and digital-first carriers is reorganizing competitive dynamics across the Middle East Business Income Insurance Market. Saudi Re leverages its treaty capacity and sovereign-linked balance sheet to anchor large infrastructure placements. GIG Gulf competes through localized underwriting platforms spanning Bahrain, Kuwait, and the UAE. Abu Dhabi National Insurance Company differentiates via bancassurance distribution and state-backed commercial relationships.
Business income insurance indemnifies policyholders against net income loss and continuing operating expenses when covered perils interrupt normal commercial operations, typically requiring proof of direct physical damage to insured property as a triggering condition. The product generates technical complexity around indemnity period calculations, coinsurance clauses, and ordinary payroll continuation endorsements that demand specialized actuarial capability. Comprehensive Coverage leads product type segmentation due to bundled peril protection preferred by multinational subsidiaries operating across Gulf jurisdictions. Small Enterprises represent the fastest-growing end user category as regulatory mandates and supply chain finance requirements push micro-businesses toward formal risk transfer. Brokers dominate distribution channels, though online platforms are gaining share among standardized SME placements.
Saudi Arabia's SAMR enforces solvency and consumer protection standards that elevate capital requirements for commercial lines writers. The UAE's central bank and Insurance Authority coordinate on fit-and-proper assessments for licensed carriers offering business interruption extensions. Stakeholders must monitor how Gulf regulators harmonize catastrophe reserve rules and whether climate risk disclosures reshape underwriting appetite for natural peril-linked income coverage.
Market Dynamics
Stricter commercial risk disclosure mandates from Saudi Arabia's SAMR are forcing Gulf carriers to rebuild capital reserves and underwriting infrastructure around business interruption exposures. This regulatory compression is accelerating market entry barriers while concentrating placement capacity among sovereign-linked balance sheets.
Growth Catalysts
- SAMR Solvency Frameworks:Saudi Arabia's capital adequacy rules push mid-market enterprises toward formal business income coverage, expanding the addressable policyholder base.
- Construction-led Demand:Mega-project pipelines across the Gulf Cooperation Council generate concentrated contractor exposure to delay and disruption risks.
- Parametric Triggers:Index-based settlement mechanisms for natural catastrophe income loss are gaining traction among energy and logistics operators seeking faster indemnity.
Market Restraints
- Reinsurance Capacity Concentration:Treaty renewal pricing volatility in Lloyd's and Bermuda markets directly pressures Gulf carriers' net retention limits.
- Physical Damage Trigger Requirement:Traditional business income policies exclude non-damage business interruption, leaving pandemic and cyber income gaps uninsured.
- Actuarial Talent Scarcity:Specialized capability in indemnity period modeling and coinsurance clause construction remains concentrated in London and Zurich.
Strategic Opportunities
- Oman and Bahrain Penetration:Underdeveloped broker networks and lower policy density create first-mover advantages for digital distribution platforms.
- Supply Chain Finance Integration:Lender-mandated business interruption coverage is embedding insurance into trade credit facilities for SME importers.
- Climate Risk Disclosures:Emerging regulatory pressure on listed entities to report natural peril exposure is driving voluntary income protection purchases.
Industry Challenges
- Legacy System Integration:Incumbent carriers struggle to embed parametric triggers into policy administration platforms built on physical damage frameworks.
- Claims Verification Timelines:Proving net income loss requires forensic accounting that stretches indemnity settlement cycles and erodes policyholder retention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Business Income Insurance Market |
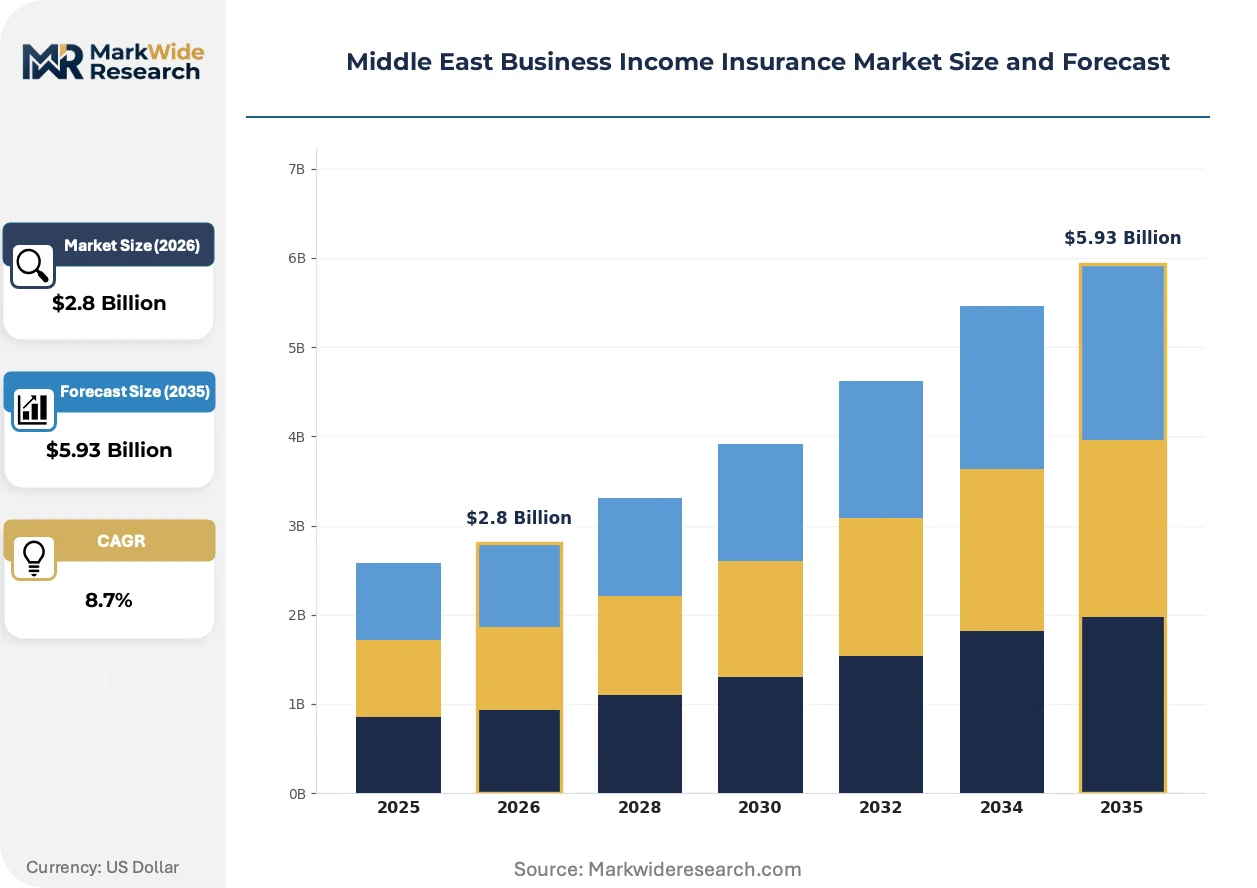
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Comprehensive Coverage, Named Perils, Business Interruption, Extended Indemnity End User: Small Enterprises, Large Corporations, Non-Profit Organizations, Government Agencies Coverage Type: Property Damage, Loss of Revenue, Additional Expenses, Rental Income Distribution Channel: Brokers, Direct Sales, Online Platforms, Agents |
| Companies Covered | Saudi Re, GIG Gulf, Abu Dhabi National Insurance Company, Sukoon Insurance, Tawuniya, Bupa Arabia for Cooperative Insurance, Orient Insurance PJSC, MedGulf, Al Rajhi Company for Cooperative Insurance, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Business Income Insurance Market Evolving Landscape
Digital distribution platforms and algorithmic underwriting are compressing placement cycles while regulatory harmonization pressures reshape product standardization across Gulf jurisdictions.
Parametric business income triggers tied to wind speed, flood depth, and seismic intensity sensors are supplanting traditional loss-adjustment methodologies for natural catastrophe exposures. Energy contractors and port operators are adopting these instruments to secure 72-hour settlement timelines. This shift is compressing demand for conventional adjuster-deployed claims processes in high-frequency peril zones.
Saudi SAMR's commercial risk disclosure rules now mandate granular reporting of business interruption concentrations by peril type and geographic exposure. Carriers must file supplementary capital charges for unmodeled catastrophe aggregations. Large infrastructure placements are restructuring into layered programs with separate parametric and indemnity towers to satisfy these requirements.
Multinational subsidiaries are consolidating insurance procurement through regional captive structures domiciled in Dubai International Financial Centre. This concentration is disintermediating local broker relationships and forcing domestic carriers to compete on fronting fees rather than risk-bearing capacity. The shift is most visible among European and Asian manufacturing affiliates with centralized regional risk management functions.
Middle East Business Income Insurance Market Segmentation
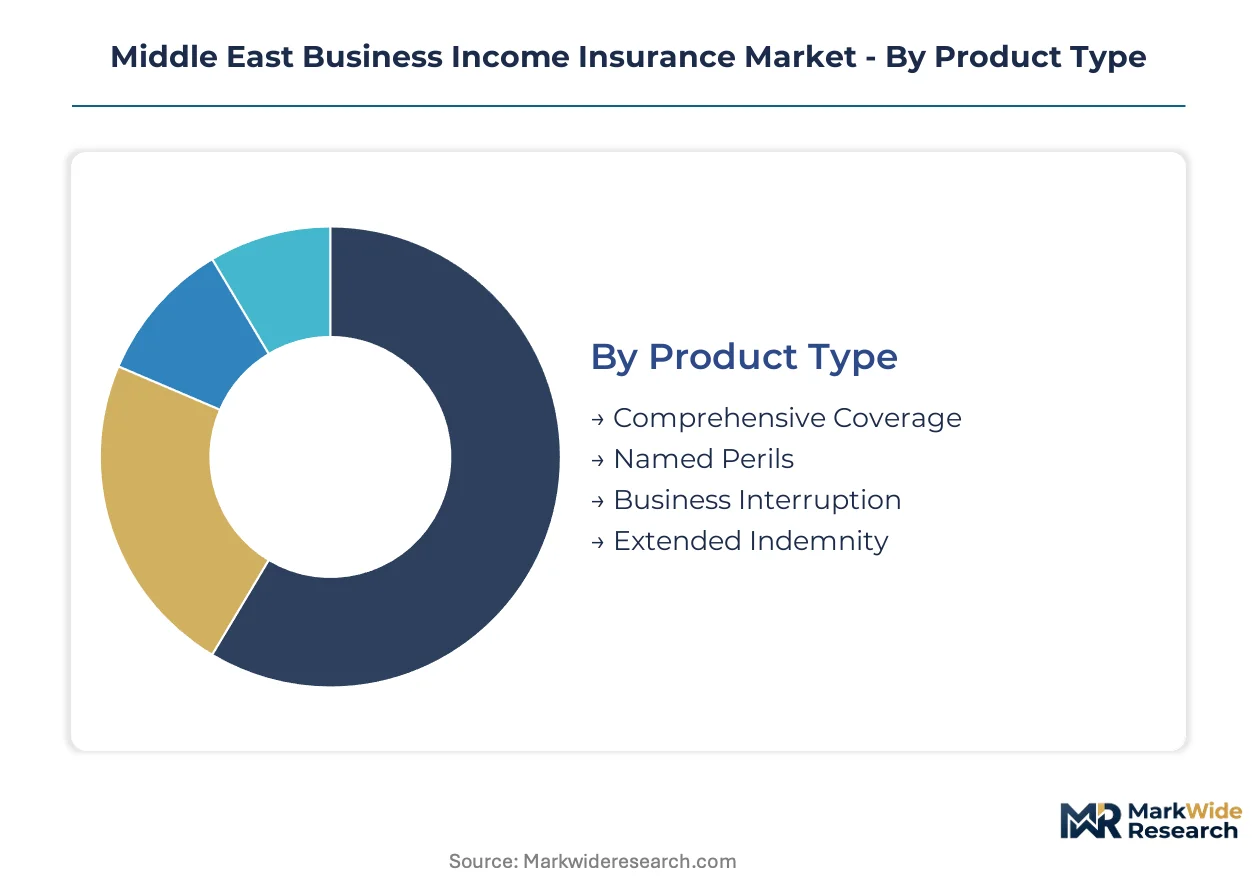
Business income insurance segmentation in the Middle East reflects divergent risk appetites between sovereign-linked infrastructure programs and fragmented SME populations. Product architecture varies sharply across these divides, with parametric triggers gaining traction in energy and logistics while traditional indemnity structures dominate retail commercial lines.
Product Type:
Substitution pressure concentrates on Named Perils policies as parametric instruments and captive alternatives displace conventional indemnity structures among large Gulf contractors.
- Comprehensive Coverage:Bundled peril protection combining property damage, business interruption, and contingent liability extensions under single policy forms. Multinational subsidiaries operating across Saudi Arabia, UAE, and Qatar prefer this structure to streamline compliance with divergent SAMR and UAE Insurance Authority capital requirements.
- Named Perils:Specified-risk contracts covering fire, explosion, and machinery breakdown only. Mid-market manufacturing affiliates in Dubai's Jebel Ali corridor select these policies to reduce premium outlays while satisfying lender-mandated coverage minimums.
- Business Interruption:Standalone income protection requiring direct physical damage triggers. Saudi construction contractors deploy this coverage against delay risks in NEOM and Red Sea Project developments.
- Extended Indemnity:Prolonged indemnity period endorsements stretching beyond standard 12-month limits. Port operators in Abu Dhabi Khalifa Industrial Zone adopt these extensions to cover extended supply chain recovery timelines.
Comprehensive Coverage anchors the volume base while Extended Indemnity gains share at the steepest rate.
End User:
Cost tier stratification separates state-backed mega-projects from premium-sensitive micro-businesses, with divergent distribution economics shaping carrier resource allocation.
- Small Enterprises:Micro-businesses with annual revenues below SAR 50 million or AED equivalent. SAMR's commercial risk disclosure mandates and supply chain finance requirements are pushing Dubai trading houses and Riyadh retail operators toward formal coverage.
- Large Corporations:Multinational affiliates and sovereign-linked entities with centralized risk management functions. These buyers consolidate procurement through DIFC-domiciled captives, compressing fronting fee margins for domestic carriers.
- Non-Profit Organizations:Charitable foundations and educational institutions with limited risk management staff. Coverage purchases concentrate in Abu Dhabi and Riyadh where donor governance requirements mandate insurance verification.
- Government Agencies:State ministries and municipal authorities self-insuring through sovereign reserves. SAMR's solvency frameworks are forcing some entities toward external risk transfer for catastrophe aggregations.
Large Corporations dominate premium volumes while Small Enterprises expand most quickly.
Coverage Type:
Application-specific triggers differentiate energy contractor programs from retail commercial policies, with natural peril linkage driving the steepest pricing divergence.
- Property Damage:Physical asset protection forming the foundational trigger for traditional business income indemnity. Saudi petrochemical facilities and UAE aluminum smelters maintain substantial placements against fire and machinery breakdown.
- Loss of Revenue:Net income indemnification covering gross profit shortfalls during operational suspension. Logistics operators in Dubai's Al Maktoum Airport corridor prioritize this coverage given high fixed cost structures.
- Additional Expenses:Extra cost reimbursement for temporary relocation, expedited shipping, and emergency contractor engagement. Port operators facing Red Sea shipping disruptions are expanding these endorsements.
- Rental Income:Commercial landlord protection against tenant default and lease interruption. Dubai property developers with hospitality and retail exposure maintain concentrated placements.
Property Damage retains the largest placement base while Loss of Revenue climbs the fastest.
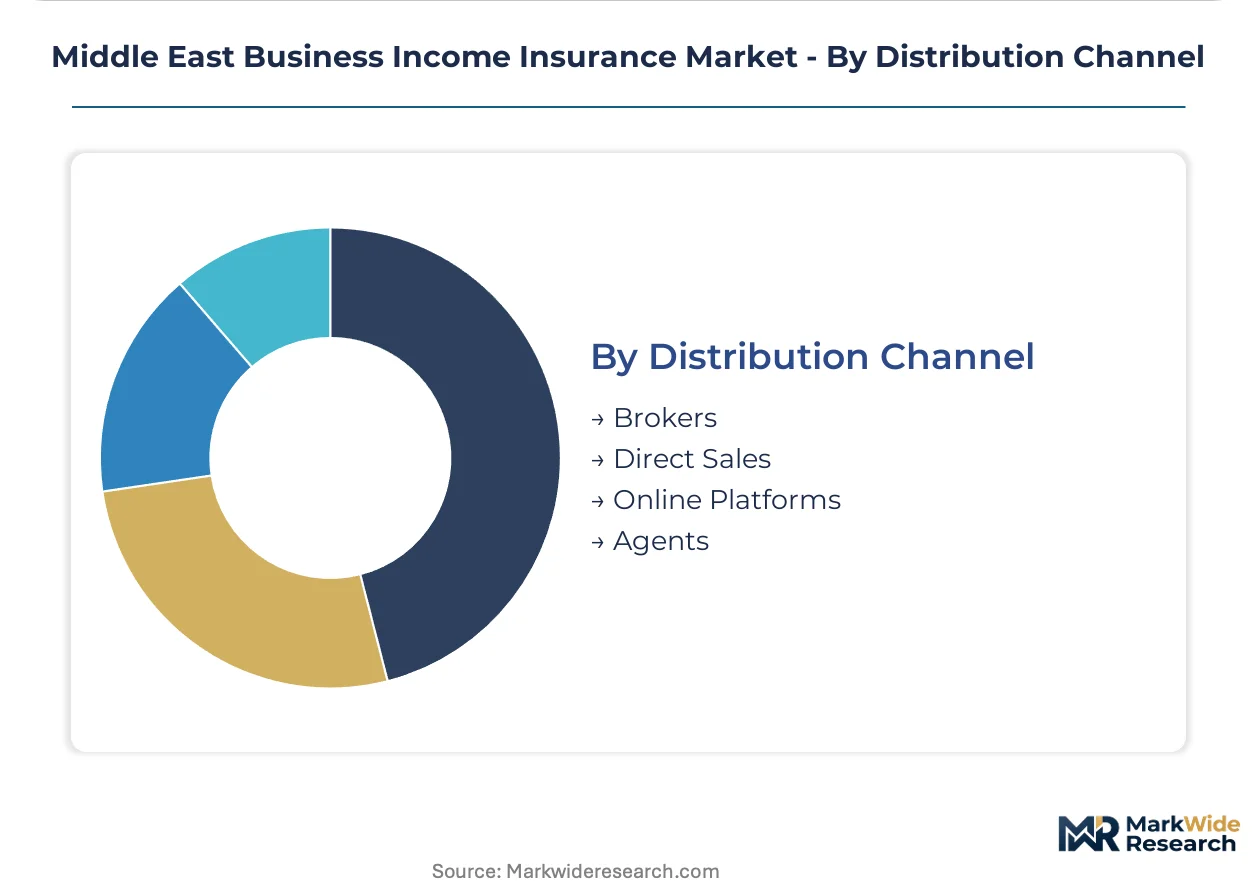
Distribution Channel:
Customer type fragmentation between sophisticated risk managers and coverage-naive micro-businesses is reorganizing channel economics across the Gulf.
- Brokers:Independent intermediaries and international networks placing complex infrastructure risks. Marsh, Aon, and Willis Towers Watson dominate large contractor placements across Saudi Arabia and UAE.
- Direct Sales:Carrier-employed account executives targeting sovereign-linked entities and DIFC captive managers. Saudi Re and ADNIC maintain dedicated corporate teams for direct negotiation.
- Online Platforms:Digital portals offering standardized SME quotations with algorithmic underwriting. GIG Gulf and Tawuniya are expanding these capabilities for small enterprise segments.
- Agents:Tied representatives distributing through bancassurance and automotive dealer networks. ADNIC leverages state-backed banking relationships for commercial lines penetration.
Brokers command the premium volume while Online Platforms achieve the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across Gulf markets. Saudi buyers absorb premium increases driven by SAMR solvency mandates, while UAE micro-enterprises in Dubai's trading corridors remain highly sensitive to rate fluctuations.
United Arab Emirates
Dubai's Jebel Ali logistics cluster and Abu Dhabi's Khalifa Industrial Zone generate concentrated business interruption exposure for port operators and aluminum smelters. The UAE Insurance Authority coordinates with the central bank on fit-and-proper assessments for carriers offering income protection extensions. Dubai International Financial Centre hosts expanding captive formations as European and Asian multinationals consolidate regional risk management functions.
Saudi Arabia
NEOM and Red Sea Project developments create contractor demand for delay and disruption coverage against extended indemnity periods. SAMR enforces stricter commercial risk disclosure rules that elevate capital charges for unmodeled catastrophe aggregations. Riyadh-based energy contractors are restructuring programs into layered towers combining parametric and traditional indemnity structures.
Kuwait
Petrochemical facilities and downstream oil operations maintain substantial property damage-triggered income protection placements. The country's national insurance regulator monitors solvency ratios for commercial lines writers serving state-linked energy entities. Kuwait City-based trading houses face emerging pressure from supply chain finance requirements to formalize coverage.
Bahrain
Underdeveloped broker networks and lower policy density create whitespace for digital distribution platforms targeting SME importers. The central bank's insurance supervision unit oversees licensing for carriers offering standardized business interruption products. Manama's financial services cluster sees tentative captive formation activity as regional risk managers test alternative domiciles.
Qatar
LNG expansion projects and associated contractor ecosystems generate demand for complex delay risk transfer. The Qatar Financial Centre Regulatory Authority governs captive structures and commercial lines capital adequacy. Doha's industrial zone concentrations in Ras Laffan sustain specialized underwriting platforms for energy-linked income exposure.
Middle East Business Income Insurance Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Middle East Business Income Insurance Market. Sovereign-linked carriers with treaty capacity and state-backed balance sheets anchor large infrastructure placements across Saudi Arabia and the UAE. Specialist national insurers compete through localized underwriting platforms and bancassurance distribution. The dominant competitive moves involve geographic platform expansion and parametric product development to capture construction-led demand.
Within the sovereign-linked tier, Saudi Re and Abu Dhabi National Insurance Company exemplify carriers leveraging state-affiliated relationships and capital reserves to secure mega-project placements. GIG Gulf occupies a position among the regional specialist platforms spanning multiple Gulf Cooperation Council jurisdictions. These three entities represent contrasting archetypes: treaty-capacity sovereign anchor, bancassurance-integrated national carrier, and multi-territory underwriting specialist.
| Leading Market Players |
|---|
| Saudi Re |
| GIG Gulf |
| Abu Dhabi National Insurance Company |
| Sukoon Insurance |
| Tawuniya |
| Bupa Arabia for Cooperative Insurance |
| Orient Insurance PJSC |
| MedGulf |
| Al Rajhi Company for Cooperative Insurance |
| Others |
Value Network & Pricing Analysis
Parametric trigger substitution for traditional indemnity structures simultaneously redraws supply geography toward Lloyd's and Bermuda capacity providers while compressing pricing economics for Gulf carriers dependent on treaty renewal cycles. This substitution dynamic forces domestic underwriters to absorb margin compression or cede large infrastructure placements to sovereign-linked balance sheets with direct reinsurance access.
Pricing Analysis
Extended indemnity endorsements and multi-year maintenance contracts generate lifetime value that exceeds initial premium capture by substantial multiples. Pricing stratifies across premium, standard, and economy tiers based on indemnity period length and claims service level agreements, with broker-negotiated infrastructure placements commanding substantial fee loads. Cost compression in SME digital channels is intensifying because algorithmic underwriting platforms eliminate placement labor. Micro-enterprises in Dubai's trading corridors exhibit acute price sensitivity, while NEOM contractors absorb rate increases driven by SAMR solvency mandates without volume reduction.
Supply Chain Analysis
Strait of Hormuz transit underwrites marine cargo accumulation risks that feed directly into business interruption pricing for port operators and energy logistics chains. Treaty capacity concentrates in Bermuda, London, and Zurich, with Gulf carriers drawing from these markets for catastrophe excess-of-loss protection. Reinsurance renewal volatility, raw material dependencies on specialty actuarial talent and catastrophe modeling software, and single-source vulnerability to Lloyd's market pricing cycles define structural risk. Distribution runs through international broker networks for large placements, while direct carrier platforms and bancassurance channels serve standardized SME segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
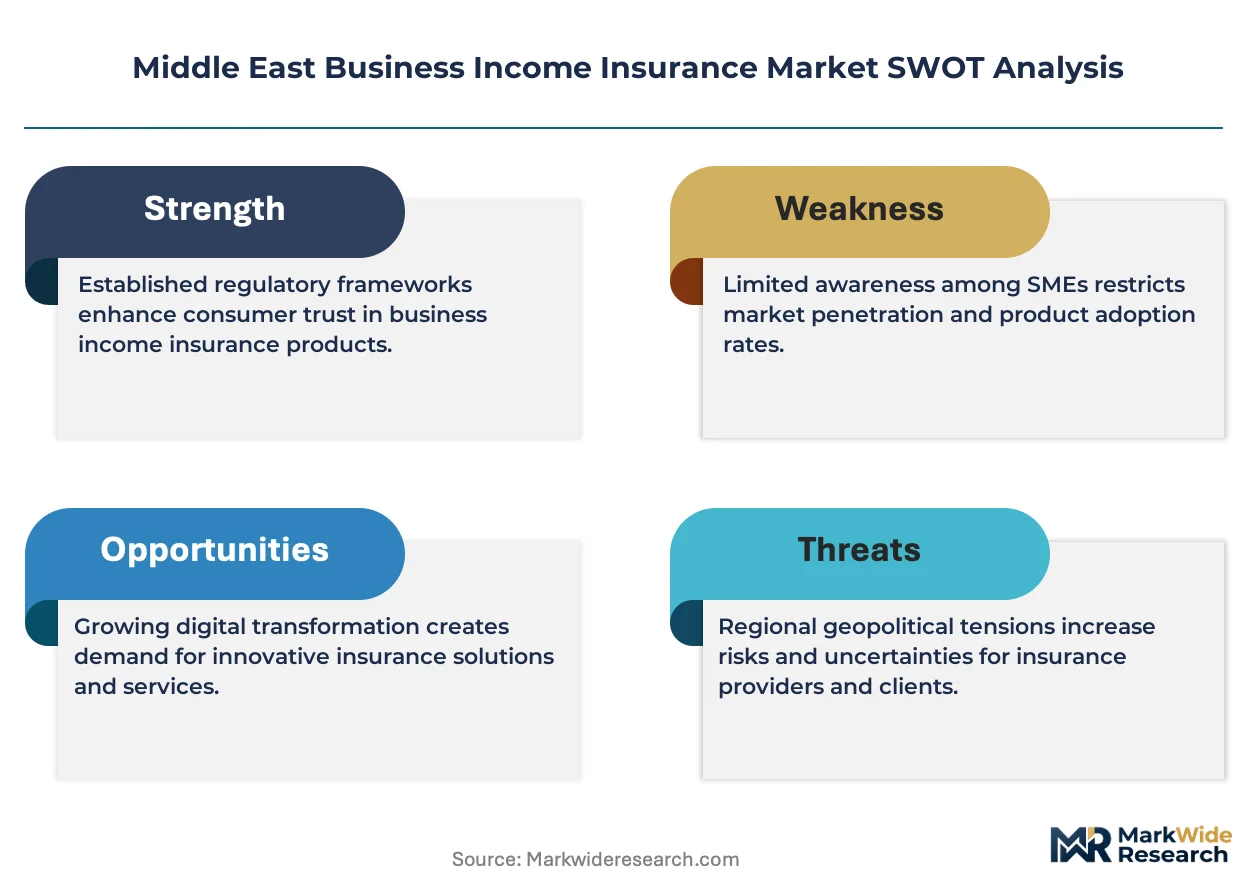
This market represents an early-cycle expansion story where regulatory mandates on commercial risk disclosure are accelerating formal coverage adoption among previously self-insured Gulf enterprises. SAMR solvency frameworks and supply chain finance requirements together expand the addressable policyholder base faster than organic demand growth alone.
For Market Incumbents: Shield treaty capacity relationships through multi-year reinsurance partnerships that lock in catastrophe excess-of-loss protection before renewal cycles harden further. Deepen vertical integration into parametric product development to capture construction-led demand before international carriers displace local risk-bearing capacity with index-based settlement instruments.
For New Entrants and Emerging Players: Lead with digital distribution platforms targeting Bahrain and Oman, where underdeveloped broker networks and lower policy density create whitespace for algorithmic underwriting at acquisition costs below incumbent expense ratios. White-space concentration in SME importers facing supply chain finance mandates offers the most penetrable entry vector.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional broker networks that have consolidated mid-market placements but lack captive management capabilities or parametric product infrastructure. Long-term viability hinges on underwriting platform scalability across multiple Gulf jurisdictions. The signal to watch is captive formation velocity at Dubai International Financial Centre, which indicates multinational risk management centralization that compresses fronting fee margins for domestic carriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Index-based triggers secure 72-hour settlement timelines for energy contractors at Khalifa Industrial Zone. |
| Captive Management Capability Buildout | DIFC-domiciled structures disintermediate local brokers and capture fronting fee revenue from multinational affiliates. |
| Digital Distribution Platform Expansion | Algorithmic underwriting compresses placement cycles for standardized SME coverage in Bahrain and Oman. |
| Treaty Capacity Partnership Structuring | Multi-year reinsurance agreements with Bermuda markets stabilize catastrophe excess-of-loss pricing volatility. |
| Bancassurance Channel Deepening | State-backed banking relationships embed business interruption coverage into supply chain finance facilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade credit facility documentation, and catastrophe modeling vendor disclosures to establish coverage penetration benchmarks and pricing elasticity parameters. Primary interviews with chief underwriting officers at Saudi Re and GIG Gulf, broker placement executives at Marsh and Aon, and risk managers at DIFC-domiciled captives provided ground-truth validation of parametric adoption rates and treaty renewal dynamics. Secondary sources included SAMR solvency disclosure filings, UAE Insurance Authority licensing records, Lloyd's market reports, and customs data on Gulf construction material imports. Bottom-up policy count estimates triangulate against top-down premium allocation from regulatory capital adequacy returns.
Segmentation dimensions modeled span product type, end user category, coverage trigger structure, and distribution channel across the analysis window. The analytical framework applies driver-based elasticity modeling to project premium volumes, with CAGRs derived from regulatory mandate implementation timelines and construction pipeline commitments. Industry-specific forecast inputs incorporate NEOM and Red Sea Project development schedules, SAMR commercial risk disclosure phase-in requirements, and parametric trigger adoption curves from energy contractor procurement patterns.
Underlying assumptions cover stable reinsurance capacity availability from Bermuda and London markets, with deviation risk concentrated in treaty renewal pricing volatility and catastrophe model revision shocks. Forecasts reflect these assumptions without contingency for sovereign reserve self-insurance reversals or pandemic-trigger non-damage business interruption regulatory mandates. Revision becomes warranted when Lloyd's market capacity contraction crosses thresholds that force Gulf carriers into punitive net retention positions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Digital Innovation in Insurance Market
Insurance
Digital Insurance Market
Insurance
Small Business Insurance Market
Insurance
Reinsurance Carriers Market
Insurance
Japan Bancassurance Market
Insurance
Europe Online Insurance Market
Insurance
Sri Lanka Cyber (Liability) Insurance Market
Insurance
MENA Health and Medical Insurance Market
Insurance
Europe EV Insurance Market
Insurance
Australia Parametric Insurance Market
Insurance
Asia-Pacific Group Health Insurance Market
Insurance
AI in Insurance Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
Business Insurance Market
Insurance
Reinsurance Market
Insurance
Estonia Property and Casualty Insurance Market