
 Aviation Insurance Market | 2026-2036
Aviation Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Insurance Market Intelligence
Capital-intensity divergence between legacy reinsurers and digital-native underwriters is collapsing as algorithmic pricing platforms compress underwriting cycles. Munich Re leverages its century-old aviation portfolio to sustain premium volume across catastrophic hull coverage. AIG Aerospace competes through specialized war-risk and lessor-protection products that dominate narrow-body fleet policies. Global Aerospace anchors its position in general aviation, where manual underwriting still commands pricing power.
Aviation insurance is a specialized risk-transfer mechanism covering physical damage to aircraft, third-party liability, and passenger injury, with policies typically structured around agreed-value hull limits and per-seat liability caps calibrated to ICAO standards. Its primary commercial purpose is enabling fleet financing and lessor confidence by absorbing catastrophic loss exposure that would otherwise ground capital deployment. Liability coverage leads premium pools as tort exposure from ground incidents and passenger claims widens under expanded jurisdiction rules, while hull insurance for commercial aircraft remains the most mature segment with thinning margins. Drone services under the market segment dimension represent the fastest-growing demand vector as underwriters develop parametric frameworks for beyond-visual-line-of-sight operations.
The FAA mandates minimum liability thresholds for Part 121 carriers, while EASA's drone-specific insurance requirements under EU Regulation 2019/947 reshape product standards for unmanned aerial system operators. The International Civil Aviation Organization's recommended practices on reinsurance pooling further constrain market access for undercapitalized national insurers. Stakeholders must monitor how climate attribution science recalibrates hull risk models before renewal cycles harden permanently.
Market Dynamics
Climate attribution science is recalibrating hull risk models as underwriters integrate real-time weather data into renewal pricing, compressing traditional annual cycles into continuous monitoring frameworks.
Growth Catalysts
- FAA Safety Directives:Updated Part 121 mandates expand liability minimums for commercial carriers, forcing fleet-wide policy upgrades that thicken premium pools.
- Drone Integration Frameworks:EASA's EU Regulation 2019/947 creates mandatory coverage categories for beyond-visual-line-of-sight operations, opening parametric product lines.
- Urban Air Mobility:Electric vertical take-off and landing operators in Dubai and Singapore are pre-purchuring hull coverage before certification, front-loading demand.
Market Restraints
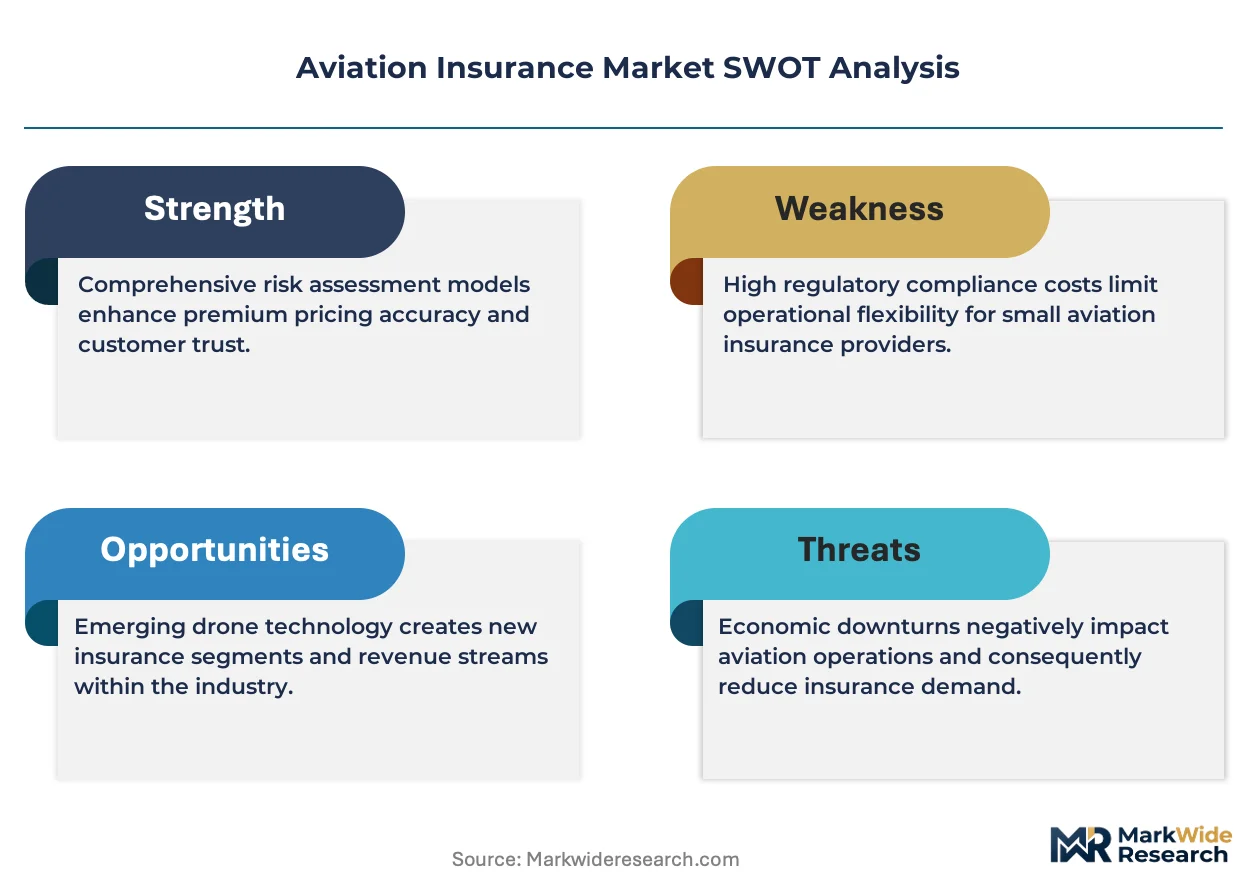
- Reinsurance Capacity Concentration:Catastrophic hull coverage depends on a narrow pool of London and Zurich-based reinsurers, creating single-point failure risk.
- Climate Model Opacity:Underwriters lack standardized methodologies for attributing extreme weather damage to specific flight operations, inflating capital reserves.
- Legacy IT Infrastructure:Established carriers operate on policy administration systems that cannot ingest real-time telemetry from connected aircraft.
Strategic Opportunities
- India's General Aviation Expansion:The Directorate General of Civil Aviation's relaxed charter regulations are spawning fixed-base operator networks without mature insurance penetration.
- Parametric Weather Products:Satellite-indexed policies that trigger automatic payouts for grounded fleets during volcanic ash events bypass claims adjustment delays.
- Lesser-Protected Cargo Routes:African and Central Asian air freight corridors operate with hull coverage gaps that specialized underwriters can fill.
Industry Challenges
- Actuarial Talent Scarcity:Aviation-specialized underwriters who understand both turbine engineering and tort law are retiring faster than training programs replace them.
- Cross-Border Claims Jurisdiction:The Montreal Convention's liability limits face challenges from US state courts applying forum non conveniens doctrines, complicating reserve calculations.
- Telematics Integration Costs:Retrofitting older aircraft with flight data monitoring hardware to satisfy usage-based pricing requirements demands capital that regional carriers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Insurance Market |
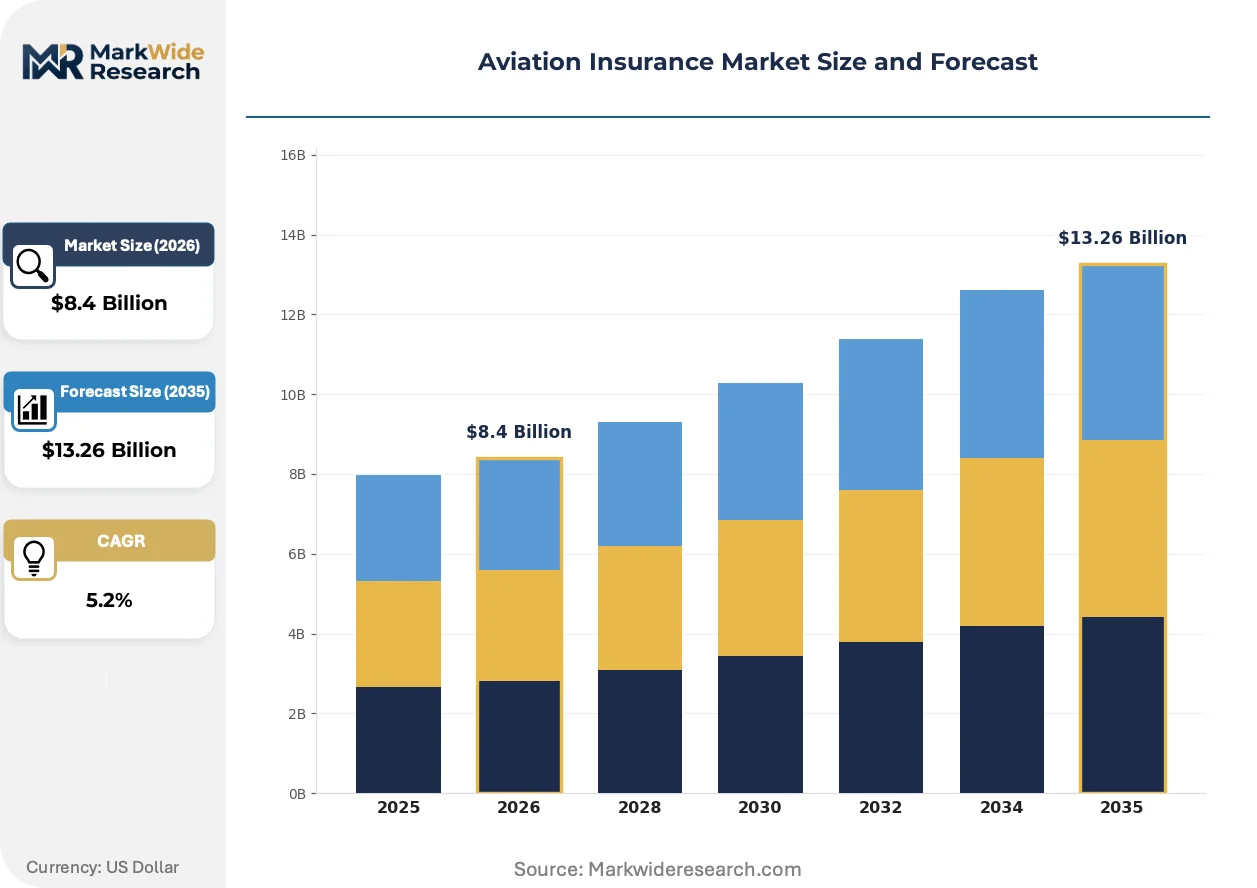
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Liability Insurance, Hull Insurance, Ground Risk Insurance, Passenger Insurance Aircraft Type: Commercial Aircraft, Cargo Aircraft, Private Jets, Helicopters Underwriter Type: National Insurers, Global Insurers, Specialty Insurers, Reinsurers Market Segment: Civil Aviation, Military Aviation, Agricultural Aviation, Drone Services |
| Companies Covered | Global Aerospace, Munich Re, AIG Aerospace, Tokio Marine HCC, Berkshire Hathaway, Chubb Ltd. Group, Allianz Aviation, AXA XL, Old Republic Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Insurance Market Strategic Shifts & Innovations
Algorithmic underwriting platforms are collapsing the traditional broker-carrier relationship, while climate risk modeling and unmanned aerial system integration reshape product architecture across commercial and general aviation lines.
Parametric hull coverage indexed to satellite-verified weather events is supplanting traditional indemnity policies for agricultural spraying and offshore helicopter fleets. Crop-dusting operators in Australia's wheat belt and North Sea oil-rig shuttle services are adopting these instruments to eliminate claims disputes over weather-related groundings. This shift is compressing loss-adjustment expenses and enabling capital-light entrants to price risks without decades of historical data.
EU Regulation 2019/947 mandates specific insurance thresholds for unmanned aerial system operators based on kinetic energy and operational airspace categories. The framework forces underwriters to develop modular products that scale from recreational drone liability to commercial beyond-visual-line-of-sight cargo coverage. European lessors are now requiring lessees to carry these policies as a condition of equipment financing, embedding insurance into supply chain contracts.
Fleet managers are unbundling maintenance and insurance procurement, previously purchased as bundled lessor packages. Low-cost carriers in Southeast Asia now tender hull coverage separately from engine maintenance agreements, driving price transparency and shortening renewal cycles. This fragmentation is most visible in Indonesia and Vietnam, where rapid narrow-body fleet expansion has outgrown the servicing capacity of integrated lessor-protector products.
Aviation Insurance Market Segmentation
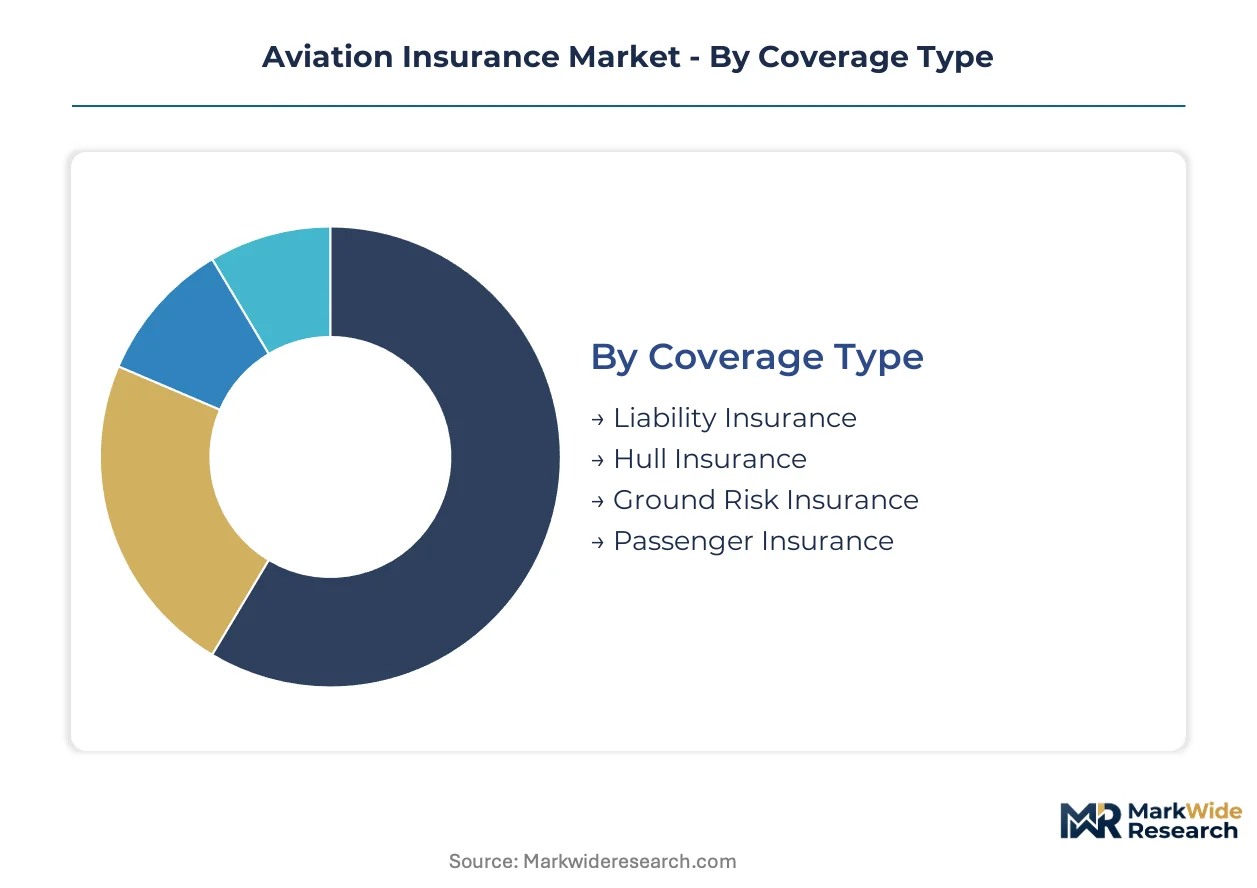
Aviation insurance segmentation reflects divergent risk profiles across aircraft operations, coverage structures, and underwriting capacities. Each dimension shapes premium calculation methodologies and determines which carriers can access specific risk pools.
Coverage Type:
Distribution channels vary sharply by coverage category, with liability policies flowing through broker networks while hull coverage often channels direct from global reinsurers to fleet operators.
- Liability Insurance:Covers third-party bodily injury and property damage from aircraft operations, typically structured around per-seat caps aligned with ICAO standards. Demand concentrates in the United States where state courts expand tort jurisdiction beyond Montreal Convention limits, forcing carriers to purchase excess layers above regulatory minimums.
- Hull Insurance:Physical damage coverage for airframes and engines, priced on agreed-value bases with deductibles scaled to fleet age and maintenance records. European commercial carriers dominate premium volume as EASA mandates drive renewal frequency and coverage breadth.
- Ground Risk Insurance:Protects against damage during maintenance, storage, and taxi operations outside active flight.
- Passenger Insurance:Covers medical expenses and accidental death benefits for ticketed travelers.
Hull insurance dominates installed base. Liability coverage is where expansion concentrates.
Aircraft Type:
Premium tiers stratify sharply across aircraft categories, with narrow-body commercial fleets commanding standardized pricing while rotorcraft and business jets require bespoke underwriting.
- Commercial Aircraft:Narrow-body and wide-body passenger jets operated under Part 121 or equivalent commercial certifications. Demand clusters in Southeast Asia where Indonesia and Vietnam carriers expand fleets faster than integrated lessor-protector products can accommodate, forcing unbundled procurement.
- Cargo Aircraft:Dedicated freighters and converted passenger-to-cargo aircraft serving express logistics networks. African and Central Asian corridors show acute underpenetration as specialized underwriters identify hull coverage gaps in high-utilization routes.
- Private Jets:Business aircraft under Part 91 or fractional ownership structures.
- Helicopters:Rotorcraft spanning offshore oil transport, emergency medical services, and executive transport.
Commercial aircraft anchor premium volume. Cargo aircraft represent the steepest expansion trajectory.
Underwriter Type:
Capital deployment patterns separate segments, with global insurers leveraging balance sheet scale while specialty carriers compete on technical expertise in niche risks.
- National Insurers:Domestic carriers operating under country-specific licensing with limited cross-border capacity. India's Directorate General of Civil Aviation relaxed charter regulations spawn fixed-base operator networks without mature insurance penetration, creating demand national carriers struggle to fulfill.
- Global Insurers:Multi-jurisdictional carriers with aviation divisions spanning hull, liability, and war-risk lines. London and Zurich-based reinsurance capacity concentrates catastrophic hull coverage, creating single-point failure risk for the entire market structure.
- Specialty Insurers:Niche underwriters focusing on specific risk categories such as agricultural spraying or unmanned systems.
- Reinsurers:Capacity providers absorbing primary carrier exposures through treaty and facultative arrangements.
Global insurers control catastrophic layers. Specialty insurers are gaining share fastest in emerging risk categories.
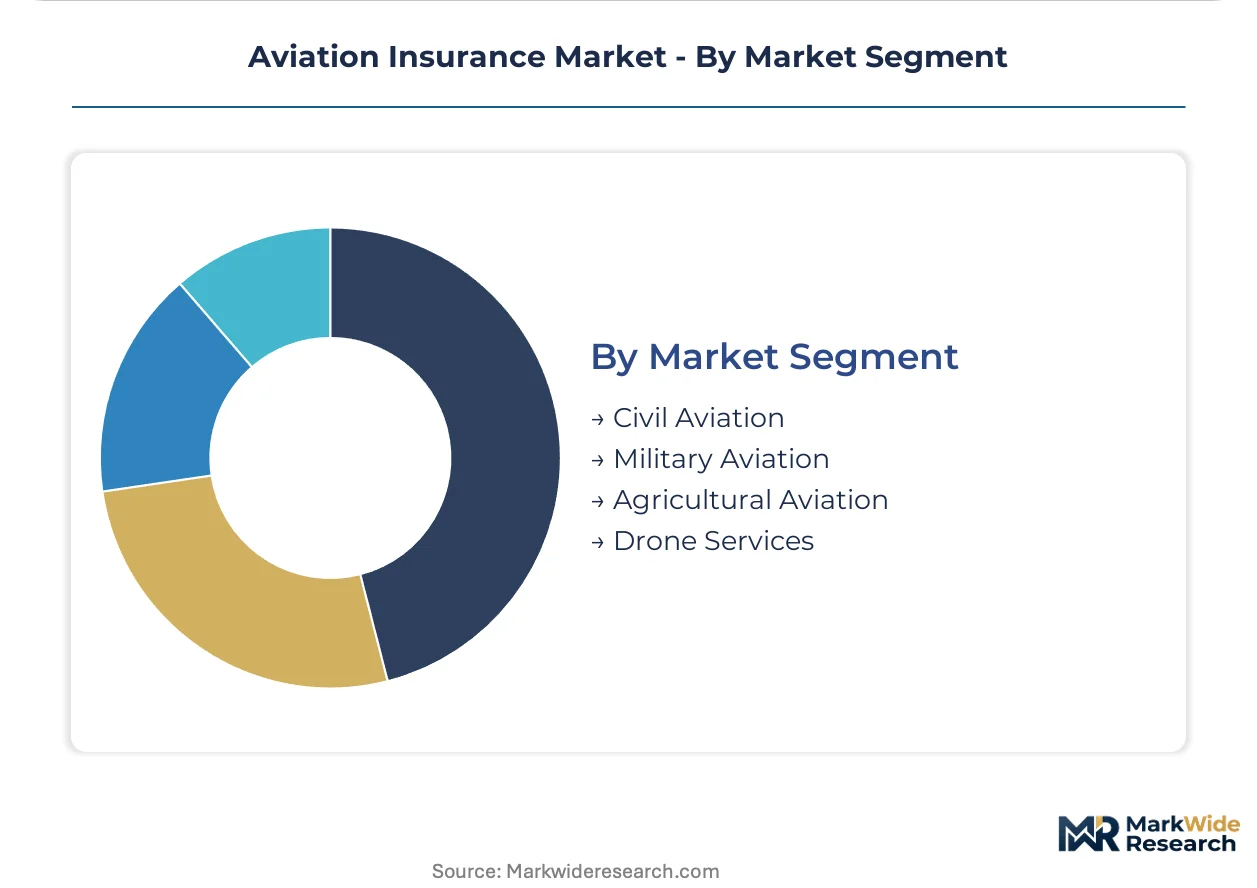
Market Segment:
Operational domains determine regulatory overlay intensity, with civil aviation facing FAA and EASA mandates while agricultural and unmanned segments confront evolving certification frameworks.
- Civil Aviation:Scheduled passenger and cargo operations under national aviation authority oversight. Dubai and Singapore electric vertical take-off and landing operators pre-purchase hull coverage before certification, front-loading demand into immature pricing models.
- Drone Services:Unmanned aerial system operations spanning photography, inspection, and cargo delivery. EU Regulation 2019/947 mandates kinetic-energy-based insurance thresholds, forcing modular product development from recreational liability through beyond-visual-line-of-sight commercial coverage.
- Military Aviation:Government-owned and operated aircraft with specialized risk-transfer arrangements.
- Agricultural Aviation:Crop-dusting and aerial application services.
Civil aviation anchors policy count. Drone services show the most rapid premium growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Southeast Asia exhibit acute price sensitivity as unbundled procurement spreads, while Middle Eastern carriers pre-purchase coverage at premium valuations before certification milestones.
United States
Legacy carriers renew policies at higher valuations as state courts expand tort jurisdiction beyond Montreal Convention limits. The FAA's updated Part 121 mandates force fleet-wide liability upgrades. Premium concentration clusters in Dallas-Fort Worth and Atlanta hub corridors where major carriers maintain operational headquarters.
Germany
EASA regulatory density drives renewal frequency for commercial hull coverage as climate risk models integrate real-time weather data. The national aviation authority enforces stringent maintenance-linked insurance requirements. Frankfurt and Munich anchor Europe's largest aviation insurance broker networks serving cross-border fleet operators.
India
Relaxed charter regulations spawn fixed-base operator networks without mature insurance penetration, creating demand-supply asymmetry. The Directorate General of Civil Aviation streamlines operational permits for non-scheduled services. Mumbai and Delhi-NCR concentrate emerging general aviation infrastructure where national carriers struggle to fulfill coverage requirements.
Singapore
Electric vertical take-off and landing operators pre-purchase hull coverage before certification, front-loading demand into immature pricing models. The Civil Aviation Authority of Singapore issues early framework guidance for urban air mobility. The city-state's status as Asia-Pacific aviation finance hub attracts specialized underwriters establishing regional headquarters.
United Arab Emirates
Dubai-based lessors unbundle maintenance and insurance procurement, driving price transparency in narrow-body fleet coverage. The General Civil Aviation Authority aligns with international standards for war-risk and lessor-protection products. Dubai International Financial Centre concentrates aviation finance legal expertise serving Gulf carrier expansion.
Aviation Insurance Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in aviation insurance. Global reinsurers with century-old aviation portfolios sustain premium volume across catastrophic hull coverage through balance sheet scale and treaty relationships. Specialty carriers compete on technical expertise in narrow-body fleet policies, war-risk instruments, and unmanned system coverage. Dominant competitive moves include parametric product development for weather-indexed policies and strategic partnerships with telemetry providers for usage-based pricing.
Among the integrated tier, Munich Re and AIG Aerospace exemplify divergent specialization strategies. Munich Re occupies a position anchored in catastrophic hull capacity provision to primary carriers globally. AIG Aerospace represents the war-risk and lessor-protection specialization vector that dominates narrow-body fleet policies. Global Aerospace sits within the general aviation segment where manual underwriting still commands pricing power in rotorcraft and business jet lines.
| Leading Market Players |
|---|
| Global Aerospace |
| Munich Re |
| AIG Aerospace |
| Tokio Marine HCC |
| Berkshire Hathaway |
| Chubb Ltd. Group |
| Allianz Aviation |
| AXA XL |
| Old Republic Aerospace |
| Others |
Cost & Logistics Intelligence
Reinsurance treaty capacity concentration in London and Zurich establishes premium floors across catastrophic hull layers, compressing margins for primary carriers unable to secure long-term quota-share arrangements. Scale economies in aviation underwriting thus concentrate pricing power among global reinsurers while regional carriers absorb basis risk through higher retentions.
Pricing Analysis
Claims adjustment service revenue and parametric payout administration now drive lifetime value beyond initial premium collection. Hull coverage for commercial narrow-body fleets operates on agreed-value transactional models with deductibles scaled to maintenance records, while liability policies differentiate through excess layer depth and war-risk endorsements. Pricing pressure stems from algorithmic platforms compressing broker-carrier spreads, with Southeast Asian low-cost carriers exhibiting acute price sensitivity compared to Middle Eastern lessors pre-purchasing coverage at premium valuations before certification milestones.
Supply Chain Analysis
London, Zurich, and Bermuda anchor catastrophic reinsurance capacity provision, feeding primary carrier hull and liability lines across all major aviation markets. Treaty arrangements draw from retrocession pools, Lloyd's syndicate paper, and collateralized reinsurance vehicles, with single-source vulnerability concentrated in London market capacity for war-risk coverage. Distribution runs through aviation-specialized broker networks in Frankfurt, New York, and Singapore, channeling coverage from reinsurers to fleet operators and lessor-protector products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation insurance functions as a service-attach business where parametric claims administration and telemetry-based usage pricing expand recurring revenue faster than traditional indemnity underwriting. The shift from annual renewal cycles toward continuous monitoring frameworks embeds after-sales service deeper into carrier-client relationships.
For Market Incumbents: Fortify treaty relationships with London and Zurich reinsurers to secure catastrophic capacity allocations before climate model hardening permanently raises attachment points. Invest in telemetry integration partnerships to defend against algorithmic platforms disintermediating traditional broker networks, particularly for narrow-body fleet policies where usage-based pricing is concentrating. For New Entrants and Emerging Players: Unmanned aerial system modular coverage represents the most penetrable white-space segment, with EU Regulation 2019/947 mandating kinetic-energy-based thresholds that incumbent carriers have under-served. Target African and Central Asian cargo corridor hull gaps through specialized underwriter partnerships, deploying satellite-indexed parametric products that bypass decades of historical loss data requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty carriers with embedded lessor-protector relationships and drone services modular product lines. Long-term viability favors acquisition targets combining aviation actuarial expertise with parametric product development capabilities, with the signal to watch being climate attribution science adoption rates among primary carrier risk modeling teams.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Satellite-indexed weather policies bypass claims adjustment delays for agricultural and offshore helicopter operators. |
| Telemetry Integration Partnership | Flight data monitoring hardware enables usage-based pricing that compresses traditional broker-carrier spreads. |
| Drone Coverage Modularization | EU Regulation 2019/947 kinetic-energy thresholds force scalable products from recreational liability through commercial cargo lines. |
| Lesser-Protected Route Specialization | African and Central Asian air freight corridors operate with acute hull coverage gaps for specialized underwriters. |
| Actuarial Talent Acquisition | Aviation-specialized underwriters who understand turbine engineering and tort law are retiring faster than training programs replace them. |
Research Approach
The analysis maps hull coverage, liability lines, war-risk products, and unmanned system policies, each validated through underwriters, aviation brokers, fleet risk managers, and lessor-protector specialists. Primary interviews with treaty reinsurance executives and parametric product developers combined with secondary validation from FAA safety directives, EASA regulatory filings, ICAO recommended practices, and national aviation authority operational statistics. Bottom-up premium pool estimates triangulated against top-down reinsurance capacity allocations.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include coverage type, aircraft category, underwriter capital structure, and operational domain. CAGRs derived from historical premium trajectory analysis adjusted for regulatory mandate timing and climate model integration rates. Forecast inputs incorporated fleet expansion pipelines from Indonesia and Vietnam carriers alongside urban air mobility pre-certification coverage purchases in Dubai and Singapore.
Forecasts assume regulatory continuity in FAA Part 121 mandates and EASA drone integration frameworks; material policy shifts would require re-modeling premium pool trajectories. Climate attribution science advances, reinsurance capacity dislocation, and telematics hardware adoption curves constitute specific revision risks. Recalibration cycles align with material shifts in renewal pricing hardening and parametric product penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
MENA Health and Medical Insurance Market
Insurance
General Insurance Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
Trade Credit Insurance Market
Insurance
Europe Mobile Phone Insurance Market
Insurance
Cybersecurity Insurance Market
Insurance
Credit Insurance Market
Insurance
Liability Insurance Market
Insurance
UK Cyber (Liability) Insurance Market
Insurance
Auto Compulsory Insurance Market
Insurance
Digital Innovation in Insurance Market
Insurance
Europe Entertainment Insurance Market
Insurance
Asia-Pacific Usage-Based Insurance Market
Insurance
Global Flood Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Europe Health Insurance Market