
 Metal IBC Market | 2026-2036
Metal IBC Market Size, Share, and Industry Trends Forecast 2026-2036
Metal IBC Market Intelligence
The expansion of integrated rental and fleet management services is rewriting traditional distribution channel dynamics. Hoover Ferguson leverages its extensive global fleet to offer comprehensive logistics and tracking solutions. THIELMANN specializes in customized stainless steel containers for high-purity applications in pharmaceuticals and food. Mauser Packaging Solutions competes across the packaging spectrum, offering a diverse product range.
A metal intermediate bulk container (IBC) is a reusable, multi-modal container designed for transporting and storing bulk liquids and granulated substances. Typically constructed from stainless steel or carbon steel, these containers are engineered to specific UN/DOT certifications for safety. Stainless steel units command a premium due to their corrosion resistance, essential for pharmaceuticals and food & beverage applications. Carbon steel containers find widespread use in the less-purity-sensitive chemicals and oil & gas sectors.
Market access and design specifications are heavily influenced by transport and safety regulations. In the United States, the FDA and DOT set stringent standards, while in Europe, compliance with REACH and EFSA is mandatory for chemical and food-grade applications. These frameworks dictate material selection and testing protocols. Future procurement decisions will increasingly balance the initial cost of acquisition against the total lifecycle value, including reusability and compliance.
Market Dynamics
The market's central dynamic is the escalating tension between the high initial acquisition cost of certified metal IBCs and the growing regulatory imperative for total lifecycle integrity, particularly for transporting hazardous and high-purity materials across international borders.
Growth Catalysts
- Stringent Transport Regulations:The enforcement of standards like the UN Model Regulations for hazardous materials transport compels shippers to use certified, durable containers, directly benefiting metal IBC manufacturers over less robust alternatives for specific chemical classes.
- Pharmaceutical Sector Expansion:Demand from pharmaceutical manufacturing for sterile, corrosion-resistant stainless steel containers is accelerating, driven by the need for aseptic transport of active pharmaceutical ingredients and other high-purity substances.
- Advanced Manufacturing Clusters:The concentration of sophisticated chemical production in regions like Germany creates dense pockets of demand for specialized IBCs that meet precise safety and material compatibility specifications for complex supply chains.
Market Restraints
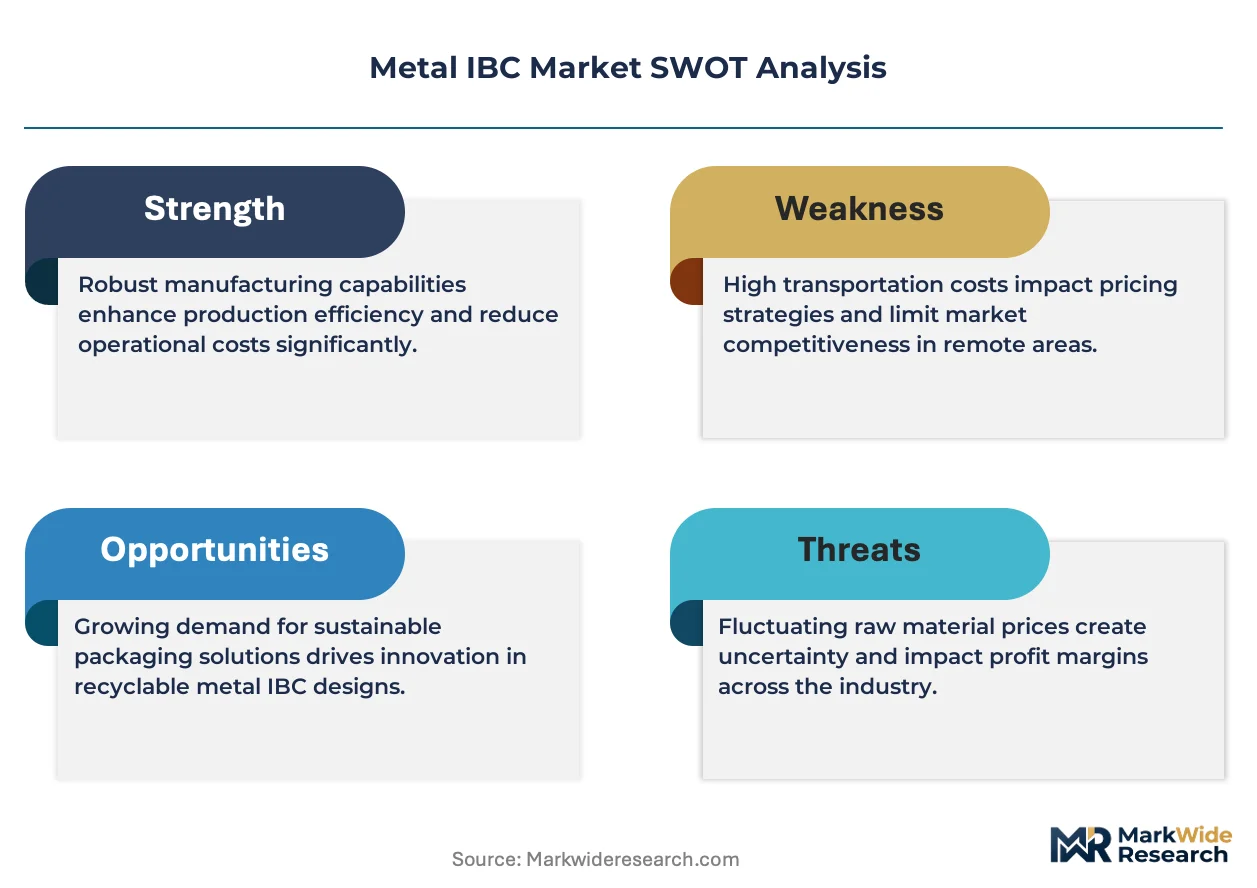
- Input Material Price Volatility:Fluctuations in the global prices of stainless steel and carbon steel create significant cost uncertainty for manufacturers and can pressure end-user margins, making budget forecasting difficult for large-scale procurement.
- Substitution from Composites:For non-hazardous or less sensitive bulk materials, advanced polymer and composite IBCs present a viable, lower-cost, and lighter-weight alternative, limiting the addressable market for metal containers in certain segments.
- High Initial Capital Outlay:The significant upfront investment required to purchase stainless steel IBCs, compared to carbon steel or plastic units, acts as a barrier for smaller enterprises or those with less intensive usage requirements.
Strategic Opportunities
- Integrated Rental Models:The expansion of rental and fleet management services provides an opportunity to capture customers unwilling to make a large capital investment, offering a total cost of ownership model that includes logistics and tracking.
- Battery Materials Transport:The burgeoning electric vehicle industry creates a new application for secure, regulated transport of battery precursors, electrolytes, and recycling materials, which often have hazardous properties requiring robust containment.
- Circular Economy Frameworks:Developing certified refurbishment, repair, and re-testing services allows providers to capture lifecycle revenue and appeal to customers with corporate sustainability mandates focused on reusability and waste reduction.
Industry Challenges
- Complex Regulatory Navigation:Manufacturers and fleet operators face significant operational overhead in ensuring containers comply with a patchwork of regional and national rules, such as US DOT standards and Europe's REACH framework.
- Specialized Labor Scarcity:A shortage of welders and technicians with the specific certifications required to manufacture and repair UN-rated pressure vessels constrains production capacity and increases labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal IBC Market |
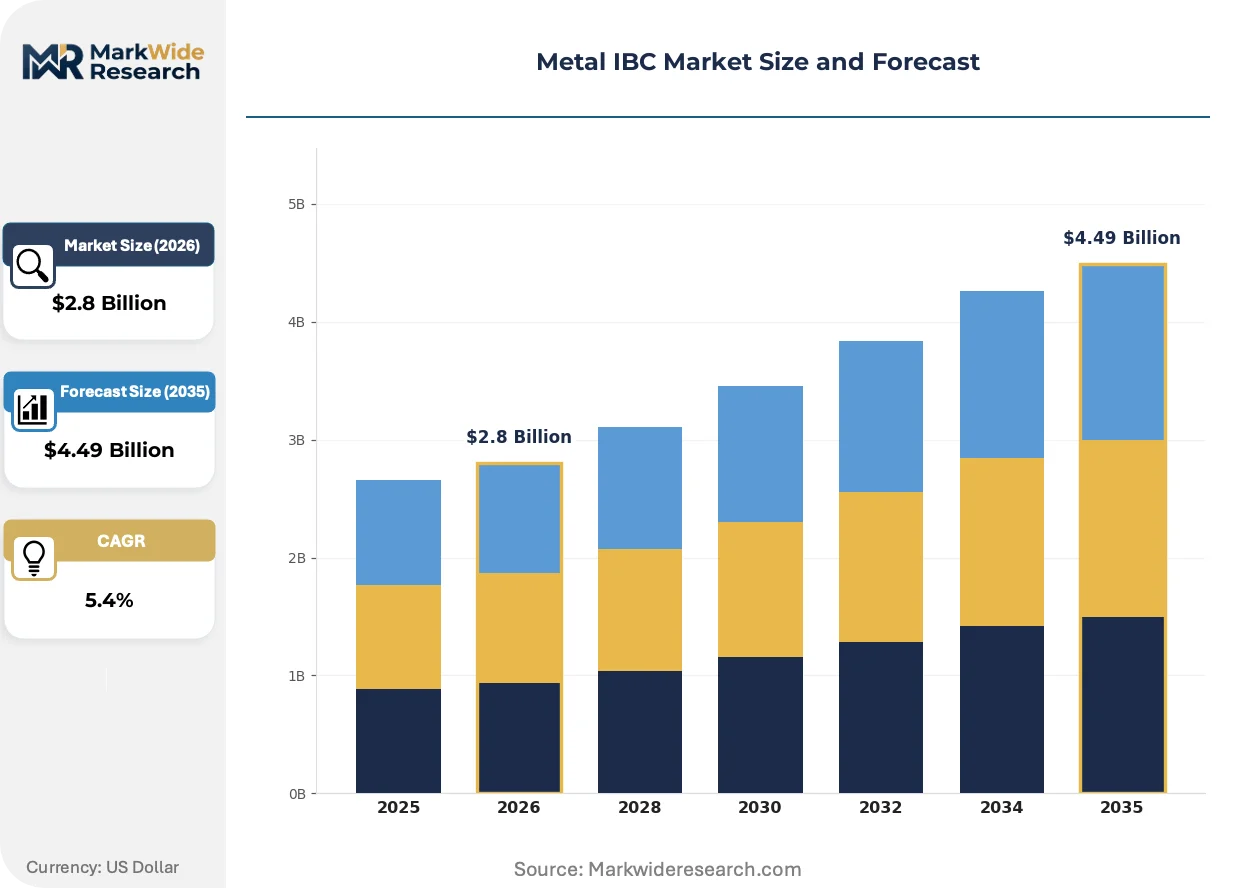
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Carbon Steel, Coated Steel, Aluminum Application: Chemicals, Pharmaceuticals, Food & Beverage, Oil & Gas Capacity: 200 Liters, 600 Liters, 1000 Liters, 1500 Liters Distribution Channel: Direct Sales, Online Retail, Distributors, Manufacturers |
| Companies Covered | Schütz GmbH & Co. KGaA, Hoover Ferguson, THIELMANN, Metal Craft Technologies Co., Precision IBC, Greif, Inc., Custom Metalcraft, SafeRack LLC, Mauser Packaging Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal IBC Market Strategic Shifts & Innovations
The integration of digital technologies with physical container assets is fundamentally altering how lifecycle value and in-transit security are managed. This shift transforms the IBC from a simple vessel into an active component of a connected supply chain ecosystem.
Smart container technology, featuring embedded IoT sensors for location tracking and condition monitoring, is gaining traction. The pharmaceutical and specialty chemical sectors are early adopters, seeking real-time data on temperature, pressure, and unauthorized access. The market is migrating from passive RFID tagging for inventory counts to active, continuous monitoring that provides auditable proof of compliance and product integrity throughout the transit journey.
European chemical and food safety regulations, particularly REACH and EFSA guidelines, are dictating material specifications with increasing force. These frameworks mandate stringent testing for substances that come into contact with container surfaces, effectively creating a non-tariff barrier for non-compliant imports. Consequently, the food and beverage and fine chemical segments are standardizing on higher-grade stainless steel to ensure compliance and mitigate contamination risks.
Fleet management and leasing models are displacing traditional outright ownership, especially for businesses with variable demand. This trend disrupts direct sales channels by introducing specialized service providers who manage logistics, maintenance, and compliance for an entire fleet. The shift is most pronounced in the North American and European chemical sectors, where operational flexibility and reduced capital expenditure are prioritized.
Metal IBC Market Segmentation
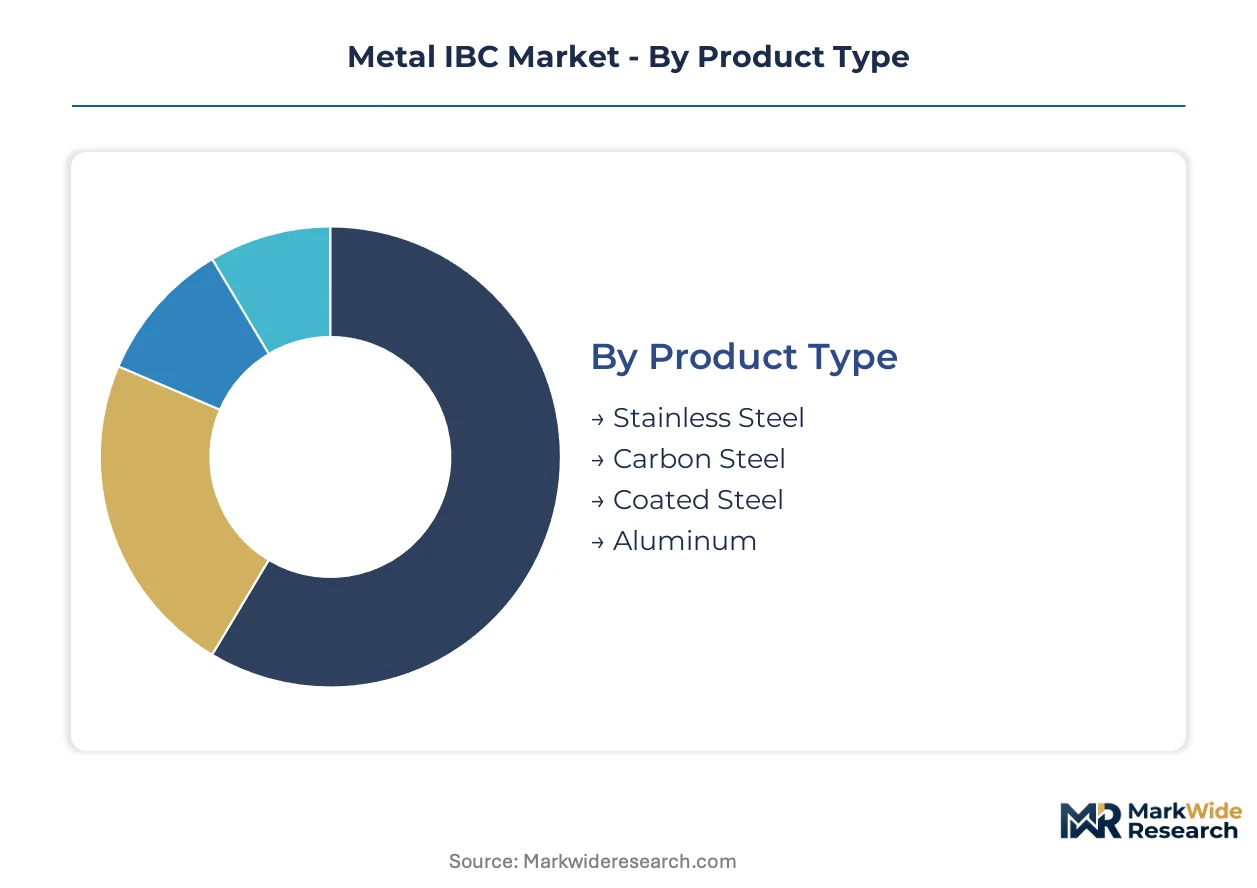
Segmentation within the Metal IBC market is essential for understanding diverse material requirements, specific application demands, and optimal distribution strategies. This granular analysis highlights where different container types are critical for safety, regulatory compliance, and operational efficiency across industrial sectors.
Product Type:
The product type segment reflects a spectrum of material maturity, from established steel formulations to specialized coated options addressing evolving purity and chemical compatibility needs.
- Stainless Steel:This product type offers superior corrosion resistance and hygienic properties, making it indispensable for high-purity applications. Demand from the pharmaceutical and food & beverage sectors is strong, driven by stringent hygiene and non-contamination requirements.
- Carbon Steel:Carbon steel containers provide a durable and cost-effective solution for general industrial use, particularly for less sensitive bulk materials. This segment finds widespread demand in the chemicals and oil & gas sectors, where purity is less critical and volume is high.
- Coated Steel:Coated steel IBCs provide enhanced chemical resistance for specific corrosive substances, extending container lifespan in niche industrial applications.
- Aluminum:Aluminum offers a lightweight alternative for certain non-corrosive chemicals or where weight reduction is a primary logistical consideration.
Carbon Steel retains volume leadership; Stainless Steel holds the steepest expansion curve.
Application:
Application-specific demands dictate the material, capacity, and certification requirements for metal IBCs across diverse industrial sectors.
- Pharmaceuticals:This application requires aseptic and corrosion-resistant containers, predominantly stainless steel, for active pharmaceutical ingredients and sterile liquids. Demand is driven by global drug manufacturing and strict regulatory compliance for product integrity.
- Chemicals:The chemicals application encompasses a broad range of substances, from hazardous to non-hazardous, necessitating diverse material compatibility and UN/DOT certifications. Demand concentrates in advanced manufacturing clusters in Germany and the US for bulk chemical transport.
- Food & Beverage:This sector demands food-grade stainless steel IBCs for hygienic transport of ingredients and finished products, adhering to EFSA and FDA standards.
- Oil & Gas:The oil & gas sector utilizes robust carbon steel IBCs for transporting lubricants, drilling fluids, and waste products in demanding operational environments.
Rising regulatory scrutiny for Pharmaceuticals is influencing material choices, while Chemicals continues to drive significant volume.
Capacity:
Logistical efficiency and batch size optimization are primary considerations influencing the selection of metal IBC capacities across various industries.
- 1000 Liters:This capacity represents a standard for bulk liquid transport, balancing transport efficiency with handling flexibility. Demand is widespread across chemical and food industries, aligning with common batch sizes and logistics infrastructure.
- 1500 Liters:This capacity provides increased volume per shipment, optimizing freight costs for high-volume, lower-density materials. It is often chosen by large-scale industrial operations, particularly in oil & gas and bulk chemical manufacturing.
- 200 Liters:This capacity caters to smaller batch requirements or specialized high-value substances, often used in laboratory or pilot plant settings.
- 600 Liters:This mid-range capacity is suitable for intermediate volumes where 1000L is too large, common in specialty chemical distribution.
The 1000 Liters segment remains the most versatile, with larger capacities gaining favor for economies of scale.
Distribution Channel:
Market access strategies vary significantly across the metal IBC landscape, reflecting different customer procurement preferences and service requirements.
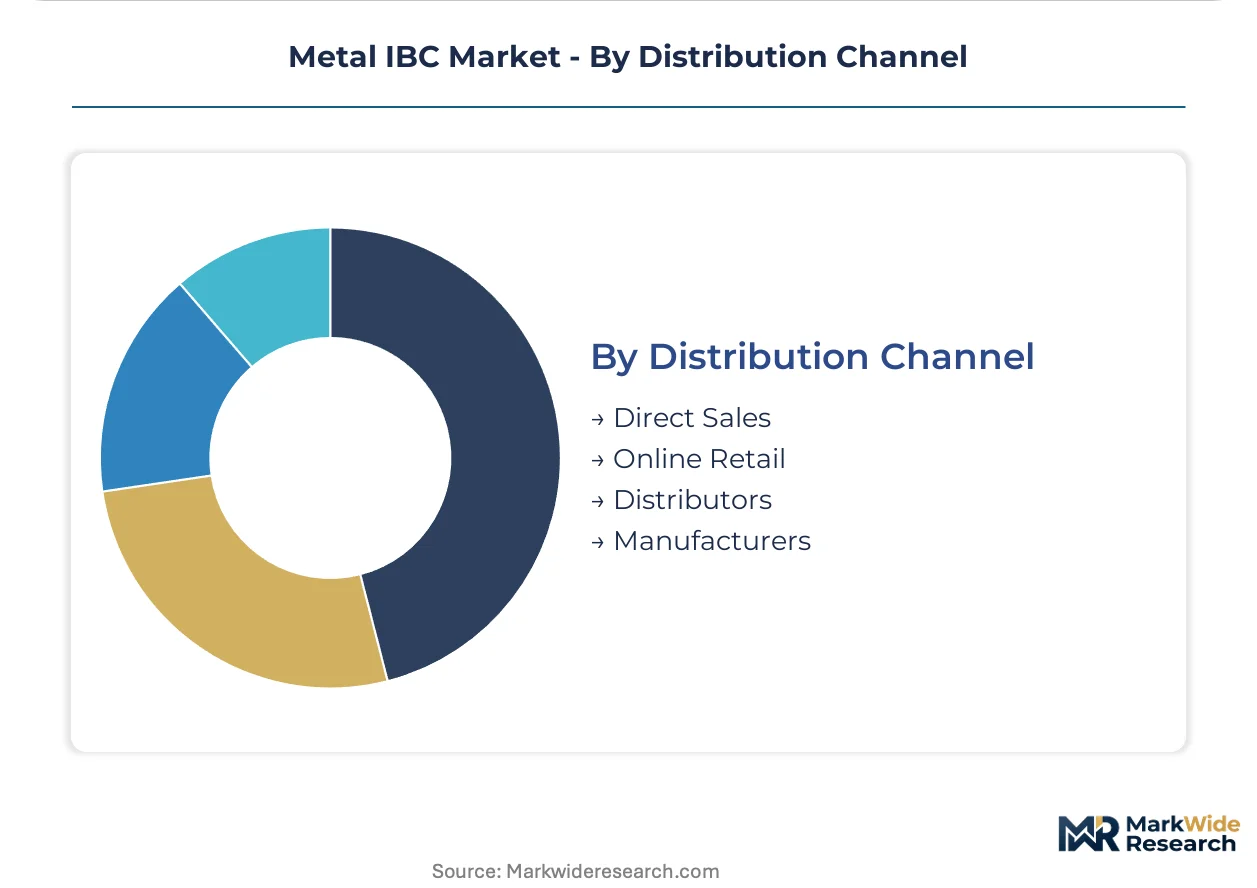
- Direct Sales:This channel involves manufacturers selling directly to end-users, facilitating customized solutions, technical support, and large-volume contracts. It is preferred by large enterprises in pharmaceuticals and specialty chemicals for complex requirements and long-term relationships.
- Distributors:Third-party entities manage sales, logistics, and often provide local inventory and support to a diverse customer base. This channel serves small to medium-sized businesses and offers regional market penetration for manufacturers.
- Online Retail:This emerging channel caters to standardized IBCs and accessories, appealing to smaller buyers seeking convenience and transparent pricing.
- Manufacturers:Manufacturers often integrate direct sales with comprehensive service offerings like leasing and fleet management, providing full lifecycle support beyond mere product sales.
Direct Sales remains critical for strategic accounts, while Distributors expand market reach for smaller enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for metal IBCs exhibits regional asymmetry, with Germany's specialized chemical manufacturing driving higher value propositions. In contrast, markets prioritizing initial acquisition cost over long-term lifecycle value exert different pricing pressures. Global demand for certified containers is influenced by diverse regulatory frameworks and industrial concentrations.
Germany
Demand for high-purity stainless steel IBCs stems from its advanced chemical and pharmaceutical industries. Compliance with REACH and EFSA guidelines mandates stringent material specifications for container surfaces. The Rhine-Main region, with its dense chemical parks, drives significant procurement of specialized IBCs for complex supply chains.
United States
The US market requires robust metal IBCs for diverse chemical transport and oil & gas operations. FDA and DOT regulations set stringent standards for container design and material choices. Industrial clusters in Texas, particularly around Houston, concentrate demand for carbon steel units in the energy sector.
China
China's expanding pharmaceutical and specialty chemical sectors fuel demand for both stainless steel and carbon steel IBCs. The country's GB standards dictate manufacturing and safety requirements for bulk material transport. The Yangtze River Delta region, a major industrial hub, sees significant investment in advanced IBC solutions for domestic and export markets.
India
India's pharmaceutical industry expansion drives demand for sterile, corrosion-resistant stainless steel containers. CDSCO guidelines for drug manufacturing influence the selection of high-purity IBCs. The pharmaceutical manufacturing clusters in Gujarat and Hyderabad are rapidly adopting specialized IBCs for active pharmaceutical ingredients.
Japan
Demand in Japan focuses on precision-engineered stainless steel IBCs for its fine chemical and food & beverage industries. JIS standards ensure high quality and safety compliance for industrial packaging. The Kansai region, home to numerous advanced materials and food processing companies, requires specialized containers for sensitive products.
Metal IBC Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying essential materials and sub-assemblies. The metal IBC market exhibits a tiered structure, with a few large players offering comprehensive fleet management solutions. Several specialized manufacturers focus on niche applications, particularly for high-purity or hazardous materials. Strategic moves include expanding rental models and pursuing geographic diversification to capture new demand.
On the premium-tier vector, THIELMANN, a German-based company, exemplifies specialization in customized stainless steel containers for high-purity applications. Hoover Ferguson, with its extensive global fleet, represents the integrated rental and fleet management archetype, providing comprehensive logistics and tracking solutions. Mauser Packaging Solutions, a prominent player, occupies a position across the broader packaging spectrum, offering a diverse product range to various industrial sectors. These companies collectively anchor different strategic approaches within the market.
| Leading Market Players |
|---|
| Schütz GmbH & Co. KGaA |
| Hoover Ferguson |
| THIELMANN |
| Metal Craft Technologies Co. |
| Precision IBC |
| Greif, Inc. |
| Custom Metalcraft |
| SafeRack LLC |
| Mauser Packaging Solutions |
| Others |
Cost & Logistics Intelligence
Commodity price volatility for stainless steel and carbon steel determines both metal IBC pricing tier spreads and supply chain resilience. This fluctuation directly impacts manufacturer costs and end-user procurement decisions.
Pricing Analysis
Customization-premium spreads define metal IBC pricing, contrasting configured-to-order solutions with standard offerings. Contract-based long-term offtake agreements dominate for large enterprises, while per-unit transactional models serve smaller buyers. Price differentiation stems from UN/DOT certification levels, specific material grades, and integrated rental services. Pricing softness affects standard carbon steel units due to composite substitution, while pharmaceutical and specialty chemical sectors exhibit lower price sensitivity for high-grade stainless steel.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the capital-intensive nature of metal IBC manufacturing. Geographic supply concentrates in Germany for specialized stainless steel units and China for broader volume production. The sector heavily relies on stainless steel coils and carbon steel sheets as primary raw materials, making input material price volatility a significant structural risk. Distribution runs through direct sales channels for large enterprises and regional distributors for smaller businesses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metal IBC market offers a significant service-attach opportunity, with integrated rental and fleet management services expanding faster than direct container sales. This shift creates recurring revenue streams and deeper customer relationships for providers.
For Market Incumbents:Harden specialized manufacturing capabilities for high-purity stainless steel IBCs to counter substitution from composite alternatives. Incumbents should expand global rental and fleet management services, leveraging existing infrastructure to control distribution channels. Investing in UN/DOT and FDA compliance certifications creates a barrier against new entrants. This strategy mitigates margin pressure from standard carbon steel segments.
For New Entrants and Emerging Players:Pursue niche applications like battery materials transport, which require robust, regulated containment solutions. New entrants can target smaller enterprises in North America and Europe, offering flexible rental models that reduce initial capital outlay. A go-to-market strategy emphasizing total cost of ownership, including logistics and compliance support, will attract price-sensitive customers. This approach allows market penetration without directly challenging established players' scale.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors vertically integrated specialists offering comprehensive lifecycle solutions. Long-term viability stems from the persistent need for secure, compliant transport of hazardous and high-purity materials. Investors should target companies with robust regulatory compliance expertise and scalable global fleet management operations. The expansion of circular economy frameworks, particularly certified refurbishment services, signals a key inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increasing stainless steel production addresses rising pharmaceutical sector demand for high-purity containers. |
| Joint Venture | Partnering for battery materials transport captures new revenue streams from the burgeoning electric vehicle industry. |
| Green Manufacturing Transition | Adopting sustainable production methods appeals to customers with corporate sustainability mandates and reduces environmental impact. |
| Distribution Channel Expansion | Growing rental fleets in North America and Europe captures market share from businesses prioritizing operational flexibility. |
| Technology Licensing | Acquiring smart container IoT solutions enhances real-time tracking and condition monitoring for high-value substances. |
Research Approach
A standing panel of chemical plant managers, pharmaceutical procurement leads, logistics fleet operators, and material scientists provided ongoing calibration for market sizing. This study combined primary interviews with industry stakeholders and secondary validation from sources like UN Model Regulations and FDA guidelines. Bottom-up and top-down triangulation ensured data accuracy across all segments. The REACH framework and customs/trade data further informed the analysis.
Scenario-bracketing established the forecast framework, integrating various market dimensions across the analysis window. Segmentation included product type, application, capacity, distribution channel, and regional regulatory clusters. Compound annual growth rates were derived from historical growth patterns and future demand projections. Global chemical production indices and pharmaceutical R&D spending served as critical forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in global trade policies or commodity prices would shift the trajectory. Forecasts reflect assumptions documented across the modeling period, acknowledging geopolitical instability and new material innovations as key risk factors. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Bulk Container Packaging Market
Containers
HDPE Crates Market
Containers
Car Lube Container Market
Containers
Screw Top Jar Market
Containers
Foldable Large Containers Market
Containers
Wooden Barrels Market
Containers
Rotomolded Containers Market
Containers
Thin Wall Containers Market
Containers
Packaging Bins Market
Containers
Acrylic Container Market
Containers
Stock Clamshell Packaging Market
Containers
Screw Top Lids Market
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
Container Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Essential Oil Containers Market