
 Acrylic Container Market | 2026-2036
Acrylic Container Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Container Market Outlook
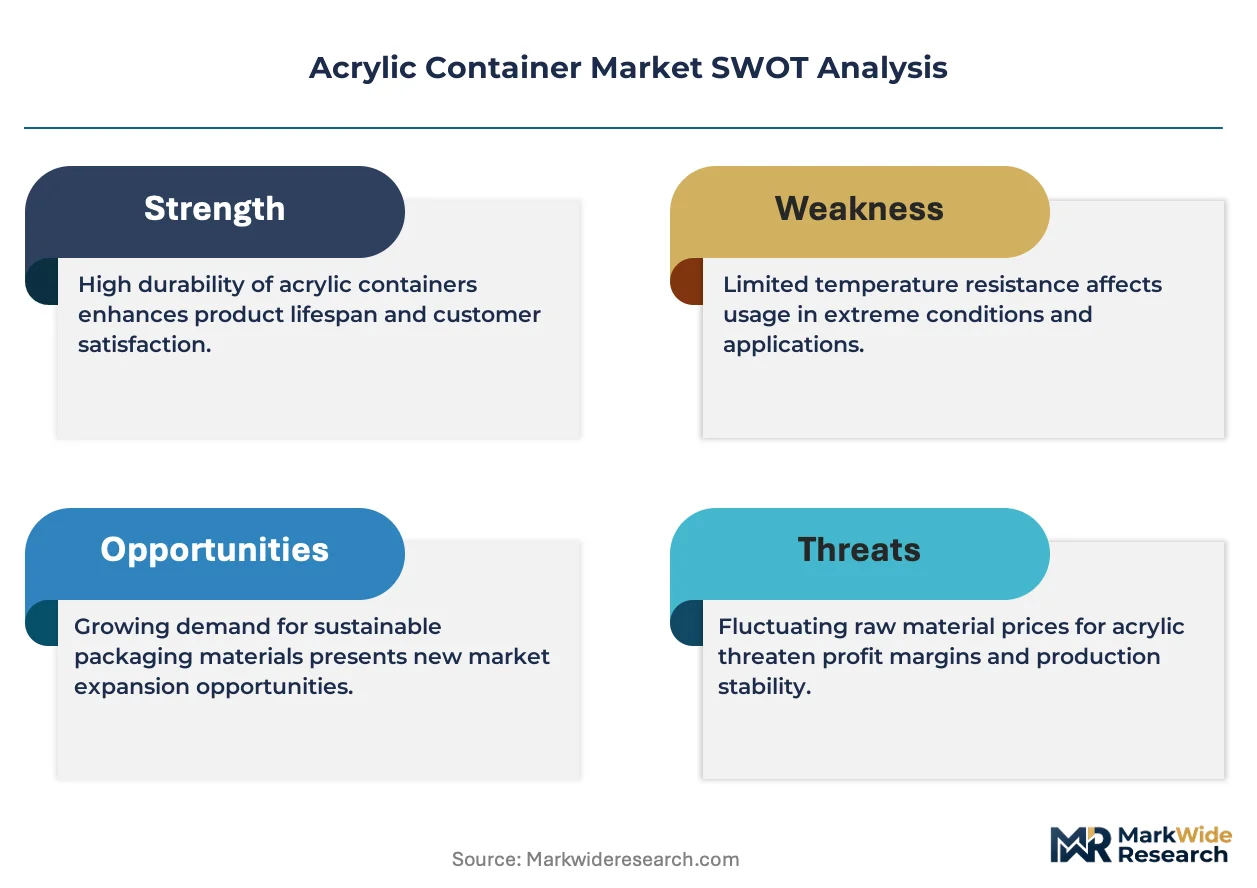
Glass is broadening its vulnerability to displacement as acrylic achieves comparable optical clarity at roughly half the weight. Evonik Industries leverages its methacrylate monomer supply chain to sustain captive resin output for container-grade formulations. Plaskolite LLC anchors North American sheet-to-container conversion through its thermoforming partnerships with display and storage OEMs.
Acrylic containers are fabricated from polymethyl methacrylate (PMMA), a thermoplastic polymer offering light transmission rates exceeding 92% and impact resistance roughly seventeen times that of equivalent glass thickness. These properties make acrylic indispensable for premium cosmetic packaging, laboratory specimen storage, and retail display systems where breakage risk and visual presentation matter equally. Bottles and jars command the dominant share of product-type revenue because skincare and fragrance brands prioritize pump-dispenser and wide-mouth formats that balance aesthetics with functional dispensing. Laboratory end users represent the fastest-expanding demand pool as academic and clinical research facilities replace glassware with shatter-resistant alternatives that maintain solvent compatibility.
FDA food-contact notification requirements and EPA resin precursor rules govern acrylic container composition in the United States, while REACH substance restrictions in Europe limit residual monomer content in consumer-facing applications. Compliance with these overlapping frameworks elevates testing costs for cross-border suppliers but simultaneously rewards certified manufacturers with preferential procurement status from multinational brand owners. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation cycles that compress margin pools.
Market Dynamics
Injection-molding clusters in Guangdong province are consolidating acrylic container supply chains, compressing lead times for export orders while forcing smaller converters to absorb higher resin costs or exit specialty grades entirely.
Growth Catalysts
- REACH Substance Restrictions:Residual monomer limits in Europe are rewarding certified manufacturers with preferential procurement status from multinational cosmetic brands seeking compliant packaging.
- Laboratory Glassware Replacement:Academic and clinical research facilities are converting specimen storage to shatter-resistant acrylic alternatives that maintain solvent compatibility without breakage risk.
- Guangdong Cluster Concentration:Injection-molding hubs serving both domestic Chinese brands and export orders are achieving scale economies that lower unit costs for premium cosmetic packaging formats.
Market Restraints
- Methacrylate Monomer Volatility:Acrylic resin pricing tracks acetone and cyanohydrin feedstock markets, exposing container converters to margin compression when petrochemical spreads widen.
- Glass Recyclability Preference:Sustainability-conscious beauty brands in Northern Europe retain glass for refillable programs where end-of-life circularity outweighs weight savings.
- FDA Notification Burden:Cross-border suppliers face elevated testing costs to satisfy food-contact notification requirements for acrylic storage containers entering US distribution.
Strategic Opportunities
- Pharmaceutical Cold Chain:Acrylic vials and transport containers for temperature-sensitive biologics offer growth white space as biopharma logistics networks expand.
- India PLI Scheme:Domestic manufacturing incentives for specialty chemicals could localize acrylic resin production and reduce import dependency for container converters.
- Digital Printing Convergence:Direct-to-container UV inkjet decoration enables lot-size-one personalization for limited-edition cosmetic releases without label substrate costs.
Industry Challenges
- Color-Matching Expertise Gap:Cosmetic brands demand batch-to-batch optical consistency that requires skilled technicians scarce in emerging manufacturing regions.
- Dual Certification Timelines:Simultaneous FDA food-contact and REACH cosmetic-grade approvals extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Container Market |
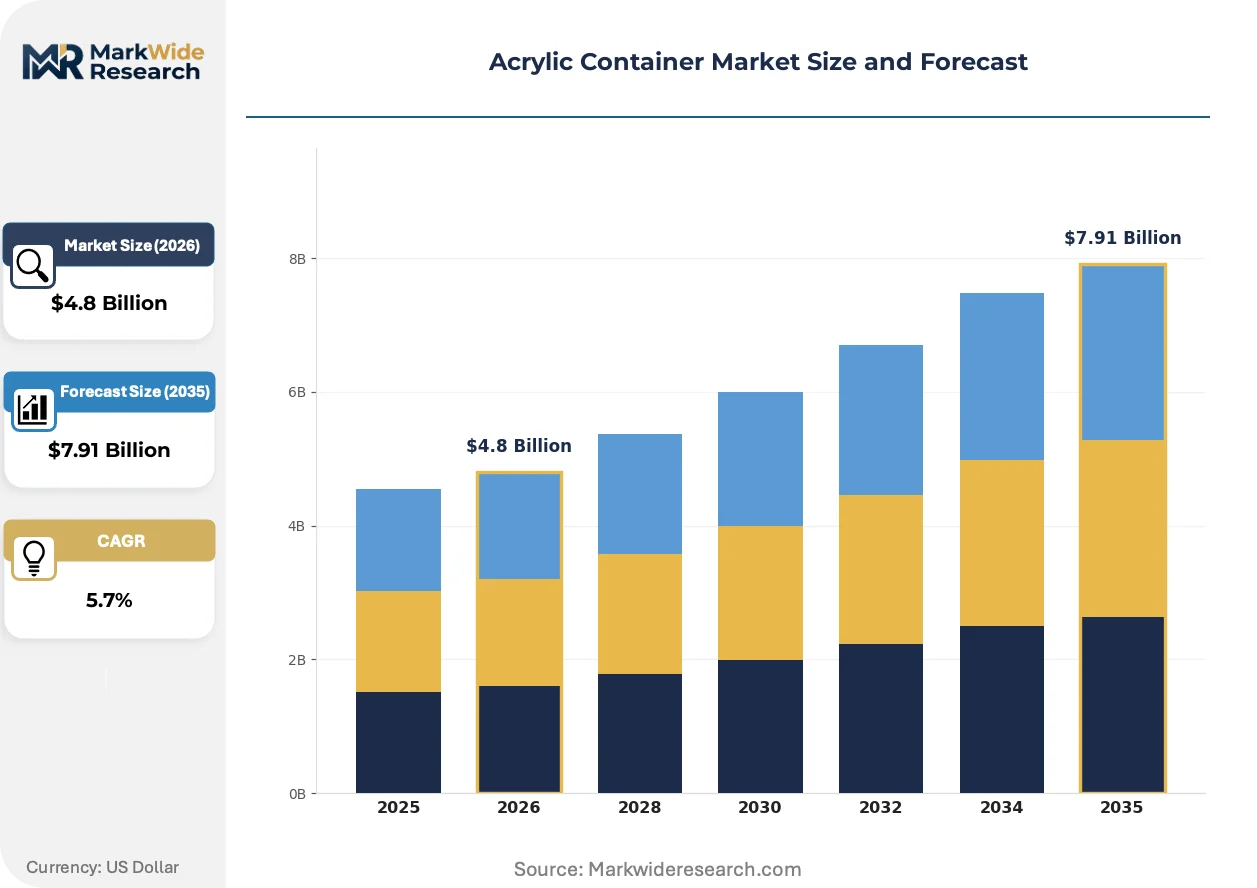
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Boxes, Trays End User: Households, Retail, Restaurants, Laboratories Shape: Round, Square, Rectangular, Hexagonal Color: Clear, Frosted, Colored, Transparent |
| Companies Covered | Liberty Industries, Shenzhen Jing Yue Acrylic Products Manufacturing, Akrylix USA, Lucite International, Plaskolite LLC, Pioneer Plastics, Cleatech, Evonik Industries, Sunday Knight, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Container Market Strategic Shifts
Acrylic container fabrication is pivoting toward lighter-weight formulations and integrated smart features as brand owners balance sustainability metrics with functional differentiation in premium packaging tiers.
Co-extruded barrier-layer PMMA is expanding into oxygen-sensitive skincare packaging, enabling brands to replace heavier glass with acrylic pump bottles that match twelve-month shelf-life requirements. Korean cosmetic houses are piloting these structures for essence and serum formats. The technology is compressing traditional multi-material lamination steps into single-pass extrusion blow molding.
EU Green Deal packaging-waste rules are mandating recyclability-by-design standards that disqualify multi-material acrylic laminates unless separable layers meet mono-material sorting thresholds. German converters are reformulating container grades to satisfy ECHA substance restrictions while maintaining optical clarity. French cosmetic distributors now require EPR-compliant packaging passports documenting polymer composition and recycling pathway.
Brand owners are consolidating supplier relationships around certified partners capable of simultaneous FDA, REACH, and MFDS documentation, displacing fragmented sourcing across regional converters. South Korean beauty conglomerates are qualifying single-source acrylic container vendors for global SKU harmonization. Procurement concentration is most visible in Guangdong and Gyeonggi-do provinces where integrated resin-to-container operations shorten qualification cycles.
Acrylic Container Market Segmentation
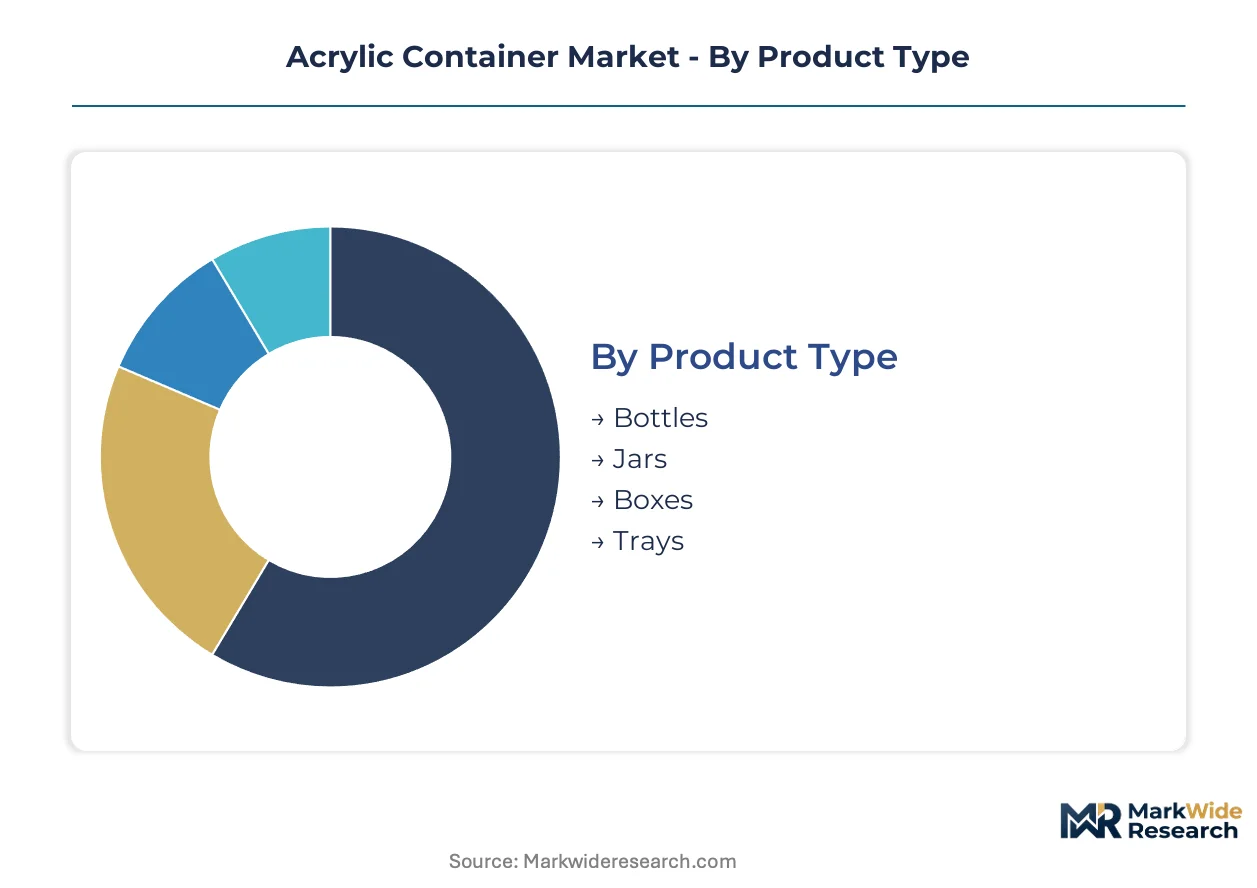
Acrylic container purchasing decisions hinge on regulatory compliance tiers, with FDA food-contact notification and REACH cosmetic-grade certification requirements varying sharply across product formats and end-use applications. Segmentation reveals how material purity standards, optical specifications, and breakage-risk tolerances reshape procurement priorities for brand owners and institutional buyers.
Product Type:
FDA food-contact notification applies to all storage formats entering US distribution, while REACH residual monomer limits govern cosmetic-facing bottles and jars bound for European markets.
- Bottles:Pump-dispenser and narrow-neck PMMA structures dominate premium skincare and fragrance packaging. Korean cosmetic houses in Seoul and Gyeonggi-do province specify these for essence and serum formats requiring twelve-month oxygen barrier performance. Certification burden concentrates on REACH compliance for EU-bound exports.
- Jars:Wide-mouth configurations serve thick-formula skincare and solid fragrance applications. Demand clusters in China's Guangdong injection-molding hubs serving both domestic brands and export orders. FDA notification requirements extend timelines for US-market entry.
- Boxes:Rigid PMMA enclosures for luxury gift sets and collectible packaging. Japanese retail display OEMs specify these for countertop presentation systems.
- Trays:Shallow-format containers for laboratory specimen organization and retail product arrangement. Academic research facilities in Germany and France convert glassware to these shatter-resistant alternatives.
Leading the category by volume: Bottles. Growing fastest: Jars.
End User:
Cost tiers separate institutional procurement with mandatory certification documentation from household purchasing where aesthetic preference dominates.
- Households:Direct-to-consumer storage and organization applications. Frosted and colored variants sell through mass-market retail channels in India and Southeast Asia where price sensitivity exceeds certification concerns.
- Retail:Point-of-sale display and premium packaging for cosmetics and electronics. South Korean beauty conglomerates consolidate supplier relationships around certified partners capable of simultaneous FDA, REACH, and MFDS documentation.
- Restaurants:Food-contact storage and presentation vessels. US operators face elevated testing costs to satisfy FDA notification requirements for acrylic containers entering commercial food service.
- Laboratories:Specimen storage, solvent-compatible containment, and shatter-resistant glassware replacement. Academic and clinical research facilities represent the steepest expansion trajectory as safety protocols mandate breakage-risk elimination.
Dominant by procurement value: Retail. Expanding most quickly: Laboratories.
Shape:
Manufacturing complexity and resin waste rates vary with geometric complexity, with polygonal formats commanding skilled technician availability scarce in emerging production regions.
- Round:Rotational symmetry minimizes injection-molding cycle times and enables uniform wall thickness. Guangdong cluster converters achieve lowest unit costs on these geometries for high-volume cosmetic packaging.
- Square:Maximized volumetric efficiency for retail shelf and laboratory rack storage. Straight edges demand precise mold temperature control to prevent warpage.
- Rectangular:Elongated profiles for document storage and drawer organization systems. German and French distributors require EPR-compliant packaging passports documenting polymer composition.
- Hexagonal:Premium cosmetic packaging differentiation with optical facet effects. Korean brands pilot these structures for limited-edition releases requiring batch-to-batch color consistency.
Highest production volume: Round. Gaining share fastest: Hexagonal.
Color:
Optical clarity specifications and pigment dispersion requirements determine which converters qualify for premium cosmetic and pharmaceutical contracts.
- Clear:Unpigmented PMMA with light transmission exceeding 92%. Evonik Industries supplies captive resin grades meeting pharmaceutical vial purity standards for temperature-sensitive biologics.
- Frosted:Surface-diffused finishes reducing glare and fingerprints. Skincare brands in Northern Europe specify these for refillable program compatibility where sustainability metrics outweigh full transparency.
- Colored:Pigmented formulations requiring batch-to-batch optical consistency. Color-matching expertise gaps constrain supplier qualification in India's emerging converter base.
- Transparent:Tinted clarity variants balancing visibility with brand color coding. Direct-to-container UV inkjet decoration enables lot-size-one personalization without label substrate costs.
Largest revenue share: Clear. Climbing the fastest: Frosted.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic brands in South Korea and laboratory procurement managers in Germany are concentrating demand for certified acrylic containers, while injection-molding clusters in China's Guangdong province capture export manufacturing volume. Regulatory divergence between FDA notification requirements and REACH substance restrictions is fragmenting supplier qualification pathways across jurisdictions.
United States
Food-contact storage and premium cosmetic packaging drive procurement from domestic brand owners and restaurant operators. FDA notification requirements for acrylic containers entering commercial distribution extend product launch timelines and elevate testing costs for cross-border suppliers. Thermoforming partnerships in Ohio and Kentucky anchor North American sheet-to-container conversion capacity.
Germany
Laboratory glassware replacement and EPR-compliant cosmetic packaging dominate institutional purchasing from academic research facilities and beauty distributors. ECHA substance restrictions under REACH limit residual monomer content, forcing converters to reformulate container grades while maintaining optical clarity. Industrial concentration in Baden-Württemberg and North Rhine-Westphalia hosts certified suppliers serving pan-European distribution.
China
Domestic cosmetic brands and export orders for Korean beauty conglomerates absorb output from injection-molding hubs. SAMR food-contact standards and evolving GB material purity rules govern local production, while dual carbon goals pressure converters toward energy-efficient processing. Guangdong province clusters achieve scale economies that compress lead times for premium packaging formats.
South Korea
Essence and serum packaging for K-beauty exports represents the steepest demand trajectory among global cosmetic markets. MFDS cosmetic-grade certification requirements run parallel to REACH and FDA documentation, rewarding single-source vendor consolidation. Gyeonggi-do province hosts integrated resin-to-container operations that shorten qualification cycles for global SKU harmonization.
India
Household storage and mass-market retail channels absorb frosted and colored variants where price sensitivity exceeds certification concerns. PLI scheme incentives for specialty chemicals could localize acrylic resin production and reduce import dependency for container converters. Maharashtra and Gujarat industrial corridors attract emerging converter investment despite color-matching expertise gaps.
Acrylic Container Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with laboratory procurement favoring certified specialists while cosmetic brands consolidate around integrated resin-to-container partners. The vendor base organizes into three strategic archetypes: captive resin producers controlling upstream methacrylate supply, sheet converters leveraging thermoforming partnerships, and injection-molding specialists serving high-volume cosmetic formats. Competitive moves concentrate on geographic expansion into certified supply corridors and portfolio diversification toward pharmaceutical-grade purity tiers.
Among Germany-based chemical conglomerates, Evonik Industries exemplifies the captive resin archetype through methacrylate monomer supply chain integration. Plaskolite LLC represents North American sheet-to-container conversion capacity anchored in thermoforming partnerships with display and storage OEMs. Shenzhen Jing Yue Acrylic Products Manufacturing occupies a position within Guangdong province injection-molding clusters serving export cosmetic packaging demand.
| Leading Market Players |
|---|
| Liberty Industries |
| Shenzhen Jing Yue Acrylic Products Manufacturing |
| Akrylix USA |
| Lucite International |
| Plaskolite LLC |
| Pioneer Plastics |
| Cleatech |
| Evonik Industries |
| Sunday Knight |
| Others |
Value Chain & Pricing Dynamics
Acetone-cyanohydrin feedstock volatility cascades through methacrylate monomer pricing into three distinct container-grade tiers, with Guangdong cluster converters capturing margin compression through scale economies while smaller specialists absorb resin cost spikes or exit REACH-certified grades entirely.
Pricing Analysis
Volume-mass cosmetic packaging commands thinner margins than pharmaceutical-grade vial formats despite higher throughput, with price differentiation driven by certification tier and optical clarity specifications. Three-tier pricing structure across premium, standard, and economy levels separates FDA-REACH-MFDS triple-certified suppliers from domestic-grade converters. Pricing pressure stems from methacrylate monomer feedstock volatility when petrochemical spreads widen. Mass-market household buyers in India and Southeast Asia exhibit highest price sensitivity, while South Korean beauty conglomerates prioritize batch-to-batch consistency over unit cost.
Supply Chain Analysis
Regional distribution centers in Guangdong province operate hub-and-spoke patterns serving Korean beauty exporters and domestic Chinese brands through consolidated injection-molding clusters. Manufacturing concentrates in China, South Korea, and Germany, with raw material dependencies on acetone, cyanohydrin, and methacrylate monomer supply. Single-source vulnerability in Evonik's captive methacrylate production creates concentration risk for container-grade resin. Distribution runs through brand-owner consolidated supplier relationships with integrated resin-to-container partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acrylic container supply is tightening around certified production corridors, with color-matching technician scarcity and dual-certification timelines propping pricing for qualified converters.
For Market Incumbents: Cement backward integration into methacrylate monomer supply or captive resin formulations to defend margin position against feedstock volatility. Expand Gyeonggi-do and Guangdong capacity to capture Korean beauty conglomerate consolidation. Lock in long-term offtake agreements with academic laboratory networks replacing glassware.
For New Entrants and Emerging Players: Pharmaceutical cold-chain logistics operators represent an underserved buyer archetype with unmet demand for temperature-sensitive biologic transport containers. Target Indian domestic manufacturing incentives under PLI schemes to localize resin production and bypass import dependency. Pursue direct-to-container UV inkjet decoration capabilities for limited-edition cosmetic personalization contracts.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap injection-molding specialists with existing REACH-FDA dual certification in Baden-Württemberg or North Rhine-Westphalia. Long-term viability hinges on pharmaceutical-grade purity tier migration as biopharma logistics networks expand. Watch for EPR-compliant packaging passport mandates accelerating supplier consolidation as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methacrylate Supply | Evonik's captive resin model demonstrates margin defense against acetone-cyanohydrin volatility. |
| Dual Certification Investment | Simultaneous FDA food-contact and REACH cosmetic-grade approvals unlock multinational brand procurement. |
| Pharmaceutical Cold Chain Expansion | Acrylic vial formats for temperature-sensitive biologics address unmet logistics network requirements. |
| Digital Printing Convergence | Direct-to-container UV inkjet enables lot-size-one personalization without label substrate costs for Korean beauty releases. |
| EPR-Compliant Packaging Passport | French and German distributor mandates accelerate supplier consolidation around certified partners. |
Study Parameters
Multi-period observation of methacrylate monomer pricing spreads, injection-molding capacity utilization in Guangdong, and certification timeline data anchored the trend analysis, supplemented by interviews with cosmetic packaging procurement managers, laboratory supply coordinators, resin plant operations directors, and regulatory affairs specialists at ECHA and FDA. Secondary validation drew from customs trade databases, SAMR food-contact standard filings, SEC 10-K disclosures from chemical conglomerates, and EU packaging-waste directive implementation reports. Bottom-up segment sizing triangulated against top-down macroeconomic demand modeling.
Input-output matrix framing connected feedstock price indices through resin formulation tiers to container-grade pricing, with segmentation across product format, end-use application, certification tier, and regional production hub. CAGRs were derived from regression analysis of historical volume trajectories against projected substitution rates for glassware in laboratory and cosmetic applications. Forecast inputs incorporated REACH substance restriction evolution timelines and Korean MFDS cosmetic-grade certification adoption curves.
Revisions become necessary when methacrylate monomer supply disruptions, abrupt regulatory divergence between FDA and ECHA frameworks, or breakthrough barrier-layer co-extrusion technologies materialize. Forecasts reflect documented assumptions on substitution elasticity and certification timeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Oblong Container Market
Containers
HDPE Crates Market
Containers
Thermoformed Containers Market
Containers
Steel Containers Market
Containers
Pocket Containers Market
Containers
Screw Top Jar Market
Containers
Composite Ibcs System Market
Containers
Asia and Africa Food Cans Market
Containers
ISO Ocean Containers Market
Containers
Laboratory Sample Container Market
Containers
Snap-Lock Container Market
Containers
Wooden Barrels Market
Containers
Soup Containers Market
Containers
Shipping Container Liners Market
Containers
Canisters Market
Containers
Oblong Tub Lids Market