
 Thin Wall Containers Market | 2026-2036
Thin Wall Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Wall Containers Market Analytics
Lightweighting through advanced thin-wall injection molding is tilting production economics toward higher cavitation tooling and faster cycle times. Plastipak Holdings, Inc. leverages captive PET resin operations to anchor cost positions across North American dairy and beverage accounts. Greiner Packaging International specializes in thermoformed polypropylene solutions for European fresh-food retail chains. Amcor plc extends global footprint through integrated design-to-recycle capabilities that navigate diverging national packaging regulations.
Thin wall containers are rigid packaging structures engineered with wall thickness below 0.8 millimeters, typically manufactured via high-speed injection molding or thermoforming to minimize material usage while preserving stack strength and barrier performance. Polypropylene dominates material selection for hot-fill and microwaveable applications due to thermal stability and hinge-flex durability. Food packaging leads end-user demand as retailers and foodservice operators pursue source reduction targets and lower per-unit logistics costs. Pharmaceutical packaging represents the fastest-expanding segment as unit-dose compliance packaging and blow-fill-seal integration drive precision thin-wall specifications.
FDA maintains strict food-contact notification requirements for recycled content in thin-wall structures, while EU REACH and F-Gas Regulation constrain certain blowing agents and additives used in foamed lightweight trays. China's SAMR enforces GB standards for food packaging migration limits that affect imported and domestically produced containers equally. Stakeholders must monitor evolving extended producer responsibility frameworks and material-specific recycling infrastructure investments to align portfolio decisions with compliance timelines and circular-economy mandates.
Market Dynamics
Thin-wall injection molding economics are compressing cycle times below three seconds while pushing cavitation counts past 128 cavities, forcing converters to choose between capital-intensive retooling or obsolescence.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory recycled-content quotas for food-contact packaging are accelerating investment in rPET and rPP purification infrastructure across German and French converter networks.
- Quick-service restaurant expansion:Cold-chain ready-meal formats in North America and Asia-Pacific are standardizing on thin-wall polypropylene clamshells for microwave-to-table convenience.
- High-speed thermoforming:Servo-driven trim-in-place systems are cutting per-unit conversion costs by eliminating secondary handling operations in European fresh-produce packaging.
Market Restraints
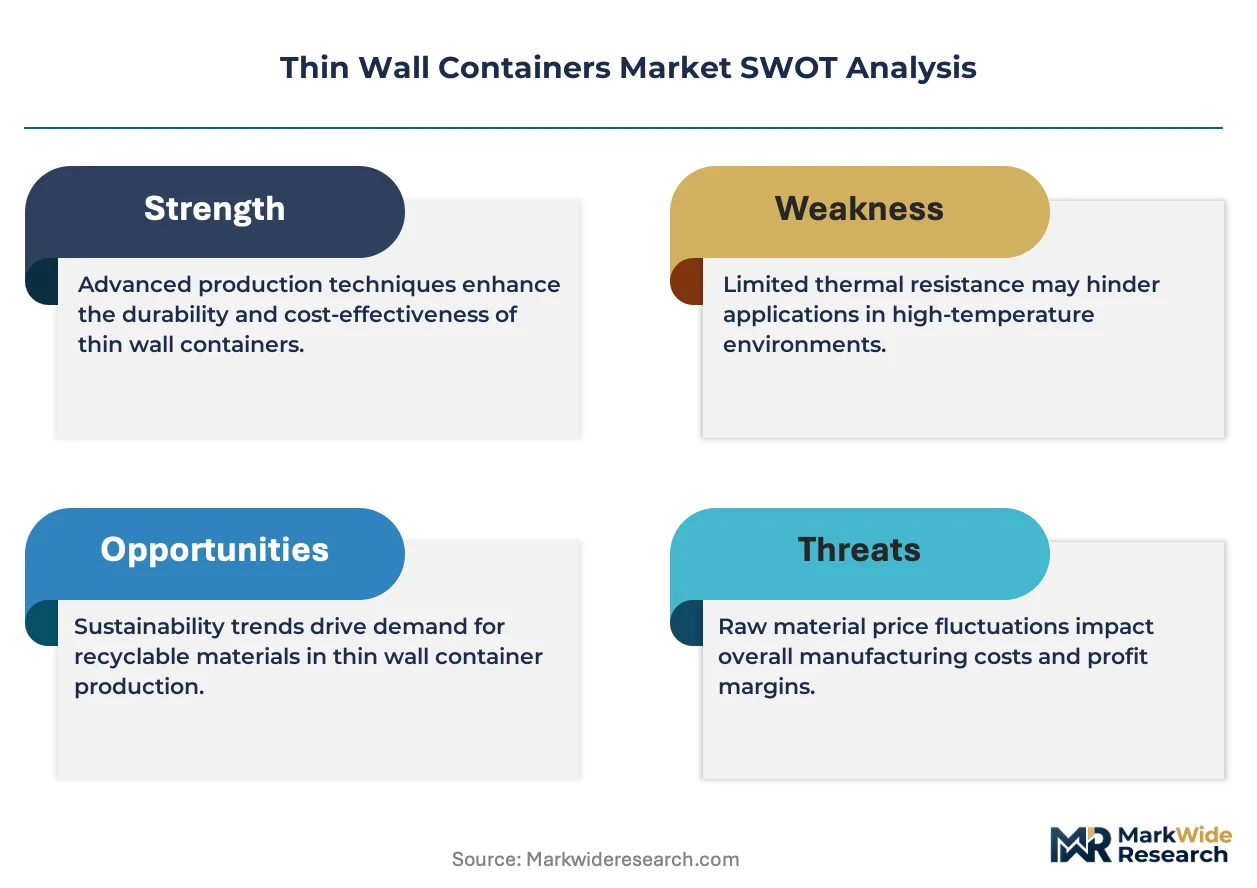
- Resin price volatility:Propylene feedstock fluctuations tied to naphtha cracking economics in Asia-Pacific create margin squeeze for non-integrated molders.
- Tooling supply concentration:Precision thin-wall mold fabrication concentrates among German and Austrian specialist shops, extending lead times to 20-26 weeks.
- Barrier performance ceilings:Sub-0.6mm polypropylene walls cannot achieve oxygen transmission rates below 0.5 cc/m²/day without metallization or coating add-ons.
Strategic Opportunities
- Indian organized retail penetration:Modern trade formats in Mumbai and Delhi are adopting pre-packed fresh produce, creating first-mover openings for thermoformed tray suppliers.
- Pharmaceutical unit-dose compliance:Blow-fill-seal integration with thin-wall ampoules is expanding in Japanese and South Korean sterile manufacturing facilities.
- Extended producer responsibility frameworks:Germany's Verpackungsgesetz and France's AGEC law are creating premium pricing corridors for design-for-recycling certified containers.
Industry Challenges
- Multi-cavity mold commissioning:Balancing fill patterns across 96+ cavity layouts requires specialized rheology expertise that outstrips regional workforce development pipelines.
- Food-contact notification timelines:FDA's 120-day review window for novel recycled-content structures delays product launches and freezes inventory positions.
- Legacy sorting infrastructure:Near-infrared detection systems at European material recovery facilities misclassify thin-wall polypropylene as film, diverting recyclable streams to energy recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Wall Containers Market |
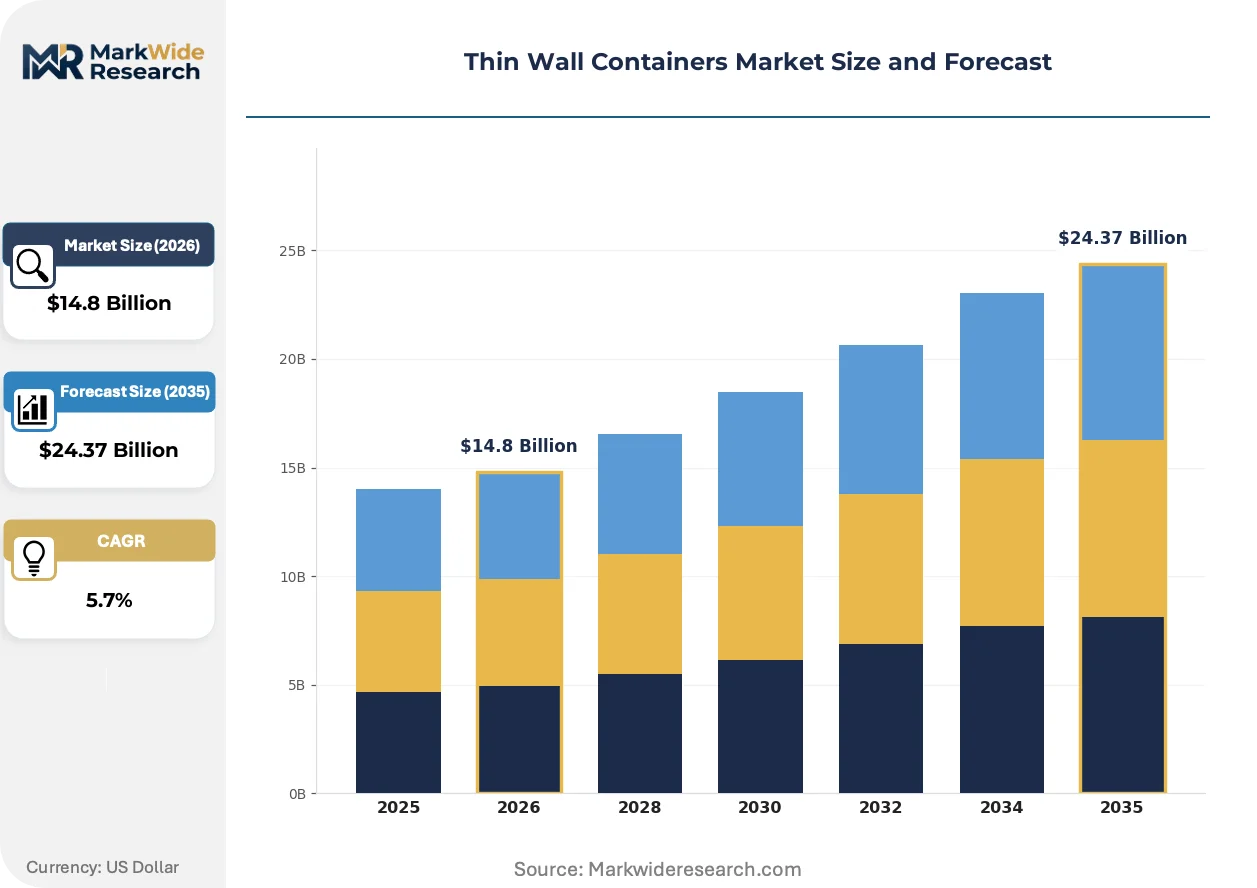
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Containers, Paper Containers, Aluminum Containers, Glass Containers End User: Food Packaging, Beverage Packaging, Cosmetic Packaging, Pharmaceutical Packaging Material: Polypropylene, Polystyrene, PET, PLA Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | Plastipak Holdings, Inc., Greiner Packaging International, Amcor plc, Graham Packaging Company, PACCOR GmbH, Berry Global Inc., ALPLA, Huhtamaki Oyj, Silgan Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Wall Containers Market Evolving Landscape
Material science breakthroughs and regulatory pressure on circularity are converging to redefine performance specifications and recovery economics for thin-wall packaging architectures.
Barrier-coated thin-wall polypropylene is hybridizing oxygen scavenging with passive EVOH lamination to extend shelf life in modified-atmosphere meat trays. North American protein processors are piloting these structures for case-ready retail formats. The technology is hybridizing commodity resin economics with high-performance barrier specifications previously reserved for multilayer structures.
EU F-Gas Regulation phase-down schedules are eliminating HFC blowing agents from foamed lightweight tray production by 2030. Thermoformers are retrofitting extrusion lines for CO₂ and hydrocarbon alternatives, absorbing capital costs of €2-4 million per facility. Italian and Spanish fresh-produce packers face the steepest compliance curves due to reliance on PS foam substitution programs.
Consolidated buying by quick-service restaurant chains is compressing supplier qualification cycles from 18 months to 8-10 months. Procurement teams at major North American operators now mandate design-for-recycle scores and post-consumer content certificates as gate criteria. This pattern is most pronounced in poultry and salad bowl categories where switching costs between qualified molders remain minimal.
Thin Wall Containers Market Segmentation
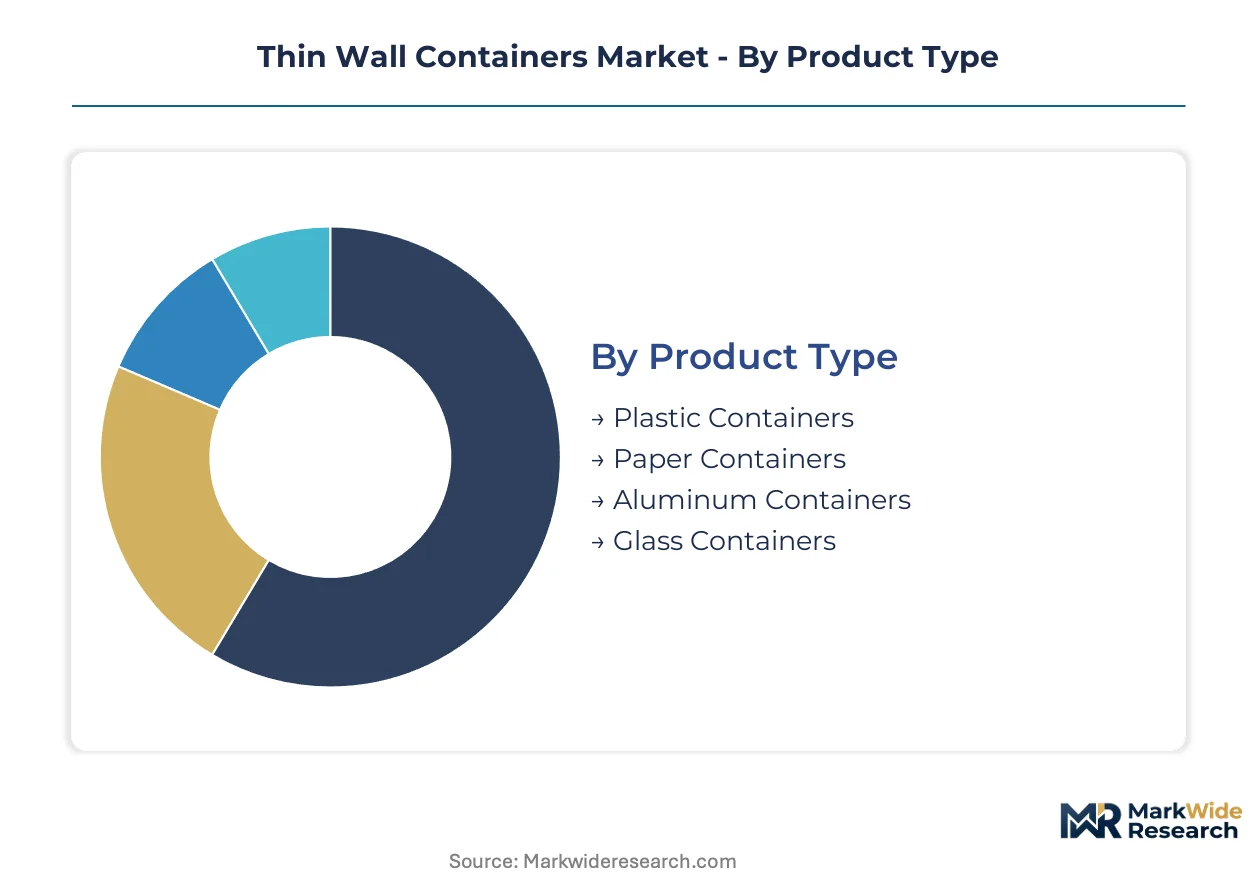
Thin wall containers demand fragments across material technologies, end-use specifications, and channel economics. Each dimension carries distinct margin profiles, tooling requirements, and regulatory exposure that shape supplier positioning.
Product Type:
Cost tier separation between commodity and engineered substrates determines converter capital allocation and customer switching thresholds.
- Plastic Containers:Polypropylene and PET structures dominate through sub-0.8mm injection molding cycles below three seconds. Quick-service restaurant chains in the United States and Germany standardize on these formats for cold-chain ready meals, though EU Single-Use Plastics Directive recycled-content mandates are forcing rPET purification investments.
- Paper Containers:Barrier-coated fiberboard solutions address fresh-produce retail in European supermarkets seeking plastic reduction credentials. Italian and Spanish packers face steep compliance curves as F-Gas Regulation eliminates HFC blowing agents from competing foam alternatives by 2030.
- Aluminum Containers:Rolled alloy trays serve premium ready-meal segments requiring oven-to-table thermal conductivity.
- Glass Containers:Thin-wall borosilicate structures retain niche pharmaceutical and cosmetic applications where chemical inertness outweighs weight penalties.
Plastic containers command the established base. The steepest expansion runs through paper containers.
End User:
Application-specific performance requirements create divergent specification corridors across barrier needs, sterilization tolerance, and consumer interaction patterns.
- Food Packaging:Modified-atmosphere meat trays and microwaveable clamshells absorb the majority of thin-wall polypropylene volume. North American protein processors pilot barrier-coated structures extending shelf life without metallization, while Japanese convenience retailers specify hinge-flex durability for repeated open-close cycles.
- Pharmaceutical Packaging:Blow-fill-seal integration with thin-wall ampoules is climbing fastest. South Korean and Japanese sterile manufacturing facilities drive precision specifications below 0.6mm wall thickness for unit-dose compliance packaging, though FDA's 120-day food-contact notification timelines delay recycled-content launches.
- Beverage Packaging:Cold-fill dairy and juice applications favor PET clarity and drop resistance over thermal performance.
- Cosmetic Packaging:Aesthetic surface finish requirements favor thermoformed polystyrene and PETG for premium personal care lines.
Food packaging anchors volume throughput. Pharmaceutical packaging is gaining share fastest.
Material:
Polymer selection trades thermal stability, barrier performance, and recycling infrastructure compatibility against resin cost volatility.
- Polypropylene:Dominates hot-fill and microwaveable segments through thermal stability above 120°C and hinge-flex durability. German and French converter networks are accelerating rPP purification investments to meet EU Single-Use Plastics Directive quotas, though propylene feedstock fluctuations tied to Asian naphtha cracking squeeze non-integrated molders.
- PET:Captive resin operations anchor cost positions for North American dairy and beverage accounts. China's SAMR enforces GB standards for migration limits that constrain both imported and domestically produced structures.
- Polystyrene:Remains entrenched in fresh-produce thermoforming despite foam substitution pressures in Italian and Spanish markets.
- PLA:Biopolymer solutions target composting infrastructure corridors in France and Germany where extended producer responsibility frameworks create premium pricing for certified circular materials.
Polypropylene holds the incumbent position. PET is expanding most quickly.
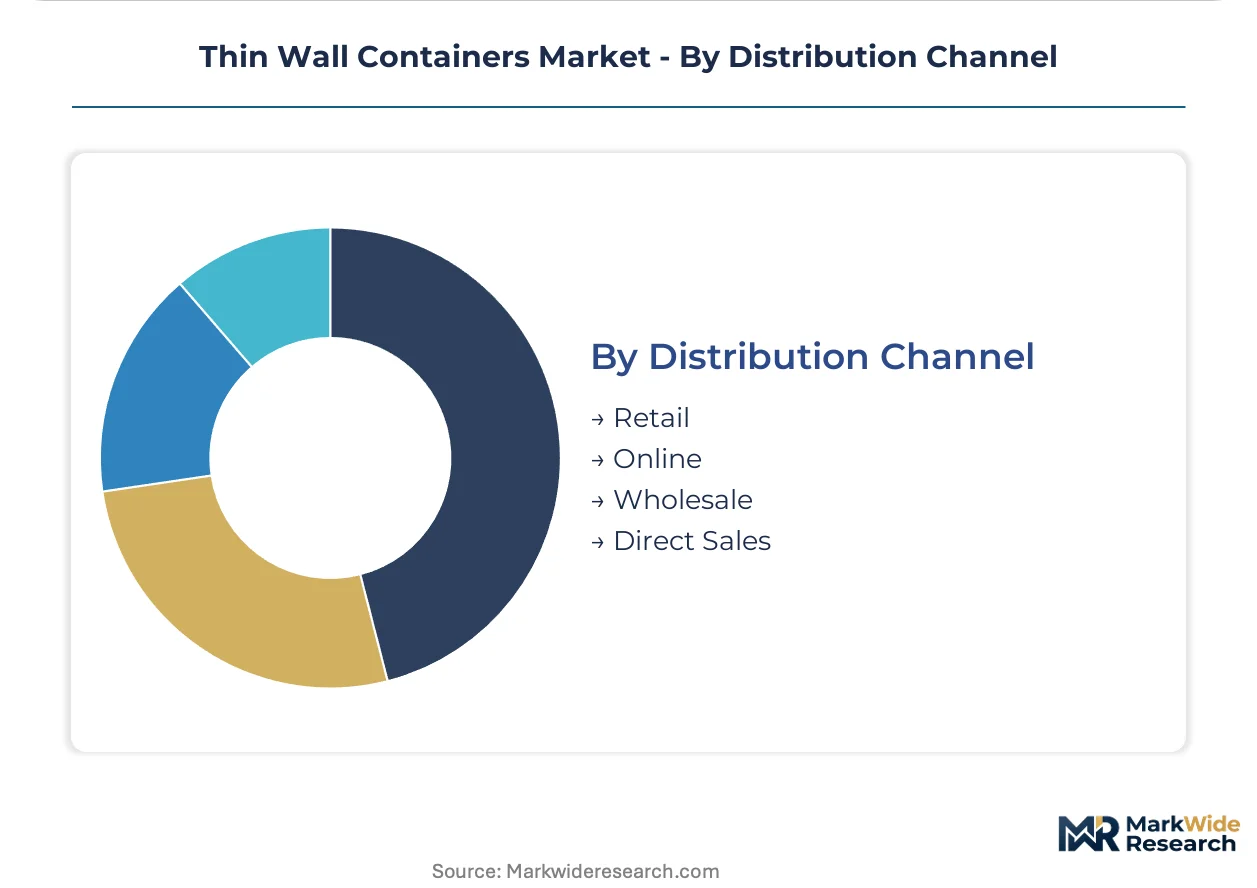
Distribution Channel:
Customer type and order scale determine service model economics from stock keeping to custom tooling amortization.
- Direct Sales:Quick-service restaurant chains and protein processors negotiate multi-year supply agreements with dedicated cavitation commitments. Procurement teams now mandate design-for-recycle scores and post-consumer content certificates as gate criteria, compressing supplier qualification cycles from 18 months to 8-10 months.
- Wholesale:Converter-to-distributor relationships serve mid-tier foodservice operators lacking volume for direct mold investment.
- Retail:Stock-keeping programs for standard tray and clamshell formats support smaller fresh-produce packers.
- Online:Digital procurement platforms are emerging for specification-heavy pharmaceutical and cosmetic segments requiring rapid sample turnaround.
Direct sales captures the largest contract value. Online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant chains and organized retail buyers concentrate procurement decisions in Germany, China, and the United States, where converter investments in thin-wall injection molding capacity are accelerating. Each geography presents distinct regulatory compliance curves and infrastructure maturity levels that shape supplier qualification timelines.
Germany
Fresh-food retail chains and dairy processors drive thermoformed polypropylene demand across Bavaria and North Rhine-Westphalia. The Verpackungsgesetz mandates minimum recycled-content thresholds that force rPP purification investments at converter networks near Stuttgart. German specialist mold fabricators in Baden-Württemberg extend lead times to 20-26 weeks due to precision tooling concentration.
China
Quick-service restaurant expansion in Shanghai and Beijing standardizes microwaveable clamshell formats for cold-chain ready meals. SAMR enforces GB standards for food packaging migration limits that constrain both imported and domestically produced containers. Yangtze River Delta converters accelerate high-cavitation tooling deployment to capture quick-serve procurement contracts.
United States
Protein processors and poultry packers pilot barrier-coated structures for case-ready retail formats across the Midwest and Southeast. FDA maintains 120-day food-contact notification requirements for recycled-content structures that delay product launches. Texas and Illinois host the densest thin-wall injection molding clusters serving national quick-service chains.
India
Modern trade formats in Mumbai and Delhi adopt pre-packed fresh produce, creating first-mover openings for thermoformed tray suppliers. FSSAI regulations on food-contact materials are tightening compliance requirements for imported substrate qualifications. Maharashtra and Gujarat converter investments target organized retail penetration with servo-driven trim-in-place thermoforming systems.
Japan
Convenience retailers specify hinge-flex durability for repeated open-close cycles in Tokyo and Osaka metropolitan markets. METI guidelines on plastic resource circulation accelerate design-for-recycle certification requirements. South Korean and Japanese sterile manufacturing facilities drive precision thin-wall specifications below 0.6mm for pharmaceutical unit-dose compliance packaging.
Thin Wall Containers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships that favor scale-driven molders with captive resin positions or design-to-recycle certification capabilities. The vendor base clusters around three strategic archetypes: integrated resin-to-container operators, precision tooling specialists with dedicated cavitation commitments, and regional thermoformers serving fresh-produce retail. Consolidated buying by quick-service chains compresses supplier qualification cycles, while multi-cavity mold commissioning requirements filter out undercapitalized entrants. M&A activity targets rPET and rPP purification assets, and capacity expansion concentrates in Germany, China, and the United States.
Among North American integrated operators, Plastipak Holdings, Inc. and Berry Global Inc. exemplify the resin-anchored archetype. Greiner Packaging International and PACCOR GmbH represent European thermoforming specialists with concentrated fresh-food retail exposure. Amcor plc occupies a position spanning both geographies with integrated design-to-recycle capabilities.
| Leading Market Players |
|---|
| Plastipak Holdings, Inc. |
| Greiner Packaging International |
| Amcor plc |
| Graham Packaging Company |
| PACCOR GmbH |
| Berry Global Inc. |
| ALPLA |
| Huhtamaki Oyj |
| Silgan Holdings Inc. |
| Others |
Value Network & Pricing Analysis
Propylene feedstock volatility tied to Asian naphtha cracking economics determines both pricing tier spreads and supply chain shape across thin-wall container markets, compressing margins for non-integrated molders while rewarding converters with captive resin positions.
Pricing Analysis
Cost-plus contracts with propylene indexation dominate converter-buyer agreements, linking unit prices to regional naphtha benchmarks with quarterly adjustments. Price differentiation rests on rPP certification grade and volume scale, with EU Single-Use Plastics Directive compliance commanding premium positioning. Cost compression in commodity polypropylene tiers is intensifying because quick-service restaurant procurement teams now mandate post-consumer content certificates as gate criteria. Mid-tier foodservice operators show highest price sensitivity, while pharmaceutical unit-dose packers prioritize barrier performance over per-unit cost.
Supply Chain Analysis
Contract manufacturing capacity concentrates among German and Austrian precision mold fabricators, with Baden-Württemberg specialist shops extending fabrication lead times. Raw material flows draw from Saudi and South Korean propylene crackers, Belgian PET resin operations, and Chinese additive compounders. Single-source vulnerability runs through precision multi-cavity tooling, where 96+ cavity layouts require specialized rheology expertise that outstrips regional workforce pipelines. Distribution runs through direct sales agreements with dedicated cavitation commitments for quick-service chains, supplemented by wholesale channels serving mid-tier foodservice operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-wall container markets present a service-attach opportunity as design-for-recycle certification and rPP purification infrastructure generate recurring revenue streams expanding faster than base container hardware.
For Market Incumbents: Harden rPP purification capabilities to defend against emerging European converters with EU Single-Use Plastics Directive compliance advantages. Lock in dedicated cavitation commitments from quick-service restaurant chains before procurement qualification cycles compress further. Backward integration into propylene feedstock hedges margin exposure to Asian naphtha volatility. For New Entrants and Emerging Players: Indian organized retail penetration in Mumbai and Delhi offers first-mover openings for thermoformed tray suppliers with servo-driven trim-in-place systems. Target pharmaceutical unit-dose compliance packaging in South Korean and Japanese sterile manufacturing facilities, where precision specifications below 0.6mm wall thickness filter out commodity molders. Lead with design-for-recycle certification to bypass legacy supplier relationships. For Investors and Strategic Acquirers: rPET and rPP purification assets with EU food-contact notification clearance represent the most defensible acquisition targets across the thin-wall container value chain. Long-term viability centers on circular-economy infrastructure positioning rather than commodity molding scale. Monitor FDA recycled-content notification approval velocities as inflection indicator for rPP market timing.| Strategic Initiative | Industry Significance |
|---|---|
| rPP Purification Capacity Expansion | Verpackungsgesetz compliance secures premium pricing corridors in German retail chains. |
| High-Cavitation Tooling Deployment | 128+ cavity layouts capture quick-service procurement contracts in Yangtze River Delta. |
| Barrier-Coating Technology Licensing | EVOH lamination partnerships extend shelf life for North American protein processors. |
| Design-for-Recycle Certification Program | AGEC law alignment unlocks French premium produce packaging segments. |
| Blow-Fill-Seal Integration Partnership | Japanese sterile manufacturing facilities demand precision thin-wall ampoule specifications. |
Research Methodology
The analysis maps injection molding, thermoforming, and blow-fill-seal sub-sectors, each validated through converter operations directors, quick-service restaurant procurement leads, pharmaceutical packaging engineers, and retail category buyers. Primary interview findings triangulate against customs trade data, FDA food-contact notification filings, EU REACH substance registrations, and SEC 10-K disclosures from integrated resin-to-container operators. Bottom-up capacity modeling and top-down demand estimation cross-validate volume projections.
Assumptions hold EU Single-Use Plastics Directive recycled-content quotas and FDA notification timelines within observed regulatory trajectories, while propylene feedstock spreads and quick-service restaurant expansion rates vary across sensitivity scenarios. Segmentation dimensions include material technology, end-use specification, and regional production hub. CAGRs derive from installed tooling capacity growth correlated with converter capital expenditure disclosures and foodservice operator procurement pipeline visibility.
The forecast holds incumbent behavior within observed patterns; aggressive rPP purification investments by Middle Eastern resin producers or accelerated F-Gas Regulation phase-downs would shift outcomes. Quarterly review of FDA notification approval velocities, German Verpackungsgesetz enforcement actions, and quick-service restaurant supplier qualification cycle durations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Disposable Cups and Lids Market
Containers
Popcorn Containers Market
Containers
Jerry Cans Market
Containers
Trays Market
Containers
Lever Lid Cans Market
Containers
Oblong Tub Lids Market
Containers
North America Plastic Bottles and Containers Market
Containers
HDPE Crates Market
Containers
Wooden Crates Market
Containers
Insert Trays Market
Containers
Trigger Sprayer Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
PVC Container Market
Containers
Container Fixed Fittings Market
Containers
Metal Crates Market
Containers
PET Containers Market