
 Screw Top Lids Market | 2026-2036
Screw Top Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Screw Top Lids Market Analytics
ISO 15378 certification for primary packaging materials is reorganizing competitive entry in pharmaceutical-grade closures. Berry Global Inc. leverages captive resin compounding and blow-molding integration across North American beverage plants. Silgan Holdings Inc. anchors its position through metal closure dominance in food canning, while Amcor plc competes via multi-material platform breadth spanning tamper-evident and child-resistant formats.
Screw top lids are threaded closure devices manufactured from plastic, metal, or composite substrates with specified torque-release profiles, designed to seal containers against contamination, oxidation, and leakage across liquid and semi-solid contents. Metal screw caps retain cost advantages in carbonated beverage and preserved food applications where oxygen ingress thresholds demand sub-1 cc annual transmission rates. Plastic closures lead volume in pharmaceutical and cosmetics end uses where child-resistant and tamper-evident mechanisms integrate molded-in band break features. Composite formats represent the fastest-growing material category as brand owners pursue lightweighting targets without sacrificing thread integrity or capping line speed compatibility.
FDA 21 CFR Part 177 indirect food additive regulations and EMA Annex 1 sterile manufacturing guidelines jointly determine material migration limits and closure validation protocols for pharmaceutical and food contact applications. EU MDR and REACH substance restrictions further constrain plasticizer and colorant selection in medical and cosmetic packaging. Stakeholders must monitor evolving extended producer responsibility frameworks in California and the EU, where post-consumer recycled content mandates are restructuring resin sourcing strategies and tooling investments for closure molds.
Market Dynamics
Post-consumer recycled content mandates in California and the EU are forcing resin sourcing strategies and tooling investments for closure molds, restructuring competitive economics across pharmaceutical and beverage packaging tiers.
Growth Catalysts
- EMA Annex 1 sterile manufacturing guidelines:Pharmaceutical manufacturers in Germany and Switzerland are validating closure integrity systems for biologics packaging, accelerating demand for high-performance screw top formats with validated torque-release profiles.
- Lightweighting targets in beverage packaging:Brand owners specify composite substrates that maintain thread integrity at reduced mass, pulling investment into multi-layer co-injection molding capabilities across closure manufacturing facilities.
- Child-resistant mechanism integration:Cosmetics and OTC pharmaceutical brands require molded-in band break features that comply with ISO 8317 testing protocols, expanding addressable volume in personal care segments.
Market Restraints
- Aluminum sheet supply concentration:Metal closure producers depend on smelter capacity in Norway and Iceland where energy cost volatility transmits directly into input pricing for carbonated beverage caps.
- REACH substance restrictions on plasticizers:ECHA constraints on phthalate alternatives limit formulation flexibility for polypropylene closures in medical device packaging, compressing margin on certified grades.
- Oxygen ingress thresholds in wine packaging:Sub-1 cc annual transmission specifications for premium spirits favor cork and synthetic stopper substitutes, constraining screw cap penetration in aged product categories.
Strategic Opportunities
- Extended producer responsibility frameworks:EU Green Deal packaging regulations mandate minimum recycled content thresholds, creating first-mover advantage for closure molders with in-house regrind processing and closed-loop collection partnerships.
- Smart closure integration:NFC-enabled tamper-evident bands that authenticate product provenance are converging with mobile payment infrastructure in Asian beverage markets, opening premium pricing tiers.
- Biologics cold-chain expansion:Cryogenic storage requirements for cell therapies in the US and Switzerland demand specialized closure materials that maintain seal integrity across thermal cycling, representing unpenetrated specification space.
Industry Challenges
- ISO 15378 certification timelines:Pharmaceutical-grade closure validation requires 18-24 month qualification cycles with documented batch consistency, constraining speed-to-market for new resin formulations.
- Multi-material separation in recycling streams:Composite closures with metalized bands complicate automated sorting infrastructure, forcing redesign investments to maintain compatibility with emerging chemical recycling technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screw Top Lids Market |
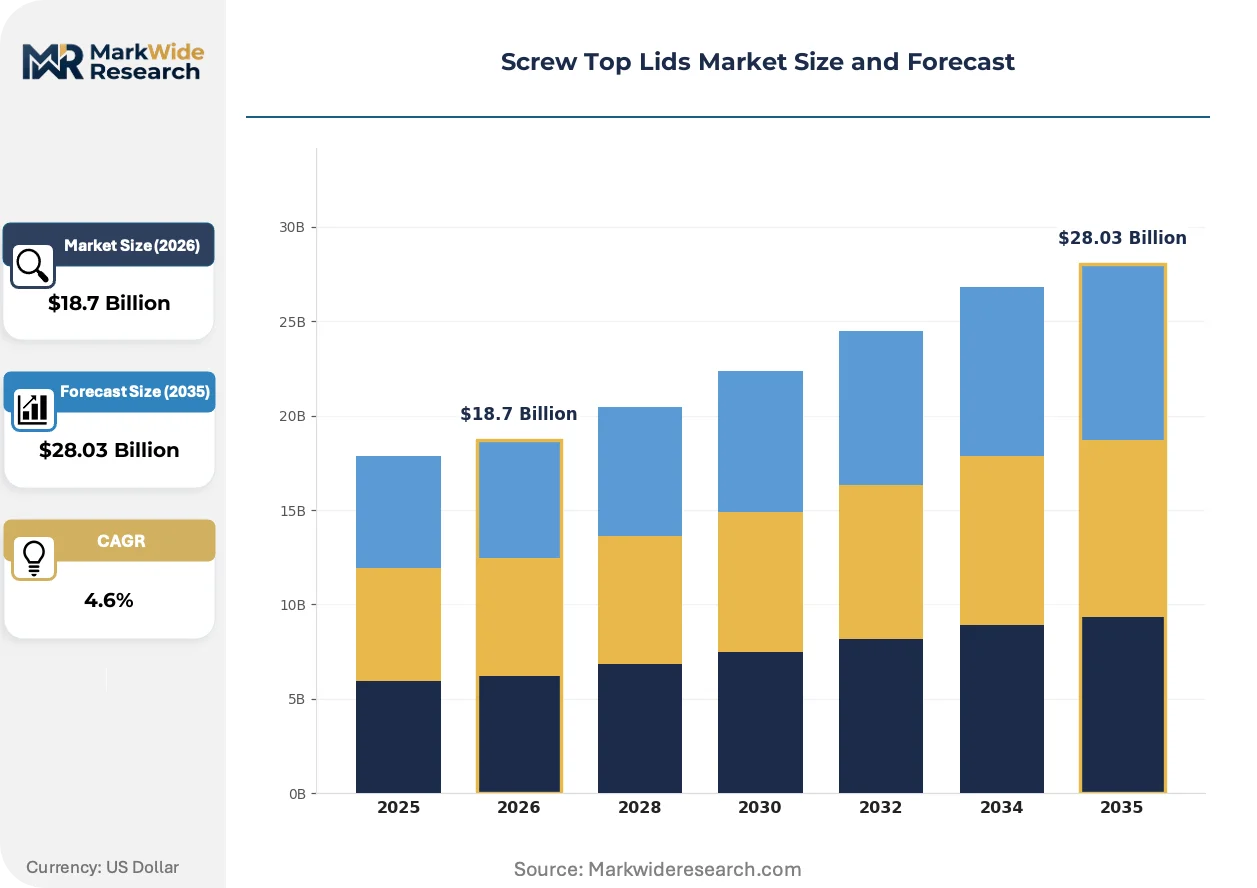
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Metal, Glass, Composite Closure Mechanism: Screw Cap, Twist-off Cap, Child-resistant Cap, Tamper-evident Cap End Use: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Size: Small, Medium, Large, Custom |
| Companies Covered | SKS Bottle and Packaging, Inc, Rayware Limited, PacZone Limited, Ardagh Group S.A, Verallia, Berry Global Inc., Silgan Holdings Inc., Amcor plc, Closure Systems International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screw Top Lids Market Evolving Landscape
Closure manufacturing is pivoting from commodity volume toward specification-driven differentiation, with material science and digital traceability converging to redefine value capture across pharmaceutical and premium beverage segments.
Mono-material polyolefin designs with integrated desiccant functionality are bifurcating moisture-sensitive pharmaceutical packaging from traditional two-component assemblies. Generic drug manufacturers in India and contract packaging organizations in the US are specifying these formats for humidity-critical solid dose products. The technology is compressing assembly steps while complicating resin selection to maintain child-resistant performance.
REACH Annex XVII restrictions on intentionally added microplastics are compelling European cosmetics brands to eliminate thermoset sealants from metal closures. The regulation forces redesign of lug-style caps toward all-thermoplastic threaded formats with molded-in compression seals. Premium skincare brands in France and Germany are responding with accelerated validation timelines for alternative sealing geometries.
Direct-to-consumer wine subscription channels are compressing closure selection cycles from annual harvest negotiations to quarterly SKU rotations. California and Oregon wineries are specifying screw caps with customizable printing for limited releases, displacing traditional cork-dominated procurement. This pattern concentrates volume with closure suppliers offering digital decoration and rapid changeover capabilities.
Screw Top Lids Market Segmentation
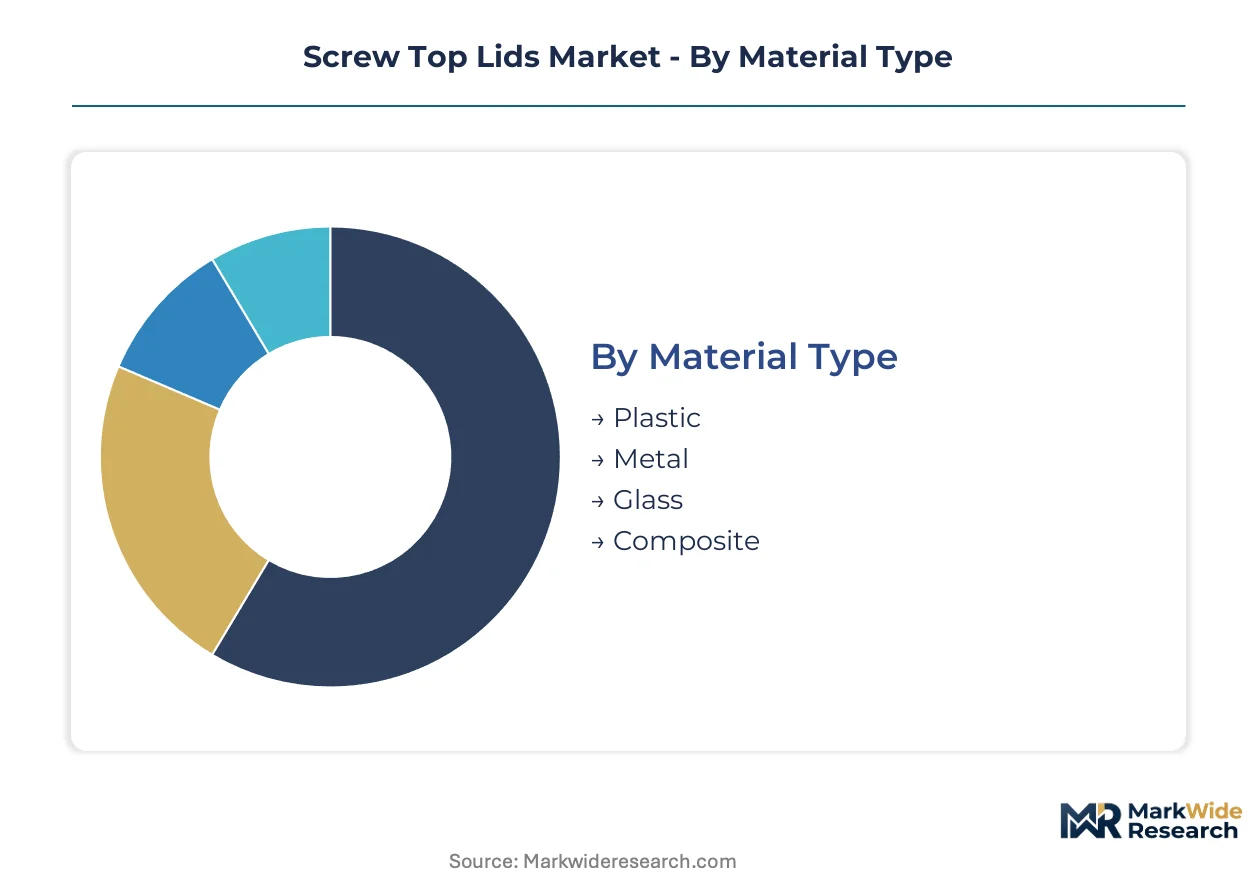
Screw top lids serve divergent performance requirements across pharmaceutical sterility, beverage carbonation retention, and chemical containment. Material selection and closure mechanism design directly determine regulatory compliance pathways and manufacturing capital intensity for molders and metal formers.
Material Type:
Domestic production dominates metal and glass closure supply, while plastic and composite formats rely heavily on export-oriented manufacturing clusters in Germany and Switzerland serving pharmaceutical certification requirements.
- Plastic:Polypropylene and polyethylene terephthalate formulations dominate pharmaceutical and cosmetics applications where child-resistant torque-release mechanisms integrate molded-in band breaks. Demand concentrates in German pharmaceutical packaging facilities validating ISO 15378 compliance for biologics containment.
- Metal:Aluminum and tinplate screw caps retain cost advantages in carbonated beverage and preserved food segments requiring sub-1 cc annual oxygen ingress thresholds. Production gravity centers on Norwegian and Icelandic smelter supply serving European beverage canning lines.
- Glass:Borosilicate and soda-lime threaded closures serve premium spirits and laboratory chemical containment where inertness outweighs fragility concerns.
- Composite:Multi-layer substrates combining polymer cores with metalized barriers address lightweighting mandates without sacrificing thread integrity or capping line speed compatibility.
Metal commands the established base in beverage volume. The steepest expansion runs through composite formats as brand owners pursue mass reduction targets.
Closure Mechanism:
Mechanism selection correlates directly with end-use regulatory tier — food contact permits simpler screw formats while pharmaceuticals mandate multi-feature compliance architectures.
- Screw Cap:Standard threaded formats with specified torque-release profiles seal against contamination and leakage across liquid and semi-solid contents. Generic drug manufacturers in India specify these for cost-sensitive solid dose packaging.
- Twist-off Cap:Lug-style mechanisms enable single-motion opening while maintaining reseal integrity for condiments and sauces.
- Child-resistant Cap:Push-and-turn or squeeze-and-turn mechanisms complying with ISO 8317 testing protocols dominate OTC pharmaceutical and household chemical segments. US FDA protocol compliance drives specification rigor.
- Tamper-evident Cap:Molded breakaway bands or shrink-sleeve integrations provide visual integrity confirmation for pharmaceuticals and premium beverages. EMA Annex 1 sterile manufacturing guidelines accelerate validation demand for biologics applications.
Screw caps anchor commodity volume across food and beverage tiers. Child-resistant mechanisms are climbing the fastest as OTC pharmaceutical brands expand compliance coverage.
End Use:
Application-driven procurement patterns separate high-volume beverage negotiations from specification-intensive pharmaceutical qualification cycles.
- Food & Beverage:Carbonated soft drinks, preserved foods, and wine packaging drive metal closure demand while premium spirits test composite alternatives. California and Oregon wineries specify screw caps with digital decoration for direct-to-consumer subscription channels.
- Pharmaceuticals:Solid dose and biologics packaging require ISO 15378 certified closures with validated batch consistency. German and Swiss manufacturers are validating closure integrity systems for cold-chain cell therapies.
- Cosmetics:Premium skincare brands in France and Germany are eliminating thermoset sealants from metal closures per REACH Annex XVII microplastic restrictions, accelerating all-thermoplastic threaded format adoption.
- Chemicals:Industrial and laboratory containment applications specify chemically inert glass or fluoropolymer-lined closures for aggressive solvents.
Food and beverage retains volume leadership. Pharmaceuticals are gaining share fastest as biologics cold-chain expansion creates specification premiums.
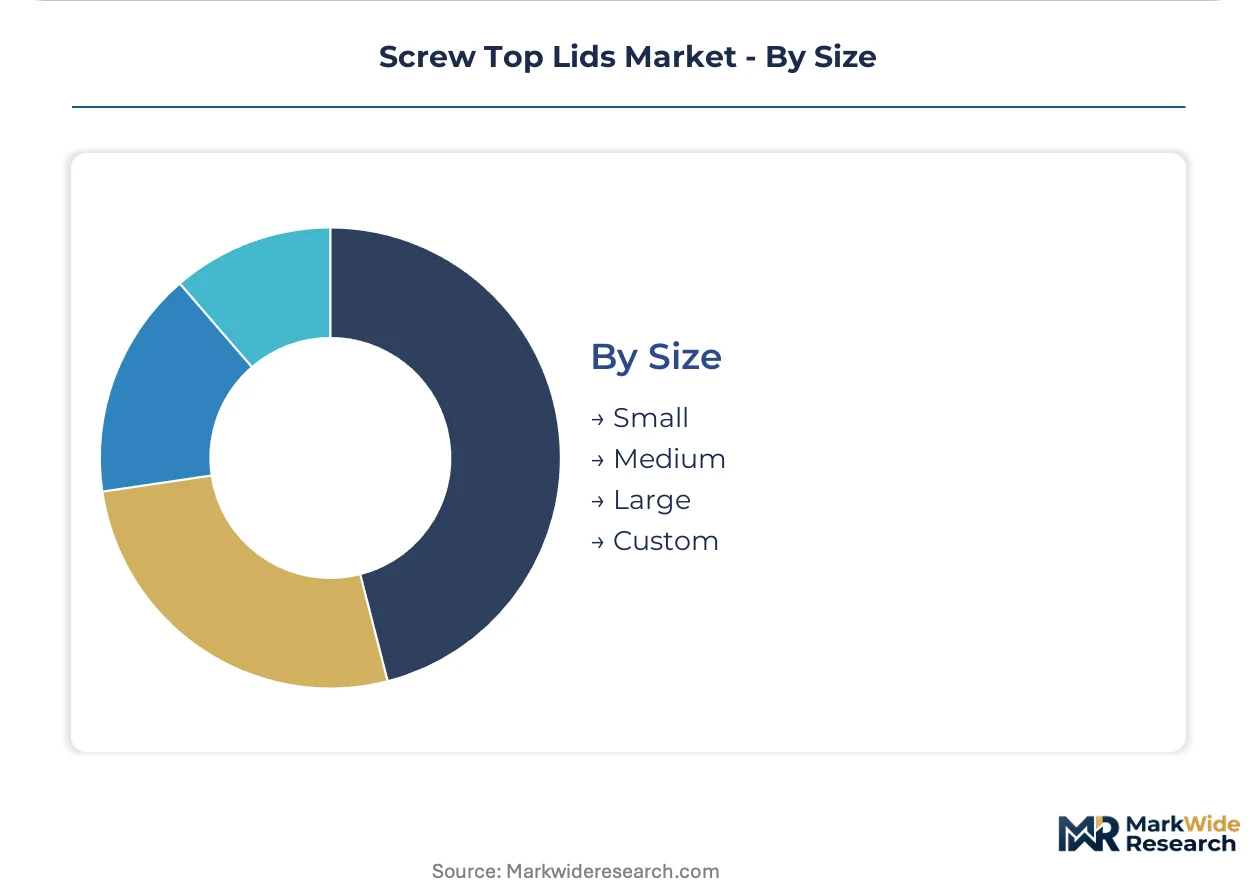
Size:
Dimensional standardization versus customization tension reflects the trade-off between mold amortization efficiency and brand differentiation requirements.
- Small:Diameter ranges under 28mm serve single-serve pharmaceuticals, cosmetics samples, and airline beverage portions.
- Medium:28-38mm formats dominate standard beverage and pharmaceutical bottles, capturing economies of scale in high-volume capping equipment.
- Large:Diameters exceeding 38mm accommodate wide-mouth jars for food spreads and industrial chemical containment.
- Custom:Proprietary thread profiles and non-standard diameters enable brand differentiation and tamper-resistance through supply exclusivity.
Medium sizes command the established base in standardized bottling infrastructure. Custom formats are expanding most quickly as premium brands pursue proprietary closure differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage bottlers and pharmaceutical contract manufacturers concentrate procurement authority in Germany, the United States, and Switzerland, with secondary demand clusters emerging in France and India as local production scales to serve regional formulation and packaging operations.
Germany
Ardagh Group and Berry Global operate major closure manufacturing facilities serving premium spirits and pharmaceutical brands. EMA Annex 1 sterile manufacturing guidelines drive validation demand for high-performance screw top formats with documented torque-release profiles. The Rhine-Ruhr industrial corridor hosts concentrated blow-molding and resin compounding capacity for ISO 15378 certified pharmaceutical closures.
United States
FDA 21 CFR Part 177 indirect food additive regulations determine material migration limits for beverage and food contact applications. California's extended producer responsibility frameworks mandate post-consumer recycled content thresholds, restructuring resin sourcing strategies for closure molds. The Pacific Northwest wine corridor specifies screw caps with digital decoration for direct-to-consumer subscription channels.
Switzerland
Swissmedic protocols govern closure validation for biologics and cell therapy packaging, accelerating demand for cryogenic storage compatible formats. Cold-chain expansion for regenerative medicines demands specialized closure materials maintaining seal integrity across thermal cycling. Basel and Zurich host concentrated pharmaceutical packaging validation laboratories serving global biologics manufacturers.
France
REACH Annex XVII restrictions on intentionally added microplastics compel cosmetics brands to eliminate thermoset sealants from metal closures. ANSM pharmaceutical packaging guidelines align with EMA standards for sterile manufacturing closure integrity. The Île-de-France region concentrates premium skincare brand headquarters accelerating all-thermoplastic threaded format adoption.
India
CDSCO pharmaceutical packaging regulations converge with WHO prequalification standards for generic drug export markets. BIS standards for food contact materials govern domestic beverage closure specifications. Maharashtra and Gujarat host expanding blow-molding capacity serving cost-sensitive solid dose pharmaceutical packaging demand.
Screw Top Lids Market Competitive Landscape
Player mix skews toward integrated packaging conglomerates with captive resin operations and metal forming capabilities. Tiered competitive structure separates specification-intensive pharmaceutical-grade suppliers from high-volume beverage commodity producers. Strategic archetypes include multi-material platform specialists, metal closure dominant food canning anchors, and pharmaceutical certification-focused validation leaders. Competitive moves concentrate on backward integration into resin compounding and geographic expansion through distribution partnerships.
Among North American integrated packaging groups, Berry Global Inc., Silgan Holdings Inc., and Amcor plc exemplify contrasting strategic positions. Berry Global represents the captive resin compounding archetype with blow-molding integration across beverage plants. Silgan Holdings occupies the metal closure dominance position in food canning applications. Amcor plc anchors the multi-material platform breadth spanning tamper-evident and child-resistant formats.
| Leading Market Players |
|---|
| SKS Bottle and Packaging, Inc |
| Rayware Limited |
| PacZone Limited |
| Ardagh Group S.A |
| Verallia |
| Berry Global Inc. |
| Silgan Holdings Inc. |
| Amcor plc |
| Closure Systems International, Inc. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Norwegian aluminum smelters directly shapes metal closure price floors across European beverage packaging, while resin compounding scale in Germany anchors plastic closure economics through ISO 15378 certification tiers.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate aluminum screw cap procurement for carbonated beverage lines. Price differentiation separates pharmaceutical-grade certified closures from commodity food-contact formats based on validation documentation and batch consistency protocols. Cost compression in standard beverage closures is intensifying because brand owners consolidate supplier panels to capture volume discounts. Generic drug manufacturers in India exhibit highest price sensitivity, while biologics contract manufacturers in Switzerland accept premium positioning for cryogenic-compatible validation.
Supply Chain Analysis
Strait of Hormuz transit risk underwrites energy cost volatility at Icelandic smelters feeding European metal closure production. Raw material flows draw from Norwegian aluminum ingot, Saudi petrochemical feedstock for polypropylene resin, and German masterbatch compounding for colorant and additive integration. Single-source vulnerability concentrates in pharmaceutical-grade resin formulation where ECHA REACH restrictions limit approved plasticizer alternatives. Distribution runs through blow-molding integration at major packaging conglomerates and specialized closure molders serving regional bottling corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 15378 certification capacity represents the critical scarcity layer separating qualified pharmaceutical suppliers from commodity closure producers, with validation timelines creating defendable moats for incumbents possessing documented batch consistency protocols.
For Market Incumbents: Consolidate backward integration into captive resin compounding to defend margin position against raw material volatility. Acquire specialized mold-making capabilities in Germany or Switzerland to compress pharmaceutical validation cycles. EMA Annex 1 sterile manufacturing guideline expansion threatens suppliers lacking biologics closure integrity systems.
For New Entrants and Emerging Players: Anchor in cryogenic storage compatible closure formats for cell therapy cold-chain expansion in the US and Switzerland. Target direct-to-consumer wine subscription channels in California and Oregon where quarterly SKU rotations favor agile digital decoration capabilities. Pursue partnership-based go-to-market positioning with regional contract packaging organizations lacking in-house closure sourcing expertise.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical certification-focused validation leaders with multi-year supply agreements locking biologics manufacturers into documented torque-release profile specifications. Long-term viability favors molders possessing in-house regrind processing and closed-loop collection infrastructure aligned with EU Green Deal packaging regulations. Monitor ECHA substance restriction announcements as inflection indicators for resin formulation obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polypropylene supply insulates Berry Global from REACH plasticizer restriction volatility. |
| ISO 15378 Certification Investment | Eighteen-month validation timelines at Ardagh Group facilities lock in biologics manufacturer switching costs. |
| Smart Closure NFC Integration | Tamper-evident authentication bands converge with mobile payment infrastructure in Asian beverage markets. |
| Closed-Loop Collection Partnership | Post-consumer recycled content mandates in California restructure tooling investments for EU Green Deal compliance. |
| Multi-Material Platform Expansion | Composite substrate capabilities enable Amcor plc to capture lightweighting mandates without sacrificing thread integrity. |
Research Methodology
A standing panel of blow-molding operations managers, pharmaceutical packaging validation leads, beverage procurement directors, and closure mold design engineers provided ongoing calibration against secondary sources including FDA 21 CFR Part 177 filings, EMA Annex 1 guidance documents, customs trade data for aluminum ingot flows, and SEC 10-K disclosures from integrated packaging conglomerates. Bottom-up demand modeling across end-use segments triangulated with top-down macroeconomic drivers.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include material substrate, closure mechanism complexity, end-use regulatory tier, geographic manufacturing cluster, and certification grade. CAGRs were derived from regression-based trending of historical shipment data and forward projection of regulatory-driven specification shifts. Forecast inputs incorporated smelter capacity utilization rates and ECHA substance restriction timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained EMA sterile manufacturing guideline enforcement and stable aluminum energy cost structures; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU extended producer responsibility thresholds and California recycled content mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Algeria Container Glass Market
Containers
Global Multi Pack Carriers Market
Containers
Lever Lid Cans Market
Containers
Single Wall Jars Market
Containers
Packaging Bins Market
Containers
Laboratory Sample Container Market
Containers
Global Styrene Compartment Boxes Market
Containers
Collapsible Sleeve Containers Market
Containers
Collapsible Food Packaging Containers Market
Containers
Spout Containers Market
Containers
Steel Containers Market
Containers
Stackable Plastic Trays Market
Containers
Reconditioned IBC Market
Containers
Global Cardboard Box and Container Market
Containers
Hinged Deli Containers Market
Containers
Global Food Storage Container Market