
 Oblong Container Market | 2026-2036
Oblong Container Market Size, Share, and Industry Trends Forecast 2026-2036
Oblong Container Market Analytics
Subscription-based container fleet management is rebalancing how buyers procure oblong formats, shifting capital expenditure into operational contracts. Pactiv leverages its North American thermoforming scale to anchor multi-year supply agreements with institutional foodservice operators. Amcor competes through global preform and barrier film integration that extends its cost position across plastic oblong lines.
Oblong containers are elongated rectangular or ellipsoidal vessels, typically manufactured through injection molding, thermoforming, or blow molding, with length-to-width ratios exceeding 1.5 to optimize shelf footprint and stackability for commercial distribution. Plastic dominates production volume due to lightweight properties and barrier customization, though metal formats retain structural share in chemical and industrial end uses where stack strength and reclosure durability command premium positioning. Food end use leads absolute demand, while pharmaceutical-grade oblong containers with child-resistant screwcaps represent the fastest-growing margin pool.
The FDA regulates direct food contact materials under 21 CFR, while the EPA governs recycled content claims and post-consumer resin pathways; together these frameworks compel manufacturers to document material provenance and migration compliance. The EU Green Deal and REACH restrict certain plasticizers and mandate recyclability design, redirecting R&D spend toward mono-material oblong structures. Stakeholders must monitor how extended producer responsibility schemes in North America and Europe alter the total cost of ownership for multi-material versus single-substrate container designs.
Market Dynamics
Subscription-based fleet management is restructuring procurement economics, converting capital-intensive container purchases into operational expenditure contracts that reshape supplier-buyer power balances across foodservice and industrial channels.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability design targets are accelerating mono-material oblong adoption across European foodservice chains, forcing format standardization that benefits scaled thermoforming operations.
- Prepared meal expansion:Food service chains are scaling sealed oblong formats for ready-to-eat distribution, creating dedicated demand for barrier-customized plastic containers with extended shelf-life performance.
- Germany's industrial corridor:Concentrated chemical and automotive packaging demand in the Rhine-Ruhr region sustains premium metal oblong volumes where stack strength commands specialized manufacturing investment.
Market Restraints
- Post-consumer resin price volatility:PCR feedstock availability fluctuations constrain cost planning for manufacturers targeting EU Green Deal recycled content thresholds.
- Multi-material design legacy:Existing barrier film and adhesive combinations complicate mechanical recycling streams, creating compliance friction under extended producer responsibility schemes.
- Pharmaceutical certification timelines:Child-resistant closure validation under FDA 21 CFR extends new product introduction cycles by 18-24 months for specialized oblong formats.
Strategic Opportunities
- Pharmaceutical-grade segment:Child-resistant screwcap oblong containers represent an underpenetrated margin pool where regulatory compliance creates defensible pricing power.
- Mono-material convergence:Barrier film and structural substrate integration into single-polymer designs unlocks streamlined recycling pathways ahead of EU mandates.
- India foodservice modernization:Quick-service restaurant expansion and cold-chain infrastructure investment create first-mover positioning for sealed oblong formats in prepared meal distribution.
Industry Challenges
- Thermoforming tool engineering scarcity:Specialized mold design expertise for high-length-to-width ratio containers concentrates among legacy equipment suppliers, constraining capacity expansion.
- Migration testing backlog:FDA direct food contact documentation requirements create laboratory capacity bottlenecks that delay product commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oblong Container Market |
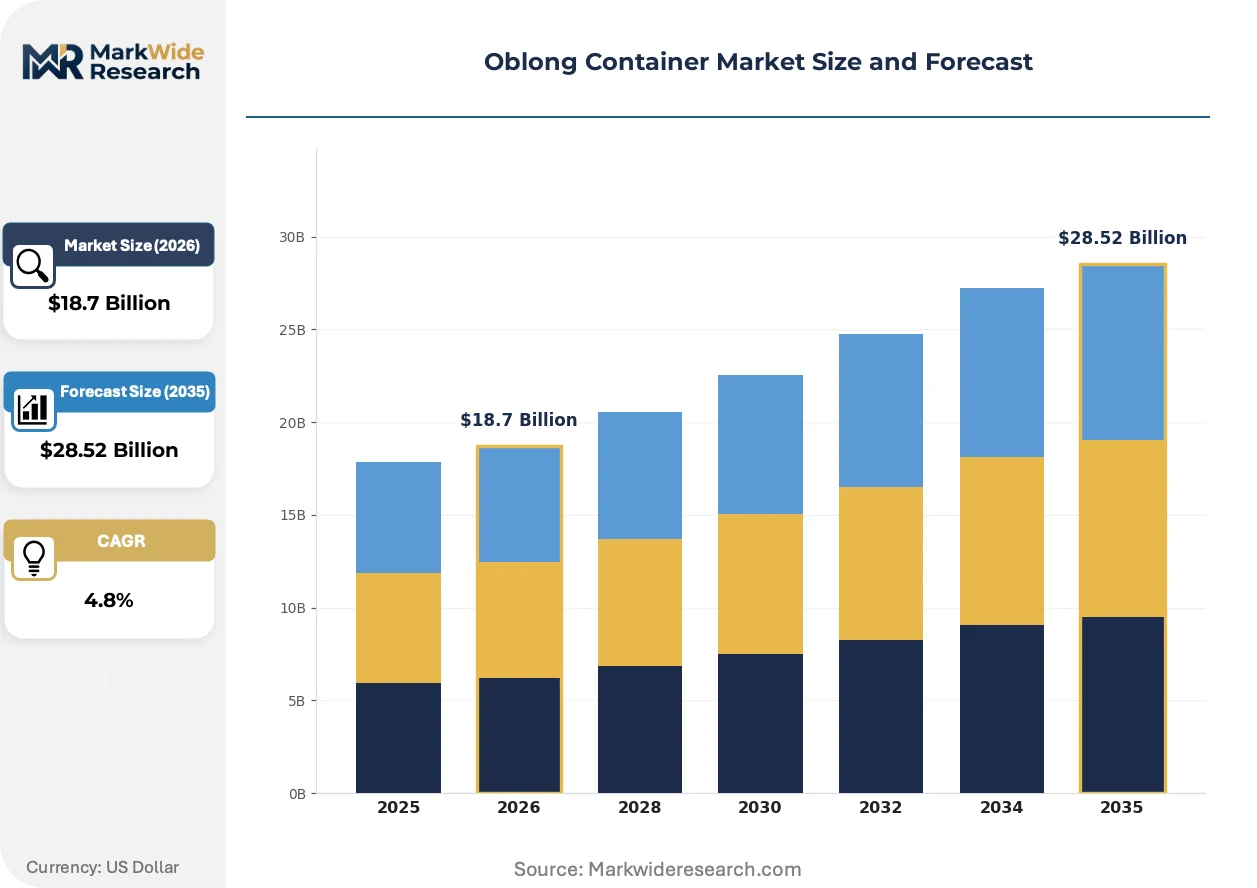
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Paper End Use Industry: Food, Cosmetics, Pharmaceuticals, Chemicals Closure Type: Screwcaps, Snap-on, Cork, Flip-top Size: Small, Medium, Large, Extra Large |
| Companies Covered | Pactiv, D&W Fine Pack, Dart Container, Oak Hill Capital Partners, Dcor, Amcor, Sabert, Berry Global, Greif, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oblong Container Market Evolving Landscape
Active redesign of material architecture and procurement mechanics is compressing traditional supply relationships while elevating regulatory compliance to a primary design constraint across all substrate categories.
Mono-material barrier structures are consolidating competitive positioning in plastic oblong manufacturing. Thermoformers are adopting co-extruded PP-EVOH-PP configurations that eliminate adhesive layers while preserving oxygen transmission performance. This substrate unification is consolidating supplier tiers by disqualifying multi-material specialists from European institutional contracts.
REACH restrictions on specific plasticizers and the EU Green Deal recyclability mandates are redirecting R&D expenditure toward design-for-recycling protocols. Manufacturers must now document material provenance and migration compliance across extended supply chains. Pharmaceutical and food-contact segments face the steepest reformulation requirements as ECHA substance evaluations progress.
Foodservice operators are consolidating procurement through multi-year supply agreements that bundle container supply with fleet management services. Institutional buyers are displacing spot-market purchasing with operational contracts that transfer inventory risk to manufacturers. This contractual evolution is most visible in North American quick-service and contract catering channels where capital-light balance sheet preferences dominate.
Oblong Container Market Segmentation
Oblong container purchasing decisions pivot on material performance specifications, regulatory compliance pathways, and end-use barrier requirements. Format selection directly determines total cost of ownership across food contact migration testing, pharmaceutical closure validation, and industrial stack strength mandates.
Product Type:
Material composition governs barrier customization, recyclability design, and manufacturing process selection across thermoforming, blow molding, and metal forming operations.
- Plastic:Injection-molded and thermoformed polypropylene and PET structures dominate prepared meal distribution through lightweight properties and oxygen barrier co-extrusion. EU Packaging and Packaging Waste Regulation recyclability targets are accelerating mono-material PP-EVOH-PP adoption across German and French foodservice chains.
- Metal:Tinplate and aluminum oblong formats retain structural positioning in chemical and automotive packaging where stack strength and reclosure durability command specialized manufacturing investment. Rhine-Ruhr industrial corridor demand sustains premium metal volumes despite plastic substitution pressure.
- Glass:Borosilicate and soda-lime configurations serve premium cosmetic and pharmaceutical applications requiring inert contact surfaces and visual product clarity.
- Paper:Barrier-coated fiberboard oblongs address single-use foodservice applications with compostability positioning under municipal organic waste diversion programs.
Plastic leads on scale; metal leads on momentum in specialized industrial niches.
End Use Industry:
Application-specific regulatory exposure and barrier performance requirements segment manufacturing capability and certification investment.
- Food:Sealed oblong formats for ready-to-eat distribution require oxygen transmission customization and FDA 21 CFR migration compliance. Quick-service restaurant chains are consolidating procurement through multi-year supply agreements that bundle container supply with fleet management services.
- Pharmaceuticals:Child-resistant screwcap oblong containers with FDA 21 CFR validation represent a margin pool where regulatory compliance creates defensible pricing power. Certification timelines extend new product introduction cycles by 18-24 months.
- Cosmetics:Premium glass and polymer formats emphasize aesthetic differentiation and airless dispensing compatibility for skincare and fragrance applications.
- Chemicals:Industrial oblong specifications prioritize UN-certified stack strength and hazardous material compatibility for automotive and agricultural chemical distribution.
Food commands absolute volume; pharmaceuticals climbs the fastest on regulatory premium capture.
Closure Type:
Reclosure mechanism selection determines child-resistance compliance, shelf-life extension, and end-user convenience positioning across consumer and institutional channels.
- Screwcaps:Threaded polypropylene and metal closures enable repeatable sealing for pharmaceutical and food applications requiring tamper-evidence and child-resistance under FDA 21 CFR protocols.
- Snap-on:Press-fit polyethylene designs serve prepared meal and deli applications where single-use convenience dominates over reclosure durability.
- Cork:Natural and synthetic stopper formats retain positioning in premium wine and spirits packaging with traditional aesthetic requirements.
- Flip-top:Hinged polypropylene closures address condiment and personal care dispensing with one-handed operation convenience.
Screwcaps dominate regulatory-intensive segments; snap-on formats gain share fastest in foodservice disposables.
Size:
Dimensional scaling affects tooling investment, logistics cube utilization, and end-use portion control specifications across retail and institutional channels.
- Small:Sub-250ml formats serve single-serve condiment, pharmaceutical sample, and cosmetic travel-size applications with high tooling changeover frequency.
- Medium:250-750ml volumes concentrate prepared meal and personal care demand where shelf footprint optimization balances with consumer portion expectations.
- Large:750ml-2L specifications address family-size food service and institutional chemical packaging with palletization efficiency priorities.
- Extra Large:Above-2L formats serve bulk industrial chemical and food ingredient applications with specialized stack strength and forklift handling requirements.
Medium sizes anchor volume concentration; small formats expand most quickly in pharmaceutical sampling and airline catering channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial packaging corridor commands premium metal oblong volumes, while the United States drives thermoformed plastic adoption through foodservice consolidation. Divergent regulatory timelines across the EU Packaging and Packaging Waste Regulation and FDA 21 CFR are reshaping material selection priorities in each market.
United States
Quick-service restaurant chains are bundling container supply with fleet management services, converting capital expenditure into operational contracts. FDA 21 CFR migration testing requirements create laboratory capacity bottlenecks that extend product commercialization timelines. The Midwest manufacturing belt concentrates thermoforming operations serving institutional foodservice channels.
Germany
The Rhine-Ruhr industrial corridor sustains demand for UN-certified metal oblong formats where stack strength and hazardous material compatibility command specialized investment. EU Packaging and Packaging Waste Regulation recyclability targets are accelerating mono-material PP-EVOH-PP adoption across foodservice chains. Bavaria's precision manufacturing clusters supply high-length-to-width ratio mold engineering expertise.
China
Dual carbon goals and GB standards for packaging recyclability are redirecting domestic production toward design-for-recycling protocols. MIIT industrial policy supports co-extrusion capacity expansion for barrier-customized containers. The Yangtze River Delta concentrates injection molding operations serving prepared meal distribution networks.
India
Quick-service restaurant expansion and cold-chain infrastructure investment are creating first-mover positioning for sealed oblong formats. FSSAI food contact material regulations are tightening documentation requirements for imported substrates. Maharashtra's industrial corridor hosts emerging thermoforming capacity targeting pharmaceutical-grade applications.
France
EMA pharmaceutical packaging guidelines and ANSM child-resistance standards are extending certification timelines for specialized oblong formats. ECHA substance evaluations under REACH are disqualifying certain plasticizers from food-contact applications. The Île-de-France region concentrates demand for premium cosmetic and pharmaceutical glass oblong containers.
Oblong Container Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with thermoforming scale operators capturing institutional foodservice contracts while metal fabricators defend industrial niches. The vendor base concentrates among North American and European players with integrated barrier film capabilities. Three archetypes dominate: multi-material specialists pivoting toward mono-material designs, fleet-management service bundlers, and pharmaceutical-grade certification holders. M&A activity targets mold engineering expertise, while strategic partnerships secure post-consumer resin supply chains.
Among North American operators, Pactiv and Dart Container exemplify scale-driven thermoforming positions, while Amcor occupies a global integration archetype spanning preform and barrier film production. These three represent contrasting strategic postures: captive North American foodservice density, diversified substrate manufacturing, and global supply chain orchestration respectively.
| Leading Market Players |
|---|
| Pactiv |
| D&W Fine Pack |
| Dart Container |
| Oak Hill Capital Partners |
| Dcor |
| Amcor |
| Sabert |
| Berry Global |
| Greif |
| Others |
Value Network & Pricing Analysis
Specialized thermoforming tool engineering expertise concentrated in Bavaria's precision manufacturing clusters feeds directly into labor-cost differentials that widen pricing-tier spreads between premium mono-material oblong formats and commodity multi-material alternatives.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for injection-molded polypropylene oblong containers. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 21 CFR certification grade and volume commitment scale. Cost compression in the standard tier is intensifying because EU Green Deal recycled content mandates force parallel PCR feedstock procurement. Quick-service restaurant chains exhibit highest price sensitivity through fleet-management contract negotiations, while pharmaceutical-grade buyers accept premium positioning for child-resistant closure validation.
Supply Chain Analysis
Post-consumer resin supply rests on fragmented municipal collection systems across Germany, France, and the Netherlands. EVOH barrier film co-extrusion draws from Japanese and South Korean specialty polymer producers, while tinplate metal forming anchors in the Rhine-Ruhr industrial corridor. Single-source vulnerability concentrates in high-length-to-width ratio mold engineering where Bavarian equipment suppliers dominate. Distribution runs through institutional foodservice procurement consortia and pharmaceutical contract manufacturing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where prepared meal distribution demands and pharmaceutical certification requirements are shifting procurement toward premium barrier-customized specifications.
For Market Incumbents: Cement mono-material PP-EVOH-PP manufacturing scale ahead of EU Packaging and Packaging Waste Regulation recyclability deadlines. Acquire specialized mold engineering capability in Bavaria to defend against emerging Asian thermoforming entrants. Prioritize backward integration into post-consumer resin sorting infrastructure to secure feedstock cost position.
For New Entrants and Emerging Players: Begin with India's quick-service restaurant cold-chain modernization where sealed oblong format penetration remains underdeveloped. Target pharmaceutical-grade child-resistant screwcap segments where FDA 21 CFR validation timelines create incumbent capacity constraints. Pursue co-development partnerships with Maharashtra-based thermoforming operations to accelerate FSSAI compliance pathways.
For Investors and Strategic Acquirers: Foodservice fleet-management service providers are the most active acquirer in this space, consolidating container supply with operational contract bundling. The five-to-ten year viability window favors targets with integrated barrier film co-extrusion and documented EU Green Deal compliance. Watch ECHA substance evaluation progress against specific plasticizers as an inflection indicator for reformulation-driven replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Integration | PP-EVOH-PP co-extrusion unlocks EU Packaging and Packaging Waste Regulation recyclability compliance ahead of mandates. |
| Fleet Management Service Bundling | Multi-year operational contracts with quick-service restaurant chains convert capital expenditure into recurring revenue streams. |
| Pharmaceutical Certification Investment | FDA 21 CFR child-resistant closure validation creates defensible pricing power in specialized oblong formats. |
| Post-Consumer Resin Supply Security | Backward integration into sorting infrastructure hedges PCR feedstock volatility under EU Green Deal thresholds. |
| India Cold-Chain Infrastructure Partnership | First-mover positioning in Maharashtra and Delhi NCR quick-service restaurant expansion captures format standardization. |
Research Methodology
Bottom-up foodservice and pharmaceutical end-use modeling reconciled against top-down thermoforming and metal forming capacity tracking forms the analytical core of this study. Primary interviews with procurement directors at institutional foodservice operators, regulatory affairs leads at container manufacturers, mold engineering specialists in Bavaria, and quick-service restaurant supply chain managers combined with secondary validation from FDA 21 CFR filings, ECHA substance evaluation databases, EU Packaging and Packaging Waste Regulation impact assessments, and German industrial production statistics. This dual approach enables cross-verification of volume assumptions against supply-side constraints.
Historical trendline analysis across material substitution patterns and regulatory compliance cost trajectories informed the projection framework. Segmentation dimensions modeled include material substrate, end-use industry, closure mechanism, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating fleet-management contract adoption rates and pharmaceutical certification timeline extensions. Industry-specific forecast inputs encompass EU Green Deal recycled content threshold schedules and FSSAI food contact documentation requirement phases.
Several conditions sit outside the modeled scope, including abrupt tariff reconfigurations affecting EVOH barrier film trade flows and unanticipated ECHA substance bans. Forecasts reflect documented assumptions about regulatory implementation timelines and material substitution elasticities. Unforeseen laboratory capacity bottlenecks for FDA migration testing or PCR feedstock supply disruptions could revise trajectory assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Reconditioned IBC Market
Containers
PS Containers Market
Containers
Containerboard Market
Containers
Pocket Containers Market
Containers
Latin America Intermediate Bulk Container Liner Market
Containers
Lift-Off Lid Box Market
Containers
Cylindrical Cans Market
Containers
Sandwich Containers Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Algeria Container Glass Market
Containers
Stock Clamshell Packaging Market
Containers
Foam Hinged Take-Out Containers Market
Containers
Collapsible Food Packaging Containers Market
Containers
Intermediate Bulk Container (IBC) Market
Containers
Old Corrugated Containers (OCC) Market
Containers
Thermoformed Containers Market