
 Bulk Container Packaging Market | 2026-2036
Bulk Container Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Container Packaging Market Intelligence
Reusable container fleet management is consolidating what buyers purchase, shifting capital from unit sales to per-trip service models. Greif, Inc. leverages its North American reconditioning network to anchor long-term chemical contracts. Mauser Packaging Solutions GmbH sustains European market presence through closed-loop pooling systems. Schütz GmbH & Co. specializes in composite intermediate bulk containers for hazardous material transport.
Bulk container packaging denotes industrial-grade vessels engineered to transport and store granular, liquid, or powdered commodities in volumes typically ranging from 500 to 3,000 liters, constructed from high-density polyethylene, galvanized steel, or multi-wall corrugated fiberboard with UN-certified stacking and drop-test ratings. These systems reduce per-unit logistics cost while enabling forklift-compatible handling across warehouse and intermodal environments. Flexible bulk bags capture expanding agricultural and construction material flows due to low tare weight and collapsible return logistics. Plastic intermediate bulk containers lead chemical manufacturing adoption where corrosion resistance and seamless interior cleaning prove critical. Metal drums retain mature positions in petroleum and lubricant distribution where spark-proof specifications govern material selection.
EPA hazardous waste container regulations in the United States mandate specific closure and labeling standards that filter non-compliant suppliers from chemical sector procurement lists. ECHA REACH restrictions on certain polymer additives compel European manufacturers to reformulate container resins or face market exclusion. FDA food contact substance notifications govern intermediate bulk containers deployed in food processing and pharmaceutical ingredient handling. Stakeholders must monitor evolving extended producer responsibility frameworks that shift end-of-life collection costs toward original equipment manufacturers.
Market Dynamics
Reusable intermediate bulk container programs are compressing capital cycles as chemical manufacturers shift from unit purchases to per-trip service models, consolidating vendor relationships around fleet management capabilities rather than manufacturing scale alone.
Growth Catalysts
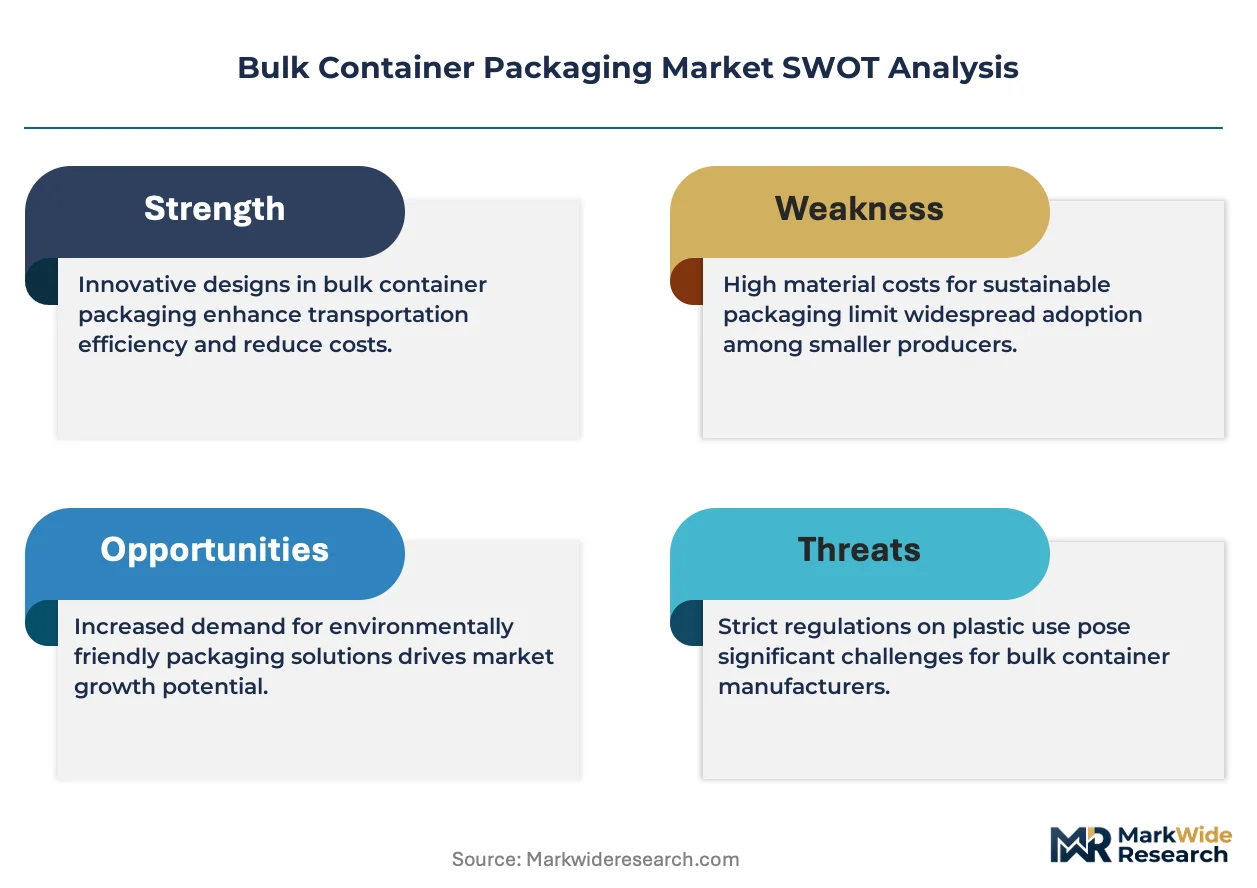
- REACH compliance mandates:ECHA restrictions on polymer additives in Europe push converters toward recyclable high-density polyethylene formulations, filtering non-compliant suppliers from procurement lists.
- Chemical sector pooling adoption:Hazardous material handlers in Germany's Rhine-Ruhr corridor deploy closed-loop systems to reduce per-trip logistics costs and satisfy UN-certified stacking requirements.
- Flexible bulk bag penetration:Agricultural commodity flows favor collapsible polypropylene containers with low tare weight for return logistics efficiency.
Market Restraints
- Resin input volatility:High-density polyethylene feedstock costs fluctuate with crude oil indices, compressing converter margins on long-term chemical sector contracts.
- Reconditioning network concentration:North American container refurbishment capacity clusters around Great Lakes industrial zones, creating regional supply bottlenecks during peak agricultural seasons.
- Metal drum substitution limits:Spark-proof specifications in petroleum distribution prevent plastic intermediate bulk container displacement despite corrosion advantages.
Strategic Opportunities
- Extended producer responsibility frameworks:EU Green Deal implementation shifts end-of-life collection costs toward original equipment manufacturers, favoring converters with captive recycling infrastructure.
- Food contact certification expansion:FDA notifications for intermediate bulk containers in pharmaceutical ingredient handling open adjacent verticals beyond chemical manufacturing.
- RFID-enabled fleet tracking:Asset management technology convergence with composite container construction enables real-time location monitoring for hazardous material compliance.
Industry Challenges
- Multi-material recycling expertise gap:Composite intermediate bulk containers combining steel cages with polymer liners require specialized dismantling skills scarce in established reconditioning workforces.
- UN certification timeline compression:Drop-test and stacking validation protocols for new container designs extend product development cycles beyond typical chemical sector procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Container Packaging Market |
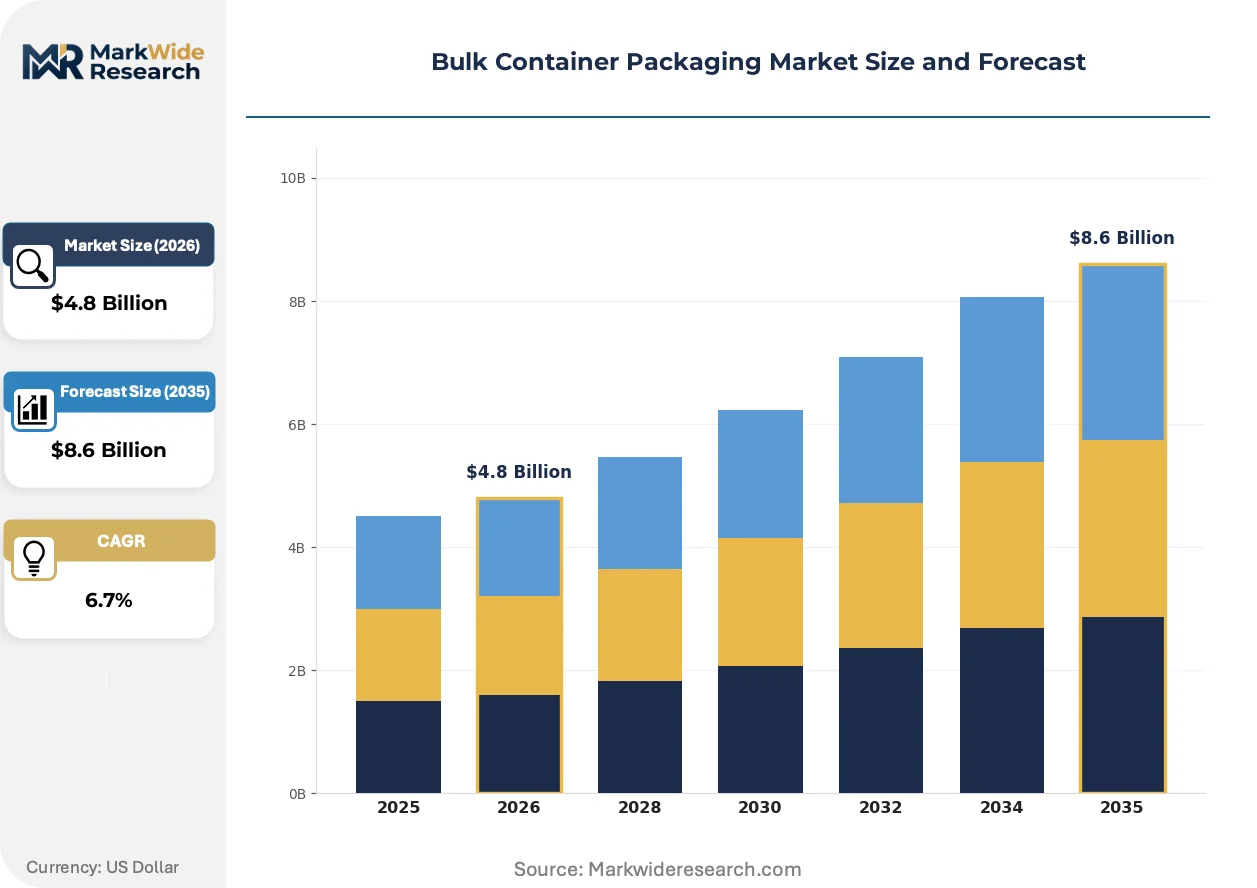
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Intermediate Bulk Containers, Drums, Pallet Containers, Cardboard Bulk Boxes, Flexible Bulk Bags Material: Plastic, Metal, Fiberboard, Composite, Steel End Use Industry: Chemical Manufacturing, Food Processing, Pharmaceuticals, Agriculture, Construction Materials Distribution Channel: Direct Sales, Distributors, Online Marketplaces, Wholesale Traders, Retail Outlets |
| Companies Covered | Mauser Packaging Solutions GmbH, Smurfit Kappa Group plc, Amcor, Time Technoplast Limited, DS Smith plc, Greif, Inc., Mondi plc, International Paper, Schütz GmbH & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Container Packaging Market Strategic Shifts & Innovations
Digital tracking integration and material science advances are reshaping how bulk container assets circulate through industrial supply chains, compressing the distinction between packaging hardware and logistics software.
Radio-frequency identification tags embedded in intermediate bulk container bases are unifying physical asset management with enterprise resource planning systems. Chemical manufacturers in the US Gulf Coast petrochemical corridor adopt these tracked fleets at accelerating rates. The technology is unifying previously siloed container inventory data with carrier scheduling platforms, enabling dynamic repositioning that reduces empty-mile ratios.
ECHA REACH restrictions on certain phthalate plasticizers are compelling European converters to reformulate high-density polyethylene resins or face market exclusion. The industrial consequence filters smaller compounders lacking R&D capacity for rapid certification turnover. Hazardous material transport applications face the steepest compliance curves, with German industrial packaging specialists accelerating substitution timelines.
Outcome-based service contracts now displace unit sales in North American chemical procurement, with buyers purchasing cubic-meter-miles rather than container assets. Third-party logistics providers and dedicated fleet operators capture margin previously held by manufacturers. This pattern concentrates most visibly in agricultural chemical distribution, where seasonal demand spikes favor flexible capacity arrangements over owned equipment.
Bulk Container Packaging Market Segmentation
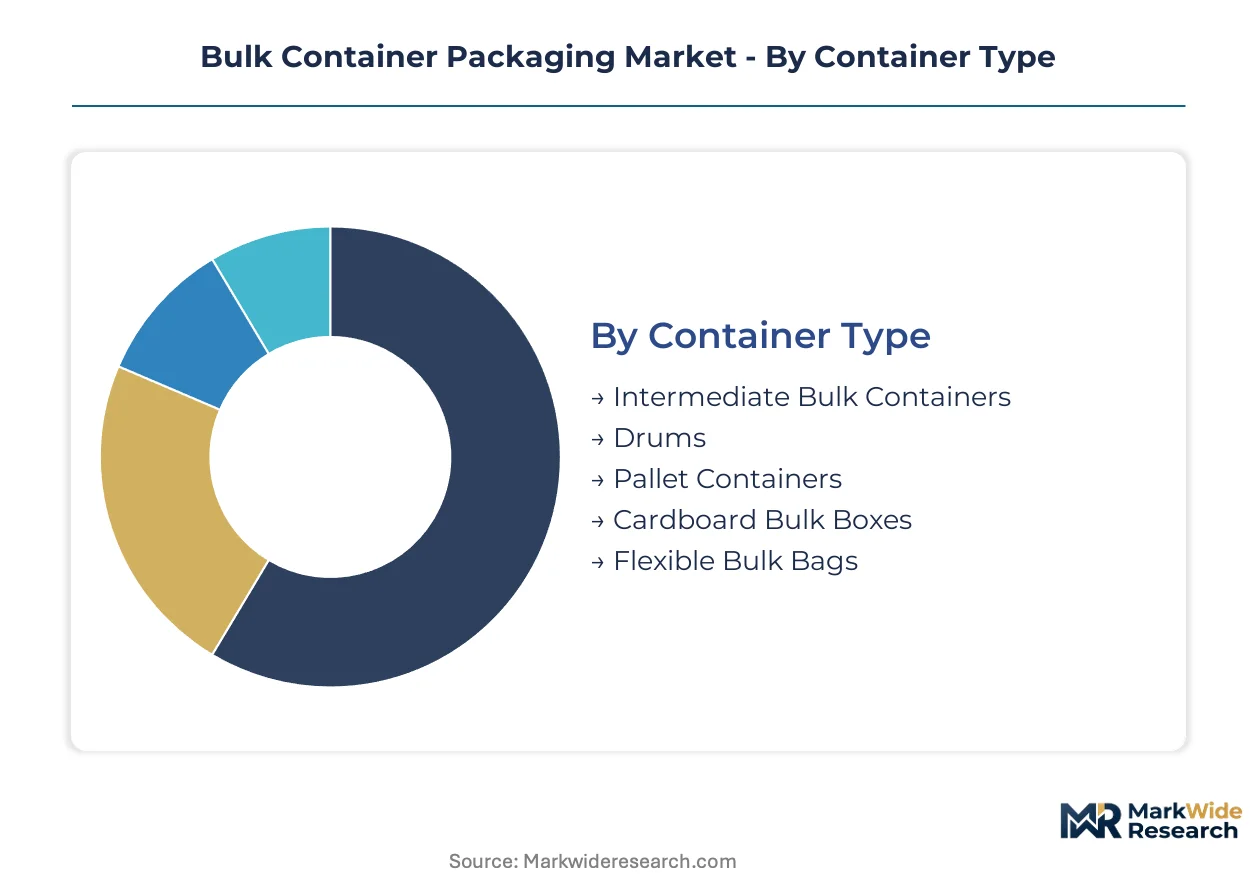
Segmentation in bulk container packaging reveals how supply-side capabilities align with divergent handling requirements across hazardous chemicals, perishable food, and construction aggregates. Container specifications, material selection, and channel configuration each filter which suppliers capture value in specific end-use contexts.
Container Type:
Supply concentration around reconditioning networks and pooling infrastructure favors container formats with established reverse logistics systems over novel designs lacking refurbishment ecosystems.
- Intermediate Bulk Containers:HDPE or steel-caged composite vessels ranging 500-3,000 liters with UN-certified stacking ratings. Chemical manufacturers in Germany's Rhine-Ruhr corridor deploy these through closed-loop pooling programs to satisfy hazardous material transport regulations while minimizing per-trip capital outlay.
- Flexible Bulk Bags:Woven polypropylene containers with 500-2,000 kg payload capacity and collapsible return logistics. Agricultural commodity flows in the US Midwest favor these for seasonal harvest transport where low tare weight reduces empty-mile fuel costs.
- Drums:Cylindrical steel or plastic vessels with 200-250 liter capacity for liquid and viscous materials.
- Pallet Containers:Rigid bulk bins designed for forklift handling of granular and solid materials.
- Cardboard Bulk Boxes:Multi-wall corrugated fiberboard containers for dry, non-hazardous goods with single-trip economics.
Intermediate bulk containers absorb the bulk of installed capacity; flexible bulk bags are expanding most quickly.
Material:
Cost tier differentiation separates commodity resin formulations from engineered composites with specialized barrier properties or spark-proof specifications.
- Plastic:High-density polyethylene and polypropylene formulations offering corrosion resistance and seamless interior cleaning. FDA food contact notifications govern pharmaceutical ingredient handling applications where residue elimination proves critical.
- Metal:Cold-rolled steel and stainless steel constructions for spark-proof petroleum distribution and high-temperature filling operations. ECHA REACH restrictions on polymer additives in Europe accelerate metal drum retention where plastic substitution faces regulatory barriers.
- Composite:Steel cage structures with polymer liner inserts combining structural integrity with chemical resistance.
- Fiberboard:Recycled paper-based materials for dry, non-hazardous goods with minimal handling cycles.
- Steel:Galvanized and coated variants for extended outdoor storage and maritime exposure.
Plastic formulations command the widest application range; composite constructions are climbing the fastest as chemical handlers seek hybrid performance attributes.
End Use Industry:
Application-specific requirements around UN certification, food contact approval, and agricultural seasonality fragment demand across incompatible specification regimes.
- Chemical Manufacturing:Hazardous material handlers requiring UN-certified stacking, drop-test ratings, and EPA-compliant closure systems. The US Gulf Coast petrochemical corridor drives RFID-enabled fleet tracking adoption for real-time compliance documentation.
- Food Processing:Ingredient and additive handling governed by FDA food contact substance notifications and sanitary design requirements.
- Pharmaceuticals:Active pharmaceutical ingredient and excipient transport with stringent cleaning validation protocols.
- Agriculture:Fertilizer, seed, and grain handling with extreme seasonal demand spikes favoring flexible capacity arrangements.
- Construction Materials:Cement, aggregates, and minerals transport where abrasion resistance and moisture protection govern material selection.
Chemical manufacturing anchors procurement volume; food processing is gaining share fastest as pharmaceutical ingredient handling expands container certification requirements.
Distribution Channel:
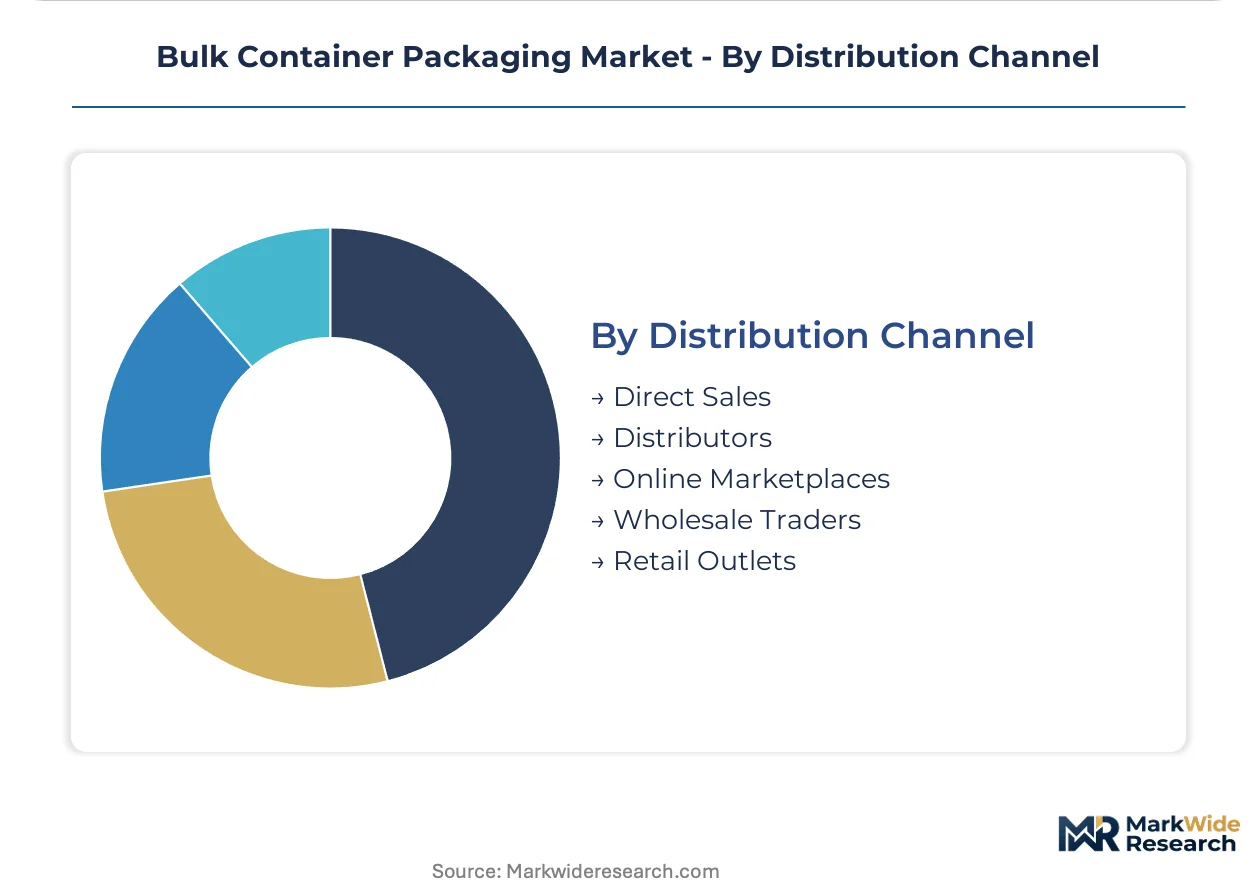
Customer type and purchase scale determine whether buyers access container supply through manufacturer-direct relationships or intermediary stocking arrangements.
- Direct Sales:Long-term chemical sector contracts with dedicated fleet management and per-trip service models. Greif, Inc. leverages its North American reconditioning network to anchor these arrangements through outcome-based cubic-meter-mile pricing.
- Distributors:Regional inventory stocking for mid-volume buyers with irregular demand patterns and mixed specification requirements.
- Online Marketplaces:Digital procurement platforms for standardized container specifications with immediate availability needs.
- Wholesale Traders:Bulk volume aggregation for agricultural cooperatives and construction material handlers.
- Retail Outlets:Small-quantity availability for maintenance, repair, and emergency replacement scenarios.
Direct sales capture the majority of contract value; distributor relationships are expanding most quickly as mid-tier chemical manufacturers seek flexible procurement terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of bulk container packaging concentrates in Germany and the United States, while consumption spreads across industrial corridors in Asia-Pacific and Europe. Manufacturing clusters align with chemical sector demand and reconditioning infrastructure density.
United States
Chemical manufacturers along the US Gulf Coast petrochemical corridor drive RFID-enabled fleet tracking adoption for hazardous material compliance. EPA hazardous waste container regulations mandate specific closure standards that filter supplier eligibility. Houston-area reconditioning networks anchor per-trip service contracts for agricultural chemical distribution.
Germany
ECHA REACH restrictions on polymer additives compel converters toward recyclable high-density polyethylene formulations or face procurement exclusion. The Rhine-Ruhr industrial corridor hosts closed-loop pooling systems for hazardous material handlers. Mauser Packaging Solutions GmbH sustains market presence through captive fleet management infrastructure.
China
MIIT industrial packaging standards govern intermediate bulk container specifications for domestic chemical distribution. Yangtze River Delta manufacturing clusters produce composite containers combining steel cages with polymer liners. Shanghai-port logistics favor collapsible flexible bulk bags for agricultural commodity export flows.
India
BIS certification requirements for industrial packaging filter import competition in chemical sector procurement. Gujarat's petrochemical corridor drives demand for UN-certified stacking and drop-test rated containers. Time Technoplast Limited occupies a position among domestic fabricators serving fertilizer and seed handling applications.
Brazil
ANVISA pharmaceutical packaging regulations extend to intermediate bulk containers for active ingredient transport. São Paulo-state agricultural cooperatives favor flexible bulk bags with low tare weight for seasonal soybean and corn flows. Construction material handlers in Minas Gerais deploy rigid pallet containers for mineral aggregate distribution.
Bulk Container Packaging Market Key Industry Players
Top-tier vendors anchor long-term chemical contracts through reconditioning networks, while mid-scale specialists compete on regional fleet responsiveness. The vendor base stratifies across integrated pooling operators, material-specific converters, and distributor-stocking intermediaries. Three archetypes dominate: captive recycling infrastructure owners, composite construction specialists, and flexible bag low-cost producers. Consolidation proceeds through reconditioning network acquisition and per-trip service model expansion.
Among German-based fabricators, Mauser Packaging Solutions GmbH and Schütz GmbH & Co. exemplify the composite intermediate bulk container archetype for hazardous material applications. Greif, Inc. represents North American reconditioning network consolidation. Smurfit Kappa Group plc and DS Smith plc occupy positions among fiberboard-based bulk packaging specialists serving construction and agricultural flows.
| Leading Market Players |
|---|
| Mauser Packaging Solutions GmbH |
| Smurfit Kappa Group plc |
| Amcor |
| Time Technoplast Limited |
| DS Smith plc |
| Greif, Inc. |
| Mondi plc |
| International Paper |
| Schütz GmbH & Co. |
| Others |
Cost & Logistics Intelligence
High-density polyethylene resin indices cascade through bulk container packaging tiers, compressing margins on long-term chemical contracts while amplifying differentiation premiums for REACH-compliant formulations. ECHA-mandated reformulation costs filter smaller compounders from European procurement lists, concentrating pricing power among converters with captive R&D infrastructure.
Pricing Analysis
Margin tightening in standard-grade IBC tiers reflects crude oil feedstock volatility and resin input cost pass-through limitations. Three-tier pricing structure across premium UN-certified, standard industrial-grade, and economy single-trip levels separates buyers by certification burden and fleet management sophistication. Cost-down pressure on mid-tier converters accelerates as Gulf Coast chemical manufacturers consolidate vendor relationships around per-trip service models. Agricultural cooperatives exhibit highest price sensitivity due to seasonal volume spikes, while pharmaceutical ingredient handlers accept premium tiers for FDA food contact validation.
Supply Chain Analysis
Reverse logistics flows for reconditioned IBCs concentrate refurbishment capacity around Germany's Rhine-Ruhr corridor and US Great Lakes industrial zones, creating regional bottlenecks during peak agricultural seasons. HDPE resin supply draws from Saudi Arabian and US Gulf Coast petrochemical complexes, with steel cage components sourcing from Chinese and Turkish metal fabrication clusters. Single-source vulnerability pervades specialized liner manufacturing for hazardous material applications. Distribution runs through manufacturer-direct fleet management contracts for chemical sector volume, with distributor intermediaries serving mid-tier buyers with irregular demand patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reconditioning network scarcity props pricing across reusable container segments, constraining supply elasticity as chemical manufacturers accelerate per-trip service adoption. Capacity bottlenecks in UN-certified composite IBC fabrication limit rapid volume response to demand surges.
For Market Incumbents: To counter resin input volatility and margin compression in standard-grade segments, deepen backward integration into HDPE compounding operations in Germany and the US Gulf Coast. Anchor long-term chemical contracts through RFID-enabled fleet tracking investments that lock in switching costs and differentiate from reconditioning-only competitors. For New Entrants and Emerging Players: Launch via digital procurement platforms targeting mid-volume agricultural cooperatives in India's Gujarat corridor and Brazil's São Paulo state, where flexible bulk bag demand outpaces established pooling infrastructure. White-space concentrates in food contact-certified IBC segments for pharmaceutical ingredient handling, where FDA notification timelines filter rapid market entry. For Investors and Strategic Acquirers: Distressed-cycle entries favor captive recycling infrastructure owners in European markets facing extended producer responsibility cost shifts under EU Green Deal implementation. Long-term viability hinges on fleet management software integration and reconditioning network density rather than manufacturing scale alone. Monitor ECHA REACH additive restriction expansions as inflection signals for reformulation-capable converter premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HDPE Compounding | Cuts resin cost exposure for REACH-compliant formulations serving German chemical manufacturers. |
| RFID-Enabled Fleet Tracking Deployment | Unifies container inventory data with carrier platforms for Gulf Coast petrochemical corridor clients. |
| Food Contact Certification Expansion | Opens pharmaceutical ingredient handling verticals beyond core chemical manufacturing procurement. |
| Reconditioning Network Acquisition | Captures per-trip service margins and consolidates vendor relationships around cubic-meter-mile pricing. |
| Closed-Loop Pooling System Expansion | Satisfies UN-certified hazardous material requirements for Rhine-Ruhr industrial corridor handlers. |
Research Approach
Multi-period observation of resin input costs, reconditioning network capacity utilization, and chemical sector procurement contract structures anchored the trend analysis, supplemented by interviews with plant managers at HDPE converters, procurement leads at downstream chemical manufacturers, distribution channel partners, and technical R&D directors specializing in composite container design. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed packaging converters, and EPA hazardous waste container regulatory filings. Bottom-up volume modeling triangulated against top-down macroeconomic indicators.
Segment-weighting across container type, material formulation, end-use industry, and regional production hub informed the analytical framework. CAGRs derived from regression analysis of historical volume trajectories and forward projection of chemical manufacturing output, agricultural commodity flows, and pharmaceutical ingredient handling requirements across the analysis window. Industry-specific forecast inputs included UN certification timeline compression effects and extended producer responsibility framework implementation schedules.
The model assumes a particular technology adoption path for RFID-enabled asset tracking; alternative pathways for blockchain-based container provenance would alter the competitive differentiation timeline and fleet management software investment requirements. Forecasts reflect assumptions regarding REACH regulatory stability and resin feedstock cost pass-through mechanisms. Practitioners should monitor ECHA additive restriction announcements, MIIT standard updates in China, and BIS certification requirement changes in India for early signals of supply chain reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Slip Lid Can Market
Containers
Global Cardboard Box and Container Market
Containers
Intermediate Bulk Container Liner Market
Containers
Twist Up Stick Container Market
Containers
Hinged Lid Tins Market
Containers
Essential Oil Containers Market
Containers
EPS Container Market
Containers
Bulk Containers Market
Containers
Wooden Crates Market
Containers
Packer Bottle Market
Containers
Oblong Tub Lids Market
Containers
PET Containers Market
Containers
Jars Market
Containers
Single Wall Jars Market
Containers
Containerboard Market
Containers
Laboratory Sample Container Market