
 Pharmaceutical Ampoules Market | 2026-2036
Pharmaceutical Ampoules Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Ampoules Market Analytics
China is fragmenting its pharmaceutical ampoule supply base as domestic glass converters expand capacity to serve local biopharma formulators. Gerresheimer AG leverages vertical integration from tubing to finished ampoules across European and Asian plants. SCHOTT AG sustains technology leadership in FIOLAX borosilicate glass tubing, the substrate standard for most Type I pharmaceutical ampoules. Stevanato Group anchors its position through integrated containment solutions combining glass primary packaging with closure and delivery systems.
Pharmaceutical ampoules are sealed, single-dose glass or plastic containers designed to hold injectable drugs, vaccines, or diagnostic solutions under sterile, inert conditions; Type I borosilicate glass dominates due to its hydrolytic resistance and chemical durability during autoclaving and long-term storage. Glass material continues to command the largest volume share given regulatory familiarity and inertness with sensitive biologics, though polymer alternatives in polypropylene and polyethylene are gaining traction for specific cytotoxic and biologic applications requiring breakage resistance. The hospital end-user segment retains the deepest procurement volume, while homecare settings represent the fastest-growing channel as self-administration of insulin and biologic therapies expands patient delivery options beyond clinical environments.
FDA standards for container closure integrity, EU MDR requirements for patient safety documentation, and revised EU GMP Annex 1 sterility guidelines collectively elevate barrier performance expectations for ampoule manufacturers seeking market access across regulated jurisdictions. The country's national pharmaceutical regulator in India and CDSCO alignment with ICH Q3D guidelines on elemental impurities further shape material selection and supplier qualification protocols for export-oriented producers. Stakeholders must monitor evolving regulatory convergence between USP <1207> package integrity testing methods and European Pharmacopoeia chapters to anticipate capital equipment requirements and validation timelines.
Market Dynamics
Ready-to-use sterile ampoule formats are compressing aseptic processing steps, forcing manufacturers to reconfigure filling line investments around pre-sterilized containment rather than in-house depyrogenation cycles.
Growth Catalysts
- EU MDR sterility mandates:Revised Annex 1 guidelines impose stricter particulate and bioburden controls, compelling parenteral drug makers to upgrade primary packaging specifications.
- Biologics expansion:Monoclonal antibody and cell therapy formulators demand Type I borosilicate glass with proven hydrolytic resistance for long-term protein stability.
- Homecare self-administration:Diabetes and autoimmune patients in Germany and the United States are transitioning from hospital infusion to prefilled ampoule-based injection protocols.
Market Restraints
- Raw material concentration:FIOLAX borosilicate glass tubing supply concentrates among German specialty glassmakers, creating single-source vulnerability for ampoule converters.
- Energy-intensive forming:Continuous flame-working of glass ampoules requires sustained natural gas input, exposing margins to European energy price volatility.
- Polymer substitution threat:Cyclic olefin polymer and polypropylene vials are capturing cytotoxic and mRNA vaccine applications where breakage risk outweighs glass inertness.
Strategic Opportunities
- Indian export manufacturing:CDSCO alignment with ICH Q3D elemental impurity guidelines positions domestic glass converters to supply regulated markets in Africa and Southeast Asia.
- Combination product integration:Ampoule-syringe systems that merge primary containment with delivery mechanisms command premium positioning in biologics.
- China domestic biopharma:NMPA accelerated approval pathways for innovative drugs are expanding local demand for high-barrier ampoule formats previously imported.
Industry Challenges
- Container closure integrity validation:USP 1207 method development requires specialized helium leak detection equipment and extended qualification timelines.
- Cross-functional talent scarcity:Engineers capable of integrating glass forming physics with pharmaceutical quality systems remain concentrated among incumbent European suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Ampoules Market |
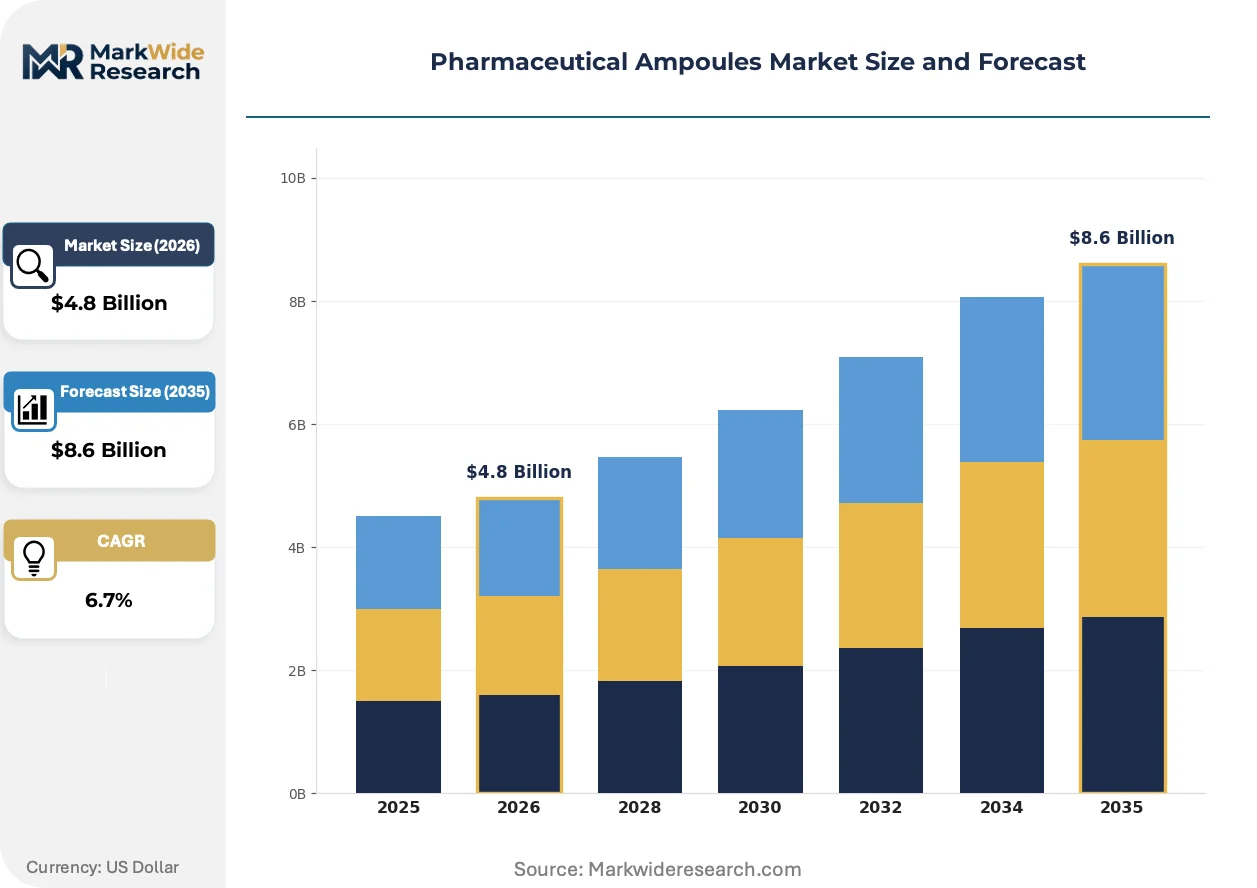
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Chloride, Dextrose, Insulin, Morphine Material: Glass, Plastic, Polypropylene, Polyethylene End User: Hospitals, Clinics, Pharmacies, Homecare Capacity: 1ml, 2ml, 5ml, 10ml |
| Companies Covered | Gerresheimer AG, SCHOTT AG, Stevanato Group, Nipro Corporation, SGD Pharma, James Alexander Corporation, ESSCO Glass, AAPL Solutions, Bormioli Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Ampoules Market Evolving Landscape
Ampoule manufacturing is bifurcating between premium borosilicate glass for biologics and engineered polymers for specialized therapeutics, with digital process controls threading through both pathways.
Barrier coating technologies are virtualizing the functional performance of pharmaceutical ampoules. Siliconization and plasma-deposited barrier layers now replicate the inertness of Type I glass on lower-cost substrates. Biopharma formulators in Switzerland and Singapore are qualifying these alternatives for non-protein parenterals. The technology is virtualizing the traditional glass-polymer material hierarchy by decoupling barrier function from base substrate selection.
EMA and national competent authorities are harmonizing extractables and leachables testing protocols under the EU MDR framework. This convergence eliminates redundant analytical work for suppliers serving multiple European markets. Small-volume parenteral manufacturers in Italy and Spain face the steepest compliance curve as they transition from legacy pharmacopoeial methods to standardized forced extraction studies.
Hospital procurement consortia are consolidating ampoule purchasing across therapeutic categories, compressing supplier negotiation cycles from annual to quarterly rhythms. Group purchasing organizations in France and the United Kingdom now bundle glass primary packaging with infusion sets and syringes. This concentration is most visible in oncology centers where traceability requirements favor single-source supply agreements over fragmented multi-vendor arrangements.
Pharmaceutical Ampoules Market Segmentation
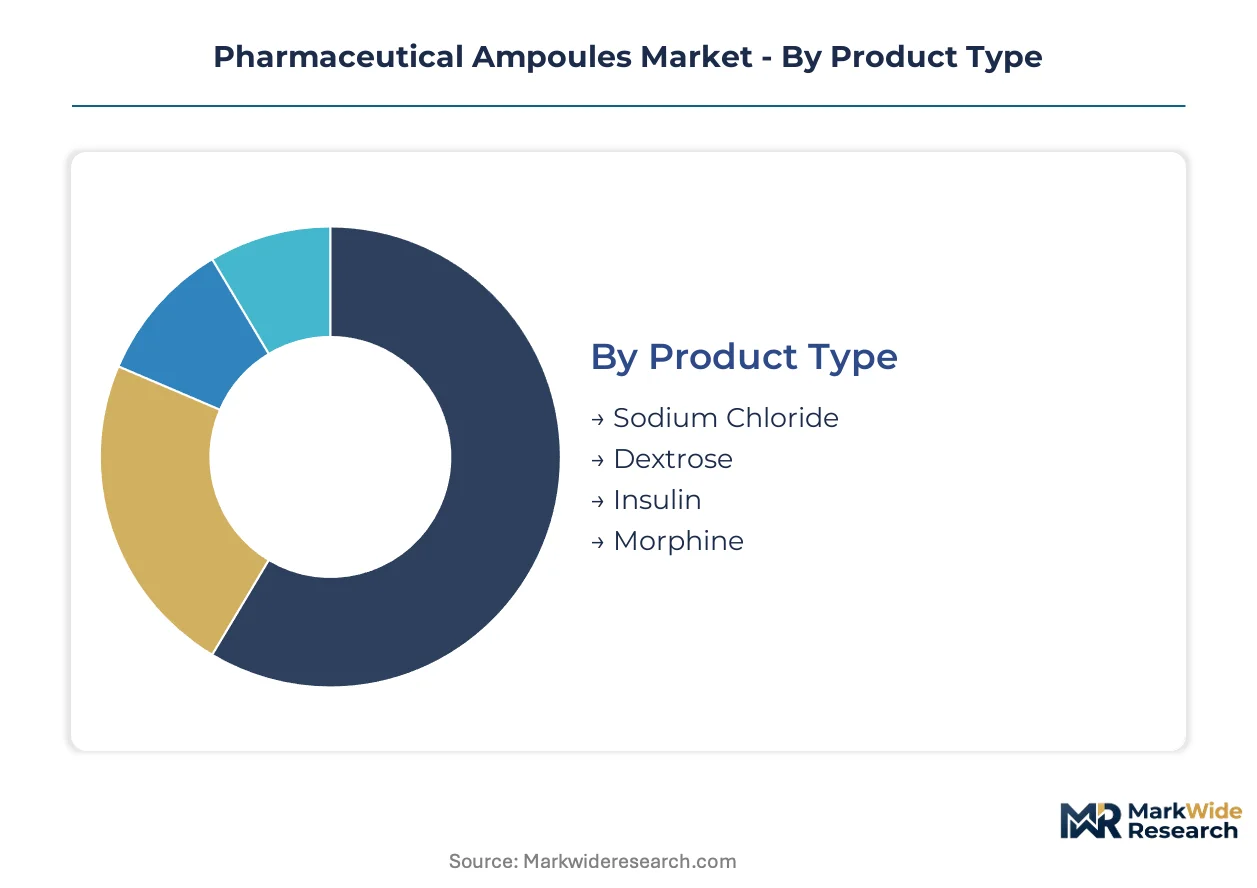
Segmentation in pharmaceutical ampoules reveals how formulation chemistry, material science, and delivery setting intersect to determine packaging specifications. Each dimension carries distinct regulatory and operational implications for manufacturers configuring production lines.
Product Type:
After-sales service intensity varies sharply across therapeutic categories, with biologic formulations demanding specialized technical support for cold chain validation and stability documentation.
- Sodium Chloride:Isotonic saline solutions for intravenous fluid replacement and dilution protocols. Demand concentrates in emergency medicine departments across German and United States hospital systems where rapid volume resuscitation protocols drive standardized procurement.
- Insulin:Temperature-sensitive peptide formulations requiring Type I borosilicate hydrolytic resistance. Homecare self-administration in Germany and the United States is accelerating prefilled ampoule demand as diabetes management shifts beyond clinical settings.
- Dextrose:Hypertonic glucose solutions for parenteral nutrition and hypoglycemia correction. Clinical nutrition protocols in French and Italian hospitals specify 5ml and 10ml formats.
- Morphine:Controlled-substance opioid analgesics with tamper-evident sealing requirements. Palliative care units in Switzerland and the United Kingdom prioritize break-resistant polymer alternatives for patient safety.
Sodium Chloride holds the largest share; momentum sits with Insulin as homecare channels expand.
Material:
Cost tier stratification separates premium borosilicate substrates from commodity polymer alternatives, with pricing spreads reflecting energy intensity and regulatory qualification burdens.
- Glass:Type I borosilicate tubing with FIOLAX composition dominates biologics packaging. EMA and FDA sterility guidelines reinforce glass preference for protein-based therapeutics requiring inert contact surfaces.
- Plastic:Engineered polymers for cytotoxic and radiopharmaceutical applications where breakage risk exceeds material inertness concerns. Oncology centers in France specify plastic for chemotherapy compounding.
- Polypropylene:Cyclic olefin polymer variants gaining share in mRNA vaccine cold chain distribution. Singapore biopharma formulators qualify these for sub-zero storage resilience.
- Polyethylene:Lower-cost option for diagnostic reagents and non-protein parenterals. Indian export manufacturers leverage polyethylene for price-sensitive African and Southeast Asian markets.
Glass commands volume leadership; Polypropylene is climbing the fastest as nucleic acid therapeutics expand.
End User:
Application setting determines packaging performance requirements, with acute care environments prioritizing sterility assurance and outpatient channels emphasizing handling safety.
- Hospitals:Centralized procurement of high-volume parenterals with lot traceability mandates. German hospital consortia bundle ampoule purchasing with infusion sets under quarterly negotiation cycles.
- Homecare:Self-administration protocols for insulin and autoimmune therapies. United States diabetes patients transition from clinic infusion to prefilled formats, expanding patient delivery options.
- Clinics:Ambulatory surgical centers requiring rapid-turnover sterile supplies. Italian day-surgery facilities specify ready-to-use formats to compress aseptic processing steps.
- Pharmacies:Compounding operations with customized dilution and admixture services. Swiss hospital pharmacies maintain glass ampoule stocks for pediatric dose preparation.
Hospitals retain the deepest procurement volume; Homecare shows the steepest expansion trajectory.
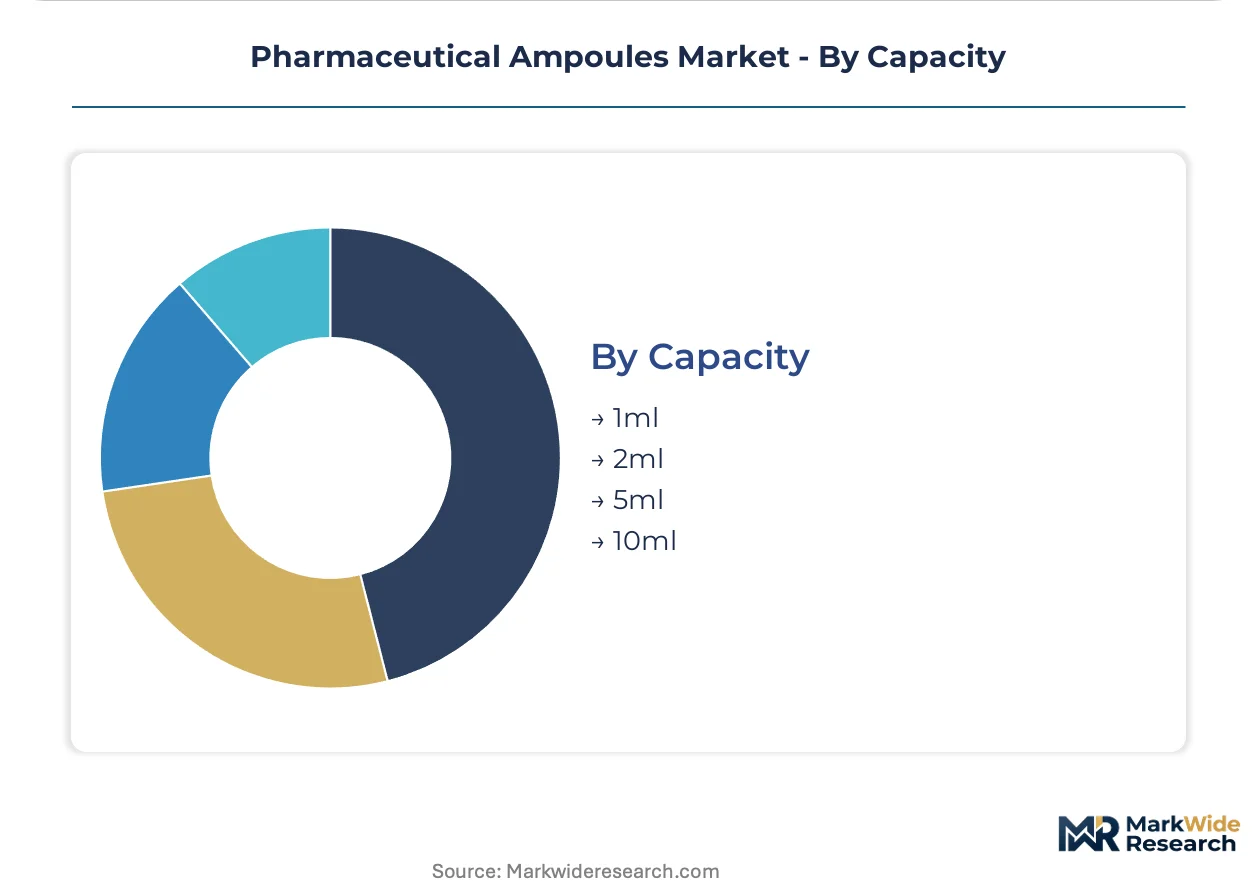
Capacity:
Volume scale aligns with dose standardization across therapeutic categories, with smaller formats commanding premium positioning for high-potency biologics.
- 1ml:High-concentration biologics and pediatric dosing. Monoclonal antibody formulators in Switzerland specify 1ml for subcutaneous injection protocols.
- 2ml:Standard insulin and vaccine presentations. United States diabetes management guidelines normalize 2ml prefilled formats for basal insulin delivery.
- 5ml:Antibiotic and diagnostic reagent volumes. Spanish hospital pharmacies standardize on 5ml for IV push antibiotic administration.
- 10ml:Large-volume parenterals and dilution reservoirs. German emergency departments stock 10ml sodium chloride for trauma resuscitation protocols.
2ml holds the largest share; 1ml gains share fastest as biologic potency concentrations rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty borosilicate glass production clusters in Germany and Switzerland supply converters worldwide, while demand expansion concentrates in North American homecare channels and Asian biopharma manufacturing zones.
Germany
Injectable drug manufacturers in Baden-Württemberg and Bavaria source FIOLAX tubing from captive glassworks for monoclonal antibody filling operations. EU MDR sterility mandates compel local converters to upgrade particulate control systems ahead of Annex 1 enforcement timelines. The Rhine-Main cluster around Mainz anchors Gerresheimer AG and SCHOTT AG production facilities serving European and export markets.
United States
Diabetes patients in Texas and Florida transition from hospital infusion to prefilled insulin ampoules for home self-administration. FDA container closure integrity standards under USP 1207 drive helium leak detection equipment investments at New Jersey and North Carolina filling sites. The Greater Boston biotech corridor demands Type I glass for cell therapy stability protocols.
China
NMPA accelerated approval pathways for innovative drugs expand domestic demand for high-barrier ampoule formats previously imported. The Yangtze River Delta biopharma cluster in Shanghai and Suzhou qualifies local glass converters for mRNA vaccine containment. Domestic tubing expansion reduces dependency on European borosilicate supply.
India
CDSCO alignment with ICH Q3D elemental impurity guidelines positions Gujarat and Maharashtra glass converters to supply regulated African and Southeast Asian markets. Export-oriented manufacturers in Ahmedabad and Mumbai qualify polyethylene formats for price-sensitive therapeutic segments. The country's national pharmaceutical regulator enforces supplier qualification protocols matching EU and US standards.
Switzerland
Swissmedic oversight of biologics packaging maintains Basel and Geneva as qualification centers for barrier-coated alternatives to traditional glass. Plasma-deposited siliconization technologies gain traction among peptide formulators seeking substrate flexibility. The Lake Geneva region hosts technical validation facilities for novel containment systems.
Pharmaceutical Ampoules Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in tubing and forming equipment. The market structures around three tiers: multinational glass converters with captive tubing supply, regional ampoule finishers dependent on merchant tubing, and polymer specialists serving cytotoxic applications. Strategic moves concentrate on backward integration into borosilicate melting and combination product partnerships merging containment with delivery mechanisms.
Among German specialty glassmakers, Gerresheimer AG and SCHOTT AG occupy positions spanning tubing production through finished ampoule conversion. Stevanato Group exemplifies the integrated containment archetype, combining glass primary packaging with closure and delivery system capabilities. These three anchors represent distinct competitive vectors: captive raw material control, technology leadership in substrate formulation, and system-level integration.
| Leading Market Players |
|---|
| Gerresheimer AG |
| SCHOTT AG |
| Stevanato Group |
| Nipro Corporation |
| SGD Pharma |
| James Alexander Corporation |
| ESSCO Glass |
| AAPL Solutions |
| Bormioli Pharma |
| Others |
Value Network & Pricing Analysis
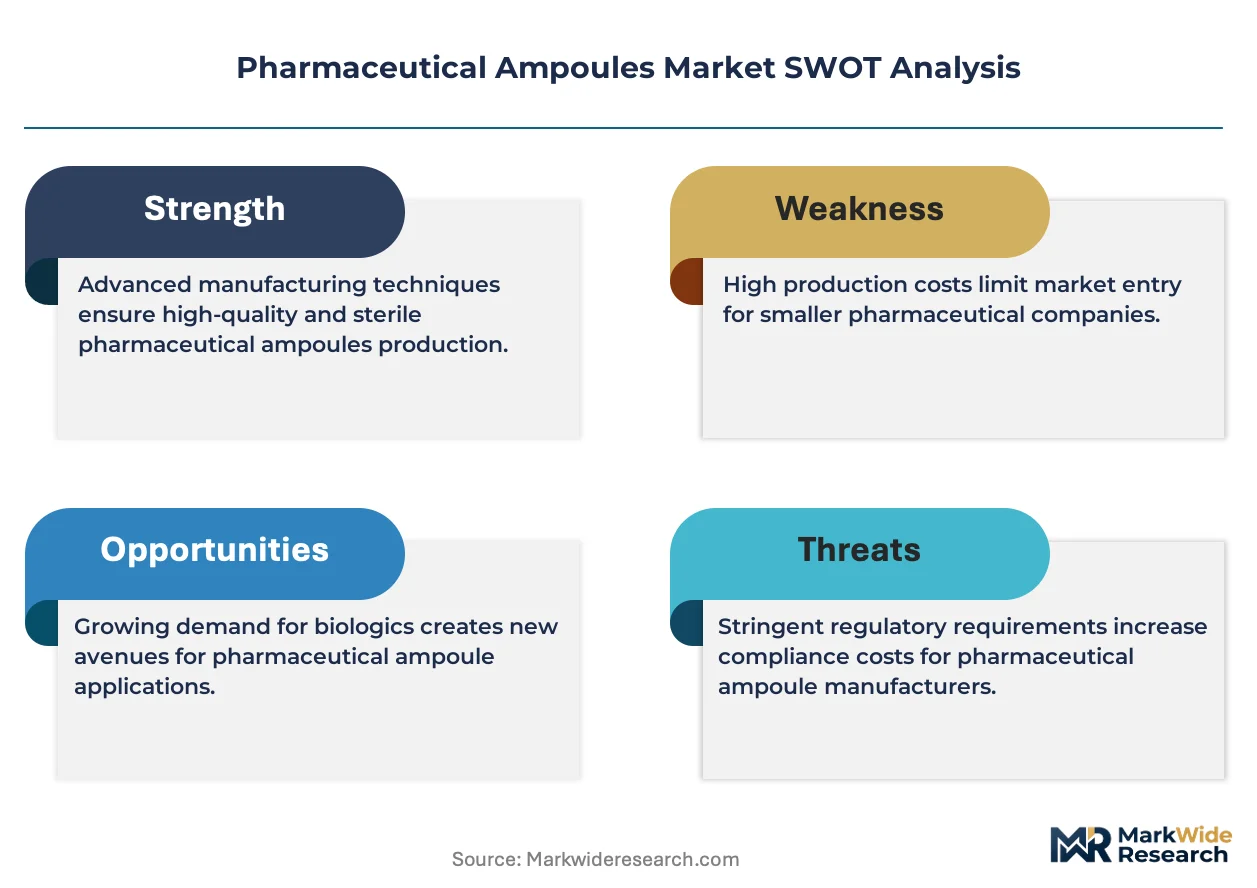
FIOLAX borosilicate glass tubing production concentrates among German specialty glassmakers, anchoring margin pools downstream with finished ampoule converters who command premium positioning through captive supply control. This upstream concentration creates pricing power asymmetries where tubing access determines competitive viability across biologics packaging tiers.
Pricing Analysis
EU MDR sterility mandates dictate the pricing tier structure across pharmaceutical ampoules, separating premium Type I borosilicate formats for biologics from standard soda-lime alternatives for generics. Price differentiation rests on certification grade for Annex 1 compliance and volume scale in hospital procurement consortia. Cost compression in standard glass tiers is intensifying because energy price volatility erodes flame-forming margins. Generic drug manufacturers in India exhibit highest price sensitivity; Swiss biologic formulators show least sensitivity given stability documentation requirements.
Supply Chain Analysis
Gerresheimer AG and SCHOTT AG hold captive borosilicate melting capacity across German and Asian plants, anchoring global supply for Type I pharmaceutical tubing. Raw material flows draw from German specialty sand deposits, natural gas networks for flame working, and platinum-rhodium forming equipment. Single-source vulnerability concentrates in FIOLAX formulation know-how held by two suppliers. Distribution runs through direct contracts with biopharma filling sites and merchant tubing sales to regional converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineers capable of integrating glass forming physics with pharmaceutical quality systems remain scarce across the supplier base, concentrating capability premiums with incumbent European manufacturers. This talent gap shapes competitive durability more than capacity scale alone.
For Market Incumbents: Entrench market position through backward integration into borosilicate melting capacity and accelerated qualification of barrier-coated alternatives to defend against polymer substitution. Polypropylene and cyclic olefin polymer vials threaten glass share in mRNA vaccine applications; vertical integration into tubing supply secures raw material access against energy cost volatility. For New Entrants and Emerging Players: Pursue white-space opportunities in Indian export manufacturing for price-sensitive African and Southeast Asian markets, and in barrier-coated polymer formats for non-protein parenterals. CDSCO-aligned converters serving regulated export markets represent the most penetrable geography; qualification support services for elemental impurity compliance offer a differentiated go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap converters with established hospital procurement relationships and technical validation capabilities for combination product integration. Long-term viability across the analysis window favors suppliers with demonstrated container closure integrity testing infrastructure and regulatory dossier depth. Watch for NMPA accelerated approval volume in China as inflection signal for domestic demand substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Melting | Captive FIOLAX tubing supply insulates Gerresheimer and SCHOTT from merchant market volatility. |
| Barrier Coating Technology Qualification | Plasma-deposited siliconization enables Swiss peptide formulators to diversify substrate options. |
| Combination Product Partnerships | Ampoule-syringe systems command premium positioning in biologics through delivery integration. |
| CDSCO Compliance Investment | ICH Q3D alignment positions Indian converters for regulated export market access. |
| Ready-to-Use Format Expansion | Pre-sterilized ampoules compress aseptic processing steps for Italian day-surgery facilities. |
Research Methodology
A standing panel of regulatory affairs leads, hospital procurement managers, glass forming engineers, and biopharma quality directors provided ongoing calibration against secondary validation. Primary interviews combined with FDA 483 inspection databases, EMA submission records, USP documentary standards, and customs trade flows enabled bottom-up and top-down triangulation.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling volume and value through therapeutic category, material substrate, end-user setting, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate synthesis incorporating biologics pipeline expansion, EU MDR enforcement timing, and homecare channel penetration curves.
Macroeconomic conditions sit as an overlay; deviation in European natural gas pricing, German specialty glass production rates, or Chinese NMPA approval velocity would shift the trajectory. Quarterly review of FIOLAX tubing spot availability, hospital GPO contract renewal cycles, and mRNA vaccine formulation material specifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Cartoning Machines for Pharmaceutical Industry Market
Pharmaceutical Packaging
Pharma Packaging Films Market
Pharmaceutical Packaging
Pharmaceutical Tubes Market
Pharmaceutical Packaging
Pharmaceutical 3PL Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Global Biodegradable Pharmaceutical Packaging Market
Pharmaceutical Packaging
Vial Box Market
Pharmaceutical Packaging
Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
India Pharmaceutical Packaging Market
Pharmaceutical Packaging
Prescription Bottles Market
Pharmaceutical Packaging
Pharmaceutical Printed Cartons Market