
 Essential Oil Containers Market | 2026-2036
Essential Oil Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Essential Oil Containers Market Analysis
Glass is shifting toward borosilicate and amber-tinted variants as brands abandon lower-grade soda-lime formats to protect volatile organic compounds from UV degradation. Gerresheimer AG leverages its pharmaceutical-grade glass expertise to dominate premium essential oil bottle supply. Piramal Glass anchors South Asian production with furnace-scale operations serving export markets. Berlin Packaging competes through its North American distribution network and private-label customization capabilities.
Essential oil containers are purpose-built vessels engineered to prevent oxidation, photodegradation, and evaporation of terpene-rich botanical extracts, typically featuring amber or cobalt glass with light transmission below 10 percent in the UV spectrum. Glass bottles command the largest volume share due to chemical inertness and brand perception, though aluminum cans are gaining traction for travel-size formats where breakage risk constrains glass adoption. Dropper tops lead closure type demand in therapeutic applications requiring precise dosing, while spray pumps expand fastest in room-spray and linen-mist segments where fine atomization determines user experience.
FDA regulations govern essential oil labeling and container safety claims in the United States, while REACH and the EU Green Deal impose material traceability and recyclability mandates across European supply chains. ISO 9001 and pharmaceutical-grade GMP standards increasingly filter into cosmetic and wellness container specifications as brands blur the line between aromatherapy and topical skincare. Stakeholders must monitor how evolving extended producer responsibility frameworks reshape material choices and regional sourcing decisions.
Market Dynamics
REACH compliance and the EU Green Deal are compressing material choice flexibility across essential oil container supply chains, forcing manufacturers to abandon conventional soda-lime glass in favor of traceable, pharmaceutical-grade alternatives that satisfy extended producer responsibility frameworks.
Growth Catalysts
- Aromatherapy brand procurement consolidation:Wellness applications now span therapeutic, cosmetic, and home-fragrance verticals, concentrating container volumes with suppliers capable of multi-format customization.
- REACH material mandates:European chemical traceability requirements are accelerating adoption of certified borosilicate and amber-tinted glass with documented recyclability credentials.
- UV-protective glass chemistry:Terpene preservation demands are pulling brands toward cobalt and amber variants with sub-10 percent light transmission in the UV spectrum.
Market Restraints
- Energy-intensive furnace operations:Glass container manufacturing requires sustained high-temperature melting, exposing producers to natural gas price volatility and carbon border adjustment exposure.
- German production cluster concentration:Essential oil processing and container sourcing gravity centers on Rhineland-Palatinate and Bavaria, creating geographic vulnerability to single-region logistics disruption.
- Aluminum substitution in travel formats:Breakage-risk constraints on glass are enabling metal can penetration in portable and airline-compliant packaging below 100 milliliters.
Strategic Opportunities
- Indian export manufacturing scale:Furnace-scale glass operations serving European and North American wellness brands offer cost-competitive pharmaceutical-grade capacity outside EU energy cost structures.
- Biophotonic glass technology convergence:Integration of violet-filtering glass chemistry with tamper-evident closure systems addresses both photodegradation and counterfeit protection in premium segments.
- Direct-to-consumer channel expansion:Subscription aromatherapy services are bypassing traditional wholesale distribution, demanding smaller-batch container runs with rapid design turnaround.
Industry Challenges
- Pharmaceutical-grade GMP certification timelines:Cosmetic and wellness brands seeking to blur positioning with topical skincare face 12-to-18-month facility qualification periods that delay market entry.
- Closure-system integration complexity:Dropper, pump, and spray mechanisms must maintain chemical inertness with terpene-rich contents while satisfying child-resistance and ISO 9001 quality benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Essential Oil Containers Market |
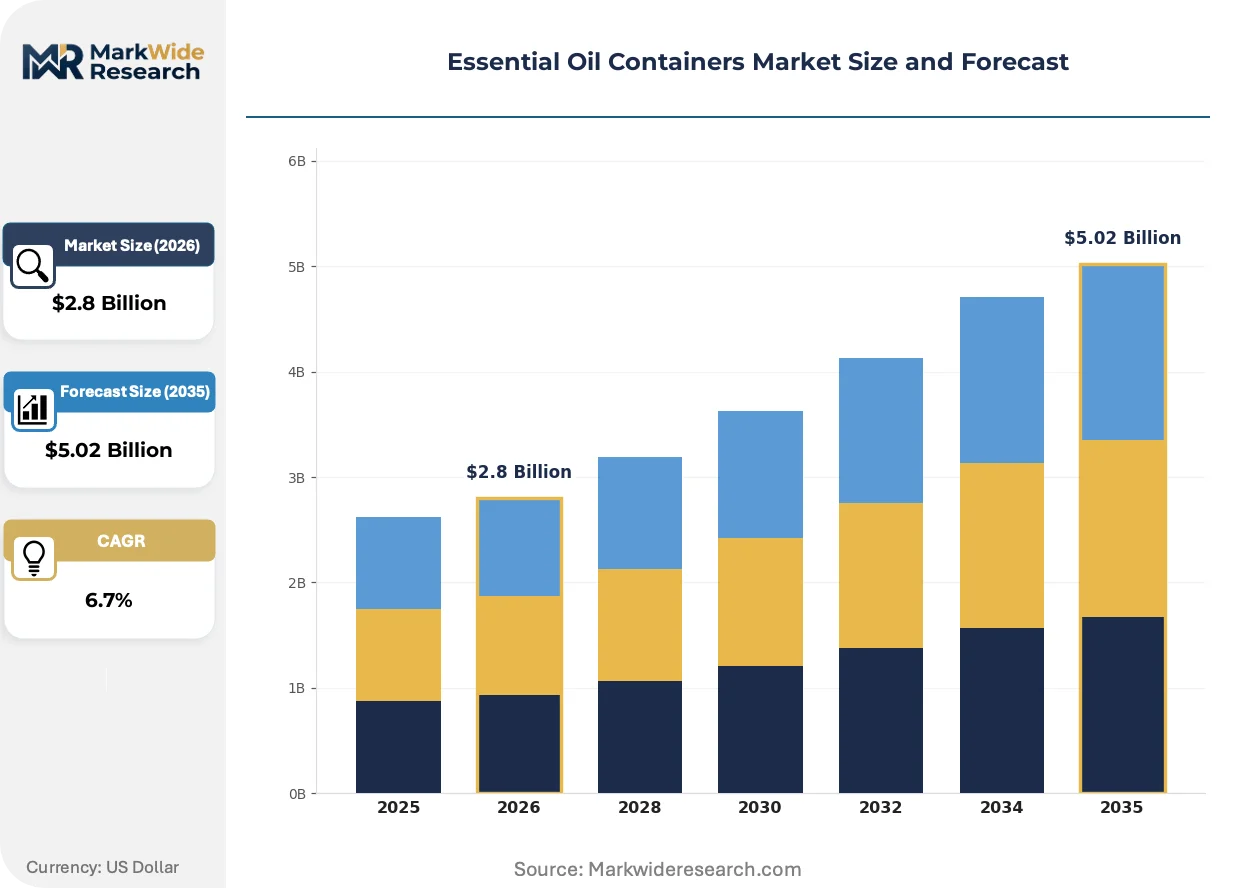
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Glass Bottles, Plastic Bottles, Aluminum Cans, Wooden Boxes Closure Type: Dropper Tops, Screw Caps, Spray Pumps, Cork Stoppers Size: 5ml, 10ml, 50ml, 100ml Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Gerresheimer AG, Ardagh Group, Piramal Glass, Vitro Packaging, JL Glass Company, Berlin Packaging, SKS Bottle & Packaging, Alpha Packaging, Drug Plastics Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Essential Oil Containers Market Emerging Trajectories
Container engineering is converging with pharmaceutical packaging standards as essential oil brands seek to signal purity and potency through material science rather than label claims alone.
Borosilicate glass is integrating into premium essential oil packaging as brands abandon thermal-shock-prone soda-lime formats. Aromatherapy and clean-beauty labels are adopting this chemistry fastest, prioritizing dimensional stability during steam sterilization and temperature cycling. The technology is integrating quality-tier segmentation into supply chains, compressing margins for commodity glass converters unable to upgrade furnace chemistry.
REACH substance restriction expansions are tightening permissible additives in colored glass and closure elastomers across European supply chains. Industrial consequence includes mandatory supply-chain documentation for cadmium, lead, and chromium content in amber and cobalt tints. Cosmetic and therapeutic essential oil brands exporting into Germany, France, and the Netherlands are reformulating specifications preemptively to avoid customs detention.
Wellness brand procurement is consolidating around suppliers offering combined container-closure-label decoration services. Mid-market aromatherapy labels are abandoning fragmented sourcing of bottles, droppers, and cartons in favor of turnkey private-label partnerships. This consolidation is most visible in North American direct-to-consumer channels where speed-to-shelf determines competitive survival.
Essential Oil Containers Market Segmentation
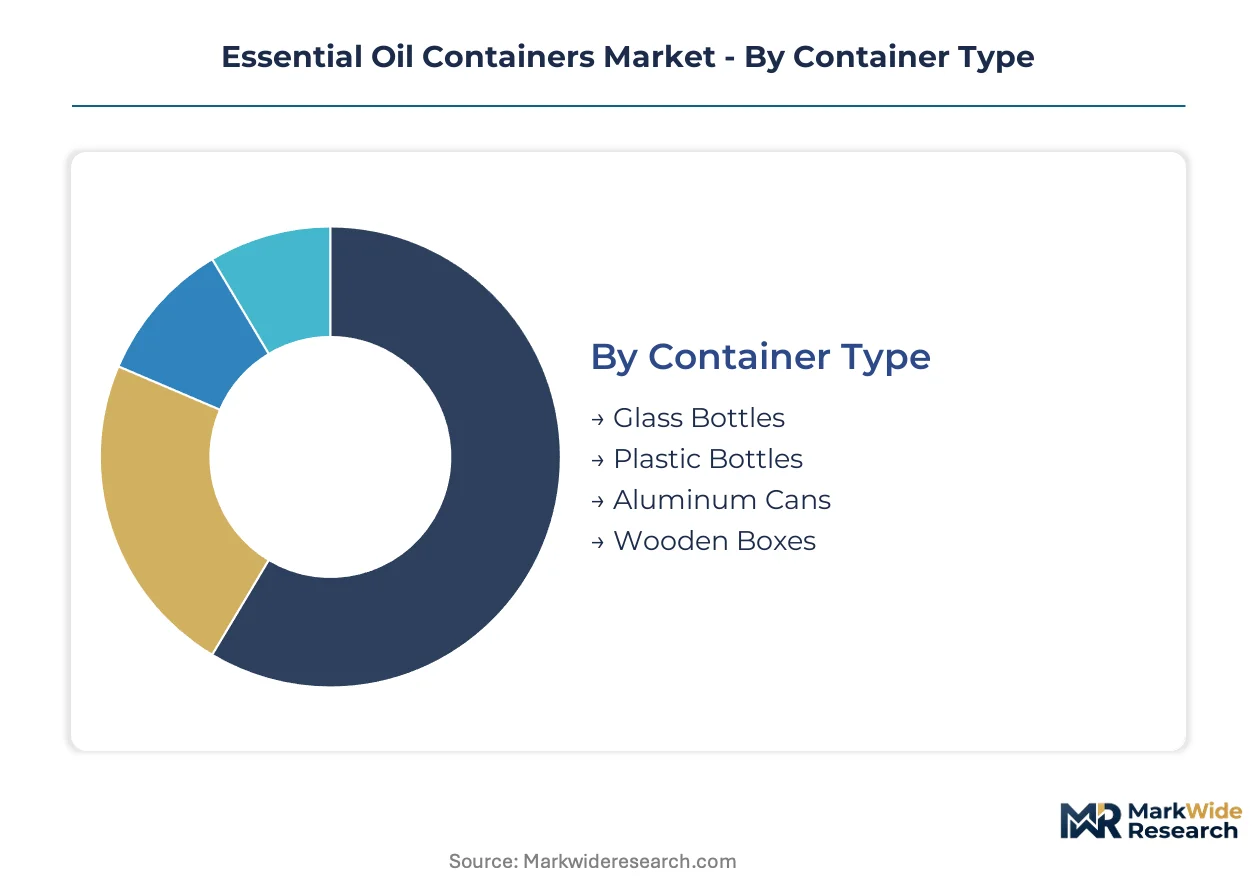
Container selection in essential oil packaging hinges on terpene preservation chemistry, regulatory compliance grade, and end-use handling requirements. Each segmentation dimension carries distinct supply chain implications for material sourcing, furnace capacity allocation, and closure system integration.
Container Type:
Glass furnace capacity concentrates with pharmaceutical-grade converters serving wellness brands with documented REACH traceability.
- Glass Bottles:Amber and cobalt borosilicate variants dominate premium positioning due to sub-10 percent UV transmission specifications. Demand clusters with German aromatherapy processors and North American clean-beauty labels seeking chemical inertness credentials.
- Plastic Bottles:Polyethylene terephthalate and fluoropolymer formats serve cost-sensitive mass-market segments where breakage risk and weight reduction outweigh photodegradation concerns. Procurement volumes concentrate with private-label wellness brands in direct-to-consumer channels.
- Aluminum Cans:Lightweight metal formats penetrate travel-size and airline-compliant packaging below 100 milliliters where glass fragility constrains adoption.
- Wooden Boxes:Secondary presentation packaging for gift sets and subscription services, sourced from sustainable forestry certified suppliers.
Glass bottles absorb the bulk of installed furnace capacity; aluminum cans are expanding most quickly in portable format segments.
Closure Type:
Closure engineering complexity rises with precision dosing requirements and child-resistance mandates across therapeutic applications.
- Dropper Tops:Glass and plastic pipette assemblies with bulb mechanisms enable milliliter-accurate dispensing for clinical aromatherapy protocols. Demand concentrates with European wellness brands positioning at the cosmetic-pharmaceutical boundary.
- Spray Pumps:Fine atomization systems serve room-spray and linen-mist applications where particle size distribution determines user experience. Fastest adoption occurs in North American home-fragrance subscription services.
- Screw Caps:Polypropylene and phenolic resin formats provide cost-efficient sealing for bulk storage and refill applications.
- Cork Stoppers:Natural and synthetic cork variants persist in artisanal and heritage-positioned brands emphasizing traditional extraction methods.
Dropper tops command the largest share of closure procurement spend; spray pumps are climbing the fastest as home-fragrance applications broaden.
Size:
Volume tiering reflects dosing frequency, portability requirements, and subscription service packaging economics.
- 10ml:Standard therapeutic dosing format balancing portability with sufficient supply duration for monthly treatment protocols. German and French aromatherapy brands anchor procurement volumes.
- 5ml:Trial-size and travel-compliant format serving airline regulation limits and sampling programs. Fastest growth tracks direct-to-consumer subscription trial boxes.
- 50ml:Professional practitioner and high-frequency home-use format where per-milliliter cost optimization outweighs portability.
- 100ml:Bulk refill and institutional supply tier for spas, clinics, and commercial diffusing installations.
10ml formats absorb the bulk of production line capacity; 5ml sizes are gaining share fastest through subscription channel expansion.
Distribution Channel:
Channel structure determines batch size requirements, labeling complexity, and speed-to-shelf pressures across container procurement.
- Online Retail:Direct-to-consumer platforms demand smaller production runs with rapid design turnaround and unboxing-optimized secondary packaging. North American wellness startups drive procurement fragmentation.
- Specialty Stores:Curated retail environments require premium finishing and tactile differentiation through embossing, silk-screening, and closure weight specifications.
- Supermarkets:Mass-market placement necessitates cost-optimized standard formats with shelf-ready secondary packaging and consolidated logistics.
- Wholesale:Institutional and practitioner supply channels prioritize palletization efficiency and bulk closure compatibility over aesthetic differentiation.
Online retail absorbs the bulk of design-flexible production capacity; specialty stores are expanding most quickly as experiential retail differentiates against digital commoditization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aromatherapy brand procurement concentrates in Germany, where essential oil processing clusters anchor glass container sourcing across the Rhine-Main corridor. Wellness applications now span therapeutic, cosmetic, and home-fragrance verticals, concentrating container volumes with suppliers capable of multi-format customization. REACH compliance and the EU Green Deal are compressing material choice flexibility across European supply chains.
Germany
Pharmaceutical-grade glass demand from Rhineland-Palatinate and Bavaria processing clusters drives borosilicate procurement volumes. The EU Green Deal imposes material traceability and recyclability mandates that favor documented supply chains. Cologne and Mainz anchor furnace-scale operations serving wellness brands with REACH-certified amber and cobalt variants.
United States
Direct-to-consumer subscription services fragment procurement toward smaller-batch container runs with rapid design turnaround. FDA regulations govern essential oil labeling and container safety claims, pushing brands toward documented chemical inertness. New Jersey and Pennsylvania distribution networks compete through private-label customization capabilities for North American clean-beauty labels.
India
Export manufacturing scale offers cost-competitive pharmaceutical-grade capacity outside EU energy cost structures. BIS standards and DGFT export facilitation support furnace-scale glass operations serving European and North American wellness brands. Gujarat and Maharashtra anchor production clusters where Piramal Glass maintains furnace-scale operations for international markets.
France
ANSM cosmetic-therapeutic boundary enforcement pulls brands toward ISO 9001 and pharmaceutical-grade GMP standards. The EU Green Deal extended producer responsibility frameworks reshape material choices for Paris and Lyon-based aromatherapy formulators. Provence-Alpes-Côte d'Azur essential oil extraction traditions sustain demand for heritage-positioned packaging formats.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance tracks for REACH-equivalent substance restrictions. London and Southeast England direct-to-consumer wellness startups drive procurement fragmentation toward unboxing-optimized secondary packaging. Midlands distribution hubs consolidate logistics for subscription aromatherapy services bypassing traditional wholesale channels.
Essential Oil Containers Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium therapeutic positioning favoring pharmaceutical-grade converters while mass-market wellness channels fragment toward private-label fabricators. The vendor base organizes around three archetypes: furnace-scale glass specialists with documented REACH traceability, North American distribution-integrated packagers with rapid-turn customization capabilities, and Indian export manufacturers leveraging cost-competitive energy structures. Consolidation pressures concentrate in European supply chains where carbon border adjustments and natural gas price volatility compress commodity converter margins. Competitive moves center on pharmaceutical-grade GMP certification timelines and combined container-closure-label decoration service bundling.
Among furnace-scale specialists, Gerresheimer AG and Piramal Glass exemplify the pharmaceutical-grade archetype, with the former leveraging German furnace chemistry expertise and the latter anchoring South Asian export capacity. Berlin Packaging occupies a position within the North American distribution-integrated tier, competing through private-label customization capabilities rather than captive manufacturing scale. These three companies represent divergent strategic responses to REACH compliance pressures and wellness brand procurement consolidation.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Ardagh Group |
| Piramal Glass |
| Vitro Packaging |
| JL Glass Company |
| Berlin Packaging |
| SKS Bottle & Packaging |
| Alpha Packaging |
| Drug Plastics Group |
| Others |
Supply Flow & Price Mechanics
Family-owned furnace operators in Germany and Gujarat anchor production capacity, connecting disciplined capacity allocation to pricing power in pharmaceutical-grade glass tiers. Their long-tenured supplier relationships with Rhineland-Palatinate aromatherapy processors reinforce contract-based offtake structures that insulate premium borosilicate pricing from commodity soda-lime volatility.
Pricing Analysis
Volume procurement concentrates with mass-market wellness brands demanding cost-optimized PET and fluoropolymer formats, while margin capture concentrates with pharmaceutical-grade borosilicate converters serving therapeutic-positioned labels. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified amber glass from ISO 9001 mid-tier formats from unbranded commodity bottles. Cost compression in standard-tier soda-lime glass is intensifying because EU carbon border adjustments expose energy-intensive furnace operations to natural gas price volatility. Direct-to-consumer subscription brands exhibit highest price sensitivity, while clinical aromatherapy practitioners purchasing 50ml practitioner formats demonstrate lowest elasticity due to terpene preservation requirements.
Supply Chain Analysis
Extended producer responsibility frameworks in Germany and France are mandating return-flow documentation for amber and cobalt glass cullet, embedding reverse logistics into furnace feedstock planning. Primary manufacturing draws from Germany, India, and the United States, with Gujarat furnace-scale operations serving North American and European export demand. Raw material dependencies center on silica sand from Bavarian quarries, soda ash from Wyoming trona deposits, and cobalt oxide for UV-protective tinting. Single-source vulnerability concentrates in Rhineland-Palatinate processing clusters where aromatherapy brand procurement anchors glass container demand. Distribution runs through North American private-label packagers and European pharmaceutical-grade converters with documented REACH traceability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container procurement is becoming a vertical-integration race as wellness brands pursue upstream control over pharmaceutical-grade furnace capacity to secure REACH-compliant supply. This structural shift rewards players with captive borosilicate production or long-term offtake agreements with German and Indian furnace operators.
For Market Incumbents: To counter aluminum substitution in travel-format segments below 100 milliliters, Gerresheimer AG and Piramal Glass should deepen backward integration into cobalt oxide sourcing and expand pharmaceutical-grade GMP certification timelines. Capacity addition in Gujarat offers cost-competitive energy structures outside EU carbon border exposure. Certification investment in ISO 9001 and REACH documentation systems reinforces switching costs for aromatherapy brands blurring cosmetic-pharmaceutical boundaries. For New Entrants and Emerging Players: REACH substance restriction expansions in France and the Netherlands open a window for specialty closure manufacturers offering documented elastomer compliance for dropper bulb assemblies. The most penetrable segment sits with North American direct-to-consumer subscription services demanding rapid-turn design capabilities and unboxing-optimized secondary packaging. A go-to-market angle combining container-closure-label decoration bundling with 5ml trial-format specialization bypasses entrenched furnace-scale competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Indian furnace operators with pharmaceutical-grade capacity and DGFT export facilitation in Gujarat and Maharashtra. Long-term viability over a 5-10 year window rests on positioning for EU Green Deal extended producer responsibility mandates and carbon border adjustment mechanics. The signal to watch is German natural gas price volatility compressing commodity converter margins and triggering consolidation among soda-lime specialists unable to upgrade borosilicate chemistry.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade GMP Certification | ISO 9001 and GMP qualification opens clinical aromatherapy procurement channels in Germany and France. |
| Backward Integration into Cobalt Oxide | Captive supply of UV-protective tinting raw materials insulates margins from REACH documentation costs. |
| Direct-to-Consumer Channel Expansion | Subscription aromatherapy services demand rapid-turn 5ml and 10ml container runs with design flexibility. |
| Combined Decoration Service Bundling | Turnkey container-closure-label partnerships consolidate fragmented procurement for mid-market wellness brands. |
| Indian Export Manufacturing Scale | Gujarat furnace operations offer cost-competitive pharmaceutical-grade capacity outside EU energy structures. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this essential oil containers analysis. Primary interviews with furnace operations managers, aromatherapy brand procurement leads, pharmaceutical packaging engineers, and REACH compliance consultants combined with ECHA substance restriction databases, BIS standards documentation, and DGFT export facilitation records. Bottom-up volume modeling across container type, closure mechanism, and size tier triangulated against top-down value estimates from furnace capacity utilization and regional pricing benchmarks.
Data-stream reconciliation across production volume disclosures, import-export trade flows, and brand procurement surveys informed the analytical framework across the analysis window. Segmentation dimensions modeled include container material chemistry, closure precision requirements, volume tier portability needs, and distribution channel batch-size economics. CAGRs derived from trend extrapolation of furnace capacity expansion, aromatherapy brand procurement consolidation patterns, and regulatory compliance cost pass-through mechanics. Industry-specific forecast inputs incorporated EU Green Deal extended producer responsibility implementation timelines and REACH substance restriction expansion schedules.
Caveats apply where EU carbon border adjustment mechanics, natural gas price volatility, or aluminum substitution acceleration in travel formats could materially shift the outlook. Forecasts reflect assumptions about pharmaceutical-grade certification adoption rates and wellness brand vertical integration propensity. Practitioners should monitor German furnace operator margin compression and Indian export capacity utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
2 Piece Cans Market
Containers
Child-Resistant Containers Market
Containers
PET Hinged Containers Market
Containers
Roll Containers Market
Containers
Wet Wipes Canister Market
Containers
Screw Top Lids Market
Containers
ISO Container Market
Containers
Collapsible Crate Market
Containers
PP Container Liner Market
Containers
Vacuum Formed Tray Market
Containers
Half Height Containers Market
Containers
Oblong Jar Market
Containers
Pail Lids Market
Containers
Container Stacking Machine Market
Containers
Insert Trays Market
Containers
HDPE Crates Market