
 Container Market | 2026-2036
Container Market Size, Share, and Industry Trends Forecast 2026-2036
Container Market Analysis
Container leasing and asset-light operating models is rewriting competitive dynamics in the maritime box sector. MSC leverages its owned-fleet scale to control slot availability across trunk routes. Maersk anchors its integrated logistics strategy through captive container supply. COSCO Shipping sustains cost leadership via backward integration into Chinese steel sourcing and domestic manufacturing.
A container is a standardized, reusable steel or aluminum enclosure built to ISO 668 dimensional and strength specifications, designed for intermodal freight transport across ship, rail, and truck networks. Wall construction typically employs corrugated corten steel panels with marine-grade plywood flooring to withstand stacking loads exceeding 190 metric tonnes and saltwater exposure. Dry containers occupy the mature volume core of the market, while refrigerated containers capture disproportionate margin pools from pharmaceutical and fresh-food cold-chain requirements. Tank containers lead specialized growth as chemical and food-grade liquid shippers convert from bulk transport to modal flexibility.
The International Maritime Organization enforces vessel efficiency standards that cascade into container fleet specifications through EEDI and CII compliance timelines. China's SAMR administers GB/T national standards for container construction and testing that govern export eligibility from domestic factories. The EU Green Deal's extended producer responsibility frameworks are pressuring European logistics operators to document container lifecycle emissions and recyclability. Stakeholders must weigh capital deployment between owned fleets and third-party leasing as regulatory compliance costs and carbon accounting obligations reshape total-cost-of-ownership calculations.
Market Dynamics
Carbon intensity regulations from the International Maritime Organization are forcing fleet-wide container renewal toward lightweight composite designs and energy-efficient refrigeration systems, compressing asset lifecycles and reshaping capital allocation across lessors and carriers.
Growth Catalysts
- Cold-chain pharmaceutical logistics:Temperature-sensitive biologics distribution is expanding reefer container deployment across intermodal networks. Vaccine and cell-therapy supply chains require validated thermal control from manufacturing through last-mile delivery.
- China's dual carbon goals:Domestic steel decarbonization mandates are accelerating production of lower-emission corten steel for container fabrication. COSCO Shipping and Yangzijiang Shipbuilding are scaling manufacturing capacity along the Yangtze River Delta.
- E-commerce perishable fulfillment:Online grocery and meal-kit platforms are driving demand for last-mile refrigerated container assets. Dark-store networks in urban clusters require modular cold-storage units compatible with drayage and final delivery.
Market Restraints
- Corten steel price volatility:Input costs for marine-grade weathering steel fluctuate with iron ore and scrap metal markets. Chinese steel export tariffs create margin pressure for container manufacturers dependent on domestic supply.
- Refrigerant regulatory transition:The EU F-Gas Regulation and US EPA SNAP program are phasing down hydrofluorocarbon refrigerants in reefer units. Retrofit costs and refrigerant availability constraints extend equipment replacement cycles.
- Asset ownership concentration:The top five container lessors control majority lease fleet capacity. TAL International, Triton International, and Textainer's combined market position limits pricing power for smaller regional operators.
Strategic Opportunities
- India port infrastructure expansion:Jawaharlal Nehru Port and Mundra Port capacity additions are creating demand for dry and specialized container assets. The Sagarmala program is modernizing coastal connectivity for manufacturing export zones.
- Blockchain-enabled asset tracking:Integration of IoT sensors with distributed ledger technology is virtualizing container documentation and custody transfer. Smart contracts for demurrage and detention are reducing dispute resolution friction.
- EU Green Deal circularity requirements:Extended producer responsibility frameworks are mandating container lifecycle documentation and end-of-life recyclability. Leasing operators can capture premium pricing for certified circular supply chains.
Industry Challenges
- Reefer technician scarcity:Specialized maintenance skills for refrigeration compressors and electronic control systems are concentrated among aging workforces in Europe and East Asia. Training pipeline gaps extend equipment downtime during peak seasons.
- CII compliance data integration:Container weight and positioning data must feed into vessel carbon intensity calculations. Legacy terminal operating systems lack API connectivity for real-time emissions reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Container Market |
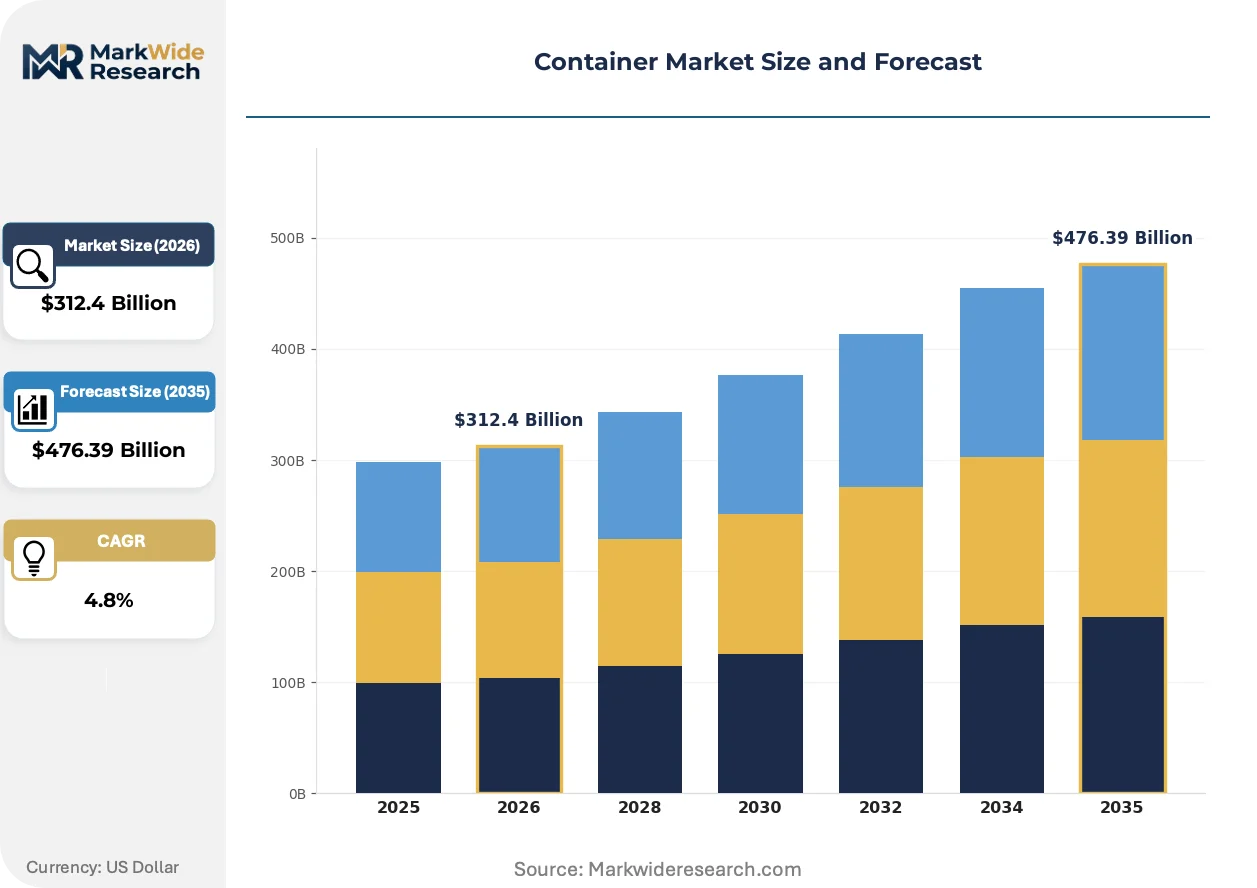
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $476.39 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Dry Containers, Refrigerated Containers, Tank Containers, Open Top Containers Material: Steel, Aluminum, Plastic, Composite Application: Logistics, Storage, Shipping, Manufacturing Size: 20 Feet, 40 Feet, 45 Feet, Custom Size |
| Companies Covered | MSC, Maersk, CMA CGM, COSCO Shipping, Hapag-Lloyd, Evergreen Marine Corporation, ONE, HMM, Yang Ming Marine Transport Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Container Market Emerging Trajectories
Digitization of container documentation and custody chains is compressing transaction costs while regulatory pressure on embodied carbon is reshaping material specifications and manufacturing geography.
Composite sandwich panel technology is virtualizing traditional corrugated steel construction in select reefer applications. Pharmaceutical shippers adopting lightweight fiber-reinforced polymer containers for high-value cold-chain lanes are reducing tare weight and fuel consumption. This material transition is displacing conventional aluminum framing in premium temperature-controlled segments where payload sensitivity outweighs capital cost premiums.
The EU Green Deal's Carbon Border Adjustment Mechanism is imposing emissions documentation requirements on imported steel-intensive goods. Container manufacturers exporting from China to European markets must verify production carbon intensity through certified auditors. Reefer container assemblers are relocating final finishing operations to EU-adjacent jurisdictions to minimize tariff exposure and logistics lead times.
Shippers are consolidating procurement through managed fleet programs rather than transactional spot leasing. Large agricultural exporters and chemical distributors are negotiating multi-year container supply agreements with embedded maintenance and repositioning services. This preference shift is most visible in Brazil's soybean export corridor and Germany's chemical Rhine-Ruhr cluster, where integrated logistics contracts now specify equipment availability guarantees rather than per-diem rates.
Container Market Segmentation
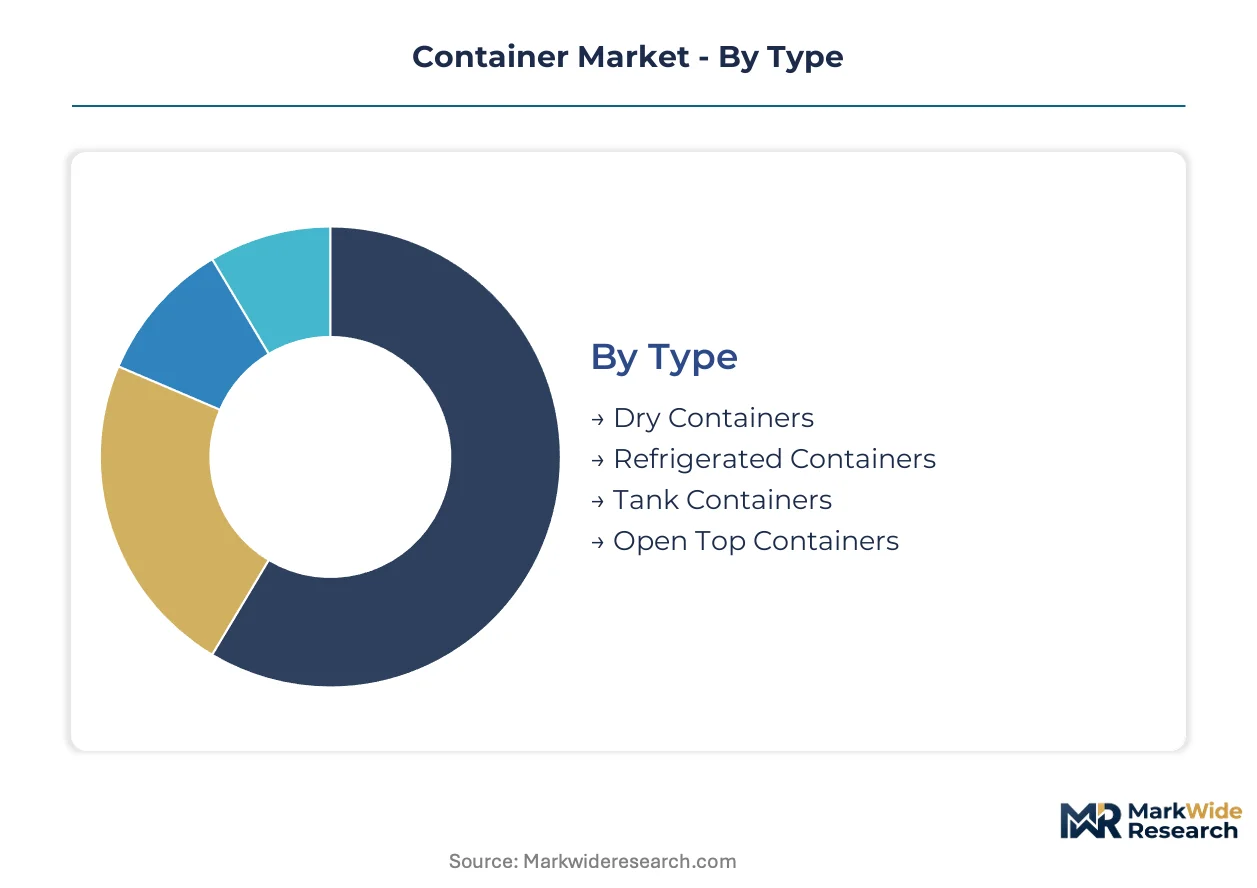
Container segmentation reveals divergent margin structures across equipment types and material specifications. Intermodal operators allocate capital between standardized dry assets and specialized reefer or tank configurations based on cargo density and regulatory exposure. Understanding these segment boundaries clarifies where leasing premiums concentrate versus where commoditization erodes returns.
Type:
Mature dry containers anchor volume throughput while specialized refrigerated and tank variants capture expanding premium pools from temperature-sensitive and liquid cargo networks.
- Dry Containers:Corrugated corten steel enclosures built to ISO 668 specifications for general cargo intermodal transport. Demand concentrates in China's Yangtze River Delta manufacturing clusters where COSCO Shipping and domestic lessors expand fleet capacity for export manufacturing. Steel price volatility and carbon border documentation requirements compress margins for standardized units.
- Refrigerated Containers:Insulated enclosures with integrated compressor units maintaining controlled temperatures for perishables and pharmaceuticals. E-commerce grocery fulfillment networks in urban clusters drive last-mile deployment for dark-store cold chains. EU F-Gas Regulation refrigerant phase-downs extend replacement cycles and concentrate technician skills in East Asia and Europe.
- Tank Containers:Cylindrical stainless steel vessels within ISO frames for chemical and food-grade liquid transport. Chemical shippers along Germany's Rhine-Ruhr corridor convert from bulk to modal-flexible intermodal solutions.
- Open Top Containers:Removable tarpaulin roof designs for heavy machinery and bulk commodity loading. Project cargo flows through Jawaharlal Nehru Port and Mundra Port infrastructure expansions under India's Sagarmala program.
Dry containers retain volume leadership; refrigerated containers hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity steel from lightweight premium alternatives where payload sensitivity justifies capital premiums.
- Steel:Corten weathering steel dominates dry container fabrication with marine-grade corrosion resistance. China's SAMR-administered GB/T national standards govern export eligibility from domestic factories. Dual carbon goals accelerate lower-emission steel production along the Yangtze River Delta.
- Aluminum:Lightweight framing historically standard in reefer construction now faces displacement. Pharmaceutical cold-chain lanes adopt fiber-reinforced alternatives reducing tare weight for high-value cargo.
- Plastic:Polymer-based modular units for urban last-mile and temporary storage applications. Dark-store networks deploy plastic containers for rapid repositioning within city distribution zones.
- Composite:Fiber-reinforced polymer sandwich panels enabling significant tare weight reduction. EU Green Deal Carbon Border Adjustment Mechanism pressures verification of embodied carbon in imported steel-intensive goods.
Steel retains cost-driven volume dominance; composite materials climb the fastest on regulatory pressure and payload optimization.
Application:
Customer type differentiation separates asset-heavy shipping lines from asset-light logistics integrators and third-party storage operators.
- Logistics:Integrated supply chain operators deploy containers across multimodal networks with embedded maintenance and repositioning services. MSC controls slot availability through owned-fleet scale while Maersk anchors captive container supply for integrated logistics strategies.
- Storage:Static deployment for inventory buffering and seasonal demand absorption. Manufacturing export zones in India require modular storage compatible with port connectivity modernization.
- Shipping:Ocean carriers balance owned versus leased fleet composition against CII compliance data integration requirements. Legacy terminal operating systems lack API connectivity for real-time emissions reporting.
- Manufacturing:Captive container supply for vertical production-to-export workflows. COSCO Shipping sustains cost leadership through backward integration into Chinese steel sourcing and domestic manufacturing.
Shipping applications retain fleet scale leadership; logistics integration holds the steepest expansion curve.
Size:
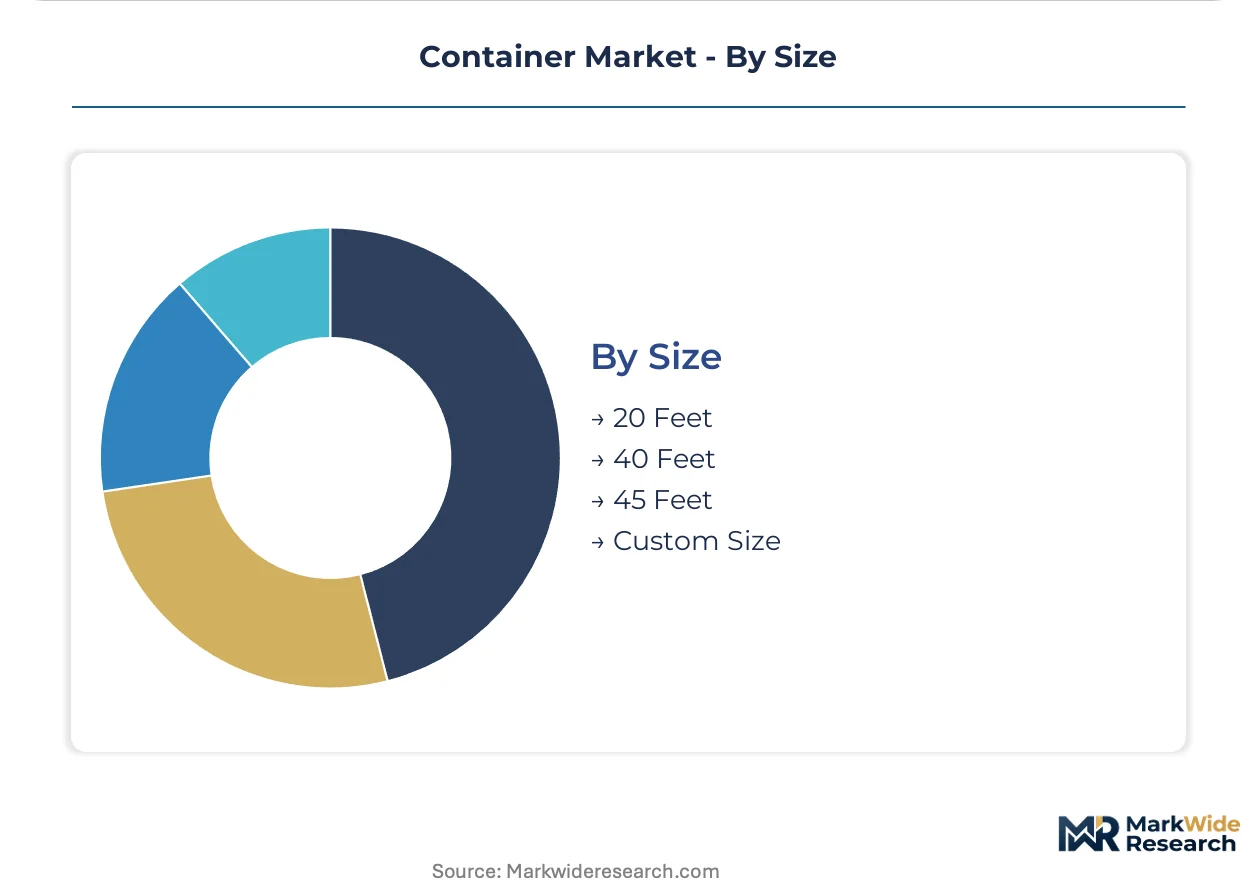
Volume concentration favors standardized twenty-foot and forty-foot equivalents while custom dimensions serve niche project cargo and regional gauge constraints.
- 20 Feet:The TEU benchmark for weight-dense cargo and regional rail gauge compatibility. Brazilian soybean export corridors specify twenty-foot availability guarantees in multi-year supply agreements.
- 40 Feet:Dominant FEU standard for volume-efficient consumer goods and light manufactured products. E-commerce fulfillment networks optimize for forty-foot cube utilization in trans-Pacific lanes.
- 45 Feet:Extended length for European road and rail intermodal compatibility. EU Green Deal circularity requirements mandate lifecycle documentation for these higher-capacity units.
- Custom Size:Project-specific dimensions for oversized machinery and specialized industrial equipment. ANVISA-regulated pharmaceutical flows in Brazil require validated thermal control in non-standard configurations.
Forty-foot containers retain volume leadership; custom sizes hold the steepest expansion curve on project cargo specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon border documentation requirements and port infrastructure modernization programs are redistributing container manufacturing and leasing activity across strategic geographies. Fleet operators navigate divergent regulatory timelines for refrigerant phase-downs, steel decarbonization mandates, and vessel efficiency standards.
China
Yangtze River Delta manufacturing clusters dominate dry container fabrication through SAMR-administered GB/T national standards compliance. Dual carbon goals accelerate lower-emission corten steel production at COSCO Shipping and Yangzijiang Shipbuilding facilities. Shanghai and Ningbo-Zhoushan port complexes anchor captive container supply chains for export manufacturing zones.
Germany
Rhine-Ruhr chemical corridors drive tank container demand as shippers convert from bulk to modal-flexible intermodal solutions. EU F-Gas Regulation refrigerant phase-downs extend reefer replacement cycles across Hamburg and Bremerhaven port networks. KBA-administered transport safety frameworks govern specialized container certification for pharmaceutical cold-chain lanes.
United States
E-commerce grocery fulfillment networks expand refrigerated container deployment across urban dark-store clusters. EPA SNAP program constraints on hydrofluorocarbon refrigerants compress equipment procurement timelines for West Coast port operators. Los Angeles-Long Beach and Savannah port authorities modernize terminal operating systems for CII compliance data integration.
India
Sagarmala program investments at Jawaharlal Nehru Port and Mundra Port generate demand for dry and open-top container assets. DGFT export incentive schemes support manufacturing export zone connectivity along western and eastern coastal corridors. Maharashtra and Gujarat industrial clusters require modular cold-storage units compatible with drayage and final-mile delivery networks.
Brazil
Soybean export corridors specify twenty-foot container availability guarantees in multi-year agricultural supply agreements. ANVISA pharmaceutical regulations mandate validated thermal control for temperature-sensitive biologics distribution. Santos and Paranaguá port infrastructure expansions accommodate project cargo flows through specialized open-top and flat-rack configurations.
Container Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven carriers, integrated logistics operators, and independent lessors occupy distinct competitive positions. Fleet ownership concentration among the top five lessors limits pricing power for regional operators while backward integration into steel sourcing and manufacturing sustains cost leadership for vertically integrated carriers. Strategic moves center on captive container supply anchoring integrated logistics strategies and multi-year managed fleet programs replacing transactional spot leasing.
Among carrier-controlled fleets, MSC exemplifies scale-driven slot availability management across trunk routes while Maersk occupies the integrated logistics archetype through captive container supply anchoring end-to-end service portfolios. COSCO Shipping represents manufacturing-integrated cost leadership through Yangtze River Delta production clusters and domestic steel sourcing control. These three carriers illustrate how fleet composition strategies diverge between owned-fleet dominance, logistics integration, and manufacturing backward integration.
| Leading Market Players |
|---|
| MSC |
| Maersk |
| CMA CGM |
| COSCO Shipping |
| Hapag-Lloyd |
| Evergreen Marine Corporation |
| ONE |
| HMM |
| Yang Ming Marine Transport Corporation |
| Others |
Supply Flow & Price Mechanics
China's Yangtze River Delta manufacturing clusters concentrate corten steel supply for dry container fabrication, anchoring margin pools in leasing premiums for specialized reefer and tank variants where ISO certification and EU Green Deal compliance documentation justify rate premiums.
Pricing Analysis
Certification level creates the primary spread between commodity dry units and premium refrigerated containers. Three-tier pricing structure separates ISO 668-standard dry boxes, F-Gas Regulation-compliant reefer units with validated thermal control, and pharmaceutical-grade containers with embedded IoT monitoring. Cost compression in standard dry segments is intensifying because Chinese steel export tariffs feed directly into manufacturing input costs. Agricultural exporters in Brazil's soybean corridors exhibit highest price sensitivity through multi-year availability guarantees, while pharmaceutical cold-chain operators absorb premium pricing for ANVISA-compliant thermal validation.
Supply Chain Analysis
Yangzijiang Shipbuilding and COSCO Shipping facilities along China's Yangtze River Delta hold dominant contract-manufacturing capacity for ISO 668-compliant enclosures. Supply draws from domestic corten steel mills, South Korean aluminum framing suppliers, and German compressor manufacturers for reefer refrigeration systems. Single-source vulnerability concentrates in marine-grade plywood flooring sourced from Southeast Asian timber processors. Distribution runs through captive fleet deployment for integrated carriers, third-party lessor pooling arrangements, and spot leasing terminals at Jawaharlal Nehru Port and Los Angeles-Long Beach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container market fragmentation creates entry niches as e-commerce perishable fulfillment demands modular cold-storage assets incompatible with legacy fleet configurations.
For Market Incumbents: Harden fleet positioning against composite material displacement by securing captive corten steel supply through Yangtze River Delta mill partnerships. Expand technician training pipelines for F-Gas Regulation refrigerant transition before skill scarcity concentrates in East Asia and Europe. Defend against blockchain-enabled lessors by integrating IoT custody documentation into existing managed fleet programs. For New Entrants and Emerging Players: Establish a beachhead in India's Sagarmala-connected manufacturing export zones where dry and open-top container demand outpaces local supply. Target pharmaceutical cold-chain logistics in Brazil's ANVISA-regulated corridors through certified thermal control partnerships with regional distributors. Go-to-market leverage rests on modular plastic container deployment for urban dark-store networks incompatible with traditional steel asset repositioning economics. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated lessors with backward steel sourcing control and EU-adjacent final finishing capabilities that minimize Carbon Border Adjustment Mechanism exposure. Long-term viability favors operators capturing circularity certification premiums under extended producer responsibility frameworks. Monitor refrigerant retrofit subsidy announcements from EPA SNAP program administrators as inflection signal for reefer replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Transition | Fiber-reinforced polymer adoption in pharmaceutical cold-chain lanes reduces tare weight for high-value cargo. |
| Backward Steel Integration | COSCO Shipping's Yangtze River Delta mill partnerships insulate manufacturing costs from export tariff volatility. |
| Blockchain Custody Integration | IoT-enabled distributed ledger documentation compresses demurrage dispute resolution friction at terminal gates. |
| EU-Adjacent Finishing Relocation | Reefer assemblers shifting final operations near European markets minimize Carbon Border Adjustment Mechanism documentation burdens. |
| Managed Fleet Program Expansion | Multi-year integrated logistics contracts with equipment availability guarantees displace transactional spot leasing in Brazil and Germany. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with container lessor fleet managers, shipping line procurement directors, and port authority terminal operators; and secondary validation through customs trade databases, ISO certification registries, and SEC filings from publicly traded lessors. Bottom-up triangulation against top-down market sizing cross-checked manufacturer capacity announcements at Yangzijiang Shipbuilding and COSCO Shipping facilities with leasing fleet deployment data.
Forecast inputs span equipment type segmentation, material specification tiers, and application differentiation across shipping, logistics, and storage deployments. Modeled dimensions include container size configuration, regional regulatory cluster alignment, and customer archetype ownership structure. CAGRs were derived through logistic diffusion curves fitted to fleet renewal cycles and carbon intensity compliance timelines. Industry-specific inputs incorporate IMO CII enforcement schedules and EU F-Gas Regulation phase-down trajectories.
Stress conditions across corten steel price volatility, refrigerant availability constraints, and technician training pipeline gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement consistency and manufacturing capacity expansion at Yangtze River Delta clusters. Quarterly review of IMO carbon intensity implementation progress and EPA SNAP program subsidy announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
PUR Containers Packaging Market
Containers
Spout Containers Market
Containers
Oblong Jar Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Global Styrene Compartment Boxes Market
Containers
Snap-Lock Container Market
Containers
Wide Mouth Jars Market
Containers
Square Pails Market
Containers
EPS Shippers Market
Containers
Belgium Container Glass Market
Containers
Global Cardboard Box and Container Market
Containers
Wooden Crates Market
Containers
Slotted Containers Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Steel Containers Market
Containers
EMEA Container Technology Market