
 Europe Plastic Bottles and Containers Market | 2026-2036
Europe Plastic Bottles and Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plastic Bottles and Containers Market Foresight
The EU Green Deal is broadening the addressable market for recycled-content packaging across the continent. Amcor Group GmbH leverages its integrated recycling infrastructure to secure long-term supply agreements with major beverage brands. Greiner Packaging International GmbH differentiates through specialized barrier technologies for sensitive food applications. ALPLA Group anchors its competitive position with dense manufacturing footprints in Central and Eastern Europe.
Europe plastic bottles and containers encompass hollow-bodied packaging structures formed through extrusion blow molding, injection stretch blow molding, or thermoforming, typically ranging from ten milliliters to twenty liters in nominal volume, designed for containment, distribution, and shelf-display of liquid, semi-solid, or granular products. PET bottles command the largest volume share due to their clarity, barrier performance, and established collection infrastructure, while HDPE containers retain strength in household and industrial chemical segments where chemical resistance and post-consumer recyclability carry premium value. The beverage sector and food industry together absorb the majority of unit demand, though personal care applications are shifting toward premium-shaped formats that command higher per-unit margins.
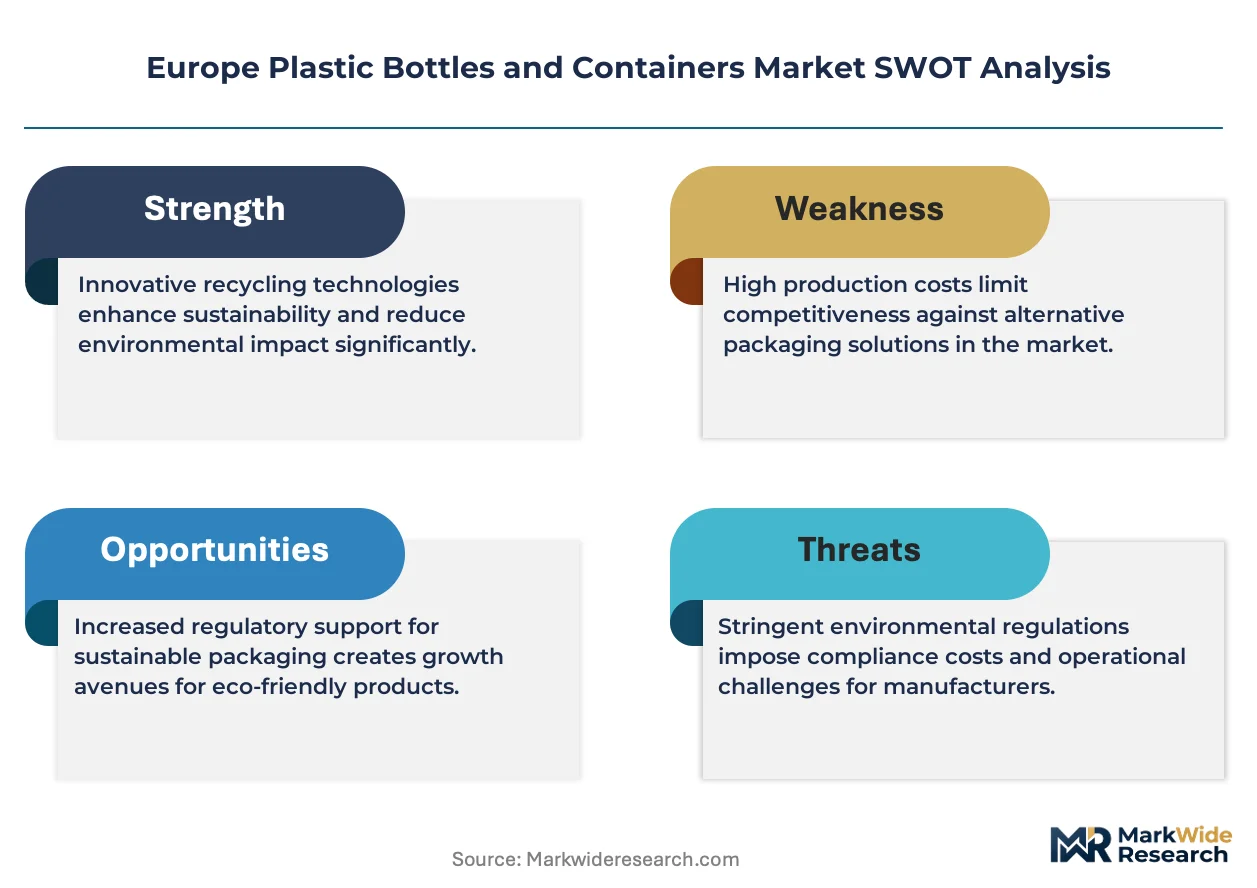
REACH, the EU Green Deal, and the F-Gas Regulation collectively mandate recycled content thresholds, restrict certain additive chemistries, and penalize carbon-intensive production methods across member states. ECHA substance evaluations and national extended producer responsibility schemes further tighten compliance costs for non-integrated converters. Stakeholders must monitor pending revisions to the Packaging and Packaging Waste Regulation, as these rules will determine which material-recycling pathways qualify for compliance credits and which facilities require capital-intensive retrofitting.
Market Dynamics
The EU Green Deal and the F-Gas Regulation are compressing virgin resin demand while mandating recycled content thresholds, forcing converters to reconfigure feedstock procurement and collection partnerships across the continent.
Growth Catalysts
- Beverage lightweighting mandates:Brand owners in Germany and France are specifying sub-ten-gram PET bottle weights for still water, cutting resin consumption per unit by double-digit percentages.
- REACH substance evaluations:ECHA assessments of phthalate and bisphenol chemistries are accelerating migration toward non-toxic barrier coatings in food-contact applications.
- Deposit-return scheme expansion:Italy's 2024 implementation of nationwide collection infrastructure is lifting post-consumer PET bale availability for reprocessors.
Market Restraints
- rPET feedstock scarcity:Collection rates in Central and Eastern Europe lag Western benchmarks, creating regional supply crunches for food-grade flake.
- Natural gas cost volatility:European polymer production remains tethered to continental energy pricing, compressing margin stability for extrusion blow molders.
- Glass substitution in premium segments:Sparkling water and spirits producers in France are reverting to refillable glass for brand positioning, eroding high-margin PET volumes.
Strategic Opportunities
- Poland's underpenetrated barrier packaging:Extended shelf-life dairy and plant-based beverages in Warsaw and Krakow corridors lack adequate oxygen-scavenging container supply.
- CSRD disclosure requirements:Corporate sustainability reporting mandates are creating audit-grade demand for mass-balance-certified packaging among pan-European food manufacturers.
- Chemical recycling integration:Pyrolysis and glycolysis outputs are converging with mechanical recycling streams to expand food-contact-eligible resin pools.
Industry Challenges
- Food-grade certification timelines:EFSA novel food and recycling process approvals stretch eighteen to thirty-six months, delaying commercialization of advanced recycling outputs.
- Legacy blow molding asset obsolescence:Mono-layer extrusion equipment across older Italian and Spanish plants cannot accommodate multi-layer barrier structures without seven-figure retrofit investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plastic Bottles and Containers Market |
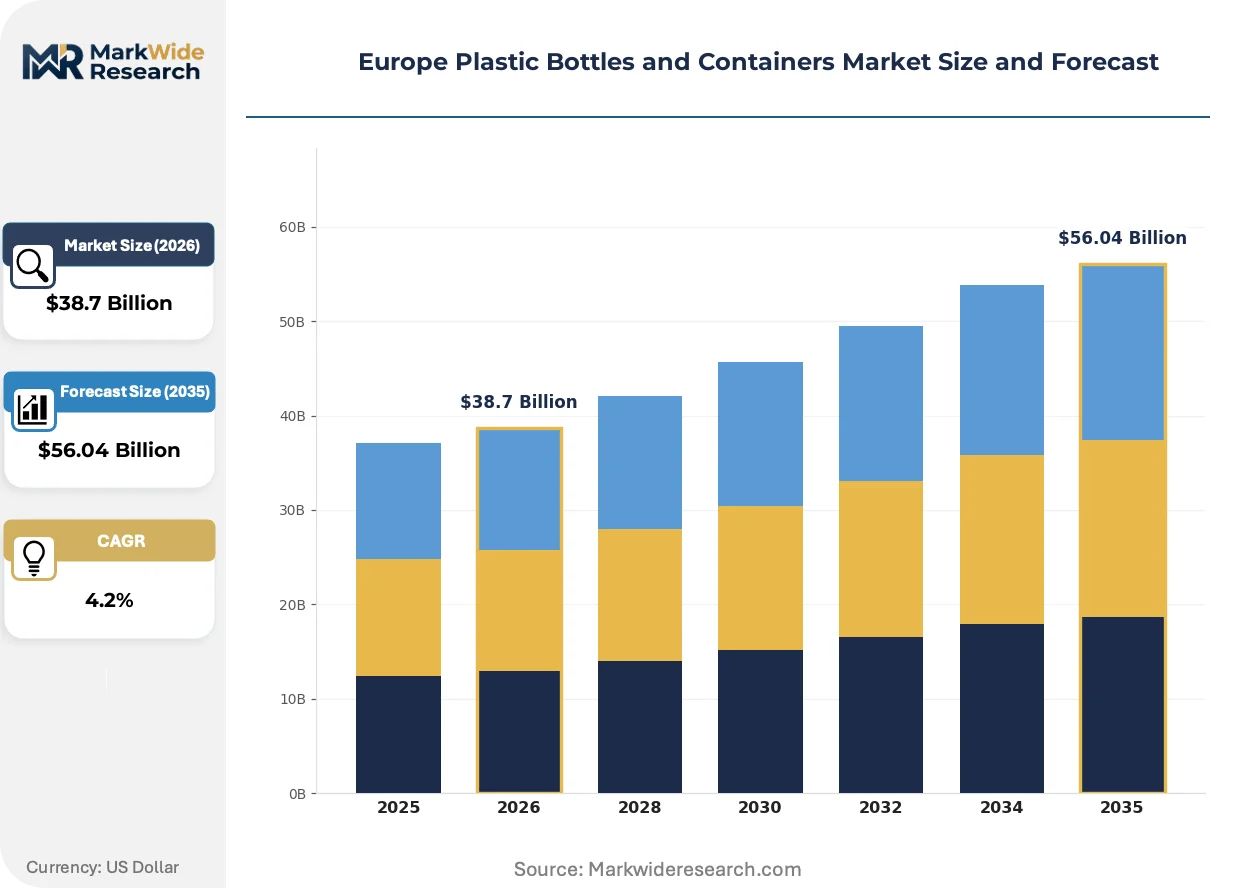
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET Bottles, HDPE Containers, PVC Bottles, LDPE Jars End User: Food Industry, Beverage Sector, Personal Care, Household Products Shape: Round Bottles, Square Jars, Rectangular Containers, Oval Bottles Size: Small Bottles, Medium Containers, Large Jugs, Bulk Packs |
| Companies Covered | Plastipak Holdings Inc, Graham Packaging, Amcor Group GmbH, Greiner Packaging International GmbH, Resilux NV, ALPLA Group, Gerresheimer AG, Alpha Packaging Inc, Berry Global Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plastic Bottles and Containers Market Shifts & Advancements
Digital watermarking and blockchain traceability systems are penetrating European packaging supply chains, enabling granular provenance verification that underpins regulatory compliance and brand claims.
Enzymatic depolymerization of PET waste is decentralizing recycling capacity by enabling smaller-scale, distributed processing units near population centers. Beverage bottlers in the Netherlands and Belgium are piloting on-site regeneration systems that convert post-consumer flake back to bottle-grade resin within fifty-kilometer loops. This distributed model is compressing logistics costs and bale contamination risks that plague centralized mechanical recycling.
The EU Packaging and Packaging Waste Regulation revision is mandating minimum recycled content rates and modulated extended producer responsibility fees based on recyclability scores. Converters in Germany and France are redesigning bottle geometries and label adhesives to qualify for top-tier fee discounts. The beverage segment faces the steepest compliance cost escalation, driving accelerated adoption of detectable black pigments and wash-off label technologies.
Retailers are consolidating procurement through centralized sustainability scorecards that weight carbon intensity and circularity metrics above unit price. Discounters in Germany and hard-format operators in Scandinavia are unbundling packaging specifications from filling-line equipment contracts, enabling direct converter relationships that bypass traditional brand-owner intermediaries. This channel shift is most visible in private-label water and soft drinks, where Aldi Nord and Lidl are specifying container designs independently.
Europe Plastic Bottles and Containers Market Segmentation
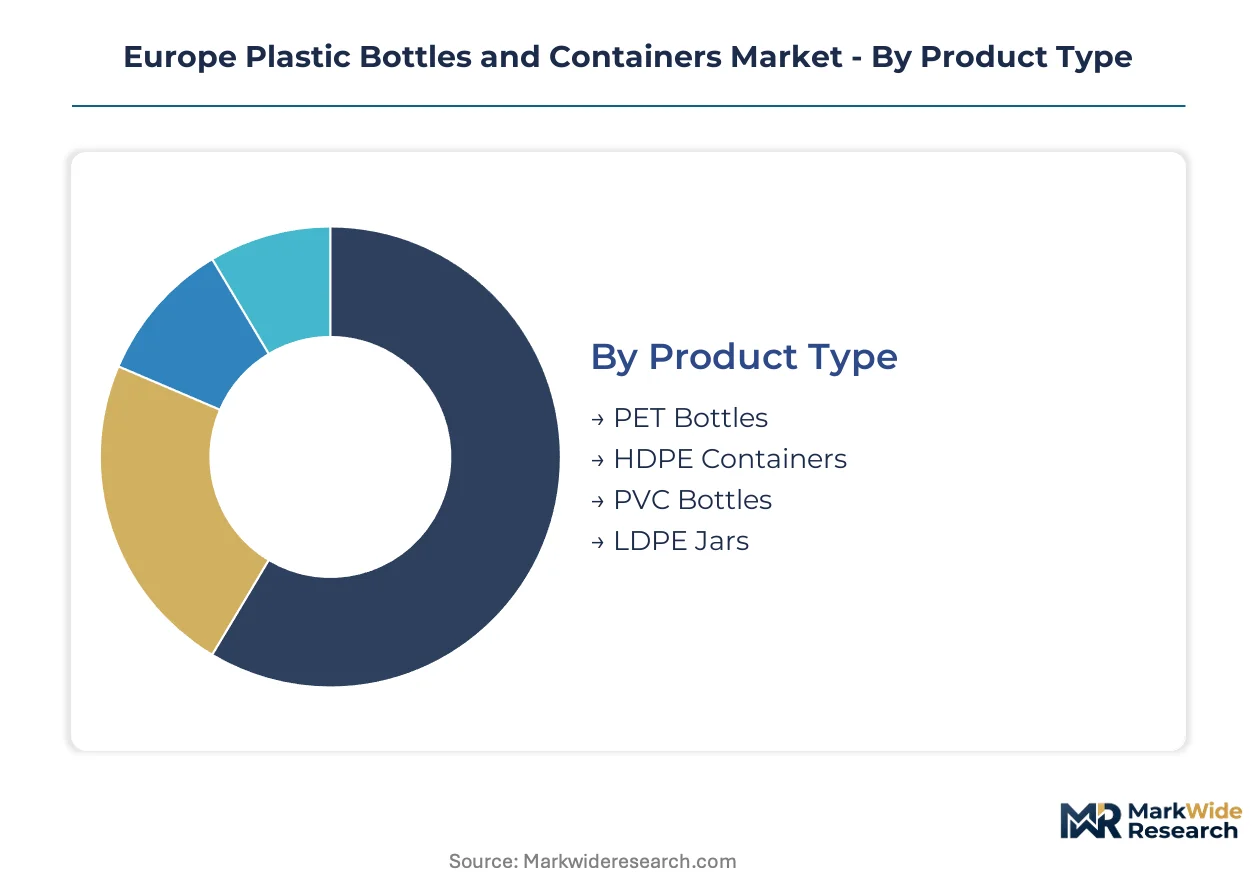
Converters across Europe calibrate mold investments and resin procurement to segment-specific barrier requirements and collection infrastructure. The beverage sector's lightweighting mandates and food-grade rPET certification timelines create divergent margin profiles across product categories.
Product Type:
Supply concentration for barrier-grade resins tilts toward PET and HDPE, where EFSA-approved recycling pathways and established bale collection networks reduce feedstock risk for converters.
- PET Bottles:Amorphous thermoplastic polyester formed through injection stretch blow molding delivers clarity and oxygen barrier performance for carbonated and still beverages. German and French beverage brands specify sub-ten-gram weights for still water, compressing resin demand per unit while maintaining mechanical integrity.
- HDPE Containers:High-density polyethylene extrusion blow molded vessels resist chemical attack from household cleaners and industrial solvents. Central European chemical packaging demand concentrates in Poland and the Czech Republic, where manufacturing investment lags Western automation levels.
- PVC Bottles:Chlorinated polymer structures face REACH restrictions on plasticizer migration in food-contact applications, limiting expansion to non-consumable industrial segments.
- LDPE Jars:Low-density polyethylene offers squeeze flexibility for condiments and personal care creams, though limited mechanical recycling compatibility constrains circularity claims.
Today's leader: PET Bottles. Tomorrow's challenger: HDPE Containers.
End User:
Application-driven specifications fragment converter capabilities across oxygen scavenging, UV blocking, and child-resistance functions.
- Food Industry:Extended shelf-life dairy and ready-meal containers require multi-layer barrier structures with ethylene vinyl alcohol interlayers. Polish and Romanian retail chains lack adequate oxygen-scavenging supply for plant-based beverage growth corridors.
- Beverage Sector:Carbonated soft drinks and bottled water absorb the majority of lightweight PET volumes, with deposit-return scheme expansion in Italy lifting post-consumer bale availability for reprocessors.
- Personal Care:Premium-shaped formats for serums and lotions command higher per-unit margins through differentiated shoulder designs and metallized finishes.
- Household Products:Chemical resistance specifications favor HDPE and PVC for bleach, detergent, and solvent containment, with refill concentrate formats reducing packaging intensity.
Beverage Sector commands current volume leadership. Food Industry presents the steepest expansion trajectory as barrier technology penetrates ambient-stable retail formats.
Shape:
Geometric optimization for pallet density and shelf presence drives mold design investment cycles.
- Round Bottles:Dominant format for carbonated beverages where internal pressure distribution favors cylindrical symmetry, with lightweighting programs maintaining structural performance at reduced wall thickness.
- Square Jars:Maximizes cubic utilization in retail display and e-commerce fulfillment, particularly for food spreads and personal care creams where scooping access matters.
- Rectangular Containers:Industrial chemical and lubricant segments specify stackable geometries for warehouse efficiency, with integrated handles molded into larger formats.
- Oval Bottles:Differentiated hand-feel and label surface area for premium shampoo and conditioner lines, though asymmetric blow molding increases cycle time and energy consumption.
Round Bottles retain manufacturing scale advantages. Square Jars gain share fastest through omnichannel logistics optimization.
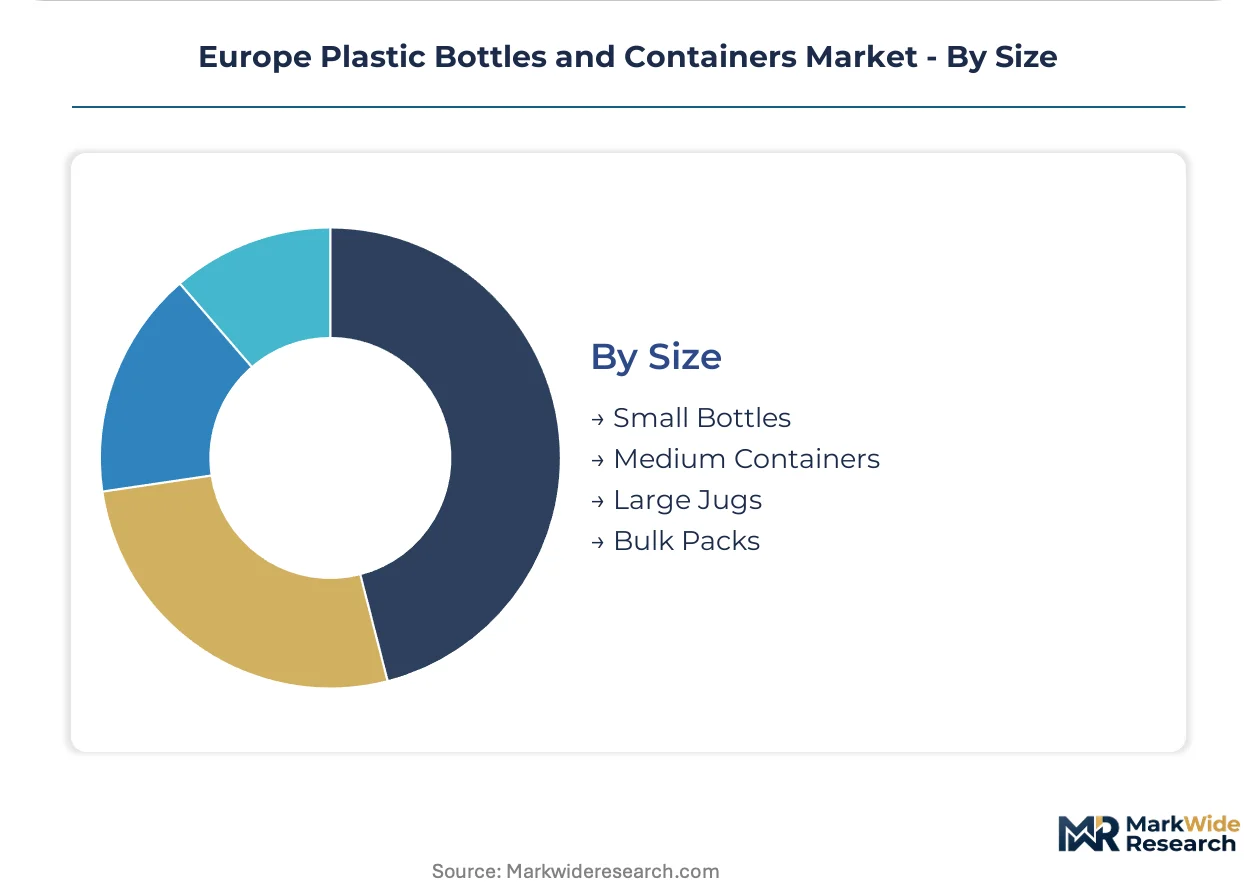
Size:
Volume tiering reflects consumption occasion fragmentation and retail format specialization.
- Small Bottles:Travel-size personal care and single-serve beverage portions face heightened scrutiny under EU Packaging and Packaging Waste Regulation minimum recyclability thresholds.
- Medium Containers:Standard household consumption units for condiments, juices, and cleaning products balance handling ergonomics with purchase frequency economics.
- Large Jugs:Water cooler refills and institutional food service formats concentrate demand in German and Benelux office and hospitality channels.
- Bulk Packs:Refill and industrial concentrate formats reduce per-liter packaging mass, aligning with retailer sustainability scorecard weighting for private-label procurement.
Medium Containers anchor current production volumes. Bulk Packs emerge as the preferred format for modulated extended producer responsibility fee optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German blow molding cooperatives pioneered PET bottle standardization in the 1970s, establishing technical protocols that diffused across Rhine-Ruhr manufacturing clusters before scaling continent-wide.
Germany
Deposit-return infrastructure processes over 90 percent of single-use PET bottles, generating food-grade flake streams that supply converters in Bavaria and North Rhine-Westphalia. The F-Gas Regulation mandates fluorinated gas phaseout in foam insulation applications, redirecting technical investment toward mechanical recycling. Hamburg reprocessors are scaling glycolysis capacity to complement existing mechanical lines.
France
Sparkling water brands in the Massif Central are specifying heavier-wall PET for carbonation retention, countering lightweighting trends elsewhere in beverage packaging. ECHA evaluations of bisphenol-A alternatives are accelerating migration to non-toxic barrier coatings for sensitive food contact. The Île-de-France corridor hosts specialized mold makers serving premium cosmetic bottle segments.
Italy
Nationwide deposit-return implementation since 2024 has lifted post-consumer bale availability for reprocessors in Lombardy and Emilia-Romagna. REACH compliance timelines for phthalate restrictions are compressing procurement windows for flexible PVC alternatives in personal care applications. Venetian converters are retrofitting mono-layer extrusion assets to accommodate multi-layer barrier structures for extended-shelf-life dairy.
Poland
Warsaw and Krakow retail corridors lack adequate oxygen-scavenging container supply for plant-based beverage growth, creating procurement gaps for barrier-grade PET. Extended producer responsibility fee modulation under pending Packaging and Packaging Waste Regulation revisions is incentivizing recyclability redesign. Silesian manufacturing zones are attracting German converter investment for proximity to Central European chemical packaging demand.
Netherlands
Enzymatic depolymerization pilots near Rotterdam are converting post-consumer flake to bottle-grade resin within fifty-kilometer logistics loops. CSRD disclosure requirements are driving audit-grade demand for mass-balance-certified packaging among Benelux food manufacturers. Eindhoven-based equipment suppliers are shipping digital watermarking systems to converters across the continent.
Europe Plastic Bottles and Containers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European plastic bottles and containers market. Integrated resin-to-package converters with captive recycling infrastructure command supply security advantages over specialized molders dependent on spot rPET markets. Three archetypes dominate: pan-European scale players with dense manufacturing footprints, mid-cap barrier technology specialists, and regional contract converters serving private-label retailers. Competitive dynamics center on backward integration into collection infrastructure and strategic partnerships with beverage brand owners for long-term offtake agreements.
Among German and Austrian headquartered fabricators, ALPLA Group and Greiner Packaging International GmbH exemplify contrasting strategic positions within the integrated converter tier. Amcor Group GmbH anchors the multinational packaging conglomerate archetype with broad geographic coverage. These three entities represent the dominant competitive anchors against which mid-cap specialists and regional players calibrate investment and partnership decisions.
| Leading Market Players |
|---|
| Plastipak Holdings Inc |
| Graham Packaging |
| Amcor Group GmbH |
| Greiner Packaging International GmbH |
| Resilux NV |
| ALPLA Group |
| Gerresheimer AG |
| Alpha Packaging Inc |
| Berry Global Inc |
| Others |
Supply & Pricing Matrix
Retailer sustainability scorecards in Germany and Scandinavia are unbundling packaging specifications from filling-line contracts, forcing converters to absorb redesign costs while competing on carbon-intensity metrics rather than unit price alone.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates converter-customer relationships in the European market. Price differentiation hinges on EFSA food-grade certification status and volume scale commitments from beverage brand owners. Pricing pressure stems from natural gas cost volatility tethered to continental energy markets, compressing margin stability for extrusion blow molders. Private-label retailers at the economy tier exhibit highest price sensitivity, while premium cosmetic brands tolerate elevated per-unit costs for differentiated shoulder designs and metallized finishes.
Supply Chain Analysis
Workforce availability constraints in Silesian manufacturing zones and Emilia-Romagna converter corridors are elevating automation investment timelines for mid-cap specialists. Geographic supply concentration centers on Germany, France, and Italy for high-volume beverage packaging, with Poland and the Czech Republic anchoring chemical container demand. Raw material dependencies draw from virgin PET resin, food-grade rPET flake, and ethylene vinyl alcohol barrier resins. Single-source vulnerability pervades food-grade rPET procurement where collection infrastructure gaps persist in Central and Eastern Europe. Distribution runs through pan-European logistics networks serving multinational beverage bottlers and consolidated retail procurement hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe plastic bottles and containers market reads as a late-cycle quality story where specification premiums widen as beverage brands prioritize carbon-accounted packaging and deposit-return compliance over commodity sourcing.
For Market Incumbents: To counter legacy asset obsolescence in Italian and Spanish mono-layer extrusion plants, accelerate retrofit investments for multi-layer barrier capability and deepen backward integration into collection infrastructure through long-term bale supply agreements with deposit-return scheme operators. For New Entrants and Emerging Players: Launch via direct converter relationships with Aldi Nord and Lidl procurement teams for private-label water and soft drinks, exploiting unbundled specification authority to introduce detectable black pigments and wash-off label technologies ahead of incumbent redesign cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap barrier technology specialists holding EFSA-approved recycling process certifications and dense manufacturing footprints in Central Europe, where food-grade rPET scarcity sustains feedstock security premiums. Watch for inflection when chemical recycling outputs achieve EFSA novel food approval at commercial scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Infrastructure | Captures bale supply security as Italy's deposit-return scheme expands post-consumer PET availability. |
| Multi-Layer Barrier Technology Investment | Addresses oxygen-scavenging gaps in Polish and Romanian extended shelf-life dairy corridors. |
| Chemical Recycling Process Certification | Unlocks food-contact eligibility for pyrolysis and glycolysis outputs under EFSA evaluation timelines. |
| Digital Watermarking System Deployment | Enables granular provenance verification for CSRD disclosure compliance among Benelux food manufacturers. |
| Lightweighting Program Acceleration | Meets sub-ten-gram PET bottle mandates from German and French beverage brands while cutting resin intensity. |
Research Methodology
Direct dialogue with blow molding plant managers, procurement leads at multinational beverage bottlers, recycling facility operators, and retail category buyers informed primary intelligence, cross-validated against EFSA recycling process approvals, EU Packaging and Packaging Waste Regulation drafts, Cefic polymer trade data, and SEC filings from listed packaging conglomerates, with bottom-up capacity assessments and top-down demand modeling subjected to iterative triangulation.
Segmented outputs across product type, end-use application, and regional regulatory cluster were generated through the analytical framework, with CAGRs derived from resin intensity trajectories, lightweighting penetration curves, and deposit-return scheme expansion schedules across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA substance evaluation delays or natural gas price spikes. Material deviation in EFSA novel food approval timelines or Packaging and Packaging Waste Regulation fee modulation schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Jerry Cans Market
Containers
2 Piece Cans Market
Containers
Global Multi Pack Carriers Market
Containers
Wooden Crates Market
Containers
Compartment Take-Out Container Market
Containers
ISO Container Market
Containers
HDPE Crates Market
Containers
Intermediate Bulk Container Liner Market
Containers
Foam Containers Market
Containers
Cylindrical Cans Market
Containers
Bulk Containers Market
Containers
Trigger Sprayer Market
Containers
Global Container Monitoring Market
Containers
Container Stacking Machine Market
Containers
Slide Top Tins Market
Containers
Container Market