
 Stock Clamshell Packaging Market | 2026-2036
Stock Clamshell Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Stock Clamshell Packaging Market Outlook
Multi-source procurement for thermoformed packaging is realigning how OEMs balance cost control with supply security. Amcor Limited leverages its global resin partnerships to sustain volume commitments across food and medical accounts. Sonoco Products Company anchors its position through captive recycling infrastructure that reduces virgin material exposure. Berry Global Inc. competes on tooling flexibility, enabling shorter production runs for seasonal retail programs.
Stock clamshell packaging denotes pre-formed, hinged plastic containers produced via thermoforming or injection molding, typically featuring a perimeter flange sealed by heat, radio frequency, or mechanical closure to create a tamper-evident cavity. PET and polypropylene formulations dominate material selection due to clarity, impact resistance, and compatibility with existing recycling streams. Rigid clamshell occupies the largest share of product type demand, driven by electronics and hardware retail channels where structural protection determines shelf acceptance. Eco-friendly clamshell variants, including PLA and post-consumer recycled content, represent the fastest-expanding material trajectory as brand owners face downstream pressure to meet extended producer responsibility targets.
The US FDA regulates food-contact substances under 21 CFR, while EPA state-delegated programs govern post-consumer resin incorporation mandates; California's SB 54 and similar state laws are forcing reformulation timelines. The EU REACH framework and F-Gas Regulation restrict certain plasticizers and blowing agents used in PVC-based clamshell production, redirecting investment toward PET and PP alternatives. Stakeholders must monitor evolving state-level packaging EPR legislation to calibrate capital allocation between virgin and recycled resin processing lines.
Market Dynamics
Extended producer responsibility mandates are compressing formulation timelines across thermoformed packaging supply chains, forcing simultaneous investment in recycled resin infrastructure and virgin line retrofits.
Growth Catalysts
- California SB 54:The state's plastic pollution reduction law mandates 30% post-consumer recycled content by 2028, pulling forward capital deployment into rPET clamshell capacity.
- E-commerce fulfillment standards:Electronics retailers now require drop-test-certified protective packaging, expanding rigid clamshell specifications for last-mile durability.
- Thermoforming automation:Servo-driven trim-in-place systems cut changeover times from hours to minutes, enabling economical short runs for seasonal SKUs.
Market Restraints
- Resin price volatility:PET flake supply concentrates in China's coastal provinces, exposing converters to freight surges and yuan fluctuation.
- Recycling stream contamination:Multi-material clamshells with paper labels or adhesive coatings fail NIR sorting at municipal facilities, limiting closed-loop recovery.
- Substitute formats:Molded fiber and corrugated protective designs capture shelf-stable food and lightweight electronics segments.
Strategic Opportunities
- Medical device serialization:FDA track-and-trace rules for pharmaceutical packaging create demand for tamper-evident clamshells with integrated RFID.
- India's organized retail expansion:Modern trade formats in Maharashtra and Karnataka adopt transparent blister packaging for consumer electronics visibility.
- Chemical recycling partnerships:Pyrolysis-based resin regeneration offers food-contact compliant feedstock bypassing mechanical recycling limitations.
Industry Challenges
- Thermoforming die expertise:Shortage of toolmakers skilled in aluminum mold finishing for micro-flange precision limits rapid prototyping capacity.
- Legacy ERP integration:Batch-oriented manufacturing execution systems struggle to synchronize with real-time resin traceability databases required by EPR reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stock Clamshell Packaging Market |
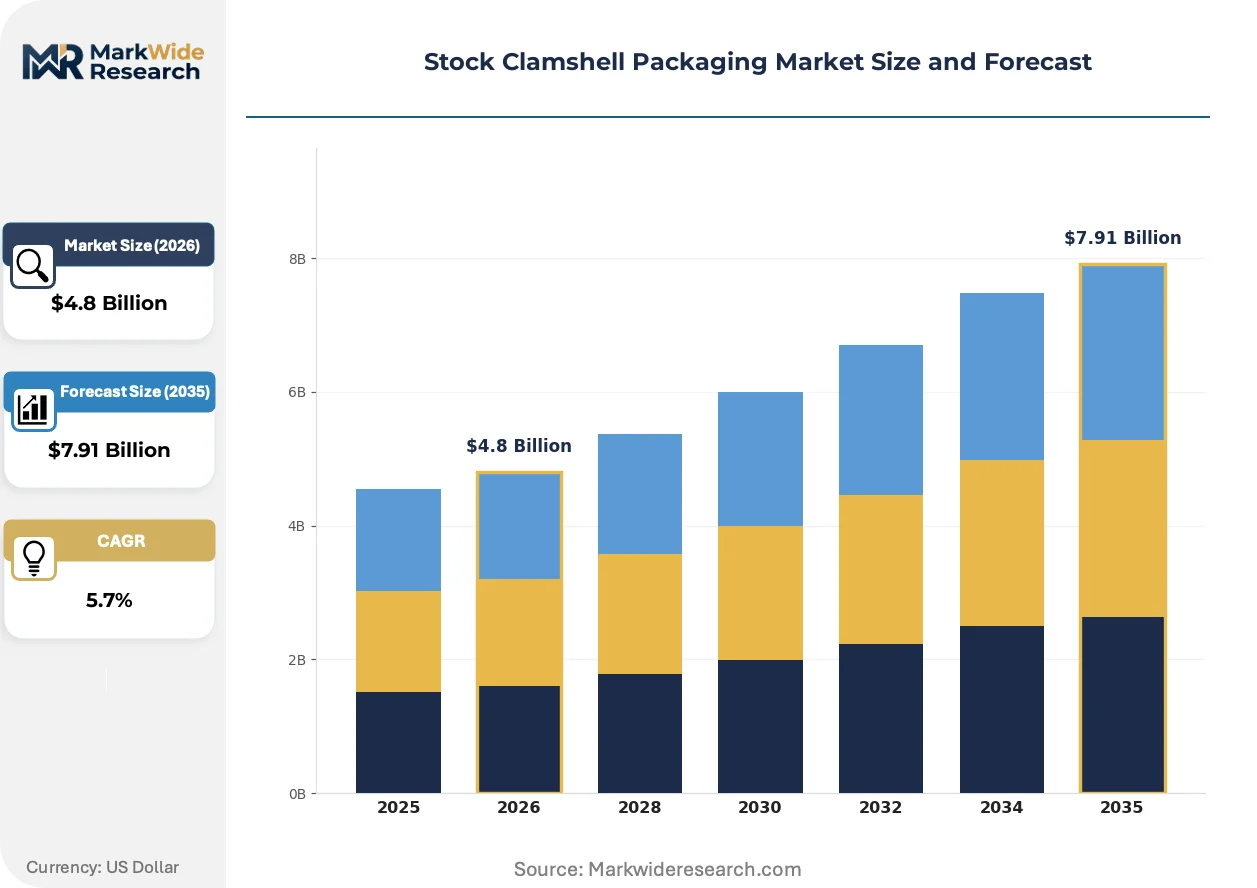
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Clamshell, Flexible Clamshell, Tray Clamshell, Eco-friendly Clamshell Material: Polypropylene, PET, PVC, PLA End User: Food Packaging, Electronics, Retail, Medical Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | Amcor Limited, Sonoco Products Company, Berry Global Inc., Pactiv Evergreen, WestRock Company, VisiPak Inc., Dordan Manufacturing Company, Sumkoka, Lacerta Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stock Clamshell Packaging Market Strategic Shifts
Material science advances and regulatory compliance automation are converging to redefine competitive advantage in thermoformed protective packaging.
Post-consumer recycled PET with near-virgin clarity is overtaking standard PET in food-contact applications. Major retail chains now specify minimum rPET thresholds in private-label packaging tenders. This shift compresses margins for converters without secured recycled feedstock contracts.
REACH restrictions on phthalate plasticizers in PVC clamshells are redirecting European medical packaging investment toward polypropylene alternatives. Manufacturers in Germany and the Netherlands face reformulation deadlines that favor in-house compounding over imported sheet. The transition accelerates tooling refresh cycles for hinge-flexibility optimization.
Direct-to-retailer procurement platforms are consolidating specification-setting power with Walmart, Target, and Carrefour. These buyers now mandate standardized flange dimensions and closure torque ranges across supplier bases. Electronics OEMs in Shenzhen and Dongguan respond by pre-certifying designs against multiple retailer protocols simultaneously.
Stock Clamshell Packaging Market Segmentation
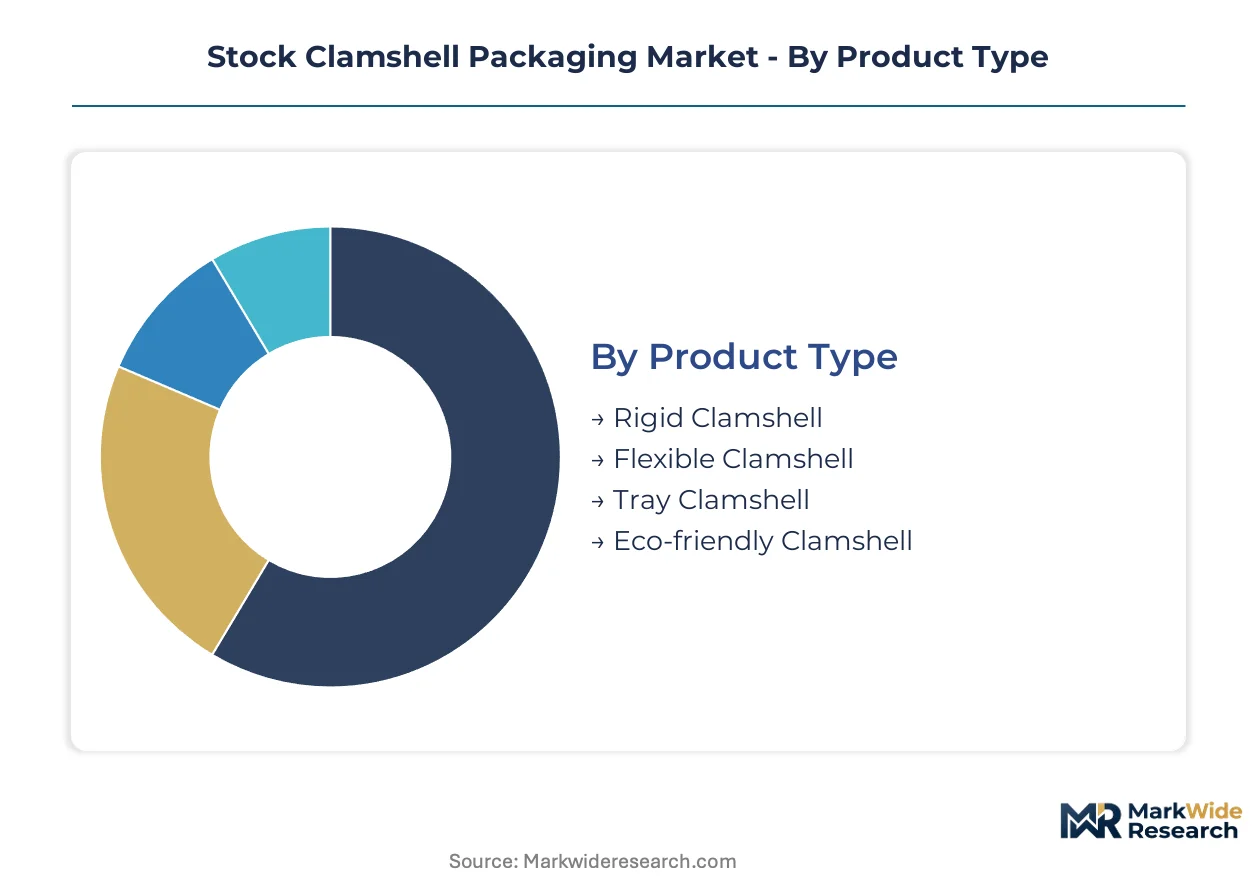
Stock clamshell packaging segments reflect divergent technical requirements across protective, display, and sustainability functions. Material specifications and end-use durability standards determine converter investment priorities and tooling configurations.
Product Type:
Integration depth varies sharply: rigid formats serve standalone protective applications while flexible variants embed within multi-layer packaging systems.
- Rigid Clamshell:Thermoformed PET or polypropylene shells with perimeter flanges and heat-sealed closures provide structural integrity for drop-test certification. Electronics retailers in China's Guangdong province specify these for last-mile shipment protection against fulfillment network handling stress.
- Eco-friendly Clamshell:PLA and post-consumer recycled PET formulations meet extended producer responsibility mandates. California SB 54 compliance deadlines are pulling forward rPET capacity investment by converters serving North American retail chains.
- Flexible Clamshell:Thinner-gauge thermoformed designs with living hinges suit lightweight consumer goods where space efficiency outweighs impact resistance.
- Tray Clamshell:Shallow-cavity formats with snap-fit closures dominate food service and prepared meal segments requiring microwave compatibility.
Rigid clamshell leads volumes today; eco-friendly clamshell is gaining share fastest.
Material:
Cost tiers separate commodity resins from premium grades with certified recycling content or bio-based feedstock.
- PET:Virgin and recycled polyethylene terephthalate delivers optical clarity and food-contact compliance. FDA 21 CFR clearance and established mechanical recycling infrastructure sustain PET's position across retail and medical applications.
- Polypropylene:Higher heat deflection temperature and hinge-flexibility endurance suit medical device packaging. REACH restrictions on phthalate plasticizers in PVC are redirecting European medical packaging investment toward PP alternatives in Germany and the Netherlands.
- PLA:Polylactic acid derived from corn starch offers industrial compostability for brand owners targeting zero-waste certifications.
- PVC:Polyvinyl chloride clamshells face declining specification due to ECHA restrictions on plasticizer migration and recycling stream incompatibility.
PET commands the largest installed base; polypropylene is climbing the fastest in medical and high-temperature applications.
End User:
Application maturity drives margin structure: established electronics and food channels compete on scale while medical and emerging retail segments extract premium pricing.
- Electronics:Protective packaging for smartphones, accessories, and components requires drop-test certification and tamper-evident seals. E-commerce fulfillment standards tightening across Asia-Pacific are expanding rigid clamshell specifications.
- Food Packaging:Fresh produce, bakery, and deli applications demand oxygen barrier properties and FDA-compliant contact surfaces. Retail chains now specify minimum rPET thresholds in private-label tenders.
- Retail:General merchandise and hardware visibility packaging emphasizes optical clarity and shelf presence for big-box store protocols.
- Medical:Sterile barrier systems with FDA track-and-trace compliance command specialized tooling and cleanroom production environments.
Electronics anchors current demand; medical is expanding most quickly on serialization requirements.
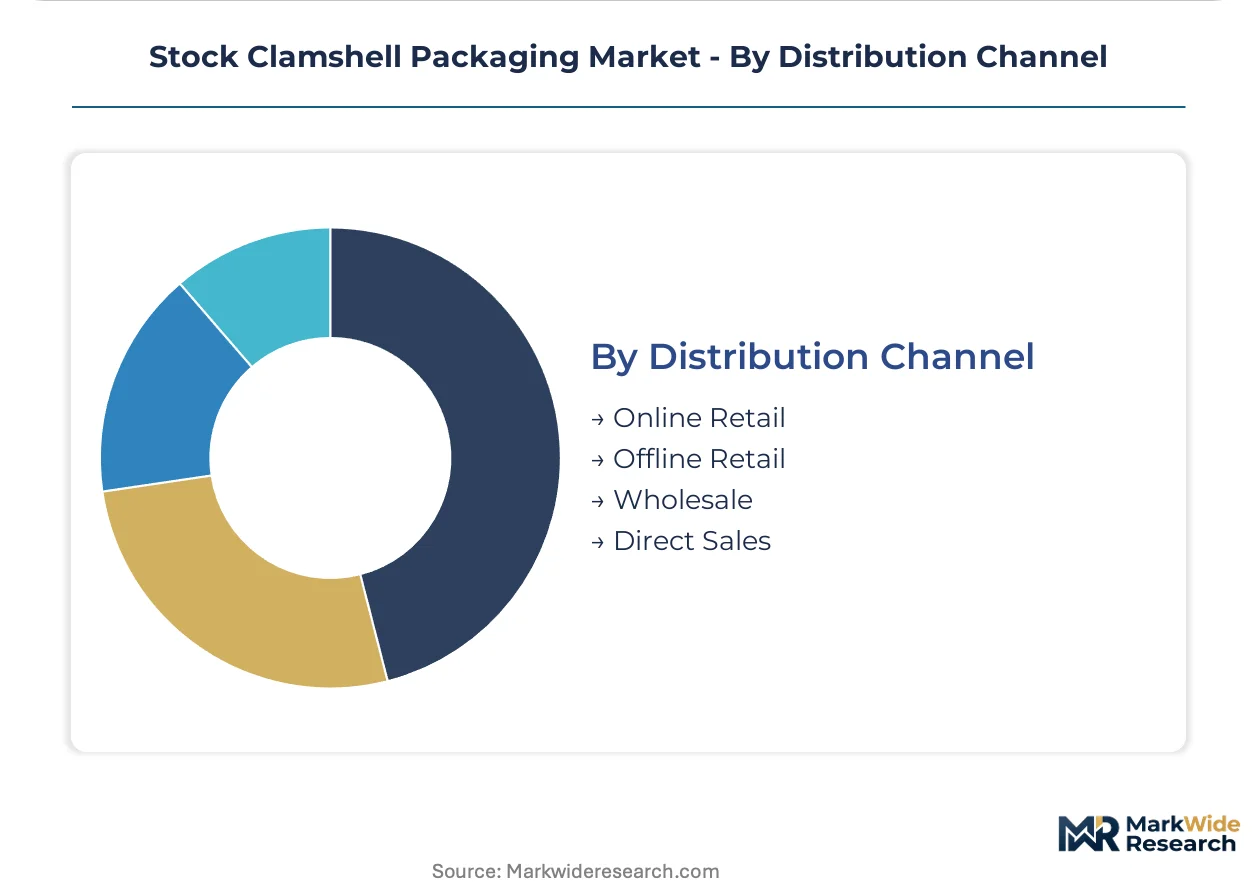
Distribution Channel:
Customer type determines order pattern: wholesale and direct sales sustain volume while online retail fragments specifications across smaller batch requirements.
- Wholesale:Distributor networks aggregate demand from regional converters and smaller OEMs, standardizing flange dimensions across supplier bases to reduce inventory complexity.
- Direct Sales:Large electronics OEMs in Shenzhen and Dongguan negotiate multi-year volume commitments with captive thermoforming capacity, bypassing distributor markups.
- Online Retail:E-procurement platforms enable smaller batch orders with rapid design iteration, though tooling amortization challenges persist for short runs.
- Offline Retail:Traditional brick-and-mortar packaging distributors serve legacy accounts with established specifications and longer lead time tolerance.
Wholesale channels dominate transaction volume; direct sales is capturing margin share fastest through OEM consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting thermoforming investment toward jurisdictions with lower compliance costs for recycled-content mandates, even as major consumer markets tighten material specifications. Production migration patterns reflect this tension between export-market requirements and manufacturing-cost optimization.
United States
California SB 54 mandates 30% post-consumer recycled content by 2028, accelerating rPET clamshell capacity investment along the West Coast. EPA state-delegated programs govern resin traceability reporting across multi-state supply chains. Thermoforming clusters in Ohio and Illinois retrofit lines to meet food-contact compliance under FDA 21 CFR while serving Midwest retail distribution networks.
China
Electronics OEMs in Guangdong province scale protective packaging orders as e-commerce fulfillment standards tighten across Asia-Pacific. SAMR standards on food-contact plastics and MEE enforcement of dual carbon goals reshape material specifications for export-bound production. Thermoforming capacity concentrates in Shenzhen and Dongguan near port logistics hubs serving North American retail accounts.
Germany
REACH restrictions on phthalate plasticizers redirect medical packaging investment from PVC toward polypropylene alternatives. ECHA compliance deadlines favor in-house compounding over imported sheet for clamshell hinge-flexibility optimization. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia anchor tooling refresh cycles for pharmaceutical serialization requirements.
India
Modern trade expansion in Maharashtra and Karnataka drives adoption of transparent blister packaging for consumer electronics visibility. BIS standards on plastic food-contact materials and FSSAI labeling rules reshape converter qualification protocols. Thermoforming investment concentrates in Gujarat and Tamil Nadu to serve organized retail growth in western and southern markets.
Japan
Medical device serialization under PMDA track-and-trace rules creates demand for tamper-evident clamshells with integrated authentication features. METI circular economy guidelines push post-industrial recycled content adoption in premium retail packaging. Production clusters in the Kansai region specialize in cleanroom-grade thermoforming for pharmaceutical export markets.
Stock Clamshell Packaging Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialty certifications and regional niche positioning. The vendor base stratifies across three maturity levels: multinational resin-integrated conglomerates, mid-cap regional converters with captive recycling infrastructure, and specialized toolmakers serving short-run prototyping demand. Two dominant competitive moves define current positioning: backward integration into recycled flake sourcing to secure rPET supply commitments, and strategic partnerships with chemical recycling ventures to bypass mechanical recycling limitations for food-contact applications.
Within the multinational tier, Amcor Limited and Berry Global Inc. exemplify resin-integrated scale positioning, while Sonoco Products Company anchors the captive-recycling archetype through infrastructure control. These three entities represent divergent responses to extended producer responsibility compression: global volume commitments versus regional feedstock security versus closed-loop material recovery.
| Leading Market Players |
|---|
| Amcor Limited |
| Sonoco Products Company |
| Berry Global Inc. |
| Pactiv Evergreen |
| WestRock Company |
| VisiPak Inc. |
| Dordan Manufacturing Company |
| Sumkoka |
| Lacerta Group Inc. |
| Others |
Value Chain & Pricing Dynamics
Tooling engineers skilled in aluminum mold finishing concentrate in Germany's Baden-Württemberg and China's Guangdong province, creating labor-cost differentials that separate premium precision-grade clamshells from standard thermoformed products. These geographic skill clusters compress margins for converters without in-house die expertise while sustaining price premiums for micro-flange medical packaging.
Pricing Analysis
Distributor margin layers absorb 12-18 points before retail markup, while direct-to-OEM contracts command volume discounts that bypass intermediary costs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FDA 21 CFR food-contact compliance and ISO 13485 medical certification command substantial premiums over general retail specifications. Cost compression in standard-grade PET clamshells is intensifying because rPET flake supply concentrates in coastal China, exposing converters to freight volatility. Electronics OEMs in Shenzhen exhibit highest price sensitivity due to thin hardware margins, while pharmaceutical packers in Japan show lowest sensitivity given serialization compliance requirements.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for rPET feedstock among North American retail chains, forcing converters to maintain relationships with both mechanical recyclers and emerging chemical recycling ventures. Geographic supply concentration centers on China for virgin PET resin and flake processing, the United States for food-contact compounding infrastructure, and Germany for precision tooling fabrication. Raw material dependencies rest on purified terephthalic acid, ethylene glycol, and post-consumer baled bottles. Single-source vulnerability in China's coastal thermoforming clusters exposes buyers to yuan fluctuation and port congestion. Distribution runs through wholesale distributor networks aggregating regional converter demand, with direct sales capturing growing share among consolidated electronics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as brand owners shift procurement specifications toward EPR-compliant packaging with certified recycled content and tamper-evident features.
For Market Incumbents: Acquire captive chemical recycling infrastructure to secure food-contact compliant rPET feedstock bypassing mechanical recycling limitations. Consolidate tooling expertise through targeted hiring in Germany's precision mold finishing clusters to defend against emerging Asian competitors. California SB 54 compliance deadlines and REACH plasticizer restrictions threaten converters without reformulation capabilities, making in-house compounding capacity the critical defensive lever. For New Entrants and Emerging Players: Chemical recycling partnerships with pyrolysis ventures offer a technology-first wedge into food-contact applications where mechanical recycling falls short. Target India's organized retail expansion in Maharashtra and Karnataka, where modern trade adoption of transparent blister packaging for consumer electronics remains underpenetrated. Pursue medical device serialization contracts requiring RFID-integrated tamper-evident clamshells, as FDA track-and-trace rules create qualification barriers that favor specialized entrants over commodity converters. For Investors and Strategic Acquirers: Packaging conglomerates with resin-integrated global footprints are the most active acquirer in this space, seeking regional converters with secured rPET supply contracts. The five-to-ten year viability window favors targets with demonstrated EPR compliance automation and cleanroom-grade thermoforming capabilities. Acquisition target archetype: mid-cap regional converters with captive recycling infrastructure and established retailer certification relationships. Watch for inflection in chemical recycling offtake agreements signaling food-contact feedstock cost parity with virgin resin.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Flake Sourcing | Secures post-consumer feedstock commitments ahead of California SB 54 compliance deadlines. |
| Chemical Recycling Partnership Formation | Enables food-contact compliant resin regeneration bypassing mechanical recycling contamination limits. |
| Servo-Driven Thermoforming Automation | Reduces changeover times from hours to minutes, enabling economical short runs for seasonal SKUs. |
| Medical Device Serialization Certification | Captures FDA track-and-trace demand for tamper-evident clamshells with integrated RFID authentication. |
| Retailer Protocol Pre-Certification | Aligns flange dimensions and closure torque ranges with Walmart, Target, and Carrefour specifications simultaneously. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down thermoforming capacity tracking forms the analytical core of this study. Primary interviews with thermoforming plant managers, procurement leads at electronics OEMs, retail category buyers, and medical packaging regulatory affairs directors combined with secondary validation from FDA 21 CFR filings, EPA state-delegated program reports, SAMR food-contact standards, and ECHA REACH restriction updates. Trade data from customs authorities and SEC 10-K disclosures of resin-integrated packaging conglomerates provided cross-referenced supply-side benchmarks.
Input-output matrices map resin consumption through converter capacity to end-use shipment volumes across the projection horizon. Segmentation dimensions modeled include product type rigidity, material formulation tier, end-use durability standard, and distribution channel structure. CAGRs derive from regression analysis against historical thermoforming output correlated with e-commerce fulfillment standards tightening and extended producer responsibility mandate implementation timelines. Industry-specific forecast inputs incorporate PET flake spot price volatility indices and retailer private-label tender specifications for minimum recycled content thresholds.
The model holds under stable regulatory enforcement trajectories for EPR mandates; deviation in resin price volatility or chemical recycling commercialization delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Tottle Containers Market
Containers
Mini Spray Bottles Market
Containers
Slide Top Tins Market
Containers
PET Containers Market
Containers
LDPE Containers Market
Containers
Soup Containers Market
Containers
Container Coating Market
Containers
Die Cut Display Container Market
Containers
Packaging Bins Market
Containers
Foam Containers Market
Containers
Wooden Crates Market
Containers
PUR Containers Packaging Market
Containers
Hinged Lid Compostable Container Market
Containers
Sanitary Cans Market
Containers
North America Plastic Bottles and Containers Market
Containers
PP Container Liner Market