
 HDPE Crates Market | 2026-2036
HDPE Crates Market Size, Share, and Industry Trends Forecast 2026-2036
HDPE Crates Market Foresight
ISO 9001 quality management certification is rotating as the baseline qualification for HDPE crate suppliers serving multinational accounts. Schoeller Allibert leverages its European manufacturing footprint to sustain just-in-time contracts with beverage bottlers. Nilkamal Ltd. anchors South Asian supply through extensive distributor networks. Brambles Limited competes via pooled pallet and crate rental systems that reduce capital expenditure for end users.
High-density polyethylene crates are injection-molded containers with typical wall thickness of 2.5–4.5 mm, melt flow index between 0.2–1.0 g/10 min, and load-bearing capacity ranging from 15 kg to 50 kg depending on rib reinforcement design; they serve as returnable transport packaging for perishables, automotive parts, and retail distribution where single-use corrugated alternatives generate excessive waste. Stackable crates dominate volume shipments due to nested empty-height ratios below 25% that cut return freight costs, while collapsible variants capture margin pools in closed-loop automotive component logistics where cube utilization governs total cost of ownership. Attached lid crates lead last-mile grocery delivery applications where tamper evidence and handheld ergonomics outweigh premium pricing.
REACH compliance in Europe and FDA food contact substance regulations in the United States constrain virgin resin formulations and recycled feedstock blending ratios, directly shaping R&D allocation toward non-phthalate stabilizers and post-consumer HDPE traceability systems. India's BIS certification for plastic food contact articles adds a separate compliance layer for exporters targeting its domestic cold chain modernization. Stakeholders must monitor evolving extended producer responsibility frameworks to determine whether regional recycling infrastructure investment or lightweighting through design optimization offers superior return on capital.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing virgin resin tolerance bands and forcing rapid recycled content integration across European supply chains. This regulatory pressure is redrawing competitive boundaries between integrated recyclers and virgin-dependent molders.
Growth Catalysts
- REACH compliance mandates:ECHA's substance restrictions on phthalate stabilizers are accelerating non-toxic additive R&D, opening premium positioning for certified suppliers in German automotive logistics corridors.
- Food and beverage cold chain expansion:Perishable distribution networks in India are adopting returnable packaging to reduce corrugated waste, with BIS food contact certification becoming a gatekeeper for import substitution.
- Injection molding automation:Robotic de-molding and in-mold labeling systems are cutting cycle times by 15-20% at high-volume plants serving European dairy cooperatives.
Market Restraints
- Post-consumer HDPE feedstock scarcity:Collection infrastructure gaps in Southern and Eastern Europe limit recycled pellet availability, forcing German molders to import bales at volatile spot prices.
- Naphtha-cracker concentration:Virgin resin supply clusters around Rotterdam and Antwerp harbors, creating freight cost penalties for inland molders in Poland and Czechia.
- Collapsible crate mechanical fatigue:Hinge and locking mechanisms in foldable designs fail after 80-100 cycles in heavy-load automotive applications, limiting closed-loop penetration.
Strategic Opportunities
- India cold chain modernization:Government PLI scheme subsidies for integrated pack-houses create first-mover advantages for crate rental operators targeting horticultural export zones.
- RFID-embedded traceability:Converging IoT sensors and blockchain verification enables unit-level lifecycle tracking for pharmaceutical distribution, commanding 40-60% rental premiums over untagged assets.
- EU Green Deal circularity targets:Extended producer responsibility fee structures favor lightweight, high-durability designs that minimize material intensity per trip.
Industry Challenges
- Recycled content verification:Mass-balance accounting complexities and auditor shortages are delaying ISCC PLUS certification timelines by 8-14 months for mid-tier molders.
- Legacy ERP integration:Pool management software from pallet-centric systems requires expensive customization to handle crate nesting ratios and variable return freight calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HDPE Crates Market |
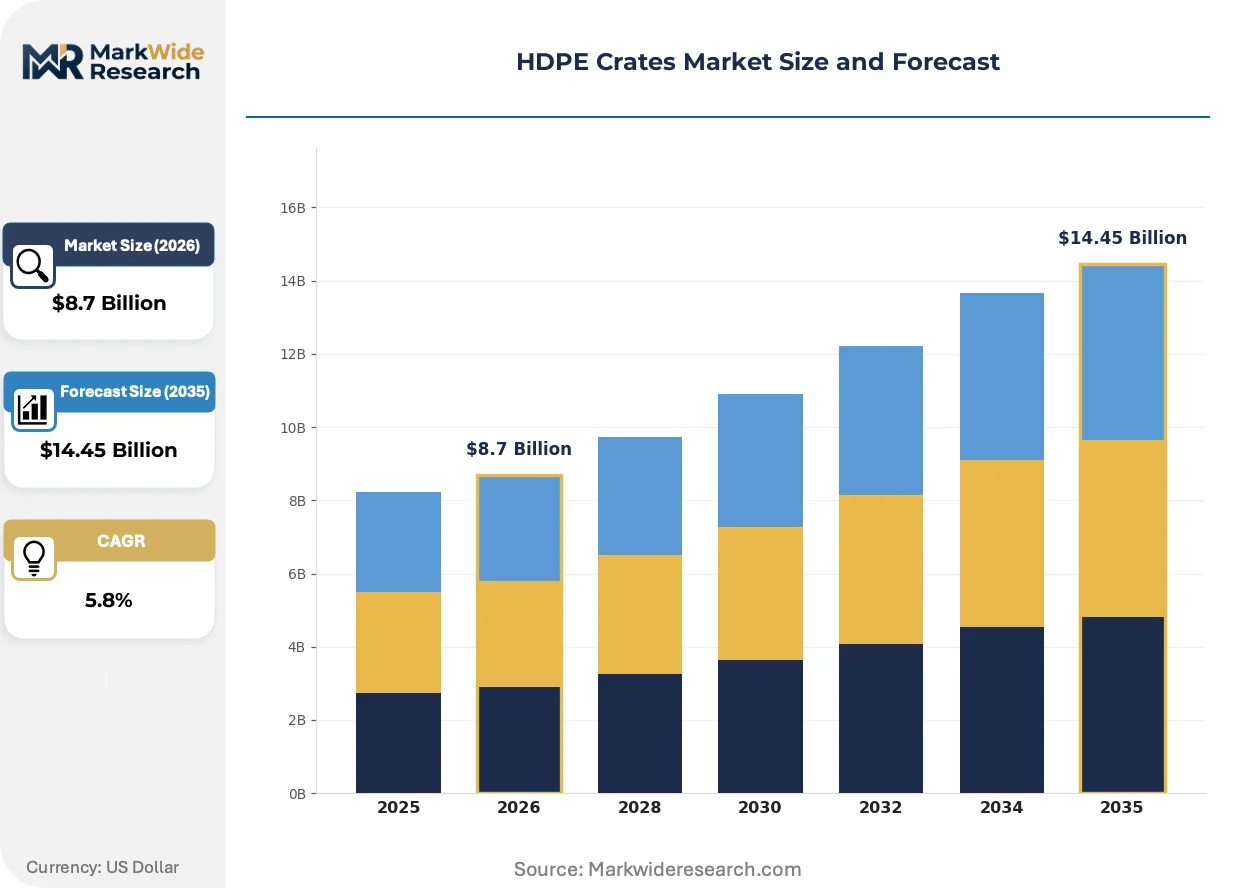
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectangular Crates, Stackable Crates, Collapsible Crates, Attached Lid Crates End Use Industry: Agriculture, Retail, Food & Beverage, Logistics Size: Small, Medium, Large, Extra Large Feature: UV Resistant, Antimicrobial, Heavy-Duty, Lightweight |
| Companies Covered | Nampak Ltd., Nilkamal Ltd., Schoeller Allibert, Brambles Limited, Rehrig Pacific Company, ENKO Plastics, Gamma Wopla N.V., Monoflo International, Sharang Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HDPE Crates Market Shifts & Advancements
Design-for-recycling principles and digital asset tracking are converging to transform how returnable packaging is specified, financed, and recovered across closed-loop supply chains.
Thin-wall injection molding with gas-assisted core-out technology is miniaturizing material usage per crate while maintaining 25-35 kg dynamic load ratings. European dairy distributors are adopting these designs for single-use elimination programs. The technology is compressing virgin resin demand intensity by 12-18% per unit shipped.
REACH Annex XVII restrictions on intentionally added microplastics are compelling reformulation of anti-slip additives and UV stabilizers in outdoor agricultural applications. Molders serving French vineyard cooperatives are switching to mineral-based alternatives. The regulatory shift is most acute in Mediterranean horticulture zones where crates face 36-month sun exposure cycles.
Rental and pooling models are displacing capital purchase patterns among mid-sized German beverage bottlers seeking balance-sheet flexibility. Third-party crate fleet managers are assuming washing, repair, and reverse logistics burdens. This behavioral pivot is most visible in Rhine-Main logistics corridors where just-in-line delivery contracts dominate procurement specifications.
HDPE Crates Market Segmentation
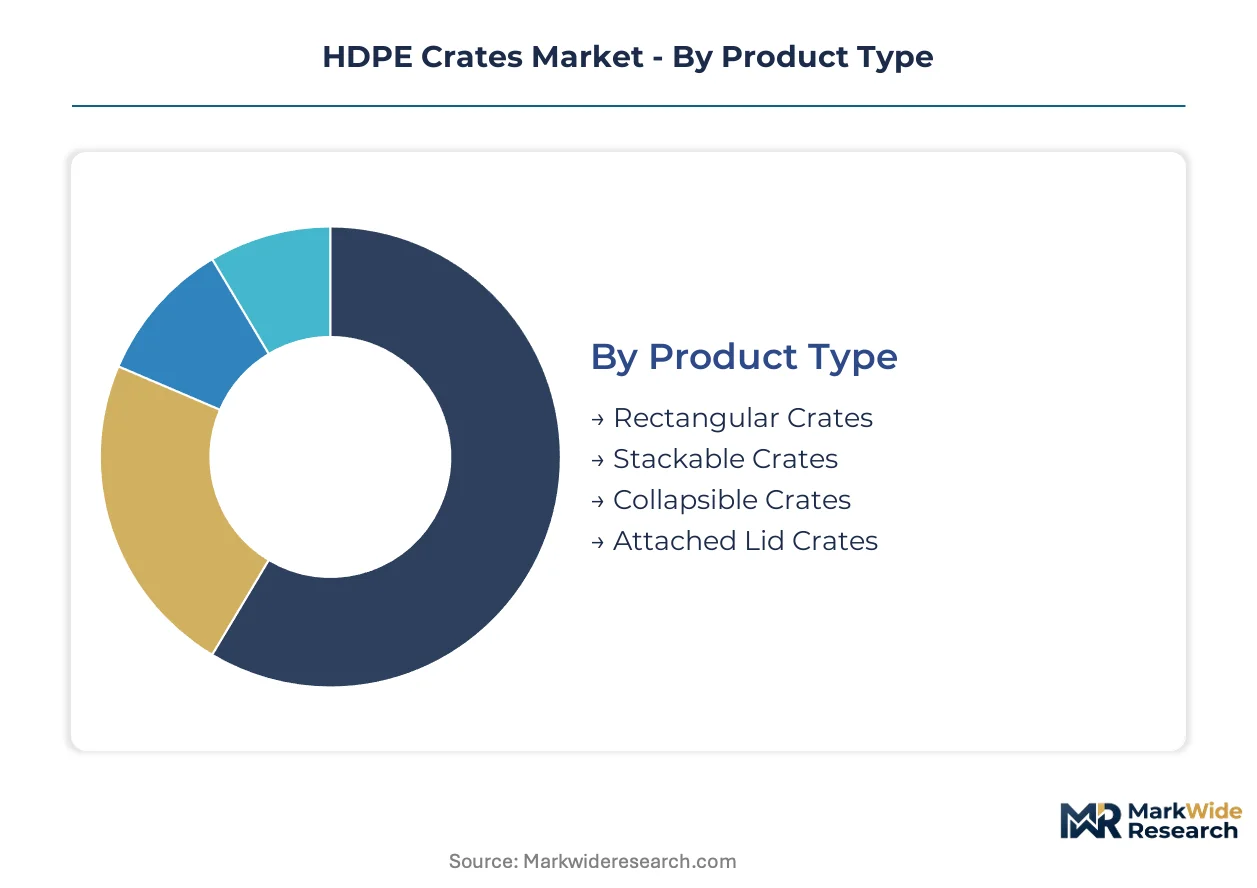
HDPE crate procurement specifications diverge sharply across closed-loop logistics versus single-use replacement applications, with design parameters and certification requirements creating distinct margin architectures. Understanding how product geometry, end-use durability demands, and regional regulatory thresholds intersect enables suppliers to align capacity investments with the highest-yield specification bands.
Product Type:
Margin pools concentrate in designs that optimize cube utilization during return freight, where nested empty-height ratios below 25% command rental premiums over single-trip alternatives.
- Rectangular Crates:Injection-molded with rib-reinforced walls of 2.5–4.5 mm thickness and melt flow index between 0.2–1.0 g/10 min. Demand clusters in German automotive component logistics where ECHA REACH compliance on phthalate stabilizers filters supplier qualification.
- Stackable Crates:Feature interlocking corner posts and typically achieve 15–50 kg load-bearing capacity depending on reinforcement design. European dairy cooperatives are adopting thin-wall gas-assisted variants that cut virgin resin intensity by 12–18% per unit for single-use elimination programs.
- Collapsible Crates:Hinge mechanisms enable flat-fold storage but suffer mechanical fatigue after 80–100 heavy-load cycles. Automotive closed-loop penetration remains constrained by total cost of ownership calculations.
- Attached Lid Crates:Tamper-evident hinged covers with handheld ergonomic grips. Last-mile grocery delivery networks in India prioritize BIS food contact certification over premium pricing for perishable security.
Stackable crates hold installed capacity across European dairy and beverage corridors. Attached lid crates are rotating up the share rankings in Asian e-grocery fulfillment.
End Use Industry:
Application-driven specification intensity creates tiered pricing structures, with pharmaceutical-grade traceability and cold chain validation commanding the steepest rental premiums.
- Agriculture:UV-stabilized formulations for 36-month sun exposure cycles in Mediterranean horticulture. REACH Annex XVII microplastic restrictions are forcing mineral-based anti-slip additive reformulation for French vineyard cooperatives.
- Retail:Lightweight designs for high-frequency handling in hypermarket replenishment. RFID-embedded traceability with blockchain verification enables 40–60% rental premiums over untagged assets in pharmaceutical-adjacent distribution.
- Food & Beverage:Cold chain expansion in India is accelerating returnable packaging adoption to reduce corrugated waste, with BIS certification as a gatekeeper for import substitution in integrated pack-houses.
- Logistics:Pooled rental systems displace capital purchases among mid-sized German beverage bottlers seeking balance-sheet flexibility; third-party fleet managers assume washing, repair, and reverse logistics burdens in Rhine-Main corridors.
Food & Beverage holds installed capacity across European regulatory-mandated recycled content integration. Logistics is rotating up the share rankings as pooling models displace direct procurement.
Size:
Volume concentration in medium and large formats reflects pallet-dimension compatibility and manual handling ergonomics, while extra-large specifications serve automated warehouse systems.
- Small:Handheld dimensions for last-mile delivery and pharmaceutical unit-dose distribution. E-commerce grocery networks in urban India specify these for two-wheeler carrier compatibility.
- Medium:Standard 600×400 mm footprint alignment with European pallet norms. Dairy cooperatives specify these for robotic de-molding and in-mold labeling compatibility at automated plants.
- Large:Bulk agricultural harvest collection with reinforced base structures. Horticultural export zones under India's PLI scheme subsidies specify these for integrated pack-house throughput.
- Extra Large:Automated storage and retrieval system dimensions. Heavy-load automotive component logistics specify these where cube utilization governs total cost of ownership calculations.
Medium crates hold installed capacity across European automated dairy processing. Large crates are rotating up the share rankings in Indian agricultural modernization programs.
Feature:
Certification-linked feature premiums separate qualified suppliers from commodity molders, with antimicrobial and heavy-duty specifications creating the widest price dispersion.
- UV Resistant:Mineral-based stabilizer formulations replacing legacy anti-slip additives under REACH microplastic restrictions. Mediterranean agricultural applications with extended sun exposure cycles specify these for 36-month service life.
- Antimicrobial:Silver-ion or organic additive integration for pharmaceutical and fresh protein distribution. FDA food contact substance regulations and EFSA compliance constrain formulation options and create qualification barriers.
- Heavy-Duty:Reinforced rib structures achieving upper load-bearing range. Automotive component logistics specify these where hinge fatigue in collapsible alternatives limits closed-loop penetration.
- Lightweight:Thin-wall gas-assisted core-out technology maintaining 25–35 kg dynamic load ratings. EU Green Deal circularity targets and extended producer responsibility fee structures favor these designs for material intensity minimization per trip.
Heavy-Duty specifications hold installed capacity in automotive logistics corridors. Lightweight designs are rotating up the share rankings under EU packaging waste regulation compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government PLI scheme subsidies and EU Packaging and Packaging Waste Regulation mandates are redirecting capacity investments toward India and Germany respectively. Cold chain modernization programs and recycled content compliance deadlines are compressing supplier qualification timelines across both markets.
Germany
Rhine-Main logistics corridors drive demand for pooled rental systems among mid-sized beverage bottlers seeking balance-sheet flexibility. ECHA REACH compliance on phthalate stabilizers filters supplier qualification for automotive component logistics. Stuttgart and Munich manufacturing clusters host injection molding automation serving just-in-line dairy cooperative contracts.
India
Horticultural export zones under PLI scheme subsidies specify large-format crates for integrated pack-house throughput. BIS certification for plastic food contact articles gates import substitution in cold chain modernization. Maharashtra and Gujarat distribution networks anchor South Asian supply through extensive dealer infrastructure.
United States
FDA food contact substance regulations constrain virgin resin formulations and recycled feedstock blending ratios for perishable distribution. Pooled pallet and crate rental systems reduce capital expenditure for regional beverage distributors. California and Texas logistics hubs concentrate demand for pharmaceutical-grade traceability specifications.
France
Vineyard cooperatives in Mediterranean horticulture zones specify UV-stabilized crates facing 36-month sun exposure cycles. REACH Annex XVII microplastic restrictions force mineral-based anti-slip additive reformulation. Bordeaux and Champagne production regions drive specification intensity for agricultural returnable packaging.
China
Automotive component logistics in Yangtze River Delta manufacturing corridors specify heavy-duty reinforced rib structures. Dual carbon goals accelerate lightweighting R&D for material intensity minimization per trip. Shanghai and Suzhou industrial parks concentrate injection molding capacity for closed-loop supply chains.
HDPE Crates Market Competitive Landscape
Player mix skews toward integrated recyclers and virgin-dependent molders redrawing boundaries under regulatory pressure. European manufacturing footprint holders sustain just-in-time contracts through geographic proximity. Asian distributor-network operators anchor regional supply through extensive dealer infrastructure. Rental and pooling system operators compete via asset-light balance-sheet solutions. Capacity expansion and strategic partnerships dominate competitive moves as suppliers position for recycled content integration mandates.
Among European manufacturing footprint holders, Schoeller Allibert represents the integrated production archetype with continental proximity to beverage bottler contracts. Nilkamal Ltd. exemplifies distributor-network dominance in South Asian supply anchoring. Brambles Limited occupies the pooled rental systems position reducing capital expenditure for end users. These three sit within distinct strategic tiers shaped by geographic coverage and service model differentiation rather than product specification overlap.
| Leading Market Players |
|---|
| Nampak Ltd. |
| Nilkamal Ltd. |
| Schoeller Allibert |
| Brambles Limited |
| Rehrig Pacific Company |
| ENKO Plastics |
| Gamma Wopla N.V. |
| Monoflo International |
| Sharang Corporation |
| Others |
Supply & Pricing Matrix
Injection-molding scale economies in Germany's Rhine-Main corridor compress unit economics for high-volume dairy cooperative contracts while simultaneously elevating price floors for smaller inland molders facing naphtha-cracker freight penalties from Rotterdam and Antwerp harbors.
Pricing Analysis
Certification level creates the primary spread between qualified suppliers and commodity molders, with ISO 9001 baseline qualification separating multinational account access from regional-only positioning. Three-tier pricing structure across premium certified, standard industrial, and economy unverified levels reflects BIS food contact and REACH compliance investment recovery. Pricing pressure stems from recycled pellet import dependency as German molders source volatile spot-market bales from Southern and Eastern Europe. Mid-sized beverage bottlers exhibit highest price sensitivity as pooled rental systems displace capital purchases for balance-sheet flexibility.
Supply Chain Analysis
Germany and China anchor injection-molding capacity for automotive component and dairy cooperative specifications respectively. Virgin resin supply draws from Rotterdam-Antwerp naphtha-cracker clusters while recycled feedstock hinges on underdeveloped collection infrastructure in Southern and Eastern Europe. Single-source vulnerability concentrates in hinge mechanism suppliers for collapsible crate designs where 80-100 cycle fatigue limits closed-loop penetration. Distribution runs through third-party fleet managers assuming washing, repair, and reverse logistics burdens in Rhine-Main corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation mandates are accelerating market disruption as recycled content integration deadlines compress supplier qualification timelines and redraw competitive boundaries between integrated recyclers and virgin-dependent molders.
For Market Incumbents: Compound geographic proximity advantages through just-in-time automation investments serving dairy cooperative contracts while accelerating ISCC PLUS certification to defend against integrated recycler encroachment. Backward integration into post-consumer HDPE bale sourcing mitigates feedstock scarcity exposure from Southern and Eastern European collection gaps. For New Entrants and Emerging Players: BIS certification fast-track for plastic food contact articles unlocks India's horticultural export zones under PLI scheme subsidies where integrated pack-house throughput demand outpaces qualified supply. Target Maharashtra and Gujarat distribution networks through dealer infrastructure partnerships rather than direct capital-intensive manufacturing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors rental and pooling system operators with asset-light balance-sheet solutions as German beverage bottlers displace direct procurement. Long-term viability rests on RFID-embedded traceability capabilities commanding rental premiums in pharmaceutical-adjacent distribution. Watch for mass-balance accounting auditor availability as inflection indicator for certification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Integration | ISCC PLUS certification enables EU Packaging and Packaging Waste Regulation compliance for premium positioning. |
| Injection Molding Automation | Robotic de-molding cuts cycle times 15-20% at high-volume plants serving European dairy cooperatives. |
| Rental System Expansion | Third-party fleet managers capture balance-sheet flexibility demand from mid-sized German beverage bottlers. |
| RFID Traceability Embedding | Blockchain-verified unit-level tracking commands 40-60% rental premiums in pharmaceutical distribution. |
| Thin-Wall Lightweighting R&D | Gas-assisted core-out technology cuts virgin resin intensity 12-18% per unit for circularity targets. |
Research Methodology
Initial hypotheses were tested against primary input from injection-molding plant managers, dairy cooperative procurement leads, automotive component logistics directors, and third-party crate fleet operators and refined through secondary validation against customs and trade data, SEC filings from listed packaging suppliers, ECHA substance restriction databases, and BIS certification registries. Bottom-up capacity utilization estimates triangulated against top-down demand projections from cold chain modernization program disclosures.
Variance decomposition across product type, end-use industry, size category, and feature specification dimensions isolates growth contribution by segment throughout the forecast period. CAGRs were derived from modeled shipment volumes and value recovery rates incorporating injection-molding cycle time improvements, recycled feedstock blending ratios, and rental penetration assumptions by geography.
Decision-makers should treat outputs as directional under sustained EU regulatory enforcement and stable naphtha-cracker supply; material deviation in post-consumer HDPE collection infrastructure buildout or REACH restriction scope expansion would warrant model refresh. Recalibration cycles align with material shifts in ECHA substance restriction timelines and PLI scheme subsidy disbursement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Thermoformed Containers Market
Containers
Jerry Cans Market
Containers
Global Multi Pack Carriers Market
Containers
Jug Shipper Market
Containers
Stack and Nest Containers Market
Containers
Concentrate Containers Market
Containers
Screw Top Lids Market
Containers
Lever Lid Cans Market
Containers
Trigger Sprayer Market
Containers
Cups and Lids Market
Containers
Container Stacking Machine Market
Containers
Roll Containers Market
Containers
Flexible Water Tanks Market
Containers
Slotted Containers Market
Containers
ISO Container Market
Containers
Pocket Containers Market