
 Rotomolded Containers Market | 2026-2036
Rotomolded Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Rotomolded Containers Market Outlook
Aftermarket service revenue for tank refurbishment and liner replacement is tilting toward specialized regional operators. Snyder Industries leverages its geographic footprint across agricultural belts to sustain recurring maintenance contracts. Berry Global Inc anchors its position through backward integration into resin compounding, controlling raw material quality for food-grade applications. Granger Plastics differentiates via custom mold capabilities for chemical containment specifications that generic producers cannot match.
Rotomolded containers are hollow, seamless plastic vessels formed through rotational molding of powdered thermoplastics—typically polyethylene—heated in biaxially rotated molds to produce stress-free walls up to several inches thick for structural durability. These containers serve primary industrial purposes including bulk liquid storage, material handling, and regulated substance containment where seam integrity and chemical resistance are mandatory. Storage tanks command the largest revenue pool given their replacement cycles in agricultural and chemical end uses, while pallets and dollies represent faster-growing segments as warehouse automation drives standardized footprint demand. Polyethylene dominates material consumption due to its processability and cost position, though polypropylene is gaining specification in elevated-temperature chemical applications.
EPA spill prevention regulations and FDA food-contact material standards shape product design requirements across domestic manufacturing. OSHA workplace safety mandates further dictate handling equipment specifications for industrial dollies and bins in manufacturing environments. Stakeholders must monitor how state-level PFAS restrictions and evolving ASTM rotational molding standards will redefine material eligibility and testing protocols.
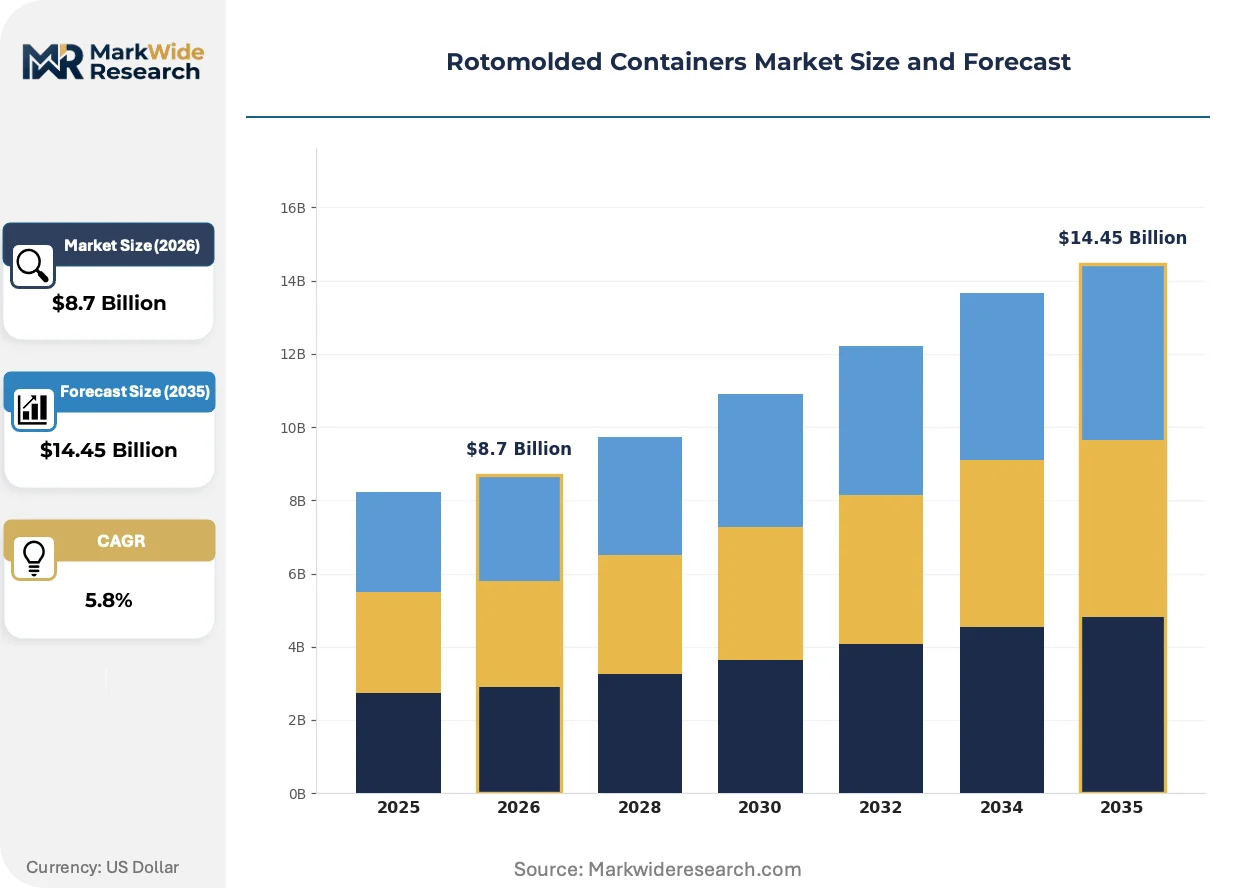
Market Dynamics
HDPE resin supply consolidation among Gulf Coast petrochemical producers is compressing raw material procurement flexibility for rotomolders serving agricultural and chemical containment end uses. This concentration is forcing container manufacturers to renegotiate long-term supply agreements or absorb margin volatility.
Growth Catalysts
- EPA Spill Prevention Regulations:Agricultural operations in the United States must replace aging single-wall tanks with double-wall containment systems, accelerating replacement demand across Midwest grain belts.
- California Agricultural Corridors:Water scarcity protocols are expanding irrigation infrastructure investment, driving specification of large-capacity rotomolded storage tanks for on-farm water management.
- Crosslinkable Polyethylene:Enhanced UV and chemical resistance properties are opening specification in outdoor chemical containment applications previously served by fiberglass alternatives.
Market Restraints
- Ethylene Feedstock Volatility:Natural gas liquid pricing swings from Permian Basin production variability directly transmit to HDPE pellet costs, squeezing rotomolder margins on fixed-price contracts.
- Mold Fabrication Concentration:Precision aluminum mold production concentrates among Ohio and Michigan tool-and-die shops, creating capacity bottlenecks for custom chemical containment specifications.
- FDA Food-Contact Compliance Burden:Evolving migration testing protocols for recycled HDPE content are extending qualification timelines for food-grade container launches.
Strategic Opportunities
- Texas and Florida Sub-Regions:Hurricane resilience infrastructure spending is creating demand for potable water storage systems in coastal counties underserved by regional rotomolders.
- Warehouse Automation Convergence:Integration of RFID tracking with standardized pallet footprints is opening specification for intelligent rotomolded material handling platforms.
- State-Level PFAS Restrictions:Bans on fluorinated container linings in Washington and Maine are accelerating substitution demand for unlined rotomolded chemical containment.
Industry Challenges
- Rotational Molding Technician Shortage:Experienced oven operators and mold technicians are retiring faster than community college vocational programs can replenish the workforce.
- ASTM Standardization Delays:Pending revisions to rotational molding material specifications are freezing procurement decisions among risk-averse municipal water authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotomolded Containers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Tanks, Pallets, Bins, Dollies Material: Polyethylene, Polypropylene, PVC, Others End User: Agriculture, Food & Beverage, Chemical, Healthcare Application: Water Storage, Waste Management, Packaging, Transport |
| Companies Covered | Berry Global Inc, Snyder Industries, REMCON Plastics Inc., Elkhart Plastics, Inc., Granger Plastics, Zero Manufacturing, Dura-Cast Products, Inc., Rotational Molding, Inc., Ameripack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotomolded Containers Market Strategic Shifts
Digital simulation tools are compressing product development cycles while regulatory pressure on material traceability is reshaping quality assurance protocols across domestic manufacturing.
Simulation-driven mold flow analysis is virtualizing traditional trial-and-error prototyping for complex chemical containment geometries. Agricultural tank manufacturers in Iowa and Nebraska are adopting these tools to reduce lead times for custom fitting configurations. The technology is virtualizing the competitive advantage of legacy mold shops with decades of empirical expertise.
FDA's updated Food Contact Notification requirements for post-consumer recycled content are mandating enhanced supply chain documentation. Container producers must now trace HDPE resin batches through compounding, molding, and distribution to demonstrate compliance. Food-grade applications in dairy and beverage handling are most affected, with manufacturers investing in spectroscopic testing equipment to verify material integrity.
Integrated service contracts are bundling tank installation, liner replacement, and regulatory inspection into multi-year agreements. Agricultural cooperatives in the Central Valley are displacing transactional procurement with performance-based partnerships that shift operational risk to container suppliers. This restructuring concentrates most visibly in California where water board inspection frequency creates recurring compliance burdens for farm operators.
Rotomolded Containers Market Segmentation
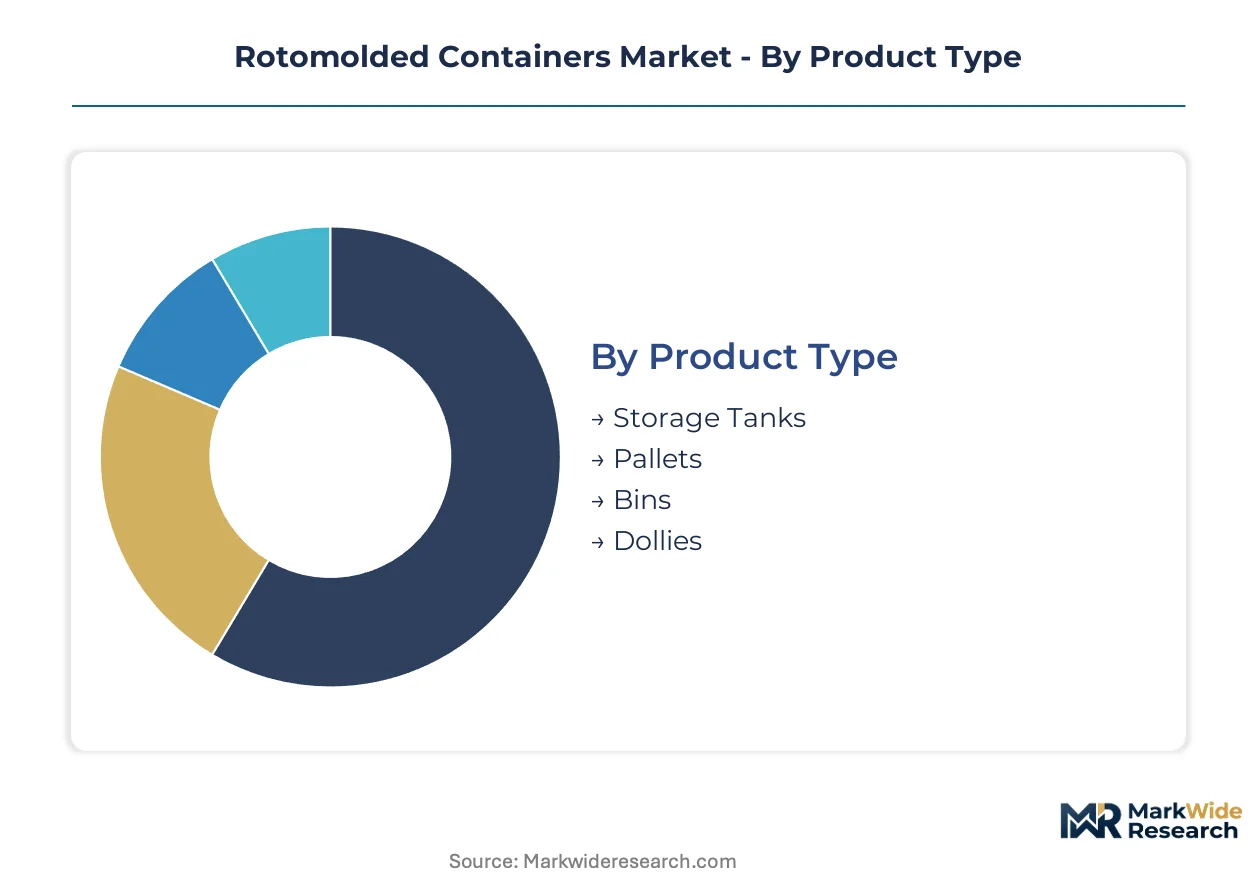
Rotomolded containers serve fundamentally different performance requirements across liquid containment, material handling, and regulated substance storage. Segmentation reveals where technical specifications diverge and where procurement patterns concentrate.
Product Type:
The use-case spectrum spans static liquid containment to dynamic material handling, with each form factor demanding distinct wall thicknesses, structural reinforcement, and surface finishes.
- Storage Tanks:These vessels feature seamless, stress-free walls engineered for bulk liquid containment with wall thicknesses reaching several inches. Agricultural operations across Midwest grain belts specify these for irrigation and chemical containment where EPA spill prevention regulations mandate double-wall configurations. Replacement cycles in aging agricultural infrastructure sustain recurring revenue pools.
- Pallets:Standardized footprints designed for warehouse automation systems integrate RFID tracking capabilities. Distribution centers in California agricultural corridors specify these for produce handling where washdown durability and dimensional consistency are critical.
- Bins:Open-top containers with tapered walls for nesting and stacking efficiency serve bulk material handling in food processing and chemical compounding operations.
- Dollies:Mobile platforms with integrated casters enable ergonomic transport of heavy loads in manufacturing environments where OSHA workplace safety mandates dictate handling specifications.
The dominant share belongs to Storage Tanks, while Pallets are closing the gap fastest.
Material:
Cost tiers separate commodity thermoplastics from performance-engineered compounds, with resin selection directly determining chemical resistance, temperature tolerance, and UV stability.
- Polyethylene:HDPE and crosslinkable polyethylene variants dominate volume consumption due to processability and favorable cost position. FDA food-contact regulations and evolving HDPE recycling protocols are tightening material compliance requirements for dairy and beverage handling applications.
- Polypropylene:Elevated-temperature resistance properties open specification in chemical containment applications previously served by fiberglass alternatives. Industrial chemical processors in Texas and Louisiana specify these for heated storage requirements.
- PVC:Specialized formulations serve niche applications requiring flame retardancy or specific chemical compatibility profiles.
- Others:Nylon and polycarbonate blends address extreme impact or transparency requirements in medical device handling and laboratory containment.
Polyethylene commands the volume lead, though Polypropylene is climbing the fastest as chemical processors substitute away from fiberglass.
End User:
Customer type determines regulatory burden, with food-grade and chemical containment applications imposing the strictest material traceability and testing protocols.
- Agriculture:Irrigation infrastructure investment and on-farm water management systems drive specification of large-capacity tanks. Water scarcity protocols in California agricultural corridors are expanding demand for potable and non-potable storage systems.
- Food & Beverage:Dairy handling and beverage distribution require FDA-compliant food-contact materials with enhanced supply chain documentation. Migration testing protocols for recycled HDPE content are extending qualification timelines.
- Chemical:Regulated substance containment mandates seamless construction and chemical-specific material compatibility. State-level PFAS restrictions in Washington and Maine are accelerating substitution demand for unlined rotomolded alternatives.
- Healthcare:Medical waste containment and pharmaceutical material handling require sterilization-compatible surfaces and contamination-resistant construction.
Agriculture holds the dominant position, while Chemical is gaining share fastest on regulatory substitution dynamics.
Application:
Geography shapes demand concentration, with water-stressed regions and hurricane-prone coastal counties driving infrastructure-specific procurement.
- Water Storage:Potable and non-potable systems serve municipal, agricultural, and emergency preparedness requirements. Hurricane resilience infrastructure spending in Texas and Florida sub-regions is creating demand in coastal counties.
- Waste Management:Containment vessels for hazardous and non-hazardous waste streams require chemical resistance and regulatory compliance documentation.
- Packaging:Reusable bulk containers for food and chemical distribution emphasize nestability, stackability, and washdown durability.
- Transport:Mobile containment and handling systems integrate with logistics infrastructure for regulated substance movement.
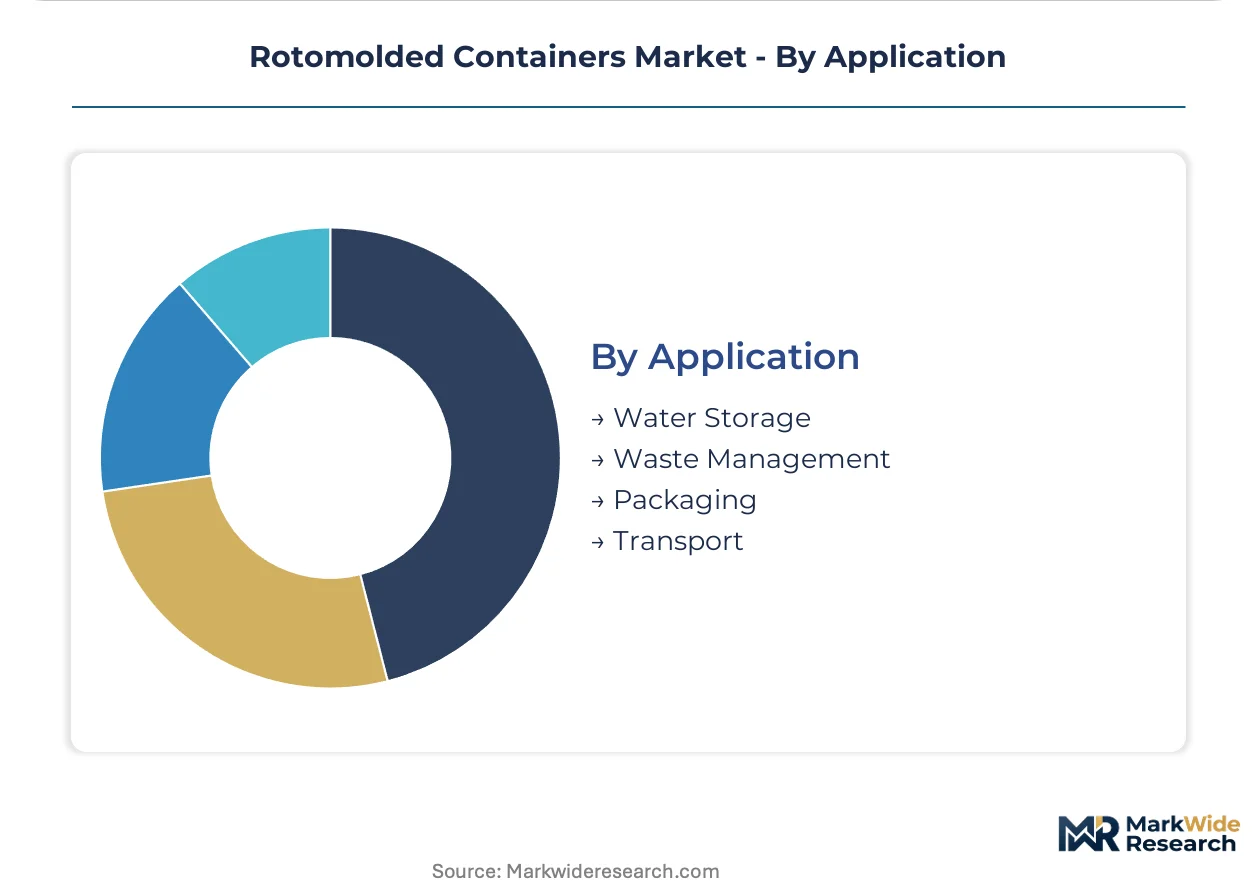
Water Storage captures the dominant share, with Waste Management expanding most quickly on tightening environmental enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Agricultural buyers in water-stressed regions absorb premium pricing for large-capacity tanks, while industrial procurement in saturated markets demands volume discounts and extended payment terms.
United States
Midwest grain belt operations drive replacement demand for double-wall containment systems under EPA spill prevention mandates. FDA food-contact regulations tighten compliance burdens for dairy and beverage handling applications. California agricultural corridors concentrate specification activity for irrigation infrastructure as water scarcity protocols expand on-farm storage requirements.
Germany
Industrial chemical processors specify elevated-temperature containment vessels as polypropylene substitutes displace fiberglass alternatives. REACH compliance protocols mandate enhanced material traceability through compounding and distribution stages. Bavaria's manufacturing belt anchors precision mold fabrication capacity serving custom chemical containment specifications.
China
Dual carbon goals accelerate HDPE recycling protocol development for food-grade container applications. GB standards enforcement tightens material qualification timelines for post-consumer recycled content. Yangtze River Delta manufacturing clusters concentrate rotational molding capacity for export-oriented material handling equipment.
Brazil
Agricultural cooperatives in São Paulo and Minas Gerais states expand irrigation infrastructure investment amid erratic rainfall patterns. ANVISA pharmaceutical containment regulations drive specification for sterilization-compatible medical waste vessels. São Paulo state's industrial corridor hosts specialized mold shops serving chemical and agricultural end uses.
Australia
Drought resilience infrastructure spending creates demand for potable and non-potable water storage systems across New South Wales and Queensland. State-level environmental enforcement tightens hazardous waste containment requirements for mining and chemical operations. Victoria's manufacturing base concentrates domestic rotational molding capacity for agricultural and industrial applications.
Rotomolded Containers Market Competitive Environment
Capability concentration sits with specialized mold shops possessing decades of empirical expertise; scale advantage sits with diversified plastics processors controlling resin supply chains. The vendor base stratifies across three tiers: integrated resin compounders with captive raw material supply, regional specialists commanding custom fabrication relationships, and commodity producers competing on throughput economics. Dominant competitive moves include backward integration into resin compounding to secure food-grade material qualification and geographic expansion through maintenance service contracts that capture recurring revenue from tank refurbishment cycles.
Among North American fabricators, Berry Global Inc exemplifies the integrated compounder archetype through upstream control over resin quality, while Snyder Industries occupies a position anchored in agricultural belt service networks. Granger Plastics represents the custom capability tier, with specialization credentials in chemical containment specifications that commodity producers cannot replicate.
| Leading Market Players |
|---|
| Berry Global Inc |
| Snyder Industries |
| REMCON Plastics Inc. |
| Elkhart Plastics, Inc. |
| Granger Plastics |
| Zero Manufacturing |
| Dura-Cast Products, Inc. |
| Rotational Molding, Inc. |
| Ameripack |
| Others |
Value Chain & Pricing Dynamics
Ethylene feedstock volatility from Permian Basin production swings determines both margin compression in fixed-price contract tiers and the geographic clustering of resin-compounding capacity near Gulf Coast petrochemical hubs. Container manufacturers absorb cost spikes in spot resin markets while long-term agricultural offtake agreements lock in pricing floors that strain working capital cycles.
Pricing Analysis
Aftermarket service revenue from tank refurbishment and liner replacement contracts drives lifetime value capture for specialized regional operators. Three-tier pricing structure across premium FDA-certified food-grade, standard industrial chemical containment, and economy agricultural storage segments reflects certification burden and material traceability requirements. Pricing pressure stems from HDPE pellet cost transmission squeezing rotomolder margins on legacy fixed-price municipal contracts. Agricultural cooperatives in water-stressed regions exhibit lowest price sensitivity, while commodity pallet producers competing for warehouse automation contracts face acute margin compression.
Supply Chain Analysis
Precision aluminum mold production concentrates among Ohio and Michigan tool-and-die shops serving custom chemical containment specifications. Raw material flows draw from Gulf Coast HDPE resin compounding, crosslinkable polyethylene additive suppliers, and recycled content processors qualifying for FDA food-contact applications. Single-source vulnerability runs through concentrated mold fabrication capacity creating lead time bottlenecks for complex geometries. Distribution runs through direct manufacturer relationships with agricultural cooperatives, regional distributors serving industrial chemical processors, and integrated service contracts bundling installation and maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA spill prevention mandates and state-level PFAS restrictions are accelerating substitution demand across double-wall containment applications, creating high-growth disruption as regulatory compliance restructures procurement patterns toward unlined rotomolded alternatives.
For Market Incumbents: Harden geographic moats through captive maintenance service networks across Midwest grain belts and California agricultural corridors where water board inspection frequency creates recurring compliance burdens. Deepen backward integration into resin compounding to secure FDA food-contact material qualification timelines that emerging competitors cannot match. Prioritize mold fabrication capacity reservations with Ohio and Michigan tool shops before custom specification backlogs extend delivery windows. For New Entrants and Emerging Players: Hurricane resilience infrastructure spending in Texas and Florida coastal counties represents the most penetrable entry point, with potable water storage demand outpacing regional rotomolder capacity. Warehouse automation convergence in distribution centers offers specification entry through RFID-integrated pallet platforms where dimensional consistency standards are still stabilizing. Pursue integrated service contract bundling to displace transactional procurement with performance-based partnerships shifting operational risk to suppliers. For Investors and Strategic Acquirers: State-level PFAS restrictions in Washington and Maine reshape the acquisition landscape toward unlined rotomolded chemical containment specialists with proven migration testing protocols. Long-term viability centers on material traceability infrastructure capable of documenting recycled HDPE batches through compounding, molding, and distribution stages. Monitor ASTM rotational molding standardization delays as early signals of procurement freeze risk among municipal water authorities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | FDA food-contact qualification timelines favor integrated compounders controlling raw material quality for dairy and beverage applications. |
| Custom Mold Capability Expansion | Ohio and Michigan tool shop partnerships enable complex chemical containment geometries that commodity producers cannot replicate. |
| Integrated Service Contract Bundling | California agricultural cooperatives are displacing transactional procurement with multi-year performance partnerships. |
| RFID-Integrated Pallet Platform Development | Warehouse automation in produce handling distribution centers demands dimensional consistency and washdown durability. |
| Crosslinkable Polyethylene Specification Push | Enhanced UV resistance opens outdoor chemical containment applications previously served by fiberglass alternatives. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA spill prevention enforcement records, FDA food-contact notification databases, and ASTM rotational molding standards documentation. Primary interviews engaged rotational molding technicians, agricultural cooperative procurement managers, chemical containment specification engineers, and resin compounding quality directors. Secondary validation drew from customs trade data, SEC filings of diversified plastics processors, and state water board inspection compliance records. Bottom-up tank replacement cycle analysis triangulates against top-down agricultural infrastructure investment tracking.
Forecast inputs include HDPE resin price transmission elasticity, replacement demand curves under EPA double-wall mandates, and crosslinkable polyethylene substitution rates in outdoor chemical applications. Segmentation dimensions span product type, material grade tier, end-use regulatory burden, and geographic water stress intensity. CAGRs derive from compounding annual replacement volumes against infrastructure investment trajectories across the projection horizon. Industry-specific inputs incorporate mold fabrication capacity utilization rates and community college vocational program graduation pipelines.
Practitioners should monitor ethylene feedstock volatility indicators, ASTM standardization revision timelines, and state PFAS restriction expansion patterns for early signals of forecast revision triggers. Quarterly review of Permian Basin natural gas liquid pricing, Ohio tool shop capacity backlogs, and FDA recycled content qualification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Clear Hinged Container Market
Containers
PET Hinged Containers Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Global Cardboard Box and Container Market
Containers
Collapsible Sleeve Containers Market
Containers
Jug Shipper Market
Containers
Injection Molding Containers Market
Containers
Thin Wall Containers Market
Containers
Container Mouth Inner Seal Market
Containers
Stainless Steel Cask Market
Containers
Flexible Water Tanks Market
Containers
PP Container Liner Market
Containers
Tottle Containers Market
Containers
Hinged Lid Compostable Container Market
Containers
Hinged Lid Tins Market
Containers
Oblong Tub Lids Market