
 Aseptic Fillers Market | 2026-2036
Aseptic Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Aseptic Fillers Market Analysis
A shift from single-source equipment procurement to multi-vendor validation partnerships is restructuring how pharmaceutical manufacturers build aseptic production lines. Tetra Pak International S.A. leverages its beverage packaging heritage to dominate high-speed liquid filling systems for dairy and nutritional products. Syntegon Technology GmbH anchors its position through deep specialization in containment and barrier isolation technology for sterile drug manufacturing. Krones AG competes by extending its bottling expertise into aseptic pharma applications with integrated cleanroom solutions.
An aseptic filler is a closed-system machine that sterilizes containers, product, and environment separately before combining them under ISO 5 (Class 100) conditions, typically achieving contamination rates below 0.1% through HEPA filtration and steam-in-place protocols. Its primary purpose is to maintain sterility assurance levels for injectable drugs, biologics, and preservative-free consumer products. Liquid fillers command the largest installed base due to overwhelming demand from intravenous and ophthalmic drug formats, while contained systems represent the fastest-expanding technology segment as isolator-based designs displace traditional cleanroom filling. Modular installations are gaining share among contract manufacturers seeking rapid line reconfiguration between small-batch biologics and high-volume generics.
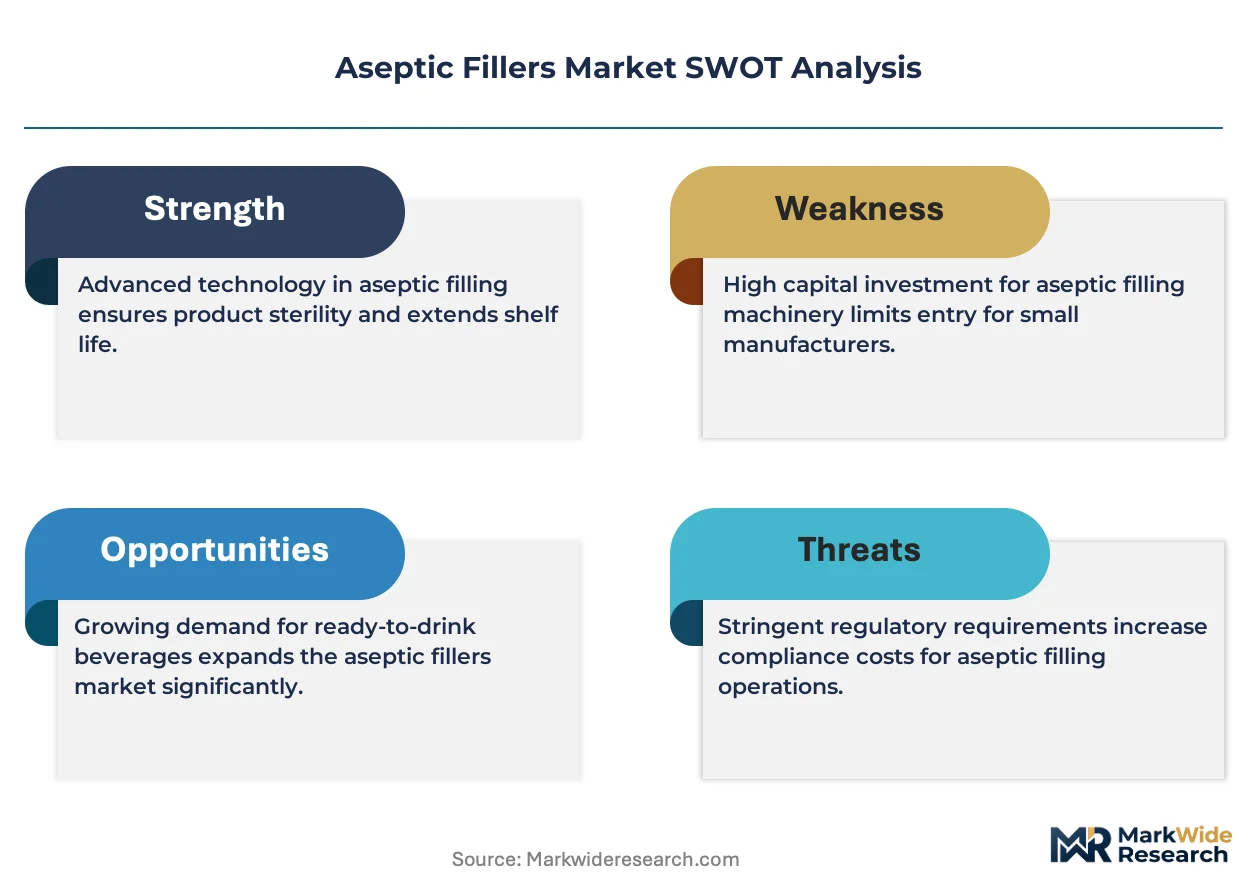
FDA sterility guidance, EU GMP Annex 1 revisions, and ISO 14644 cleanroom classifications collectively mandate continuous monitoring of viable and non-viable particulates, directly driving replacement demand for legacy open-manifold equipment. The EU AI Act and MDR framework additionally require documented process validation for automated filling operations, favoring vendors with embedded audit-trail software. Stakeholders must weigh the capital intensity of contained robotics against regulatory exposure from manual intervention points when planning facility upgrades.
Market Dynamics
Isolator-based containment systems are compressing the installed base of open-manifold aseptic fillers as pharmaceutical manufacturers race to preempt FDA 483 observations and EU GMP Annex 1 enforcement actions.
Growth Catalysts
- Biologics pipeline expansion:Monoclonal antibody and cell therapy manufacturing in the United States, Germany, and Switzerland is absorbing new isolator-based filling lines at triple the rate of small-molecule capacity additions.
- EU GMP Annex 1 revision:The 2022 update mandates continuous viable particle monitoring and barrier technology, forcing replacement of legacy open-RABS equipment across European sterile drug facilities.
- Steam-in-place sterilization protocols:SIP-enabled modular fillers reduce changeover time between batches, enabling contract manufacturers to service both high-volume generics and orphan-drug biologics on shared assets.
Market Restraints
- Stainless steel and HEPA filter cost volatility:Input material prices for pharmaceutical-grade 316L steel and H14 filtration media fluctuate with energy costs, compressing margins on fixed-price equipment contracts.
- Precision engineering supply concentration:Critical motion-control components and isolator glove-port assemblies originate from a narrow base of German and Swiss suppliers, exposing lead times to single-source risk.
- Legacy cleanroom infrastructure lock-in:Existing Grade B filling suites in mature facilities cannot accommodate isolator footprints without structural demolition, delaying upgrade cycles.
Strategic Opportunities
- Indian biopharma contract manufacturing:CDMOs in Hyderabad and Bengaluru are greenfielding isolator-based capacity to capture outsourced sterile filling from Western innovators seeking cost arbitrage.
- Cell and gene therapy personalization:Autologous therapies requiring patient-specific batch sizes favor flexible, single-use manifold systems over stainless steel infrastructure.
- US FDA Quality Manufacturing Maturity Model:The emerging rating system rewards advanced aseptic technology adoption with reduced inspection frequency, creating preference pull for premium equipment tiers.
Industry Challenges
- Containment engineering talent scarcity:Qualified specialists in isolator airflow modeling and viable particle detection system validation command premium compensation, constraining vendor scaling.
- Multi-year validation timelines:IQ/OQ/PQ documentation for new aseptic lines extends 18-24 months, delaying revenue recognition and complicating capacity planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aseptic Fillers Market |
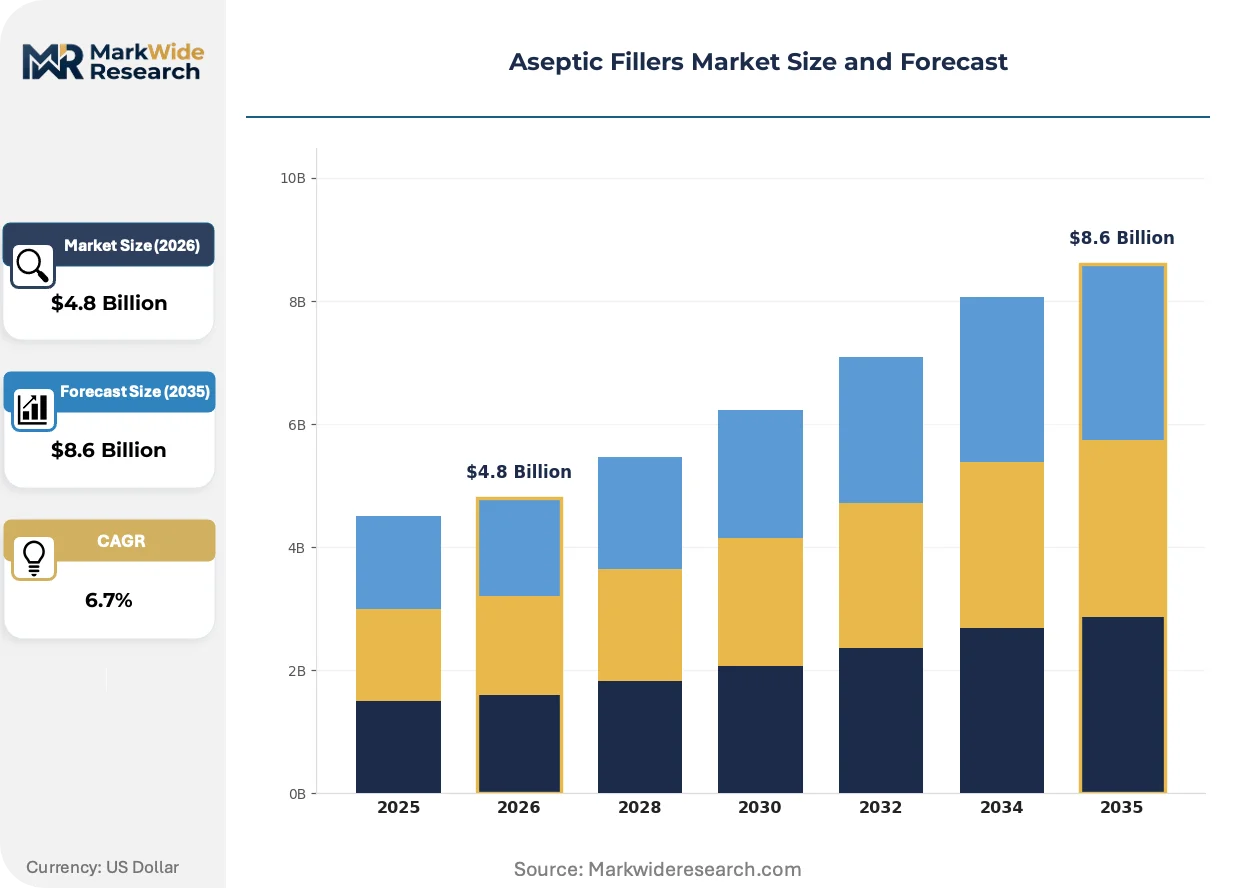
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Fillers, Powder Fillers, Paste Fillers, Gel Fillers End User: Pharmaceutical Companies, Cosmetic Manufacturers, Food Processors, Biotechnology Firms Technology: Robotic Filling, Machine Automation, Contained Systems, Transfer Systems Installation: On-Site Installation, Modular Systems, Dedicated Facilities, Mobile Units |
| Companies Covered | Tetra Pak International S.A., Syntegon Technology GmbH, IMA Group, Krones AG, GEA Group AG, Groninger Holding GmbH & Co. KG, OPTIMA, Bausch+Ströbel, AST, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aseptic Fillers Market Emerging Trajectories
Closed-system robotics and real-time environmental monitoring are collapsing the distinction between aseptic processing and absolute containment, redefining equipment specifications across pharmaceutical manufacturing.
Single-use disposable fluid paths are integrating gamma-irradiated polymer manifolds and pre-sterilized assemblies into rotary filling machines. Biologics manufacturers in Switzerland and Massachusetts are adopting these configurations to eliminate CIP/SIP cycles between campaigns. This integration is compressing batch turnaround from days to hours while reducing cross-contamination risk profiles for multi-product facilities.
EU GMP Annex 1's 2022 revision mandates continuous viable particle monitoring with alarm-triggered intervention protocols. European sterile drug manufacturers must retrofit or replace filling lines lacking real-time microbial detection capabilities. Isolator-based designs with integrated rapid microbial monitoring systems are capturing replacement demand ahead of national competent authority inspections.
Multi-vendor validation partnerships are displacing single-source equipment procurement as the dominant contracting model. Large pharmaceutical manufacturers in Germany and the United States now require pre-integrated qualification packages spanning filling, capping, and inspection modules from distinct suppliers. This pattern concentrates specification-setting power with end-users while fragmenting equipment vendor relationships across production lines.
Aseptic Fillers Market Segmentation
Aseptic filler procurement decisions pivot on sterilization protocol compatibility and batch flexibility requirements. Pharmaceutical manufacturers weigh capital deployment against regulatory exposure when selecting across product formats, automation tiers, and installation architectures.
Product Type:
Capital intensity escalates with product viscosity and containment complexity, driving divergent investment patterns across pharmaceutical manufacturing.
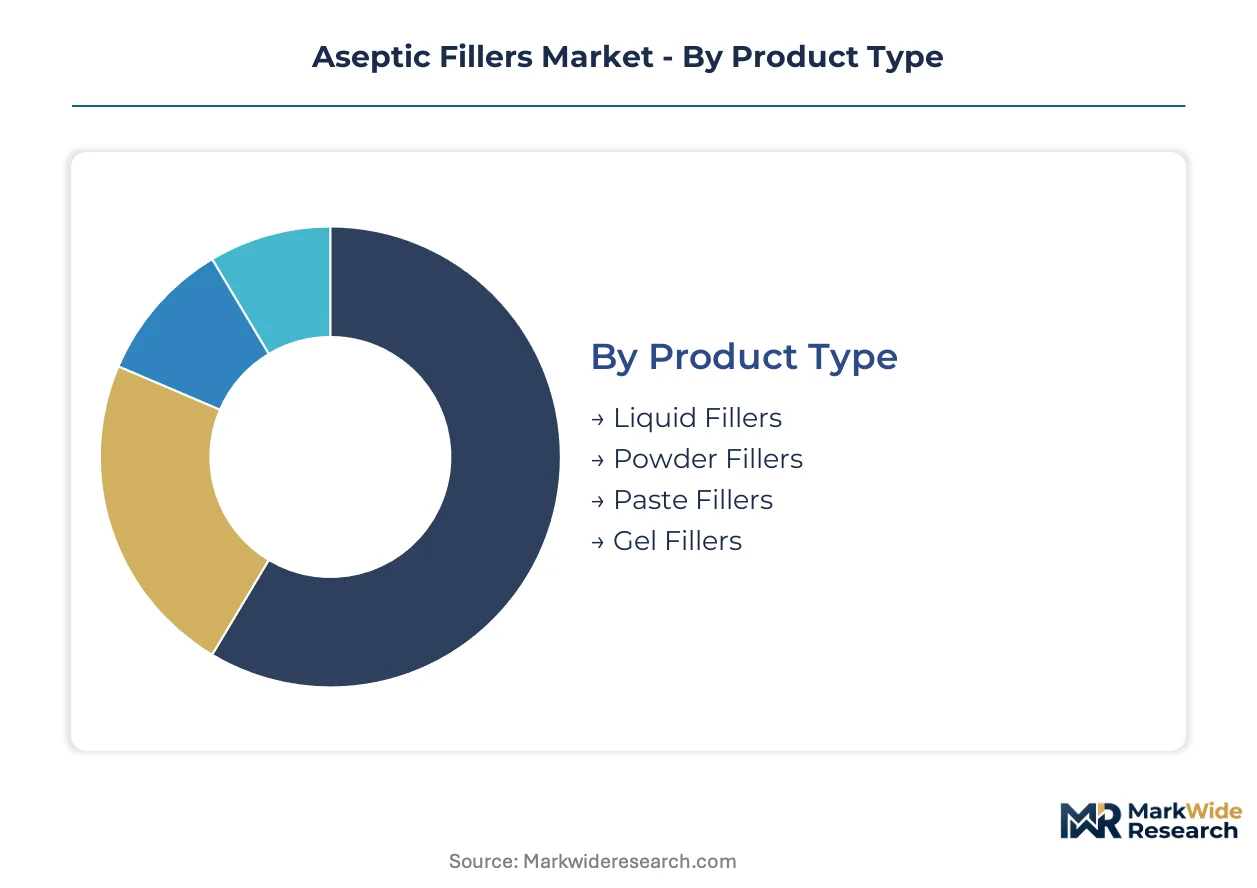
- Liquid Fillers:Rotary piston and peristaltic pump configurations dominate intravenous and ophthalmic drug production. Demand concentrates in Switzerland and Massachusetts biologics clusters where monoclonal antibody formulations require precision dosing within isolator environments.
- Powder Fillers:Auger and vacuum transfer systems handle lyophilized therapeutics with moisture-sensitive stability profiles. German sterile drug facilities are retrofitting powder lines with continuous viable particle monitoring to preempt EMA enforcement actions under revised Annex 1 guidelines.
- Paste Fillers:Positive-displacement pumps with heated manifolds manage semi-solid dermatological and wound-care formulations.
- Gel Fillers:Specialized dosing valves accommodate shear-sensitive ophthalmic and topical preparations with narrow viscosity windows.
Most installed capacity flows through Liquid Fillers. Expansion is steepest in Powder Fillers.
End User:
Regulatory stringency and batch scale separate customer segments by validation burden and equipment specification priorities.
- Pharmaceutical Companies:In-house sterile injectable manufacturing demands isolator-based containment with embedded audit-trail software. FDA sterility guidance and EU GMP Annex 1 revisions are forcing replacement of legacy open-manifold lines across United States and European facilities.
- Biotechnology Firms:Cell therapy and gene therapy developers favor single-use disposable fluid paths to eliminate cross-contamination between patient-specific autologous batches. Massachusetts and Swiss biotech clusters are absorbing flexible modular installations at premium price points.
- Cosmetic Manufacturers:Preservative-free skincare and ophthalmic cosmetic formulations require Grade A filling environments with lower validation overhead than pharma.
- Food Processors:Extended-shelf-life dairy and nutritional beverages deploy high-speed rotary fillers with clean-in-place protocols rather than isolator containment.
Pharmaceutical Companies command the largest equipment spend. Biotechnology Firms are climbing the fastest as cell therapy manufacturing scales.
Technology:
Automation depth determines labor qualification requirements and contamination risk exposure at manual intervention points.
- Contained Systems:Isolator-based designs with unidirectional airflow and rapid transfer ports achieve absolute separation between operator and product. European sterile drug manufacturers are capturing replacement demand ahead of national competent authority inspections.
- Robotic Filling:Six-axis articulated arms with gloveless intervention capabilities eliminate human-borne contamination in Grade A zones. German precision engineering suppliers dominate motion-control component sourcing for these configurations.
- Machine Automation:Programmable logic controller-driven filling with automated in-process checks reduces operator presence without full robotic substitution.
- Transfer Systems:Rapid transfer ports and alpha-beta docking mechanisms enable material movement across containment boundaries without breaking sterility.
Contained Systems anchor current installed base. Robotic Filling is gaining share fastest as labor scarcity and regulatory pressure converge.
Installation:
Facility commitment duration and reconfiguration flexibility shape procurement economics for contract manufacturers versus dedicated producers.
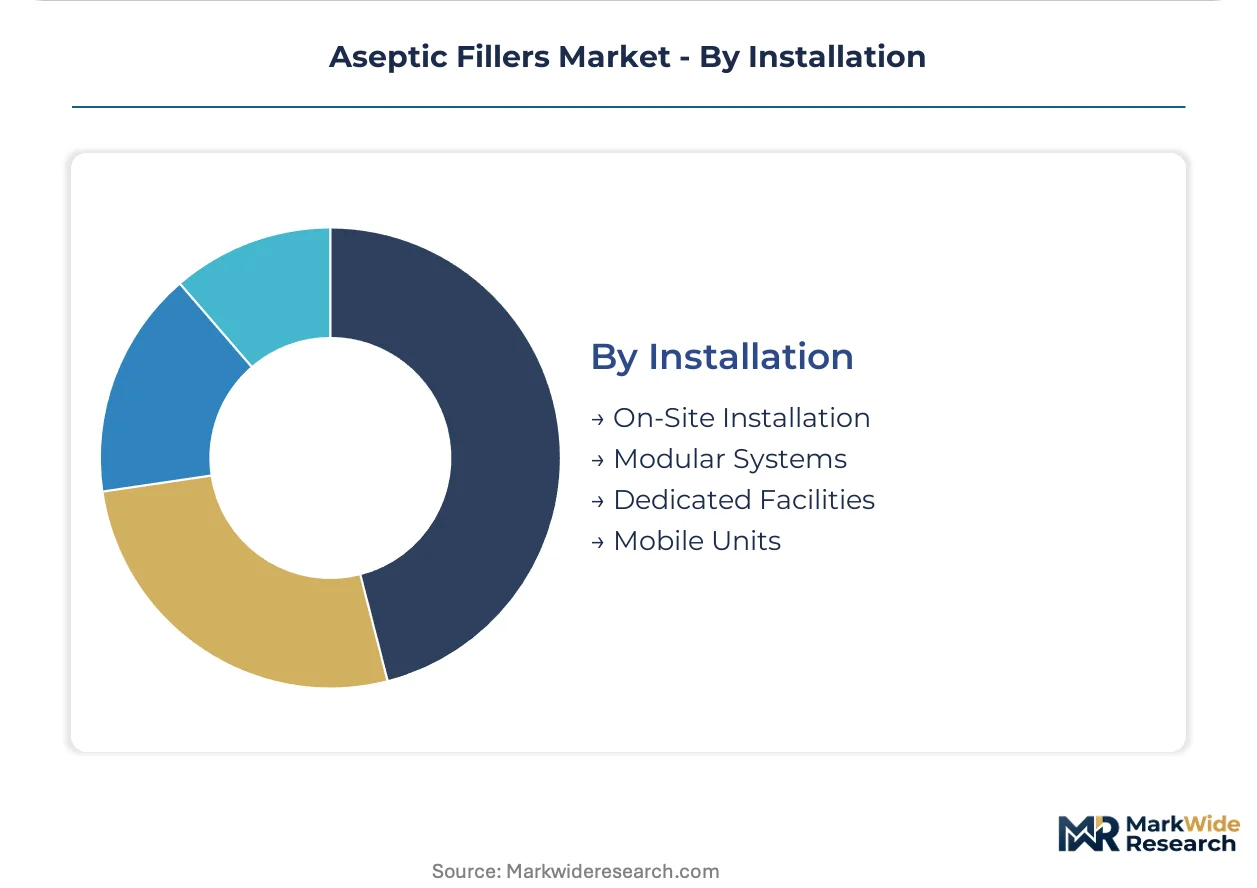
- Modular Systems:Pre-validated skids with steam-in-place capability enable rapid line reconfiguration between high-volume generics and orphan-drug biologics. Indian CDMOs in Hyderabad and Bengaluru are greenfielding this architecture to capture outsourced sterile filling from Western innovators.
- Dedicated Facilities:Permanent Grade B suites with integrated isolator infrastructure suit blockbusters with decade-long production horizons. Swiss and German manufacturing clusters favor this model for monoclonal antibody capacity.
- On-Site Installation:Custom-engineered lines with extended IQ/OQ/PQ timelines serve mature facilities with legacy cleanroom footprints requiring structural adaptation.
- Mobile Units:Containerized filling lines with self-contained HVAC support clinical trial material production and emergency pandemic response manufacturing.
Dedicated Facilities hold the majority of stainless steel infrastructure. Modular Systems are expanding most quickly as multi-product CDMOs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters anchor sterile drug manufacturing investment, with regulatory tightening across multiple jurisdictions reshaping equipment procurement geography.
United States
FDA sterility guidance and the Quality Manufacturing Maturity Model drive isolator-based line replacements across Massachusetts and North Carolina biologics hubs. Monoclonal antibody manufacturers absorb new contained filling capacity at triple the rate of small-molecule additions. Boston and Research Triangle Park clusters favor modular installations with embedded audit-trail software.
Germany
EMA Annex 1 enforcement actions accelerate replacement of legacy open-RABS equipment in Baden-Württemberg and Bavaria sterile drug facilities. Steam-in-place modular fillers reduce batch changeover time for contract manufacturers serving both high-volume generics and orphan-drug biologics. Stuttgart and Munich precision engineering suppliers dominate motion-control component sourcing for robotic filling configurations.
Switzerland
Swissmedic oversight and continuous viable particle monitoring mandates concentrate investment in Basel and Zürich biopharma manufacturing corridors. Cell therapy developers favor single-use disposable fluid paths to eliminate cross-contamination between patient-specific autologous batches. Swiss clusters absorb flexible modular installations at premium price points.
India
CDSCO regulatory alignment with EU GMP standards drives greenfield isolator-based capacity in Hyderabad and Bengaluru contract manufacturing organizations. Western innovators seek cost arbitrage for outsourced sterile filling of biologics and sterile injectables. Indian CDMOs deploy pre-validated skids with rapid line reconfiguration capabilities.
China
NMPA sterile drug manufacturing standards and domestic biologics pipeline expansion concentrate aseptic filling investment in Yangtze River Delta pharmaceutical corridors. Shanghai and Suzhou clusters integrate isolator-based designs with real-time microbial detection capabilities. Local equipment fabricators compete on modular system configurations for multi-product facilities.
Aseptic Fillers Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue isolator-based containment specialization and single-use disposable integration. The vendor base stratifies across three archetypes: beverage packaging heritage conglomerates, precision-engineered pharmaceutical specialists, and modular system integrators. Dominant competitive moves include multi-vendor validation partnerships displacing single-source procurement and backward integration into critical motion-control component supply.
Within the precision-engineered pharmaceutical specialist tier, Syntegon Technology GmbH and Groninger Holding GmbH & Co. KG exemplify German and Austrian fabrication excellence in barrier isolation technology. Tetra Pak International S.A. anchors the beverage-to-pharma extension archetype, leveraging rotary filling heritage into nutritional and extended-shelf-life applications. These three entities occupy positions spanning distinct automation depth requirements across liquid, powder, and paste filling configurations.
| Leading Market Players |
|---|
| Tetra Pak International S.A. |
| Syntegon Technology GmbH |
| IMA Group |
| Krones AG |
| GEA Group AG |
| Groninger Holding GmbH & Co. KG |
| OPTIMA |
| Bausch+Ströbel |
| AST, LLC |
| Others |
Supply Flow & Price Mechanics
Isolator-grade certification separates premium containment systems from standard rotary fillers, with this performance divergence manifesting in both pricing stratification and sourcing patterns across German precision engineering clusters and Indian modular assembly operations. Pharmaceutical-grade 316L stainless steel and H14 HEPA filtration media anchor cost structures at the premium tier, while commodity-grade components service economy installations for food and cosmetic applications.
Pricing Analysis
Input-cost pass-through from pharmaceutical-grade 316L stainless steel and H14 filtration media volatility compresses margins on fixed-price equipment contracts, forcing vendors toward cost-plus indexing. Three-tier pricing structure across isolator-premium, RABS-standard, and open-manifold-economy levels differentiates by contamination assurance grade and FDA 483 exposure risk. Pricing pressure stems from energy-driven raw material swings and extended 18-24 month IQ/OQ/PQ validation timelines that delay revenue recognition. Contract manufacturers in India exhibit highest price sensitivity due to cost-arbitrage business models, while Swiss biologics clusters prioritize containment performance over capital expenditure minimization.
Supply Chain Analysis
Refurbishment flows for isolator glove-port assemblies and motion-control components create secondary supply channels that extend equipment lifecycle and moderate new-build demand. Critical component fabrication concentrates in Germany, Switzerland, and Austria, with Stuttgart and Munich suppliers dominating precision motion-control sourcing for robotic filling configurations. Raw material dependencies rest on pharmaceutical-grade 316L steel, gamma-irradiated polymer manifolds, and H14 HEPA filtration media. Single-source vulnerability in glove-port assembly supply exposes lead times to disruption. Distribution runs through direct vendor relationships with large pharmaceutical manufacturers and CDMO procurement consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Western regulatory stringency and Indian cost structures creates viable entry pathways for modular system integrators, with EU GMP Annex 1 compliance costs in Germany and Switzerland running substantially above CDSCO-aligned facility investments in Hyderabad and Bengaluru.
For Market Incumbents: Deploy backward integration into critical motion-control component supply to secure glove-port assembly and precision actuator sourcing against German supplier concentration risk. Consolidate multi-vendor validation partnership capabilities to capture specification-setting power from pharmaceutical manufacturers replacing legacy open-RABS equipment. Counter emerging modular system integrators in India by embedding audit-trail software and rapid microbial monitoring as bundled service differentiators. For New Entrants and Emerging Players: Begin with single-use disposable fluid path specialization for autologous cell therapy manufacturing, where patient-specific batch requirements favor flexible configurations over stainless steel infrastructure. Target Massachusetts and Swiss biotech clusters with gamma-irradiated polymer manifold integration into pre-validated skid architectures. Pursue CDMO relationships in Hyderabad and Bengaluru through cost-arbitrage positioning against Western incumbent pricing. For Investors and Strategic Acquirers: Consolidation pressure builds where precision engineering talent scarcity constrains vendor scaling and multi-year validation timelines delay revenue recognition. Long-term viability favors isolator-based containment specialization over open-manifold legacy exposure. Acquisition target archetype: German or Swiss precision engineering specialists with embedded rapid microbial monitoring capabilities and established FDA 483 remediation track records. Monitor FDA Quality Manufacturing Maturity Model implementation velocity as inflection indicator for premium equipment tier preference formation.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Based Containment Retrofit | EU GMP Annex 1 enforcement actions accelerate replacement demand across European sterile drug facilities. |
| Single-Use Disposable Fluid Path Integration | Cell therapy developers in Basel and Massachusetts eliminate CIP/SIP cycles between autologous batches. |
| Backward Integration into Motion-Control Supply | Precision component captive production secures glove-port assembly sourcing against German supplier concentration. |
| Multi-Vendor Validation Partnership Formation | End-user specification-setting power concentrates with pharmaceutical manufacturers fragmenting vendor relationships. |
| Modular System Pre-Validation for CDMOs | Indian contract manufacturers in Hyderabad capture outsourced sterile filling through rapid line reconfiguration capabilities. |
Methodological Framework
Coverage spans the United States, Germany, Switzerland, India, and China, with primary inputs from each market gathered through structured interviews with sterile manufacturing directors, regulatory affairs leads, CDMO procurement managers, and containment engineering specialists. Secondary validation draws from FDA 483 observation databases, EMA inspection findings, ISO 14644 cleanroom classification standards, and EU GMP Annex 1 revision documentation. Bottom-up equipment installation tracking and top-down pharmaceutical capital expenditure analysis enable triangulation across market sizing approaches.
Granularity-level modeling disaggregates volume and value outputs across product type, technology tier, end-user segment, and installation architecture dimensions throughout the forecast period. CAGRs derive from regression analysis against biologics pipeline expansion rates and regulatory enforcement intensity indices. Industry-specific forecast inputs include monoclonal antibody manufacturing capacity additions and cell therapy autologous batch scaling trajectories.
Several conditions sit outside the modeled scope, including pandemic emergency manufacturing authorization reversals and abrupt tariff reconfigurations affecting pharmaceutical-grade steel trade flows. Forecasts reflect documented assumptions regarding EU GMP Annex 1 national competent authority inspection pacing and FDA Quality Manufacturing Maturity Model adoption velocity. Practitioners should monitor CDSCO regulatory alignment progress and steam-in-place protocol standardization for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aseptic & Retort Packaging
Global Aseptic Paper Packaging Market
Aseptic & Retort Packaging
Global Aseptic Sampling Market
Aseptic & Retort Packaging
Latin America Aseptic Packaging Market
Aseptic & Retort Packaging
North America Retort Packaging Market
Aseptic & Retort Packaging
Global Pillow Shape Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Films Market
Aseptic & Retort Packaging
Aseptic Containment Systems Market
Aseptic & Retort Packaging
Aseptic Packaging Equipment Market
Aseptic & Retort Packaging
North America Aseptic Packaging Market
Aseptic & Retort Packaging
Retort Grade BOPET Films Market
Aseptic & Retort Packaging
Aseptic Carton Bottles Market
Aseptic & Retort Packaging
Europe Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Carton Packaging Market
Aseptic & Retort Packaging
Aseptic Packaging Market
Aseptic & Retort Packaging
Aseptic Transfer System Market
Aseptic & Retort Packaging
Retort Machine Market