
 Car Lube Container Market | 2026-2036
Car Lube Container Market Size, Share, and Industry Trends Forecast 2026-2036
Car Lube Container Market Outlook
Aftermarket distribution through quick-lube chains and workshop networks is rewriting how car lube containers reach end users. Mold Tek Packaging leverages its blow-molding expertise to supply standardized bottles across India's growing service station chains. Graham Packaging sustains its position through high-volume contracts with North American motor oil brands. Plastipak Packaging anchors European demand with recyclable PET designs that meet retailer sustainability mandates.
A car lube container is a purpose-built vessel, typically blow-molded from high-density polyethylene or injection-stretched PET, engineered to resist hydrocarbon permeation and withstand stacking loads during transport and storage. Its primary function is to preserve lubricant integrity from filling through point-of-use while enabling controlled pouring and accurate volume dispensing. Plastic bottles occupy the dominant volume position across retail and workshop channels due to cost efficiency and design flexibility, while bag-in-box formats are gaining traction among fleet services seeking reduced packaging waste and optimized storage density. Metal cans retain niche demand in premium synthetic lubricant segments where perceived durability supports brand positioning.
The US EPA regulates resin emissions under TSCA Section 5, while the EU REACH framework restricts phthalate plasticizers in food-contact-grade resins that often share production lines with lube packaging. India's BIS certification mandates minimum wall thickness and closure integrity standards for petroleum product containers. Stakeholders must monitor how extended producer responsibility schemes in Europe and state-level recycled content laws in the US reshape material specifications and supplier qualification requirements.
Market Dynamics
Automotive OEMs are tightening proprietary container specifications to lock in supply chain consistency, forcing converters to retool lines for brand-specific geometries while absorbing resin volatility.
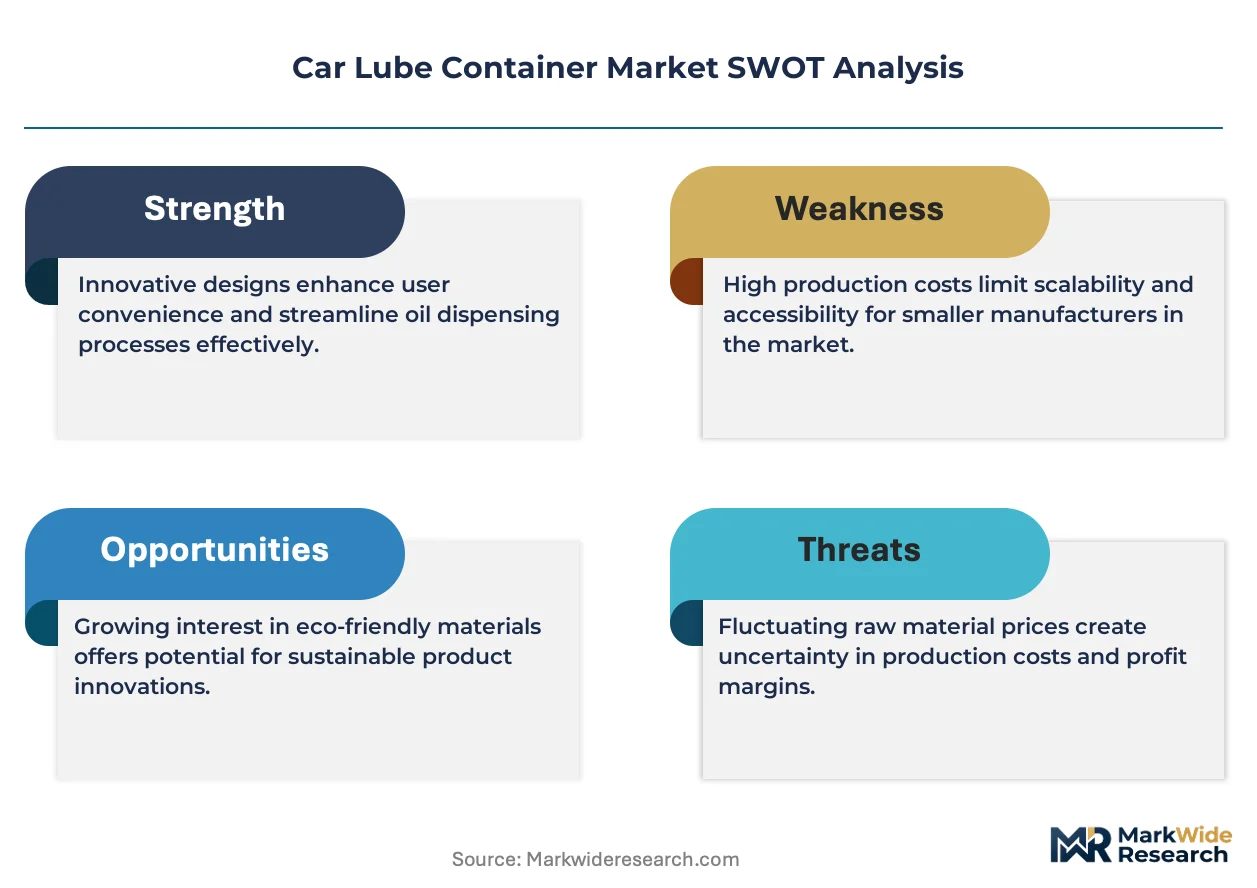
Growth Catalysts
- REACH phthalate restrictions:European converters are accelerating migration to non-plasticized HDPE grades, opening specification windows for certified suppliers.
- India's workshop formalization:Domestic quick-lube chains are consolidating procurement under single-source national contracts, concentrating volume with qualified molders.
- Blow-molding automation:Servo-driven extrusion systems are cutting cycle times and enabling thinner-wall designs without sacrificing stack strength.
Market Restraints
- HDPE resin concentration:Gulf Coast petrochemical outages transmit price spikes within weeks, squeezing converter margins on fixed-price annual contracts.
- California ARB VOC limits:The state's resin emission caps force dual inventory management for national brands serving both compliant and non-compliant states.
- Steel can substitution in synthetics:Premium lubricant marketers retain metal packaging for perceived durability, capping plastic penetration in high-margin segments.
Strategic Opportunities
- India's BIS certification expansion:Stricter closure integrity standards will disqualify informal suppliers, consolidating share with compliant domestic molders.
- Bag-in-box fleet services:Reduced packaging waste and cube-optimized storage are displacing rigid bottles in commercial vehicle maintenance depots.
- Post-consumer recycled content mandates:State-level recycled HDPE floors in the US are creating first-mover advantage for converters with food-grade rHDPE sourcing.
Industry Challenges
- Blow-molding technician scarcity:Experienced process engineers capable of tuning parison programs for hydrocarbon barrier resins command premiums that inflate plant-level costs.
- Multi-site qualification timelines:OEMs require 18-month validation cycles for each production location, slowing geographic expansion for mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Lube Container Market |
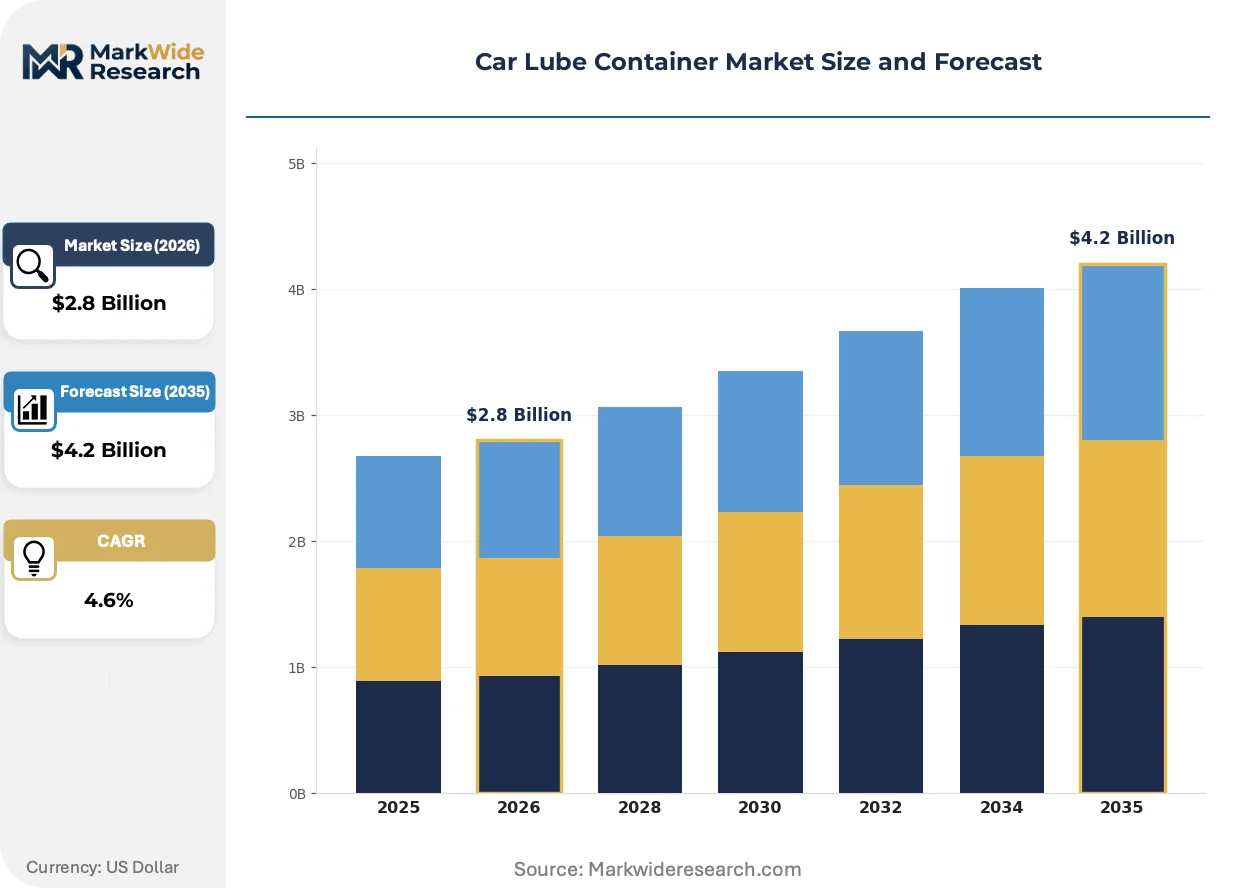
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bottle, Metal Can, Bag-in-Box, Pouch Distribution Channel: Retail Stores, Online Platforms, Wholesalers, Direct Sales End User: Individual Consumers, Workshops, Automotive OEMs, Fleet Services Size: 1 Liter, 5 Liters, 20 Liters, 55 Liters |
| Companies Covered | RPC Promens, Industrial Plenmeller, Balmier Lawrie & Co. Ltd., Mold Tek Packaging, Komal Packaging, Bright Containers, Graham Packaging, Plastipak Packaging, RPS Promens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Lube Container Market Strategic Shifts
Material science and regulatory chemistry are converging to redefine acceptable performance thresholds, with sustainability metrics now embedded in procurement scorecards alongside unit cost.
Barrier-enhanced PET is hybridizing with scavenger additives and multilayer coextrusion to match HDPE's hydrocarbon resistance while delivering superior clarity and retail shelf appeal. Quick-lube chains in North America are piloting these bottles for synthetic motor oils where brand visibility drives purchase decisions. The structural consequence is compressing the traditional HDPE monopoly in mid-tier lubricant segments.
EPA TSCA Section 5 pre-manufacture notifications are tightening scrutiny on novel resin additives used in lube packaging, extending approval timelines for reformulated grades. Converters face inventory stranding risk if formulations fail notification while customer specifications freeze. North American motor oil brands are responding by locking multi-year supply agreements with resin producers whose additive packages carry grandfathered approval status.
Workshop procurement consolidation is compressing supplier counts as national quick-lube chains centralize purchasing through dedicated category managers. Independent distributors that historically served fragmented service stations are losing shelf position to direct converter relationships. India exhibits the most visible concentration, where formalizing workshop networks are eliminating the informal bottle suppliers that dominated secondary cities.
Car Lube Container Market Segmentation
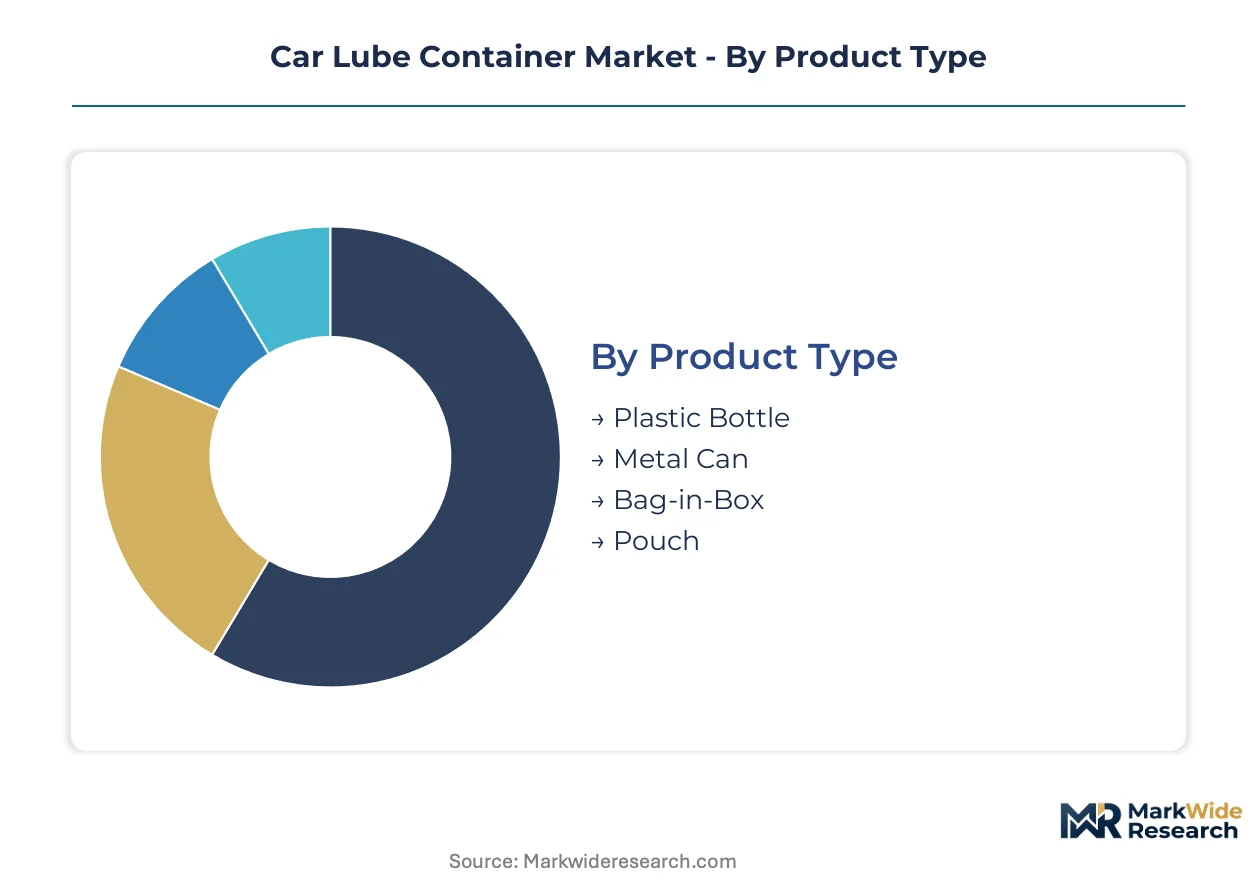
Segmentation in the car lube container market reveals how after-sales service intensity varies dramatically across end-use scenarios. Workshop networks and fleet depots demand rugged, high-volume formats with rapid dispensing features, while retail channels prioritize shelf visibility and consumer handling ergonomics. Understanding these divergent requirements helps converters align blow-molding investments with specific performance thresholds.
Product Type:
After-sales service intensity peaks with formats that withstand repeated handling in high-throughput workshop environments. Plastic bottles dominate quick-lube bays where technicians execute rapid oil changes under time pressure. Metal cans and flexible formats serve differentiated needs based on durability perceptions and storage optimization.
- Plastic Bottle:Blow-molded HDPE and multilayer PET constructions deliver hydrocarbon barrier performance at unit costs that sustain margin structures in price-sensitive workshop contracts. India's formalizing service station chains are consolidating procurement around standardized 1-liter and 5-liter PET designs with integrated spouts and tamper-evident closures.
- Metal Can:Tinplate and aluminum constructions command premium positioning in synthetic lubricant segments where brand marketers emphasize perceived durability and heritage aesthetics. California ARB VOC compliance adds cost layers through specialized interior coatings that prevent resin-liner interaction.
- Bag-in-Box:Collapsible inner bags with corrugated outer shells reduce packaging waste and optimize warehouse cube utilization for fleet maintenance depots managing bulk synthetic inventories.
- Pouch:Stand-up flexible formats with precision spouts target DIY consumers seeking lightweight portability and controlled dispensing for top-off applications.
Plastic bottles hold the largest share; momentum sits with bag-in-box formats displacing rigid containers in commercial vehicle operations.
Distribution Channel:
Cost tier differentiation separates mass-market retail from premium direct relationships. National quick-lube chains are bypassing traditional distribution layers to negotiate direct converter contracts, compressing margin pools for intermediate wholesalers.
- Retail Stores:Mass merchandisers and auto parts chains demand pallet-optimized packaging with maximum shelf-facing efficiency. EPA TSCA compliance documentation accompanies every resin batch to satisfy retailer sustainability scorecards.
- Online Platforms:E-commerce fulfillment requires damage-resistant designs that survive last-mile handling without secondary protective packaging, favoring thicker-wall HDPE over thin-gauge alternatives.
- Wholesalers:Regional distributors serving fragmented independent workshops face volume concentration as national chains centralize procurement, eroding their historical intermediary role.
- Direct Sales:Converter-to-OEM relationships lock in proprietary geometries and color-matched branding through multi-year supply agreements with 18-month qualification cycles.
Retail stores maintain volume leadership; online platforms are climbing the fastest as workshop procurement digitizes.
End User:
Application severity determines barrier specifications and closure engineering. Fleet services operating commercial vehicle depots impose the most demanding throughput requirements, while individual consumers prioritize convenience over industrial durability.
- Individual Consumers:DIY purchasers respond to ergonomic grip geometries and clear volume markings that reduce overfill risk during residential driveway maintenance.
- Workshops:Quick-lube bays require rapid-dispense spouts and stack-stable bases that withstand continuous handling in high-rotation service environments across India's expanding formalized chains.
- Automotive OEMs:Factory-fill operations demand lot-traceable containers with tamper-evident features that integrate with assembly line fluid dispensing systems.
- Fleet Services:Commercial vehicle operators are consolidating lubricant procurement under national contracts that specify bag-in-box formats for cube-optimized depot storage and reduced packaging disposal costs.
Workshops represent the dominant volume segment; fleet services show the steepest expansion trajectory as logistics operators professionalize maintenance operations.
Size:
Volume scale aligns with customer operational rhythm and inventory turnover velocity. Smaller formats serve retail impulse purchases and residential top-offs; bulk containers optimize unit economics for high-consumption commercial users.
- 1 Liter:Single-serve PET bottles dominate retail shelf space for passenger vehicle owners executing occasional top-offs between scheduled services.
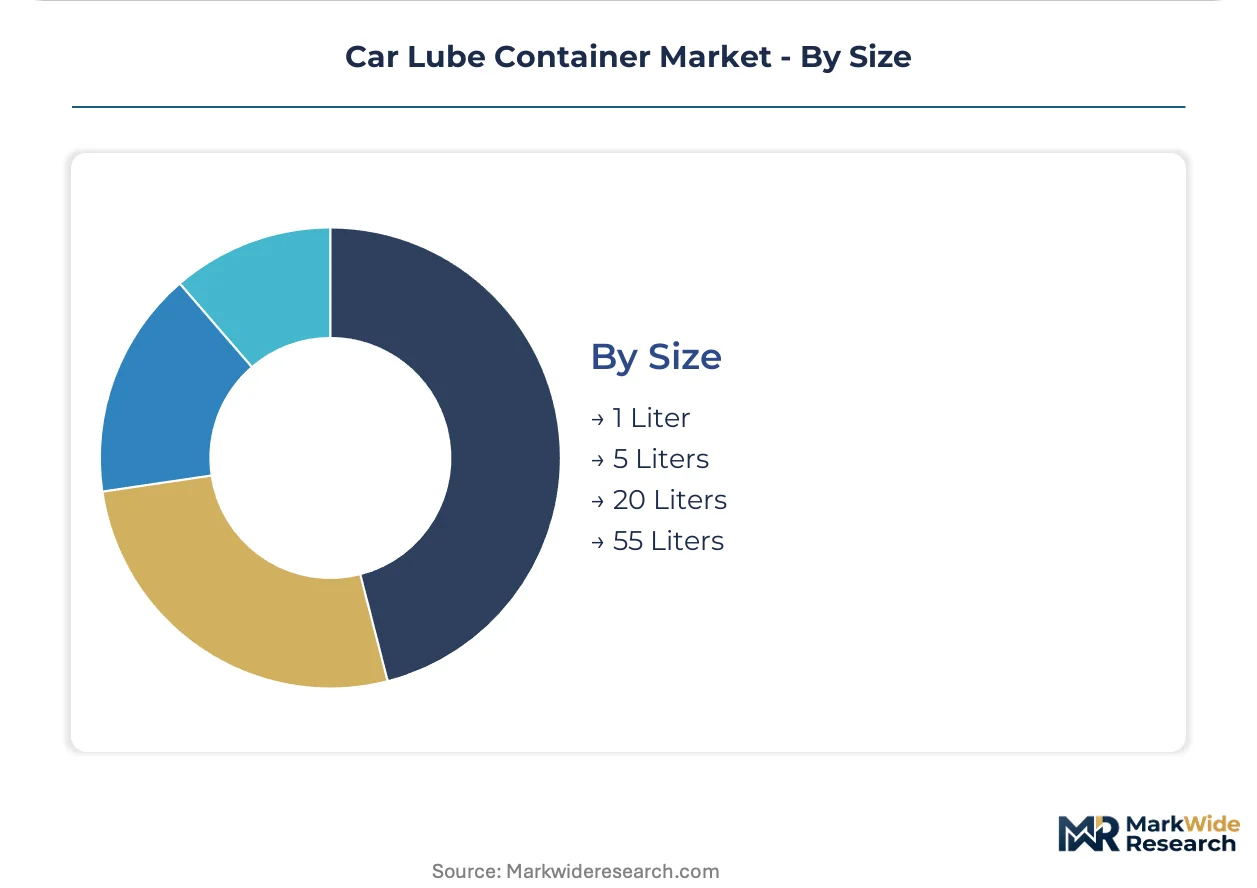
- 5 Liters:The standard workshop format balances handling ergonomics with sufficient capacity to complete most passenger vehicle oil changes without residual waste.
- 20 Liters:Intermediate bulk containers serve small fleet operators and independent workshops with moderate throughput seeking per-liter cost advantages over retail sizes.
- 55 Liters:Drum formats anchor commercial fleet depot operations where bulk synthetic procurement and centralized dispensing systems minimize packaging unit costs.
5-liter containers capture the largest share; 55-liter formats are gaining share fastest as fleet services consolidate lubricant purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility schemes and recycled content mandates are redrawing procurement maps for blow-molded packaging across major automotive markets. National regulators are tightening volatile organic compound limits while workshop networks professionalize, creating divergent qualification hurdles by geography.
United States
California ARB VOC caps on plastic packaging resins force dual inventory systems for national lubricant brands serving compliant and non-compliant states. EPA TSCA Section 5 pre-manufacture notifications extend approval timelines for novel resin additives, stranding converter inventory when formulations fail notification. The Gulf Coast petrochemical corridor concentrates HDPE resin production, transmitting price volatility within weeks when outages occur.
Germany
EU REACH phthalate restrictions accelerate converter migration to non-plasticized HDPE grades, opening specification windows for certified suppliers. The country's automotive OEMs tighten proprietary container geometries through multi-year supply agreements with 18-month qualification cycles. Industrial clusters in Bavaria and Baden-Württemberg host specialized molders serving factory-fill operations with lot-traceable packaging.
India
BIS certification mandates minimum wall thickness and closure integrity standards that disqualify informal suppliers in secondary cities. Domestic quick-lube chains consolidate procurement under single-source national contracts, concentrating volume with qualified molders. Maharashtra and Gujarat host the principal blow-molding operations supplying India's formalizing workshop networks.
China
Dual carbon goals and provincial emissions trading schemes raise energy costs for petrochemical-based resin production. The country's national packaging regulator enforces stricter migration limits on additives used in lubricant-contact plastics. Yangtze River Delta manufacturing hubs supply standardized containers for both domestic vehicle production and export markets.
Brazil
ANVISA alignment with Mercosur technical regulations creates harmonized standards for petroleum product packaging across South American trade corridors. São Paulo state industrial parks concentrate blow-molding capacity serving both domestic lubricant blenders and Andean export markets. Fleet operators in the Southeast region pilot bag-in-box formats for commercial vehicle depot operations.
Car Lube Container Market Competitive Environment
On the supply side, the industry is consolidating around converters with proven hydrocarbon barrier expertise and multi-site qualification capabilities. Tiered competitive dynamics separate high-volume contract manufacturers serving North American motor oil brands from regional specialists capturing India's workshop formalization wave. Two strategic archetypes dominate: scale-driven operators with food-grade rHDPE sourcing advantages, and technical specialists with servo-driven blow-molding automation. Dominant competitive moves include backward integration into resin compounding and geographic expansion through dedicated category manager relationships with national quick-lube chains.
Within the scale-driven tier, Graham Packaging and Plastipak Packaging exemplify converters with high-volume contract structures and recyclable PET design capabilities. Mold Tek Packaging occupies a position representing India's domestic qualified molder archetype, capturing share as BIS certification eliminates informal competitors. These three companies illustrate how geographic specialization and regulatory compliance credentials partition competitive advantage across regional markets.
| Leading Market Players |
|---|
| RPC Promens |
| Industrial Plenmeller |
| Balmier Lawrie & Co. Ltd. |
| Mold Tek Packaging |
| Komal Packaging |
| Bright Containers |
| Graham Packaging |
| Plastipak Packaging |
| RPS Promens |
| Others |
Value Chain & Pricing Dynamics
Gulf Coast petrochemical concentration transmits HDPE resin volatility directly to converter margin pools, with annual fixed-price contracts amplifying exposure when outages strike. National quick-lube chains exploit this upstream brittleness to extract volume concessions through centralized procurement mandates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by barrier performance and certification grade. Premium metal cans command positioning power through synthetic lubricant brand heritage, while standard HDPE bottles face cost compression from India's BIS-certified domestic molders. Price erosion runs through economy tiers as informal suppliers exit under regulatory pressure. Fleet services exhibit highest price sensitivity due to bulk procurement scale, whereas automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates with Graham Packaging, Plastipak Packaging, and Mold Tek Packaging anchoring regional capacity pools across North America, Europe, and India respectively. HDPE resin draws from Gulf Coast petrochemical complexes, PET feedstock sources from integrated refinery operations, and closure components rely on precision injection molders in Germany and China. Single-source vulnerability concentrates around blow-molding technician scarcity capable of tuning parison programs for hydrocarbon barrier resins. Distribution runs through direct converter relationships with national quick-lube chains, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as national quick-lube chains consolidate procurement under single-source contracts, fragmenting historical distributor margins and forcing supply chain restructuring.
For Market Incumbents: Entrench barrier-enhanced PET capabilities to defend against HDPE displacement in synthetic lubricant segments. Lock multi-year resin supply agreements with grandfathered EPA TSCA approval status to neutralize formulation stranding risk. Deepen backward integration into rHDPE compounding to capture state-level recycled content mandate premiums before competitors qualify food-grade sourcing. For New Entrants and Emerging Players: Establish a beachhead in India's BIS-certified workshop supply tier as informal molders face disqualification under closure integrity standards. Target bag-in-box fleet services with cube-optimized designs displacing rigid bottles in commercial vehicle depots. Pursue direct category manager relationships with consolidating quick-lube chains rather than distributor intermediation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional molders lacking multi-site qualification capabilities to serve OEM factory-fill contracts. Long-term viability hinges on regulatory compliance credentials rather than pure scale. Monitor BIS certification expansion timelines as inflection indicators for Indian market consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures recycled HDPE premiums under California and European content floors. |
| Servo-Driven Blow-Molding Automation | Reduces cycle times for Mold Tek Packaging serving India's formalizing workshop chains. |
| Multi-Site Qualification Expansion | Enables Graham Packaging to meet OEM 18-month validation requirements across geographies. |
| Barrier-Enhanced PET Product Launch | Positions Plastipak Packaging against HDPE in synthetic motor oil retail visibility segments. |
| Direct Quick-Lube Chain Partnership | Bypasses wholesale erosion as national chains centralize procurement through category managers. |
Study Parameters
The analysis maps blow-molded HDPE, multilayer PET, metal can, and bag-in-box sub-sectors, each validated through blow-molding process engineers, lubricant brand procurement directors, quick-lube chain category managers, and BIS certification auditors. Primary fieldwork combined with secondary validation from EPA TSCA filings, EU REACH substance registrations, Indian BIS standards documentation, and automotive OEM packaging specifications. Bottom-up volume triangulation across converter capacity utilization and top-down demand modeling from vehicle production and service intensity metrics anchored segment outputs.
Assumptions held resin price volatility within historical bands and regulatory timelines per published implementation schedules, while varying workshop formalization rates and recycled content mandate adoption across regions. Segmentation dimensions modeled include product format, distribution channel structure, end-user application severity, and regional regulatory cluster. CAGRs derived from regression against vehicle stock growth, service interval extension trends, and packaging format substitution elasticities. Forecast inputs incorporated blow-molding automation adoption curves and BIS certification penetration rates.
Sensitivities concentrate around Gulf Coast petrochemical outage frequency, REACH phthalate restriction enforcement intensity, and quick-lube chain procurement consolidation velocity. Forecasts reflect documented assumptions on resin supply stability and regulatory implementation adherence. Quarterly review of HDPE spot price spreads, BIS auditor deployment rates, and national chain contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
PP Container Liner Market
Containers
Hinged Deli Containers Market
Containers
Tin Containers Market
Containers
Slotted Containers Market
Containers
Sandwich Containers Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Stainless Steel Cask Market
Containers
Latin America Intermediate Bulk Container Liner Market
Containers
PET Containers Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Grab and Go Containers Market
Containers
Pail Lids Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Metal IBC Market
Containers
Cups and Lids Market
Containers
Slide Top Tins Market